
 Leukemia Therapeutics Market | 2026-2036
Leukemia Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Leukemia Therapeutics Market Analysis
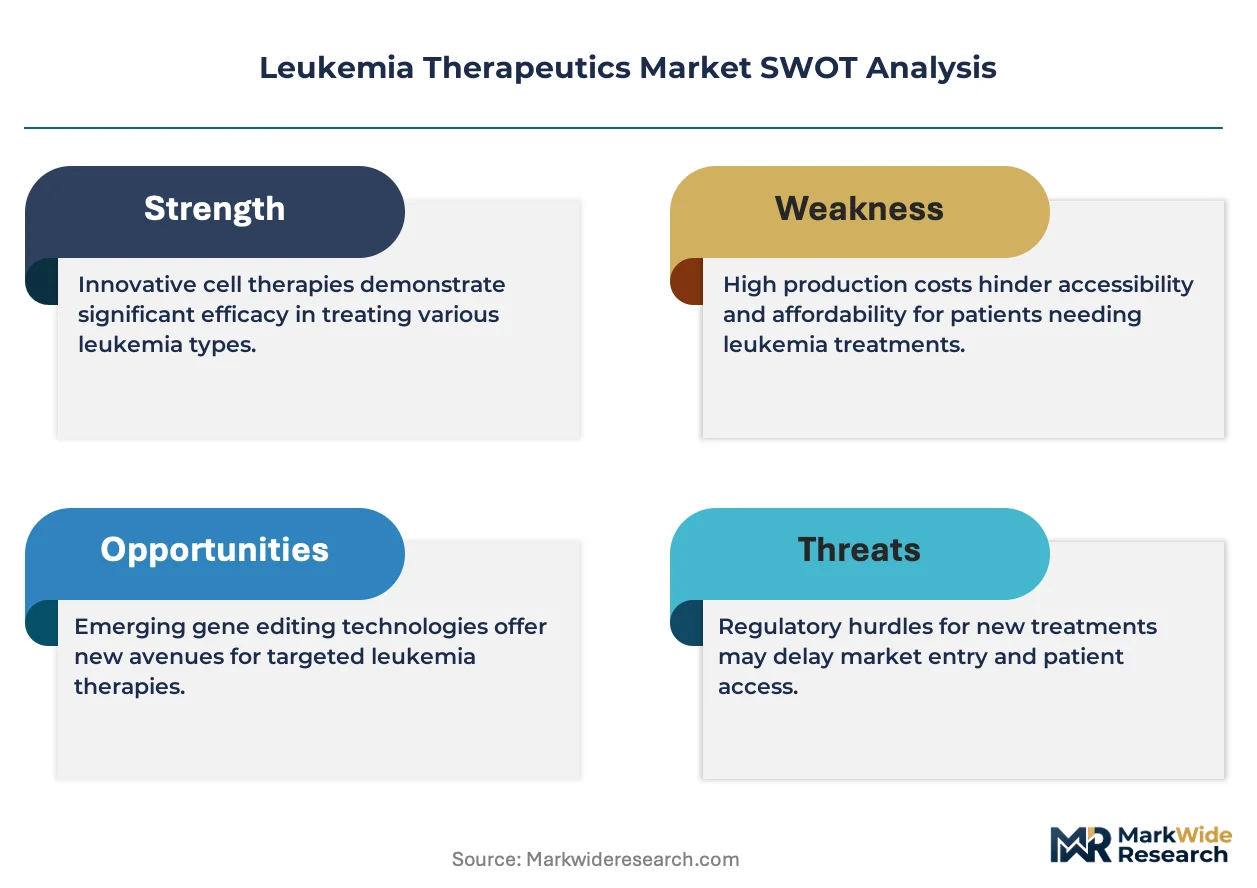
FDA accelerated approval pathways for breakthrough therapies is consolidating the cost-of-entry calculus for novel leukemia therapeutics, demanding larger confirmatory trial investments from sponsors. Novartis leverages its pioneering CAR-T manufacturing infrastructure to sustain leadership in relapsed acute lymphoblastic leukemia. Bristol-Myers Squibb anchors its position through dual immunotherapy platforms spanning checkpoint inhibition and cell therapy. AbbVie differentiates via targeted small-molecule combinations that compete across chronic lymphocytic leukemia lines of therapy.
Leukemia therapeutics encompass pharmaceutical and biologic interventions designed to destroy malignant hematopoietic cells, restore normal bone marrow function, and prevent systemic dissemination through mechanisms including cytotoxic induction, kinase inhibition, monoclonal antibody engagement, and genetic modification of autologous T-cells. These interventions serve the primary commercial purpose of extending overall survival and achieving minimal residual disease negativity in hematologic malignancies. Targeted therapy occupies the largest margin pool as BCR-ABL and BTK inhibitors command premium pricing across chronic myelogenous and lymphocytic leukemia populations. Immunotherapy represents the fastest-growing structural segment, with CAR-T cell products expanding from pediatric acute lymphoblastic leukemia into adult acute myeloid leukemia indications. Chemotherapy remains entrenched as induction backbone despite shrinking share in maintenance settings.
The FDA, EMA, and Japan's PMDA enforce divergent evidentiary standards for cell and gene therapy approvals, with FDA breakthrough therapy designation enabling earlier market access than EMA's conditional marketing authorization pathway. China's NMPA and India's CDSCO are harmonizing with ICH E6(R2) guidelines while maintaining local manufacturing requirements that shape regional supply strategies. Stakeholders must monitor how post-market confirmatory trial failures trigger regulatory withdrawal mechanisms and reshape portfolio risk calculations.
Market Dynamics
FDA breakthrough therapy designation is compressing development timelines for CAR-T and bispecific antibody programs, forcing sponsors to front-load manufacturing capacity investments before confirmatory readouts.
Growth Catalysts
- Accelerated Approval Pathways:FDA's breakthrough therapy and EMA's PRIME designation enable earlier commercial access for cell therapies, reducing time-to-revenue for sponsors with robust Phase II data packages.
- Autologous Cell Manufacturing Scale-Up:Closed-system bioreactors and automated cell processing platforms are expanding production capacity at tertiary treatment centers across the United States, Germany, and Japan.
- Minimal Residual Disease Testing Integration:Next-generation sequencing-based MRD assays are driving treatment-intensification decisions in acute lymphoblastic leukemia maintenance protocols.
Market Restraints
- Vein-to-Vein Logistics Complexity:Cryogenic cold chain requirements for autologous cell products limit treatment access to urban academic medical centers with specialized apheresis and infusion capabilities.
- Plasma-Derived Raw Material Concentration:Serum and growth factor supply for cell culture media concentrates among a handful of specialty chemical suppliers, creating input vulnerability.
- Post-Market Confirmatory Trial Risk:FDA accelerated approval mandates expose sponsors to revenue reversal if Phase III trials fail to verify clinical benefit, reshaping portfolio risk calculations.
Strategic Opportunities
- Allogeneic Off-the-Shelf Platforms:Gene-edited donor-derived cell therapies eliminate patient-specific manufacturing delays, opening community oncology settings currently excluded from autologous programs.
- Japan's Sakigake Designation:PMDA's priority review system offers reduced data requirements and dedicated consultation for regenerative medicines, creating regulatory arbitrage for early entrants.
- Real-World Evidence Infrastructure:Flatiron Health and similar oncology data networks enable post-approval efficacy tracking that satisfies FDA confirmatory requirements without traditional randomized trials.
Industry Challenges
- Vector Manufacturing Bottleneck:Lentiviral and retroviral vector production capacity constraints delay IND-enabling studies and create queue dependencies for multiple CAR-T programs.
- Cross-Border Cell Transport Harmonization:Divergent customs clearance protocols for living therapeutic products between the United States, European Union, and Japan complicate multi-site clinical trial execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leukemia Therapeutics Market |
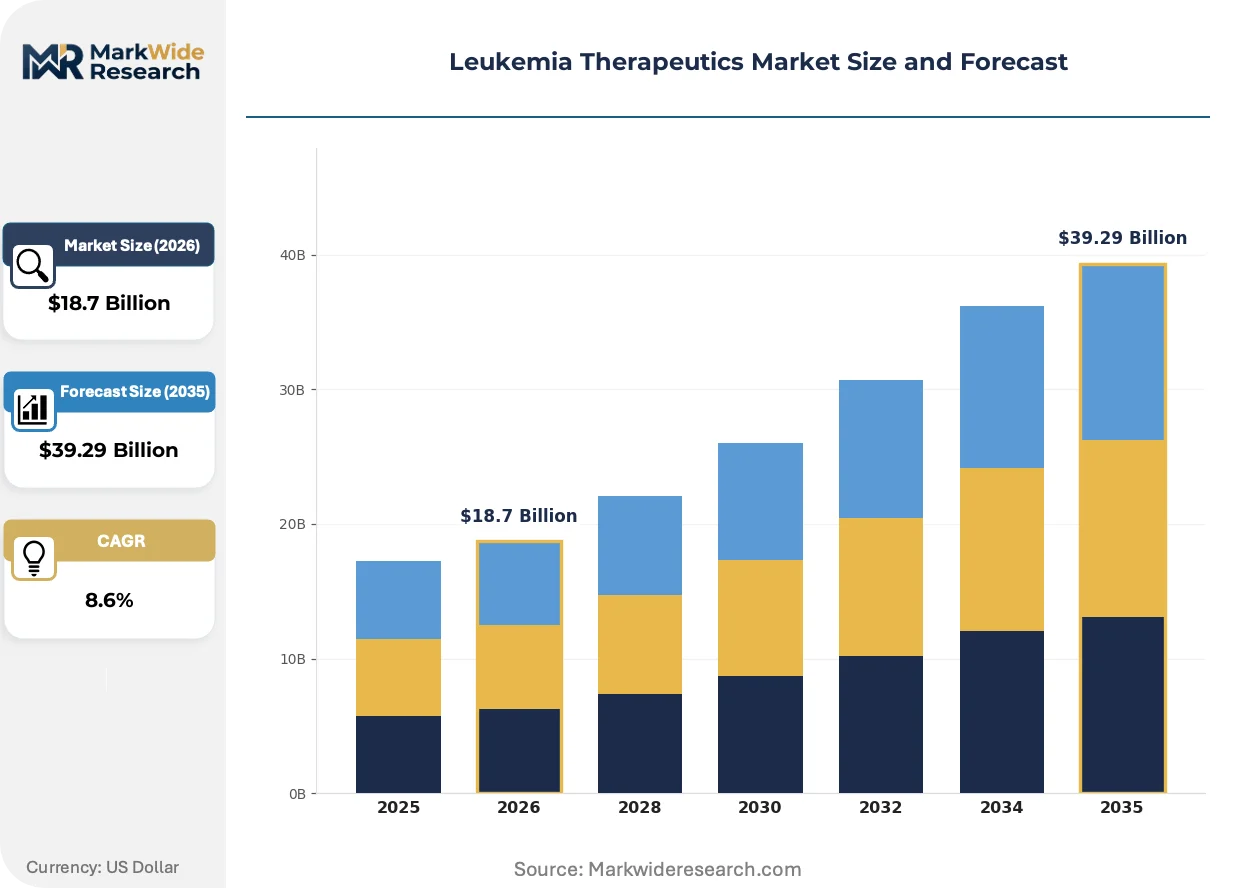
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Stem Cell Transplant End User: Hospitals, Oncology Clinics, Research Institutions, Home Healthcare Therapy Area: Acute Lymphoblastic Leukemia, Chronic Lymphocytic Leukemia, Acute Myeloid Leukemia, Chronic Myelogenous Leukemia Administration Route: Oral, Intravenous, Subcutaneous, Intramuscular |
| Companies Covered | Novartis, Bristol-Myers Squibb, AbbVie, F. Hoffmann-La Roche, Pfizer, Amgen, Sanofi, Gilead Sciences, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leukemia Therapeutics Market Emerging Trajectories
Cell therapy manufacturing automation and in vivo delivery platforms are compressing cost structures while regulatory agencies pilot novel evidentiary frameworks for gene-modified products.
Next-generation CAR constructs incorporating armored receptors and switch mechanisms are consolidating clinical development pipelines around more durable remission profiles. Hematology-oncology departments at academic medical centers in Boston and Houston are adopting these platforms for relapsed acute lymphoblastic leukemia protocols ahead of community hospital diffusion. The technology is consolidating competitive advantage among sponsors with integrated vector biology and cell processing capabilities.
EMA's new ATMP certification pathway for academic and small commercial manufacturers reduces GMP compliance burden for early-phase cell therapy production. The framework enables decentralized manufacturing models that shorten vein-to-vein intervals for autologous products. France and Germany are piloting mutual recognition agreements under this scheme, with hospital-based facilities in Paris and Heidelberg securing first certifications.
Hospital pharmacy and therapeutics committees are tightening prior authorization requirements for high-cost cell therapies, substituting step-therapy protocols and outcomes-based contracts for traditional fee-for-service reimbursement. United States payers including Medicare Advantage plans and large employer groups are deploying this approach most aggressively, with some requiring documented minimal residual disease positivity before CAR-T approval.
Leukemia Therapeutics Market Segmentation
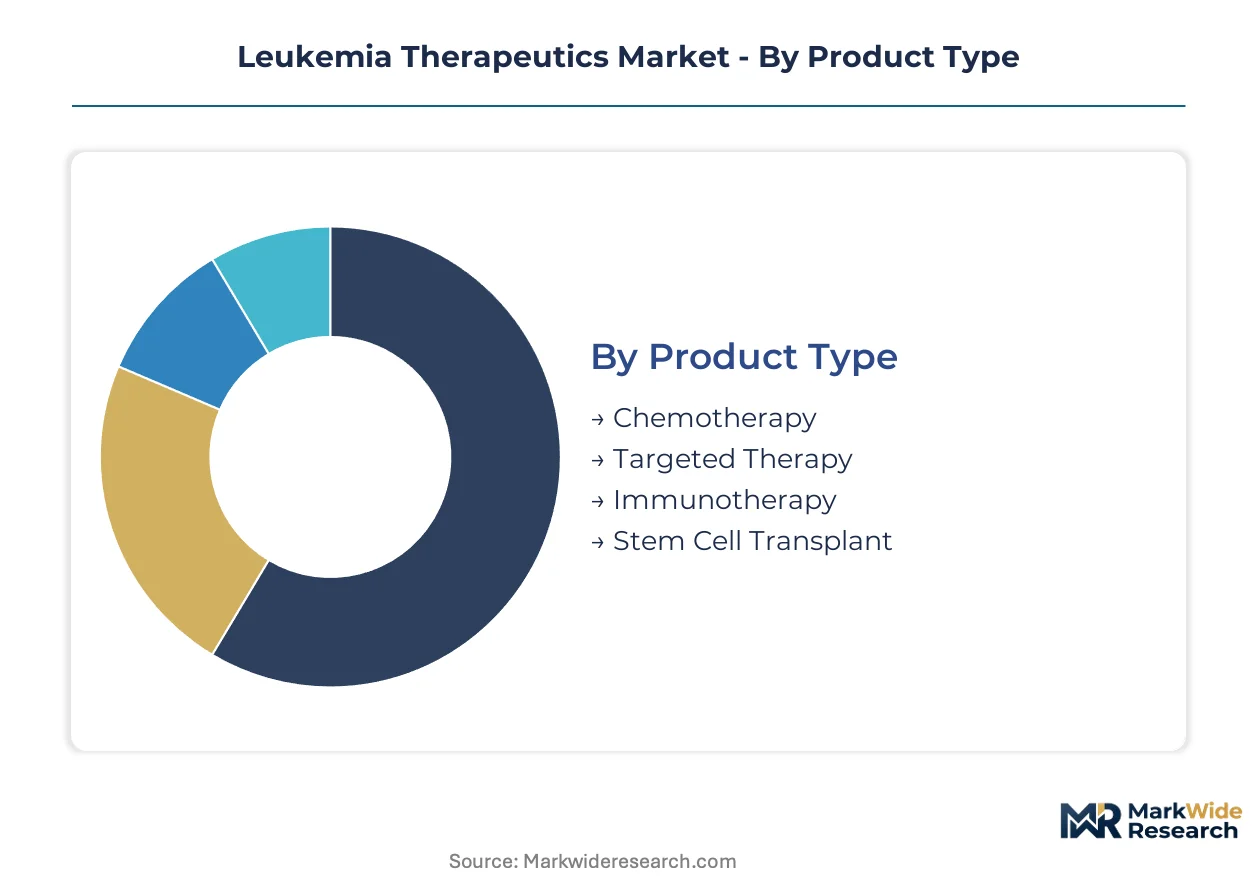
Therapeutic modality selection in leukemia treatment follows distinct clinical pathways driven by disease biology, patient fitness, and reimbursement architecture. Each segmentation axis reveals how capital allocation, regulatory positioning, and manufacturing infrastructure concentrate across the value chain.
Product Type:
Cost tier differentiation separates acute induction protocols from chronic maintenance regimens, with manufacturing complexity and reimbursement intensity diverging sharply across modalities.
- Targeted Therapy:Small-molecule kinase inhibitors including BCR-ABL and BTK inhibitors deliver precision blockade of oncogenic signaling with oral bioavailability. Demand concentrates in chronic lymphocytic and myelogenous leukemia populations where prolonged daily dosing sustains pharmacy revenue. Pricing power reflects biomarker-defined patient selection and resistance-profile differentiation.
- Immunotherapy:CAR-T cell products and bispecific antibodies redirect immune effector function against CD19 and BCMA targets. Manufacturing at tertiary academic centers in Boston, Houston, and Philadelphia limits access to transplant-eligible patients with relapsed acute lymphoblastic leukemia. Vector supply constraints and cryogenic logistics compress margins despite premium reimbursement.
- Chemotherapy:Cytotoxic induction regimens combine anthracyclines, cytarabine, and alkylating agents as backbone therapy for acute myeloid leukemia.
- Stem Cell Transplant:Allogeneic and autologous hematopoietic cell replacement remains curative standard for high-risk disease.
Volume sits with chemotherapy; growth tilts toward immunotherapy.
End User:
Site-of-care capabilities determine which therapeutic modalities reach specific patient populations, with infrastructure investment creating tiered access boundaries.
- Hospitals:Tertiary academic medical centers with FACT-accredited transplant programs administer cellular therapies and complex induction protocols. Concentration in designated cancer centers across Germany, Japan, and the United States restricts CAR-T access to urban referral networks. CMS new technology add-on payments and DRG carve-outs sustain capital intensity.
- Oncology Clinics:Community-based infusion centers deliver oral targeted therapy monitoring and maintenance chemotherapy. Patient volume flows to networks with integrated pharmacy benefit management and prior authorization expertise. Flatiron Health data partnerships enable outcomes-based contracting with commercial payers.
- Research Institutions:NCI-designated comprehensive cancer centers conduct Phase I/II trials for novel construct evaluation.
- Home Healthcare:Oral kinase inhibitor dispensing and remote monitoring expand through specialty pharmacy networks.
Patient volume concentrates in hospitals; expansion is accelerating fastest in oncology clinics.
Therapy Area:
Disease biology and addressable population size create divergent competitive intensity across hematologic malignancy types.
- Acute Lymphoblastic Leukemia:Pediatric and adult B-cell malignancies drive CAR-T commercialization with tisagenlecleucel and brexucabtagene autoleucel approvals. CD19-directed therapy demand clusters at pediatric oncology centers and young adult programs. Minimal residual disease negativity rates determine payer authorization thresholds.
- Chronic Lymphocytic Leukemia:BTK inhibitor and BCL-2 antagonist combinations displace chemoimmunotherapy in frontline and relapsed settings. Ibrutinib, acalabrutinib, and zanubrutinib compete on cardiovascular toxicity profiles and CNS penetration. Fixed-duration venetoclax combinations reshape treatment economics.
- Acute Myeloid Leukemia:FLT3 and IDH inhibitor combinations address molecularly defined subpopulations with hypomethylating agent backbones.
- Chronic Myelogenous Leukemia:BCR-ABL tyrosine kinase inhibitor generations maintain deep molecular response as treatment endpoint.
Revenue concentrates in chronic lymphocytic leukemia; pipeline investment is climbing fastest in acute myeloid leukemia.
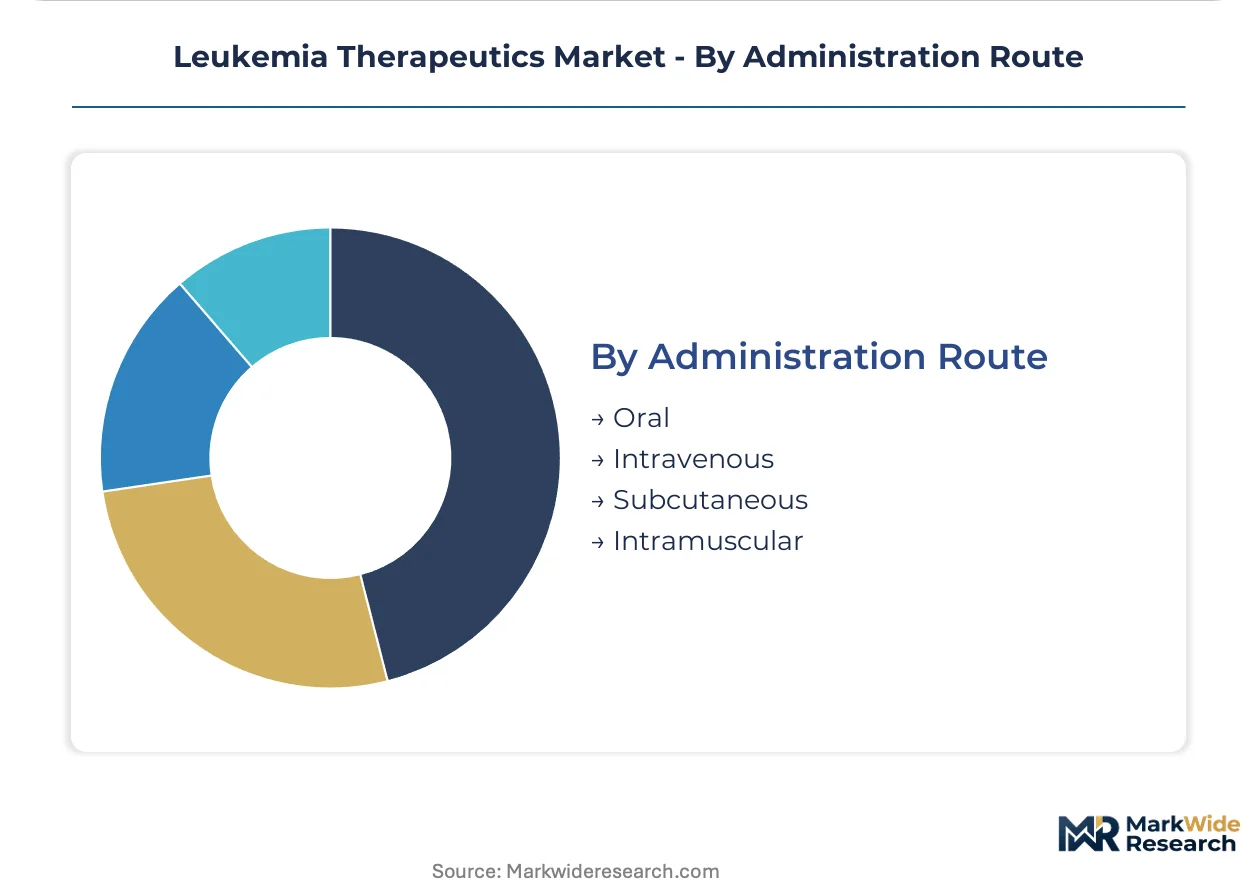
Administration Route:
Delivery mechanism shapes site-of-care economics, patient compliance, and manufacturing infrastructure requirements.
- Intravenous:Infusion-dependent monoclonal antibodies, cytotoxics, and cellular products require specialized nursing and adverse event monitoring. Hospital outpatient departments capture reimbursement premiums for complex biologics. Cold chain and compounding pharmacy investments create entry barriers.
- Oral:Kinase inhibitors and hormone modulators enable community dispensing with specialty pharmacy oversight. Patient assistance programs and copay accumulator regulations shape access dynamics. Adherence monitoring through digital therapeutics platforms is gaining traction.
- Subcutaneous:Monoclonal antibody formulations reduce infusion chair time and nursing costs.
- Intramuscular:Limited application for supportive care agents and depot formulations.
Dose volume sits with intravenous; patient convenience preference is expanding oral share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan as these countries host the highest density of Phase III CAR-T trials and specialized leukemia treatment centers. Regulatory pathways and manufacturing infrastructure create tiered access boundaries that shape regional competitive positioning.
United States
FDA breakthrough therapy designation compresses development timelines for CAR-T programs, with sponsors front-loading manufacturing capacity investments at tertiary academic centers. Medicare Advantage plans and large employer groups deploy outcomes-based contracts requiring documented minimal residual disease positivity prior to CAR-T authorization. Boston, Houston, and Philadelphia anchor the highest concentration of FACT-accredited transplant programs administering cellular therapies.
Germany
EMA's ATMP certification pathway for academic and small commercial manufacturers reduces GMP compliance burden for early-phase cell therapy production. Hospital-based facilities in Heidelberg secure first certifications under pilot mutual recognition agreements with France. The country's hematology-oncology departments expand adoptive cell therapy protocols through decentralized manufacturing models that shorten vein-to-vein intervals.
Japan
PMDA's Sakigake designation offers reduced data requirements and dedicated consultation for regenerative medicines, creating regulatory arbitrage for early entrants in cell therapy development. The priority review system accelerates market access for breakthrough hematologic oncology products. Tokyo and Osaka metropolitan areas concentrate specialized leukemia treatment centers with cryogenic cold chain infrastructure for autologous cell products.
United Kingdom
NHS England's Cancer Drugs Fund enables conditional reimbursement for novel leukemia therapeutics pending real-world evidence generation. The Early Access to Medicines Scheme compresses time-to-patient for promising CAR-T constructs in relapsed acute lymphoblastic leukemia. London and Cambridge clusters integrate next-generation sequencing-based minimal residual disease testing into treatment-intensification protocols.
China
NMPA harmonization with ICH E6(R2) guidelines proceeds alongside maintained local manufacturing requirements that shape regional supply strategies for cell therapies. Domestic CD19-directed CAR-T developers leverage cost advantages in vector production and cell processing platforms. Beijing and Shanghai academic medical centers pilot allogeneic off-the-shelf platforms to extend access beyond urban referral networks.
Leukemia Therapeutics Market Vendor Landscape
Swiss and American producers anchor the premium-tier cell therapy segment; German and Japanese specialists hold positions in targeted small-molecule and monoclonal antibody platforms. Market structure consolidates around integrated vector biology capabilities and captive manufacturing infrastructure. Three archetypes dominate: pioneers with first-mover CAR-T manufacturing scale, dual-platform immunotherapy houses combining checkpoint inhibition with cell therapy, and targeted therapy specialists competing on resistance-profile differentiation. Capacity expansion and strategic partnerships constitute the dominant competitive moves reshaping participant positioning.
Within the pioneer archetype, Novartis and Bristol-Myers Squibb exemplify integrated cell therapy scale. Novartis leverages pioneering CAR-T manufacturing infrastructure to sustain leadership positions in relapsed acute lymphoblastic leukemia. Bristol-Myers Squibb anchors its market presence through dual immunotherapy platforms spanning checkpoint inhibition and cell therapy. AbbVie occupies a differentiated position within the targeted therapy tier, competing across chronic lymphocytic leukemia lines of therapy via small-molecule combination approaches.
| Leading Market Players |
|---|
| Novartis |
| Bristol-Myers Squibb |
| AbbVie |
| F. Hoffmann-La Roche |
| Pfizer |
| Amgen |
| Sanofi |
| Gilead Sciences |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up plasma-derived raw material specialists anchor the supply base for cell culture media, translating single-source concentration into premium pricing power for lentiviral vector inputs while forcing CAR-T sponsors to accept cost-plus contracts with limited renegotiation leverage.
Pricing Analysis
Premium pricing for short lead times on cryopreserved autologous cell products commands substantial markups over standard vein-to-vein scheduling, with tertiary academic centers in Boston and Houston extracting differential rates based on FACT accreditation tier and integrated apheresis capacity. Pricing stratifies across premium CAR-T constructs, standard bispecific antibody infusions, and economy-tier chemotherapy backbones, with quality-grade differentiation tied to minimal residual disease negativity rates and progression-free survival benchmarks. Cost compression in the chemotherapy tier is intensifying because of biosimilar entry and payer step-therapy mandates, while cell therapy pricing remains insulated due to manufacturing complexity and site-of-care scarcity. Community oncology clinics exhibit the highest price sensitivity, constrained by prior authorization requirements and outcomes-based contract exposure, whereas designated cancer centers with captive transplant programs demonstrate the lowest sensitivity due to DRG carve-out protection and new technology add-on payments.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Indian plasma fractionators for serum and growth factor inputs, with vector manufacturing capacity concentrated among a handful of contract manufacturers in the United States and Germany. Lentiviral vector production, cryogenic cold chain logistics, and specialized apheresis equipment represent critical input dependencies that tether supply security to geopolitical stability and customs clearance harmonization. Tariff exposure on Chinese-sourced cell culture media components creates margin volatility for sponsors without backward integration into captive vector biology platforms. Distribution runs through hospital-based pharmacy and therapeutics committees at tertiary academic centers, with limited penetration into community oncology settings due to infrastructure requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over lentiviral vector manufacturing and cryogenic logistics infrastructure determines margin capture and site-of-care access expansion.
For Market Incumbents: Anticipate vector supply bottlenecks by securing long-term offtake agreements with contract manufacturers or building in-house GMP facilities in Heidelberg and Boston clusters, while defending against allogeneic off-the-shelf platform disruption through accelerated next-generation CAR construct development. Prioritize certification investment under EMA's ATMP pathway to lock in decentralized manufacturing advantages before mutual recognition agreements expand competitor access. For New Entrants and Emerging Players: Launch via Japan's Sakigake designation pathway to exploit regulatory arbitrage and reduced data requirements for regenerative medicines, targeting community oncology clinics excluded from autologous programs through allogeneic donor-derived cell therapy platforms. Penetrate the acute myeloid leukemia indication fastest, where pipeline investment is climbing and competitive intensity remains lower than in saturated acute lymphoblastic leukemia segments. For Investors and Strategic Acquirers: Distressed-cycle entries favor vector biology specialists with captive manufacturing infrastructure in the United States and Germany, where capacity scarcity and clinical trial queue dependencies create durable competitive moats. Monitor post-market confirmatory trial readouts as the critical inflection signal, with FDA accelerated approval withdrawal mechanisms capable of reversing revenue trajectories and reshaping portfolio risk calculations abruptly.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Closed-system bioreactor deployment at tertiary centers in Boston and Houston expands CAR-T access capacity. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines and front-loads confirmatory investment requirements. |
| Backward Integration | In-house lentiviral vector production eliminates queue dependencies and secures IND-enabling study timelines. |
| Licensing Agreement | Allogeneic platform partnerships with academic medical centers extend reach beyond urban referral networks. |
| Pipeline Diversification | Next-generation CAR constructs with armored receptors address resistance mechanisms in relapsed acute lymphoblastic leukemia. |
Methodological Framework
Independent corroboration across drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers underwrites the qualitative findings, with secondary validation drawing from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation reconcile segmentation outputs across treatment line, administration route, and regional regulatory cluster dimensions.
Rate-of-change decomposition separates volume expansion from price-mix effects across the analysis window, with CAGRs derived from segmented patient population forecasts and therapy penetration assumptions. The analytical framework incorporates biomarker-defined eligibility rates, site-of-care capacity constraints, and payer authorization threshold evolution as leukemia-specific forecast inputs throughout the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for allogeneic off-the-shelf platforms would alter the outlook if manufacturing cost structures compress faster than anticipated or if FDA confirmatory requirements tighten. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
North America Gene Therapy Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
Cell and Gene Supply Chain Services Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Automated and Closed Cell Therapy Processing Systems Market
Cell & Gene Therapy
Oncolytic Virus Cancer Therapy Market
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
Viral Vector Production (Research-Use) Market
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Cell Therapy Contract Development and Manufacturing Organization Market