
 Global T-Cell Lymphoma Market | 2026-2036
Global T-Cell Lymphoma Market Size, Share, and Industry Trends Forecast 2026-2036
Global T-Cell Lymphoma Market Foresight
Oncology clinics and specialty infusion centers is reorganizing treatment demand away from general hospital settings as outpatient administration of monoclonal antibodies and immunotherapy expands. Bristol Myers Squibb anchors its position through deep vertical integration in cell therapy manufacturing. Novartis leverages its CAR-T infrastructure to compete across peripheral T-cell lymphoma indications. Gilead Sciences specializes in targeted small-molecule portfolios that complement its cell therapy assets.
T-cell lymphoma comprises a heterogeneous group of non-Hodgkin lymphomas arising from mature T-cell or natural killer-cell lineages, characterized by clonal proliferation of post-thymic lymphocytes with CD3, CD4, or CD8 surface marker expression; these malignancies require histopathologic confirmation via immunohistochemistry and flow cytometry for accurate subtyping and treatment selection. Monoclonal antibodies command the highest margin pools among product types due to premium pricing and orphan drug exclusivity, while immunomodulators represent the fastest-expanding category as checkpoint inhibitors and cytokine modulators gain label extensions across cutaneous and peripheral subtypes. Peripheral T-cell lymphoma dominates therapy area volume, though anaplastic large cell lymphoma attracts disproportionate R&D investment driven by ALK-targeted therapy development.
The FDA's accelerated approval framework and the EMA's PRIME designation scheme both compress development timelines for novel T-cell lymphoma therapeutics, while Japan's PMDA Sakigake designation channels early access to innovative oncology products. These regulatory pathways shape demand by enabling earlier commercialization of breakthrough therapies, though post-marketing confirmatory trial obligations create reimbursement uncertainty. Stakeholders must monitor evolving payer evidence requirements across the FDA, EMA, and PMDA as conditional approvals mature and health technology assessments tighten.
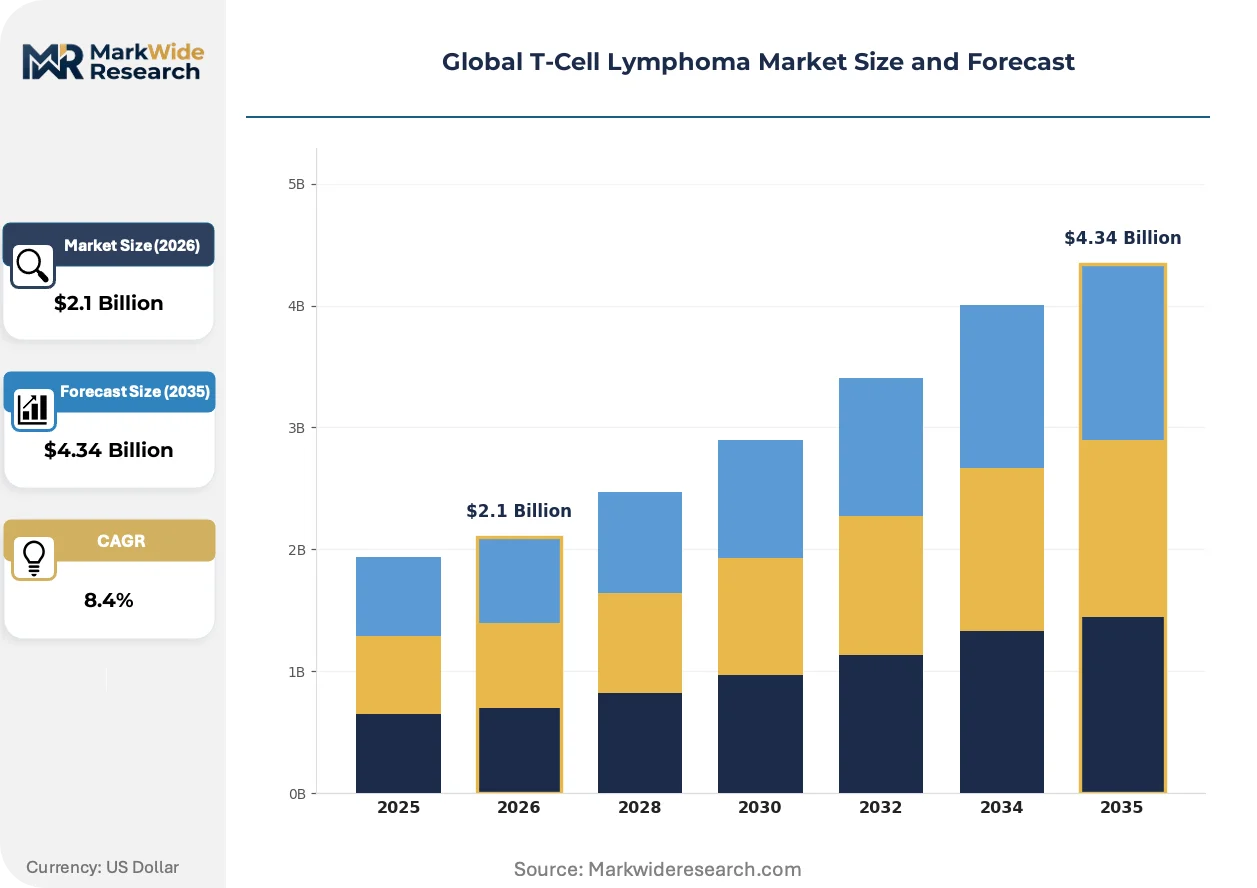
Market Dynamics
The FDA's accelerated approval pathway is compressing commercial timelines for novel T-cell lymphoma therapeutics, forcing manufacturers to front-load manufacturing capacity and payer engagement before confirmatory data matures.
Growth Catalysts
- Orphan drug exclusivity frameworks:The FDA's orphan drug designation and EMA's PRIME scheme compress regulatory review periods for peripheral T-cell lymphoma indications, enabling earlier revenue recognition for developers.
- Academic medical center expansion:Leading oncology centers in the United States, Germany, and Japan are building dedicated cellular therapy infrastructure to handle autologous CAR-T administration.
- Biomarker-driven patient stratification:ALK and CD30 testing protocols are sharpening eligibility criteria for targeted therapies, improving response rates and justifying premium positioning.
Market Restraints
- Plasma-derived raw material volatility:Human serum albumin and recombinant cytokine supply concentrate among a limited base of European and North American suppliers, creating input cost pressure.
- Viral vector manufacturing bottleneck:Lentiviral and retroviral vector production capacity remains structurally constrained, throttling cell therapy expansion regardless of clinical demand.
- Post-marketing confirmatory trial obligations:The FDA's accelerated approval framework mandates ongoing studies that create reimbursement uncertainty and payer hesitation.
Strategic Opportunities
- Japan's PMDA Sakigake pathway:Early access designation for innovative oncology products enables first-mover positioning in the world's third-largest pharmaceutical market.
- Outpatient administration infrastructure:Specialty infusion centers are displacing hospital-based delivery, opening channel expansion for subcutaneous and short-infusion regimens.
- Checkpoint inhibitor combinations:PD-1 and CTLA-4 blockade paired with chemotherapy backbone is creating new label expansion opportunities across cutaneous T-cell lymphoma subtypes.
Industry Challenges
- Cell therapy manufacturing workforce scarcity:Qualified aseptic processing technicians and vector production specialists command premium compensation, constraining operational scale-up.
- Health technology assessment divergence:Germany's IQWiG, England's NICE, and France's HAS apply inconsistent evidentiary standards, fragmenting European market access strategy.
- Cold chain integrity requirements:Cryopreserved cellular products demand specialized logistics infrastructure that remains underdeveloped in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global T-Cell Lymphoma Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antineoplastics, Immunomodulators, Monoclonal Antibodies, Chemotherapy Agents, Biosimilars Therapy Area: Cutaneous T-Cell Lymphoma, Peripheral T-Cell Lymphoma, Anaplastic Large Cell Lymphoma, Adult T-Cell Leukemia Lymphoma End User: Hospitals, Oncology Clinics, Specialty Clinics, Diagnostic Laboratories, Research Institutes Delivery Mode: Intravenous Injection, Oral Administration, Subcutaneous Injection, Immunotherapy, Targeted Therapy |
| Companies Covered | Bristol Myers Squibb, Novartis, Gilead Sciences, Johnson & Johnson, Citius Pharma, Acrotech Biopharma, Daiichi Sankyo Company, Merck & Co., Innate Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global T-Cell Lymphoma Market Shifts & Advancements
Next-generation sequencing and real-world evidence platforms are decomposing traditional clinical trial architectures, enabling faster biomarker validation and adaptive label expansion across T-cell lymphoma subtypes.
Allogeneic or "off-the-shelf" CAR-T platforms are decomposing the autologous manufacturing model that has dominated cell therapy. Biotech developers and contract manufacturers are investing in donor-derived T-cell banks and gene-editing infrastructure to compress vein-to-vein timelines from weeks to days. This shift threatens to collapse the premium pricing power of patient-specific products.
REACH authorization requirements for novel chemical entities are tightening impurity profiling standards for small-molecule lymphoma therapeutics manufactured in European facilities. The EMA's expanded mandate on genotoxic impurities is forcing reformulation of established histone deacetylase inhibitors and forcing sponsors to relocate active pharmaceutical ingredient synthesis to qualified third-party sites.
Site-of-care economics are driving purchasing consolidation among integrated delivery networks in the United States. Oncology clinics and hospital outpatient departments are unbundling drug acquisition from administration services, pressuring manufacturers to justify spread pricing through outcomes guarantees. This behavioral shift is most pronounced in Medicare Advantage–dominated markets where risk-bearing entities control referral patterns.
Global T-Cell Lymphoma Market Segmentation
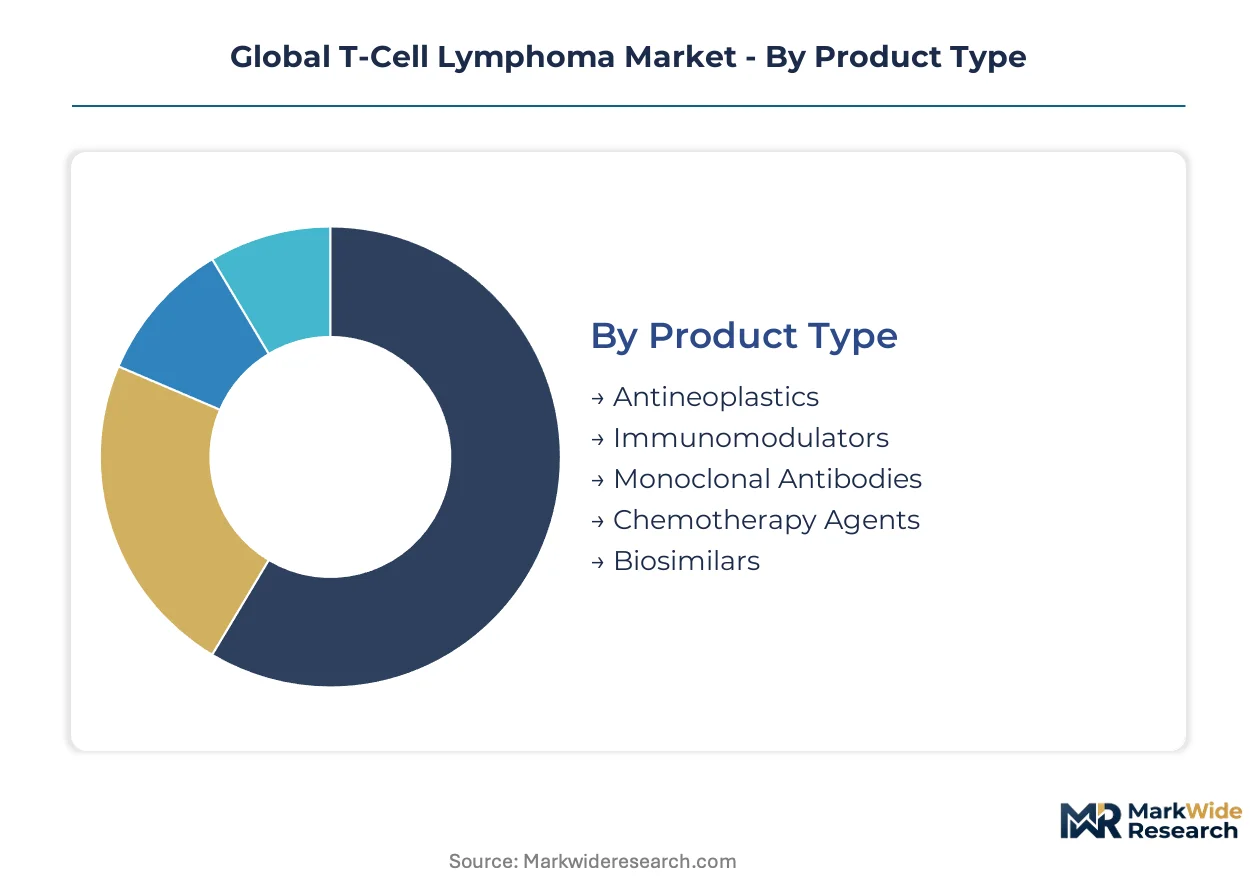
T-cell lymphoma's molecular heterogeneity demands precise therapeutic matching across product classes and administration settings. Each segment carries distinct margin profiles, regulatory pathways, and infrastructure requirements that shape commercial strategy.
Product Type:
Margin pools concentrate in biologic modalities where orphan exclusivity sustains premium positioning, while small-molecule generics face commoditization pressure.
- Monoclonal Antibodies:Engineered immunoglobulins targeting CD30, CD52, or CCR4 surface markers with high specificity and extended half-lives. Demand clusters in United States academic medical centers where prior authorization infrastructure supports premium reimbursement, though payer scrutiny intensifies for off-label extensions.
- Immunomodulators:Cytokine modulators and checkpoint inhibitors that reconstitute anti-tumor immunity through PD-1 or CTLA-4 blockade. Germany's IQWiG assessments create access friction despite clinical efficacy, forcing manufacturers to generate Germany-specific health economic evidence.
- Antineoplastics:Cytotoxic agents including purine analogs and alkylating compounds with established reimbursement codes.
- Chemotherapy Agents:Platinum-based and anthracycline regimens serving as combination backbones.
- Biosimilars:Follow-on biologics entering as reference products lose exclusivity in European and Japanese markets.
The dominant share belongs to Monoclonal Antibodies, while Immunomodulators are gaining share fastest through label expansions across cutaneous and peripheral subtypes.
Therapy Area:
Volume distribution tracks disease prevalence, but R&D investment disproportionately targets molecularly defined subtypes with druggable alterations.
- Peripheral T-Cell Lymphoma:Aggressive nodal malignancies encompassing multiple subtypes with poor prognosis under conventional chemotherapy. Japan's PMDA Sakigake designation has accelerated approval of novel agents here, creating early-access revenue windows before European or United States launches.
- Anaplastic Large Cell Lymphoma:ALK-positive and ALK-negative variants distinguished by chromosomal rearrangements and CD30 expression. ALK inhibitor development in United States and European trials is reshaping first-line protocols, with companion diagnostic mandates tightening eligibility criteria.
- Cutaneous T-Cell Lymphoma:Mycosis fungoides and Sézary syndrome variants managed through skin-directed and systemic approaches.
- Adult T-Cell Leukemia Lymphoma:HTLV-1-associated malignancy with endemic concentration in southwestern Japan and Caribbean basin.
Peripheral T-Cell Lymphoma commands the largest patient pool, though Anaplastic Large Cell Lymphoma exhibits the steepest expansion trajectory in pipeline investment.
End User:
Site-of-care migration is redistributing purchasing authority from inpatient pharmacy committees to outpatient specialty networks.
- Oncology Clinics:Dedicated cancer centers administering infused and injectable therapies in ambulatory settings. United States Medicare Advantage penetration is consolidating referrals into risk-bearing oncology networks that negotiate drug acquisition directly, bypassing hospital markup structures.
- Hospitals:Inpatient and outpatient departments managing complex cases with comorbidities requiring admission. Germany's DRG-based reimbursement creates disincentives for extended stays, pushing stable patients toward affiliated day clinics.
- Specialty Clinics:Focused infusion centers handling monoclonal antibody administration.
- Diagnostic Laboratories:Flow cytometry and molecular testing facilities supporting subtype classification.
- Research Institutes:Academic centers conducting early-phase clinical trials.
Oncology Clinics now capture the dominant share of administration volume, while Specialty Clinics are expanding capacity fastest through dedicated infusion infrastructure.
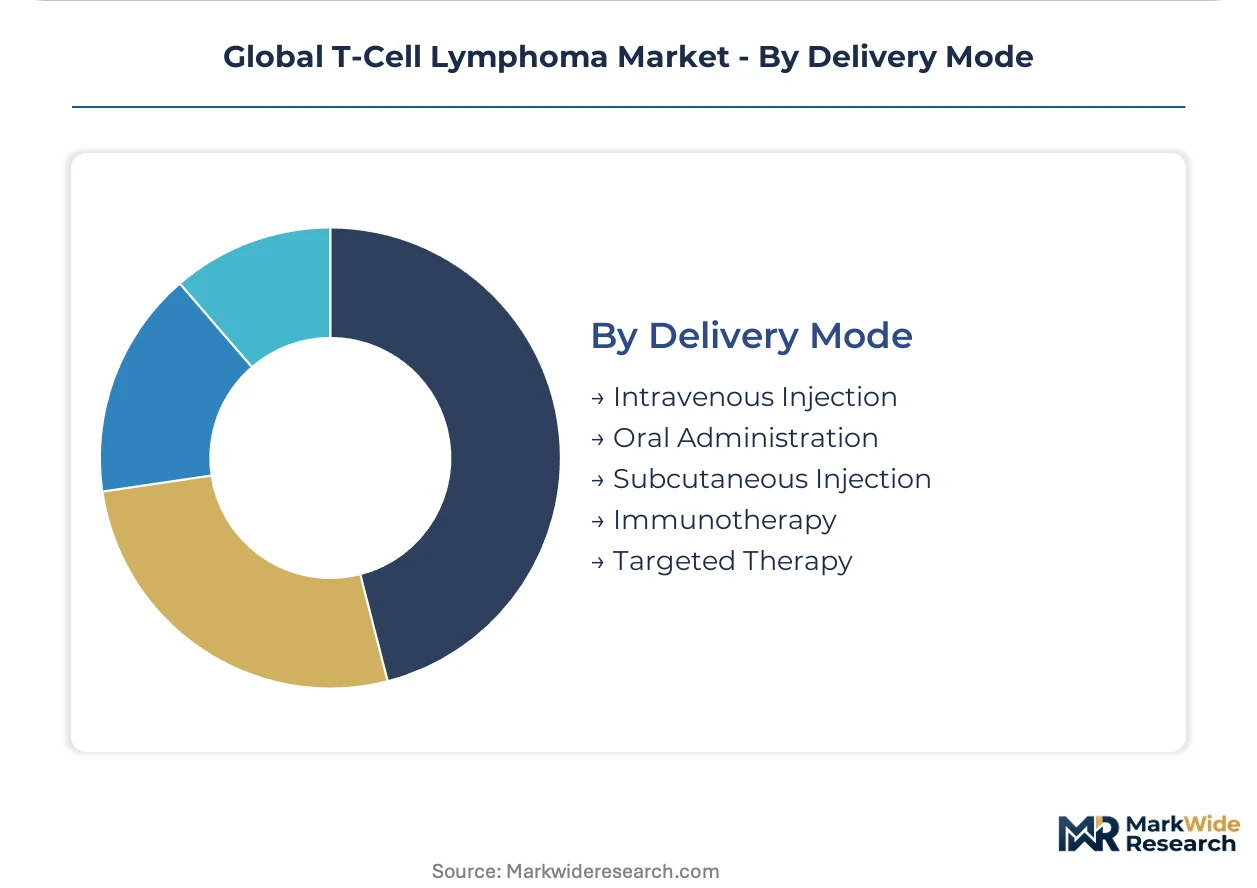
Delivery Mode:
Administration convenience is becoming a competitive differentiator as oral and subcutaneous alternatives challenge intravenous dominance.
- Intravenous Injection:Infusion-based delivery of monoclonal antibodies, chemotherapy, and cellular therapies requiring specialized nursing and monitoring. Cold chain requirements and cryopreserved CAR-T logistics limit this mode to tertiary centers in United States, Germany, and Japan with validated handling protocols.
- Targeted Therapy:Small-molecule inhibitors with oral bioavailability and specific kinase or epigenetic targets. Japan's PMDA has prioritized review of oral agents enabling outpatient management, reducing hospital dependency for chronic therapy.
- Oral Administration:Histone deacetylase inhibitors and other small molecules with home-based dosing.
- Subcutaneous Injection:Reformulated monoclonal antibodies reducing administration time and facility requirements.
- Immunotherapy:Cellular products and immune engagers with complex manufacturing and handling needs.
Intravenous Injection retains the dominant share for biologics and cellular therapies, though Targeted Therapy is climbing fastest through oral small-molecule launches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized immunomodulator compounds to United States oncology networks, while Japan's PMDA Sakigake designation accelerates early-access shipments of novel T-cell therapeutics to Asian markets.
United States
FDA's accelerated approval pathway compresses commercial timelines for peripheral T-cell lymphoma therapeutics, while Medicare Advantage penetration consolidates referrals into risk-bearing oncology networks. Academic medical centers in Boston and Houston are building dedicated CAR-T manufacturing infrastructure to handle autologous cellular therapy administration.
Germany
EMA's PRIME designation scheme channels early regulatory attention toward innovative lymphoma biologics, though IQWiG health technology assessments create reimbursement friction for immunomodulators. The Rhine-Ruhr corridor hosts concentrated pharmaceutical manufacturing capacity for monoclonal antibody production serving European distribution.
Japan
PMDA's Sakigake designation enables priority review timelines for novel T-cell lymphoma agents, creating first-mover revenue windows before Western launches. Tokyo and Osaka academic centers lead regional adoption of biomarker-driven patient stratification protocols for ALK-targeted therapy selection.
United Kingdom
NICE technology appraisals apply stringent cost-effectiveness thresholds to new lymphoma therapeutics, forcing manufacturers to generate England-specific health economic evidence. London's Royal Marsden and Manchester's Christie Hospital anchor national cellular therapy infrastructure for CAR-T administration.
India
CDSCO's streamlined oncology approval pathways are shortening timelines for biosimilar monoclonal antibodies targeting CD30 and CCR4 markers. Mumbai and Hyderabad pharmaceutical clusters are expanding contract manufacturing capacity for viral vector production serving global cell therapy developers.
Global T-Cell Lymphoma Market Competitive Landscape
Player mix skews toward integrated biopharmaceutical conglomerates with captive cell therapy manufacturing infrastructure. Market structure concentrates around three strategic archetypes: vertically integrated oncology majors controlling end-to-end CAR-T production, targeted therapy specialists with deep small-molecule portfolios, and emerging biotech developers pursuing allogeneic platform technologies. Dominant competitive moves include backward integration into viral vector manufacturing and strategic partnerships with academic medical centers for real-world evidence generation.
Within the integrated biopharmaceutical tier, Bristol Myers Squibb and Novartis exemplify archetypes combining cellular therapy infrastructure with established oncology commercialization networks. Gilead Sciences occupies a distinct position bridging targeted small-molecule development with cell therapy assets. These three anchors represent contrasting strategic postures: manufacturing control, platform diversification, and portfolio complementarity respectively.
| Leading Market Players |
|---|
| Bristol Myers Squibb |
| Novartis |
| Gilead Sciences |
| Johnson & Johnson |
| Citius Pharma |
| Acrotech Biopharma |
| Daiichi Sankyo Company |
| Merck & Co. |
| Innate Pharma |
| Others |
Supply & Pricing Matrix
Fourteen-day vein-to-vein timelines for autologous CAR-T products concentrate pricing power among United States and German manufacturers with captive viral vector capacity, while plasma-derived input scarcity compresses margins for second-tier developers lacking backward integration into cytokine production.
Pricing Analysis
First-generation CD30-directed monoclonal antibodies command premium positioning against commoditized chemotherapy backbones, while next-generation allogeneic platforms threaten to collapse patient-specific pricing premiums through manufacturing scale. Three-tier pricing structure across cellular therapies, targeted small molecules, and generic chemotherapy regimens reflects divergent reimbursement codes and orphan exclusivity windows. Pricing pressure stems from biosimilar entry in European markets as reference biologics lose patent protection. Hospital outpatient departments exhibit highest price sensitivity due to DRG-based reimbursement caps, while academic medical centers retain negotiating leverage through trial participation.
Supply Chain Analysis
Viral vector manufacturing chokepoints in the United States and European contract development organizations throttle cell therapy expansion regardless of clinical demand. Lentiviral production draws from plasmid DNA sourced from North American suppliers and fetal bovine serum concentrated among Australian and New Zealand processors. Single-source vulnerability in gamma-irradiation sterilization services creates bottleneck risk for cryopreserved cellular products. Distribution runs through validated cold-chain logistics partners serving tertiary oncology centers in Boston, Houston, and the Rhine-Ruhr corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as FDA accelerated approvals compress development timelines and restock pipelines after a period of confirmatory trial setbacks.
For Market Incumbents: Fortify viral vector manufacturing capacity through captive production facilities or exclusive CDMO partnerships to secure supply against emerging allogeneic platform developers. Deepen formulary relationships with Medicare Advantage oncology networks before biosimilar entry erodes monoclonal antibody pricing. Prioritize companion diagnostic co-development to tighten eligibility criteria and defend reimbursement positioning. For New Entrants and Emerging Players: Differentiate on allogeneic or off-the-shelf manufacturing platforms that compress vein-to-vein timelines and undercut autologous premium pricing. Target Japan's PMDA Sakigake pathway for early-access revenue windows before Western regulatory submissions. Pursue subcutaneous formulation development to access specialty infusion center channels displacing hospital-based delivery. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because cell therapy manufacturing infrastructure scarcity will drive rollup activity as pipelines mature. Acquisition targets with validated viral vector production and academic medical center partnerships command strategic premium. Watch FDA confirmatory trial readouts as inflection indicators for reimbursement durability.| Strategic Initiative | Industry Significance |
|---|---|
| Allogeneic Platform Development | Off-the-shelf CAR-T manufacturing threatens to collapse autologous pricing premiums through scale economics. |
| Companion Diagnostic Co-Development | ALK and CD30 testing mandates sharpen eligibility criteria and defend targeted therapy reimbursement positioning. |
| Viral Vector Manufacturing Scale-Up | Captive lentiviral production capacity insulates against CDMO bottlenecks throttling cell therapy expansion. |
| Japan PMDA Sakigake Registration | Priority review timelines create first-mover revenue windows in the world's third-largest pharmaceutical market. |
| Subcutaneous Formulation Investment | Reduced administration time opens specialty infusion center channels displacing hospital-based delivery. |
Research Methodology
A spread of perspectives from cell therapy manufacturing executives, regulatory affairs leads at oncology developers, hospital formulary directors, and payer access specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA accelerated approval filings, EMA PRIME designations, ClinicalTrials.gov protocols, and hospital procurement databases. Bottom-up patient-flow modeling and top-down revenue triangulation anchored volume and value estimates.
Segmentation dimensions modeled include product type, therapy area, end-user setting, and delivery mode across the analysis window. CAGRs derived from treatment-line expansion curves, label extension probabilities, and site-of-care migration patterns. Forecast inputs incorporated biomarker testing adoption rates, manufacturing capacity buildouts, and conditional approval conversion rates.
Material uncertainties — confirmatory trial failures, reimbursement reversals, and viral vector supply disruptions — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as regulatory evidence requirements and health technology assessment criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
Gene Panel Market
Cell & Gene Therapy
Asia-Pacific Gene Therapy Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Autologous Stem Cell and Non Stem Cell Based Therapies Market
Cell & Gene Therapy
North America Gene Therapy Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Osteoarthritis Gene Therapy Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Global Cancer Vaccine Market
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
RNA Therapy Clinical Trials Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Europe Gene Therapy Market