
 Global Cell and Gene Therapy Manufacturing Services Market | 2026-2036
Global Cell and Gene Therapy Manufacturing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cell and Gene Therapy Manufacturing Services Market Foresight
Plasmid DNA is repositioning viral vectors as the dominant starting material for gene therapy production, reducing cost-of-goods and shortening batch release cycles. Lonza leverages its global footprint to anchor clinical-to-commercial manufacturing transitions across three continents. Catalent sustains competitive intensity through specialized viral vector capacity in Maryland and Belgium. Thermo Fisher Scientific controls upstream raw material supply, extending its influence from plasmid sourcing through fill-finish services.
Cell and gene therapy manufacturing services encompass the outsourced production, testing, and regulatory preparation of patient-specific or donor-derived biological medicines, requiring ISO 5-7 cleanroom environments, cryogenic supply chains maintaining below minus 150 degrees Celsius, and vector titers exceeding 10 to the 14th viral particles per batch. The primary commercial purpose is converting laboratory-scale genetic constructs into reproducible clinical and commercial doses that meet pharmacopeial sterility, potency, and identity standards. Process development and commercial manufacturing command the deepest margin pools, while analytical testing is expanding fastest as regulators tighten release criteria for replication-competent virus. CAR-T technology dominates current capacity allocation, though CRISPR-based allogeneic platforms are attracting disproportionate investment for their off-the-shelf scalability potential.
The FDA's gene therapy CMC guidance, EMA's ATMP certification pathways, and Japan's PMDA regenerative medicine framework collectively determine facility design standards, batch release timelines, and market access eligibility across major jurisdictions. Compliance with these evolving standards shapes capital allocation decisions, with manufacturers prioritizing dual FDA-EMA inspection readiness to avoid supply disruptions. Stakeholders must monitor regulatory divergence between adaptive trial frameworks and fixed commercial specifications, as this tension will determine which CDMO platforms capture long-term biopharmaceutical outsourcing contracts.
Market Dynamics
Plasmid DNA manufacturing is electrifying capacity planning across the cell and gene therapy services sector, compressing viral vector dependency timelines and forcing CDMOs to reconfigure upstream bioreactor suites around bacterial fermentation rather than mammalian cell culture platforms.
Growth Catalysts
- FDA Streamlined CMC Guidance:The FDA's gene therapy chemistry, manufacturing, and controls framework accelerates facility qualification timelines, reducing batch release delays for CAR-T sponsors seeking commercial readiness.
- Allogeneic Platform Scaling:CRISPR-based off-the-shelf cell therapies attract disproportionate capital allocation, creating pull-through demand for standardized master cell banks and closed-system bioprocessing equipment.
- Singapore Cold-Chain Clustering:Specialized logistics infrastructure around Changi Biomedical Park anchors regional distribution for cryogenic therapies requiring below minus 150 degrees Celsius stability.
Market Restraints
- Plasmid Supply Concentration:High-quality supercoiled plasmid DNA production concentrates among a limited supplier base, exposing CDMOs to raw material bottlenecks during batch scale-up.
- EMA ATMP Certification Friction:The European Medicines Agency's advanced therapy medicinal product pathway imposes divergent facility standards from FDA requirements, complicating dual-inspection readiness investments.
- Replication-Competent Virus Testing Burden:Regulator-mandated analytical release criteria for replication-competent lentivirus extend quality control timelines, constraining batch throughput at commercial scale.
Strategic Opportunities
- Japan Regenerative Medicine Framework:PMDA's conditional approval pathway for gene therapies creates first-mover advantages for CDMOs establishing GMP-compliant capacity in Kansai and Kanto regions.
- Automated Closed-System Convergence:Integration of single-use bioreactors with artificial intelligence process control enables distributed manufacturing models that reduce cleanroom infrastructure intensity.
- In-Vivo Gene Editing Applications:Lipid nanoparticle delivery of base editors opens service opportunities beyond ex vivo cell modification, attracting ophthalmology and CNS therapeutic developers.
Industry Challenges
- Vector Bioprocess Engineer Scarcity:Specialized expertise in adherent cell culture, transfection optimization, and harvest recovery operations remains concentrated among a limited talent pool, inflating compensation costs.
- ISO 5-7 Cleanroom Capex Intensity:Facility qualification for combined cell therapy and viral vector production requires segregated air handling systems, extending capital deployment timelines beyond 36 months.
- Cross-Border Cryogenic Logistics Integration:Harmonizing temperature excursion protocols between US, Swiss, and Singaporean regulatory jurisdictions creates operational complexity for multi-site manufacturing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cell and Gene Therapy Manufacturing Services Market |
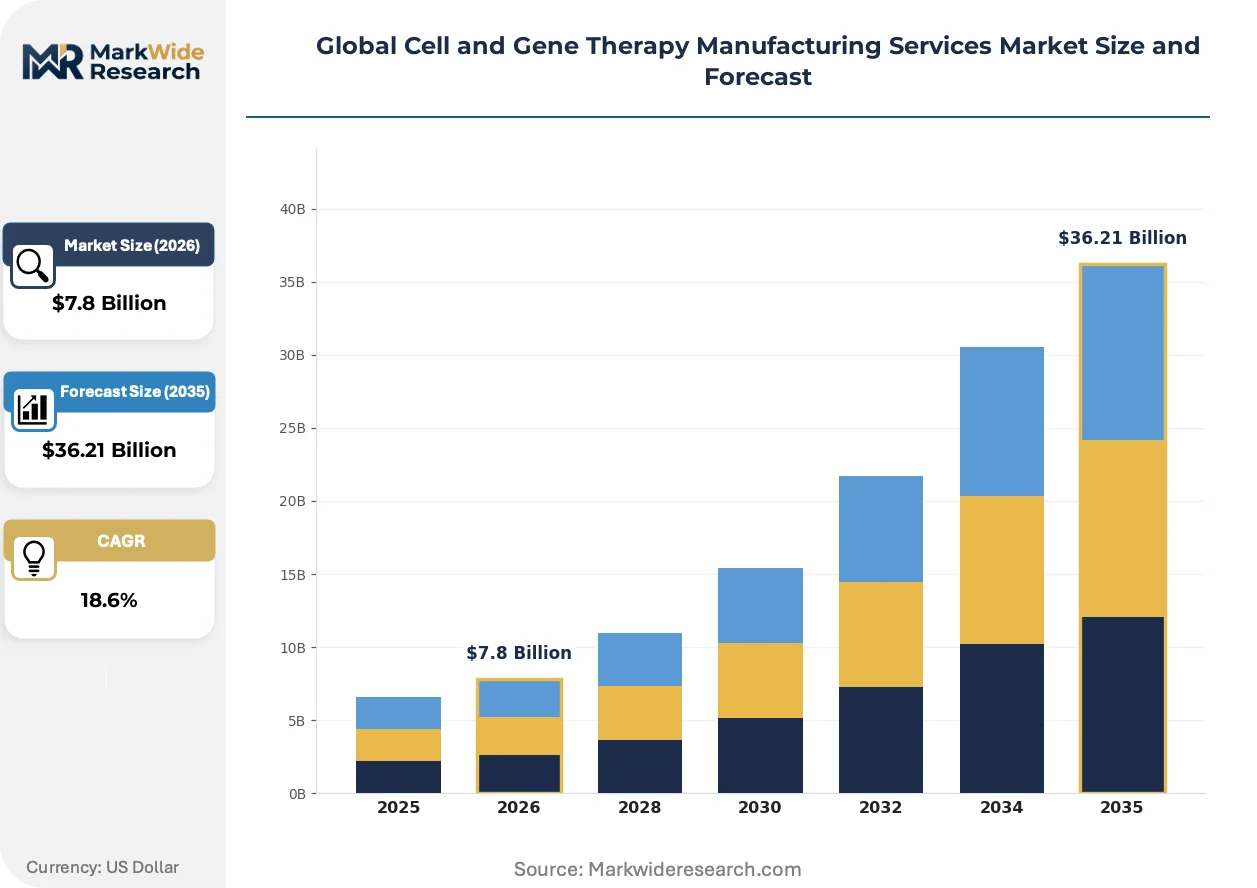
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $36.21 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Process Development, Clinical-Scale Manufacturing, Commercial Manufacturing, Analytical Testing, Regulatory Support Technology: Viral Vector, Non-Viral Vector, CRISPR, TALEN, ZFN, CAR-T Therapy Area: Oncology, Rare Genetic Disorders, Immunology, Neurology, Cardiovascular Diseases, Hematology End User: Biopharmaceutical Companies, Research Institutes, Contract Development Organizations, Academic Hospitals |
| Companies Covered | Lonza, Catalent, Thermo Fisher Scientific, Charles River Laboratories, Merck KGaA, FUJIFILM Diosynth Biotechnologies, WuXi AppTec, Oxford Biomedica, Cell and Gene Therapy Catapult, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cell and Gene Therapy Manufacturing Services Market Shifts & Advancements
Continuous manufacturing modalities and real-time release testing are compressing traditional batch-oriented paradigms, forcing CDMOs to retrain quality organizations around process analytical technology rather than end-point testing.
Suspension-adapted AAV production platforms are electrifying viral vector economics, enabling 2,000-liter bioreactor scales that were technically inaccessible with adherent HEK293 systems. Gene therapy sponsors in ophthalmology and neurology are adopting these platforms fastest, demanding CDMO partners with demonstrated suspension titers exceeding 10 to the 14th viral particles per batch. The structural consequence is a bifurcation in the CDMO landscape between legacy adherent-capable facilities and new-build suspension-dedicated sites.
The FDA's guidance on long-term follow-up for gene therapies mandates 15-year patient monitoring databases, compelling CDMOs to integrate pharmacovigilance infrastructure directly into manufacturing service agreements. This regulatory architecture elevates total cost-of-ownership calculations for sponsors, pushing mid-cap biotechs toward risk-sharing partnerships rather than fee-for-service arrangements. Pediatric and ultra-rare disease indications face the steepest compliance burden under this framework.
Biopharmaceutical procurement organizations are consolidating manufacturing service contracts around platform CDMOs capable of spanning plasmid sourcing through fill-finish, displacing fragmented multi-vendor strategies. Large-cap gene therapy developers in the United States and Switzerland are driving this consolidation, using master service agreements to lock capacity across clinical-to-commercial transitions. The shift is most visible in CAR-T programs where supply security concerns outweigh unit cost optimization.
Global Cell and Gene Therapy Manufacturing Services Market Segmentation
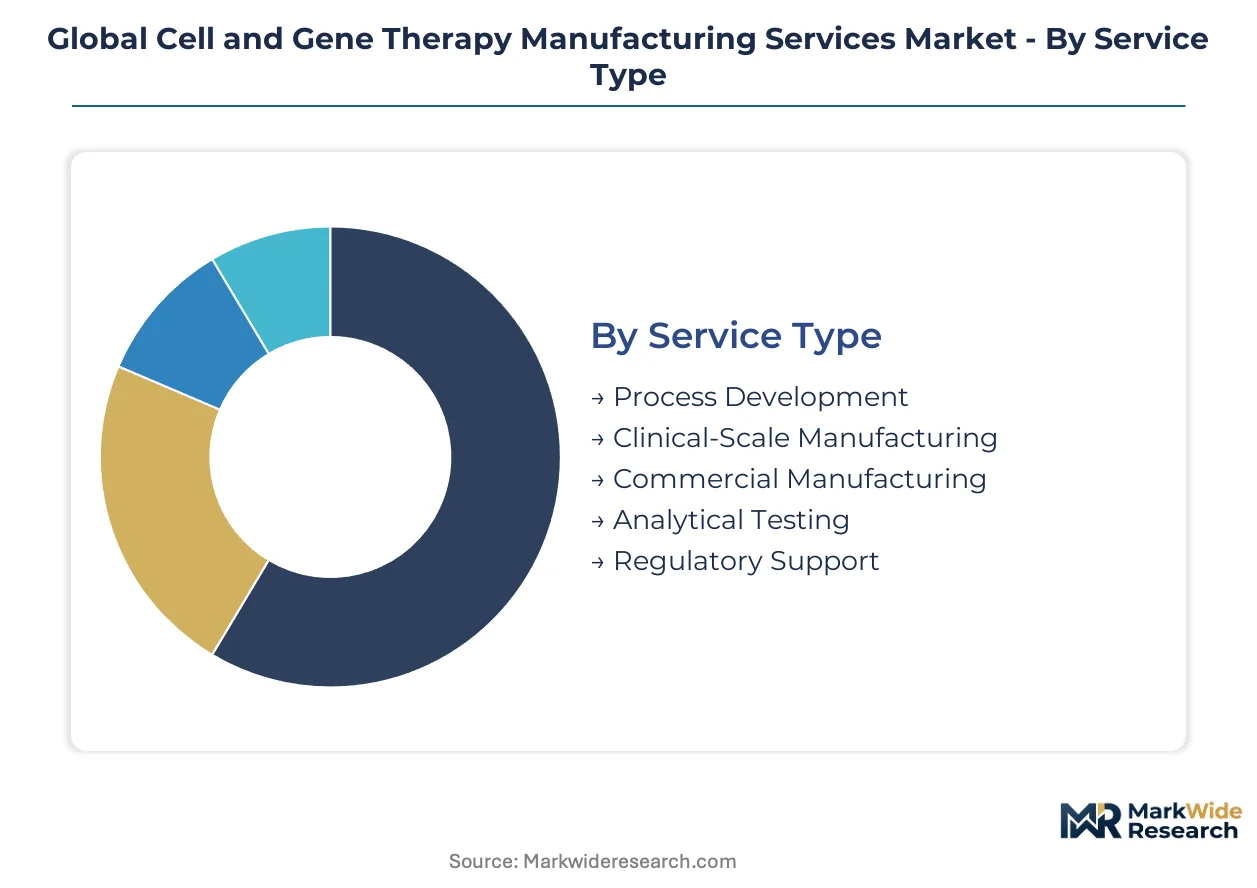
Service specialization determines margin capture in cell and gene therapy manufacturing, with process development and commercial manufacturing commanding premium pricing while analytical testing expands fastest under tightening regulatory release criteria. CDMOs configure facility footprints around specific segment combinations rather than pursuing horizontal coverage across all service categories.
Service Type:
Supply concentration clusters around commercial manufacturing capacity, where ISO 5-7 cleanroom infrastructure and dual FDA-EMA inspection readiness create defendable competitive moats for established operators.
- Process Development:Cell line engineering, transfection optimization, and scale-up validation for viral vector titers exceeding 10 to the 14th particles per batch. Demand concentrates among US biopharmaceutical sponsors preparing IND submissions, driven by FDA streamlined CMC guidance compressing timeline risk.
- Clinical-Scale Manufacturing:GMP production of Phase I/II materials with adaptive batch sizing for patient-specific autologous therapies. Sponsors in Switzerland prioritize Swissmedic-aligned facilities to anchor European trial expansion from US-developed assets.
- Commercial Manufacturing:Validated production at 2,000-liter bioreactor scale with 15-year pharmacovigilance database integration per FDA long-term follow-up mandates.
- Analytical Testing:Replication-competent lentivirus detection, potency assays, and sterility verification extending quality control timelines.
- Regulatory Support:CMC documentation, facility qualification protocols, and agency correspondence management spanning FDA, EMA, and PMDA jurisdictions.
Today's leader: Commercial Manufacturing. Tomorrow's challenger: Analytical Testing.
Technology:
Cost tier differentiation separates legacy adherent platforms from suspension-adapted systems, with capital intensity bifurcating sponsor preferences between established HEK293 workflows and higher-yield AAV production.
- Viral Vector:AAV, lentiviral, and retroviral delivery systems produced via adherent or suspension culture. Ophthalmology and neurology sponsors in the United States adopt suspension platforms fastest, demanding CDMO partners with demonstrated 2,000-liter scale capabilities.
- Non-Viral Vector:Lipid nanoparticle and electroporation-based delivery reducing immunogenicity risk for in vivo gene editing applications.
- CRISPR:Guide RNA design, RNP complex assembly, and HDR/NHEJ efficiency optimization for allogeneic cell engineering. Singapore-based CDMOs attract disproportionate CRISPR platform investment due to cold-chain clustering around Changi Biomedical Park.
- TALEN:Transcription activator-like effector nucleases for targeted gene disruption with reduced off-target profiles.
- ZFN:Zinc finger nuclease platforms with established regulatory precedent in HIV-resistant cell therapies.
- CAR-T:Chimeric antigen receptor T-cell manufacturing dominating current capacity allocation with patient-specific autologous workflows.
CAR-T absorbs the deepest capacity share. CRISPR-based allogeneic platforms are climbing the fastest as off-the-shelf scalability attracts capital reallocation.
Therapy Area:
Application maturity varies sharply, with oncology commanding established reimbursement pathways while neurology and cardiovascular indications face longer development horizons.
- Oncology:Hematologic malignancy targeting via CAR-T and TCR-T platforms with validated clinical endpoints. US and Swiss sponsors concentrate manufacturing demand around CDMOs with commercial release experience.
- Rare Genetic Disorders:Single-gene correction for monogenic diseases with small patient populations and premium pricing tolerance. EMA ATMP certification friction complicates dual-inspection readiness for European rare disease programs.
- Immunology:Autoimmune modulation via engineered regulatory T-cells and CAR-Treg platforms.
- Neurology:CNS-targeted gene delivery for Parkinson's, ALS, and Huntington's disease via AAV9 and engineered capsids.
- Cardiovascular Diseases:Angiogenic factor delivery and cardiomyocyte regeneration therapies.
- Hematology:Sickle cell disease and beta-thalassemia correction via CRISPR-edited stem cells.
Oncology maintains revenue concentration. Rare Genetic Disorders show the steepest expansion trajectory as regulatory pathways mature for ultra-small populations.
End User:
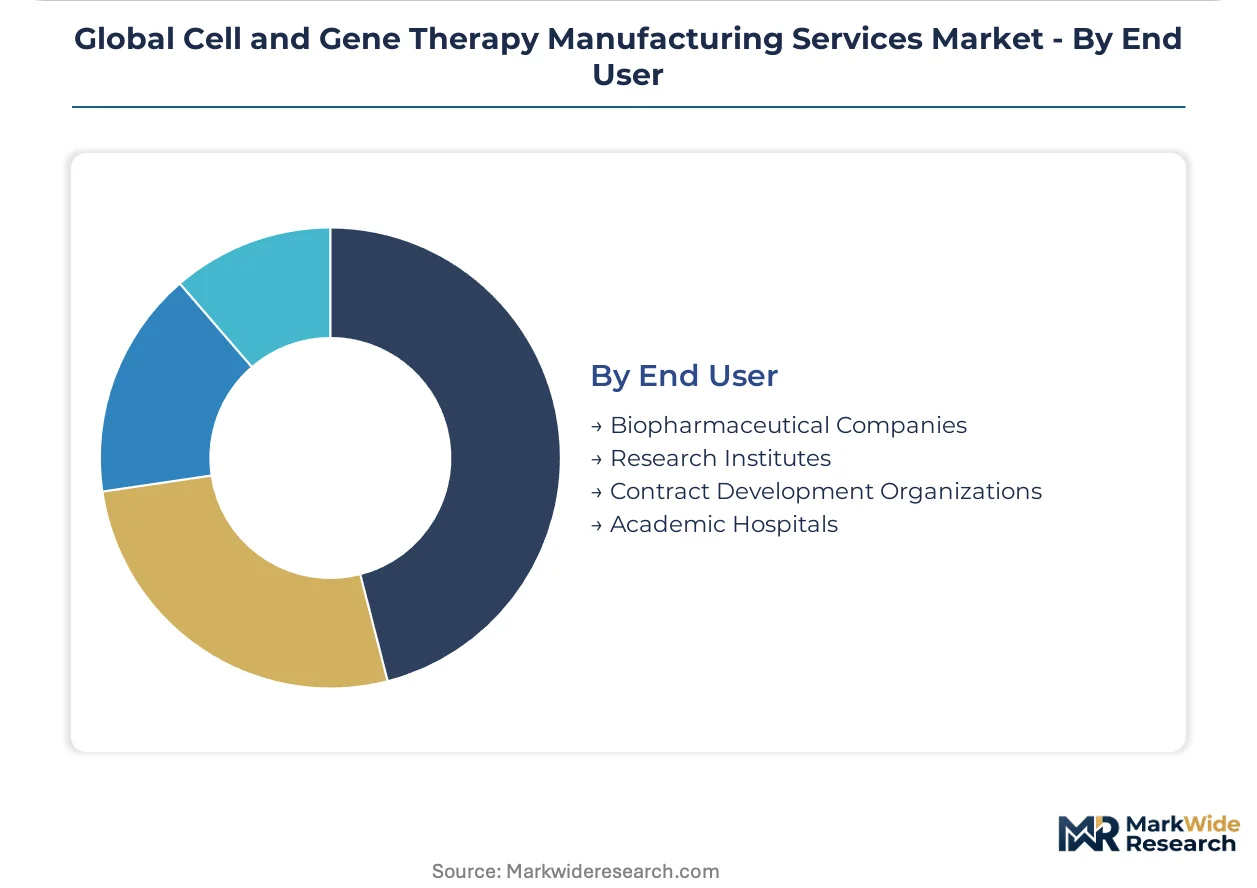
Customer type shapes contract structure, with large-cap biopharmaceuticals consolidating around platform CDMOs while research institutes fragment demand across specialized analytical providers.
- Biopharmaceutical Companies:Integrated clinical-to-commercial manufacturing with master service agreements locking capacity across plasmid sourcing through fill-finish. US and Switzerland-based developers drive consolidation, prioritizing supply security over unit cost.
- Research Institutes:Early-phase process development and non-GMP vector production for exploratory programs. Japan's Kansai and Kanto regions attract institute demand under PMDA conditional approval frameworks.
- Contract Development Organizations:Subcontracted analytical testing and regulatory support from manufacturing-focused CDMOs lacking in-house capabilities.
- Academic Hospitals:Point-of-care manufacturing for investigator-initiated trials with institutional GMP facilities.
Biopharmaceutical Companies anchor contract value. Academic Hospitals are gaining share fastest as decentralized manufacturing models reduce cold-chain dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Changi Biomedical Park anchors cold-chain logistics infrastructure for cryogenic therapies requiring sub-minus 150 degrees Celsius stability. Singapore's cluster attracts disproportionate CRISPR platform investment from sponsors seeking Asia-Pacific distribution hubs. The United States, Switzerland, and Germany concentrate regulatory expertise and commercial manufacturing capacity.
United States
FDA streamlined CMC guidance accelerates facility qualification timelines for CAR-T sponsors seeking commercial readiness. The agency's 15-year pharmacovigilance mandate for gene therapies elevates total cost-of-ownership calculations. Maryland and Greater Boston anchor viral vector capacity expansion among CDMOs targeting ophthalmology and neurology sponsors.
Switzerland
Swissmedic-aligned facilities attract US sponsors anchoring European trial expansion from domestically developed assets. The country's dual FDA-EMA inspection readiness prioritization shapes capital allocation decisions. Basel-Zurich corridor CDMOs lock capacity through master service agreements spanning clinical-to-commercial transitions.
Germany
EMA ATMP certification friction complicates dual-inspection readiness investments for rare disease programs. The country's central European location enables distribution reach across member states with divergent facility standards. Heidelberg and Munich clusters concentrate adherent cell culture expertise for legacy viral vector platforms.
Singapore
PMDA-aligned regulatory positioning creates first-mover advantages for CDMOs establishing GMP-compliant capacity with Japan market access. Changi Biomedical Park's specialized logistics infrastructure anchors regional distribution for cryogenic therapies. Government biomedical manufacturing incentives attract CRISPR-based allogeneic platform investment.
Japan
PMDA's conditional approval pathway for gene therapies creates procurement urgency among sponsors targeting accelerated market entry. The Kansai and Kanto regions attract research institute demand under regenerative medicine frameworks. Tokyo-Osaka corridor facilities prioritize pharmacovigilance infrastructure integration per long-term follow-up mandates.
Global Cell and Gene Therapy Manufacturing Services Market Competitive Landscape
Global majors compete with regional champions across regulatory jurisdiction coverage and cold-chain infrastructure density. The market structure consolidates around platform CDMOs capable of spanning plasmid sourcing through fill-finish, displacing fragmented multi-vendor strategies. Three archetypes dominate: integrated life science conglomerates with raw material supply control, specialized viral vector pure-plays with suspension platform capabilities, and regional champions with single-jurisdiction regulatory depth. Capacity expansion and strategic partnerships represent the dominant competitive moves, with sponsors locking manufacturing slots through long-term master service agreements.
Among integrated conglomerates, Thermo Fisher Scientific exemplifies upstream-to-downstream supply chain control, while Lonza occupies a position spanning three continents with clinical-to-commercial transition anchoring. Catalent represents the specialized viral vector tier with Maryland and Belgium facility clustering. These three names illustrate how competitive positioning stratifies between raw material dominance, geographic footprint breadth, and therapeutic modality specialization.
| Leading Market Players |
|---|
| Lonza |
| Catalent |
| Thermo Fisher Scientific |
| Charles River Laboratories |
| Merck KGaA |
| FUJIFILM Diosynth Biotechnologies |
| WuXi AppTec |
| Oxford Biomedica |
| Cell and Gene Therapy Catapult |
| Others |
Supply & Pricing Matrix
Vector bioprocess engineer scarcity in the United States and Switzerland inflates compensation costs across ISO 5-7 cleanroom operations, widening spreads between premium FDA-EMA dual-certified facilities and standard single-jurisdiction sites. Labor-cost differentials between these talent-concentrated markets and emerging Singaporean clusters directly shape three-tier pricing stratification across process development, clinical-scale, and commercial manufacturing tiers.
Pricing Analysis
Input-cost pass-through from supercoiled plasmid DNA supply concentration dominates pricing formation, with raw material bottlenecks during batch scale-up compressing margins for CDMOs lacking captive bacterial fermentation capacity. Price differentiation separates premium dual-inspection-ready facilities from standard single-agency sites and economy-tier analytical-only providers. Cost compression in clinical-scale manufacturing is intensifying because sponsor procurement organizations are consolidating contracts around platform CDMOs capable of spanning plasmid sourcing through fill-finish. Mid-cap biotechs exhibit highest price sensitivity, prioritizing risk-sharing partnerships over fee-for-service arrangements, while large-cap developers in the United States and Switzerland prioritize supply security over unit cost optimization.
Supply Chain Analysis
Direct-to-sponsor channels handle commercial-scale demand from large-cap biopharmaceutical developers, while subcontracted analytical testing flows through manufacturing-focused CDMOs lacking in-house capabilities. Supply concentrates in the United States, Switzerland, and Singapore, where specialized CDMO clusters have formed around regulatory expertise and cold-chain logistics infrastructure. Raw material dependencies center on high-quality supercoiled plasmid DNA, viral vector titers exceeding 10 to the 14th particles per batch, and cryogenic supply chains maintaining below minus 150 degrees Celsius. Single-source vulnerability in plasmid supply exposes CDMOs to batch release delays. Distribution runs through master service agreements locking capacity across clinical-to-commercial transitions rather than spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
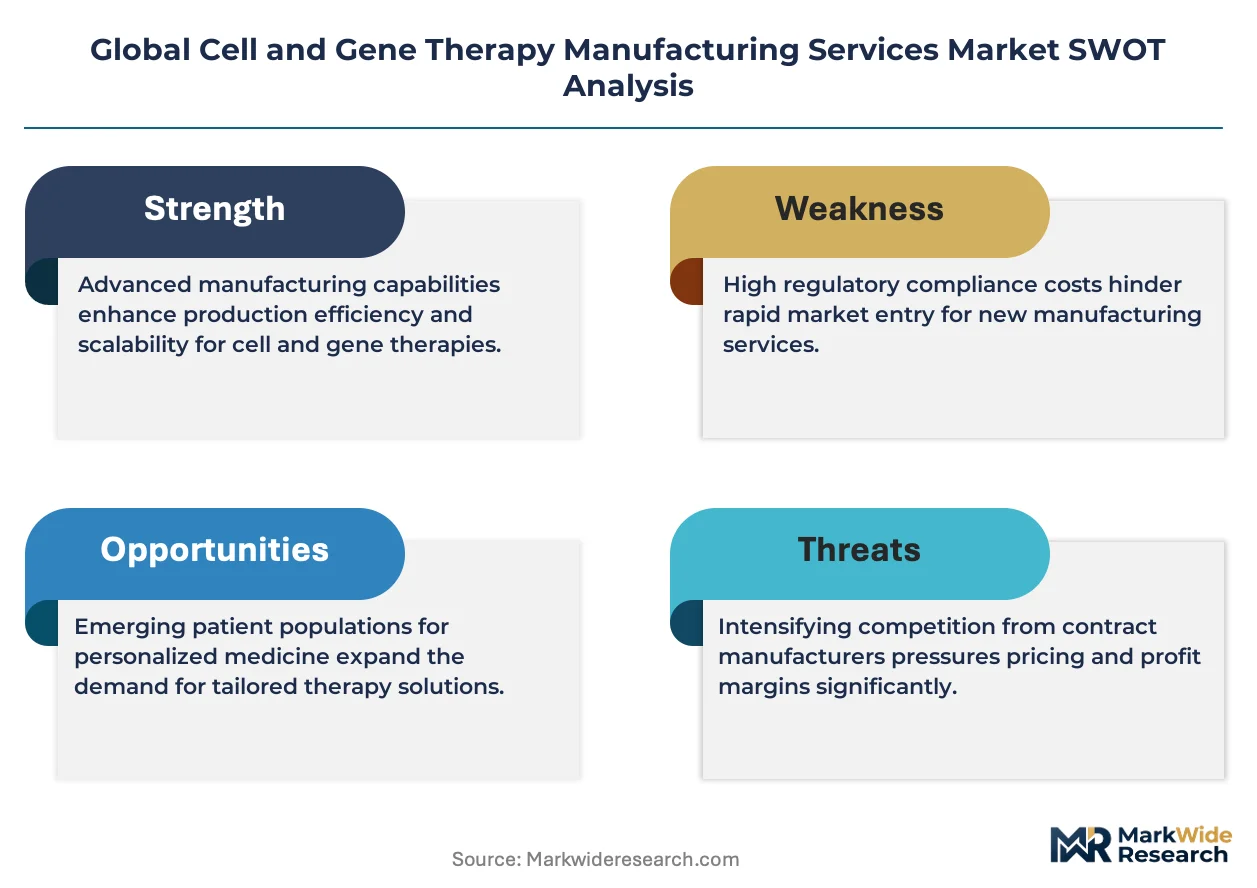
This market reads as a late-cycle quality story. Sponsor procurement organizations are consolidating manufacturing service contracts around platform CDMOs capable of spanning plasmid sourcing through fill-finish, displacing fragmented multi-vendor strategies and elevating specifications for dual FDA-EMA inspection readiness.
For Market Incumbents: Cement defensive positioning through backward integration into plasmid DNA manufacturing and capacity expansion in Singapore's Changi Biomedical Park cluster. Suspension-adapted AAV production platforms from emerging pure-plays threaten legacy adherent-capable facilities. Dual-inspection readiness investments in the Basel-Zurich corridor anchor European trial expansion from US-developed assets. For New Entrants and Emerging Players: Capture white-space in Japan's Kansai and Kanto regions under PMDA's conditional approval pathway for gene therapies. Automated closed-system convergence with artificial intelligence process control enables distributed manufacturing models that reduce cleanroom infrastructure intensity. Target research institute demand from academic hospitals establishing point-of-care manufacturing for investigator-initiated trials. For Investors and Strategic Acquirers: Large-cap biopharmaceutical developers are the most active acquirer in this space, consolidating manufacturing slots through long-term master service agreements to secure supply across clinical-to-commercial transitions. Acquisition targets with demonstrated suspension titers exceeding 10 to the 14th viral particles per batch and integrated pharmacovigilance infrastructure offer strongest long-term viability. Monitor regulatory divergence between adaptive trial frameworks and fixed commercial specifications as the critical inflection indicator for CDMO platform winners.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | 2,000-liter suspension bioreactor deployment enables AAV production economics for ophthalmology sponsors. |
| Regulatory Approval Pathway | PMDA conditional approval framework in Japan accelerates market entry for CRISPR-based allogeneic platforms. |
| Backward Integration | Captive plasmid DNA fermentation reduces raw material bottleneck exposure during commercial batch scale-up. |
| Strategic Partnership | Risk-sharing agreements with mid-cap biotechs displace fee-for-service models under FDA 15-year pharmacovigilance mandates. |
| Geographic Expansion | Singapore facility clustering leverages Changi Biomedical Park cold-chain infrastructure for Asia-Pacific distribution. |
Research Methodology
Multiple input streams — executive interviews with CDMO operations directors and biopharmaceutical procurement leads, regulatory filing analysis across FDA, EMA, and PMDA jurisdictions, and trade data on plasmid DNA and viral vector equipment imports — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from FDA gene therapy CMC guidance documents, EMA ATMP certification pathway records, ClinicalTrials.gov enrollment data, and Swissmedic facility inspection reports.
Historical capacity utilization patterns were cross-referenced against panel input from viral vector manufacturing heads and cell therapy supply chain managers to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include service type, technology platform, therapy area, and end-user category, with CAGRs derived from sponsor pipeline progression rates and CDMO capacity expansion announcements. Forecast inputs incorporated regulatory approval velocity for CAR-T and CRISPR-based allogeneic therapies.
Regulatory divergence between adaptive trial frameworks and fixed commercial specifications, plasmid supply concentration disruptions, and vector bioprocess engineer availability shocks are the dominant revision risks to base-case projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
High Density (HD) Cell Banking Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
RNAI Technology Market
Cell & Gene Therapy
Cell Expansion Market
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market
Cell & Gene Therapy
Ipilimumab Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Gene Delivery Technologies Market
Cell & Gene Therapy
Viral Vector and Plasmid DNA Testing Service Market
Cell & Gene Therapy
Cell and Gene Therapy CDMO Market
Cell & Gene Therapy
Cell Therapy Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Stem Cell Reconstructive Market
Cell & Gene Therapy
Rare Disease Gene Therapy Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market