
 Reed Sensor Market | 2026-2036
Reed Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Reed Sensor Market Analysis
Modular sensor packaging is shifting buyer choice toward integrated reed modules that combine switching, signal conditioning, and connector housings in single units. Standex Electronics specializes in hermetically sealed reed switches for harsh-environment industrial applications. Littelfuse leverages vertical integration into contact material processing to sustain margin pools in automotive-grade products. TE Connectivity anchors its position through broad channel control across aerospace and medical device supply chains.
A reed sensor is a magnetically actuated switching device composed of ferromagnetic contacts hermetically sealed within a glass envelope containing inert gas, typically operating at switching speeds up to 400 Hz with contact resistance below 150 milliohms; its primary purpose is to detect proximity, position, or fluid level without mechanical wear in sealed environments. Magnetic reed switches occupy the largest volume share due to decades of standardization in appliance and security applications, though digital reed sensors represent the fastest structural expansion as microcontroller-integrated outputs displace raw switch signals in IoT endpoints. Reed relays command premium positioning in test and measurement equipment where isolation resistance exceeding 10^12 ohms justifies unit cost multiples over standard configurations.
Europe's REACH regulation and RoHS directives constrain mercury and cadmium content in contact plating, while the EU's F-Gas Regulation indirectly pressures hermetic sealing processes; China's GB/T electromagnetic compatibility standards and SAMR certification requirements shape market access for imported reed components. The US FAA and NHTSA impose reliability benchmarks on aerospace and automotive applications respectively. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's material circularity mandates recast supplier qualification criteria for glass-to-metal seal technologies.
Market Dynamics
Electrified automotive architectures are compressing replacement cycles for position and speed sensing components, forcing reed sensor suppliers to requalify products under stricter electromagnetic compatibility regimes while simultaneously defending margin pools against solid-state alternatives.
Growth Catalysts
- Automotive safety mandates:NHTSA reliability benchmarks for electrified powertrains require redundant position sensing in braking and steering systems, expanding specification volumes for hermetically sealed switches.
- REACH material compliance:ECHA restrictions on mercury and cadmium in contact plating are accelerating R&D into alternative metallurgies that extend operational life in corrosive environments.
- Industry 4.0 integration:Germany's industrial automation corridor is driving replacement demand as precision sensor modules become embedded in predictive maintenance networks.
Market Restraints
- Rare earth magnet cost volatility:Neodymium price swings compress margins for reed switch manufacturers dependent on consistent magnetic field specifications.
- Hermetic sealing concentration:Glass-to-metal seal capabilities cluster among a handful of European and Japanese suppliers, creating single-source vulnerability for aerospace-grade products.
- Solid-state displacement:Hall-effect and magnetoresistive sensors eliminate mechanical contacts entirely, eroding volume share in consumer appliance applications.
Strategic Opportunities
- Medical device miniaturization:Implantable and wearable diagnostic equipment requires sub-miniature reed switches with isolation resistance exceeding 10^12 ohms, commanding premium positioning.
- EU Green Deal circularity:Material recovery mandates for glass and noble metals create first-mover advantage for suppliers with closed-loop plating processes.
- IoT endpoint proliferation:Microcontroller-integrated digital reed outputs are displacing raw switch signals in smart home and building automation networks.
Industry Challenges
- Glassblower craft scarcity:Hermetic envelope manufacturing depends on skilled artisan labor with decade-long training curves, constraining capacity expansion.
- Dual certification timelines:Simultaneous FAA and NHTSA qualification processes for aerospace-autotive crossover products extend time-to-revenue by 18-24 months.
- Legacy system integration:Analog reed outputs require signal conditioning hardware retrofits in digital-native industrial control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reed Sensor Market |
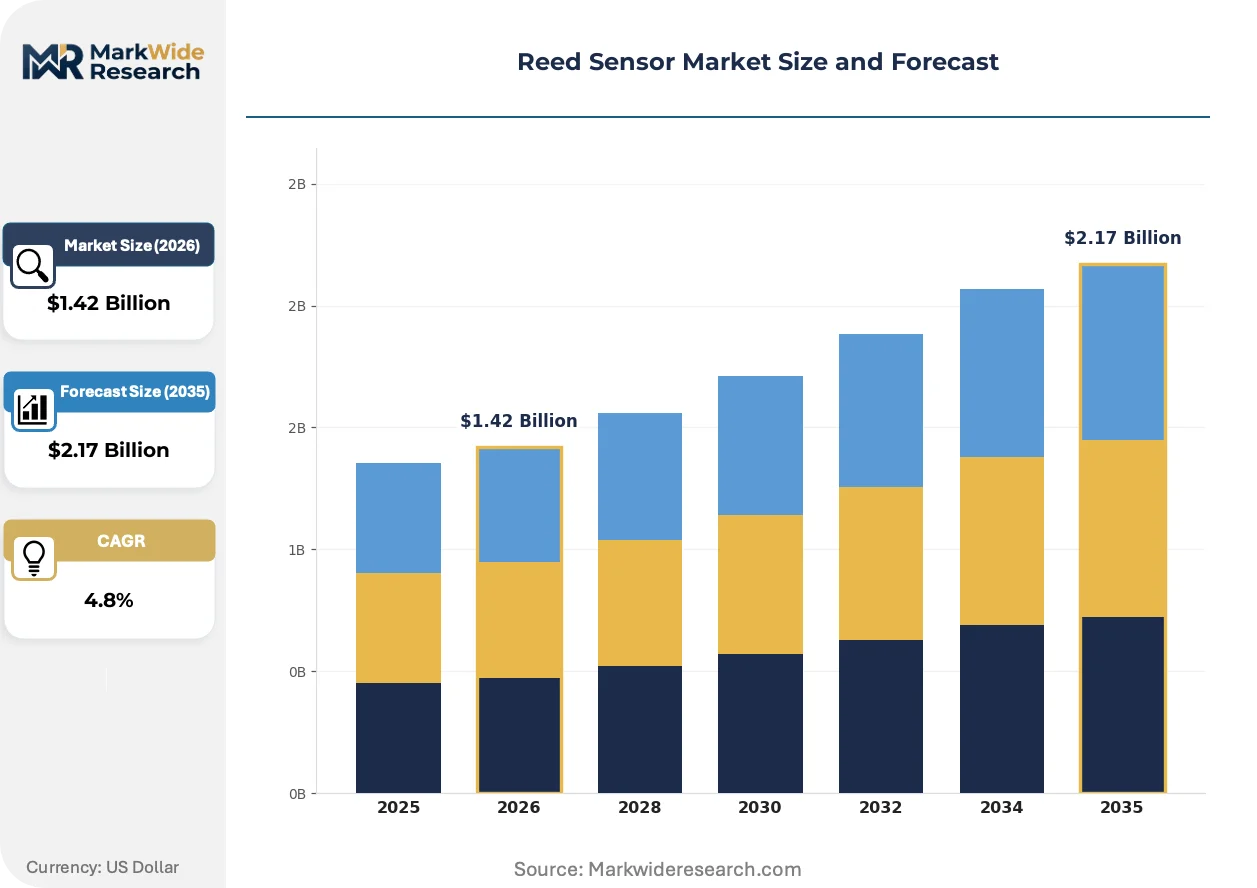
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Reed Switches, Digital Reed Sensors, Analog Reed Sensors, Reed Relays Application: Automotive, Consumer Electronics, Industrial Automation, Healthcare End User: Manufacturers, Distributors, Retailers, Service Providers Connectivity: Wired, Wireless, Hybrid, Others |
| Companies Covered | ZF Friedrichshafen AG, Schneider Electric SE, Standex Electronics, Hamamatsu Photonics, Ryazan Metal Ceramics Instrumentation Plant JSC, Littelfuse, Coto Technology, Murata Manufacturing, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reed Sensor Market Emerging Trajectories
Reed sensor architecture is bifurcating between commodity switching and intelligent modules, with material science and regulatory chemistry dictating competitive survival more than manufacturing scale alone.
Surface-mount reed switches with vacuum-deposited rhodium contacts are absorbing switching frequency demands from 400 Hz legacy designs toward kilohertz-range applications in robotic encoders. Automotive tier-1 suppliers are qualifying these variants for transmission position sensing. The technology is absorbing market share previously served by electromechanical microswitches in sealed environments.
China's GB/T electromagnetic compatibility standards and SAMR certification requirements are tightening radiated emission limits for imported components, forcing foreign suppliers to redesign coil suppression circuits. Industrial automation OEMs in Shenzhen and Suzhou are demanding test documentation in Mandarin with third-party verification. Medical device exporters are responding by pre-certifying products through NMPA-recognized laboratories.
Specification consolidation among German automotive OEMs is compressing approved vendor lists from dozens to single-digit preferred suppliers per component category. Buyers are unbundling after-sales technical support from unit pricing, creating service revenue streams for engineering-intensive reed relay configurations. This concentration is most visible in Stuttgart and Munich, where powertrain electrification programs specify 15-year operational life guarantees.
Reed Sensor Market Segmentation
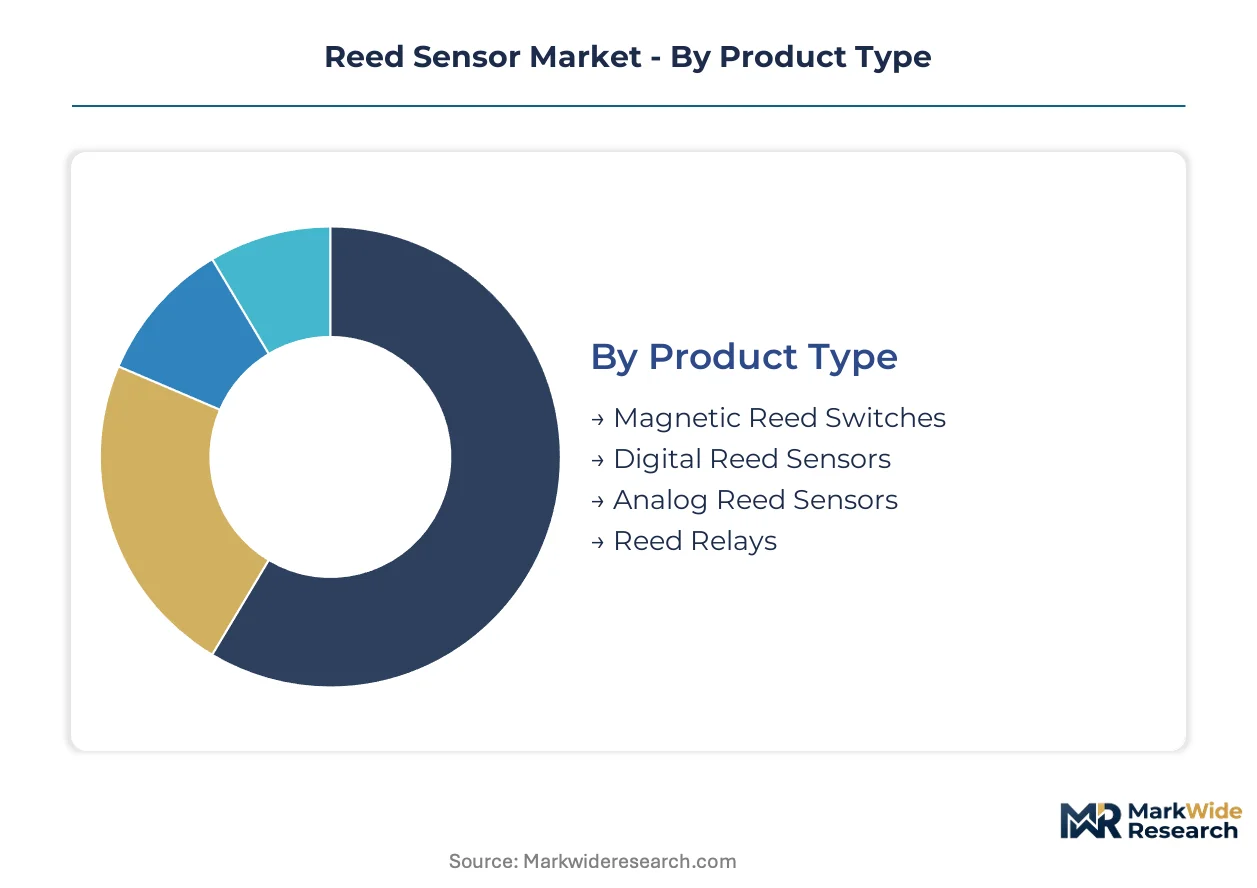
Reed sensor procurement patterns diverge sharply between standalone replacement components and embedded system modules, with integration depth dictating specification complexity, certification requirements, and supplier qualification timelines across automotive and industrial verticals.
Product Type:
Standalone reed switches serve discrete replacement demand in legacy equipment, while sensor-integrated modules with signal conditioning and connector housings penetrate new OEM architectures in electrified vehicles and Industry 4.0 deployments.
- Magnetic Reed Switches:Ferromagnetic contacts hermetically sealed within inert gas-filled glass envelopes operate at switching speeds up to 400 Hz with contact resistance below 150 milliohms. Appliance manufacturers in Germany's industrial corridor specify these for washing machine water level detection, though solid-state alternatives erode share in cost-sensitive consumer applications.
- Digital Reed Sensors:Microcontroller-integrated outputs displace raw switch signals in IoT endpoints, embedding analog-to-digital conversion and diagnostic protocols within the sensor housing. Smart building automation networks in Shenzhen and Suzhou specify these for occupancy detection and security panel integration.
- Analog Reed Sensors:Raw voltage outputs require external signal conditioning hardware, finding residual demand in retrofit industrial control systems where digital-native architectures prove cost-prohibitive.
- Reed Relays:Hermetic switching elements with isolation resistance exceeding 10^12 ohms command premium positioning in test and measurement equipment where signal integrity justifies unit cost multiples.
Magnetic reed switches lead volumes today; digital reed sensors are gaining share fastest.
Application:
Specification intensity escalates from consumer electronics through industrial automation toward automotive and healthcare, with regulatory burden and operational life guarantees determining viable supplier pools.
- Automotive:NHTSA reliability benchmarks for electrified powertrains mandate redundant position sensing in braking and steering systems, requiring hermetic sealing validation under extended thermal cycling. Stuttgart and Munich-based OEMs specify 15-year operational life guarantees for transmission position sensors.
- Healthcare:Implantable and wearable diagnostic equipment demands sub-miniature form factors with biocompatibility certification through FDA and EMA pathways. Isolation resistance specifications exceeding 10^12 ohms support premium pricing in cardiac monitoring and insulin delivery devices.
- Industrial Automation:Predictive maintenance networks in Germany's Industry 4.0 corridor embed precision sensor modules, driving replacement demand as legacy analog outputs require retrofit signal conditioning hardware.
- Consumer Electronics:Cost compression and solid-state displacement constrain reed sensor viability to niche applications in appliance door interlocks and security system magnetic contacts.
Automotive applications command the highest specification intensity; healthcare represents the steepest expansion trajectory.
End User:
Procurement authority concentrates among manufacturers with captive engineering resources, while distributor and retail channels serve fragmented replacement demand with limited technical specification influence.
- Manufacturers:Tier-1 automotive suppliers and industrial automation OEMs dictate design specifications, qualification protocols, and approved vendor list consolidation. Direct procurement relationships with reed sensor specialists enable custom metallurgy and packaging configurations.
- Distributors:Electronics component distributors aggregate fragmented demand from small and mid-sized equipment builders, carrying standardized magnetic reed switch inventories with limited technical support differentiation.
- Retailers:Hardware and home improvement channels serve DIY security installation and appliance repair segments, emphasizing price competition over performance specification.
- Service Providers:Maintenance and repair organizations source replacement components through authorized distributor networks, with procurement decisions constrained by existing equipment compatibility requirements.
Manufacturers control specification authority; distributors intermediate the broadest volume flows.
Connectivity:
Interface selection reflects the tension between legacy infrastructure retrofit requirements and greenfield digital-native system architectures across building automation and industrial control networks.
- Wired:Established 4-20 mA and digital output protocols dominate industrial process control and automotive harness integration, with proven electromagnetic immunity under GB/T certification requirements.
- Wireless:Battery-powered magnetic sensors with integrated radio frequency transmission penetrate smart home and building automation installations, eliminating conduit installation costs in retrofit applications.
- Hybrid:Dual-mode architectures with wired primary connectivity and wireless backup address reliability-critical applications in healthcare monitoring and industrial safety systems.
- Others:Emerging energy-harvesting and mesh network protocols remain pre-commercial for reed sensor integration, constrained by magnetic actuation power budgets.
Wired interfaces retain volume dominance; wireless configurations climb the fastest in building automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reed sensor manufacturing traces its industrial lineage to mid-20th century glass-to-metal sealing innovations pioneered in Germany and the United States, with subsequent scaling across precision electronics corridors in Japan and China.
Germany
Automotive electrification programs in Stuttgart and Munich drive specification intensity for transmission position sensors with 15-year operational life guarantees. ECHA REACH restrictions on mercury and cadmium in contact plating accelerate alternative metallurgy R&D. The Baden-Württemberg industrial automation corridor embeds precision reed modules into predictive maintenance networks.
China
Industrial automation OEMs in Shenzhen and Suzhou specify digital reed sensors for smart building automation and security panel integration. GB/T electromagnetic compatibility standards and SAMR certification requirements tighten radiated emission limits for imported components. The Yangtze River Delta manufacturing belt demands test documentation in Mandarin with third-party verification.
United States
NHTSA reliability benchmarks for electrified powertrains mandate redundant position sensing in braking and steering systems. FAA qualification protocols for aerospace-grade hermetic sealing run parallel to automotive certification timelines. The Southeast electronics manufacturing corridor concentrates appliance and security system production.
Japan
METI industrial policy supports precision component manufacturing for automotive and medical device export markets. JIS standards govern hermetic sealing performance in high-reliability applications. The Chubu region around Nagoya anchors tier-1 automotive supplier ecosystems specifying sub-miniature reed switches.
Reed Sensor Market Vendor Landscape
The competitive structure tilts toward vertically integrated specialists with captive glass-to-metal sealing capabilities. Three tiers operate: multinational diversified electronics conglomerates with broad channel control, mid-cap component specialists focused on hermetic technologies, and regional fabricators serving cost-sensitive appliance markets. Dominant competitive moves include backward integration into contact material processing and strategic partnerships with automotive tier-1 suppliers for joint qualification programs.
Among German-origin industrial conglomerates, ZF Friedrichshafen AG and Schneider Electric SE exemplify the diversified tier with cross-sector electronics portfolios. Japanese precision manufacturers including Hamamatsu Photonics and Murata Manufacturing occupy positions emphasizing miniaturization and high-reliability specifications. Standex Electronics and Littelfuse represent the specialist archetype with concentrated focus on reed-based switching technologies.
| Leading Market Players |
|---|
| ZF Friedrichshafen AG |
| Schneider Electric SE |
| Standex Electronics |
| Hamamatsu Photonics |
| Ryazan Metal Ceramics Instrumentation Plant JSC |
| Littelfuse |
| Coto Technology |
| Murata Manufacturing |
| TE Connectivity |
| Others |
Supply Flow & Price Mechanics
Automotive OEM consolidation in Stuttgart and Munich toward single-digit approved vendor lists per component category is compressing supplier margins while simultaneously demanding 15-year operational life guarantees that force captive investment in glass-to-metal sealing capabilities. This procurement concentration rewards reed sensor specialists with backward integration into contact material processing while penalizing distributors unable to bundle after-sales technical support with unit pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the reed sensor market by certification intensity and application criticality. Premium tiers command multiples for aerospace-grade hermetic sealing validated under FAA protocols and medical device isolation resistance exceeding 10^12 ohms, while economy tiers face cost compression from solid-state displacement in appliance applications. Price differentiation hinges on REACH-compliant alternative metallurgies versus legacy mercury and cadmium plating, with automotive tier-1 suppliers least sensitive due to electrification program timelines and DIY security installers most sensitive due to commoditized magnetic contact replacement demand.
Supply Chain Analysis
Rare earth magnet supply rests on Chinese neodymium processing and Japanese specialty alloy refinement, creating input cost volatility that propagates through reed switch magnetic field specifications. Glass-to-metal seal capabilities concentrate in Germany, Japan, and select European artisan workshops, tethering aerospace-grade production to decade-long glassblower training pipelines. Single-source vulnerability in hermetic envelope manufacturing compounds tariff exposure on imported noble metals for contact plating. Distribution runs through authorized networks serving tier-1 automotive suppliers and industrial automation OEMs, with electronics component distributors aggregating fragmented replacement demand from smaller equipment builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The reed sensor market functions as a geographic-arbitrage play where ECHA REACH compliance costs in Europe exceed China's GB/T certification burden, creating margin expansion opportunity for suppliers with dual-qualified production footprints.
For Market Incumbents: Deploy backward integration into rhodium and ruthenium contact material processing to defend margin pools against solid-state Hall-effect displacement in automotive position sensing. Capture channel control through joint qualification programs with Stuttgart-based tier-1 suppliers, while accelerating R&D into alternative metallurgies that preempt ECHA restrictions on mercury and cadmium content. For New Entrants and Emerging Players: Capture white-space in medical device miniaturization where FDA and EMA biocompatibility certification creates barrier-protected premium positioning for sub-miniature reed switches. Target Shenzhen and Suzhou industrial automation OEMs demanding Mandarin test documentation with third-party SAMR verification, leveraging digital reed sensor integration into smart building automation networks as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing captive glass-to-metal sealing capabilities and established FAA or NHTSA qualification timelines. Long-term viability over a multi-year horizon favors suppliers with closed-loop noble metal recovery processes aligned to EU Green Deal circularity mandates. Watch neodymium price volatility and glassblower labor availability as inflection indicators for supply-constrained premium tier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Metallurgy | Captive rhodium processing defends margins against REACH-driven material substitution costs. |
| Joint Qualification with Tier-1 Automotive Suppliers | Stuttgart OEM consolidation toward single-digit vendor lists rewards early engineering partnership investment. |
| Dual Certification for Aerospace-Automotive Crossover | Parallel FAA and NHTSA qualification extends time-to-revenue but unlocks premium positioning pools. |
| Closed-Loop Noble Metal Recovery | EU Green Deal material circularity mandates create first-mover advantage for sustainable plating processes. |
| Digital Reed Sensor Platform Launch | Microcontroller-integrated outputs displace raw switch signals in Shenzhen smart building automation deployments. |
Methodological Framework
Direct dialogue with reed sensor procurement managers at tier-1 automotive suppliers, glass-to-metal sealing engineers, industrial automation OEM technical directors, and medical device regulatory affairs specialists grounded qualitative insight. Secondary validation drew from ECHA REACH restriction updates, FAA qualification protocols, NMPA certification databases, and SEC filings of diversified electronics conglomerates. Bottom-up demand modeling across automotive, healthcare, industrial automation, and consumer electronics verticals triangulated against top-down macroeconomic indicators.
Segment-level outputs across the projection horizon reflect product type, application intensity, end-user procurement authority, and connectivity interface selections. CAGRs were derived from regression analysis of historical electrification program specifications and Industry 4.0 sensor replacement cycles, incorporating neodymium price volatility indices and glassbower labor supply constraints as industry-specific forecast inputs.
Regulatory timeline acceleration, rare earth magnet supply disruption, and solid-state sensor cost parity are the dominant revision risks to modeling assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia Pacific Safety I/O Modules Market
Sensors and Controls
Europe Touch Sensor Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Ozone Meter Market
Sensors and Controls
Digital Thermohygrometers Market
Sensors and Controls
Capacitive Pressure Sensor Market
Sensors and Controls
Global Digital Electronic Thermometers Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
ECG Sensor Market
Sensors and Controls
United States Scintillator Market
Sensors and Controls
Asia-Pacific Electric Vehicle Sensor Market
Sensors and Controls
Electrochemical Gas Sensor Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Conveyor Belt Tracking Devices Market