
 Digital Thermohygrometers Market | 2026-2036
Digital Thermohygrometers Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Thermohygrometers Market Insights
Multi-source procurement for sensor components is shifting toward captive production of capacitive humidity elements among established instrument manufacturers. Testo SE & Co. KGaA leverages its German manufacturing base to sustain precision calibration dominance across European pharmaceutical chains. Fluke Corporation anchors industrial channel access through distributor networks serving facility maintenance teams. Vaisala differentiates via aerospace-grade sensing technology that competes in meteorological and cleanroom applications.
A digital thermohygrometer combines temperature and relative humidity measurement in a single instrument, typically employing capacitive polymer or thin-film sensor elements with accuracy thresholds of ±2% RH and ±0.5°C for professional-grade units. These devices serve critical environmental validation roles in regulated storage, manufacturing, and research settings where deviation logs trigger corrective action protocols. Portable units lead volume shipments for field technicians and spot-check workflows, while fixed installations capture recurring revenue through calibration service contracts in pharmaceutical and semiconductor cleanrooms. Smart thermohygrometers with cloud-connected data logging represent the fastest-expanding segment as facilities automate 21 CFR Part 11-compliant documentation.
FDA 21 CFR Part 11 and EU Good Distribution Practice jointly shape product requirements for data integrity, audit trails, and alarm documentation in regulated cold chains. EPA energy efficiency standards for commercial HVAC systems indirectly stimulate demand by mandating integrated environmental controls in new building retrofits. Stakeholders must monitor evolving cybersecurity labeling requirements for networked sensor devices as NIST frameworks extend into IoT environmental monitoring equipment.
Market Dynamics
Wireless sensor integration is compressing installation timelines in climate-controlled facilities while EU Good Distribution Practice mandates force continuous environmental monitoring upgrades across pharmaceutical distribution networks.
Growth Catalysts
- EU Good Distribution Practice:Mandates for continuous temperature and humidity documentation in pharmaceutical warehouses drive replacement cycles for legacy logging equipment across Germany, France, and Italy.
- Capacitive polymer sensors:Advances in thin-film humidity sensing elements enable ±2% RH accuracy thresholds that satisfy FDA 21 CFR Part 11 validation requirements for cold chain logistics.
- Cloud-connected data logging:Smart thermohygrometers with automated 21 CFR Part 11-compliant documentation are capturing recurring revenue through calibration service contracts in semiconductor cleanrooms.
Market Restraints
- Precious metal electrode costs:Capacitive humidity sensors require gold or platinum thin-film deposition, exposing manufacturers to commodity price volatility in precious metals markets.
- Calibration infrastructure concentration:Precision humidity calibration facilities cluster in Germany, Switzerland, and the United States, creating geographic bottlenecks for Asian and Latin American end-users.
- Optical hygrometer substitution:Chilled-mirror dew point instruments retain dominance in metrology laboratories and national standards institutes where ±0.5% RH accuracy is mandatory.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO enforcement of cold chain documentation for vaccine exports creates demand for calibrated thermohygrometers in Mumbai and Hyderabad production clusters.
- CSRD environmental disclosure:EU Corporate Sustainability Reporting Directive mandates granular energy and climate data collection, extending thermohygrometer deployment into commercial HVAC retrofits beyond regulated industries.
- LoRaWAN protocol convergence:Integration of low-power wide-area networking with battery-powered field sensors enables five-year maintenance-free operation in remote agricultural and warehouse monitoring applications.
Industry Challenges
- Metrology technician scarcity:Precision humidity calibration requires specialized training in saturated salt solution methods and pressure-temperature compensation algorithms that few technical institutes currently teach.
- Legacy BMS integration friction:BACnet and Modbus protocol mismatches between new wireless thermohygrometers and 1990s-era building management systems delay deployment in institutional facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Thermohygrometers Market |
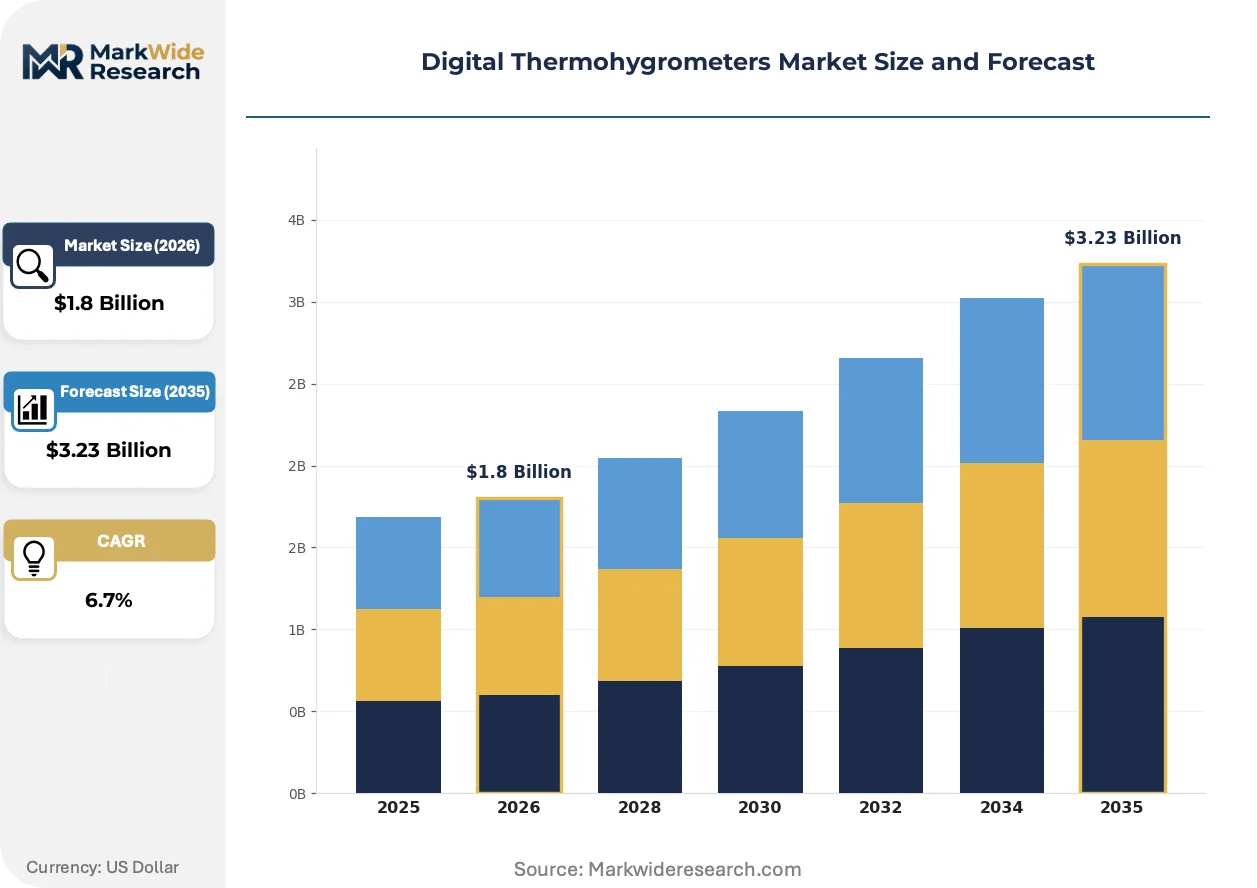
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Fixed, High Precision, Smart Application: HVAC, Greenhouses, Laboratories, Home End User: Commercial, Industrial, Residential, Institutional Technology: Digital, Analog, Wireless, Bluetooth |
| Companies Covered | Testo SE & Co. KGaA, Fluke Corporation, Honeywell International Inc., Vaisala, ThermoPro, Govee, AcuRite, Extech Instruments, PCE Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Thermohygrometers Market Trends and Innovations
Sensor miniaturization and edge computing capabilities are collapsing the boundary between portable spot-check devices and fixed monitoring infrastructure, forcing manufacturers to reconceive product architectures.
MEMS-based multi-sensor arrays is rewriting how environmental validation equipment gets specified. These silicon-integrated modules combine temperature, humidity, and pressure sensing in single packages. Pharmaceutical contract manufacturers in Ireland and Singapore are specifying MEMS-based instruments for new facility builds. The technology is rewriting procurement criteria by collapsing three separate instrument categories into unified validation platforms.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant leak detection mandates in commercial cold storage. Thermohygrometers with integrated pressure sensing now serve dual compliance roles for environmental monitoring and refrigeration system integrity. German supermarket chains and Dutch floral distribution centers are deploying these hybrid instruments to satisfy parallel regulatory obligations.
Buyers are unbundling hardware procurement from calibration service contracts that historically bundled multi-year commitments. Facility managers in FDA-regulated industries now source instruments through distributor marketplaces while negotiating calibration directly with accredited laboratories. This pattern is most visible in the United States where third-party calibration laboratories in Research Triangle Park and San Diego compete for pharmaceutical and biotechnology accounts.
Digital Thermohygrometers Market Segmentation
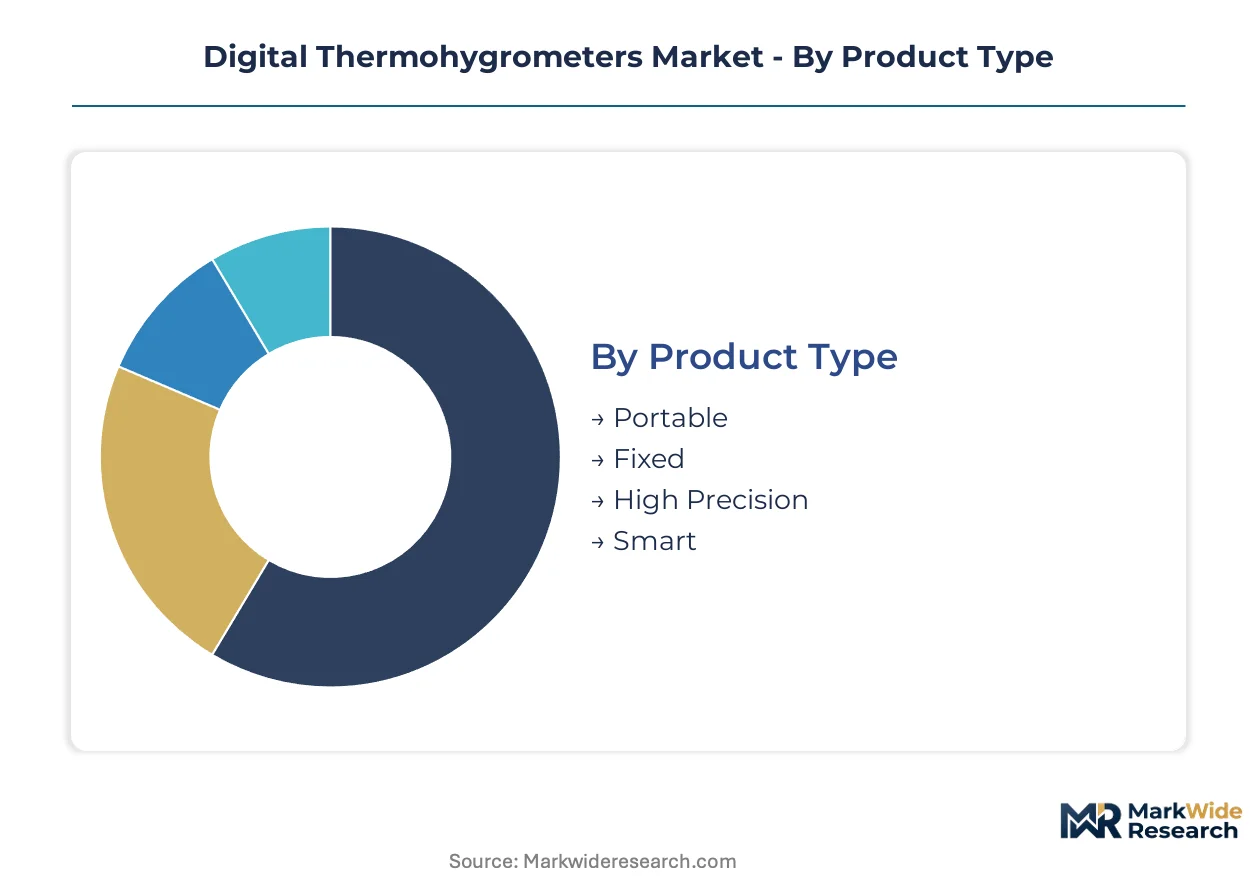
Digital thermohygrometer procurement splits across four distinct decision axes. Product architecture determines calibration protocols and service revenue potential. Application context dictates accuracy thresholds and regulatory validation requirements.
Product Type:
Facility managers select product architecture based on mobility requirements and integration depth with building systems.
- Portable:Handheld units with capacitive polymer sensors deliver ±2% RH accuracy for field technicians conducting spot-check validations. Pharmaceutical warehouse operators in Germany deploy these for EU Good Distribution Practice compliance audits across multiple storage zones. Volume sits with Portable; growth tilts toward Smart.
- Fixed:Wall-mounted installations with continuous data logging anchor environmental monitoring in semiconductor cleanrooms and climate-controlled manufacturing. These systems capture recurring calibration service contracts that extend revenue lifecycles beyond hardware margins.
- High Precision:Chilled-mirror and thin-film instruments achieve ±0.5% RH thresholds for metrology laboratories and national standards institutes where traceability to SI units is mandatory.
- Smart:Cloud-connected devices with automated 21 CFR Part 11-compliant documentation are climbing the fastest as FDA-regulated cold chains automate deviation logging and alarm protocols.
Portable dominates shipment volumes; Smart instruments command expanding share through subscription-based calibration services.
Application:
End-use environment shapes sensor specification, certification grade, and documentation rigor.
- HVAC:Building automation integration drives demand for BACnet and Modbus-compatible instruments. EPA energy efficiency standards for commercial retrofits indirectly stimulate deployment across United States institutional facilities.
- Greenhouses:Battery-powered LoRaWAN sensors enable five-year maintenance-free operation in remote agricultural monitoring. Dutch floral distribution centers deploy hybrid pressure-sensing units to satisfy EU F-Gas refrigerant leak detection mandates.
- Laboratories:Pharmaceutical contract manufacturers in Ireland and Singapore specify MEMS-based multi-sensor arrays that collapse temperature, humidity, and pressure validation into unified procurement platforms.
- Home:Consumer-grade capacitive sensors with ±5% RH accuracy serve residential comfort monitoring. This segment trails professional applications in revenue contribution but sustains volume manufacturing scale.
Laboratories concentrate premium revenue; HVAC applications scale fastest through building retrofit mandates.
End User:
Organizational scale and regulatory exposure determine procurement channel and service bundling preferences.
- Commercial:Supermarket chains and third-party logistics operators prioritize total cost of ownership over upfront hardware expense. German retail cold storage operators unbundle instrument procurement from calibration contracts, sourcing devices through distributor marketplaces while negotiating service directly with accredited laboratories.
- Industrial:Semiconductor fabs and battery manufacturing facilities demand aerospace-grade sensing technology with documented traceability chains.
- Residential:Price-sensitive demand concentrates in smart home ecosystems where thermohygrometers integrate with climate control platforms.
- Institutional:Universities and government research facilities balance precision requirements against grant-funded capital constraints.
Commercial buyers drive service revenue expansion; Industrial users anchor premium pricing tiers.
Technology:
Connectivity architecture and signal processing method determine deployment flexibility and cybersecurity posture.
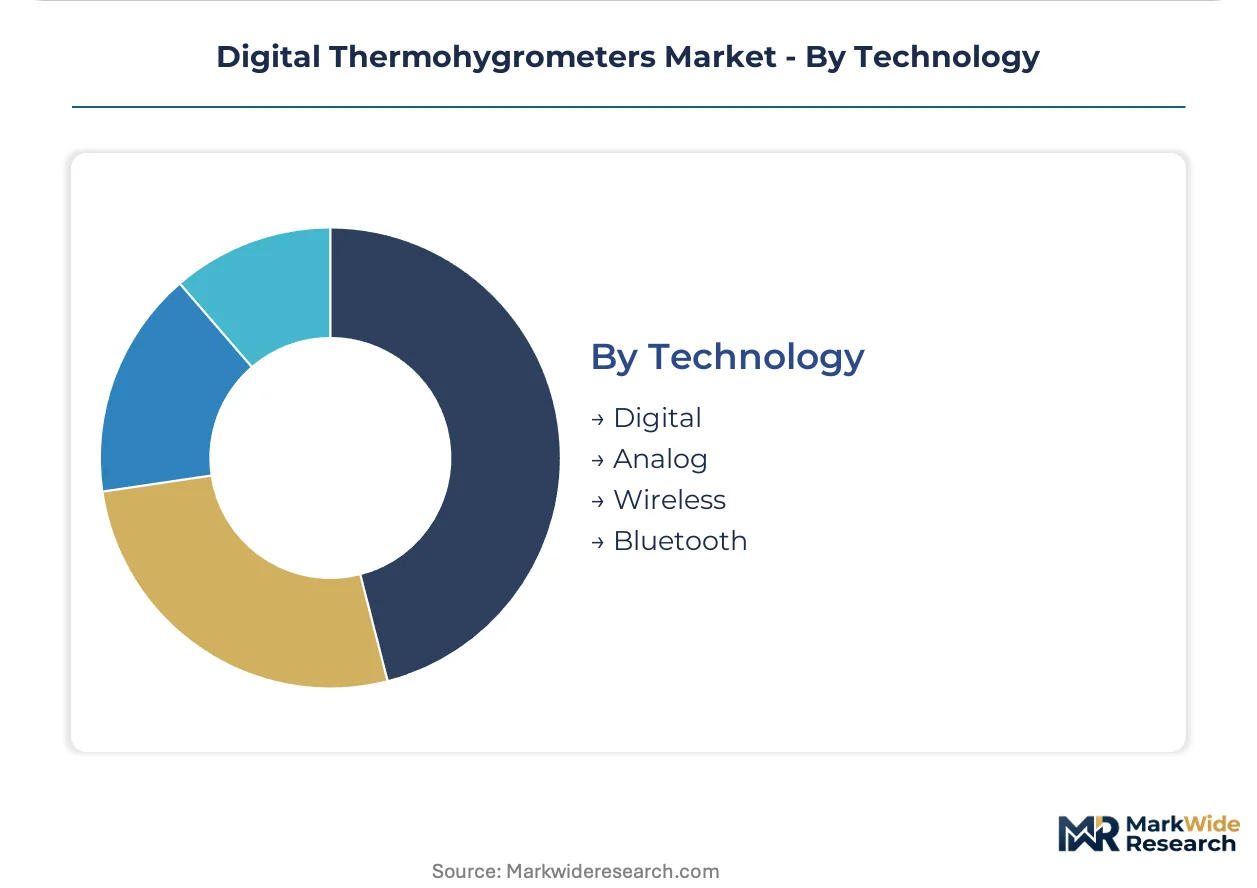
- Digital:Microprocessor-based instruments with onboard calibration curves dominate professional-grade installations. CDSCO enforcement of cold chain documentation for Indian vaccine exports accelerates deployment in Mumbai and Hyderabad production clusters.
- Analog:Voltage-output sensors persist in legacy building management systems where 4-20mA loops remain standard. BACnet protocol mismatches with 1990s-era infrastructure create integration friction that delays replacement cycles.
- Wireless:Mesh-networked sensors compress installation timelines in climate-controlled warehouses. EU Corporate Sustainability Reporting Directive mandates extend deployment into commercial HVAC retrofits beyond regulated industries.
- Bluetooth:Short-range connectivity serves technician spot-check workflows and consumer applications where cloud integration is secondary to immediate display readability.
Digital platforms command installed base; Wireless connectivity gains fastest through new facility builds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision calibration facilities anchor the supply base for capacitive humidity sensors, with Lenzkirch and Titisee-Neustadt hosting accredited laboratories serving pharmaceutical chains across continental Europe.
United States
FDA-regulated cold chain logistics drive calibrated humidity traceability requirements. EPA energy efficiency standards for commercial HVAC retrofits stimulate integrated environmental controls in institutional buildings. Research Triangle Park and San Diego host third-party calibration laboratories competing for biotechnology and pharmaceutical accounts.
Germany
Pharmaceutical warehouses in Baden-Württemberg and Bavaria mandate continuous environmental monitoring under EU Good Distribution Practice. The country's national pharmaceutical regulator enforces documentation protocols that compress replacement cycles for legacy logging equipment. Calibration infrastructure concentrates in the Black Forest region, creating geographic bottlenecks for Asian end-users seeking precision humidity validation.
India
CDSCO enforcement of cold chain documentation for vaccine exports generates demand in Mumbai and Hyderabad production clusters. The national pharmaceutical regulator mandates calibrated thermohygrometers for export-oriented manufacturing. Domestic calibration capabilities remain underdeveloped, forcing reliance on German and Swiss service providers.
China
Semiconductor fabs in the Yangtze River Delta specify MEMS-based multi-sensor arrays for new facility builds. GB standards for cleanroom environmental monitoring tighten accuracy thresholds for professional-grade instruments. Domestic manufacturers capture consumer-grade volume while import dependence persists for ±0.5% RH precision units.
Netherlands
Dutch floral distribution centers deploy hybrid pressure-sensing thermohygrometers to satisfy EU F-Gas refrigerant leak detection mandates. The country's national environmental agency enforces parallel compliance obligations for cold storage environmental monitoring. Rotterdam port logistics operators unbundle instrument procurement from calibration contracts, sourcing through distributor marketplaces.
Digital Thermohygrometers Market Competitive Landscape
Global majors compete with regional champions across calibration service networks and distribution channel depth. The vendor base clusters around three tiers: precision instrument specialists with captive sensor production, industrial channel players leveraging facility maintenance relationships, and consumer electronics brands scaling through retail marketplaces. Strategic moves concentrate on backward integration into capacitive humidity element manufacturing and geographic expansion of accredited calibration laboratories.
Within the precision calibration tier, Testo SE & Co. KGaA exemplifies German manufacturing-based dominance, while Vaisala occupies a position serving aerospace-grade sensing applications. Fluke Corporation anchors industrial channel access through distributor networks. These three represent distinct strategic archetypes: captive production with service bundling, aerospace technology lateralization, and maintenance-channel scale.
| Leading Market Players |
|---|
| Testo SE & Co. KGaA |
| Fluke Corporation |
| Honeywell International Inc. |
| Vaisala |
| ThermoPro |
| Govee |
| AcuRite |
| Extech Instruments |
| PCE Instruments |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FDA-validated instruments and uncalibrated consumer units manifests in parallel supply chain configurations. Premium thermohygrometers draw from German and Swiss calibration infrastructure with captive precious metal electrode production, while commodity sensors source from Asian contract manufacturers with minimal traceability investment.
Pricing Analysis
Warranty and calibration service bundling separates premium positioning from transactional hardware sales. Three-tier pricing structure across pharmaceutical-grade, industrial-standard, and residential-economy levels reflects certification investment and traceability documentation. Price differentiation hinges on 21 CFR Part 11 compliance validation and geographic proximity to accredited laboratories. Cost compression in the residential tier intensifies as consumer electronics brands scale through retail marketplaces. Commercial buyers in FDA-regulated industries demonstrate lowest price sensitivity due to audit risk exposure.
Supply Chain Analysis
Precious metal electrode supply rests on German thin-film deposition specialists and Swiss precision component manufacturers. Capacitive polymer sensing elements, platinum thin-film substrates, and MEMS wafer fabrication anchor raw material dependencies. Single-source vulnerability concentrates in Black Forest calibration facilities serving pharmaceutical validation chains. Distribution runs through industrial distributor networks for professional instruments and retail marketplaces for consumer units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless sensor integration is displacing wired installations across climate-controlled facilities, compressing replacement cycles for legacy BACnet and Modbus infrastructure. This technology transition rewards suppliers with cloud-native architectures and recurring service revenue models.
For Market Incumbents: Deepen backward integration into capacitive humidity element manufacturing to insulate margins from precious metal volatility. Expand accredited calibration laboratory footprint in India and China to reduce geographic bottlenecks for Asian pharmaceutical exporters. Defend against MEMS-based multi-sensor substitution by emphasizing documented traceability chains and FDA validation pedigree.
For New Entrants and Emerging Players: Mid-sized Indian pharmaceutical contract manufacturers represent an underserved buyer archetype with CDSCO-mandated cold chain documentation needs and limited access to German calibration services. Target LoRaWAN-enabled agricultural monitoring in Dutch greenhouse clusters where EU F-Gas Regulation creates dual compliance demand. Pursue direct calibration service partnerships rather than hardware-only distribution.
For Investors and Strategic Acquirers: Re-rating potential sits with precision calibration service providers given CSRD environmental disclosure mandates extending thermohygrometer deployment into commercial HVAC retrofits. Long-term viability favors vertically integrated instrument manufacturers with captive sensor production and recurring revenue from 21 CFR Part 11-compliant documentation services. Watch CDSCO enforcement intensity in Indian vaccine export corridors as inflection indicator for emerging market demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Elements | Captive production of capacitive humidity elements insulates Testo and Vaisala from precious metal price volatility. |
| Calibration Laboratory Geographic Expansion | Accredited facility investment in Mumbai and Hyderabad addresses CDSCO-mandated demand for Indian pharmaceutical exporters. |
| Cloud-Connected Data Logging Platform Launch | Smart thermohygrometers with automated 21 CFR Part 11 documentation capture recurring service contracts in semiconductor cleanrooms. |
| LoRaWAN Protocol Integration | Battery-powered wide-area networking enables five-year maintenance-free deployment in remote Dutch agricultural monitoring. |
| MEMS-Based Multi-Sensor Array Development | Silicon-integrated temperature, humidity, and pressure modules collapse procurement categories for Irish pharmaceutical contract manufacturers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with calibration laboratory directors, pharmaceutical quality assurance managers, HVAC controls procurement leads, and semiconductor facilities engineers combined with secondary validation from FDA 483 observation databases, EU EUDAMED device registrations, and German BNetzA frequency allocation records. Bottom-up shipment modeling and top-down market sizing triangulated volume estimates.
Granularity-level modeling disaggregated the analysis window by product architecture, application environment, end-user scale, and connectivity technology. Professional-grade, industrial-standard, and consumer-economy tiers were modeled separately with distinct replacement cycle assumptions. CAGRs derived from regression against pharmaceutical capital expenditure trends, EPA commercial building retrofit schedules, and EU pharmaceutical distribution volume growth. MEMS adoption curves and LoRaWAN deployment rates served as technology-specific forecast inputs.
Revisions become necessary when CDSCO enforcement intensity shifts, EU F-Gas Regulation timelines accelerate, or NIST cybersecurity frameworks extend into IoT environmental monitoring equipment. Forecasts reflect assumptions about calibration infrastructure expansion rates and wireless protocol standardization. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Automation Control Components and Devices Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Smartphone Biometric Sensors Market
Sensors and Controls
Sound Sensor Market
Sensors and Controls
Position Sensor Market
Sensors and Controls
Subcool Metering Device Market
Sensors and Controls
Piezoelectric Accelerometer Market
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market
Sensors and Controls
Piezoresistive Pressure Sensor Market
Sensors and Controls
MEMS Microphones Market
Sensors and Controls
Phototransistor Market
Sensors and Controls
PID Controller Market
Sensors and Controls
Thermal Flow Meter Market