

Conveyor Belt Tracking Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Conveyor Belt Tracking Devices Market Insights
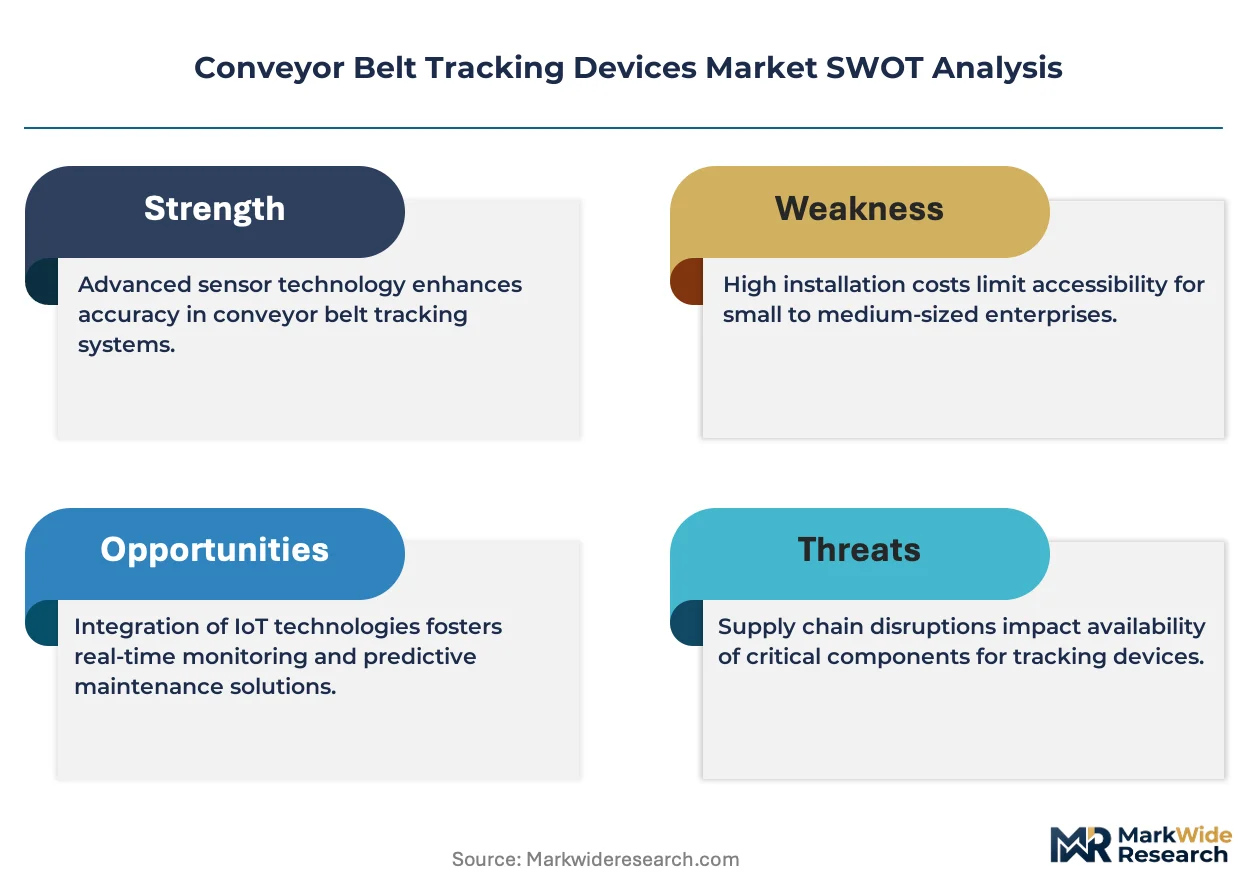
The EU Green Deal is broadening compliance obligations for energy-intensive material handling operations across European quarry and mining sites. Flexco leverages its integrated manufacturing footprint to supply mechanical tracking hardware with shorter lead times than Asian competitors. Martin Engineering anchors its position through specialized training programs that lock in maintenance contracts with North American coal and aggregate producers. Tru-Trac differentiates via concentrated R&D on self-adjusting roller frames for extreme-temperature environments.
Conveyor belt tracking devices are electromechanical and sensor-based systems designed to maintain lateral alignment of continuous belting, typically operating within positional tolerances of ±5 millimeters to prevent edge damage and spillage. These units deploy load cells, proximity switches, or optical arrays to detect deviation and trigger corrective roller pivoting or tension modulation, primarily serving bulk material transport where misalignment causes catastrophic belt failure or fugitive dust emissions. Electromechanical units dominate installed base volumes due to proven durability in abrasive mining conditions, while electronic sensors represent the fastest-expanding category as digital mine investments accelerate predictive maintenance adoption. Laser tracking technology commands premium pricing in precision-critical food processing lines where contamination thresholds approach zero tolerance for particulate shedding.
OSHA conveyor safety standards and MSHA hazard reduction mandates in the United States enforce mandatory guarding and emergency stop integration, directly shaping product certification requirements and procurement specifications for tracking device vendors. REACH chemical compliance and CE machinery directives in Europe restrict polymer compositions used in tracker rollers, pushing manufacturers toward validated substitute materials. Stakeholders must monitor evolving interoperability standards between tracking sensors and centralized plant control systems to avoid stranded asset risk from proprietary communication protocols.
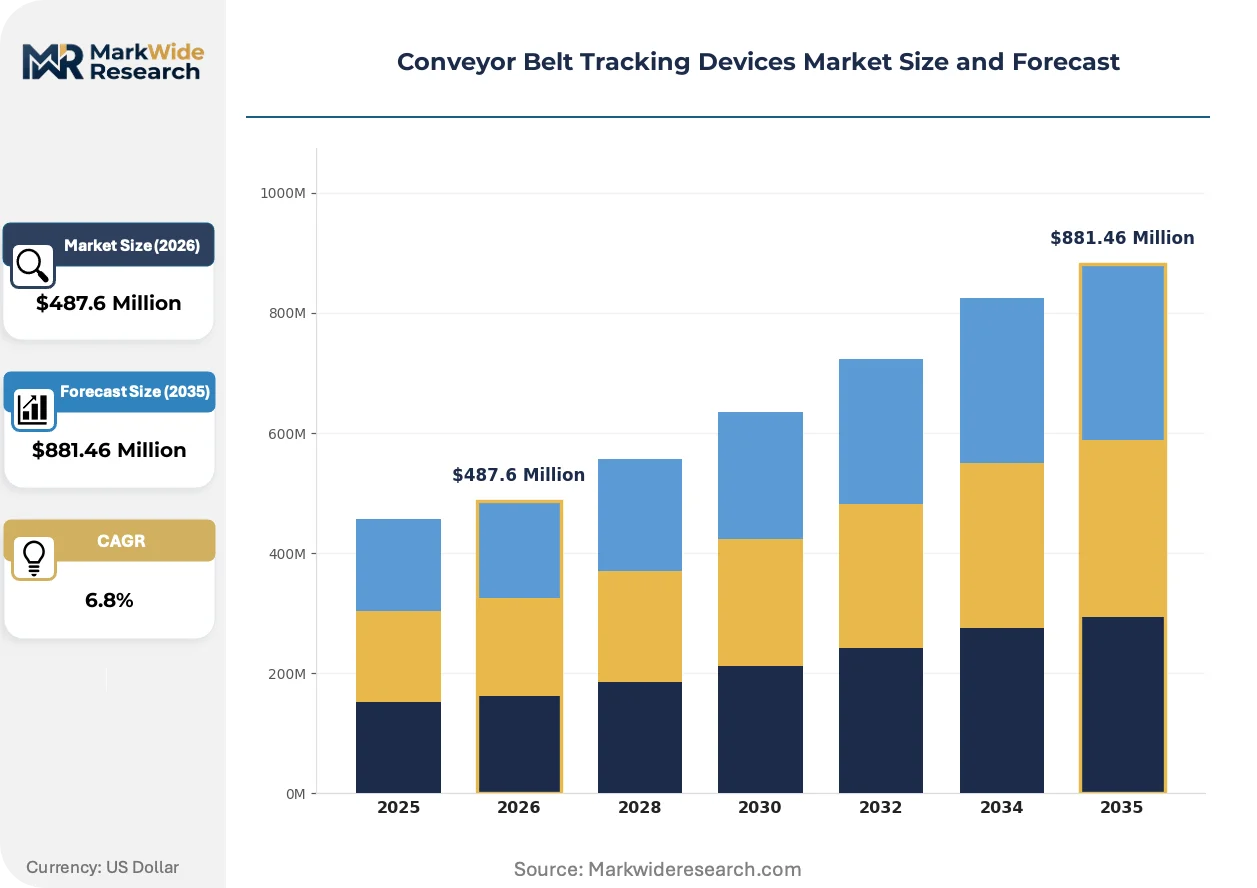
Market Dynamics
Automated belt alignment systems are displacing manual adjustment protocols across mechanized mining corridors, compressing maintenance windows from hours to minutes and forcing capital reallocation toward sensor-integrated hardware.
Growth Catalysts
- ISO 14890 safety mandates:Bulk material handling operators in Chile and Australia face accelerated replacement cycles for legacy tracking hardware to satisfy updated conformity assessment procedures.
- Mechanized surface mining expansion:Belt lengths exceeding five kilometers in Pilbara and Atacama corridors generate positional tolerance requirements that electromechanical trackers uniquely satisfy.
- Sensor fusion architectures:Proximity switches married to optical arrays enable predictive deviation detection before edge damage propagates across high-tension belting.
Market Restraints
- Polymer input volatility:REACH chemical compliance restricts validated roller compositions, forcing manufacturers toward substitute elastomers with elongated qualification timelines.
- Specialized technician scarcity:Laser tracking calibration demands optical engineering expertise concentrated in German and Japanese industrial clusters.
- Proprietary protocol lock-in:Stranded asset risk emerges when tracking sensors lack OPC-UA interoperability with centralized plant control architectures.
Strategic Opportunities
- Underpenetrated Indonesian coal corridors:Kalimantan surface operations still rely on manual alignment, creating first-mover advantage for automated retrofit suppliers.
- EU Green Deal compliance services:Energy-intensive quarry operators require tracking device vendors to bundle carbon footprint documentation with hardware procurement.
- Edge-computing convergence:On-roller microprocessors processing deviation data locally reduce latency versus cloud-dependent competitor architectures.
Industry Challenges
- Legacy system integration friction:Electromechanical tracker retrofits onto 1980s-era belt structures demand custom mounting fabrication that extends commissioning timelines.
- CE machinery directive certification backlog:Third-party notified body queues for tracker roller validation currently stretch twelve to eighteen months for European market entry.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conveyor Belt Tracking Devices Market Trends and Innovations
Digital mine investments are compressing the feedback loop between deviation detection and corrective action, embedding intelligence directly at the roller frame rather than routing signals through centralized SCADA hierarchies.
Self-adjusting roller frame architectures are modularizing field maintenance protocols. Mining operators in Western Australia deploy cartridge-style pivot mechanisms that permit component swap-out without belt stoppage. This modularity compresses mean-time-to-repair from four hours to forty-five minutes, enabling maintenance crews to cover multiple belt sections per shift.
REACH chemical compliance is forcing material substitution across European supply chains. ECHA restrictions on specific polymer plasticizers push manufacturers toward bio-based elastomer validation programs. Food-grade tracking applications face the steepest reformulation burden, as contamination thresholds near zero tolerance for particulate shedding.
Maintenance contract unbundling is fragmenting traditional vendor relationships. North American coal producers now separate hardware procurement from training and calibration services, soliciting specialist firms for each function. This disintermediation pressures integrated suppliers to defend position through captive service arms or risk margin compression from pure-play competitors.
Conveyor Belt Tracking Devices Market Segmentation
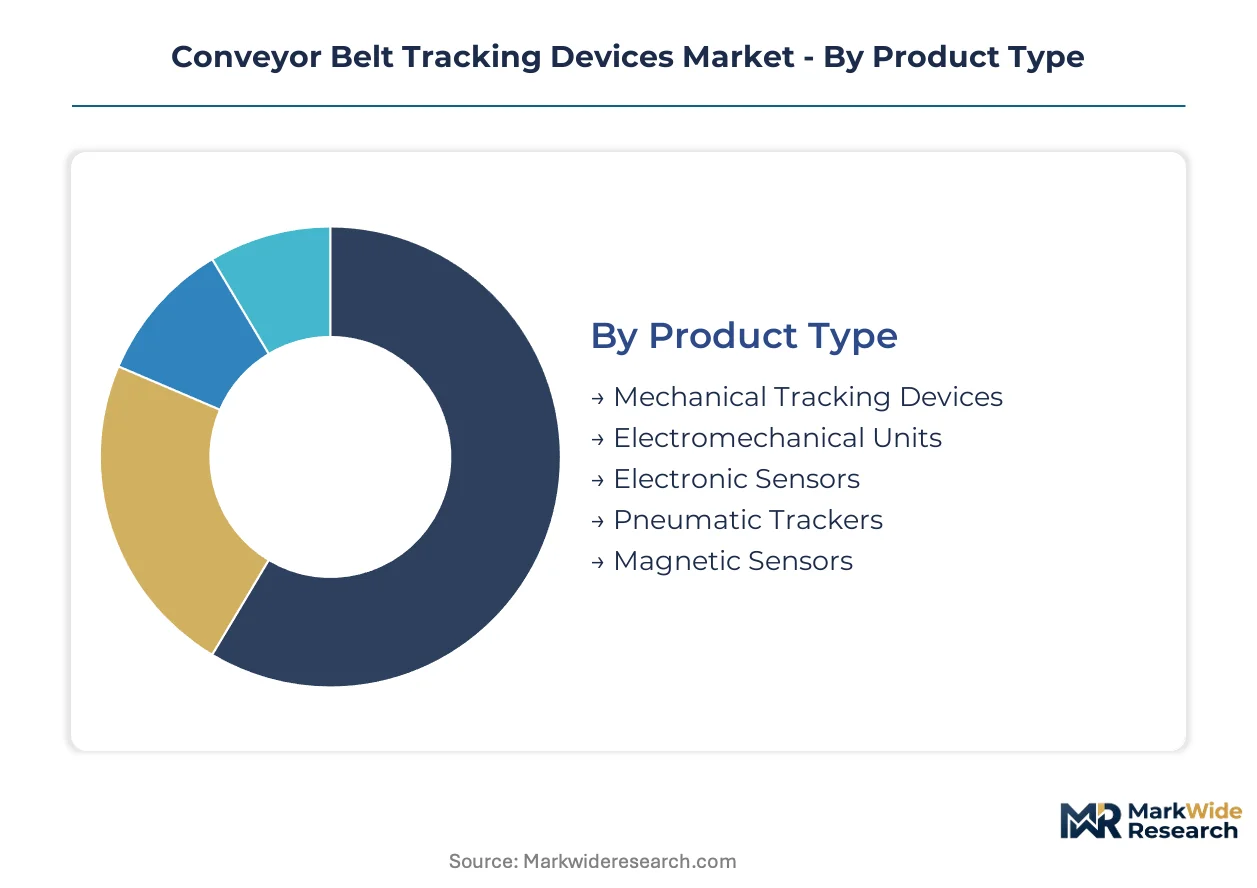
Conveyor belt tracking devices serve divergent operational requirements across abrasive mining environments and precision-critical food processing lines. Segmentation reveals how electromechanical durability competes with electronic intelligence for capital allocation in mechanized material handling corridors.
Product Type:
Electromechanical units dominate installed base volumes through proven abrasion resistance, while electronic sensors capture premium expansion in digitized operations.
- Mechanical Tracking Devices:Spring-loaded pivot frames and friction-based correction mechanisms operate without external power in remote mining installations. Pilbara iron ore corridors rely on these units for belt lengths exceeding five kilometers where electrical infrastructure remains sparse.
- Electromechanical Units:Hybrid architectures combine mechanical actuation with basic limit switches for deviation detection. Australian surface mining operators specify these for maintenance windows compressed under ISO 14890 compliance mandates.
- Electronic Sensors:Proximity switches and optical arrays feed deviation data into predictive maintenance architectures.
- Pneumatic Trackers:Compressed-air actuation suits explosive atmosphere classifications in coal handling facilities.
- Magnetic Sensors:Non-contact detection operates through dust-laden environments where optical systems fail.
Today's leader: Electromechanical Units. Tomorrow's challenger: Electronic Sensors.
Technology:
Laser systems command pricing premiums in contamination-sensitive applications, while vibration monitoring scales across volume-driven mining procurement.
- Laser Tracking:Sub-millimeter positional accuracy through triangulated beam arrays satisfies zero-tolerance particulate thresholds in food-grade belting. German and Japanese industrial clusters concentrate calibration expertise for these precision-critical installations.
- Ultrasonic Detection:Time-of-flight measurement penetrates dust plumes that blind optical alternatives. Chilean copper concentrators deploy these sensors in high-altitude Atacama corridors where atmospheric particulate density fluctuates.
- Infrared Sensors:Thermal deviation detection functions in extreme-temperature environments.
- Vibration Monitoring:Accelerometer arrays predict misalignment through spectral analysis.
- Pressure Sensing:Load cell integration tracks belt tension distribution across roller stations.
Volume concentrates in Vibration Monitoring. Margins accumulate in Laser Tracking.
Application:
Mining operations generate absolute unit demand, while food processing lines drive specification intensity for contamination-proof architectures.
- Mining Operations:Mechanized surface extraction demands tracking hardware rated for continuous duty in abrasive conditions. Kalimantan coal corridors present retrofit opportunity as Indonesian operators transition from manual alignment protocols.
- Food Processing Lines:Stainless steel construction and sealed bearing assemblies satisfy FDA and EFSA contact-surface mandates. REACH chemical compliance forces polymer reformulation in European dairy and bakery installations.
- Packaging Systems:High-speed throughput requires rapid-response correction loops.
- Recycling Plants:Contaminant-heavy feed streams test tracker durability.
- Textile Manufacturing:Low-tension belting permits lighter-duty tracker specifications.
Installed base anchors in Mining Operations. Specification intensity peaks in Food Processing Lines.
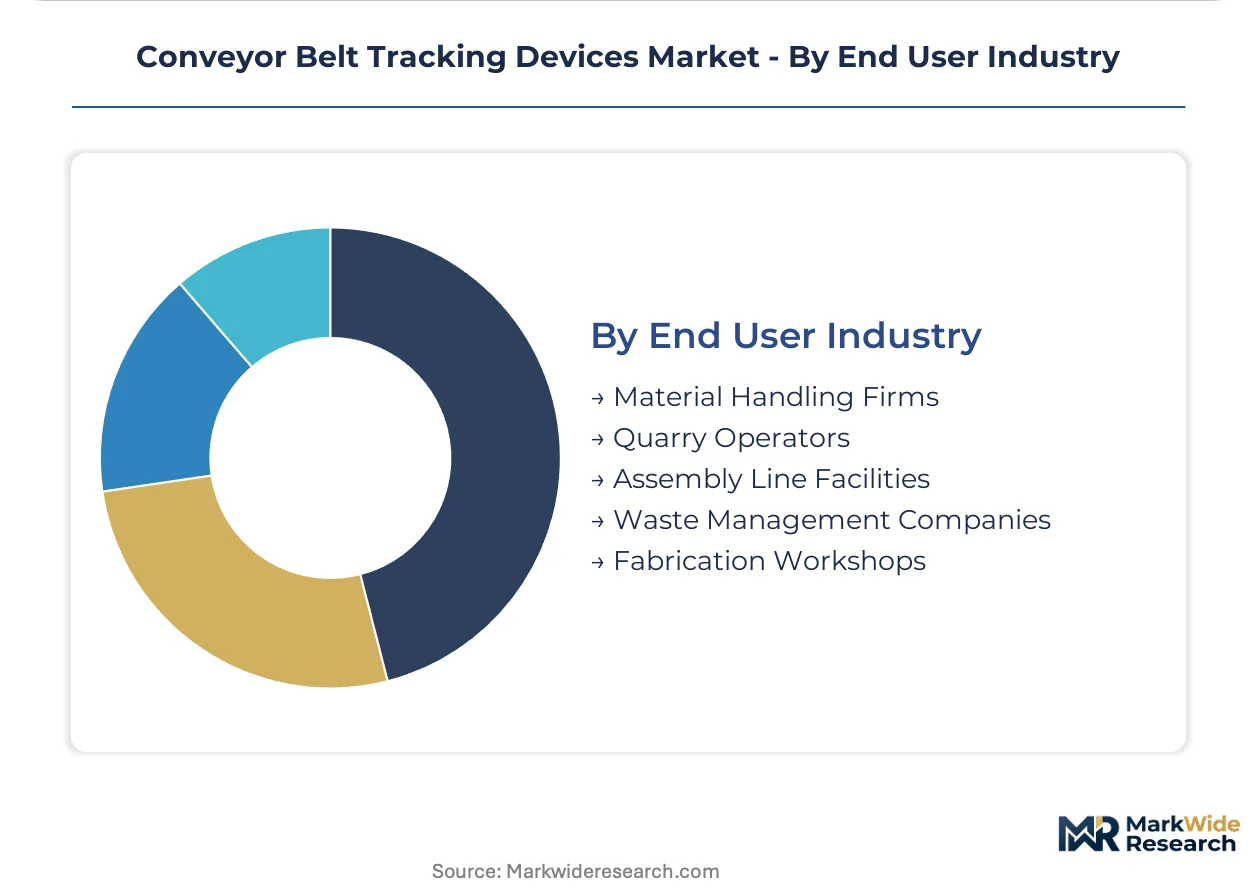
End User Industry:
Material handling firms consolidate procurement across multiple belt systems, while quarry operators drive replacement cycles under stricter safety protocols.
- Material Handling Firms:Integrated logistics providers standardize tracker specifications across distributed facility networks. EU Green Deal carbon documentation requirements now bundle with hardware procurement for European distribution centers.
- Quarry Operators:Fragmented ownership structures across European aggregate sites complicate vendor relationship consolidation. CE machinery directive certification backlogs stretch market entry timelines for tracker suppliers.
- Assembly Line Facilities:Automotive and electronics manufacturing demand precision alignment.
- Waste Management Companies:Corrosive environments accelerate tracker replacement frequencies.
- Fabrication Workshops:Job-shop operations prioritize lowest-first-cost procurement.
Procurement scale concentrates with Material Handling Firms. Compliance intensity concentrates with Quarry Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision conveyor engineering during the post-war industrial expansion, establishing quality benchmarks that persist across European quarry and mining procurement specifications today.
Australia
Pilbara iron ore operators deploy electromechanical trackers across belt systems exceeding five kilometers in length. ISO 14890 safety mandates from Standards Australia accelerate replacement cycles for legacy alignment hardware. Perth-based maintenance contractors now bundle automated tracking retrofits with predictive maintenance service agreements.
Chile
Atacama copper concentrators generate concentrated demand for dust-resistant tracking sensors in high-altitude corridors. The national mining regulator enforces stricter bulk material handling protocols under updated workplace safety codes. Antofagasta mineral processing clusters anchor procurement volumes for extreme-temperature tracker specifications.
United States
Appalachian coal producers and Great Lakes aggregate operators drive replacement demand under MSHA hazard reduction mandates. OSHA conveyor safety standards enforce mandatory guarding integration for all new tracking installations. Pittsburgh and St. Louis industrial corridors concentrate distributor networks for North American belt system components.
Germany
Ruhr Valley quarry operators and Bavarian cement manufacturers face compressed procurement timelines under CE machinery directive certification requirements. REACH chemical compliance from ECHA restricts polymer compositions used in tracker roller manufacturing. Stuttgart engineering clusters concentrate optical calibration expertise for laser tracking systems.
Indonesia
Kalimantan surface coal operations present underpenetrated retrofit opportunity as operators transition from manual alignment protocols. The national mineral and coal directorate issues technical guidance on bulk handling safety equipment standards. Samarinda industrial zones concentrate domestic fabrication capacity for mechanical tracking hardware.
Conveyor Belt Tracking Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology intensity and service bundling dimensions. The vendor base organizes into three tiers: integrated multinational suppliers with captive manufacturing footprints, specialized regional fabricators with deep mining relationships, and emerging sensor technology specialists targeting predictive maintenance architectures. Consolidation pressure concentrates among mid-scale electromechanical producers facing REACH compliance cost escalation. Dominant competitive moves include backward integration into polymer compounding and geographic expansion through distributor acquisition.
Among integrated multinational suppliers, Flexco and Martin Engineering exemplify archetypes with differentiated positioning strategies. Flexco leverages manufacturing footprint proximity to reduce lead times versus Asian competitors. Martin Engineering anchors market presence through specialized training programs that secure recurring maintenance contract revenue. Tru-Trac occupies a distinct position within the sensor technology specialist tier, concentrating development resources on self-adjusting roller architectures for temperature-extreme environments. These three entities collectively represent the competitive spectrum from mechanical durability emphasis through electronic intelligence integration.
| Leading Market Players |
|---|
| Flexco |
| MLT Group |
| Martin Engineering |
| ASGCO |
| Tru-Trac |
| ContiTech |
| PHOENIX CBS |
| Beltscan Systems |
| Yellotec |
| Others |
Pricing and Supply Chain Analysis
Backward integration into polymer compounding anchors supply position and pricing power for electromechanical tracker manufacturers facing REACH compliance cost escalation. Captive roller production in Ruhr Valley facilities insulates German vendors from Asian elastomer price volatility while compressing lead times for Australian mining procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies around certification grade and after-sales bundling intensity. Premium tiers command position through CE machinery directive pre-certification and bundled maintenance training, while economy tiers serve Indonesian fabricators prioritizing lowest-first-cost procurement. Cost compression in standard tiers is intensifying because REACH-mandated material substitution elongates qualification timelines without commensurate performance gains. Quarry operators in Europe exhibit highest price sensitivity due to fragmented ownership structures, whereas Pilbara iron ore majors prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Elastomer supply rests on German specialty chemical producers, Japanese precision bearing manufacturers, and Chinese steel forging operations for roller frame fabrication. Critical inputs encompass REACH-validated polymer compounds, sealed bearing assemblies rated for abrasive dust ingress, and high-tensile steel for pivot mechanisms. Single-source vulnerability concentrates in optical sensor calibration expertise clustered around Stuttgart and Nagoya engineering corridors. Distribution runs through captive service arms of integrated multinationals and regional distributor networks anchored in Perth, Santiago, and Pittsburgh industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between European REACH compliance costs and Australian mining capital intensity creates margin expansion opportunity for vendors with dual-continent manufacturing footprints.
For Market Incumbents: Cement market position through captive polymer compounding facilities that neutralize ECHA restriction impacts on roller formulations. Prioritize OPC-UA interoperability certification to preempt stranded asset risk from proprietary sensor protocols. Acquire specialized calibration firms in German industrial clusters to lock in laser tracking service revenue against emerging sensor technology specialists. For New Entrants and Emerging Players: Direct-to-mine digital sales channels bypass established distributor relationships in Kalimantan surface coal corridors where manual alignment protocols still dominate. Target retrofit opportunities in Indonesian operations transitioning from mechanical to electromechanical tracking under national mineral directorate technical guidance. Lead with edge-computing roller architectures that reduce latency versus cloud-dependent incumbent systems. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale electromechanical fabricators because CE certification backlogs create twelve-to-eighteen-month barriers against new European market entrants. Long-term viability hinges on sensor fusion capability migration and predictive maintenance contract attachment rates. Monitor OPC-UA standardization adoption velocity across Australian Pilbara installations as inflection indicator for interoperability-premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | REACH compliance cost insulation secures margin position against substitute elastomer volatility. |
| OPC-UA Interoperability Certification | Standardized sensor protocols prevent stranded asset risk in centralized plant control architectures. |
| Edge-Computing Roller Architecture Development | On-roller microprocessors reduce deviation response latency versus cloud-routed competitor systems. |
| Kalimantan Distribution Network Establishment | First-mover positioning captures Indonesian coal corridor transition from manual alignment protocols. |
| Predictive Maintenance Service Unbundling | Separate training and calibration contracts defend margin against pure-play specialist competitors. |
Research Methodology
Multiple input streams — maintenance director interviews at Pilbara iron ore operations, procurement lead discussions with European quarry operators, and technical director engagements at German sensor calibration firms — were reconciled against customs data for roller component trade flows, MSHA incident reports on belt misalignment events, and SEC filings from integrated material handling equipment suppliers. Bottom-up unit demand estimation across mechanized mining corridors was triangulated with top-down replacement cycle analysis under ISO 14890 and CE machinery directive compliance mandates.
Data-stream reconciliation anchored volume projections across the modeling period through segmented modeling of product type, technology intensity, application severity, and end-user procurement consolidation patterns. CAGRs were derived from replacement cycle compression analysis and digital mine investment trajectories. Industry-specific forecast inputs encompassed ECHA polymer restriction timelines and Australian Standards Australia safety mandate enforcement velocity.
The model assumes a particular technology adoption path; alternative pathways for laser tracking standardization would alter the outlook if optical calibration expertise disperses beyond German and Japanese industrial clusters. Forecasts reflect assumptions on REACH reformulation qualification durations and Indonesian regulatory enforcement acceleration. A small set of named triggers — OPC-UA protocol adoption rates, CE certification backlog resolution, and Kalimantan mechanization subsidy programs — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.