
 Reed Switch Market | 2026-2036
Reed Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Reed Switch Market Outlook
Multi-source procurement for hermetically sealed magnetic switches is shifting toward qualified dual-source arrangements as OEMs reduce dependency on single Japanese suppliers. Standex Electronics leverages captive glass-to-metal sealing operations across its Mexico and Germany plants to sustain margin control on Form A variants. Littelfuse anchors North American supply through its automotive-qualified reed relay portfolio, while Nippon Aleph dominates ultra-miniature switches for pacemaker and hearing-aid applications where hermetic integrity is non-negotiable.
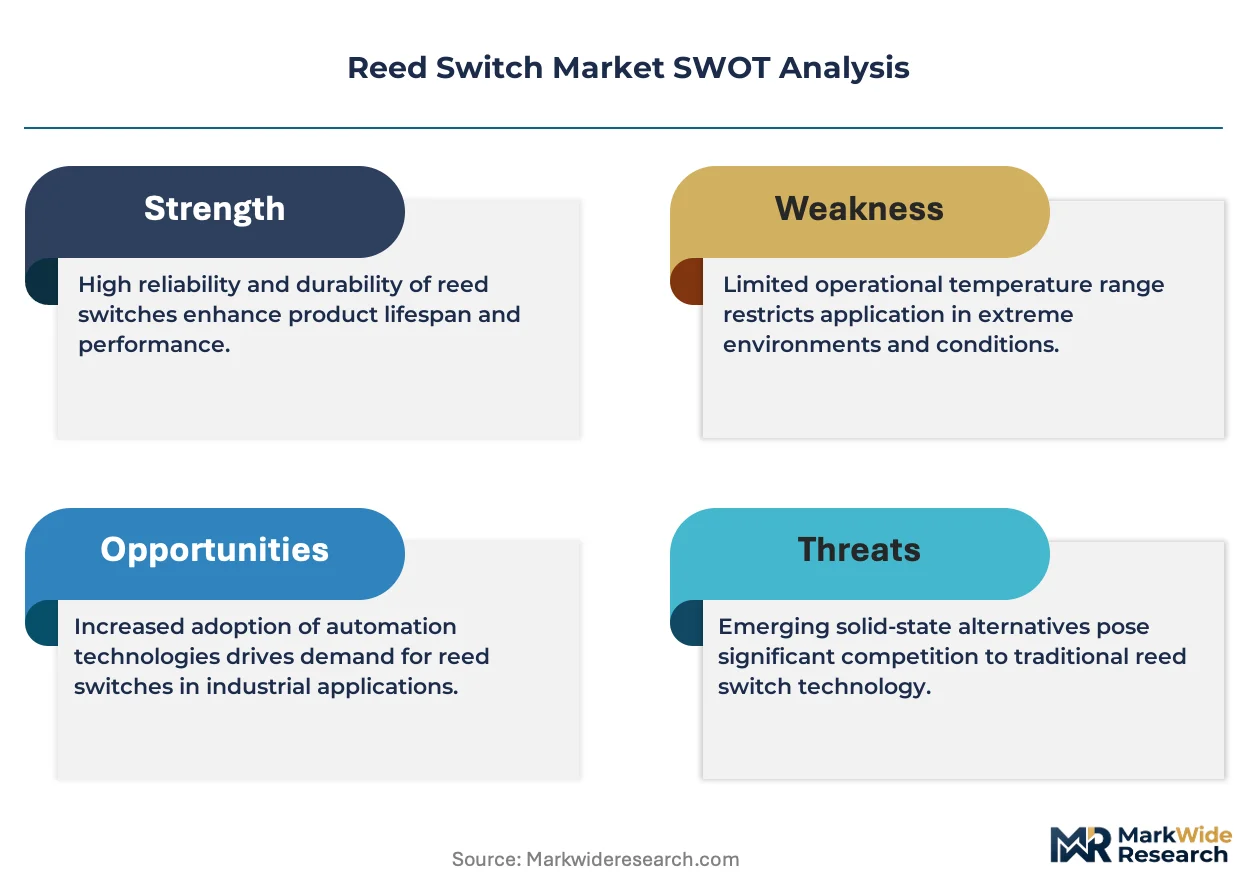
A reed switch is a magnetically actuated electromechanical device comprising ferromagnetic reeds hermetically sealed within a glass envelope containing inert gas, typically switching currents up to one ampere at voltages ranging from millivolts to several hundred volts; its contactless operation eliminates mechanical wear, making it indispensable for position sensing, flow metering, and security loop applications requiring millions of cycles. Form A normally-open configurations occupy the largest volume share due to their simplicity and compatibility with standard relay drivers, while magnetic reed switches command premium positioning in safety-critical aerospace and medical deployments where failure modes must be predictable. Passive technology variants lead unit shipments across consumer appliance and automotive door-latch applications, though active reed switches with integrated signal conditioning are capturing share in industrial automation networks requiring direct PLC interfacing.
FDA device-grade requirements for implantable and patient-contact equipment constrain supplier qualification timelines, while EU REACH restrictions on mercury and cadmium in electrical contacts are accelerating migration to rhodium- and ruthenium-plated reed surfaces. Japan's METI enforces JIS standards on dimensional tolerances and thermal cycling performance that effectively filter out non-specialist manufacturers from precision instrumentation supply chains. Stakeholders must monitor how IEC 61010 safety standards for measurement and control equipment evolve, as revised insulation coordination rules could disqualify legacy reed switch designs from new industrial product certifications.
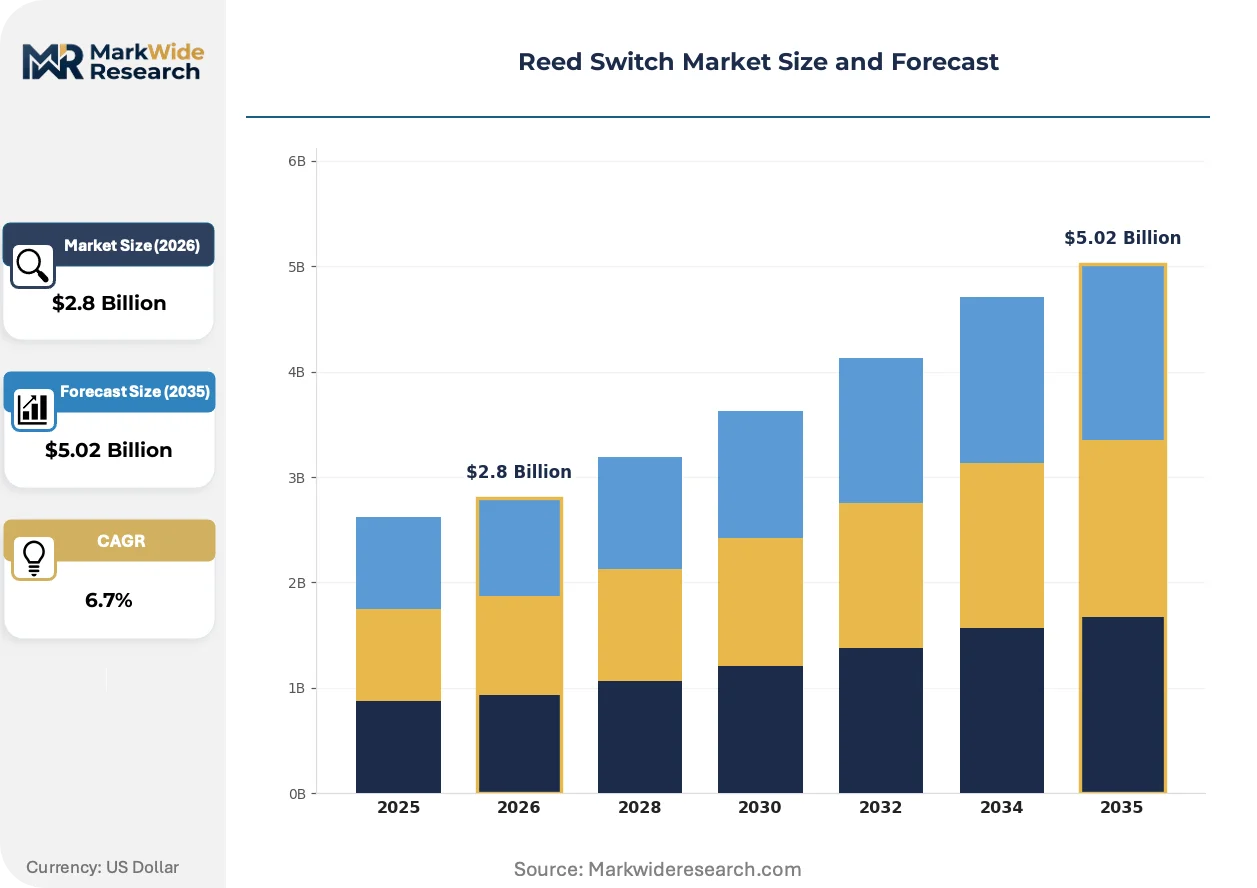
Market Dynamics
Automotive electrification is pulling reed switch demand toward contactless position sensing as battery management systems and motor controls displace mechanical limit switches across hybrid and fully electric platforms. This shift is compressing supplier qualification timelines while elevating hermetic integrity requirements.
Growth Catalysts
- EU REACH restrictions:Mercury and cadmium bans in electrical contacts are accelerating OEM migration to rhodium-plated reed surfaces, expanding addressable market for compliant suppliers.
- East Asian manufacturing clusters:Shenzhen and Nagoya sensor module integrators are sourcing reed switches directly, bypassing traditional distribution layers and concentrating volume with qualified vendors.
- Passive technology variants:Simplified Form A configurations are capturing replacement cycles in consumer appliance door-latch applications where millions of operational cycles justify contactless switching.
Market Restraints
- Rhodium and ruthenium price volatility:Precious metal plating costs for EU-compliant contact surfaces are compressing margins on standard-grade reed switches.
- Japanese supplier concentration:Ultra-miniature hermetic switch supply for pacemaker and hearing-aid applications remains concentrated with single-source qualified vendors, creating procurement risk.
- Solid-state magnetic sensors:Hall-effect and magnetoresistive alternatives are displacing reed switches in cost-sensitive automotive position sensing below 200°C operating thresholds.
Strategic Opportunities
- India appliance manufacturing:BIS efficiency mandates and domestic production incentives are creating first-mover advantage for mercury-free reed switch suppliers establishing local qualification.
- Active reed switch convergence:Integration of signal conditioning electronics with traditional magnetic reed elements is opening direct PLC interfacing in industrial automation networks.
- China dual carbon goals:Stricter appliance efficiency standards under MEE oversight are tightening material specifications and favoring hermetically sealed alternatives in white goods.
Industry Challenges
- FDA device-grade certification timelines:Implantable and patient-contact equipment qualification cycles extend 18-24 months, constraining revenue recognition for new supplier entrants.
- Glass-to-metal sealing capex intensity:Captive hermetic sealing operations require furnace and metallization investments that filter out sub-scale competitors.
- Legacy industrial system integration:Active reed switches with integrated electronics face compatibility friction with established 24V DC relay driver architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reed Switch Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Form A, Form B, Form C, Magnetic Reed Switches Technology: Passive, Active, Digital, Analog End User: Automotive, Aerospace, Consumer Electronics, Industrial Automation Application: Position Sensing, Flow Measurement, Security Systems, Power Management |
| Companies Covered | Standex Electronics, Littelfuse, Coto Technology, TE Connectivity, Nippon Aleph, HSI Sensing, RMCIP, Amphenol Corporation, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reed Switch Market Strategic Shifts
Reed switch architecture is fragmenting into application-specific variants as end-users demand tighter integration with electronic control systems. This evolution is compressing the boundary between passive electromechanical components and intelligent sensor modules.
Magnetic reed switch packaging is modularizing around surface-mount and through-hole configurations optimized for automated assembly lines. Automotive tier-one suppliers are specifying tape-and-reel formats for door-latch and seat-position modules. This standardization is enabling contract manufacturers to consolidate component sourcing across multiple vehicle programs while reducing manual handling damage rates.
EU F-Gas Regulation phase-down schedules are indirectly tightening hermetic sealing requirements as refrigeration compressor manufacturers seek leak-proof alternatives for variable-speed drives. Compressor OEMs in Germany and Italy are qualifying reed switches for oil-level sensing in CO2 transcritical systems. This regulatory pressure is accelerating migration from elastomeric seals toward glass-to-metal construction methods.
Direct sourcing from module integrators is displacing traditional electronic component distribution in high-volume automotive and appliance applications. Tier-one sensor module manufacturers in Mexico and Thailand are establishing vendor-managed inventory programs with qualified reed switch suppliers. This channel compression is most visible in automotive door-latch applications where annual contract volumes exceed ten million units.
Reed Switch Market Segmentation
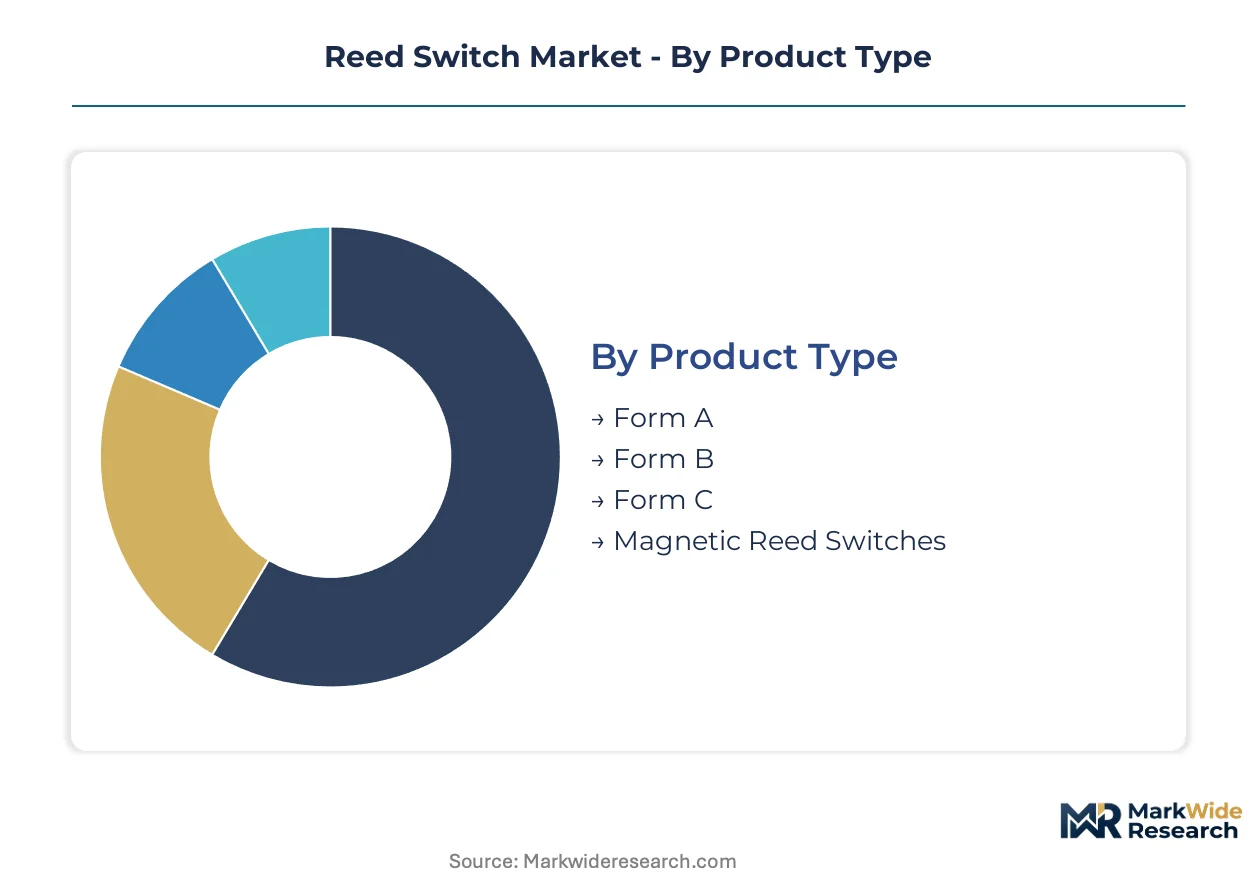
Reed switch segmentation reflects divergent supply chain configurations across passive electromechanical and active electronic variants. Glass-to-metal sealing capabilities concentrate with specialized manufacturers, fragmenting procurement patterns by product complexity and end-use certification requirements.
Product Type:
Supply concentration for hermetically sealed variants tilts toward Japanese and German furnace operators with captive metallization lines.
- Form A:Normally-open configurations employ two ferromagnetic reeds in a simple contact closure arrangement. Automotive door-latch modules in Mexico and Thailand consume the highest volumes, driven by tape-and-reel packaging specifications from tier-one suppliers.
- Magnetic Reed Switches:These variants integrate permanent magnet biasing for precise actuation thresholds. Aerospace position sensing in Germany and medical implantables in Japan command premium positioning due to predictable failure mode requirements under JIS and FDA oversight.
- Form B:Normally-closed arrangements suit safety-critical interrupt circuits.
- Form C:Changeover configurations enable single-pole double-throw functionality in relay replacement applications.
Form A absorbs the bulk of installed capacity; magnetic reed switches are expanding most quickly.
Technology:
Cost tier differentiation separates commodity passive devices from signal-conditioned active variants requiring semiconductor integration.
- Passive:Unpowered magnetic actuation relies solely on reed physical movement for circuit completion. White goods manufacturers in China source these for appliance door-latch applications under tightening MEE efficiency mandates.
- Active:Integrated electronics provide signal conditioning, threshold detection, and direct PLC interfacing. Industrial automation networks in Germany specify these for 24V DC control architectures, though legacy system compatibility creates integration friction.
- Digital:Binary output formats suit microcontroller interface requirements.
- Analog:Variable resistance output enables proportional position sensing.
Passive variants dominate unit shipments; active configurations are climbing the fastest as factory automation demands intelligent edge devices.
End User:
Application maturity varies sharply, with automotive electrification compressing qualification timelines while medical devices extend them.
- Automotive:Battery management systems and motor controls in hybrid platforms displace mechanical limit switches. OEMs in Germany and Japan specify contactless position sensing for electrified powertrains with hermetic integrity requirements.
- Industrial Automation:PLC interfacing and safety loop applications demand millions of operational cycles. Manufacturing clusters around Shenzhen integrate reed switches directly into sensor modules, bypassing distribution layers.
- Aerospace:Predictable failure modes and wide temperature ranges define procurement specifications.
- Consumer Electronics:Hearing aids and portable devices drive miniaturization requirements.
Automotive absorbs the bulk of installed capacity; industrial automation is gaining share fastest through direct sourcing consolidation.
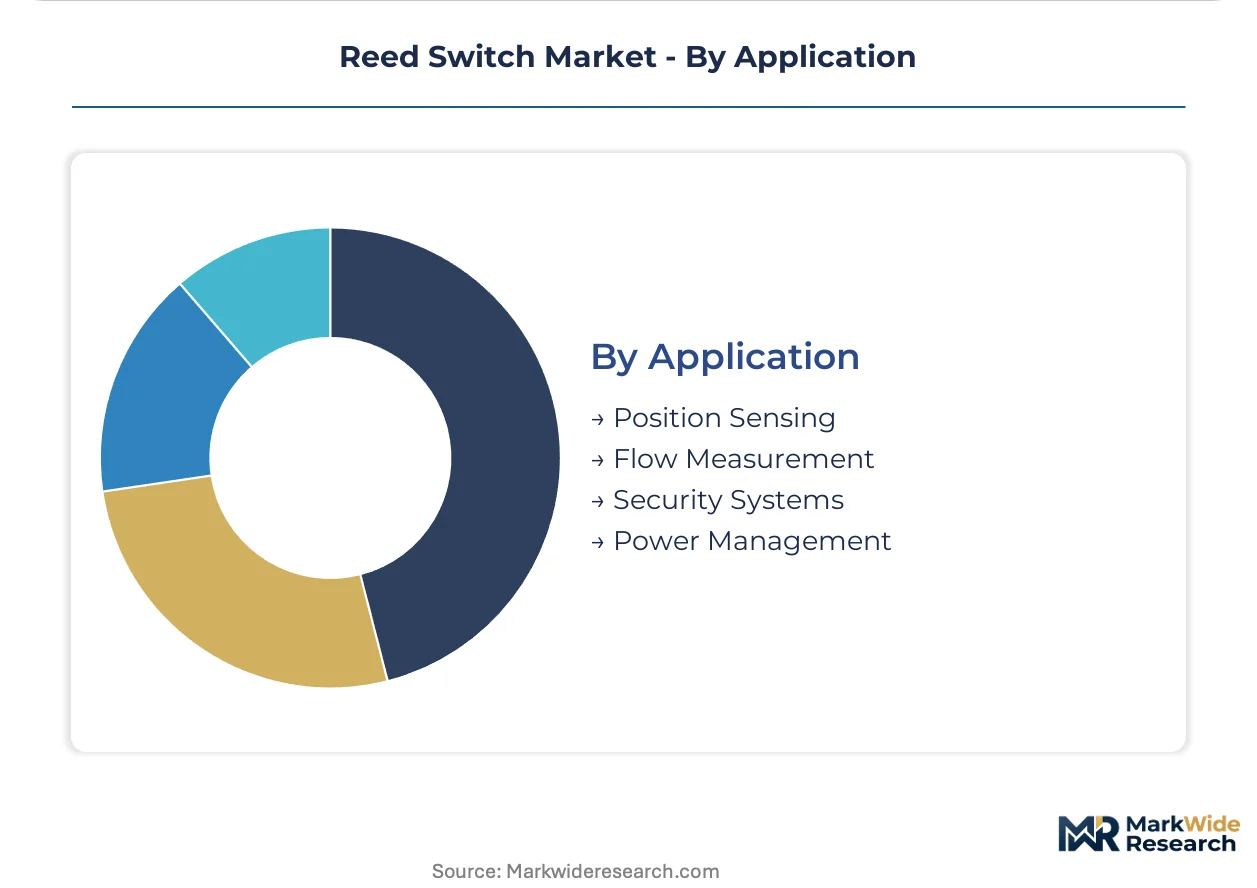
Application:
Volume concentration clusters around position sensing, while regulatory pressure reshapes power management specifications.
- Position Sensing:Contactless detection of mechanical location eliminates wear in high-cycle applications. Seat-position modules and door-latch sensors in automotive programs specify tape-and-reel formats for automated assembly.
- Flow Measurement:Paddle-wheel and turbine meters employ reed switches for pulse generation. EU F-Gas Regulation phase-down schedules tighten hermetic sealing requirements for refrigeration compressor oil-level sensing in CO2 transcritical systems.
- Security Systems:Perimeter loops and access control rely on predictable contact resistance.
- Power Management:Battery isolation and charge control circuits require low-leakage switching.
Position sensing commands the bulk of installed capacity; flow measurement is expanding most quickly through regulatory-driven compressor redesigns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in manufacturing clusters where sensor module integrators source reed switches directly, bypassing traditional distribution layers. East Asian production hubs anchor volume, while European regulatory pressure and North American automotive electrification reshape procurement patterns.
China
Domestic white goods manufacturers under MEE oversight drive mercury-free reed switch consumption for appliance door-latch applications. The country's dual carbon goals tighten material specifications across refrigeration compressor oil-level sensing. Shenzhen sensor module integrators consolidate procurement with qualified vendors, establishing vendor-managed inventory programs.
Germany
Automotive tier-one suppliers specify tape-and-reel formats for electrified powertrain position sensing modules. EU F-Gas Regulation phase-down schedules accelerate hermetic sealing qualification for CO2 transcritical refrigeration systems. Stuttgart and Munich industrial automation clusters integrate active reed switches with PLC architectures.
Japan
Ultra-miniature hermetic switch demand from pacemaker and hearing-aid manufacturers concentrates supply with specialized vendors. METI-enforced JIS standards on dimensional tolerances filter non-specialist manufacturers from precision instrumentation supply chains. Nagoya sensor module integrators source directly from qualified furnace operators.
United States
FDA device-grade certification requirements constrain supplier qualification timelines for implantable equipment. NHTSA safety mandates accelerate contactless position sensing adoption across hybrid and electric vehicle platforms. Mexico-based automotive contract manufacturers establish direct procurement relationships with hermetic sealing specialists.
India
BIS efficiency mandates and domestic production incentives create first-mover positioning for mercury-free reed switch suppliers establishing local qualification. Appliance manufacturing clusters in Maharashtra and Gujarat integrate reed switches into compressor control modules. CDSCO medical device regulations extend supplier certification cycles for patient-contact applications.
Reed Switch Market Competitive Environment
Dual-source procurement arrangements dominate the current landscape as OEMs reduce dependency on single suppliers. The vendor base organizes around three tiers: captive glass-to-metal sealing operators, automotive-qualified relay specialists, and ultra-miniature medical-grade fabricators. Strategic archetypes include hermetic sealing specialists with furnace operations, diversified electromechanical component houses, and precision instrumentation-focused niche players. Capacity expansion in Mexico and Thailand, alongside qualification-driven partnerships with East Asian module integrators, constitutes the primary competitive thrust.
Among Japanese fabricators, Nippon Aleph occupies a position exemplifying ultra-miniature medical-grade specialization. Standex Electronics represents the captive sealing archetype with multi-plant furnace operations. Littelfuse anchors the automotive-qualified tier within North American supply chains. These three entities collectively illustrate how geographic and technical specialization stratifies competitive positioning across the value chain.
| Leading Market Players |
|---|
| Standex Electronics |
| Littelfuse |
| Coto Technology |
| TE Connectivity |
| Nippon Aleph |
| HSI Sensing |
| RMCIP |
| Amphenol Corporation |
| Schneider Electric |
| Others |
Value Chain & Pricing Dynamics
Rhodium spot price volatility cascades through reed switch manufacturing into three distinct pricing tiers, with EU REACH-compliant plating specifications compressing margins on standard-grade units while medical-grade hermetic variants sustain premium positioning through FDA certification moats.
Pricing Analysis
Volume concentrates in commodity Form A door-latch configurations where automotive tier-one buyers in Mexico and Thailand extract scale discounts, while margin accretion clusters in ultra-miniature medical-grade variants for pacemaker applications where Nippon Aleph and specialized Japanese fabricators command price premiums through JIS-certified hermetic integrity. Price differentiation hinges on glass-to-metal sealing furnace ownership and FDA device-grade certification status, with uncertified suppliers facing 40-60% price discounts against qualified vendors. Cost compression in standard-grade automotive position sensing intensifies as Hall-effect magnetic sensors displace reed switches below 200°C thresholds. Appliance manufacturers in China under MEE efficiency mandates exhibit highest price sensitivity, while aerospace procurement teams in Germany prioritize predictable failure modes over unit cost.
Supply Chain Analysis
FDA device-grade and JIS precision instrumentation certifications gate supply access, concentrating captive glass-to-metal sealing operations in Japan, Germany, and Mexico where Standex Electronics and Littelfuse anchor regional supply. Raw material dependencies span rhodium and ruthenium plating metals from South African and Russian refining channels, specialized borosilicate glass tubing from German and Japanese specialty glasshouses, and ferromagnetic reed alloys from precision strip mills in Sweden and Japan. Single-source vulnerability pervades ultra-miniature hermetic switch supply for implantable medical devices, where qualification timelines extending 18-24 months effectively freeze vendor rotation. Distribution runs through direct vendor-managed inventory programs with Shenzhen and Nagoya sensor module integrators, bypassing traditional electronic component distribution layers in high-volume automotive and appliance applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH mercury and cadmium prohibitions erect a cost-of-compliance barrier that entrenches qualified rhodium-plated suppliers against commodity entrants, transforming regulatory adherence into a defendable margin structure.
For Market Incumbents: Deepen captive furnace operations in Mexico and Thailand to defend automotive door-latch volume against Hall-effect magnetic sensor substitution, while accelerating FDA certification pipeline investments to extend medical-grade pricing power against emerging Asian competitors. Prioritize backward integration into rhodium plating lines to buffer precious metal cost volatility compressing standard-grade margins.
For New Entrants and Emerging Players: Active reed switch convergence with integrated signal conditioning electronics offers a technology-first wedge into German industrial automation networks, where legacy 24V DC PLC architectures create integration friction for established passive suppliers. Target India appliance manufacturing clusters in Maharashtra and Gujarat under BIS efficiency mandates, qualifying mercury-free alternatives ahead of incumbent certification cycles. Lead with direct module integrator relationships rather than distribution channel penetration.
For Investors and Strategic Acquirers: Distressed-cycle entries favor hermetic sealing specialists with dormant FDA certifications in Germany and Japan, where CDSCO and PMDA pathway investments have stranded smaller fabricators unable to sustain qualification costs. Long-term viability centers on glass-to-metal furnace ownership and medical-grade certification depth rather than commodity automotive volume exposure. Watch for rhodium price stabilization as inflection signal for standard-grade margin recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Furnace Expansion | Mexico and Thailand capacity additions anchor automotive tier-one supplier relationships against Asian competition. |
| Rhodium Plating Integration | Backward control over EU REACH-compliant contact surfaces buffers precious metal cost volatility. |
| Active Reed Switch Development | Signal conditioning integration opens German industrial automation PLC networks to new entrants. |
| FDA Certification Pipeline | Device-grade qualification moats sustain premium pricing in pacemaker and implantable applications. |
| Direct Module Integrator Partnerships | Vendor-managed inventory programs with Shenzhen sensor houses displace traditional distribution layers. |
Study Parameters
SEC 10-K filings, EU ECHA REACH registration databases, and Japan METI industrial production statistics formed the secondary backbone, supplemented by customs trade data tracking rhodium and ruthenium plating material flows. Primary interviews with glass-to-metal sealing furnace operators, automotive tier-one sensor module procurement directors, and FDA regulatory affairs consultants validated demand assumptions across medical, automotive, and industrial automation segments. Bottom-up unit shipment estimates from Shenzhen and Nagoya manufacturing clusters triangulated against top-down value projections derived from precious metal plating cost models.
Bottom-up volume modeling tracked Form A, magnetic reed, Form B, and Form C configurations across passive, active, digital, and analog technology tiers, while top-down value analysis applied plating cost pass-through coefficients across automotive, industrial automation, aerospace, and consumer electronics end-use segments. CAGRs emerged from regression analysis of historical qualification timeline compression and electrified powertrain adoption curves. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules for refrigeration compressor applications and China MEE dual carbon efficiency mandate enforcement intensity.
Several conditions sit outside the modeled scope, including speculative solid-state magnetic sensor cost curves below 200°C thresholds and unannounced FDA guidance revisions for implantable device hermetic integrity standards. Forecasts reflect assumptions about rhodium supply chain stability and JIS certification maintenance continuity. A model refresh is warranted upon material change in EU REACH enforcement intensity or NHTSA electrified vehicle platform safety mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Europe Low Voltage Switchgear Market
Switches
Antenna Switch Module Market
Switches
Matrix Switches Market
Switches
Fusible Switches Market
Switches
Optical Switches Market
Switches
North America Push Buttons & Signaling Devices Market
Switches
Mexico Rocker Switch Market
Switches
Tactile Switch Keyboard Market
Switches
Pressure Switch Market
Switches
South Korea Reed Sensors Switches Market
Switches
Molded Case Circuit Breaker Market
Switches
Rocker Switch Market
Switches
United States Switchgear Market
Switches
Paralleling Switchgear Market
Switches
Level Switches Market
Switches
North America MV Switchgear Market