
 Fusible Switches Market | 2026-2036
Fusible Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Fusible Switches Market Insights
North American electrical component manufacturing is realigning around reshoring incentives and domestic content thresholds for federally funded infrastructure projects. Littelfuse leverages its vertically fused product portfolio to serve utility-scale solar installations across the southwestern United States. Eaton anchors its position through extensive distribution partnerships with industrial supply houses serving the MRO channel. ABB competes on IEC-certified switchgear platforms that bridge North American and European specification requirements.
Fusible switches combine a disconnect mechanism with an integrated overcurrent protection element, typically employing silver or copper fuse links within a molded housing rated for specific fault-current interruption capacities; they serve primarily to isolate circuits safely while protecting downstream equipment from thermal damage during overload or short-circuit events. Panel mount configurations dominate unit volumes in commercial construction, while medium-voltage switchgear commands the largest margin pools due to engineering intensity and certification barriers. Motor disconnect applications are expanding fastest in food-processing plants where NFPA 70E arc-flash compliance mandates visible-blade isolation points.
UL 98 and UL 508 standards govern fusible switch construction and performance testing in the United States, while the EU's Low Voltage Directive and CE marking requirements shape product access across European member states. OSHA enforcement of electrical safe-work practices and the EPA's evolving rules on SF6-containing switchgear alternatives are redirecting specification trends toward air-insulated fused disconnects. Stakeholders must monitor how dual carbon mandates in key manufacturing economies reshape material sourcing and end-of-life recovery obligations for fuse-element metals.
Market Dynamics
Data center rack densities are forcing specification upgrades across medium-voltage fusible disconnects, while NEC Article 240 coordination mandates are rewiring procurement priorities for electrical contractors and facility engineers.
Growth Catalysts
- Industrial Automation Corridor Demand:Germany's machine-tool OEMs specify fused disconnect switches to satisfy CE-marked machinery compliance, pulling procurement volumes through the Ruhr manufacturing belt.
- Utility-Scale Solar Expansion:Southwestern United States solar developers deploy medium-voltage fusible disconnects to isolate inverter stations and collector circuits under FERC interconnection standards.
- NFPA 70E Arc-Flash Mandates:Food-processing plants across the Midwest install visible-blade fusible motor disconnects to satisfy OSHA electrical safe-work practice enforcement.
Market Restraints
- Silver and Copper Fuse Element Volatility:Precious metal price swings compress margin predictability for fuse-link manufacturers dependent on COMEX-traded raw materials.
- SF6 Phase-Out Regulatory Pressure:EPA rules on greenhouse gas-containing switchgear alternatives force R&D redirection toward air-insulated designs with lower interrupting ratings.
- IEC-UL Certification Duality:Dual-standard testing requirements for products bridging European and North American markets extend time-to-revenue by eight to fourteen months.
Strategic Opportunities
- Reshoring Procurement Tailwinds:Domestic content thresholds in federally funded infrastructure projects redirect specification authority toward UL-certified suppliers with captive North American manufacturing.
- End-of-Life Metal Recovery:Dual carbon mandates in key manufacturing economies are creating structured take-back obligations for silver-alloy fuse elements, opening circular-economy service revenue.
- MRO Channel Digitization:Industrial supply houses are consolidating online procurement portals for fusible switch replenishment, compressing distributor tiers and expanding direct manufacturer access.
Industry Challenges
- Medium-Voltage Engineering Talent Scarcity:Specialized switchgear design expertise concentrates among aging engineering cohorts, constraining product development velocity for next-generation arc-resistant housings.
- Legacy System Integration Friction:Retrofit installations in brownfield industrial facilities require custom bus-bar configurations, extending project engineering cycles and inflating non-recurring engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fusible Switches Market |
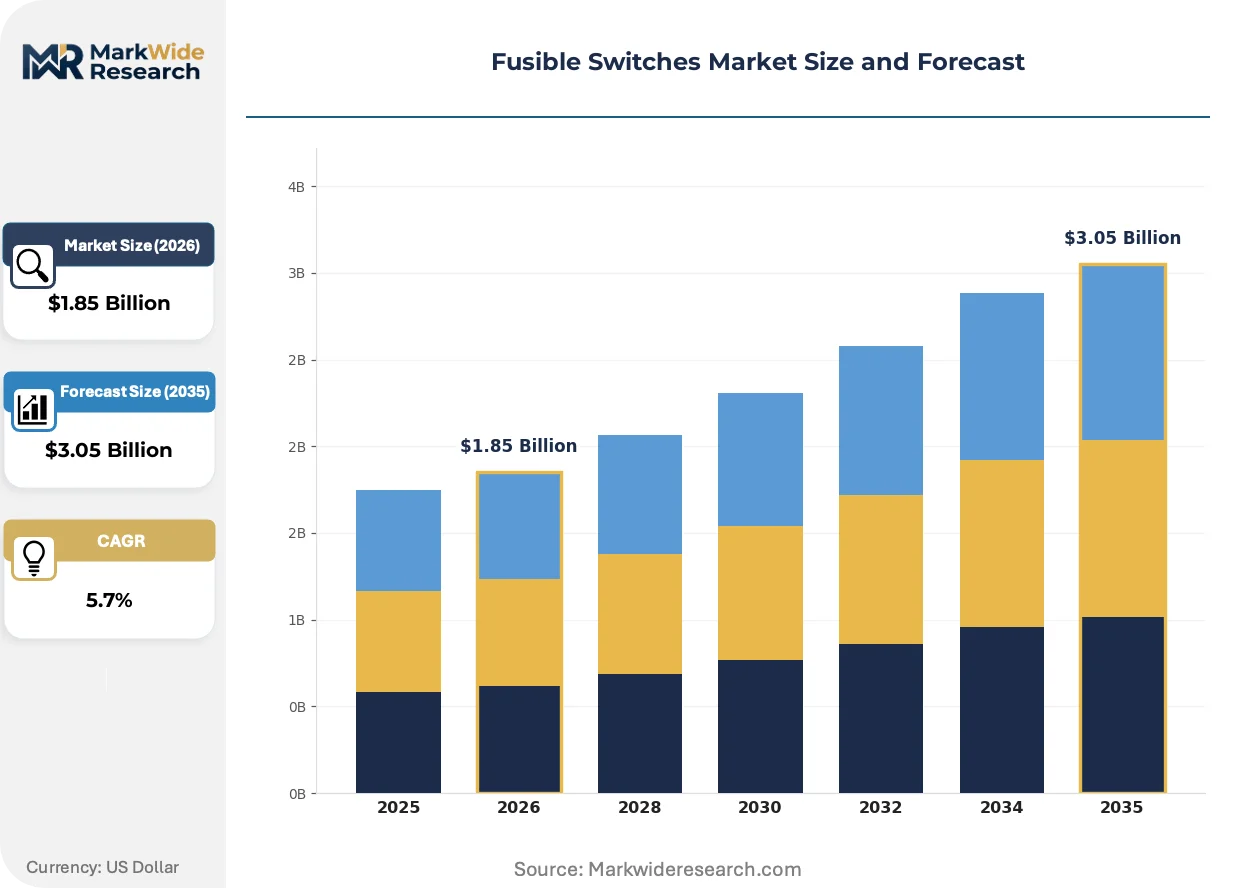
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Mount, Load Break, Motor Disconnect, Switchgear Installation Type: Indoor, Outdoor, Surface-Mounted, Flush-Mounted End User: Manufacturing, Power Generation, Oil & Gas, Transportation Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage |
| Companies Covered | Littelfuse, Eaton, ABB, Schneider Electric, Siemens, Mersen, Rockwell Automation, General Electric, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fusible Switches Market Trends and Innovations
Fusible switch architectures are converging with digital monitoring capabilities and modular housing designs, compressing the traditional separation between protection, isolation, and condition-aware asset management.
Smart fuse monitoring is integrating microprocessor-based temperature and current sensing directly into fusible switch housings, enabling predictive maintenance alerts before thermal degradation compromises protection integrity. Data center operators in hyperscale facilities are piloting these units to reduce unplanned downtime during thermal runaway events. This convergence is integrating protection hardware with building management system protocols, collapsing the procurement categories that historically separated switches from sensors.
OSHA enforcement of electrical safe-work practices is tightening visible-blade isolation requirements across industrial maintenance protocols, forcing specification upgrades in legacy motor control centers. The agency's emphasis on arc-flash boundary calculations is redirecting capital toward fusible disconnects with enhanced fault-current interrupting visibility. Food-processing and pharmaceutical clean-room environments are responding fastest, driven by combined pressure from worker safety audits and insurance underwriting standards.
Specification authority is migrating from electrical contractors toward facility engineering departments with centralized asset-management platforms, compressing the traditional distributor-mediated procurement cycle. Industrial buyers are unbundling after-sales service contracts from hardware purchases, preferring third-party maintenance providers with multi-brand capabilities. This behavioral shift is most pronounced in automotive manufacturing clusters, where plant engineering teams standardize on common fusible switch platforms across multiple production lines to simplify spare parts logistics.
Fusible Switches Market Segmentation
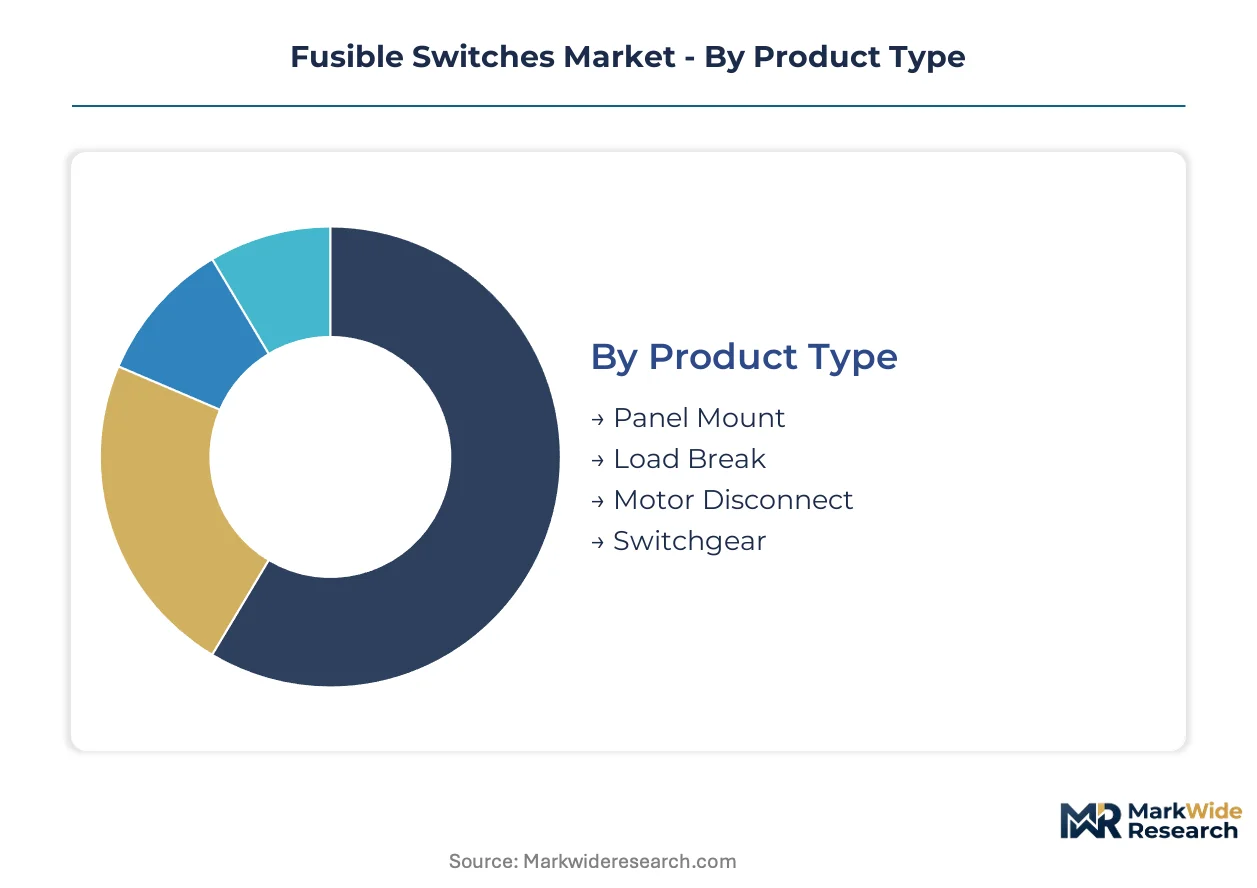
Fusible switch procurement patterns diverge sharply across voltage tiers and installation environments, with specification authority migrating from contractors toward facility engineering departments. Segment boundaries are blurring as smart monitoring capabilities integrate across traditional product categories, collapsing historical distinctions between protection hardware and condition-aware asset management.
Product Type:
Voltage interruption capacity and fault-current coordination requirements determine specification logic across the four product architectures.
- Panel Mount:Molded housings with integrated fuse holders dominate commercial construction unit volumes, serving branch circuit protection in retail and office buildings where NEC Article 240 coordination mandates drive procurement. Contractors in the southwestern United States specify these for utility-scale solar collector circuits under FERC interconnection standards.
- Load Break:Visible-blade designs with enhanced arc-quenching chambers command premium positioning in industrial MRO channels, isolating energized circuits during maintenance windows. Food-processing plants across the Midwest deploy these to satisfy OSHA arc-flash boundary enforcement and NFPA 70E visible-isolation requirements.
- Motor Disconnect:Compact fusible units with rotary handles protect motor branch circuits in manufacturing environments, climbing fastest as automotive OEMs standardize platforms across production lines to simplify spare parts logistics.
- Switchgear:Metal-enclosed assemblies with drawout fuse elements serve medium-voltage distribution nodes, facing R&D redirection toward air-insulated alternatives as EPA SF6 phase-out rules tighten.
Panel Mount leads on scale; Motor Disconnect leads on momentum.
Installation Type:
Environmental exposure ratings and enclosure IP classifications segment procurement across facility infrastructure types.
- Indoor:NEMA 1 and NEMA 12 enclosures protect against dust and incidental contact, concentrating in clean-room pharmaceutical manufacturing where contamination control overrides cost considerations.
- Outdoor:NEMA 3R and NEMA 4X housings withstand precipitation and corrosive atmospheres, serving solar inverter stations and substation yard installations across desert and coastal climates.
- Surface-Mounted:External box configurations simplify retrofit installation in brownfield industrial facilities, though custom bus-bar requirements extend project engineering cycles.
- Flush-Mounted:Recessed designs integrate with architectural finishes in commercial buildings, gaining share in data center white spaces where aisle containment aesthetics matter.
Indoor commands the largest installed base; Outdoor is expanding most quickly.
End User:
Operational criticality and maintenance protocol stringency shape fuse coordination requirements across industrial sectors.
- Manufacturing:Machine-tool OEMs in Germany's Ruhr corridor specify fused disconnect switches for CE-marked machinery compliance, pulling procurement through industrial automation supply chains.
- Power Generation:Utility-scale solar developers deploy medium-voltage fusible disconnects to isolate inverter stations, with southwestern United States installations driving specification volume under domestic content thresholds.
- Oil & Gas:Hazardous-location rated enclosures serve upstream and midstream facilities, though project deferrals in exploration segments are compressing near-term demand.
- Transportation:Traction power and charging infrastructure applications are emerging, constrained by specialized engineering talent scarcity for arc-resistant housing design.
Manufacturing dominates current revenue; Power Generation shows the steepest expansion trajectory.
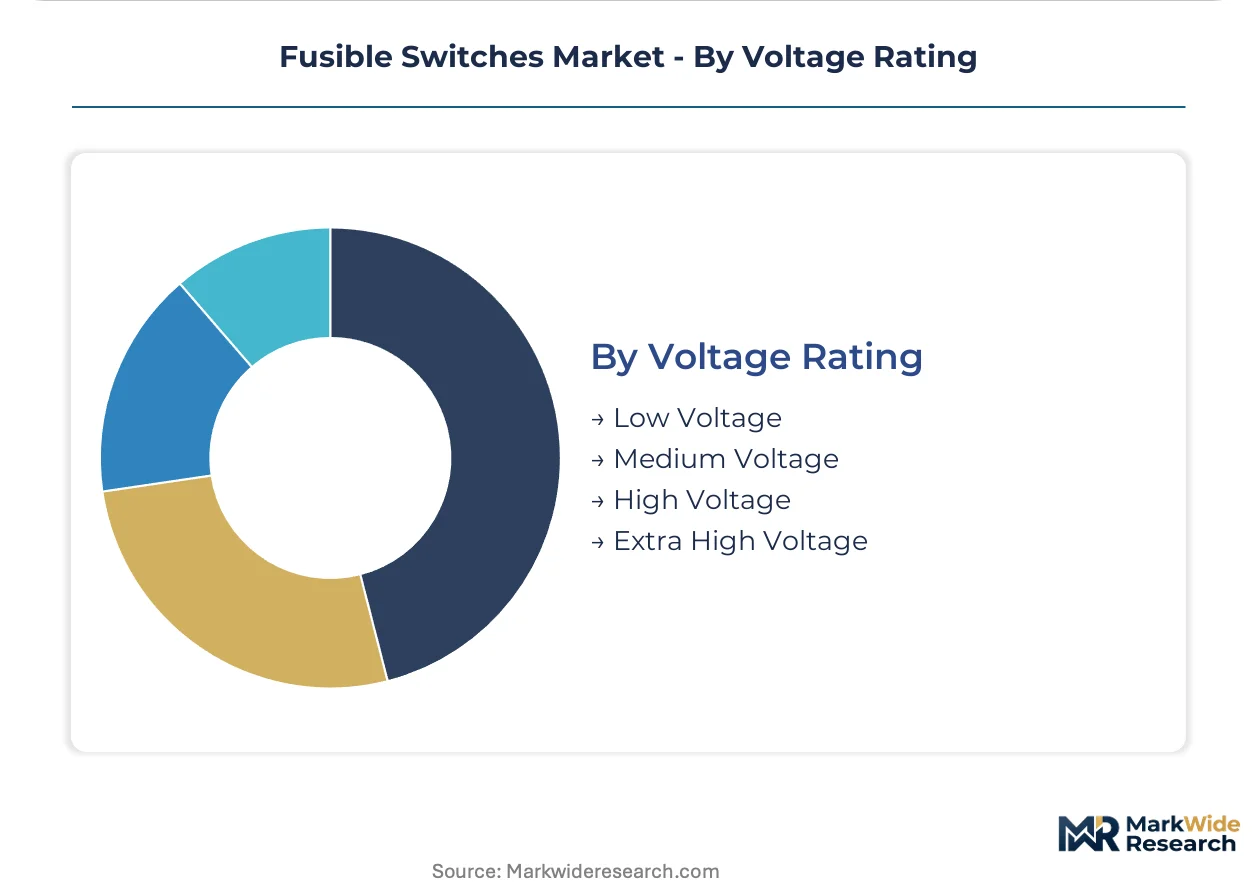
Voltage Rating:
Interrupting capacity and certification complexity stratify margin pools across the electrical hierarchy.
- Low Voltage:600V-class devices serve residential and light commercial branch circuits, competing on cost efficiency in highly price-sensitive construction segments.
- Medium Voltage:5kV to 38kV ratings command the largest margin pools due to engineering intensity and UL/IEC dual certification barriers, with data center operators upgrading specifications to manage rising rack densities.
- High Voltage:69kV to 230kV applications concentrate in utility transmission infrastructure, facing extended time-to-revenue from dual-standard testing requirements.
- Extra High Voltage:345kV-plus ratings serve grid interconnection points, limited to specialized manufacturers with captive high-voltage testing facilities.
Medium Voltage leads on margin contribution; Low Voltage leads on unit volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting fusible switch production toward jurisdictions with streamlined certification pathways, as dual UL-IEC testing requirements inflate time-to-revenue by eight to fourteen months for manufacturers serving multiple markets.
United States
Data center operators across Virginia's Loudoun County and Texas's Dallas-Fort Worth corridor are upgrading medium-voltage fusible disconnect specifications to manage rising rack densities. NEC Article 240 coordination mandates are tightening procurement priorities for electrical contractors serving federally funded infrastructure projects. Southwestern solar developers in Arizona and California deploy these switches under FERC interconnection standards to isolate inverter stations.
Germany
Machine-tool OEMs in the Ruhr industrial belt specify fused disconnect switches to satisfy CE-marked machinery compliance requirements under the EU's Low Voltage Directive. Germany's industrial automation corridor pulls procurement volumes through supply chains serving automotive and precision manufacturing clusters. The country's national electrical safety regulator enforces stringent coordination standards that favor certified switchgear platforms.
China
Domestic content thresholds in state-funded renewable energy projects are redirecting specification authority toward locally certified suppliers with captive manufacturing. The country's dual carbon goals are creating structured take-back obligations for silver-alloy fuse elements in key manufacturing provinces. Yangtze River Delta industrial zones are consolidating procurement through centralized asset-management platforms.
India
Utility-scale solar installations in Gujarat and Rajasthan are driving specification volume for medium-voltage fusible disconnects under national renewable energy targets. The country's Central Electricity Authority mandates technical standards for grid interconnection equipment that shape product access. Maharashtra's automotive manufacturing clusters are standardizing fusible switch platforms across multiple production lines.
Japan
Semiconductor fabrication facilities in Kyushu's Kumamoto region require visible-blade fusible disconnects to satisfy strict electrical safe-work practice protocols. METI industrial efficiency standards are accelerating specification upgrades in legacy motor control centers. The country's precision manufacturing base maintains demand for high-reliability switchgear with enhanced fault-current interrupting visibility.
Fusible Switches Market Competitive Landscape
North American producers anchor the premium-tier segment through vertically integrated fuse-link manufacturing; European specialists hold position on IEC-certified platforms that bridge specification requirements across jurisdictions. The vendor base stratifies across three tiers: multinational electrical conglomerates with captive distribution networks, mid-cap specialists focused on medium-voltage engineering intensity, and regional fabricators serving price-sensitive construction segments. Dominant competitive moves include strategic partnerships with industrial supply houses and geographic expansion through distribution tier compression.
Among diversified electrical conglomerates, Eaton and ABB occupy positions representing scale-driven portfolio breadth and dual-standard certification capability respectively. Littelfuse exemplifies the specialist archetype with concentrated exposure to fuse-element technologies. These three entities represent the competitive anchors around which procurement patterns and specification authority are consolidating across data center, solar, and industrial automation end markets.
| Leading Market Players |
|---|
| Littelfuse |
| Eaton |
| ABB |
| Schneider Electric |
| Siemens |
| Mersen |
| Rockwell Automation |
| General Electric |
| Mitsubishi Electric |
| Others |
Pricing and Supply Chain Analysis
Air-insulated switchgear R&D redirection simultaneously compresses engineering cost curves and consolidates procurement authority toward captive North American manufacturers with UL-certified testing facilities. Silver-alloy fuse element volatility feeds directly into margin predictability concerns for fuse-link producers dependent on COMEX-traded raw materials.
Pricing Analysis
Distributor markups in industrial supply houses compress as MRO channel digitization collapses procurement tiers and expands direct manufacturer access. Three-tier pricing structure across premium, standard, and economy levels differentiates by UL/IEC dual certification status and after-sales service bundling. Cost compression in low-voltage panel mount segments intensifies because of commodity copper pricing and construction sector price sensitivity. Solar developers and data center operators show least price sensitivity due to project finance structures and uptime premium valuation.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale data center and utility-scale solar demand, while industrial supply houses mediate fragmented MRO replenishment. Manufacturing concentrates in the United States, Germany, and China, with each jurisdiction serving distinct certification ecosystems. Silver and copper fuse elements, arc-quenching ceramic housings, and microprocessor-based monitoring modules constitute critical input dependencies. Single-source vulnerability in specialized medium-voltage engineering talent constrains product development velocity for next-generation arc-resistant designs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
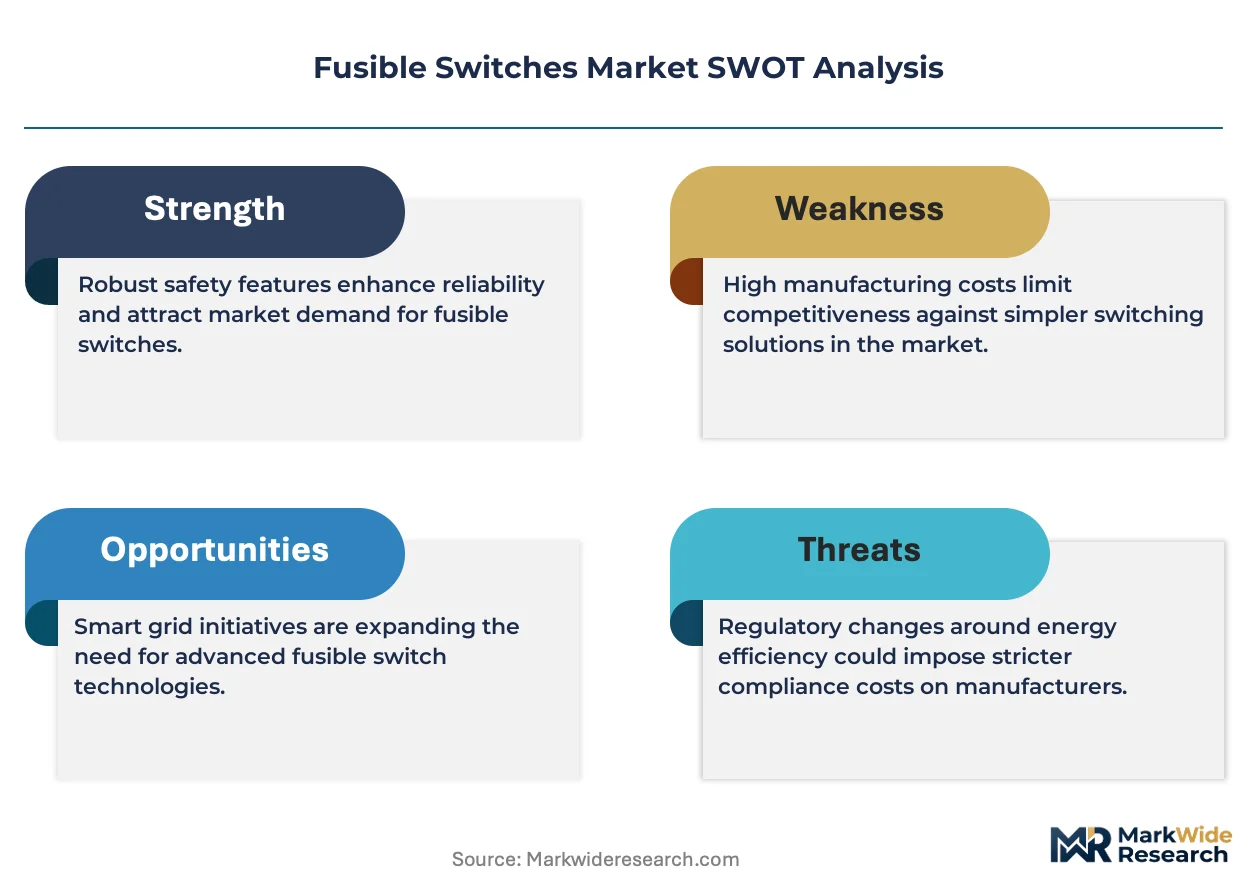
This market operates as a geographic-arbitrage play where dual UL-IEC certification requirements inflate time-to-revenue by eight to fourteen months, favoring incumbent suppliers with streamlined North American testing pathways over European competitors facing extended approval cycles.
For Market Incumbents: Anticipate margin pressure from emerging air-insulated switchgear specialists by deepening backward integration into silver-alloy fuse element production and securing captive recycling capabilities for end-of-life metal recovery. Prioritize certification investment in EPA-compliant SF6-free designs to preempt regulatory displacement. Channel control through exclusive industrial supply house partnerships defends against direct procurement migration. For New Entrants and Emerging Players: Brownfield industrial retrofit contractors represent an underserved buyer archetype with extended project engineering cycles and custom bus-bar requirements that larger incumbents disfavor. Food-processing plant engineering departments in the Midwest offer penetrable entry points given NFPA 70E compliance urgency and visible-blade specification mandates. A go-to-market angle anchored on rapid-turn custom configuration capabilities bypasses standardized product catalog limitations. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap specialists with concentrated medium-voltage engineering expertise and aging founder ownership. Long-term viability hinges on circular-economy service revenue from structured fuse-element take-back obligations under dual carbon mandates. The signal to watch is EPA enforcement acceleration on SF6 phase-out timelines, which would reprice air-insulated technology leaders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fuse Element Production | Captive supply of silver-alloy materials insulates margin predictability from COMEX volatility. |
| Dual Certification Investment | Simultaneous UL 98 and IEC pursuit collapses time-to-revenue for transatlantic market access. |
| Air-Insulated Switchgear R&D Expansion | EPA SF6 phase-out rules redirect specification trends toward greenhouse-gas-free alternatives. |
| Circular Economy Service Development | Structured take-back obligations for fuse-element metals open recurring revenue under carbon mandates. |
| MRO Channel Digitization Partnership | Direct manufacturer access through online procurement portals compresses distributor tier economics. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with plant engineers, electrical contractors, OEM procurement teams, and aftermarket service heads with secondary validation. Secondary sources include UL certification databases, NEC Article 240 regulatory filings, FERC interconnection standards documentation, and industrial supply house procurement records. Bottom-up unit demand modeling triangulates against top-down market size estimates from trade association data.
Granularity-level modeling disaggregates volume and value across voltage rating tiers, installation environment classifications, and end-use sector applications throughout the forecast period. CAGRs derive from regression analysis against industrial capital expenditure cycles, renewable energy deployment trajectories, and data center construction permits. Industry-specific inputs include silver price forward curves, SF6 regulatory phase-out schedules, and electrical contractor wage inflation indices.
Inputs from regulatory filing databases and primary fieldwork were available through the study window; gaps in real-time procurement transaction data introduce uncertainty bands around distributor channel estimates. Forecasts reflect documented assumptions regarding NEC adoption timelines and EPA enforcement intensity. Periodic stress-testing of base assumptions against commodity price shocks and certification backlog fluctuations is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Residual Current Circuit Breaker Market
Switches
Haptic Feedback Switch and Button Platforms Market
Switches
High-Voltage Disconnect Switch Market
Switches
Electric Switch Market
Switches
DC Circuit Breaker Market
Switches
5G Electromechanical RF Switch Market
Switches
Brazil Switchgear Market
Switches
Dual Power Transfer Switches Market
Switches
China Switchgear Market
Switches
Push Button Dropper Market
Switches
Analog Switches Market
Switches
Europe Low Voltage Switchgear Market
Switches
Global Safety Switches Market
Switches
Proximity Switches Market
Switches
ASEAN Switchgear Market
Switches
Canada Switch Gear Market