
 Ozone Meter Market | 2026-2036
Ozone Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Ozone Meter Market Intelligence
Modular sensor-head configurations is realigning buyer choice in the ozone meter landscape. 2B Technologies leverages compact, field-swappable electrochemical modules to compete in environmental monitoring deployments. DKK-TOA Corporation anchors its position through UV absorption platforms calibrated to Japanese Industrial Standards precision thresholds. Teledyne API sustains technology leadership in gas-phase chemiluminescence systems for regulatory-grade ambient monitoring networks.
An ozone meter measures ozone concentration in air or water using electrochemical cells, UV absorption spectroscopy, or semiconductor sensing elements, typically resolving parts-per-billion levels for compliance and process control. Portable ozone meters command premium pricing in emergency response and field audit applications where mobility outweighs laboratory precision. Fixed ozone meters dominate industrial emission control installations, while online ozone sensors capture recurring revenue through subscription calibration services tied to water treatment plant automation.
The US EPA enforces National Ambient Air Quality Standards that mandate continuous ozone monitoring, compelling environmental agencies to maintain certified analyzer fleets. Japan's METI oversees industrial emissions disclosure rules that drive fixed sensor adoption at manufacturing facilities. Stakeholders must weigh electrochemical cost efficiency against UV absorption regulatory acceptance when specifying next-generation procurement frameworks.
Market Dynamics
Portable electrochemical modules are displacing fixed UV systems in environmental monitoring deployments, compressing procurement cycles from twelve-month capital budgets to six-week operational expenditures.
Growth Catalysts
- EU Drinking Water Directive thresholds:German water utilities accelerate portable ozone meter procurement to meet tightened contaminant limits. Municipal testing protocols now mandate field-verifiable dissolved ozone readings.
- Semiconductor cleanroom protocols:East Asian fabrication clusters deploy fixed ozone sensors for airborne molecular contamination control. Process tool manufacturers specify continuous monitoring as a qualification requirement.
- Electrochemical miniaturization:Field-swappable sensor heads reduce calibration downtime from days to hours. Environmental contractors prioritize mobility over laboratory-grade precision.
Market Restraints
- Precious metal electrode costs:Platinum and iridium price volatility squeezes electrochemical sensor margins. Manufacturers pass input cost swings through annual contract renegotiations.
- UV lamp supply concentration:Mercury-free UV source fabrication concentrates in Japanese and German specialty lamp foundries. Disruption risks elevate lead times for regulatory-grade analyzers.
- Cross-sensitivity limitations:Electrochemical cells exhibit interference from nitrogen dioxide and chlorine compounds. Ambient monitoring networks favor UV absorption despite higher capital outlay.
Strategic Opportunities
- India water treatment automation:Smart city initiatives drive online ozone sensor deployment at municipal disinfection plants. Subscription calibration services capture recurring revenue streams.
- Pharmaceutical sterilization validation:VHP (vaporized hydrogen peroxide) cycle monitoring creates demand for combined ozone-peroxide sensors. Contract manufacturers seek integrated environmental monitoring suites.
- Wastewater reuse mandates:California's Title 22 regulations compel advanced oxidation process verification. Industrial reclamation facilities specify continuous ozone residual monitoring.
Industry Challenges
- EPA-equivalent method certification timelines:New analyzer designs require eighteen to thirty-six months for Federal Reference Method equivalence determination. Product development cycles misalign with procurement windows.
- Legacy SCADA integration complexity:Water treatment plant automation systems operate on proprietary communication protocols. Sensor vendors must maintain multiple fieldbus translators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ozone Meter Market |
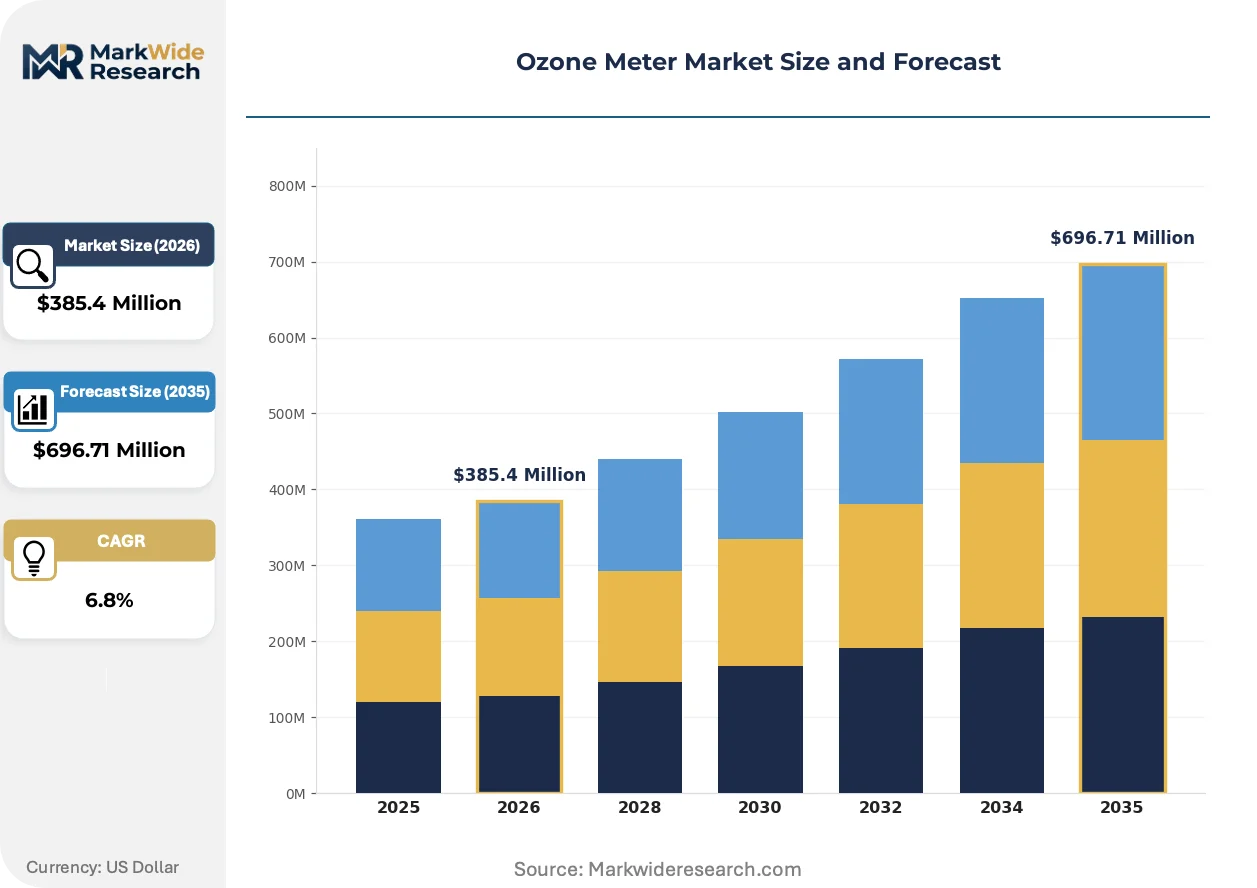
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Ozone Meters, Fixed Ozone Meters, Online Ozone Sensors, Handheld Ozone Detectors Technology: Electrochemical, UV Absorption, Metal Oxide Semiconductor, Gas-Phase Chemiluminescence Application: Environmental Monitoring, Industrial Emission Control, Water Treatment, Food Packaging End User: Environmental Agencies, Water Utilities, Research Laboratories, Food Processing Companies |
| Companies Covered | DKK-TOA Corporation, Emerson Electric, 2B Technologies, Teledyne API, Hach, Aeroqual, Eco Sensors, Ozone Solutions, BMT Messtechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ozone Meter Market Strategic Shifts & Innovations
Sensor fusion architectures are collapsing single-parameter instruments into multi-analyte platforms. Vendors compete on integration depth rather than standalone accuracy specifications.
MEMS-based electrochemical arrays is converging with machine learning drift-correction algorithms. Semiconductor fabs in South Korea and Taiwan adopt these compact modules for spatially dense cleanroom mapping. The technology is converging with predictive maintenance platforms, compressing sensor replacement cycles from annual to condition-based triggers.
Japan's METI industrial emissions disclosure framework tightens reporting granularity for volatile organic compound precursors. Manufacturing facilities must install continuous ozone monitors as proxy indicators of photochemical reactivity. Chemical processors in the Kanto and Kansai corridors accelerate fixed sensor deployment to preempt enforcement actions.
Buyers unbundle hardware procurement from calibration service contracts. Water utilities negotiate separate agreements for sensor supply and third-party verification. This pattern concentrates in North American municipal markets where public purchasing rules favor competitive service rebidding.
Ozone Meter Market Segmentation
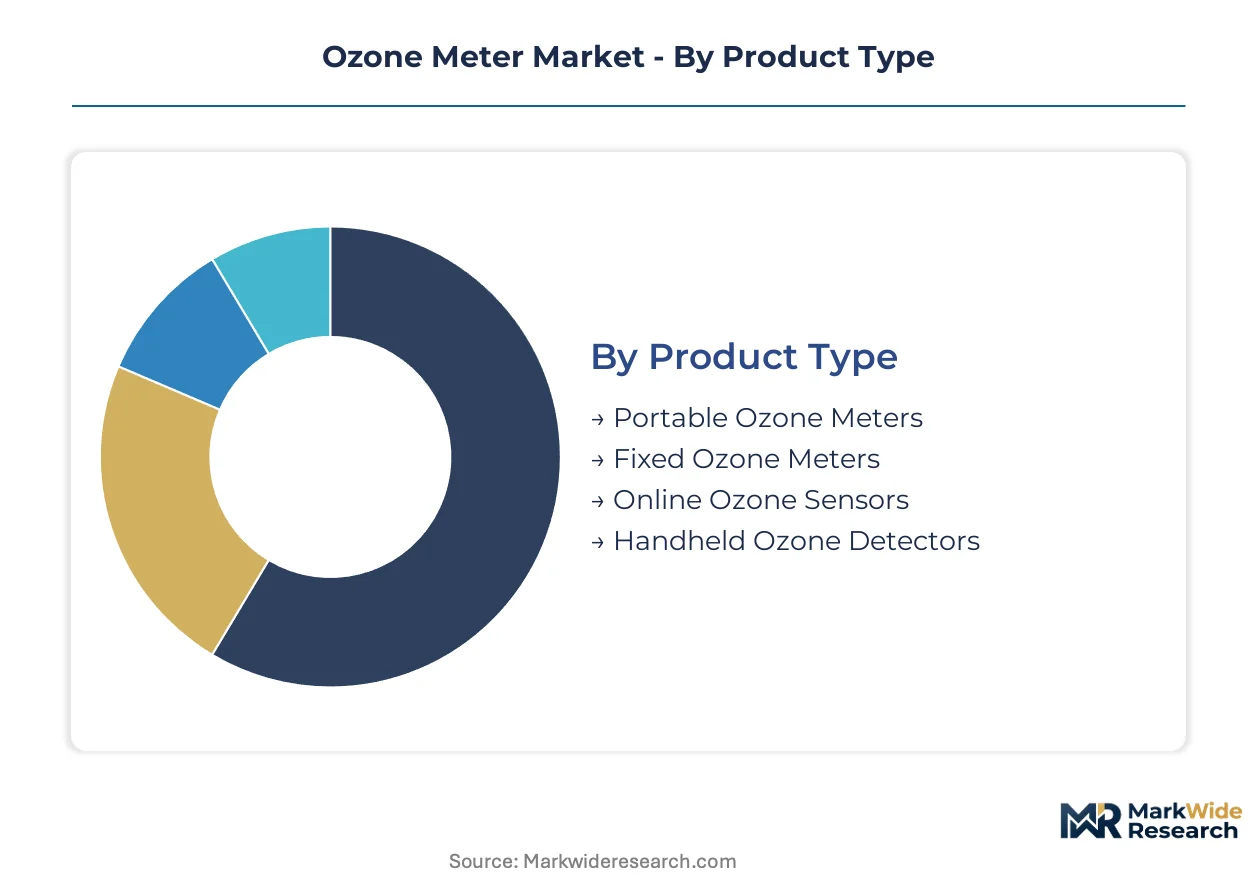
Segmentation in the ozone meter market reflects divergent buyer priorities across mobility requirements, regulatory compliance tiers, and process integration depth. Procurement frameworks differ sharply between environmental agencies seeking field-deployable units and industrial facilities requiring continuous fixed installations.
Product Type:
The customization-to-standardization spectrum stretches from fully configurable portable units to mass-produced fixed sensors with locked specifications.
- Portable Ozone Meters:Battery-powered electrochemical or UV-based units with data logging and GPS tagging for field audits. German water utilities under the EU Drinking Water Directive deploy these for municipal testing protocols requiring dissolved ozone verification at distribution points.
- Fixed Ozone Meters:Wall-mounted or rack-mounted systems with hardwired power and analog output for SCADA integration. East Asian semiconductor fabs specify these for cleanroom airborne molecular contamination control as a process tool qualification requirement.
- Online Ozone Sensors:Submersible or flow-through probes with 4-20mA output for water treatment plant automation.
- Handheld Ozone Detectors:Single-purpose alarms with audible alerts for emergency response and confined space entry.
Most installed capacity flows through Fixed Ozone Meters. Expansion is steepest in Online Ozone Sensors.
Technology:
Cost tier stratification separates regulatory-grade capital equipment from operational expenditure instruments for field contractors.
- Electrochemical:Amperometric cells using precious metal electrodes to resolve parts-per-billion concentrations at lower capital cost. Field-swappable sensor heads reduce calibration downtime, driving adoption among environmental contractors prioritizing mobility.
- UV Absorption:Spectroscopic measurement at 254nm wavelength with mercury or mercury-free lamp sources. US EPA Federal Reference Method equivalence drives demand despite higher capital outlay and Japanese-German lamp supply concentration risks.
- Metal Oxide Semiconductor:Tin oxide or tungsten oxide films with resistance changes proportional to ozone partial pressure.
- Gas-Phase Chemiluminescence:Ethylene-ozone reaction detection for ambient monitoring networks requiring highest precision.
Volume concentrates in Electrochemical platforms. UV Absorption commands the premium tier for regulatory certification.
Application:
Customer type segmentation distinguishes between compliance-driven public procurement and process optimization in private manufacturing.
- Environmental Monitoring:Ambient air quality networks and stack emission verification requiring certified analyzers. US EPA National Ambient Air Quality Standards enforcement compels continuous ozone monitoring at state and local agency stations.
- Water Treatment:Disinfection validation and advanced oxidation process control in municipal and industrial plants. India's smart city initiatives drive online sensor deployment with subscription calibration revenue models.
- Industrial Emission Control:Manufacturing facility perimeter and stack monitoring for regulatory disclosure.
- Food Packaging:Cold storage atmosphere verification and modified atmosphere packaging line integration.
Environmental Monitoring carries the largest installed base. Water Treatment is climbing the fastest on automation investment cycles.
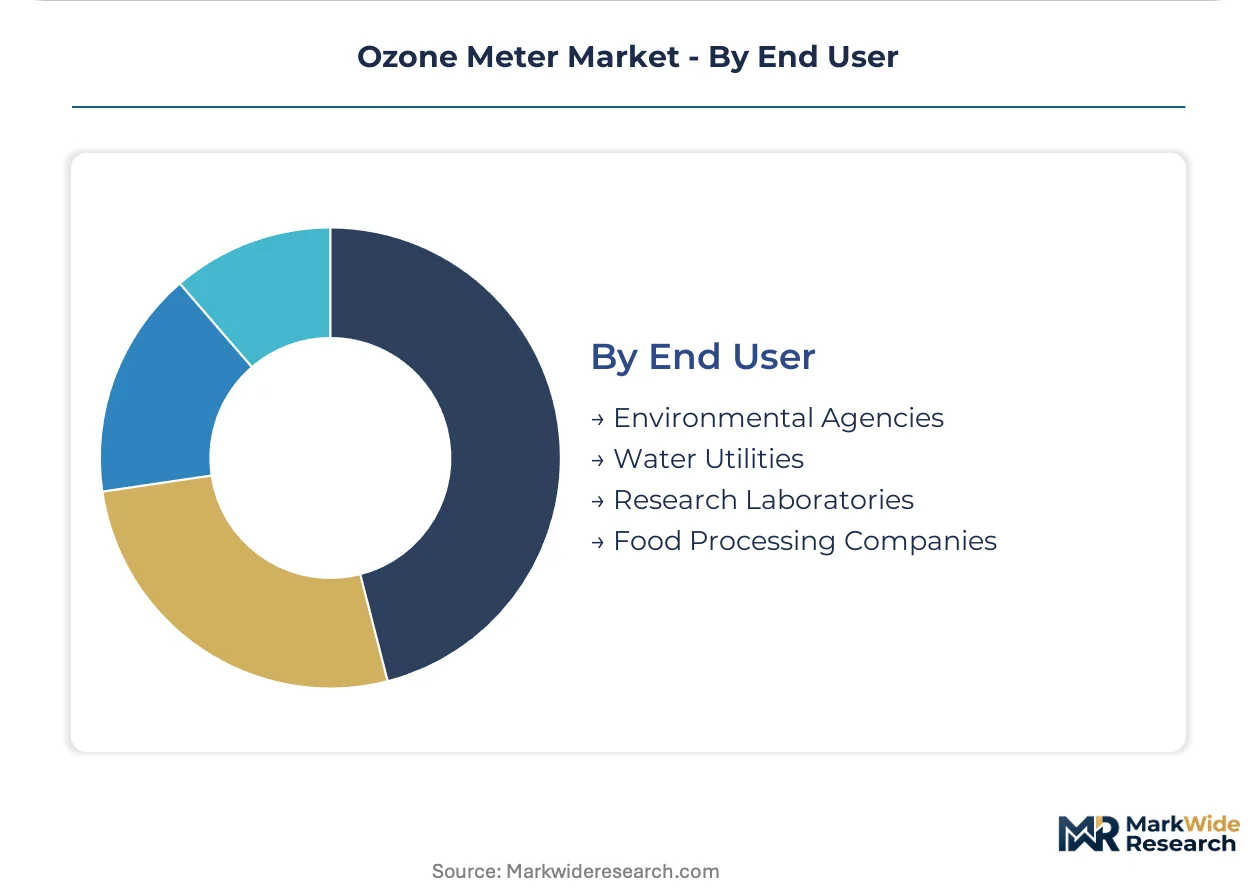
End User:
Maturity differentiation separates established regulatory frameworks from emerging procurement standardization.
- Environmental Agencies:Federal, state, and local government laboratories operating certified analyzer fleets. US EPA equivalence determination timelines of eighteen to thirty-six months shape product development alignment with procurement windows.
- Water Utilities:Municipal treatment plants and private water companies with SCADA integration requirements. Legacy proprietary communication protocols force sensor vendors to maintain multiple fieldbus translators.
- Research Laboratories:Academic and government research facilities requiring multi-analyte flexibility.
- Food Processing Companies:Cold chain operators and packaging manufacturers with HACCP validation needs.
Water Utilities represent the dominant procurement volume. Environmental Agencies maintain the most stringent specification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UV absorption spectroscopy for ozone measurement originated in German and Japanese laboratory settings during the 1970s, establishing technical foundations that persist in regulatory-grade instrumentation today. Industrial adoption subsequently diffused through semiconductor manufacturing clusters and municipal water treatment networks across East Asia and North America.
United States
Environmental agencies maintain certified analyzer fleets under EPA National Ambient Air Quality Standards enforcement. The eighteen-to-thirty-six-month Federal Reference Method equivalence determination shapes procurement alignment with agency budget cycles. California's Title 22 wastewater reuse regulations drive continuous ozone residual monitoring at industrial reclamation facilities in the Los Angeles Basin and Central Valley.
Germany
Water utilities accelerate portable ozone meter procurement to meet tightened EU Drinking Water Directive contaminant thresholds. Municipal testing protocols now mandate field-verifiable dissolved ozone readings at distribution points. The Rhine-Ruhr industrial corridor concentrates fixed sensor deployment for manufacturing emissions disclosure compliance.
Japan
METI industrial emissions disclosure rules tighten reporting granularity for volatile organic compound precursors. Manufacturing facilities in the Kanto and Kansai corridors install continuous ozone monitors as proxy indicators of photochemical reactivity. Japanese Industrial Standards precision thresholds anchor UV absorption platform specifications for domestic and export markets.
South Korea
Semiconductor fabs in the Seoul Capital Area and Busan-Ulsan corridor deploy MEMS-based electrochemical arrays for spatially dense cleanroom mapping. Machine learning drift-correction algorithms compress sensor replacement cycles from annual to condition-based triggers. Process tool manufacturers specify continuous monitoring as a qualification requirement for equipment procurement.
India
Smart city initiatives drive online ozone sensor deployment at municipal disinfection plants in Maharashtra and Gujarat. Subscription calibration services capture recurring revenue streams from water treatment automation investments. The country's national environmental regulator develops certification frameworks for continuous monitoring equipment in industrial zones.
Ozone Meter Market Key Industry Players
The competitive structure tilts toward technology-specialized mid-cap manufacturers rather than diversified industrial conglomerates. UV absorption specialists compete on regulatory equivalence certification timelines while electrochemical module vendors compete on field-swappable calibration efficiency. Two strategic archetypes dominate: precision-instrument laboratories with JIS or EPA method equivalence portfolios, and mobility-optimized field contractors with rapid-deployment sensor head platforms. Capacity expansion in mercury-free UV source fabrication and strategic partnerships for SCADA protocol integration represent the dominant competitive moves.
Among precision-instrument specialists, DKK-TOA Corporation and Teledyne API exemplify the regulatory-grade tier with UV absorption and gas-phase chemiluminescence platforms. 2B Technologies occupies a position within the field-mobility archetype through compact electrochemical module configurations. These three anchors illustrate the bifurcation between laboratory certification depth and operational expenditure flexibility that defines procurement segmentation across environmental agencies and industrial facilities.
| Leading Market Players |
|---|
| DKK-TOA Corporation |
| Emerson Electric |
| 2B Technologies |
| Teledyne API |
| Hach |
| Aeroqual |
| Eco Sensors |
| Ozone Solutions |
| BMT Messtechnik |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists in German and Japanese lamp fabrication anchor supply-side pricing discipline through multi-generational ownership structures that resist short-term margin compression. Their captive control over mercury-free UV source production transfers downstream into premium-tier analyzer pricing, while electrochemical module vendors compete on operational expenditure flexibility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EPA-equivalent certified analyzers from field-swappable electrochemical modules and handheld alarm units. Price differentiation hinges on certification grade—Federal Reference Method equivalence commands substantial premiums—and volume scale, with municipal fleet procurement extracting discounts unavailable to single-unit environmental contractors. Cost compression in electrochemical tiers is intensifying because platinum electrode volatility squeezes manufacturer margins. Water utilities exhibit highest price sensitivity, while semiconductor fabs prioritize qualification compliance over unit cost.
Supply Chain Analysis
Specialized photonics workforce availability in Japanese and German manufacturing geographies constrains mercury-free UV lamp expansion. Supply concentrates in Japan, Germany, and South Korea for precision optical components, electrochemical cell fabrication, and MEMS sensor arrays respectively. Raw material dependencies include platinum-iridium electrode alloys, high-purity quartz for UV cuvettes, and rare-earth phosphors for lamp excitation. Single-source vulnerability runs through Japanese specialty lamp foundries. Distribution runs through direct OEM partnerships for fixed industrial systems and environmental instrumentation distributors for portable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ozone metering rests on electrochemical miniaturization cost curves and the shift toward subscription calibration services that capture recurring revenue streams.
For Market Incumbents: Lock in regulatory certification moats by accelerating EPA-equivalent method submissions for emerging MEMS-based platforms. Invest in backward integration into mercury-free UV source fabrication to neutralize Japanese-German lamp supply concentration risks. Prioritize SCADA protocol translators for legacy water treatment plant integration. For New Entrants and Emerging Players: Municipal water utilities in Indian smart city initiatives represent the most penetrable buyer archetype. Target subscription calibration service unbundling in North American municipal markets where public purchasing rules favor competitive rebidding. Pursue combined ozone-peroxide sensor development for pharmaceutical VHP cycle validation as a qualification wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among electrochemical module vendors lacking regulatory-grade certification portfolios. Five-to-ten year viability favors precision-instrument laboratories with JIS or EPA method equivalence rather than mobility-optimized field contractors exposed to commodity sensor pricing. Watch for MEMS array adoption inflection in South Korean and Taiwanese semiconductor fabs as a signal for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Mercury-Free UV Source Capacity Expansion | Reduces supply concentration risk in German and Japanese lamp foundries. |
| MEMS Electrochemical Array Development | Enables spatially dense cleanroom mapping for South Korean semiconductor fabs. |
| Subscription Calibration Service Launch | Captures recurring revenue from Indian municipal water automation investments. |
| SCADA Protocol Integration Partnership | Resolves legacy communication barriers in North American water utilities. |
| Combined Ozone-Peroxide Sensor Platform | Addresses pharmaceutical sterilization validation requirements under FDA guidance. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with plant engineers at water treatment facilities, procurement leads at semiconductor fabs, regulatory affairs specialists at environmental agencies, and aftermarket service heads at instrumentation distributors. Secondary validation draws from EPA certification databases, Japanese Industrial Standards publications, EU Drinking Water Directive implementation reports, and customs trade data for ozone analyzer imports. Bottom-up unit shipment estimates triangulate against top-down market value reconstruction.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models product type, technology platform, application vertical, and end-user procurement maturity as core segmentation dimensions. CAGRs derive from regression against macroeconomic indicators, regulatory enforcement intensity, and industrial capital expenditure cycles specific to semiconductor fabrication and water treatment automation.
Underlying measurement precision varies by segment; EPA-equivalent certified analyzers carry tighter precision than electrochemical field units. Forecasts reflect assumptions about regulatory timeline adherence, precious metal price stability, and smart city execution pace in Indian municipal markets. Material deviation in METI enforcement intensity or EU Drinking Water Directive threshold revision warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
Fingerprint Identification Chip Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Capacitive Tactile Sensor Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Tooth Mounted Sensor Market
Sensors and Controls
Flow Sensor Market
Sensors and Controls
Mexico Digital Thermometer Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Global Wireless Sensors Market
Sensors and Controls
US Wireless Sensors Market
Sensors and Controls
Current Transducer Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Pressure Transmitter and Transducer Market
Sensors and Controls
Torque Sensor Market
Sensors and Controls
Electromagnetic Tracking Systems Market