
 Capacitive Pressure Sensor Market | 2026-2036
Capacitive Pressure Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Capacitive Pressure Sensor Market Outlook
Buyer concentration among automotive OEMs and Tier 1 module suppliers is restructuring procurement dynamics across the capacitive pressure sensor value chain. Infineon Technologies leverages its MEMS fabrication depth to sustain long-term supply agreements with German and Japanese vehicle manufacturers. Sensata Technologies anchors its position through ceramic-capacitive specialization for harsh-environment industrial applications.
A capacitive pressure sensor measures fluid or gas pressure by detecting capacitance changes between a fixed electrode and a deflecting diaphragm, typically fabricated from silicon, ceramic, or thin-film substrates with gap tolerances measured in micrometers. The device transduces mechanical deformation into electrical signals for process control, safety systems, and diagnostic monitoring across pneumatic, hydraulic, and ambient pressure regimes. Differential pressure configurations dominate flow-measurement installations where accuracy tolerance bands below 0.1% full scale command premium positioning. Micro-scale silicon variants represent the fastest-expanding technology segment, driven by medical wearable integration and miniaturized HVAC controls. High-pressure ceramic designs occupy mature margin pools in oilfield services and aerospace hydraulics where Mean Time Between Failure specifications exceed 100 million cycles.
FDA 21 CFR Part 820 quality-system requirements and ISO 13485 medical-device standards shape product validation protocols for sensors deployed in patient-monitoring and infusion-pump applications. EPA emissions-monitoring mandates and NHTSA brake-system regulations in the United States, alongside ECE R13 braking standards and EU MDR medical-device frameworks in Europe, create compliance thresholds that filter out non-certified suppliers. Stakeholders must monitor evolving functional-safety classifications and material-substance restrictions, as REACH SVHC candidate-list expansions and RoHS recast directives threaten legacy ceramic formulations and electrode metallizations.
Market Dynamics
Automotive electrification programs in Germany and China are compressing qualification timelines for ISO 26262-certified sensing modules while MEMS foundries in Taiwan and South Korea consolidate wafer supply.
Growth Catalysts
- EU F-Gas Regulation phase-down:HVAC-R OEMs in France and Italy are retrofitting commercial refrigeration systems with capacitive pressure transducers to monitor alternative refrigerant circuits.
- China dual carbon goals:MIIT mandates for industrial energy efficiency are accelerating deployment of precision pneumatic sensors in compressed-air monitoring networks across Jiangsu and Guangdong manufacturing corridors.
- Silicon-on-insulator wafer availability:200mm SOI substrate expansion at Taiwanese foundries is reducing die costs for MEMS capacitive designs serving wearable medical applications.
Market Restraints
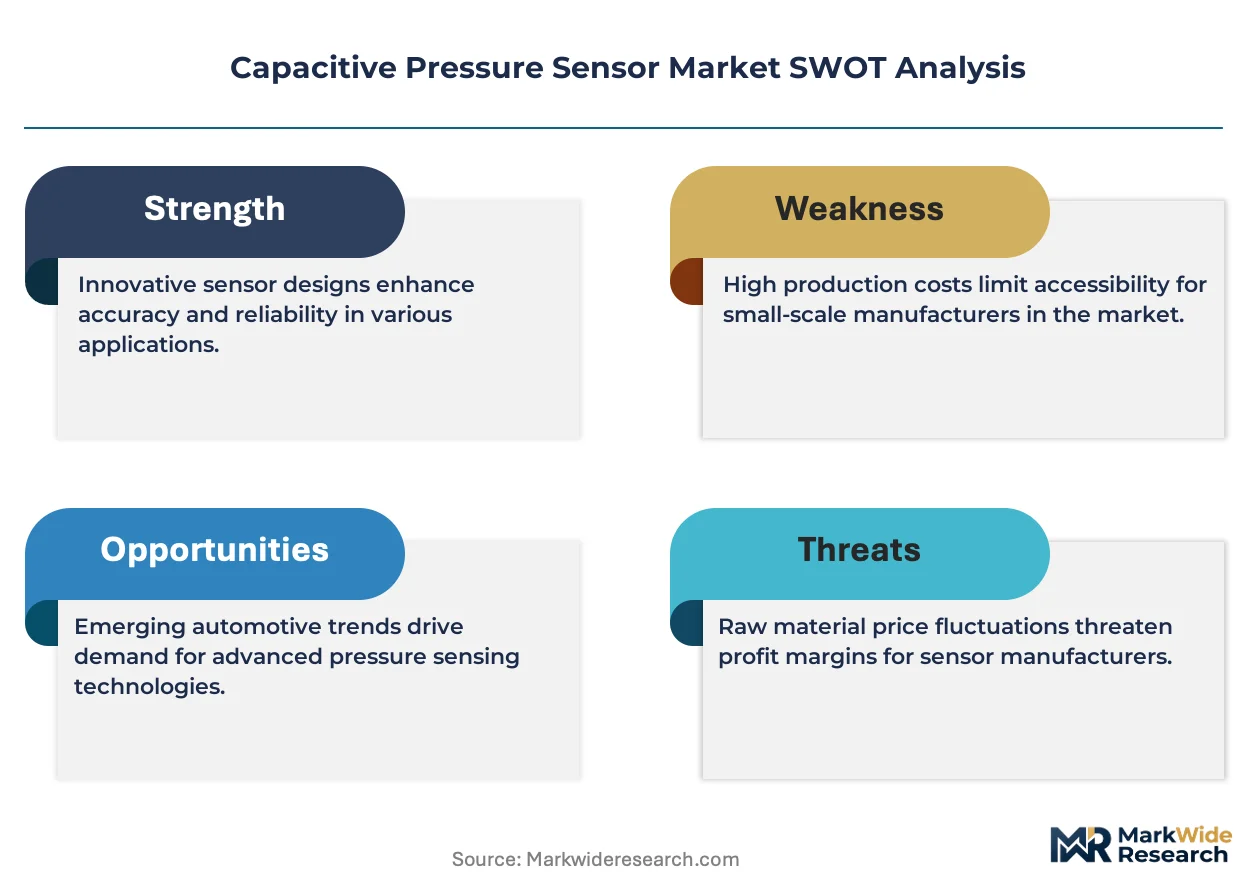
- Palladium electrode metallization costs:REACH SVHC scrutiny of nickel alloys is forcing ceramic sensor manufacturers toward palladium-based electrodes, compressing gross margins on oilfield service contracts.
- Single-source ceramic substrate dependence:High-purity alumina supply concentrates in Japanese and German specialty ceramics houses, exposing aerospace hydraulic sensor programs to allocation risk.
- Piezoresistive displacement in sub-10 bar ranges:Wheatstone-bridge MEMS alternatives from Chinese suppliers are capturing price-sensitive HVAC control board sockets.
Strategic Opportunities
- India PLI scheme for medical devices:CDSCO fast-track approvals for Class B diagnostic equipment are opening local assembly opportunities for capacitive sensors in patient-monitoring systems.
- Digital twin integration:Convergence of capacitive sensing with edge-AI inference engines is enabling predictive maintenance contracts for compressed-air infrastructure.
- Direct-to-OEM module supply:Bypassing traditional Tier 1 automotive distributors through qualified direct shipment programs to Stuttgart and Shanghai vehicle engineering centers.
Industry Challenges
- ISO 26262 ASIL-D functional safety certification:Brake-system sensor programs require 18-24 month validation cycles with German KBA and Japanese MLIT homologation authorities.
- MEMS process engineer scarcity:Deep reactive-ion etching expertise concentrates in Eindhoven, Dresden, and Hsinchu, constraining foundry expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Capacitive Pressure Sensor Market |
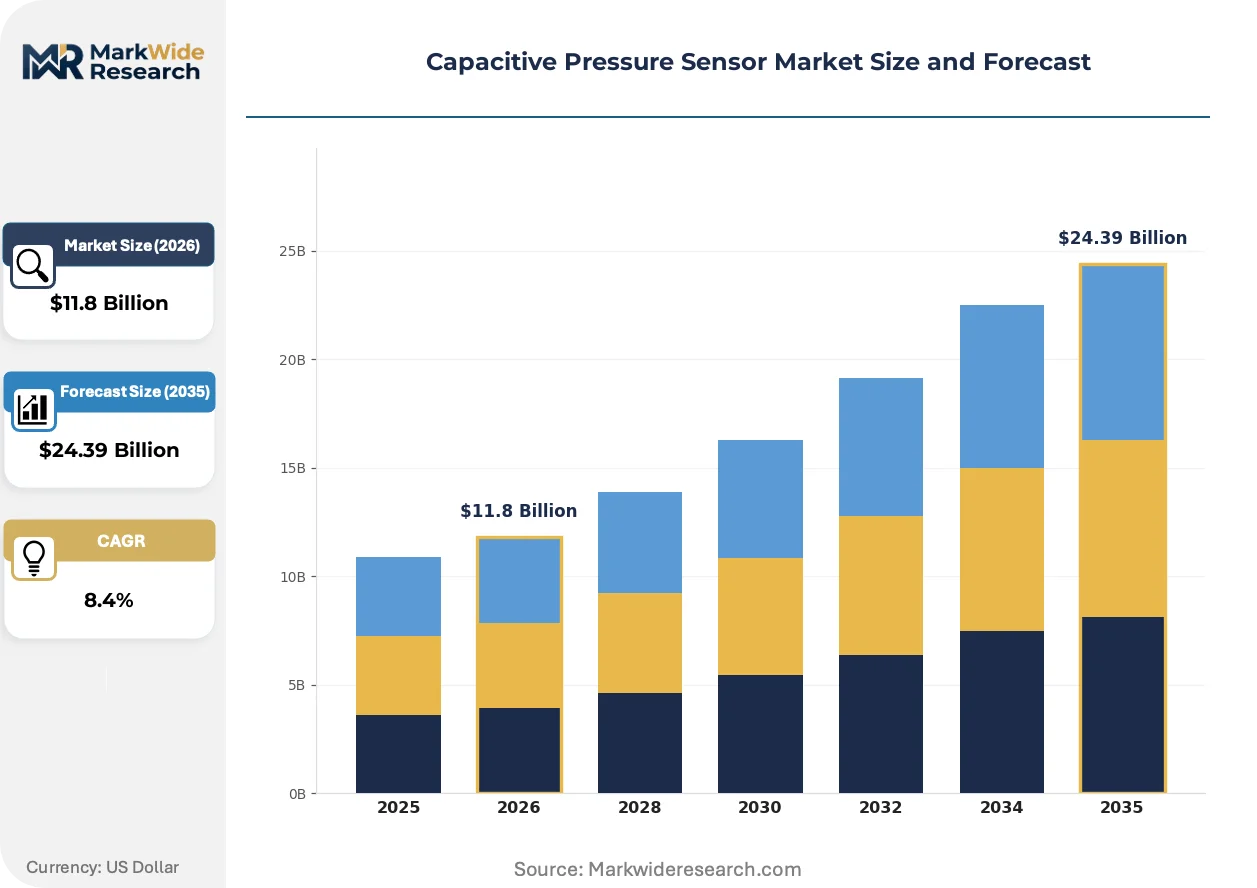
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micro, Standard, High-Pressure, Differential Technology: Silicon, Piezoelectric, Thin-Film, Ceramic End User: Aerospace, Automotive, Medical, Industrial Application: Level Measurement, Pressure Monitoring, Flow Measurement, Fatigue Testing |
| Companies Covered | Infineon Technologies, Honeywell International, Sensata Technologies, Amphenol Corporation, TE Connectivity, Vega Americas, STMicroelectronics, NXP Semiconductors, Setra Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Capacitive Pressure Sensor Market Strategic Shifts
Silicon MEMS process refinements and ceramic thin-film metallization advances are compressing form factors while tightening accuracy tolerances across automotive, medical, and industrial pressure regimes.
Deep-trench capacitive sensing architectures are automating self-calibration routines in automotive brake-by-wire modules. German and Japanese OEMs are qualifying these designs for ASIL-D safety loops during 2024-2025 platform refreshes. The technology is automating elimination of manual trim steps during module assembly, collapsing production cycle times at Tier 1 integrators.
EPA emissions-monitoring mandates for pneumatic leak detection are tightening calibration traceability requirements across process industries. Industrial sensor manufacturers must now maintain NIST-traceable pressure standards for five-year record retention. Oilfield service contractors in the Permian Basin and North Sea installations are absorbing compliance costs through dedicated quality-system personnel.
Consolidated procurement through automotive platform engineering centers is displacing distributed purchasing through Tier 1 module houses. Volkswagen Group and Toyota Motor are centralizing capacitive sensor specifications at group-level commodity boards. This pattern is most visible in Stuttgart and Nagoya, where brake-system and HVAC module suppliers now negotiate frame contracts against consolidated technical requirement documents.
Capacitive Pressure Sensor Market Segmentation
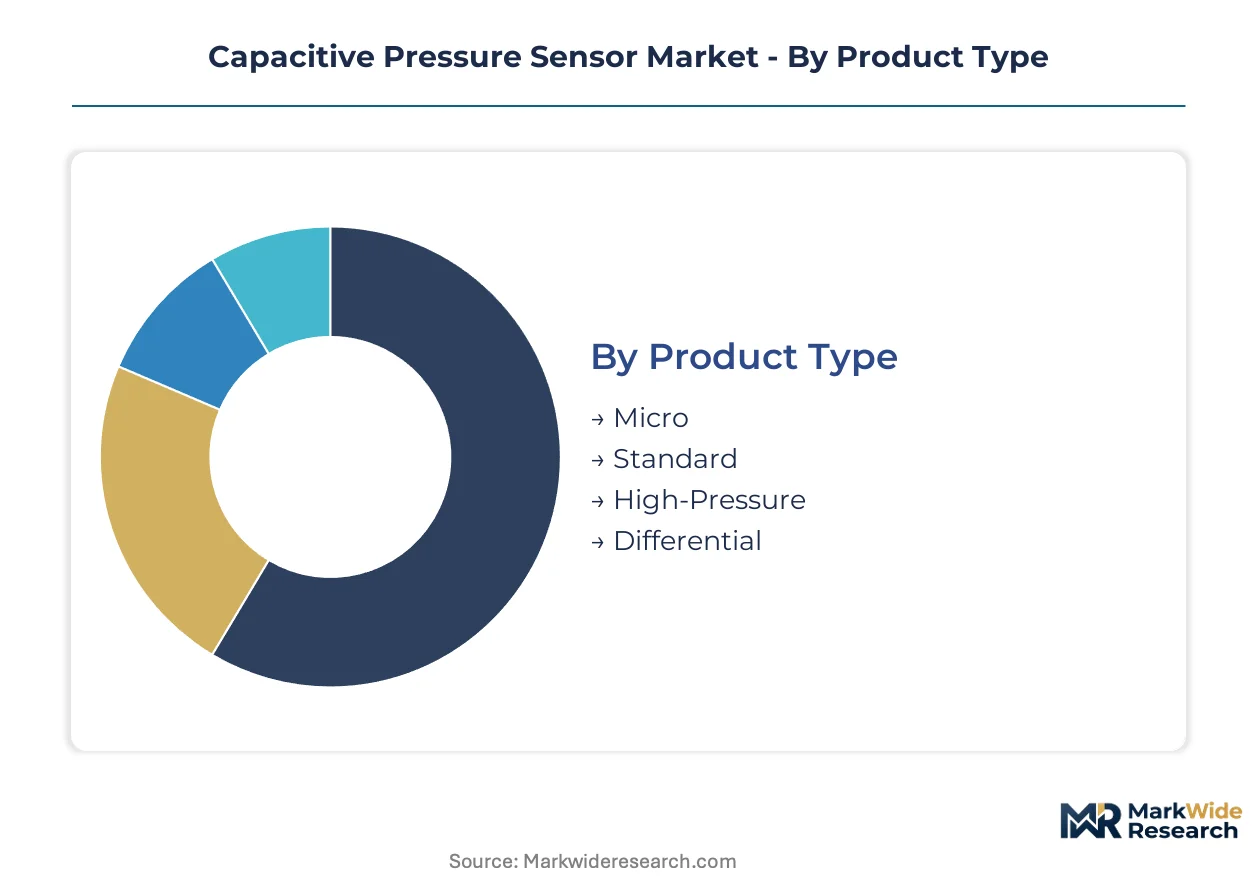
Capacitive pressure sensor procurement varies sharply by certification burden and performance tier. Automotive brake-system modules demand ISO 26262 ASIL-D validation, while medical wearables require FDA 21 CFR Part 820 and ISO 13485 compliance. Industrial oilfield sensors face API Q1 quality-system audits alongside hazardous-area certifications.
Product Type:
ISO 26262 functional-safety classifications and FDA 510(k) pathways determine which product types qualify for automotive brake modules versus patient-monitoring wearables. Medical micro-sensors face biocompatibility ISO 10993 testing that high-pressure oilfield variants bypass entirely.
- Micro:Silicon MEMS die with sub-millimeter diaphragm geometries transduce physiological pressure ranges below 100 mbar. South Korean wearable manufacturers in Suwon and Seongnam source these for continuous blood-pressure monitoring patches, constrained by FDA 510(k) clearance timelines stretching 12-18 months.
- Standard:Mid-range diaphragm sensors handle 0-10 bar industrial pneumatic circuits with 0.25% accuracy tolerance. German automotive HVAC module suppliers in Stuttgart specify these for refrigerant pressure monitoring under EU F-Gas Regulation leak-detection mandates.
- High-Pressure:Ceramic capacitive designs withstand 700+ bar hydraulic regimes in aerospace landing gear.
- Differential:Twin-diaphragm architectures measure minute pressure deltas across flow-restriction orifices.
Leading the category by volume: Standard. Growing fastest: Micro.
Technology:
Cost tiers separate silicon MEMS wafers from ceramic substrates by an order of magnitude in raw material input. Thin-film metallization commands premium positioning where corrosion resistance outweighs die cost sensitivity.
- Silicon:Deep reactive-ion etched cavities on 200mm SOI wafers enable sub-micron gap control for medical and automotive miniaturization. Taiwanese foundries in Hsinchu supply these dies to tier-one module integrators, with wafer costs declining as 200mm capacity expands.
- Piezoelectric:Quartz-crystal resonant structures dominate aerospace dynamic pressure measurement where frequency-output stability exceeds voltage-mode alternatives.
- Thin-Film:Sputtered metal strain elements on steel substrates tolerate aggressive process media in chemical plants.
- Ceramic:Alumina-based capacitive cells with thick-film palladium electrodes serve oilfield pressure gauges.
Volume concentrates in Silicon. Steepest expansion trajectory: Thin-Film for corrosive industrial deployments.
End User:
Customer-type segmentation reveals divergent procurement patterns. Automotive OEMs consolidate specifications at platform engineering centers, while medical device manufacturers fragment purchasing across specialized contract manufacturers.
- Aerospace:Hydraulic system sensors for flight-control surfaces must satisfy FAA TSO-C88a and EASA CS-25 airworthiness standards. Wichita and Toulouse airframe integrators specify Mean Time Between Failure rates exceeding 100 million cycles for landing-gear pressure transducers.
- Automotive:Brake-by-wire and thermal-management modules drive ISO 26262 ASIL-B through ASIL-D qualification demand. Volkswagen Group and Toyota Motor centralize capacitive sensor procurement at Stuttgart and Nagoya commodity boards, collapsing Tier 1 distributor margins.
- Medical:Infusion pumps and ventilators require FDA 21 CFR Part 820 quality-system compliance.
- Industrial:Compressed-air monitoring networks absorb the highest unit volumes.
Automotive commands revenue share. Climbing the fastest: Medical wearables integrating continuous monitoring.
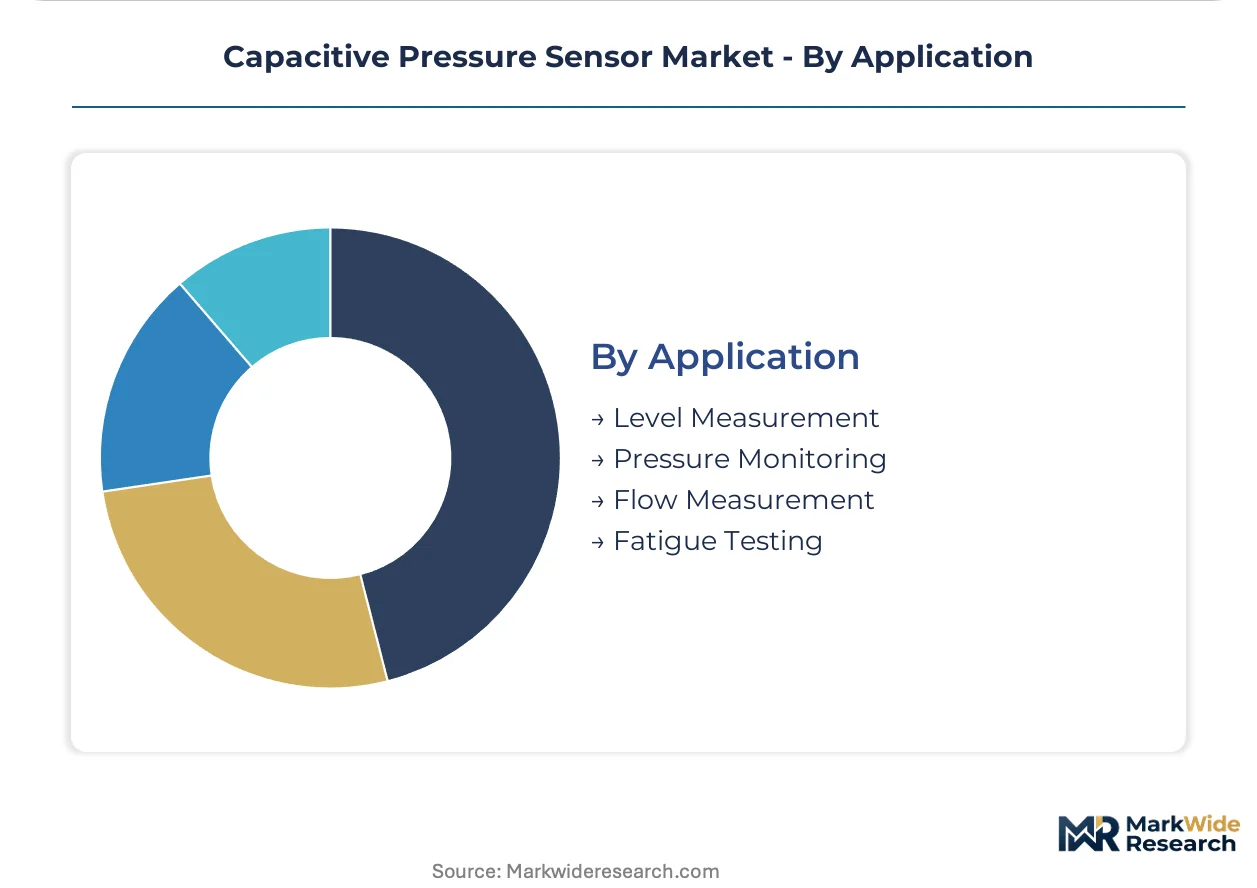
Application:
Application selection determines accuracy specification and calibration protocol. Flow measurement demands differential pressure architectures with 0.1% full-scale tolerance, while level measurement tolerates wider bands in bulk storage tanks.
- Level Measurement:Hydrostatic pressure sensing calculates fluid column height in petrochemical storage and water treatment. Permian Basin operators deploy ceramic capacitive probes for crude-oil tank gauging, absorbing NIST-traceable calibration costs through dedicated field-service personnel.
- Pressure Monitoring:Real-time pneumatic and hydraulic circuit surveillance enables predictive maintenance contracts. Jiangsu manufacturing corridors under MIIT energy-efficiency mandates install precision pressure sensors across compressed-air distribution networks.
- Flow Measurement:Orifice-plate differential pressure installations dominate process industries.
- Fatigue Testing:Structural validation laboratories cycle sensors through millions of pressure pulses.
Pressure Monitoring leads unit shipments. Gaining share fastest: Flow Measurement with EPA emissions-monitoring tightening calibration traceability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electrification programs and MEMS foundry capacity expansions are redistributing procurement leverage across three continents. German and Chinese OEMs now dictate qualification timelines while Taiwanese wafer supply tightens supplier margins.
Germany
Volkswagen Group and BMW brake-by-wire programs absorb ISO 26262 ASIL-D certified modules at volume. KBA homologation protocols extend validation cycles to 18-24 months for safety-critical sensing loops. Stuttgart engineering centers consolidate specifications at group commodity boards, collapsing Tier 1 distributor influence.
China
MIIT dual carbon mandates accelerate precision pneumatic sensor deployment across Jiangsu and Guangdong manufacturing corridors. Compressed-air monitoring networks absorb standard-range capacitive transducers under industrial energy-efficiency directives. Shanghai vehicle engineering centers qualify domestic MEMS suppliers for thermal-management modules.
United States
EPA emissions-monitoring mandates for pneumatic leak detection tighten NIST-traceable calibration requirements. Oilfield service contractors in the Permian Basin deploy ceramic capacitive probes for crude-oil tank gauging. Wichita airframe integrators specify Mean Time Between Failure rates exceeding 100 million cycles for landing-gear pressure transducers.
South Korea
Suwon and Seongnam wearable manufacturers source silicon MEMS die for continuous blood-pressure monitoring patches. MFDS regulatory alignment with FDA 510(k) pathways constrains product launch timelines to 12-18 months. Hsinchu foundry supply chains feed Korean module integrators with 200mm SOI wafer capacity.
Japan
Toyota Motor centralizes capacitive sensor procurement at Nagoya commodity boards alongside brake-system and HVAC module consolidation. MLIT homologation authorities enforce parallel validation cycles with German KBA for export platform compatibility. Nagoya Tier 1 integrators negotiate frame contracts against consolidated technical requirement documents.
Capacitive Pressure Sensor Market Competitive Environment
German and Japanese producers anchor one tier; Taiwanese foundry specialists hold wafer supply leverage; Chinese module integrators capture price-sensitive HVAC sockets. The vendor base stratifies across automotive safety-certification holders, industrial ceramic specialists, and MEMS fabrication scale players. Three archetypes dominate: ISO 26262-certified automotive suppliers, FDA-validated medical device component providers, and API Q1-audited oilfield service contractors. Capacity expansion at 200mm SOI foundries and ceramic substrate qualification programs constitute the dominant competitive moves.
Among European semiconductor fabricators, Infineon Technologies and STMicroelectronics exemplify the automotive-certification archetype through MEMS fabrication depth. Sensata Technologies occupies a position within the industrial ceramic specialization tier. These three entities represent the geographic and capability span of the competitive landscape without exhausting the field of qualified suppliers.
| Leading Market Players |
|---|
| Infineon Technologies |
| Honeywell International |
| Sensata Technologies |
| Amphenol Corporation |
| TE Connectivity |
| Vega Americas |
| STMicroelectronics |
| NXP Semiconductors |
| Setra Systems |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM platform engineering centers in Stuttgart and Nagoya concentrate procurement leverage, forcing contract-based long-term offtake pricing with volume-scaled discounts and ASIL-certification premiums.
Pricing Analysis
Volume concentrates in standard-range ceramic and silicon MEMS die for industrial pneumatic monitoring, while margins accrue to ASIL-D certified automotive modules and FDA-validated medical micro-sensors. Price differentiation hinges on ISO 26262 functional-safety tier and FDA 510(k) clearance status, with uncertified industrial variants facing cost compression from Chinese piezoresistive alternatives. Pricing pressure stems from palladium electrode metallization costs under REACH SVHC scrutiny, eroding gross margins on oilfield service contracts. HVAC control board buyers in Jiangsu manufacturing corridors exhibit highest price sensitivity, whereas aerospace hydraulic programs in Wichita tolerate premium positioning for MTBF specifications exceeding 100 million cycles.
Supply Chain Analysis
Reverse-logistics flows for automotive brake-system modules center on remanufacturing calibration drift sensors at Stuttgart service depots and Nagoya refurbishment centers under MLIT quality protocols. Geographic supply concentrates in Taiwan, South Korea, and Germany, with 200mm SOI wafer output from Hsinchu foundries feeding Korean wearable integrators and German automotive Tier 1s. Raw material dependencies include high-purity alumina substrates from Japanese specialty ceramics houses, palladium electrode metallization, and deep reactive-ion etching equipment anchored in Eindhoven and Dresden. Single-source ceramic substrate vulnerability exposes aerospace programs to allocation risk. Distribution runs through consolidated OEM platform engineering centers, displacing traditional Tier 1 module house purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The capacitive pressure sensor market sits in a technology-transition phase as silicon MEMS architectures displace legacy ceramic designs across sub-10 bar applications, driven by wearable medical integration and automotive miniaturization mandates.
For Market Incumbents: Deepen backward integration into 200mm SOI wafer supply through captive foundry partnerships in Hsinchu or Dresden, insulating against Taiwanese capacity allocation risk. Accelerate ASIL-D certification pipelines for brake-by-wire modules to defend position against emerging Chinese piezoresistive suppliers capturing HVAC control board sockets. Prioritize FDA 510(k) pathway investment for continuous blood-pressure monitoring patches before South Korean wearable manufacturers consolidate supplier relationships. For New Entrants and Emerging Players: India's PLI scheme for medical devices opens a window for Class B diagnostic equipment assembly targeting CDSCO fast-track approvals, bypassing entrenched German and Japanese automotive certification barriers. Target industrial compressed-air monitoring networks in Jiangsu and Guangdong under MIIT dual carbon mandates, where domestic Chinese suppliers lack precision calibration capabilities. Pursue direct-to-OEM module supply contracts with Shanghai vehicle engineering centers, circumventing traditional Tier 1 distributor margins. For Investors and Strategic Acquirers: The window for entry favors MEMS fabrication specialists with ISO 26262 certification infrastructure and established foundry relationships in Taiwan or South Korea. Acquisition targets should exhibit ceramic-thin-film metallization expertise for harsh-environment industrial applications, complementing silicon MEMS scale players. Watch for inflection in EPA emissions-monitoring calibration traceability requirements, which would compress margins for non-compliant industrial sensor manufacturers and trigger consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | KBA and MLIT homologation unlocks brake-system supply contracts with Volkswagen Group and Toyota Motor. |
| 200mm SOI Wafer Capacity Expansion | Taiwanese foundry partnerships reduce die costs for MEMS designs serving wearable medical applications. |
| Direct-to-OEM Supply Programs | Bypassing Tier 1 distributors captures margin from consolidated procurement at Stuttgart and Nagoya engineering centers. |
| FDA 510(k) Pathway Acceleration | Fast-track clearance for continuous monitoring patches secures supply relationships with Suwon wearable manufacturers. |
| Palladium Electrode Metallization Shift | REACH SVHC compliance maintains oilfield service contract eligibility under tightening EU chemical regulations. |
Study Parameters
Document review covered SEC 10-K filings, EU F-Gas Regulation implementation reports, and MIIT industrial energy-efficiency directives, complemented by interviews with MEMS foundry operations managers, automotive Tier 1 procurement leads, and biomedical engineers at patient-monitoring device manufacturers. Primary fieldwork included conversations with ceramic substrate specialists in Japanese specialty materials houses and HVAC module suppliers in Stuttgart. Secondary validation drew from ISO 26262 certification databases, FDA 510(k) clearance records, and REACH SVHC candidate list updates. Bottom-up demand modeling across automotive brake-system, medical wearable, and industrial pneumatic segments triangulated against top-down wafer supply forecasts from Taiwanese foundry disclosures.
Segment-level outputs across product type, technology, end user, and application dimensions informed the projection framework, with automotive electrification program timelines and MEMS process yield curves as key model inputs. CAGRs were derived from elasticity-adjusted demand curves incorporating substitution effects from piezoresistive alternatives in sub-10 bar ranges. The analysis window spans the full forecast period without interim breakpoint assumptions.
The model assumes a particular technology adoption path; alternative pathways for ceramic-to-silicon MEMS displacement in high-pressure oilfield applications would alter the outlook for alumina substrate demand. Forecasts reflect assumptions about KBA and MLIT homologation cycle durations, EPA emissions-monitoring calibration enforcement intensity, and Taiwanese 200mm SOI wafer capacity expansion schedules. Material deviation in automotive platform electrification timelines or REACH SVHC list expansion velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Latin America Gas Sensors Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Sound Sensor Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Digital Pump Controller Market
Sensors and Controls
Wearable Temperature Sensors Market
Sensors and Controls
Global Wireless Brain Sensors Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
Chemical Sensors Market
Sensors and Controls
Oxygen Gas Sensors Market
Sensors and Controls
Asia Pacific Lidar Market
Sensors and Controls
Micro-Electro Mechanical Systems Market
Sensors and Controls
Room Pressure Monitor Market
Sensors and Controls
Asia-Pacific Smart Glove Market