
 Asia Pacific Safety I/O Modules Market | 2026-2036
Asia Pacific Safety I/O Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Safety I/O Modules Market Outlook
High-integrity SIL 3 certification is rotating through the Asia Pacific supply base as the default specification tier for new plant builds. Siemens AG leverages its TÜV-certified portfolio to anchor premium positioning across Japanese automotive lines. Mitsubishi Electric Corporation dominates domestic factory automation channels with captive semiconductor sourcing. Rockwell Automation, Inc. competes through channel density in Australia's mining automation sector.
Safety I/O modules are electromechanical interface devices that translate discrete and continuous field signals into fault-tolerant safety communications for programmable logic controllers, typically rated for SIL 2 or SIL 3 functional safety integrity with response times under 30 milliseconds. Their primary purpose is to isolate hazardous machinery states while maintaining deterministic control loop performance in automated production environments. Digital I/O modules sustain the largest volume base across the region's manufacturing end user segment, though Ethernet-enabled safety controllers represent the fastest structural expansion as plants retrofit fieldbus architectures. DIN rail installation types occupy the dominant hardware format given their compatibility with existing control cabinet standards across Chinese and Korean system integrators.
China's SAMR enforces GB/T functional safety standards that mandate certified safety I/O in new robotic installations, while Japan's METI administers industrial machinery certification through JIS B 9960 series requirements. Australia's WHS regulations and South Korea's KOSHA factory safety codes create additional compliance layers that module vendors must navigate for market access. Stakeholders should monitor divergence between China's domestic certification pathways and IEC 62061 harmonization timelines when allocating regional product development resources.
Market Dynamics
Factory automation standards across Asia Pacific are forcing simultaneous upgrades to safety architectures, compressing replacement cycles for electromechanical interface devices as automotive and electronics manufacturers pursue SIL 3 certification parity with European production lines.
Growth Catalysts
- Automotive Assembly Expansion:Southeast Asian vehicle manufacturing corridors are mandating certified safety I/O in new robotic cells to satisfy export market requirements.
- GB/T Functional Safety Mandates:China's SAMR enforcement of national standards for robotic installations creates replacement demand across eastern manufacturing clusters.
- Ethernet-Enabled Retrofit Cycles:Fieldbus architecture upgrades in Korean and Taiwanese electronics plants are accelerating module refresh timelines.
Market Restraints
- Semiconductor Supply Concentration:Captive chip sourcing from Japanese and Korean component houses limits second-source availability for module vendors.
- Certification Cost Burden:TÜV SIL 3 validation expenses disproportionately burden mid-tier system integrators in Vietnam and Indonesia.
- Legacy Fieldbus Entrenchment:Profibus and DeviceNet installations in Australian mining automation resist Ethernet migration due to capital lock-in.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme beneficiaries in semiconductor packaging and mobile assembly lack established safety I/O supply relationships.
- Battery Gigafactory Buildouts:Cell production lines in China's interior provinces require SIL-rated modules for electrode handling and electrolyte filling stations.
- Remote Monitoring Convergence:Integration of safety I/O with industrial edge computing platforms opens service revenue models for Australian resource extraction operators.
Industry Challenges
- Functional Safety Engineering Talent:Shortage of TÜV-certified safety engineers in Vietnam and Thailand delays commissioning timelines for automotive projects.
- Multi-Standard Harmonization:Divergence between China's GB certification pathways and IEC 62061 timelines forces vendors to maintain parallel product variants.
- Legacy PLC Integration Complexity:Retrofitting SIL 3 modules into 1990s-era control architectures in Japanese automotive plants requires custom gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Safety I/O Modules Market |
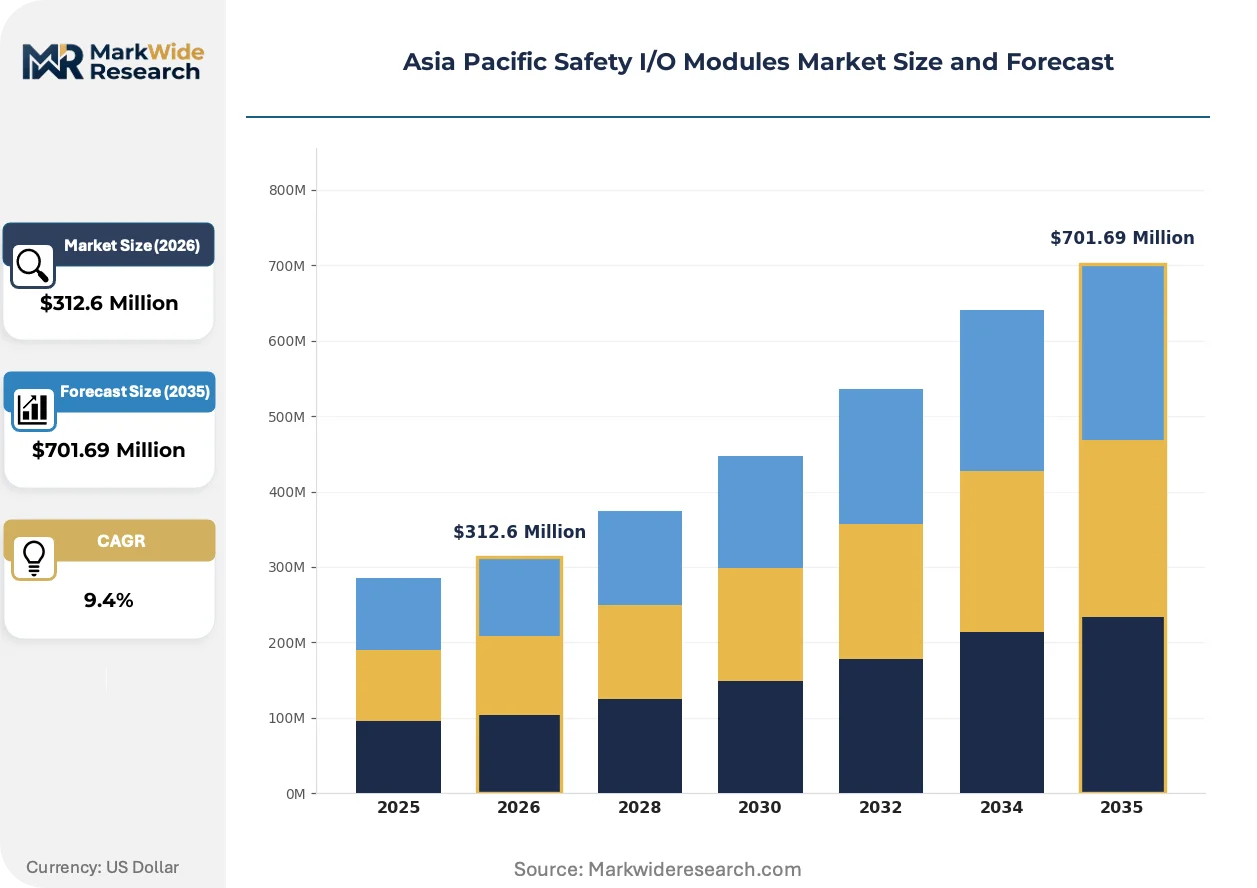
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $701.69 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital I/O, Analog I/O, Relay Modules, Safety Controllers End User: Manufacturing, Oil & Gas, Food Processing, Automotive Technology: Wired, Wireless, Fieldbus, Ethernet Installation Type: Panel Mount, DIN Rail, Embedded, Rack Mount |
| Companies Covered | Schneider Electric SE, Advantech Co. Ltd., ABB Ltd., Lumberg Automation, Parmlay Graham Ltd., Siemens AG, Honeywell International, Inc., Mitsubishi Electric Corporation, Rockwell Automation, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Safety I/O Modules Market Strategic Shifts
Ethernet-based safety communication protocols are displacing proprietary fieldbus architectures across Asia Pacific manufacturing, while regulatory convergence pressures and buyer procurement consolidation reshape competitive positioning for electromechanical interface suppliers.
Single-pair Ethernet (SPE) physical layer technology is fragmenting traditional safety I/O connectivity paradigms by enabling 10 Mbps transmission over unshielded twisted pair across 1000-meter spans. Automotive paint shops in Thailand and Indonesia are piloting SPE-enabled safety modules to reduce cabling mass in robotic cells. This topology compression is fragmenting the installed base between legacy four-wire DeviceNet installations and streamlined two-wire SPE architectures.
Japan's METI is tightening JIS B 9960 series certification requirements for collaborative robot installations, extending safety I/O mandates to previously exempt light-payload cobot workcells. Japanese automotive suppliers are accelerating module procurement to meet revised compliance deadlines. Electronics contract manufacturers in Osaka and Nagoya prefectures represent the most affected segment, with safety controller purchases expanding beyond traditional automotive tier-1s.
Consolidated procurement by Chinese battery manufacturers is compressing vendor margins and shifting contract structures toward multi-year framework agreements with volume guarantees. CATL and BYD supply chain managers are unbundling hardware from commissioning services, forcing module vendors to compete on unit economics alone. This disaggregation is most visible in Fujian and Sichuan province gigafactory clusters, where direct sourcing teams bypass traditional system integrator channels.
Asia Pacific Safety I/O Modules Market Segmentation
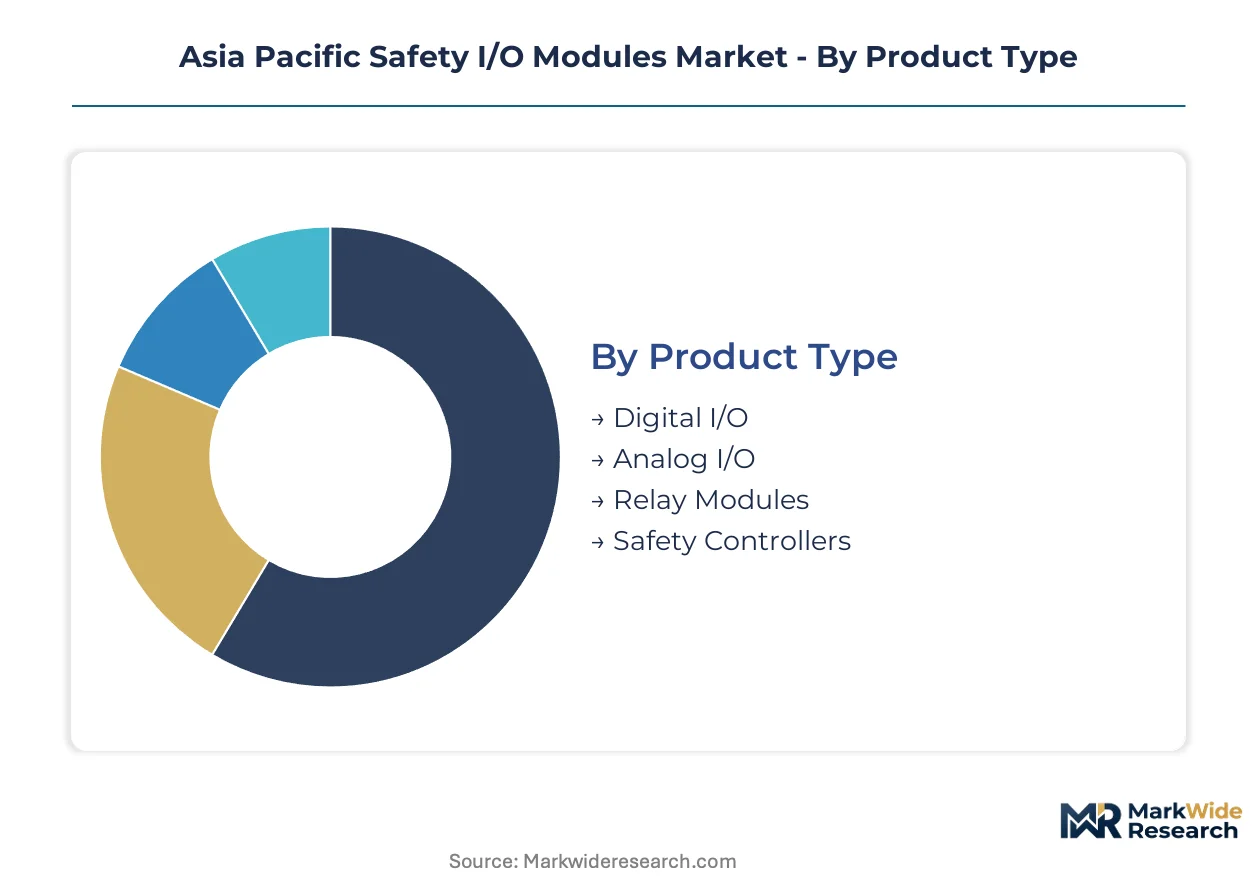
Segmentation in the Asia Pacific Safety I/O Modules Market reveals how substitution pressures and compliance mandates reshape procurement patterns across discrete manufacturing clusters. Understanding these divides exposes where module vendors must defend incumbent positions against protocol migration and form-factor innovation.
Product Type:
Digital I/O modules face the strongest substitution threat from integrated safety controllers, while analog I/O resists displacement due to sensor diversity requirements in process industries.
- Digital I/O:Binary signal processing modules dominate discrete manufacturing applications with deterministic response characteristics under 10 milliseconds. Demand concentrates across Chinese automotive assembly corridors where SAMR-mandated SIL 3 retrofits drive replacement volumes.
- Analog I/O:Continuous signal conversion modules handle 4-20 mA and 0-10 V sensor ranges for temperature and pressure monitoring. Japanese chemical processors along the Osaka Bay industrial zone sustain procurement for legacy DCS integration projects.
- Relay Modules:Electromechanical switching interfaces provide galvanic isolation for high-voltage safety circuits.
- Safety Controllers:Integrated logic platforms embed I/O, processing, and communication in unified enclosures.
Digital I/O retains volume leadership; Safety Controllers hold the steepest expansion curve.
End User:
Cost tier stratification separates premium-certified module deployments from standard-tier procurement, with automotive and electronics manufacturing occupying opposite ends of this spectrum.
- Manufacturing:General industrial automation spans packaging machinery, material handling, and assembly equipment across diverse factory floors. Korean electronics contract manufacturers in Gyeonggi Province drive Ethernet-enabled module refresh cycles for smartphone assembly lines.
- Automotive:Vehicle production facilities require the highest functional safety integrity levels for robotic welding and painting operations. Thai and Indonesian assembly plants are mandating certified modules in new cells to satisfy export market access requirements.
- Oil & Gas:Hydrocarbon processing and offshore platforms demand explosion-proof housing certifications.
- Food Processing:Hygienic design requirements dictate stainless steel enclosures and washdown-rated sealing.
Manufacturing sustains the broadest installed base; Automotive commands the highest per-unit certification premiums.
Technology:
Volume concentration favors established wired architectures, though connectivity migration accelerates fastest where greenfield construction permits protocol selection freedom.
- Ethernet:Industrial Ethernet protocols including PROFIsafe and CIP Safety enable deterministic safety communication over standard network infrastructure. Taiwanese semiconductor fabs are retrofitting fieldbus architectures to EtherNet/IP for tool integration standardization.
- Fieldbus:Legacy proprietary networks including PROFIBUS and DeviceNet retain substantial installed bases in mature facilities. Australian mining automation operators resist migration due to capital lock-in across remote extraction sites.
- Wired:Point-to-point discrete wiring persists in simple safety circuits and maintenance access points.
- Wireless:Industrial Wi-Fi and 5G safety radio modules address mobile equipment and temporary installations.
Fieldbus maintains the largest legacy footprint; Ethernet gains share fastest among new plant constructions.
Installation Type:
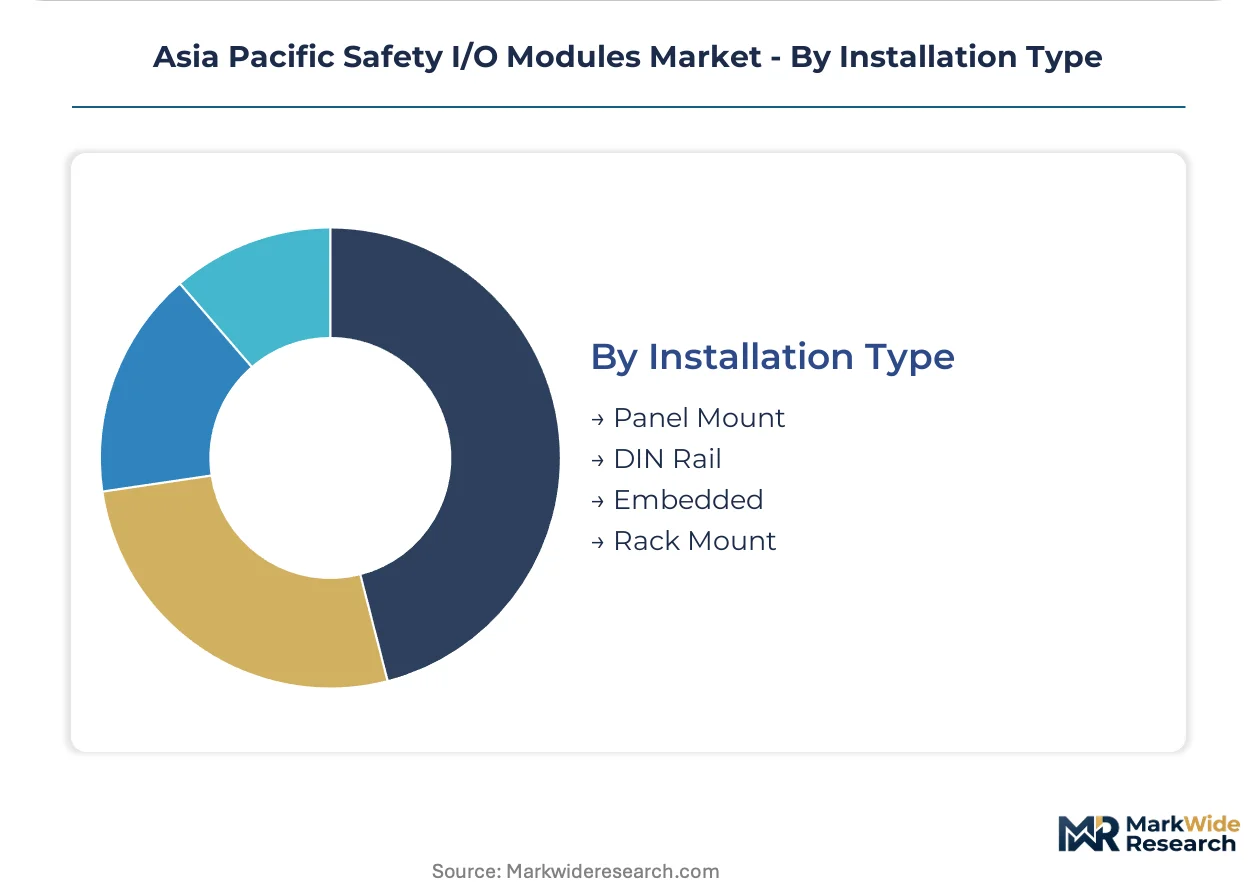
Supply concentration among Chinese and Korean panel builders elevates DIN rail compatibility to a default procurement specification, marginalizing alternative mounting approaches.
- DIN Rail:Standardized 35 mm top-hat mounting dominates control cabinet construction across Asia Pacific system integrators. Chinese integrators in the Yangtze River Delta specify DIN rail modules exclusively for GB/T-compliant robotic installations.
- Panel Mount:Direct enclosure attachment suits customized machinery builds and OEM-integrated safety systems. Japanese machine tool builders in Aichi Prefecture favor panel mount configurations for compact lathe and machining center designs.
- Embedded:PCB-level integration targets original equipment manufacturer designs with space-constrained architectures.
- Rack Mount:19-inch standard enclosures serve centralized safety control rooms and distributed I/O stations.
DIN Rail captures the dominant hardware format; Panel Mount defends position in machinery OEM channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia Pacific's safety I/O module trade flows reflect a regional production surplus, with China and Japan exporting certified hardware to Southeast Asian assembly corridors while importing specialized analog components from South Korea and Taiwan. Import dependency concentrates in high-integrity semiconductor substrates and TÜV validation services.
China
Domestic module production scales fastest along the Shanghai-Shenzhen manufacturing corridor, driven by SAMR enforcement of GB/T functional safety standards for new robotic installations. Battery gigafactory buildouts in Fujian and Sichuan provinces consume SIL-rated modules for electrode handling lines. Yangtze River Delta system integrators specify DIN rail formats exclusively for GB/T-compliant deployments.
Japan
Automotive tier-1 suppliers in Aichi and Osaka prefectures accelerate procurement to meet METI's tightened JIS B 9960 certification deadlines for collaborative robot workcells. Domestic factory automation channels favor captive semiconductor sourcing from Mitsubishi Electric's in-house supply base. Nagoya-area electronics contract manufacturers represent the most affected compliance segment.
South Korea
KOSHA factory safety codes and electronics manufacturing expansion in Gyeonggi Province drive Ethernet-enabled module refresh cycles for smartphone assembly lines. Korean semiconductor component houses limit second-source availability for regional module vendors. Busan-Ulsan industrial corridors concentrate demand for process industry analog I/O integration.
Australia
Mining automation operators in Western Australia resist Ethernet migration due to capital lock-in across remote extraction sites with legacy Profibus and DeviceNet installations. WHS regulations create additional compliance layers for module market access. Queensland resource extraction operators pilot safety I/O integration with industrial edge computing platforms.
Thailand
Automotive assembly plants in the Eastern Economic Corridor mandate certified safety I/O in new robotic cells to satisfy export market access requirements. Single-pair Ethernet pilot programs in Rayong province paint shops test topology compression for reduced cabling mass. Certification cost burdens disproportionately affect mid-tier system integrators serving Indonesian and Vietnamese satellite facilities.
Asia Pacific Safety I/O Modules Market Competitive Environment
Concentration sits with diversified industrial automation conglomerates possessing captive semiconductor sourcing and established TÜV certification pipelines. The vendor base stratifies across three tiers: premium-positioned European majors with full SIL 3 portfolios, Asia-based integrated suppliers leveraging backward integration into component manufacturing, and specialized connectivity providers serving machinery OEM channels. Competitive moves center on multi-year framework contracting with volume guarantees and protocol licensing arrangements for Ethernet safety stacks.
Among European-based automation majors, Siemens AG and ABB Ltd. occupy positions exemplifying the premium-certification archetype through TÜV-validated product lines. Mitsubishi Electric Corporation represents the Asia-integrated model with captive supply chain control. Rockwell Automation, Inc. anchors the North American-origin competitive vector with channel density in resource extraction sectors.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Advantech Co. Ltd. |
| ABB Ltd. |
| Lumberg Automation |
| Parmlay Graham Ltd. |
| Siemens AG |
| Honeywell International, Inc. |
| Mitsubishi Electric Corporation |
| Rockwell Automation, Inc. |
| Others |
Value Chain & Pricing Dynamics
Multi-year framework agreements with volume guarantees lock in supply access for Chinese battery manufacturers while compressing price visibility for module vendors serving CATL and BYD procurement teams. This contracting pattern concentrates pricing power among consolidated buyers in Fujian and Sichuan province gigafactory clusters.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Pricing stratifies across premium, standard, and economy tiers based on SIL certification grade and volume scale. Cost compression in the standard tier is intensifying because Chinese battery manufacturers unbundle hardware from commissioning services. Automotive tier-1 suppliers exhibit the lowest price sensitivity due to export compliance mandates, while Vietnamese mid-tier system integrators face acute margin pressure from TÜV validation expenses.
Supply Chain Analysis
Japan and South Korea anchor semiconductor substrate production for safety I/O modules, while China dominates final assembly and DIN rail enclosure manufacturing. Module production draws from Japanese and Korean component houses for high-integrity substrates, Taiwanese PCB fabrication, and Chinese steel for enclosure housings. Single-source vulnerability concentrates in TÜV validation services and captive chip sourcing from Mitsubishi Electric's in-house supply base. Distribution runs through Yangtze River Delta system integrators for GB/T-compliant deployments and Australian mining automation channels for legacy fieldbus retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ethernet protocol migration and METI's tightened JIS B 9960 certification deadlines are accelerating replacement cycles across Asia Pacific manufacturing corridors. This regulatory-technological inflection creates asymmetric opportunity windows for prepared participants.
For Market Incumbents: Secure backward integration into semiconductor sourcing to defend against captive supply advantages held by Mitsubishi Electric. Expand TÜV certification pipeline capacity to capture Japanese automotive tier-1 procurement acceleration ahead of revised compliance deadlines. Lock in multi-year framework agreements with Chinese battery manufacturers before procurement consolidation hardens further. For New Entrants and Emerging Players: Differentiate on SPE-enabled module architectures for Thai automotive paint shop retrofits seeking topology compression. Target India's PLI scheme beneficiaries in semiconductor packaging and mobile assembly, where established safety I/O supply relationships remain underdeveloped. Pursue direct sourcing relationships with Australian mining automation operators piloting edge computing integration. For Investors and Strategic Acquirers: Regional system integrators with GB/T certification expertise and established SAMR relationships represent the highest-conviction acquisition archetype. Long-term viability hinges on positioning for IEC 62061 harmonization convergence rather than parallel variant maintenance. Watch for divergence resolution between China's domestic certification pathways and international standards as the decisive inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Captive chip supply from Japanese component houses limits second-source availability for module vendors. |
| TÜV SIL 3 Certification Pipeline Expansion | METI's tightened JIS B 9960 deadlines accelerate procurement from automotive tier-1 suppliers in Aichi Prefecture. |
| Single-Pair Ethernet Product Line Launch | Thai paint shops in Rayong province pilot SPE-enabled modules to reduce robotic cell cabling mass. |
| Multi-Year Framework Agreement Negotiation | CATL and BYD supply chain managers unbundle hardware from services, forcing pure unit economics competition. |
| India Electronics Manufacturing Channel Entry | PLI scheme beneficiaries in semiconductor packaging lack established safety I/O supplier relationships. |
Study Parameters
Operator-level perspectives from plant engineers, OEM procurement teams, aftermarket service heads, and system integration specialists anchored the qualitative base for this analysis. Primary fieldwork combined with secondary validation from SEC filings, customs and trade data, SAMR regulatory filings, and METI certification records. Bottom-up demand modeling across manufacturing clusters triangulated with top-down industry aggregation.
Sensitivity analysis tested forecast robustness across alternative Ethernet adoption trajectories and certification timeline scenarios. Segmentation dimensions modeled include product type, end user industry, communication protocol, and installation format across the projection horizon. CAGRs derived from installed base replacement cycles, greenfield construction permits, and regulatory mandate enforcement schedules. Battery gigafactory buildout announcements and automotive assembly expansion timelines served as industry-specific demand inputs.
Material uncertainties — semiconductor supply disruptions, regulatory divergence persistence, and legacy fieldbus migration delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about protocol substitution rates and compliance deadline adherence. Recalibration cycles align with material shifts in SAMR enforcement intensity and METI certification revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Position Sensor Market
Sensors and Controls
Environmental Sensing and Monitoring Technologies Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Battery Monitor Market
Sensors and Controls
Electric Pipette Controllers Market
Sensors and Controls
United States Scintillator Market
Sensors and Controls
Steam Trap Monitor Market
Sensors and Controls
Global Smart Biosensors Market
Sensors and Controls
Level Measuring Equipment Market
Sensors and Controls
Biometric Sensors Market
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
Global Fluid Management and Visualization Systems Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Rotary Encoders Market
Sensors and Controls
Europe Advanced CO2 Sensor Market