
 Wireless Pressure Sensors Market | 2026-2036
Wireless Pressure Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Pressure Sensors Market Analytics
Modular sensor-plus-transmitter bundles is pivoting procurement patterns across process industries. Emerson Electric Company leverages its Plantweb digital ecosystem to anchor long-term service contracts alongside hardware sales. Honeywell International sustains differentiation through unified software platforms that integrate pressure data with broader asset performance management. Siemens AG competes by extending its SIMATIC portfolio into edge-computing-enabled wireless nodes.
Wireless pressure sensors are transducers that convert fluid or gas pressure into radio-frequency signals for remote monitoring, typically operating across ranges from vacuum to 10,000 psi with accuracy classes of 0.1% to 0.25% full scale. They eliminate conduit and wiring costs in hazardous environments while enabling real-time data acquisition for distributed control systems. Gauge pressure sensors dominate unit shipments in HVAC and environmental monitoring due to standardized atmospheric reference designs and lower calibration overhead. Capacitive technology leads in aerospace and healthcare applications where drift stability and temperature compensation justify premium positioning. Optical sensing, though nascent, is capturing attention in robotics for immunity to electromagnetic interference in compact actuator assemblies.
The US Occupational Safety and Health Administration mandates process safety management protocols that incentivize continuous pressure monitoring in chemical facilities, directly expanding addressable demand for wireless instrumentation. The European Union's F-Gas Regulation drives refrigerant system leak detection requirements that elevate sensor density in commercial HVAC deployments. Stakeholders must weigh interoperability certifications against proprietary ecosystem lock-in when specifying wireless pressure architectures for multi-vendor plant environments.
Market Dynamics
The transition from wired to wireless Industrial Internet of Things architectures is compressing installation timelines and eliminating conduit costs in process control environments. Oil and gas refineries are rewriting procurement specifications to favor sensor-plus-transmitter bundles over discrete component sourcing.
Growth Catalysts
- OSHA Process Safety Management:Continuous pressure monitoring mandates in US chemical facilities are expanding addressable demand for wireless instrumentation that eliminates wiring in hazardous classified locations.
- Capacitive drift stability:Aerospace and healthcare applications are prioritizing temperature-compensated designs that justify premium positioning over piezoresistive alternatives.
- German automotive clusters:Predictive maintenance programs at Stuttgart and Wolfsburg manufacturing hubs are integrating wireless sensor networks into assembly line condition monitoring.
Market Restraints
- Proprietary ecosystem lock-in:Multi-vendor plant environments face interoperability certification costs that favor single-supplier contracts and limit hardware sourcing flexibility.
- Optical sensing immaturity:Robotics applications requiring electromagnetic immunity in compact actuator assemblies await volume manufacturing scale for cost-effective deployment.
- Calibration overhead variance:Gauge pressure sensors carry lower atmospheric reference calibration burdens than absolute pressure designs, fragmenting unit economics across HVAC versus process control segments.
Strategic Opportunities
- EU F-Gas Regulation:Refrigerant leak detection requirements are elevating sensor density in commercial HVAC deployments across France, Germany, and Italy.
- Edge-computing convergence:Wireless nodes with onboard analytics are compressing latency for distributed control systems in upstream oil and gas operations.
- India process industries:Chemical and pharmaceutical manufacturing under BIS standards adoption is creating first-mover advantages for wireless instrumentation suppliers establishing local calibration networks.
Industry Challenges
- IECEx/ATEX certification timelines:Hazardous area approvals for wireless devices require 12-18 month validation cycles that delay product launches in oil and gas segments.
- Legacy DCS integration:Brownfield installations demand protocol translation gateways that add cost and complexity to wireless pressure sensor deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Pressure Sensors Market |
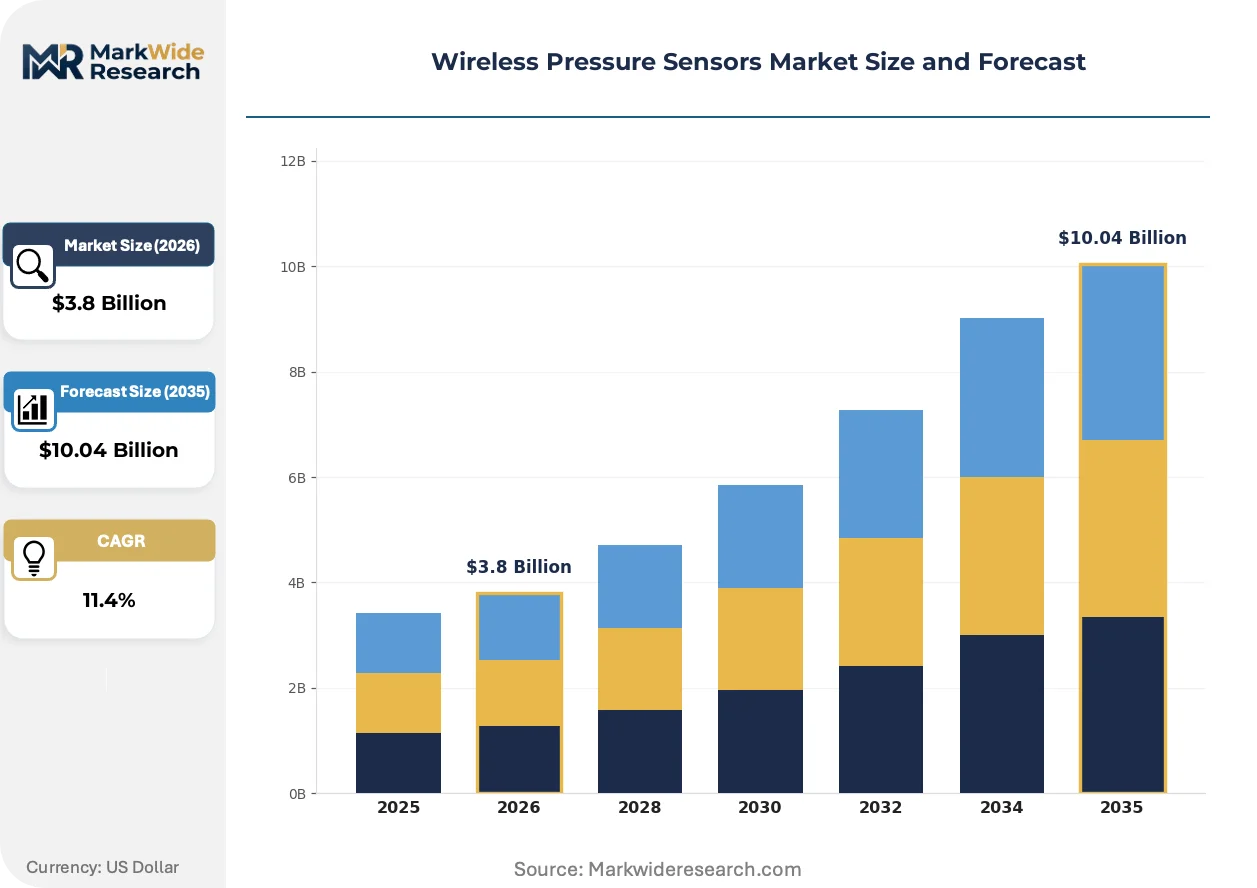
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute Pressure Sensors, Gauge Pressure Sensors, Differential Pressure Sensors, Sealed Pressure Sensors Technology: Piezoelectric, Capacitive, Strain Gauge, Optical End User: Automotive, Aerospace, Healthcare, Industrial Application: Process Control, Environmental Monitoring, HVAC Systems, Robotics |
| Companies Covered | ABB Group, Emerson Electric Company, Honeywell International, Infineon Technologies AG, TE Connectivity, Siemens AG, Texas Instruments, Rockwell Automation, OleumTech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Pressure Sensors Market Evolving Landscape
Modular hardware-software bundles are displacing discrete component procurement across process industries. Vendors are anchoring long-term service contracts through digital ecosystems rather than transactional hardware sales.
MEMS-based pressure transduction is automating calibration routines through self-diagnostic firmware that compensates for temperature drift in real time. Automotive tier-one suppliers are adopting these designs for tire pressure monitoring and transmission control systems. The technology is automating field maintenance schedules and reducing technician dispatch frequency for recalibration.
The EU F-Gas Regulation is mandating refrigerant system monitoring thresholds that elevate sensor density in commercial HVAC deployments. Equipment manufacturers must demonstrate leak detection capabilities to maintain CE marking for climate-relevant installations. German and French HVAC OEMs are responding by specifying wireless pressure sensors with integrated temperature compensation for rooftop unit applications.
Buyer specifications are consolidating around unified software platforms that integrate pressure data with broader asset performance management systems. Process industries are unbundling after-sales service from hardware procurement, favoring outcome-based contracts with guaranteed uptime metrics. This behavioral shift is most visible in North American oil and gas operations where operator consolidation has concentrated purchasing power among supermajors.
Wireless Pressure Sensors Market Segmentation
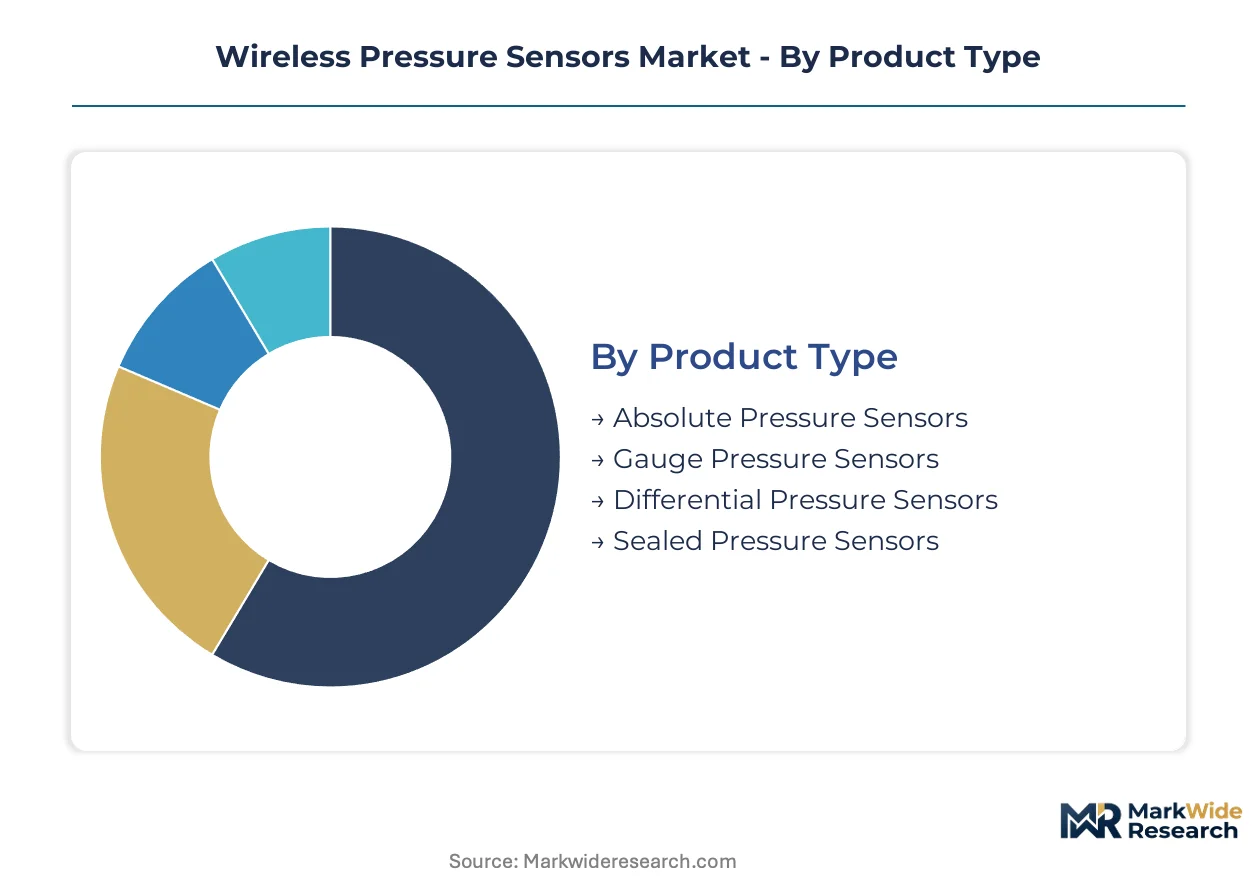
Wireless pressure sensors fragment across four distinct dimensions, each commanding different margin structures and certification requirements. Procurement specifications diverge sharply between process industries seeking hazardous-area ratings and automotive OEMs prioritizing MEMS miniaturization.
Product Type:
Supply concentration clusters around gauge pressure architectures where standardized atmospheric reference designs reduce calibration overhead and accelerate production scale.
- Absolute Pressure Sensors:These devices reference sealed vacuum chambers to measure pressure against zero-point baselines. Aerospace applications in Germany and France demand these for altitude compensation in flight control systems, with temperature drift specifications driving unit premiums.
- Gauge Pressure Sensors:Atmospheric-referenced designs dominate unit economics through simplified calibration protocols. HVAC deployments across Italy and Spain leverage these for refrigerant monitoring under EU F-Gas Regulation mandates, with sensor density requirements elevating procurement volumes.
- Differential Pressure Sensors:Twin-port architectures measure pressure variance across filtration and flow systems. Industrial facilities in the US deploy these for cleanroom validation and pipeline monitoring where OSHA process safety protocols apply.
- Sealed Pressure Sensors:Pre-pressurized reference chambers withstand corrosive media exposure. Offshore oil platforms specify these for subsea wellhead monitoring where saltwater ingress risks mandate hermetic sealing.
Today's leader: Gauge Pressure Sensors. Tomorrow's challenger: Absolute Pressure Sensors.
Technology:
Cost tiers separate piezoelectric volume manufacturing from optical prototyping where electromagnetic immunity justifies development investment.
- Piezoelectric:Quartz crystal transduction delivers microsecond response times for dynamic pressure events. Automotive transmission control systems in Stuttgart manufacturing clusters specify these for real-time shift optimization, with tier-one suppliers automating calibration through self-diagnostic firmware.
- Capacitive:MEMS-fabricated diaphragm-capacitor pairs achieve drift stability below 0.1% annually. Medical device manufacturers in Switzerland and the Netherlands prioritize these for invasive pressure monitoring where long-term accuracy preserves patient safety margins.
- Strain Gauge:Bonded foil or semiconductor elements convert mechanical deformation to resistance change. Industrial weighing and hydraulic systems favor these for proven durability in high-cycle fatigue environments.
- Optical:Fiber-Bragg grating and interferometric methods eliminate electrical conductivity in explosive atmospheres. Robotics developers in Japan await volume manufacturing scale for compact actuator integration where EMI immunity enables precision positioning.
Piezoelectric architectures anchor present volume. Optical methods claim the steepest expansion trajectory as robotics applications mature.
End User:
Application maturity varies dramatically, with industrial automation commanding established specification standards while healthcare navigates biocompatibility validation cycles.
- Automotive:Tire pressure monitoring systems and transmission controls drive MEMS sensor consumption. Wolfsburg and Stuttgart production hubs integrate wireless nodes into predictive maintenance programs, with edge-computing convergence compressing latency for assembly line condition monitoring.
- Aerospace:Flight control surface actuation and environmental control systems demand MIL-STD-810G qualification. German and French airframe manufacturers specify capacitive designs for altitude and airspeed measurement where temperature compensation preserves accuracy across -55°C to 125°C operational ranges.
- Healthcare:Invasive hemodynamic monitoring and ventilator pressure sensing require FDA and CE marking under MDR. Swiss and Dutch medical technology clusters prioritize drift-stable capacitive architectures for multi-day patient monitoring.
- Industrial:Oil and gas refineries, chemical processing, and water treatment facilities constitute the largest addressable base. US OSHA process safety management mandates expand procurement specifications for wireless instrumentation in hazardous classified locations.
Industrial end-use commands current procurement volumes. Healthcare applications are climbing fastest as wireless telemetry displaces wired bedside monitoring.
Application:
Customer type differentiation separates process control engineers specifying IECEx certifications from facilities managers prioritizing plug-and-play HVAC retrofit compatibility.
- Process Control:Distributed control system integration demands HART, WirelessHART, or ISA100 protocol compatibility. Oil and gas supermajors in the US Gulf Coast and North Sea rewrite procurement specifications to favor sensor-plus-transmitter bundles over discrete component sourcing.
- Environmental Monitoring:Atmospheric and water quality sensing networks require low-power wide-area connectivity. French and German environmental agencies deploy these for flood warning and air quality index validation.
- HVAC Systems:Rooftop unit and chiller applications concentrate sensor density for refrigerant leak detection. EU F-Gas Regulation mandates elevate specifications across France, Germany, and Italy, with integrated temperature compensation becoming standard.
- Robotics:Compact actuator feedback and collaborative robot safety systems seek EMI-immune sensing. Japanese and South Korean automation developers prototype optical methods for electromagnetic compatibility in dense motor environments.
Process Control anchors present revenue. Robotics represents the fastest-growing trajectory as collaborative automation penetrates manufacturing floors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wireless pressure sensor manufacturing originated in German precision engineering clusters during the 1990s, with early adoption spreading through North Sea oil platforms and US chemical corridors before establishing production footprints across Asia-Pacific automotive hubs.
United States
Gulf Coast refineries and Permian Basin upstream operations drive hazardous-area instrumentation procurement. OSHA Process Safety Management mandates continuous pressure monitoring in chemical facilities, expanding specification requirements for WirelessHART-certified devices. Houston engineering contractors are bundling sensor-plus-transmitter packages into multi-year service agreements with supermajor operators.
Germany
Stuttgart and Wolfsburg automotive manufacturing clusters integrate wireless sensor networks into predictive maintenance programs for assembly line condition monitoring. The EU F-Gas Regulation elevates refrigerant leak detection specifications across commercial HVAC deployments. Bavarian industrial automation specialists are extending edge-computing capabilities into wireless pressure nodes for real-time process optimization.
China
Yangtze River Delta chemical processing complexes are retrofitting distributed control systems with wireless instrumentation to reduce conduit installation costs. The country's national standards body is aligning industrial wireless protocols with IEC specifications for hazardous-area certification. Shanghai-based system integrators are localizing calibration networks for MEMS pressure transducers serving domestic pharmaceutical manufacturers.
Japan
Chubu region robotics developers prototype optical pressure sensing methods for electromagnetic immunity in compact actuator assemblies. METI industrial digitization programs incentivize wireless sensor adoption in precision manufacturing facilities. Nagoya automotive suppliers are qualifying capacitive pressure designs for transmission control systems with self-diagnostic firmware capabilities.
India
Gujarat and Maharashtra chemical corridors under BIS standards adoption are creating first-mover opportunities for wireless instrumentation suppliers establishing local calibration infrastructure. The country's national pharmaceutical regulator is aligning active medical device requirements with international electromagnetic compatibility standards. Mumbai engineering procurement teams are specifying ISA100 protocol compatibility for greenfield refinery expansions.
Wireless Pressure Sensors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-tier and software-integration dimensions. The vendor base stratifies into three tiers: diversified industrial conglomerates with digital ecosystem anchoring, specialized sensor fabricators with hazardous-area expertise, and semiconductor suppliers with MEMS fabrication scale. Consolidation pressure concentrates among mid-scale automation specialists lacking protocol translation gateway portfolios. Dominant competitive moves include strategic partnerships for edge-computing software stacks and geographic expansion through local calibration network establishment.
Within the diversified industrial tier, Emerson Electric Company, Honeywell International, and Siemens AG exemplify platform-centric positioning. Emerson leverages its Plantweb digital ecosystem to anchor long-term service contracts. Honeywell sustains differentiation through unified software platforms integrating pressure data with asset performance management. Siemens extends its SIMATIC portfolio into edge-computing-enabled wireless nodes. These three conglomerates represent the premium-tier archetype where hardware procurement unbundles from outcome-based service agreements.
| Leading Market Players |
|---|
| ABB Group |
| Emerson Electric Company |
| Honeywell International |
| Infineon Technologies AG |
| TE Connectivity |
| Siemens AG |
| Texas Instruments |
| Rockwell Automation |
| OleumTech Corporation |
| Others |
Value Network & Pricing Analysis
MEMS wafer fabrication costs anchor pricing tiers across wireless pressure sensor architectures, flowing from Taiwanese foundries through German calibration houses to oil and gas supermajors bundling hardware into multi-year service agreements. This input cost structure fragments downstream, with IECEx-certified devices commanding premium positioning against HVAC-destined gauge pressure alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates hazardous-area certified instrumentation from commercial HVAC components and commodity MEMS modules. Price differentiation hinges on ATEX/IECEx certification grade and after-sales service bundling. Cost compression in the standard tier intensifies as Chinese MEMS fabricators scale capacitive diaphragm production. Chemical facilities under OSHA mandates show least price sensitivity, while commercial HVAC retrofitters prioritize economy-tier plug-and-play compatibility.
Supply Chain Analysis
Domestic-content mandates in India's BIS standards adoption and China's GB alignment initiatives are reshaping sourcing patterns for calibration networks and protocol translation gateways. Manufacturing concentrates in Germany, China, and the United States, with MEMS wafer supply drawing from Taiwanese foundries and specialized glass-to-metal seal suppliers in Switzerland. Single-source vulnerability clusters around hermetic sealing for subsea applications. Distribution runs through system integrators anchoring long-term service contracts with end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless pressure sensor margins expand through MEMS miniaturization cost curves and predictive maintenance service bundling that unbundles hardware procurement from outcome-based uptime guarantees.
For Market Incumbents: Anticipate optical sensing disruption in robotics applications by securing fiber-Bragg grating intellectual property and prototyping partnerships with Japanese automation developers. Deepen backward integration into MEMS wafer supply through captive foundry arrangements or long-term offtake agreements with Taiwanese fabricators. Anchor Plantweb-style digital ecosystems to resist proprietary protocol fragmentation. For New Entrants and Emerging Players: The price-point gap between Emerson-tier premium instrumentation and unbranded Chinese MEMS modules creates entry space for mid-tier specialists. Target India's BIS-aligned chemical corridors where local calibration infrastructure remains underdeveloped. Pursue ISA100 protocol certification as a go-to-market wedge against entrenched WirelessHART incumbents in greenfield refinery expansions. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale automation specialists lack edge-computing software stacks and protocol translation gateway portfolios. Long-term viability favors vendors with hazardous-area certification depth and recurring service revenue anchoring. Watch optical sensing volume manufacturing scale as the inflection signal for robotics application monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Software Stack Partnership | Compresses latency for distributed control systems in Permian Basin upstream operations. |
| Local Calibration Network Establishment | Captures first-mover positioning in India's BIS-aligned pharmaceutical manufacturing corridors. |
| Optical Sensing Volume Manufacturing Scale-Up | Enables cost-effective EMI-immune deployment in Japanese robotics actuator assemblies. |
| ISA100 Protocol Certification Investment | Unlocks greenfield refinery specifications in Mumbai engineering procurement pipelines. |
| Backward Integration into MEMS Wafer Supply | Secures cost positioning against Chinese capacitive diaphragm fabricators scaling production. |
Research Methodology
Direct dialogue with plant engineers, OEM procurement managers, hazardous-area certification specialists, and aftermarket service heads grounded the qualitative foundation. Secondary validation drew from OSHA enforcement databases, EU F-Gas Regulation implementation reports, IECEx certification registries, and SEC filings of diversified industrial conglomerates. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Segmented outputs across product type, technology architecture, end-user industry, and application use case informed the analytical framework. Modeled dimensions included certification tier, protocol compatibility, and regional regulatory cluster. CAGRs derived from installation base expansion rates and replacement cycle compression in process control environments. MEMS cost curve trajectories and predictive maintenance service attach rates served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for optical sensing in robotics would alter the outlook if electromagnetic interference regulations tighten faster than anticipated. Forecasts reflect embedded assumptions about IECEx/ATEX certification timeline stability and wireless protocol standardization convergence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Nanosensors Market
Sensors and Controls
North America Turbomachinery Control Systems Market
Sensors and Controls
Sensor Patch Market
Sensors and Controls
Asia-Pacific Machine Control System Market
Sensors and Controls
Fingerprint Sensor Market
Sensors and Controls
Heart Beat Sensor Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Fluid Sensors Market
Sensors and Controls
Surface Vision and Inspection Market
Sensors and Controls
Semiconductor Sensor Market
Sensors and Controls
High-End Accelerometer Market
Sensors and Controls
Air Pressure Sensor Market
Sensors and Controls
Thermal Anemometer Market
Sensors and Controls
Thermal Flow Meter Market
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market