
 Height Measurement Devices Market | 2026-2036
Height Measurement Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Height Measurement Devices Market Foresight
Pediatric measurement is pivoting toward non-contact modalities as infection-control protocols harden in clinical settings. Seca GmbH & Co. KG leverages its German manufacturing base to dominate electromechanical stadiometer supply across European hospital networks. Detecto Scale Company anchors North American demand through deep distribution into federally qualified health centers. Tanita Corporation differentiates via ultrasonic technology leadership in compact footprint designs for Asian clinic environments.
Height measurement devices are instruments engineered to quantify vertical human stature with precision typically within one millimeter, employing mechanical counterweights, ultrasonic time-of-flight sensors, or laser triangulation arrays calibrated against rigid reference standards. Their primary commercial purpose centers on clinical growth monitoring, nutritional assessment, and anthropometric research requiring reproducible longitudinal data. Digital stadiometers command the widest installed base across hospital systems due to interoperability with electronic health records, while laser height measurement segments attract premium positioning in high-throughput fitness assessment chains where speed determines throughput economics. Electromechanical technology retains cost advantages in resource-constrained clinics, though ultrasonic modules capture replacement cycles as practices modernize diagnostic workflows.
FDA 510(k) clearance requirements shape product development timelines for devices entering US clinical channels, while EU MDR conformity assessments impose stricter post-market surveillance obligations on manufacturers serving European hospitals. China's NMPA medical device classification system creates registration bottlenecks that favor established players with dedicated regulatory affairs teams in Beijing and Shanghai. Stakeholders must monitor divergence between FDA software-as-medical-device guidance and EU AI Act implications for instruments incorporating automated growth-velocity algorithms.
Market Dynamics
Ultrasonic sensor miniaturization from Japanese component makers is compressing device footprints without sacrificing accuracy, forcing electromechanical incumbents to accelerate R&D cycles or cede clinic upgrade contracts to ultrasonic-first vendors.
Growth Catalysts
- EU MDR post-market surveillance obligations:Stricter conformity assessments in European hospitals are accelerating replacement cycles for legacy stadiometers that lack digital traceability and automated calibration logging.
- WHO growth-chart protocol tightening:Pediatric clinics in Germany are expanding procurement of digital stadiometers as international health standards demand sub-millimeter precision for longitudinal growth monitoring.
- China's tier-one hospital infrastructure upgrades:Municipal health bureaus in Beijing and Shanghai prioritize integrated diagnostic stations, concentrating demand for connected height measurement modules within multi-parameter examination systems.
Market Restraints
- Precision sensor input cost volatility:Ultrasonic transducer chips and laser diode arrays face price instability from concentrated wafer fabrication in East Asian foundries, squeezing margins for mid-tier device assemblers.
- Regulatory registration bottlenecks:China's NMPA medical device classification system creates multi-year approval timelines that favor established players with dedicated regulatory affairs teams in Beijing and Shanghai.
- Mechanical stadiometer substitution ceiling:Electromechanical technology retains cost advantages in resource-constrained clinics, slowing ultrasonic module penetration in price-sensitive procurement channels.
Strategic Opportunities
- Fitness assessment chain throughput economics:Laser height measurement segments attract premium positioning in high-throughput wellness centers where measurement speed determines client processing capacity and revenue per square meter.
- Software-as-medical-device divergence:FDA guidance on automated growth-velocity algorithms creates first-mover advantages for vendors with embedded AI development teams, separate from EU AI Act compliance pathways.
- Federally qualified health center distribution gaps:Deep distribution into US community health centers remains underpenetrated by ultrasonic technology vendors focused on hospital system sales.
Industry Challenges
- Electronic health record interoperability complexity:Digital stadiometer vendors face fragmented HL7 FHIR implementation standards across hospital IT systems, requiring costly custom integration engineering per deployment.
- ISO 13485 quality management system certification timelines:New market entrants encounter 12-18 month quality system establishment periods before regulatory submissions, delaying revenue recognition and consuming working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Height Measurement Devices Market |
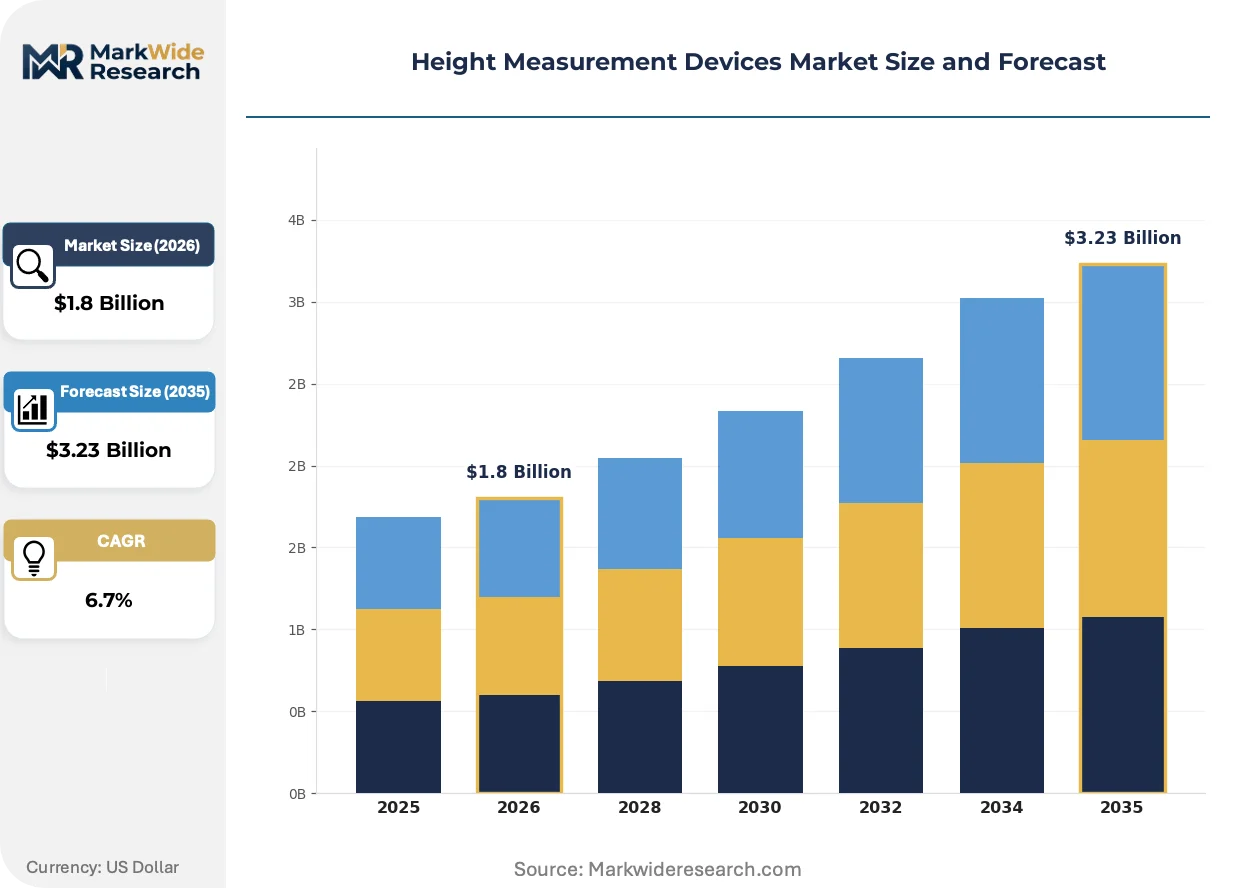
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Stadiometer, Mechanical Stadiometer, Anthropometric Measurement Kit, Laser Height Measurement End User: Hospitals, Clinics, Fitness Centers, Research Laboratories Technology: Ultrasonic, Laser, Optical, Electromechanical Application: Pediatric Measurement, Fitness Assessment, Medical Diagnosis, Anthropometry |
| Companies Covered | Seca GmbH & Co. KG, Detecto Scale Company, Tanita Corporation, Health o meter Professional, Charder Electronic Co., Ltd., ADE Germany GmbH, Marsden Weighing Group, Befour, Inc., Rice Lake Weighing Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Height Measurement Devices Market Shifts & Advancements
Non-contact measurement modalities are hardening infection-control protocols in clinical settings while sensor fusion architectures enable multi-parameter diagnostic stations that consolidate anthropometric workflows into single-platform deployments.
Time-of-flight ultrasonic arrays are automating stature capture in pediatric examination rooms by eliminating physical contact between patient and instrument. Children's hospitals in Japan and South Korea are deploying these systems at replacement-cycle pace to reduce cross-contamination risks. The technology is automating staff workflow efficiency while compressing examination room turnover intervals by removing manual stadiometer positioning steps.
EU AI Act implications for automated growth-velocity algorithms are forcing divergence between European and American product development roadmaps. Manufacturers serving EU hospitals must implement explainability requirements and human-in-the-loop validation that FDA software-as-medical-device guidance does not yet mandate. Pediatric endocrinology practices in Germany and France face extended procurement delays as vendors re-engineer algorithmic transparency features.
Diagnostic station integration contracts are consolidating vendor relationships around multi-parameter platform suppliers. Hospital procurement departments in China's tier-one cities now specify height measurement as a module within integrated examination systems rather than standalone device purchases. This behavioral shift compresses addressable market scope for pure-play stadiometer manufacturers while expanding systems integrator margins.
Height Measurement Devices Market Segmentation
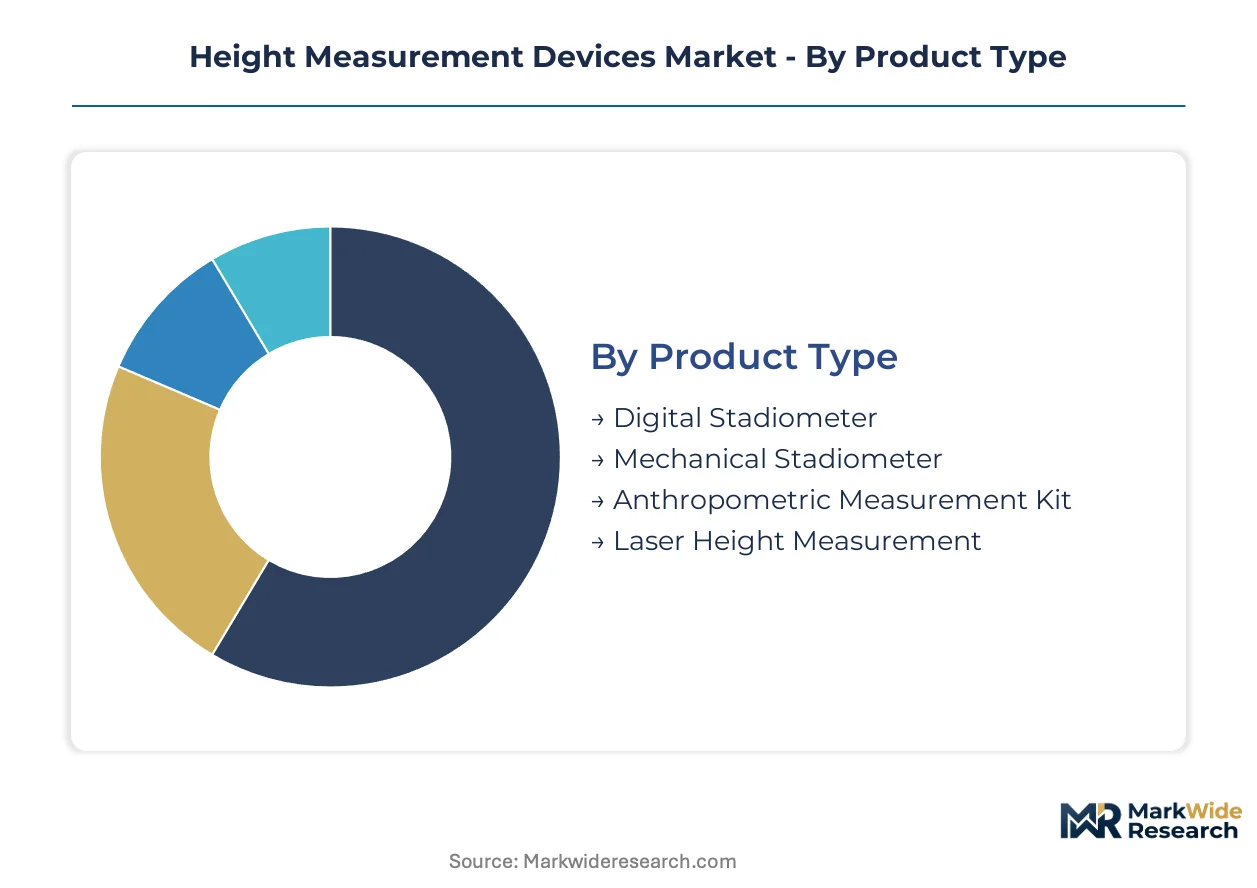
Segmentation reveals divergent upgrade cycles across clinical and commercial settings. Technology substitution patterns vary sharply between pediatric hospitals prioritizing infection control and fitness chains optimizing throughput economics.
Product Type:
Replacement cycles accelerate where digital traceability and EHR interoperability become procurement requirements.
- Digital Stadiometer:Electronic height rods with integrated data transmission modules enable direct HL7 FHIR connectivity to hospital information systems. Demand concentrates in German pediatric clinics as WHO growth-chart protocols tighten precision requirements for longitudinal monitoring.
- Mechanical Stadiometer:Counterweight-based analog instruments with sliding headpieces and printed measurement scales retain procurement share in resource-constrained settings. Cost advantages slow displacement in India's tier-two district hospitals and Latin American primary care centers.
- Anthropometric Measurement Kit:Bundled instruments combining stadiometers with calipers and circumference tapes for comprehensive body composition assessment.
- Laser Height Measurement:Triangulation-based non-contact systems capturing stature via structured light projection without patient positioning.
Digital stadiometers sit at the top of the volume ranking, with laser height measurement climbing the fastest.
End User:
Procurement authority structures determine vendor access and contract consolidation patterns.
- Hospitals:Acute care and specialty institutions with centralized biomedical engineering departments managing multi-parameter diagnostic station deployments. China's tier-one municipal health bureaus specify integrated examination systems bundling height modules with vital signs monitors.
- Clinics:Outpatient facilities including pediatric endocrinology practices and community health centers requiring compact footprint instruments. Federally qualified health centers in the US represent underpenetrated distribution channels for ultrasonic technology vendors.
- Fitness Centers:Commercial wellness chains and corporate health programs processing high daily measurement volumes.
- Research Laboratories:Academic anthropometry units and longitudinal growth studies demanding calibrated reference-standard precision.
Hospitals command the largest procurement volumes, while fitness centers are expanding most quickly as wellness chain penetration deepens.
Technology:
Component miniaturization from Japanese suppliers is compressing device footprints and reshaping competitive positioning.
- Ultrasonic:Time-of-flight sensor arrays measuring stature via acoustic pulse reflection without physical patient contact. Pediatric examination rooms in Japan and South Korea deploy these systems at replacement-cycle pace to harden infection-control protocols.
- Laser:Triangulation modules projecting structured light patterns for sub-second capture in high-throughput environments. Fitness assessment chains in North America specify these for throughput economics where measurement speed determines client processing capacity.
- Optical:Camera-based vision systems with edge-detection algorithms for automated stature extraction.
- Electromechanical:Motorized height rods with rotary encoders translating mechanical displacement into digital signals.
Electromechanical technology retains the widest installed base, though ultrasonic modules are gaining share fastest on infection-control demand.
Application:
Precision requirements and regulatory exposure vary substantially across use cases.
- Pediatric Measurement:Growth monitoring applications demanding sub-millimeter reproducibility for velocity calculations and endocrine referral thresholds. EU AI Act explainability requirements are forcing algorithm re-engineering for automated growth-velocity systems in Germany and France.
- Fitness Assessment:Commercial wellness applications prioritizing speed and user experience over clinical-grade precision. Premium positioning in high-throughput chains where revenue per square meter depends on examination room turnover intervals.
- Medical Diagnosis:Diagnostic workflows supporting nutritional assessment, syndrome screening, and pharmaceutical dosing calculations.
- Anthropometry:Research-grade measurement for epidemiological studies, sports science, and ergonomic design applications.
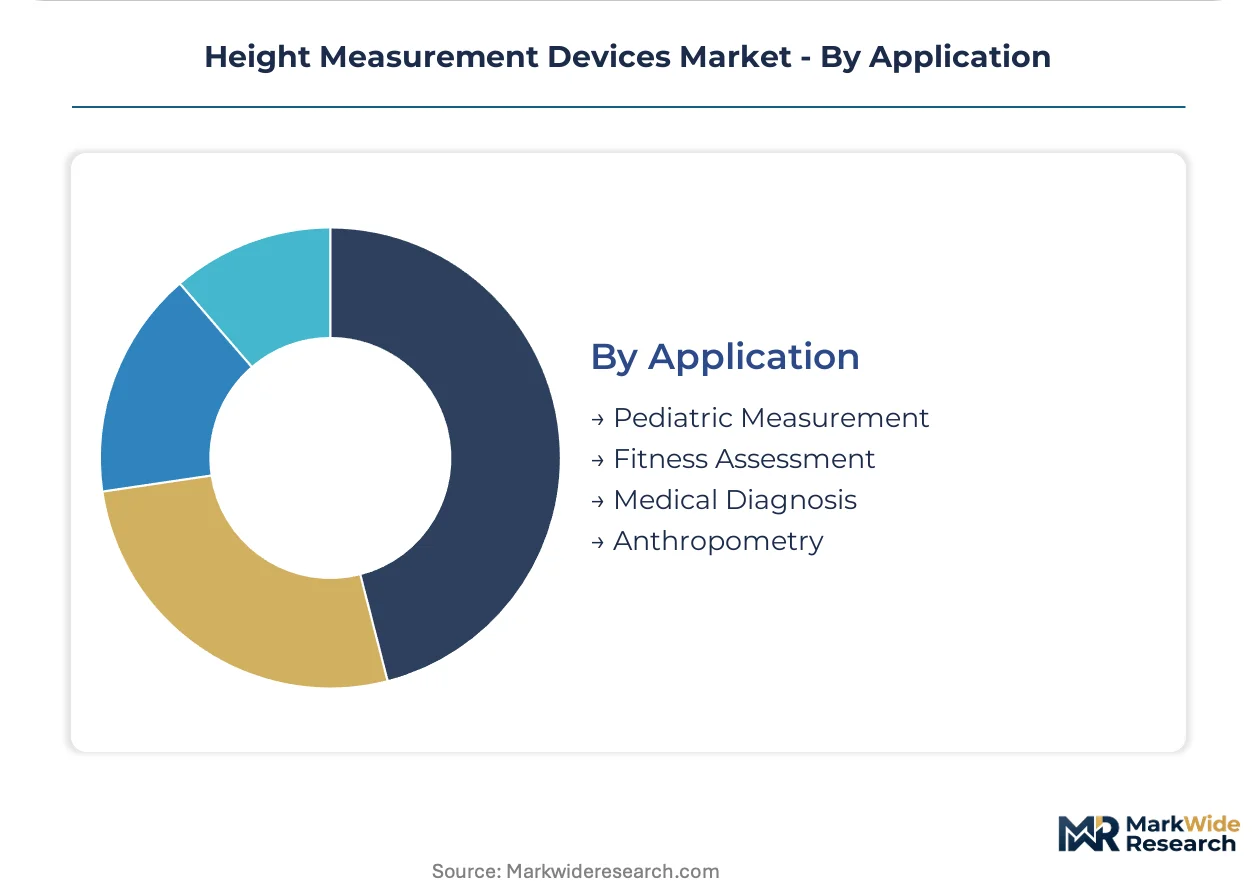
Pediatric measurement dominates clinical procurement volumes, with fitness assessment expanding most steeply on commercial wellness chain growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as EU MDR compliance costs accelerate production migration toward jurisdictions with streamlined quality system certification. Japanese component suppliers exploit this gap by miniaturizing ultrasonic sensors for export to European assemblers seeking cost-efficient module sourcing.
United States
Federally qualified health centers drive procurement volume for electromechanical stadiometers with basic EHR connectivity. FDA 510(k) clearance timelines shape product development cycles for devices entering clinical channels. Manufacturing concentrates in Midwest industrial corridors serving domestic hospital system demand.
Germany
Pediatric clinics in Bavaria and North Rhine-Westphalia are expanding digital stadiometer procurement as WHO growth-chart protocols tighten precision requirements. EU MDR post-market surveillance obligations accelerate replacement cycles for legacy instruments lacking automated calibration logging. Seca GmbH anchors electromechanical supply across European hospital networks from its Hamburg manufacturing base.
China
Tier-one municipal health bureaus in Beijing and Shanghai prioritize integrated diagnostic stations bundling height modules with vital signs monitors. NMPA medical device classification creates registration bottlenecks favoring established players with dedicated regulatory affairs teams. Yangtze River Delta manufacturing clusters supply ultrasonic transducer assemblies to domestic and export markets.
Japan
Pediatric examination rooms in Tokyo and Osaka deploy time-of-flight ultrasonic systems at replacement-cycle pace to harden infection-control protocols. METI industrial standards guide sensor miniaturization R&D at component makers in Nagoya industrial zones. Tanita Corporation leverages domestic ultrasonic technology leadership for compact footprint designs targeting Asian clinic environments.
South Korea
Children's hospitals in Seoul Capital Area automate stature capture via non-contact modalities to reduce cross-contamination risks. MFDS medical device regulations align with international standards while maintaining streamlined approval pathways for innovative sensor technologies. Busan-Ulsan manufacturing corridors supply optical detection modules for domestic diagnostic equipment assemblers.
Height Measurement Devices Market Competitive Landscape
Technology licensing dominates the current landscape as ultrasonic-first vendors compress device footprints and force electromechanical incumbents into accelerated R&D cycles. The vendor base stratifies across three tiers: integrated diagnostic platform suppliers capturing hospital system contracts, pure-play stadiometer manufacturers defending clinic upgrade cycles, and component specialists supplying sensor modules to tier-one assemblers. Competitive moves center on strategic partnerships with EHR interoperability vendors and geographic expansion into underpenetrated federally qualified health center channels.
Among German-based precision instrument fabricators, Seca GmbH & Co. KG and ADE Germany GmbH occupy positions within the electromechanical tier, exemplifying European manufacturing heritage in clinical measurement equipment. Tanita Corporation represents the ultrasonic technology archetype, anchoring Japanese innovation in compact sensor design. Detecto Scale Company sits within the North American distribution-focused tier, leveraging deep channel relationships into community health infrastructure.
| Leading Market Players |
|---|
| Seca GmbH & Co. KG |
| Detecto Scale Company |
| Tanita Corporation |
| Health o meter Professional |
| Charder Electronic Co., Ltd. |
| ADE Germany GmbH |
| Marsden Weighing Group |
| Befour, Inc. |
| Rice Lake Weighing Systems |
| Others |
Supply & Pricing Matrix
Captive ultrasonic sensor production in Japanese industrial corridors anchors both component availability and premium-tier pricing power for manufacturers serving pediatric infection-control protocols. This integration choice insulates tier-one vendors from wafer-fabrication volatility while forcing electromechanical assemblers into margin compression as they source miniaturized modules at spot-market terms.
Pricing Analysis
Distributor margin layers in European hospital procurement channels absorb fifteen to twenty-five points before devices reach biomedical engineering departments. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared laser systems from CE-marked ultrasonic units and unclassified mechanical stadiometers. Cost compression in mid-tier electromechanical segments is intensifying because Japanese component miniaturization enables ultrasonic-first vendors to undercut legacy pricing. Federally qualified health centers exhibit highest price sensitivity, while German pediatric clinics purchasing under EU MDR compliance show lowest elasticity.
Supply Chain Analysis
ISO 13485 certification gating extends quality-system establishment timelines to twelve-to-eighteen months before regulatory submissions can proceed. Manufacturing concentrates in Germany, Japan, and China, with Yangtze River Delta clusters supplying ultrasonic transducer assemblies and Hamburg-area fabricators producing electromechanical height rods. Raw material dependencies include precision-machined aluminum extrusions, MEMS ultrasonic wafers from East Asian foundries, and laser diode arrays. Single-source vulnerability in wafer fabrication creates procurement risk for vendors lacking qualified secondary suppliers. Distribution runs through medical device distributors and direct hospital system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value as EU MDR post-market surveillance obligations accelerate replacement cycles for legacy instruments lacking digital traceability.
For Market Incumbents: Anchor market position through backward integration into ultrasonic sensor module production and accelerated FDA 510(k) clearance pipelines for AI-enabled growth-velocity algorithms. Electromechanical incumbents face displacement from ultrasonic-first vendors compressing device footprints; defend through exclusive EHR interoperability partnerships with Epic and Cerner installations. For New Entrants and Emerging Players: The price-point gap between premium laser systems and economy mechanical stadiometers creates white-space opportunity for mid-tier ultrasonic vendors with compact footprint designs. Target federally qualified health centers in the US Midwest and South where electromechanical penetration remains highest. Pursue software-as-medical-device certification as a differentiation wedge against hardware-only competitors. For Investors and Strategic Acquirers: Roll-up economics work for pure-play stadiometer manufacturers because diagnostic station integration contracts are consolidating vendor relationships around multi-parameter platform suppliers. Five-to-ten year viability hinges on algorithmic capability in automated growth monitoring. Watch FDA software-as-medical-device guidance divergence from EU AI Act as the signal for regulatory-arbitrage investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Acceleration | Fast-tracks market access for digital stadiometers with automated calibration logging in German hospital networks. |
| Ultrasonic Sensor Miniaturization | Compresses device footprints for Japanese component makers supplying pediatric infection-control deployments. |
| HL7 FHIR Interoperability Investment | Reduces custom integration engineering costs for EHR-connected stadiometers in US acute care systems. |
| Federally Qualified Health Center Distribution | Captures underpenetrated US community health infrastructure with cost-optimized electromechanical offerings. |
| AI Algorithm Explainability Engineering | Enables EU AI Act compliance for automated growth-velocity systems in French and German pediatric endocrinology practices. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital biomedical engineers, pediatric endocrinologists, GPO contracts managers, and regulatory affairs specialists at device manufacturers with secondary validation against FDA 510(k) filings, EU MDR conformity databases, NMPA registration records, and hospital procurement contract disclosures. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates across the analysis window.
Segment-weighting approaches distributed value projections across product type, end user, technology, and application dimensions, with pediatric measurement and fitness assessment receiving distinct growth-velocity coefficients. CAGRs derived from regression analysis of historical replacement cycles and forward-looking procurement pipeline visibility. Forecast inputs incorporated WHO growth-chart protocol revision timelines and tier-one Chinese hospital infrastructure budget allocations.
Caveats apply where NMPA registration timeline extensions or EU AI Act algorithmic transparency requirement escalations could materially shift the outlook. Forecasts reflect assumptions about ultrasonic sensor cost curves and EHR interoperability standardization momentum. A model refresh is warranted upon material change in FDA software-as-medical-device guidance or WHO pediatric growth reference protocol adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Ultrasonic Pulse Velocity Tester Market
Test and Measurement
Sound Meter Market
Test and Measurement
LCR Meter Market
Test and Measurement
Advanced Probe Card and Wafer Probing Test Systems Market
Test and Measurement
Video Test Equipment Market
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
Global Bench Scale Market
Test and Measurement
Flow Meter Market
Test and Measurement
Thin Film Metrology Systems Market
Test and Measurement
Duct Integrity Tester (DIT) Market
Test and Measurement
Voltage Calibrator Market
Test and Measurement
Chiplet Integration and Die-to-Die Interconnect Test Solutions Market
Test and Measurement
Gauss Meter Market
Test and Measurement
IoT Testing Equipment Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Over-The-Air (OTA) Testing Market