
 North America Pressure Sensors Market | 2026-2036
North America Pressure Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pressure Sensors Market Foresight
AS9100 certification is rotating as the primary gating qualification for aerospace-grade pressure sensor suppliers across the region. Honeywell International Inc. leverages its vertically integrated MEMS fabrication to dominate military and commercial aviation contracts. Sensata Technologies Inc. anchors its position through specialized automotive pressure sensing for electric vehicle battery packs. TE Connectivity competes aggressively in industrial process automation with broad channel control across North American distributors.
Pressure sensors transduce fluid or gas pressure into electrical signals through piezoresistive, capacitive, or piezoelectric mechanisms, typically operating across ranges from fractions of a psi to tens of thousands of psi with accuracy tolerances down to 0.1% full scale. These devices serve critical functions in closed-loop control, safety interlock, and condition monitoring systems across industrial, transportation, and medical equipment. Differential pressure sensors lead volume in HVAC and process automation applications where flow measurement dominates, while wireless pressure sensing represents the fastest-expanding technology segment as Industrial Internet of Things deployments accelerate predictive maintenance programs. Piezoelectric variants command premium positioning in high-frequency dynamic pressure measurement for aerospace propulsion testing and automotive combustion analysis.
NHTSA mandates on tire pressure monitoring and EPA emissions testing protocols shape automotive sensor specifications and calibration traceability requirements. FDA Class II medical device regulations govern pressure sensor integration into infusion pumps and ventilators, while OSHA process safety management rules drive replacement cycles in hazardous chemical manufacturing. Stakeholders must monitor how NXP Semiconductors and Infineon Technologies AG advance integrated sensor-plus-ASIC architectures that could displace discrete component supply chains in cost-sensitive automotive and consumer medical applications.
Market Dynamics
Automotive electrification programs across Michigan and Ontario are compressing sensor calibration cycles and forcing suppliers to requalify production lines for AS9100 aerospace-grade specifications alongside AEC-Q200 automotive standards.
Growth Catalysts
- EPA emissions testing protocols:Mandates for real-time exhaust pressure monitoring in heavy-duty diesel applications expand sensor deployment across commercial vehicle fleets operating in the US Great Lakes corridor.
- MEMS fabrication advances:Piezoresistive micro-electromechanical systems achieve sub-0.1% full-scale accuracy at volume price points, penetrating HVAC differential pressure applications previously served by capacitive alternatives.
- Battery thermal management:Electric vehicle manufacturers in Detroit and Ohio require multi-point pressure sensing for coolant loop integrity, creating dedicated procurement channels for automotive-grade suppliers.
Market Restraints
- Silicon wafer supply concentration:MEMS die fabrication depends on 200mm and 300mm wafer supply chains concentrated in East Asian foundries, exposing North American sensor assemblers to geopolitical logistics disruptions.
- Calibration equipment capex:NIST-traceable pressure standards and automated test systems require capital outlays exceeding two million dollars per production line, consolidating manufacturing among scale players.
- Optical pressure sensing substitution:Fiber-optic pressure transducers eliminate electromagnetic interference vulnerabilities in MRI suites and high-voltage battery enclosures, capturing niche medical and automotive applications.
Strategic Opportunities
- Industrial IoT predictive maintenance:Wireless pressure sensing modules with edge computing capabilities enable continuous equipment monitoring, opening replacement cycles in Ohio chemical processing and Illinois food manufacturing plants.
- Canadian aerospace cluster:Montreal and Toronto defense contractors seek second-source pressure sensor qualification for F-35 and maritime patrol programs, creating entry points for AS9100-certified suppliers.
- OSHA process safety management:Mandatory replacement intervals for pressure instrumentation in hazardous chemical facilities accelerate recurring revenue streams for certified industrial sensor distributors.
Industry Challenges
- Cross-domain engineering talent:Sensor design requires simultaneous fluency in MEMS physics, analog signal conditioning, and embedded firmware, with qualified practitioners concentrated in Boston and Silicon Valley rather than Midwest manufacturing hubs.
- Dual-certification timelines:Simultaneous AEC-Q200 automotive and AS9100 aerospace qualification cycles extend product launch schedules by 18-24 months, compressing revenue realization windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pressure Sensors Market |
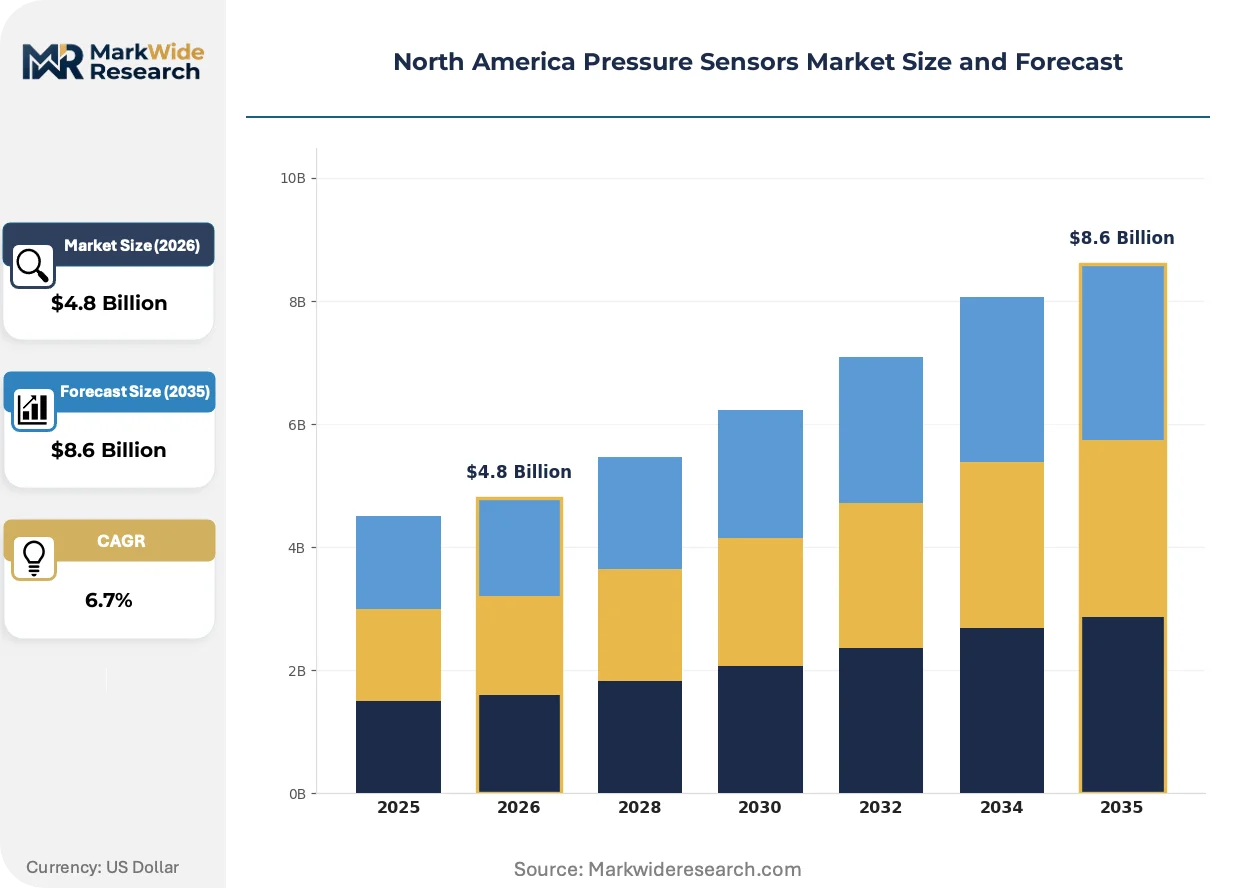
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute, Differential, Gauge, Sealed Technology: Analog, Digital, Wireless, Piezoelectric End User: Aerospace, Automotive, Healthcare, Manufacturing Application: Monitoring, Control, Safety, Process Automation |
| Companies Covered | Honeywell International Inc., ABB Ltd, Sensata Technologies Inc., TE Connectivity, Schneider Electric, Emerson Electric Co., Bosch Sensortec GmbH, Infineon Technologies AG, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pressure Sensors Market Shifts & Advancements
Sensor-plus-ASIC integration is collapsing discrete component supply chains while wireless architectures and predictive analytics platforms redefine how pressure data generates value beyond raw measurement.
Capacitive micromachined pressure sensors is supplanting traditional piezoresistive designs in automotive tire pressure monitoring systems. Tier-1 suppliers in Michigan and Ohio are converting module designs to capacitive architectures for improved temperature stability. This technology is supplanting incumbent suppliers lacking in-house MEMS fabrication capabilities, compressing margins for module assemblers dependent on external die sourcing.
NHTSA tire pressure monitoring mandates and EPA heavy-duty emissions protocols are tightening calibration traceability requirements across automotive sensor procurement. Suppliers must maintain NIST-traceable documentation through three tiers of subcomponent vendors. The commercial vehicle segment in Illinois and Ohio faces the steepest compliance burden, with fleet operators demanding serialized calibration certificates for each installed sensor.
Condition-based maintenance contracts are displacing traditional sensor replacement schedules in Great Lakes manufacturing facilities. Industrial distributors in Michigan now bundle wireless pressure sensors with cloud analytics subscriptions, unbundling hardware from service revenue. This shift concentrates procurement authority among plant reliability engineers rather than maintenance purchasing departments, altering vendor sales engagement protocols across the region.
North America Pressure Sensors Market Segmentation
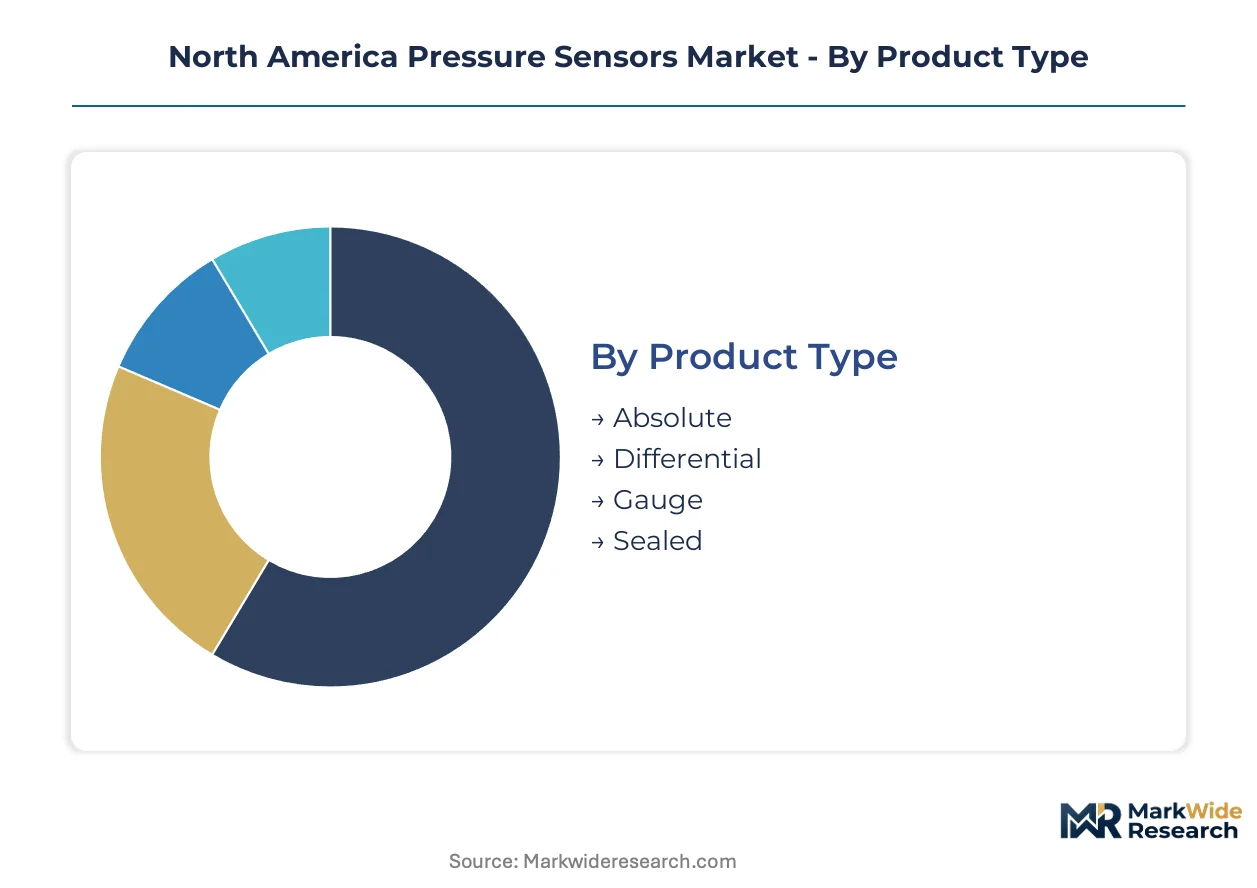
Pressure sensor procurement in North America fragments across distinct technical specifications and regulatory environments. Each segment channels through specialized distribution networks shaped by certification requirements and end-use criticality.
Product Type:
Industrial distributors in the Great Lakes corridor stock differential and gauge sensors most heavily, while absolute and sealed variants move through aerospace-certified channels.
- Differential:Measures pressure variance between two independent ports using piezoresistive MEMS diaphragms. HVAC contractors across Ohio and Illinois specify these for airflow measurement in commercial building automation, with EPA energy efficiency codes driving retrofit demand.
- Absolute:References sealed vacuum chamber for altitude and barometric applications. Aerospace suppliers in Montreal and Toronto qualify these for flight control systems under Transport Canada and FAA dual-certification protocols.
- Gauge:Ventilated to ambient atmosphere for tire pressure and industrial hydraulics. Automotive module assemblers in Michigan source these in highest volume for NHTSA-mandated TPMS deployment.
- Sealed:Hermetic construction prevents contamination in submersible and corrosive media. Chemical processors in Louisiana and Texas specify these for offshore platform instrumentation under OSHA process safety management.
By volume, gauge sensors lead. By growth pace, absolute pressure variants are climbing the fastest.
Technology:
Cost tiers separate mature analog architectures from premium wireless and piezoelectric implementations requiring specialized signal conditioning.
- Analog:Voltage or current-loop output dominates legacy industrial infrastructure. Food processing plants in Wisconsin and Minnesota maintain extensive installed bases of 4-20mA transmitters, though replacement cycles lengthen as wireless retrofits gain approval.
- Wireless:Integrated radio modules with edge preprocessing enable predictive maintenance deployments. Ohio chemical facilities and Illinois refineries pilot these for rotating equipment monitoring, bypassing wiring costs in hazardous area classifications.
- Digital:I2C and SPI interfaces suit embedded automotive and medical applications. EV battery pack manufacturers in Detroit specify digital protocols for coolant pressure telemetry to central battery management systems.
- Piezoelectric:Quartz or ceramic crystals measure dynamic pressure transients in combustion and propulsion testing. Aerospace ground test facilities in California and Florida command premium pricing for high-frequency response specifications.
By installed base, analog dominates. By expansion trajectory, wireless modules are gaining share fastest.
End User:
Customer type determines procurement authority, with automotive buyers consolidating volume and healthcare purchasers fragmenting across device OEMs.
- Automotive:Tier-1 module suppliers in Michigan and Ohio drive the largest procurement volumes. Electrification programs require multi-point pressure sensing for thermal management, brake systems, and fuel cell cathode pressure regulation.
- Manufacturing:Process industries across the US Great Lakes corridor represent the most fragmented demand base. Plant reliability engineers specify instrumentation for compressed air systems, hydraulic presses, and pneumatic conveying equipment.
- Aerospace:Defense contractors in Montreal and Toronto seek second-source qualification for F-35 and maritime patrol programs. AS9100 certification gates entry, compressing the qualified supplier base.
- Healthcare:Ventilator and infusion pump manufacturers in Massachusetts and Minnesota integrate pressure sensors under FDA Class II device regulations. Calibration traceability requirements extend through three tiers of subcomponent vendors.
By revenue concentration, automotive leads. By margin structure, healthcare commands premium positioning.
Application:
Maturity gradients separate established safety interlock applications from emerging predictive analytics deployments.
- Process Automation:Closed-loop control of valves, pumps, and compressors constitutes the largest installed application base. Petrochemical facilities on the US Gulf Coast and in Alberta deploy redundant pressure transmitters for critical loop control.
- Monitoring:Condition-based maintenance programs are displacing scheduled replacement. Great Lakes manufacturing plants now bundle wireless sensors with cloud analytics subscriptions, unbundling hardware from service revenue.
- Control:Real-time pressure regulation in engine management and HVAC systems requires sub-millisecond response times. Automotive engine control modules in Detroit integrate manifold absolute pressure sensors for fuel injection calibration.
- Safety:Interlock systems prevent equipment operation outside pressure limits. OSHA mandates drive replacement intervals for pressure instrumentation in hazardous chemical facilities, creating recurring revenue for certified distributors.
By deployment scale, process automation leads. By growth momentum, monitoring applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive electrification programs and aerospace defense procurement dominate buyer profiles across the region, with procurement authority consolidating among Tier-1 module suppliers and defense contractors seeking AS9100-certified second sources.
United States
EV battery pack manufacturers in Detroit and Ohio drive multi-point pressure sensing demand for thermal management systems. NHTSA tire pressure monitoring mandates and EPA heavy-duty emissions protocols tighten calibration traceability requirements. The Great Lakes manufacturing corridor spanning Michigan, Ohio, and Illinois anchors the highest sensor procurement volumes.
Canada
Defense contractors in Montreal and Toronto seek second-source qualification for F-35 and maritime patrol programs under Transport Canada oversight. Health Canada governs pressure sensor integration into medical devices through Class II device regulations. The Montreal aerospace cluster generates specialized demand for absolute pressure variants in flight control applications.
Mexico
Automotive assembly plants in Nuevo León and the Bajío Region import pressure sensors for engine management and brake systems serving US export markets. Mexican automotive manufacturing regulations align with USMCA technical standards. The Querétaro aerospace hub attracts sensor distributors seeking proximity to Bombardier and GE Aviation operations.
North America Pressure Sensors Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive MEMS fabrication capabilities. Consolidation pressure favors scale players capable of dual AEC-Q200 and AS9100 qualification cycles. Strategic archetypes include vertically integrated MEMS fabricators, automotive-focused module specialists, and broad-line industrial distributors. Competitive moves center on backward integration into wafer-level processing and strategic partnerships with EV battery manufacturers.
Within the diversified industrial tier, Honeywell International Inc. and Sensata Technologies Inc. occupy positions reflecting deep automotive and aerospace exposure. TE Connectivity exemplifies the channel-control archetype across North American industrial distribution. These three anchors demonstrate how qualification breadth and manufacturing scale separate sustainable competitors from module assemblers dependent on external die sourcing.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| ABB Ltd |
| Sensata Technologies Inc. |
| TE Connectivity |
| Schneider Electric |
| Emerson Electric Co. |
| Bosch Sensortec GmbH |
| Infineon Technologies AG |
| NXP Semiconductors |
| Others |
Supply & Pricing Matrix
Sixteen-week lead times for 200mm MEMS wafers concentrate pricing power among foundries in Taiwan and South Korea, forcing North American sensor assemblers to absorb cost volatility or surrender margin to secure allocation. Automotive OEMs in Michigan and Ohio leverage long-term offtake agreements to lock volume, while smaller industrial distributors face spot-market exposure on silicon die procurement.
Pricing Analysis
Cost-plus contracts with quarterly indexation to silicon wafer spot prices dominate procurement between Tier-1 automotive module suppliers and MEMS fabricators. Price differentiation separates AS9100 aerospace-certified sensors from AEC-Q200 automotive grades, with calibration documentation adding premium tiers. Pricing pressure stems from capacitive MEMS architectures displacing piezoresistive alternatives in tire pressure monitoring, compressing margins for module assemblers lacking in-house fabrication. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while healthcare device OEMs prioritize calibration traceability over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Michigan automotive module assemblers, though Ohio chemical processors maintain strategic stockpiles of sealed sensors for OSHA-mandated replacement cycles. Geographic supply concentration centers on Taiwan, South Korea, and Japan for MEMS die fabrication, with North American operations limited to back-end assembly and calibration. Raw material dependencies span silicon wafers, ceramic substrates, and epoxy packaging compounds. Single-source vulnerability in 300mm wafer supply creates tariff exposure risk. Distribution runs through authorized industrial distributors with NIST-traceable calibration capabilities serving the Great Lakes manufacturing corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment—specifically dual AEC-Q200 and AS9100 certification requirements—creates structural barriers that compound over time for qualified incumbents.
For Market Incumbents: Compound certification breadth into channel lock-in by securing second-source qualification with Canadian aerospace contractors in Montreal and Toronto. Invest in backward integration into wafer-level MEMS processing to defend against price erosion from integrated sensor-plus-ASIC architectures advanced by NXP Semiconductors and Infineon Technologies. Prioritize capacity addition in Ohio and Michigan to serve EV battery thermal management procurement channels. For New Entrants and Emerging Players: AS9100 certification fast-track through Transport Canada recognition agreements opens entry points into F-35 and maritime patrol second-source programs. Target wireless pressure sensing modules for Industrial IoT predictive maintenance in Ohio chemical facilities and Illinois food plants, where incumbent distributors lack edge-computing integration capabilities. Pursue direct sales engagement with plant reliability engineers rather than traditional maintenance purchasing departments. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because certification timelines and calibration infrastructure requirements extend competitive moats beyond typical technology cycles. Acquisition targets should display dual AEC-Q200 and AS9100 qualification with captive MEMS fabrication or exclusive foundry relationships. Watch for inflection when integrated sensor-plus-ASIC architectures from semiconductor suppliers achieve cost parity with discrete component supply chains in automotive applications.| Strategic Initiative | Industry Significance |
|---|---|
| AS9100 Certification Fast-Track | Opens aerospace second-source contracts with Transport Canada oversight in Montreal and Toronto. |
| Backward Integration into MEMS Fabrication | Captures margin from wafer processing and insulates against East Asian foundry concentration risk. |
| Wireless Sensor-Plus-Analytics Bundling | Shifts procurement authority to reliability engineers in Ohio chemical and Illinois food manufacturing. |
| Dual AEC-Q200 and AS9100 Qualification | Creates cross-domain pricing power across automotive electrification and defense aerospace procurement. |
| EV Battery Thermal Management Partnership | Locks multi-point pressure sensing volumes with Detroit and Ohio electric vehicle manufacturers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and technical standards documentation. Primary interviews engaged MEMS fabrication engineers, Tier-1 automotive procurement managers, aerospace certification specialists, and industrial distributor technical sales leads. Secondary sources included NHTSA rulemaking dockets, EPA emissions testing protocols, FDA Class II device guidance, and customs import records for pressure sensor components. Bottom-up demand modeling from end-use applications triangulates against top-down supply-side capacity assessments across North American assembly operations.
Segmentation dimensions modeled span product type, technology architecture, end-user industry, and application function across the projection horizon. The analytical framework incorporates vehicle electrification content per unit, HVAC retrofit cycles under EPA energy codes, and OSHA-mandated replacement intervals in hazardous chemical facilities. CAGRs derive from installed base growth, technology substitution rates, and regulatory compliance-driven replacement demand. Industry-specific forecast inputs include EV battery pack penetration curves and aerospace defense procurement schedules under Transport Canada and FAA oversight.
Underlying assumptions cover sustained automotive electrification investment in Michigan and Ontario, stable East Asian wafer supply availability, and continued NHTSA enforcement of tire pressure monitoring mandates, with deviation risk concentrated in geopolitical logistics disruptions and optical pressure sensing substitution in medical applications. Revision becomes warranted when integrated sensor-plus-ASIC cost structures cross thresholds that displace discrete component architectures in high-volume automotive applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia Pacific Industrial Sensors Market
Sensors and Controls
Inline Quality Control Sensors Market
Sensors and Controls
Surface Acoustic Wave Sensors Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
North America Nano Sensors Market
Sensors and Controls
Europe Pressure Sensors Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Atomic Clock Market
Sensors and Controls
Germany Non-Contact Infrared Thermometer Market
Sensors and Controls
Ambient Light Sensor Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
Gyroscope Market
Sensors and Controls
Water Cut Monitor Market
Sensors and Controls
MEMS Inertial Sensors Market