
 Europe Touch Sensor Market | 2026-2036
Europe Touch Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Touch Sensor Market Intelligence
Expanded semiconductor fabrication capacity in Germany and Ireland is rewriting the supply dynamics for touch sensor components across Europe. This localized production strengthens the market position of key suppliers. STMicroelectronics leverages its extensive European manufacturing footprint to serve automotive and industrial clients. Meanwhile, Infineon Technologies AG specializes in high-reliability sensors for demanding automotive applications, and NXP Semiconductors competes on integrated solutions for smart home devices.
A touch sensor is an electronic component that detects and registers physical touch or proximity, typically on a display screen or surface. These sensors operate by measuring changes in capacitance, resistance, or acoustic waves when an object interacts with the sensor's field. The primary function is to enable intuitive human-machine interaction in electronic devices. Capacitive technologies dominate the market due to their use in consumer electronics, while resistive sensors maintain a foothold in rugged industrial automation equipment where durability is paramount.
European market access for touch sensors is governed by stringent directives, including RoHS for hazardous substances and CE marking for product safety conformity. The EU's Medical Device Regulation (MDR) also imposes strict requirements on sensors used in healthcare instruments, shaping design and material choices. For component suppliers, navigating the evolving requirements of the EU AI Act for interactive systems will be a critical determinant of future market share.
Market Dynamics
The European touch sensor market's structure is being defined by the automotive industry's rapid integration of advanced human-machine interfaces. This trend is propelled by both consumer expectations for smartphone-like experiences and stringent safety regulations enforced by bodies like Germany's KBA.
Growth Catalysts
- Automotive Mandates:Regulations from authorities like Germany's KBA requiring advanced driver-assistance systems and interactive displays accelerate the integration of touch sensors into new vehicle models, concentrating demand within German manufacturing hubs.
- Industrial Automation:The push for Industry 4.0 across Europe's manufacturing base fuels demand for resistive touch sensors in ruggedized control panels and HMIs used on factory floors, especially in industrial centers.
- Consumer Electronics Proliferation:Widespread use of capacitive sensors in consumer devices establishes a large-scale production ecosystem, lowering component costs and encouraging adoption in adjacent European industrial and automotive sectors.
Market Restraints
- Component Dependencies:A structural reliance on semiconductor precursors and specific transparent conductive films sourced from outside Europe creates supply chain vulnerabilities and input cost volatility for the region's sensor manufacturers.
- Compliance Overhead:Navigating the complex requirements of the EU's RoHS directive and the Medical Device Regulation (MDR) adds significant cost and extends time-to-market for sensors targeting healthcare applications.
- Technical Durability Mismatches:The superior user experience of capacitive sensors often conflicts with the extreme durability and glove-use requirements of heavy industrial or outdoor applications, limiting deployment in these specialized niches.
Strategic Opportunities
- Medical Device Specialization:The EU's MDR, while a restraint, creates an opportunity for specialized, high-margin sensors in diagnostic equipment and patient monitoring systems where verified compliance becomes a competitive advantage.
- Haptic Feedback Integration:Converging touch sensors with advanced haptic feedback technology presents a significant opportunity in automotive dashboards and industrial controls, enhancing user safety and interaction quality through tactile confirmation.
- Eastern European Expansion:Underpenetrated markets in Eastern Europe, particularly within their growing automotive and consumer electronics assembly sectors, offer new geographic growth avenues for established European component suppliers.
Industry Challenges
- Legacy System Integration:Incorporating modern capacitive touch interfaces with older industrial machinery and control systems across European factories presents significant technical and software compatibility hurdles for system integrators.
- AI Act Ambiguity:The lack of final, clear technical standards for the forthcoming EU AI Act creates uncertainty for developers designing next-generation interactive systems, potentially delaying investment and product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Touch Sensor Market |
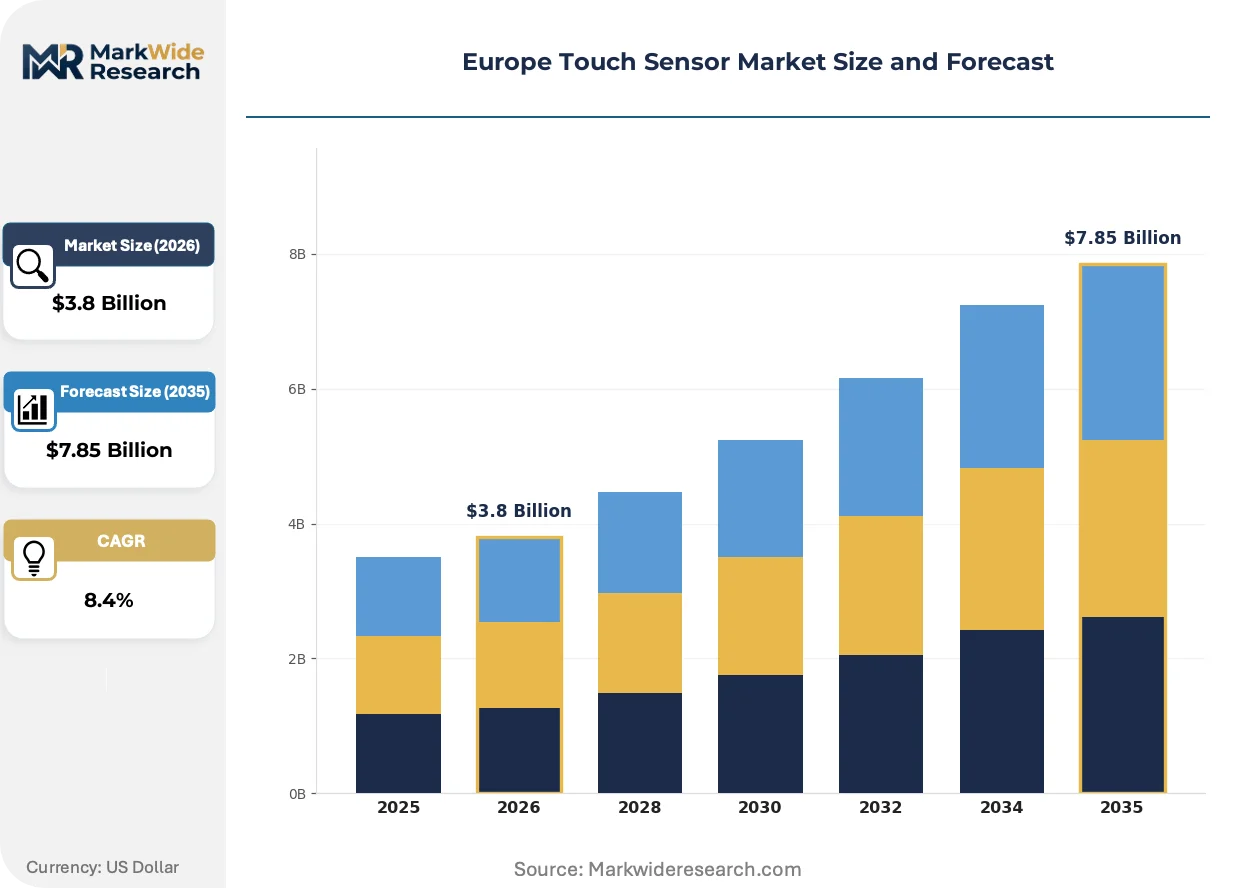
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capacitive, Resistive, Surface Acoustic Wave, Infrared, Optical, Dispersive Signal Technology Technology: Projected Capacitive, Surface Capacitive, Mutual Capacitance, Self Capacitance, Optical Imaging, Force Sensing Application: Consumer Electronics, Gaming Devices, Industrial Automation Equipment, Medical Instruments, Automotive Control Panels, Smart Home Devices End User: Smartphone Manufacturers, Arcade Operators, Factory Automation Firms, Healthcare Providers, Vehicle Interface Suppliers, Home Automation Installers |
| Companies Covered | Infineon Technologies AG, STMicroelectronics, NXP Semiconductors, Texas Instruments, Synaptics Incorporated, Renesas Electronics Corporation, Silicon Laboratories, Zytronic PLC, Microchip Technology, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Touch Sensor Market Strategic Shifts & Innovations
The evolution of touch sensors in Europe is shifting from simple surface interaction towards integrated systems that blend tactile feedback, proximity sensing, and embedded intelligence. This transformation is driven by demands for more intuitive and safer human-machine interfaces across all major end-use sectors.
In-cell and on-cell touch technologies integrate the sensor directly into the display stack, reducing device thickness and improving optical clarity. Automotive and consumer electronics manufacturers are rapidly adopting these solutions to create sleeker profiles for vehicle cockpits and smart devices. The market is migrating from discrete sensor overlays to fully integrated display modules, which compresses the value chain.
Legislation such as the EU AI Act introduces risk-based classifications for artificial intelligence systems, including those using sensor data for interaction. This regulation forces manufacturers to document data provenance and ensure algorithmic transparency for HMIs in critical applications. Automotive and medical device sectors are most affected, now re-evaluating their HMI design philosophies to ensure compliance.
A shift towards custom-shaped and non-rectangular touch surfaces is gaining momentum in automotive interiors and high-end home appliances. Original equipment manufacturers are moving away from standardized rectangular screens to differentiate their products with unique, aesthetically integrated control surfaces. This design trend is most visible within the German premium automotive segment and Italian appliance manufacturing.
Europe Touch Sensor Market Segmentation
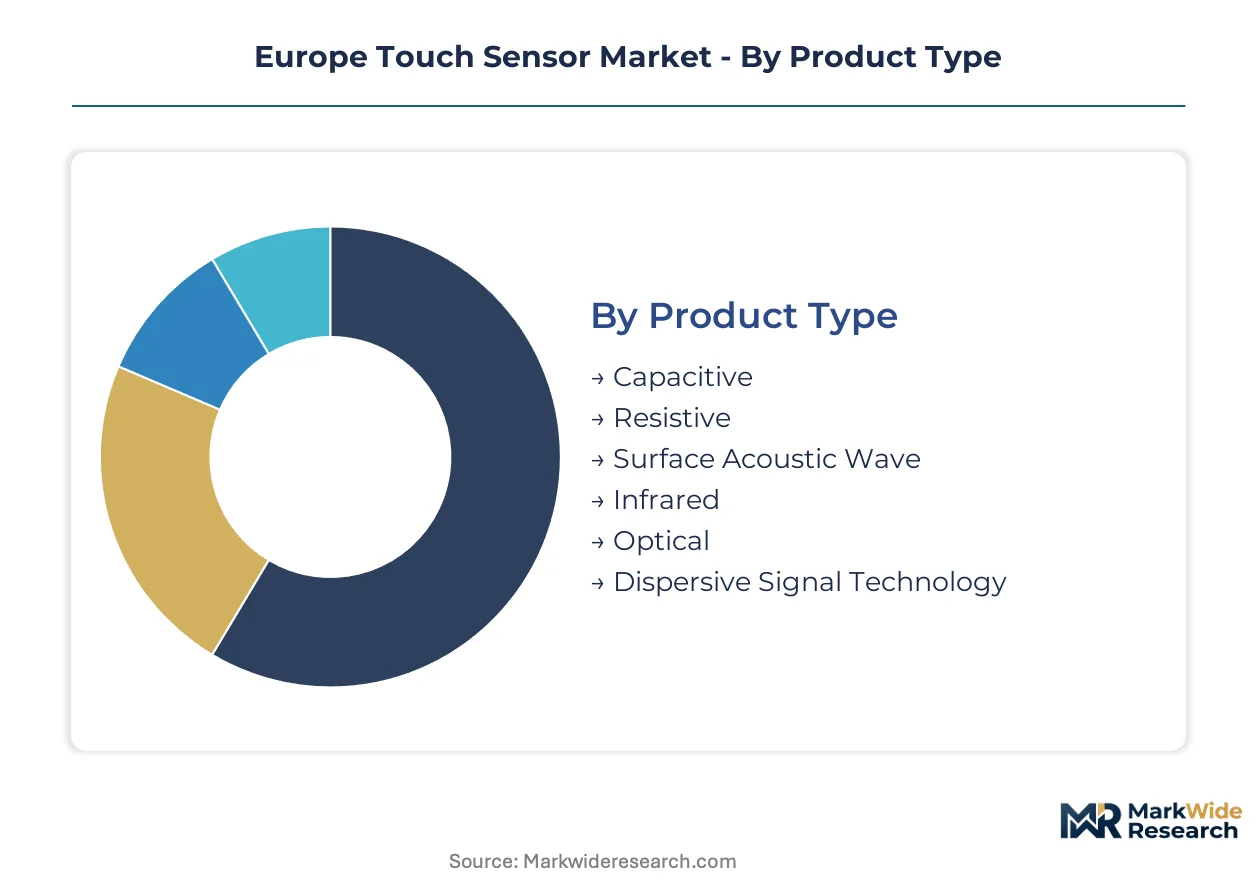
The Europe touch sensor market segmentation provides a granular view of product types, technologies, applications, and end-users, highlighting distinct demand patterns and compliance requirements. Understanding these segments is critical for manufacturers to tailor their offerings and navigate the region's diverse regulatory landscape effectively.
Product Type:
Touch sensor product types dictate the complexity and cost of after-sales service, impacting long-term operational expenditures for European end-users.
- Capacitive:Capacitive sensors detect touch by measuring changes in an electrical field, offering multi-touch capabilities and high responsiveness. Demand concentrates in European consumer electronics and automotive human-machine interfaces due to user preference for intuitive interactions.
- Resistive:Resistive sensors operate by detecting pressure on two conductive layers, providing durability and glove compatibility. Demand focuses on industrial automation equipment across Germany and Italy, where ruggedness is critical for factory floor operations.
- Surface Acoustic Wave:These sensors use ultrasonic waves across a glass panel, finding niche use in public kiosks and large displays within European retail environments.
- Infrared:Infrared sensors detect touch by interrupting an array of light beams, suitable for outdoor displays and large-format interactive signage in public spaces.
- Optical:Optical sensors utilize cameras or light-emitting diodes to detect touch, often employed in large-format interactive whiteboards and specialized design studios.
- Dispersive Signal Technology:This technology detects mechanical vibrations from touch, enabling robust interaction on various surfaces without a dedicated overlay, preferred for specialized industrial applications.
Capacitive holds the largest share; momentum sits with Dispersive Signal Technology.
Technology:
The underlying technology significantly influences the manufacturing cost and integration complexity for touch sensors, affecting their adoption across diverse European industries.
- Projected Capacitive:Projected capacitive technology uses a grid of electrodes to create a multi-touch interface, enabling precise and responsive interaction. Demand is concentrated in premium automotive cockpits and high-end smart home devices across Western Europe, driven by advanced user experience requirements.
- Mutual Capacitance:Mutual capacitance measures the change in capacitance between transmitting and receiving electrodes when a finger approaches. This technology is gaining traction in medical instruments and industrial control panels in Germany and France due to its noise immunity and high accuracy.
- Surface Capacitive:Surface capacitive sensors provide single-touch detection, commonly used in simpler human-machine interfaces and kiosks.
- Self Capacitance:Self capacitance measures the capacitance of individual electrodes to ground, often integrated into smaller, cost-sensitive consumer gadgets.
- Optical Imaging:Optical imaging relies on cameras to detect touch points, primarily utilized in large interactive displays and specialized design tables.
- Force Sensing:Force sensing technology measures pressure applied to a surface, offering tactile feedback and enabling new interaction paradigms in automotive and industrial applications.
Projected Capacitive technology dominates the market, while Force Sensing is expanding most quickly.
Application:
Application segments dictate the volume and specific performance requirements for touch sensors, influencing design choices and material specifications for European manufacturers.
- Automotive Control Panels:Touch sensors in automotive control panels provide intuitive interaction for infotainment, navigation, and climate systems. Demand is heavily concentrated in German automotive manufacturing clusters due to stringent safety regulations and consumer expectations for advanced human-machine interfaces.
- Medical Instruments:Touch sensors for medical instruments require high reliability, chemical resistance, and precise input for diagnostic and patient monitoring devices. The EU's Medical Device Regulation drives demand for specialized, compliant sensors in healthcare facilities across Europe.
- Consumer Electronics:This segment includes smartphones, tablets, and wearables, primarily utilizing capacitive sensors for everyday interaction.
- Industrial Automation Equipment:Rugged resistive sensors are crucial for control panels and human-machine interfaces in factories, enabling reliable operation in harsh European industrial environments.
- Smart Home Devices:Touch sensors integrate into thermostats, lighting controls, and security panels, enhancing user experience in connected European homes.
- Gaming Devices:Touch interfaces in gaming consoles and accessories offer immersive interaction, catering to a broad European entertainment market.
Automotive Control Panels represent a significant volume segment, with Medical Instruments offering the highest margin potential.
End User:
End-user categories define the specific procurement channels and integration expertise required for touch sensor suppliers operating within the European market.
- Vehicle Interface Suppliers:These suppliers integrate touch sensors into complete human-machine interface modules for automotive original equipment manufacturers, requiring deep expertise in automotive-grade components and compliance. Demand is driven by the German automotive industry's push for advanced cockpit designs and connectivity features.
- Healthcare Providers:Healthcare providers procure touch-enabled medical devices, emphasizing reliability, regulatory compliance (MDR), and ease of sterilization. Hospitals and clinics across Western Europe are key buyers, seeking advanced diagnostic and patient care solutions.
- Smartphone Manufacturers:These companies integrate high-volume capacitive touchscreens into mobile devices for the mass consumer market.
- Factory Automation Firms:Firms specializing in industrial automation implement rugged touch panels for machinery control and monitoring across European manufacturing facilities.
- Home Automation Installers:Installers integrate touch interfaces into smart home systems, focusing on user-friendly and aesthetically pleasing designs.
- Arcade Operators:Arcade operators use durable touch screens for interactive gaming machines, prioritizing robust performance in public use settings.
Vehicle Interface Suppliers represent the most consolidated end-user segment, while Healthcare Providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Expanded semiconductor fabrication capacity in Germany and Ireland is rewriting the supply dynamics for touch sensor components across Europe. This localized production strengthens the market position of key suppliers within the region. Consequently, the European market for touch sensors benefits from a robust domestic supply chain, reducing reliance on external sources for critical components.
Germany
German automotive manufacturing clusters drive demand for advanced touch sensors in vehicle human-machine interfaces. Regulations from authorities like Germany's KBA mandate enhanced safety and driver interaction features in new vehicle models. The Stuttgart region, a prominent automotive hub, sees significant integration of these interactive displays into premium vehicles.
France
French medical instrument manufacturers require highly reliable touch sensors for diagnostic equipment and patient monitoring systems. The EU's Medical Device Regulation (MDR) imposes strict requirements on sensor design and material choices for healthcare applications. The Grenoble region, a hub for microelectronics, focuses on developing specialized, compliant sensors for the medical sector.
Italy
Italian industrial automation firms utilize rugged resistive touch sensors for factory floor control panels and human-machine interfaces. Compliance with CE marking for product safety conformity is essential for market access across Europe. Manufacturing hubs in Lombardy and Emilia-Romagna integrate custom-shaped touch surfaces into premium appliances and industrial machinery.
United Kingdom
UK consumer electronics and smart home device sectors create demand for advanced capacitive touch interfaces. Products sold within the EU must adhere to directives like RoHS for hazardous substances. The Cambridge tech cluster innovates in integrated touch solutions for both consumer and niche industrial applications, enhancing user experience.
Ireland
Ireland's robust medical device industry requires specialized touch sensors for advanced healthcare instruments. Strict adherence to the EU Medical Device Regulation (MDR) is paramount for market entry and product validation. The Cork region, a prominent medtech cluster, drives innovation in high-reliability, compliant sensor components for global distribution.
Europe Touch Sensor Market Key Industry Players
Integrated semiconductor manufacturers and specialized sensor component providers split the European touch sensor market. The market features a blend of large-scale component suppliers and niche innovators, each targeting specific application areas. These players pursue capacity expansion to meet growing automotive demand and diversify portfolios into medical and industrial sectors. Strategic partnerships with automotive original equipment manufacturers and industrial integrators are crucial for market penetration.
Large-scale semiconductor firms like Infineon Technologies AG, a German-based company, exemplify suppliers specializing in high-reliability sensors for demanding automotive applications. STMicroelectronics, a Swiss-based semiconductor manufacturer, leverages its extensive European manufacturing footprint to serve both automotive and industrial clients. NXP Semiconductors, a Netherlands-based company, occupies a position focused on integrated solutions for smart home devices and broader automotive human-machine interface systems, representing a diversified approach to market segments.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| STMicroelectronics |
| NXP Semiconductors |
| Texas Instruments |
| Synaptics Incorporated |
| Renesas Electronics Corporation |
| Silicon Laboratories |
| Zytronic PLC |
| Microchip Technology |
| Others |
Cost & Logistics Intelligence
Expanded semiconductor fabrication capacity in Germany and Ireland drives supplier behavior, strengthening market positions and reducing reliance on external sources. This localized production capacity influences pricing strategies by providing a more stable cost base for European manufacturers.
Pricing Analysis
The EU's Medical Device Regulation (MDR) dictates the pricing tier structure for specialized sensors, enabling contract-based long-term offtake agreements. Price differentiation stems from certification levels, customization requirements for automotive clients, and comprehensive after-sales service bundles. Pricing softness runs through the consumer electronics segment due to volume-driven competition. Consumer electronics manufacturers remain highly price-sensitive, while medical device and automotive OEMs prioritize compliance and reliability over cost.
Supply Chain Analysis
Semiconductor precursors and specific transparent conductive films sourced from outside Europe create upstream dependencies for touch sensor manufacturers. Geographic supply concentration for these critical inputs lies primarily in Asia. This structural reliance introduces single-source vulnerability and input cost volatility. Distribution runs through direct sales channels to large automotive OEMs and medical device firms, alongside specialized industrial integrators for factory automation equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a service-attach opportunity, with compliant sensor data services for interactive systems expanding faster than core hardware sales.
For Market Incumbents: Harden existing automotive client relationships through co-development of EU AI Act compliant HMIs. Invest in localized production capacity within Germany to mitigate supply chain risks and leverage regional incentives. Focus R&D on advanced haptic feedback integration to differentiate premium offerings. This strategy defends against potential market share erosion from new entrants with specialized compliance expertise.
For New Entrants and Emerging Players: Pursue niche applications within the medical instruments segment, leveraging the stringent MDR requirements as a barrier to entry for generalists. Target underpenetrated markets in Eastern Europe, particularly their growing automotive assembly sectors. A go-to-market angle focusing on specialized compliance expertise and tailored, high-reliability solutions offers a clear path to market penetration.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across advanced HMI development and compliant medical sensor manufacturing, signaling long-term viability. Focus acquisition profiles on specialized component providers with proven EU AI Act compliance capabilities or firms pioneering haptic technology integration. The adoption rates of integrated display modules in new premium vehicle models serve as a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand localized semiconductor fabrication | Reduces reliance on external supply, stabilizing component costs for European manufacturers. |
| Invest in EU AI Act compliance platforms | Ensures future market access for interactive systems, particularly in automotive and medical sectors. |
| Acquire specialized haptic technology firm | Enhances user experience in automotive dashboards and industrial controls, creating product differentiation. |
| Target Eastern European automotive assembly | Leverages growing manufacturing hubs for new geographic growth avenues for component suppliers. |
| Develop high-reliability medical sensors | Addresses stringent EU MDR requirements, capturing high-margin opportunities in healthcare facilities. |
Research Approach
A spread of perspectives from automotive OEMs, medical device manufacturers, semiconductor executives, and industrial integrators converged on the working assumptions for this analysis. This approach combined insights from primary interviews with secondary validation from sources like KBA regulations, EU MDR guidelines, and industry association publications, ensuring bottom-up and top-down triangulation.
Demand-supply-balance models underpinned the analytical framework, projecting market evolution across the analysis window. The study meticulously segmented the market by product type, technology, application, end-user, and geographic region. Compound annual growth rates were derived from historical data and projected growth drivers, with vehicle production forecasts and industrial automation investment trends serving as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in semiconductor supply or energy costs would shift the trajectory of the market. Forecasts reflect assumptions documented through extensive research. Cross-checking against Eurostat industrial production indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
HVAC Sensor Market
Sensors and Controls
Turbomachinery Control Systems Market
Sensors and Controls
Europe MEMS and Sensors Market
Sensors and Controls
Digital Radiography Sensor Market
Sensors and Controls
Instrumented Load Shackle Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Aeroderivative Sensor Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
Phototransistor Market
Sensors and Controls
Inertial Sensing Products Market
Sensors and Controls
MEMS Accelerometer and Gyroscope Market
Sensors and Controls
Electronics Control Management Market
Sensors and Controls
Air Quality Monitoring System Market
Sensors and Controls
Pressure Transmitter and Transducer Market
Sensors and Controls
60GHz Radar Evaluation Kit Market