
 China Digital Thermometer Market | 2026-2036
China Digital Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
China Digital Thermometer Market Insights
E-commerce channel control is fragmenting across the China digital thermometer landscape. Guangzhou Berrcom Medical Device Co., Ltd. leverages its Pearl River Delta manufacturing base to dominate infrared production volumes. Hangzhou Sejoy Electronics & Instruments Co., Ltd. sustains probe-sensor R&D intensity for hospital-grade contracts. Shenzhen Brav Electronic Technologies Co., Ltd. competes through aggressive pricing in consumer Bluetooth segments on domestic platforms.
A digital thermometer converts temperature into electronic signals via thermistors or infrared sensors, displaying readings on LCD or LED screens with typical accuracy of ±0.1°C for clinical models. The device serves primary purposes in fever monitoring, industrial process control, and veterinary diagnostics across Chinese commercial and residential settings. Infrared thermometers lead volume shipments due to post-pandemic hygiene preferences in healthcare institutions and transport hubs. Smart thermometers with Wi-Fi connectivity represent the fastest-expanding technology tier as consumers integrate health data with mobile applications. Home use applications anchor the mass-market revenue pool while hospital and laboratory end users command premium pricing for calibrated precision units.
NMPA medical device registration rules mandate clinical accuracy validation for hospital-bound thermometer models, filtering lower-grade manufacturers from institutional procurement channels. GB national standards and MIIT electronics certifications shape product specifications for electromagnetic compatibility and wireless transmission protocols in connected devices. Stakeholders must monitor evolving SAMR quality enforcement actions and provincial hospital procurement centralization trends to anticipate margin compression or access barriers.
Market Dynamics
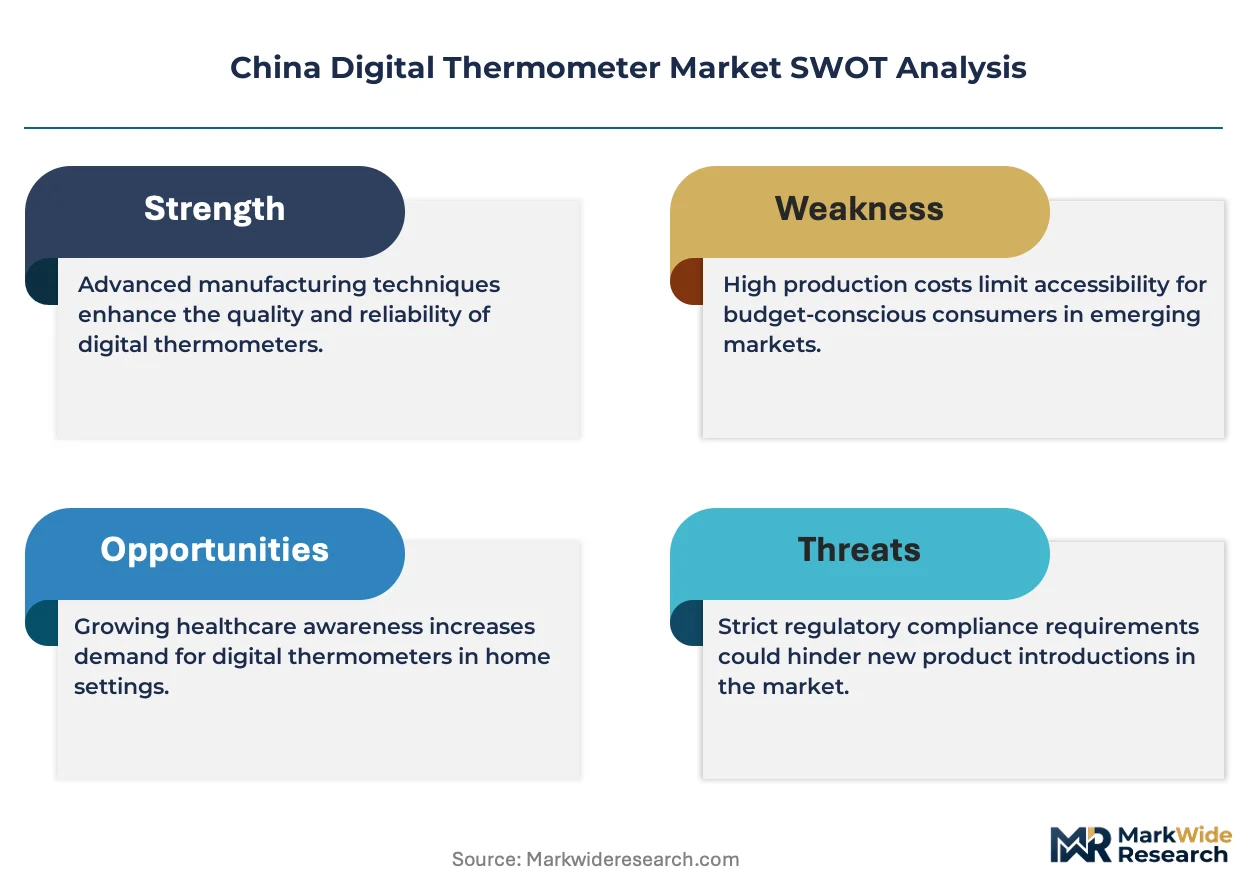
NMPA medical device classification tightening is compressing margins for uncertified manufacturers while concentrating procurement authority in provincial hospital consortiums across Jiangsu and Zhejiang.
Growth Catalysts
- Home healthcare infrastructure:Post-pandemic hygiene protocols sustain infrared thermometer demand in Chinese residential settings and primary care clinics.
- MIIT wireless certification:GB standards for electromagnetic compatibility accelerate Bluetooth-enabled smart thermometer deployment on domestic e-commerce platforms.
- Jiangsu-Zhejiang manufacturing clusters:Component supplier density in the Yangtze River Delta reduces sensor assembly lead times for clinical-grade units.
Market Restraints
- MEMS thermistor supply concentration:Domestic infrared sensor production depends on imported semiconductor substrates subject to export control volatility.
- NMPA registration timelines:Clinical accuracy validation protocols extend product launch cycles by eight to fourteen months for hospital-bound models.
- Mercury thermometer substitution:WHO phase-out mandates for mercury devices create price ceiling pressure on budget digital alternatives in rural clinics.
Strategic Opportunities
- Sichuan-Chongqing corridor:Western province healthcare infrastructure investment lags coastal saturation, opening distribution partnerships for mid-tier probe thermometers.
- Telemedicine integration:Wi-Fi connectivity convergence with hospital information systems creates recurring revenue streams through firmware subscription models.
- SAMR quality enforcement:Centralized procurement centralization favors manufacturers with established NMPA Class II certificates in institutional tenders.
Industry Challenges
- Calibration technician scarcity:Clinical-grade thermometer maintenance requires ISO 17025-certified personnel concentrated in tier-one cities.
- Legacy system integration:Hospital ERP compatibility with Bluetooth Low Energy protocols demands custom API development for each provincial health network.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Digital Thermometer Market |
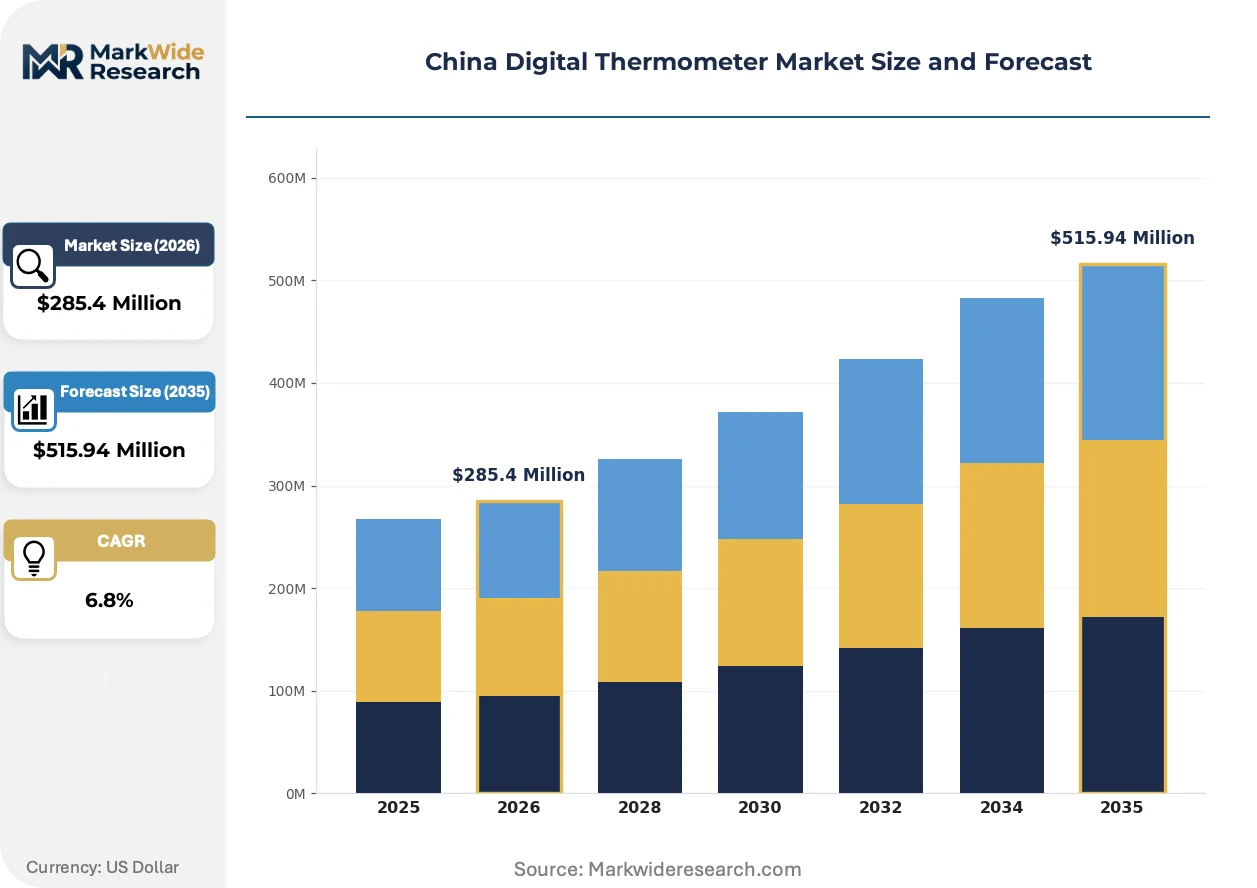
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Thermometers, Infrared Thermometers, Bluetooth Thermometers, Smart Thermometers Application: Home Use, Healthcare Institutions, Veterinary Use, Industrial Use Technology: Digital Display, Probe Sensors, Contactless, Wi-Fi Enabled End User: Consumers, Hospitals, Clinics, Laboratories |
| Companies Covered | Guangzhou Berrcom Medical Device Co., Ltd., Hangzhou Hua’an Medical & Health Instruments Co., Ltd., Microlife Corporation, Radiant Innovation Inc., Shenzhen Brav Electronic Technologies Co., Ltd., Guangzhou JinXinBao Electronic Co., Ltd., Easywell Bio, Shenzhen Dongdixin Technology Co., Ltd., Hangzhou Sejoy Electronics & Instruments Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Digital Thermometer Market Trends and Innovations
Sensor miniaturization and wireless protocol standardization are redrawing competitive boundaries between component suppliers and finished-device manufacturers in China's thermometer value chain.
Thermopile array sensors with integrated ASIC signal processing are rendering obsolete single-point infrared detectors in non-contact clinical thermometers. Tertiary hospital fever clinics in Beijing and Shanghai are adopting multi-pixel thermal imaging for mass screening workflows. The technology shift is compressing average selling prices for legacy infrared guns while elevating specification requirements for new tenders.
NMPA medical device registration rules now mandate electromagnetic compatibility testing under GB 9706 standards for all wireless-connected thermometers. Manufacturers must submit radio frequency emission documentation alongside clinical accuracy trials. The regulation most affects Shenzhen-based producers of consumer Bluetooth segments, forcing redesign cycles for products previously certified only for domestic MIIT compliance.
Centralized provincial procurement platforms are consolidating hospital thermometer purchasing authority away from individual facility buyers. Jiangsu province's medical consumables consortium now negotiates annual frame contracts covering probe-sensor calibration services. The behavioral shift is visible in Zhejiang, where municipal health bureaus aggregate demand across county-level hospitals to extract volume discounts from NMPA-certified suppliers.
China Digital Thermometer Market Segmentation
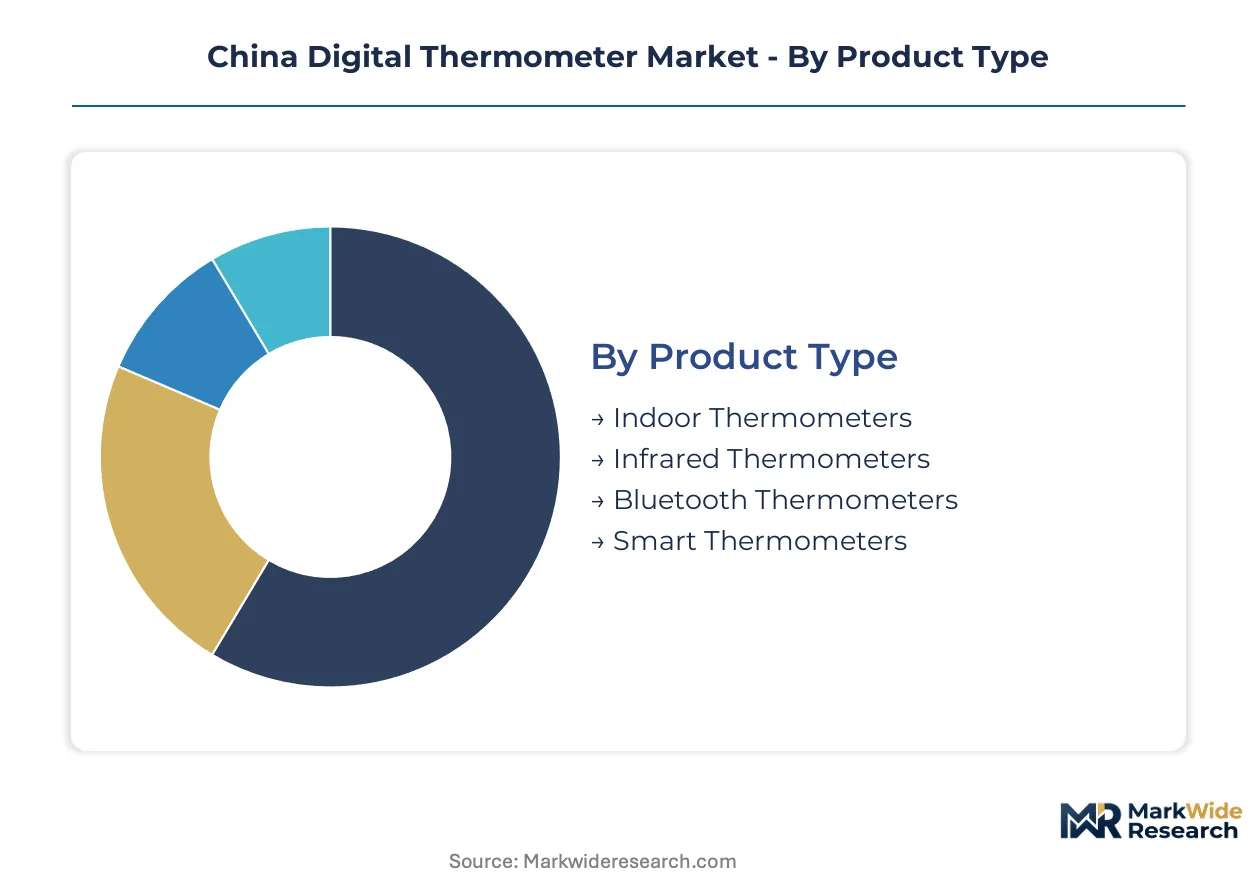
Product differentiation in China's digital thermometer market follows distinct replacement cycles and certification tiers. Segment boundaries blur as infrared and smart technologies converge in hospital procurement frameworks.
Product Type:
Infrared thermometers turn inventory fastest through transport hub and retail channel demand, while smart thermometers face longer NMPA validation timelines that stretch working capital cycles.
- Infrared Thermometers:Non-contact thermopile sensors measure surface temperature without patient contact, enabling rapid throughput in fever screening stations. Jiangsu province hospital consortiums specify multi-pixel arrays for mass triage workflows. Post-pandemic hygiene protocols sustain institutional procurement despite price compression from legacy single-point detector oversupply.
- Smart Thermometers:Wi-Fi connectivity integrates temperature logs with hospital information systems and consumer health applications. MIIT wireless certification under GB standards delays launch timelines for Shenzhen-based manufacturers previously compliant only with domestic protocols. Firmware subscription models are emerging as secondary revenue streams in tertiary hospital pilots.
- Bluetooth Thermometers:Low-energy protocols enable smartphone pairing for home health monitoring. Domestic e-commerce platforms favor these units for consumer segment penetration.
- Indoor Thermometers:Ambient temperature tracking for climate control applications. Commercial building automation systems drive steady replacement demand in Zhejiang manufacturing zones.
Infrared thermometers anchor the volume base while smart thermometers gain share at the steepest rate.
Application:
Cost tier stratification separates calibrated clinical units from consumer-grade alternatives, with veterinary and industrial applications occupying intermediate price bands.
- Home Use:Mass-market penetration concentrates in first-tier cities where dual-income households prioritize convenience. E-commerce platforms fragment price competition across probe and infrared formats.
- Healthcare Institutions:NMPA Class II certification mandates clinical accuracy validation for hospital-bound models. Provincial procurement centralization in Jiangsu and Zhejiang filters uncertified suppliers from institutional tenders.
- Veterinary Use:Livestock monitoring applications in Sichuan-Chongqing corridor drive demand for ruggedized probe sensors. Agricultural cooperatives specify waterproofing and extended temperature ranges.
- Industrial Use:Process control applications in Yangtze River Delta manufacturing clusters require calibrated precision for quality assurance protocols.
Home use applications generate the highest unit volumes while healthcare institutions command premium pricing tiers.
Technology:
Volume concentration favors mature digital display and probe sensor platforms, with contactless and Wi-Fi formats expanding fastest through technology substitution.
- Contactless:Thermopile arrays with integrated ASIC signal processing displace single-point infrared detectors in clinical settings. Beijing and Shanghai fever clinics adopt multi-pixel thermal imaging for mass screening workflows.
- Wi-Fi Enabled:Continuous data transmission to hospital information systems enables remote patient monitoring. SAMR quality enforcement actions under GB 9706 electromagnetic compatibility standards force redesign cycles for previously MIIT-only certified products.
- Probe Sensors:Thermistor-based contact measurement maintains accuracy leadership in laboratory calibration workflows. Hangzhou manufacturing clusters sustain component supplier density for clinical-grade assembly.
- Digital Display:LCD and LED screen formats dominate budget consumer segments. Price ceilings from mercury thermometer substitution mandates constrain margin expansion in rural clinic channels.
Probe sensors and digital displays retain installed base dominance while contactless and Wi-Fi formats climb the fastest through technology refresh cycles.
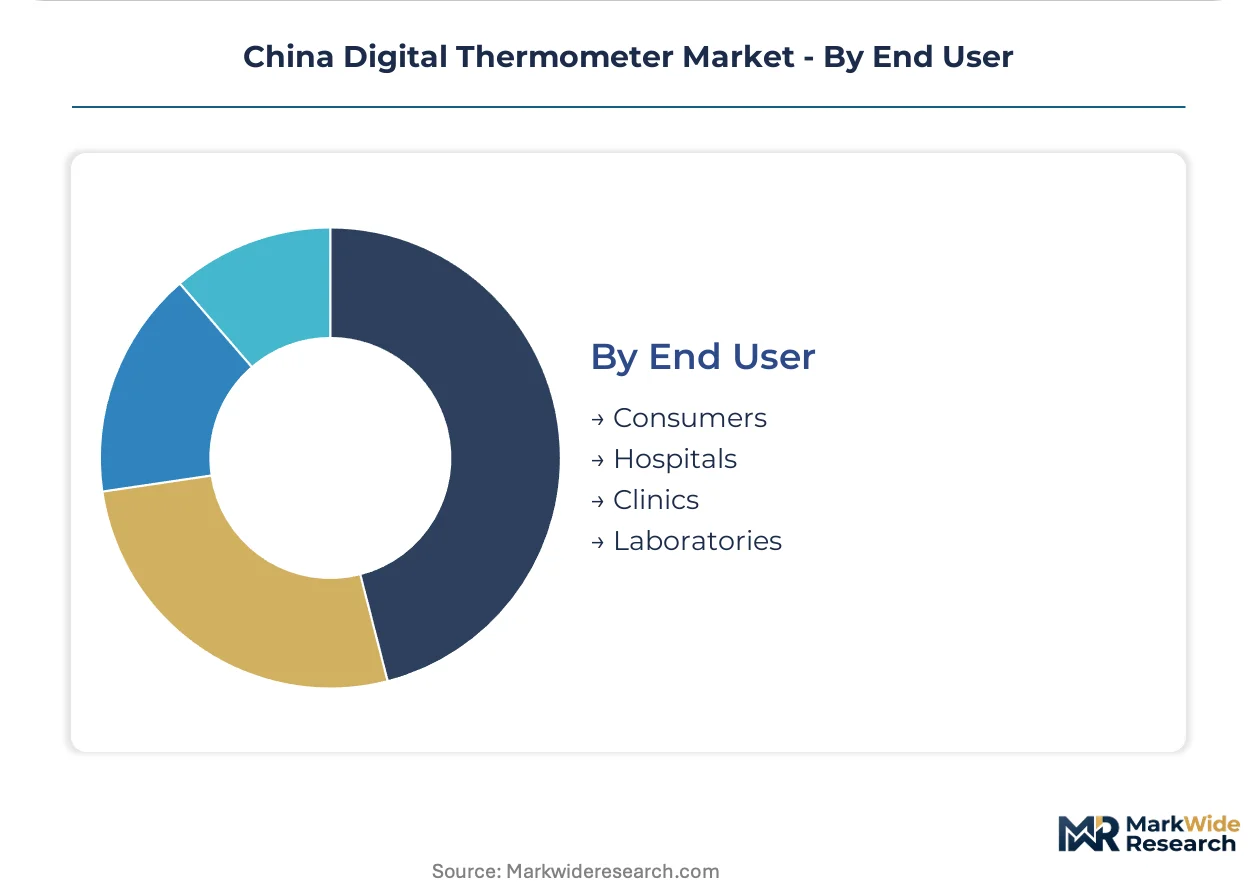
End User:
Customer type segmentation maps directly to certification tier requirements, with hospitals and laboratories demanding ISO 17025 traceability that consumer channels bypass.
- Hospitals:Tertiary institutions in Beijing, Shanghai, and Guangzhou specify NMPA Class II certificates with electromagnetic compatibility documentation. Centralized provincial procurement platforms aggregate demand across county-level facilities to extract volume discounts.
- Laboratories:ISO 17025 calibration requirements concentrate maintenance technician demand in tier-one cities. Precision units command sustained premium pricing through traceability mandates.
- Clinics:Primary care facilities balance accuracy requirements against budget constraints. County-level health bureaus participate in municipal procurement aggregation in Zhejiang province.
- Consumers:E-commerce channel fragmentation enables aggressive pricing from Pearl River Delta manufacturers. Bluetooth-enabled segments compete on domestic platform visibility rather than clinical certification depth.
Consumer channels move the highest unit volumes while hospital and laboratory segments sustain margin concentration through certification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Beijing-Shanghai high-speed rail corridor underwrites distribution velocity for temperature monitoring equipment moving between northern manufacturing bases and eastern consumption centers. Provincial health infrastructure investments diverge sharply across coastal saturation and western expansion zones. NMPA regulatory harmonization attempts to standardize device certification nationwide despite execution variance at provincial SAMR offices.
Jiangsu Province
Hospital procurement centralization concentrates thermometer demand through the provincial medical consumables consortium. SAMR quality enforcement actions filter uncertified suppliers from institutional tenders. Suzhou and Nanjing manufacturing clusters sustain component supplier density for clinical-grade probe-sensor assembly.
Zhejiang Province
Municipal health bureaus aggregate county-level hospital demand to extract volume discounts from NMPA-certified manufacturers. Hangzhou anchors probe-sensor R&D intensity for hospital-grade contracts. The Ningbo port facilitates infrared component importation despite semiconductor substrate supply volatility.
Guangdong Province
Pearl River Delta manufacturing bases dominate infrared production volumes through integrated thermopile sensor assembly. Shenzhen MIIT wireless certification requirements shape Bluetooth-enabled product design cycles. Guangzhou Berrcom Medical Device Co., Ltd. exemplifies the region's scale-driven fabrication archetype.
Sichuan-Chongqing Corridor
Western province healthcare infrastructure investment lags coastal saturation, opening distribution partnerships for mid-tier probe thermometers. Agricultural cooperatives drive veterinary thermometer specification for livestock monitoring applications. Chengdu's growing medical device sector attracts component suppliers seeking labor cost arbitrage.
Beijing-Tianjin-Hebei
Tertiary hospital fever clinics in Beijing specify multi-pixel thermal imaging arrays for mass screening workflows. NMPA headquarters proximity accelerates regulatory consultation for novel connected device submissions. Tianjin port logistics support northern distribution networks for calibrated precision units.
China Digital Thermometer Market Competitive Landscape
On the supply side, the industry is consolidating around NMPA-certified manufacturers capable of navigating extended clinical validation timelines. Uncertified producers face margin compression from provincial procurement centralization. Three archetypes dominate: Pearl River Delta scale fabricators, Yangtze River Delta R&D specialists, and Shenzhen-based connectivity innovators. Competitive moves concentrate on backward integration into sensor component production and firmware subscription model development for hospital information system integration.
Among Yangtze River Delta specialists, Hangzhou Sejoy Electronics & Instruments Co., Ltd. and Hangzhou Hua'an Medical & Health Instruments Co., Ltd. occupy positions emphasizing probe-sensor precision for institutional contracts. Guangzhou Berrcom Medical Device Co., Ltd. anchors the Pearl River Delta fabrication tier through volume-oriented infrared production. Shenzhen Brav Electronic Technologies Co., Ltd. exemplifies the connectivity-focused archetype competing in consumer Bluetooth segments. These three company structures illustrate the geographic stratification of competitive positioning across China's thermometer value chain.
| Leading Market Players |
|---|
| Guangzhou Berrcom Medical Device Co., Ltd. |
| Hangzhou Hua'an Medical & Health Instruments Co., Ltd. |
| Microlife Corporation |
| Radiant Innovation Inc. |
| Shenzhen Brav Electronic Technologies Co., Ltd. |
| Guangzhou JinXinBao Electronic Co., Ltd. |
| Easywell Bio |
| Shenzhen Dongdixin Technology Co., Ltd. |
| Hangzhou Sejoy Electronics & Instruments Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
MEMS thermistor substrate export controls from US and Japanese semiconductor suppliers determine both the premium tier spreads separating NMPA-certified hospital units from consumer-grade alternatives and the geographic clustering of assembly capacity across Jiangsu and Zhejiang manufacturing bases. Domestic infrared sensor fabrication draws from imported wafers subject to dual-use technology restrictions, compressing margins for uncertified manufacturers while elevating procurement costs for clinical-grade precision.
Pricing Analysis
Volume-discount tiering structures separate provincial hospital consortium frame contracts from spot-market e-commerce transactions. Three-tier pricing stratification across NMPA Class II certified, MIIT-compliant consumer, and uncertified economy segments reflects certification depth and electromagnetic compatibility documentation. Cost compression in the Bluetooth-enabled consumer tier intensifies because Shenzhen manufacturers absorb redesign cycles for GB 9706 compliance. County-level clinics exhibit highest price sensitivity, while tertiary hospital laboratories demonstrate lowest sensitivity due to ISO 17025 traceability mandates.
Supply Chain Analysis
Export-control regimes limiting semiconductor substrate flows from the United States, Japan, and Taiwan concentrate thermopile sensor fabrication risk in Yangtze River Delta assembly plants. Domestic production draws from germanium wafers, ASIC signal processors, and LCD display modules. Single-source vulnerability in thermistor-grade silicon creates procurement chokepoints for clinical-grade probe manufacturers. Distribution runs through provincial medical consumables consortiums in Jiangsu and Zhejiang, with Ningbo port logistics supporting infrared component importation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home healthcare infrastructure expansion across Chinese households signals early-cycle penetration acceleration for connected temperature monitoring devices. Post-pandemic hygiene protocol institutionalization sustains replacement demand beyond the initial surge phase.
For Market Incumbents: Pre-empt margin erosion from provincial procurement centralization by securing NMPA Class II certificates ahead of SAMR quality enforcement tightening. Backward integration into thermopile sensor assembly reduces exposure to semiconductor substrate export volatility. Channel control through Jiangsu and Zhejiang hospital consortium frame contracts defends position against Pearl River Delta scale fabricators.
For New Entrants and Emerging Players: Build out distribution partnerships in the Sichuan-Chongqing corridor where western province healthcare infrastructure investment lags coastal saturation. Mid-tier probe thermometers for agricultural cooperatives and county-level clinics represent the most penetrable segment. Firmware subscription models for telemedicine integration provide a differentiated go-to-market angle against hardware-only competitors.
For Investors and Strategic Acquirers: NMPA registration timeline extensions reshape the acquisition landscape toward manufacturers with established Class II certificates and validated clinical accuracy protocols. Long-term viability centers on hospital information system integration capabilities and recurring revenue streams from connected device platforms. Monitor SAMR enforcement action intensity as the signal indicating margin compression acceleration for uncertified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class II Certification Investment | Clinical accuracy validation opens provincial hospital consortium procurement channels in Jiangsu and Zhejiang. |
| Backward Integration into Sensor Assembly | Thermopile production control reduces dependency on US and Japanese semiconductor substrate suppliers. |
| Hospital Information System Partnership | Wi-Fi connectivity integration with provincial health networks enables firmware subscription revenue streams. |
| GB 9706 Electromagnetic Compliance Redesign | MIIT-to-GB certification bridging maintains e-commerce platform access for Shenzhen manufacturers. |
| Sichuan-Chongqing Distribution Expansion | Western province infrastructure investment gaps create white-space capture opportunities for mid-tier probe units. |
Research Methodology
Operator-level perspectives from hospital procurement managers, biomedical engineers, NMPA regulatory consultants, and GPO contracts managers anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from SAMR enforcement action databases, provincial medical consumables consortium tender records, MIIT wireless certification filings, and customs trade data for semiconductor substrate imports. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates across the analysis window.
Scenario-bracketing framed projections across conservative, baseline, and expansion cases without year-specific anchoring. Segmentation dimensions modeled include product type, application tier, connectivity technology, and end-user certification requirements. CAGRs derived from replacement cycle analysis, technology substitution rates, and provincial healthcare infrastructure investment trajectories. NMPA registration timeline variability and thermopile sensor supply elasticity served as industry-specific forecast sensitivity inputs.
Stress conditions across semiconductor export control intensity, SAMR enforcement acceleration, and provincial procurement centralization pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hospital information system adoption curves and connected health platform penetration. Material shifts in US-Japan-Taiwan semiconductor substrate trade policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Inductive Encoder Market
Sensors and Controls
Middle East and Africa Wireless Sensors Market
Sensors and Controls
Pressure Transmitter Market
Sensors and Controls
MEMS-Based IMU Market
Sensors and Controls
Temperature Monitoring System Market
Sensors and Controls
Magnetic Absorption Data Line Market
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Digital Pump Controller Market
Sensors and Controls
HVAC Sensor Market
Sensors and Controls
Piezoelectric Accelerometer Market
Sensors and Controls
Air Particle Monitor System Market
Sensors and Controls
Digital Thermohygrometers Market
Sensors and Controls
Asia-Pacific Nano Radiation Sensors Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
Instrumented Load Shackle Market