
 United States Scintillator Market | 2026-2036
United States Scintillator Market Size, Share, and Industry Trends Forecast 2026-2036
United States Scintillator Market Intelligence
Silicon photomultiplier substitution for traditional photomultiplier tubes is tilting scintillator system architectures toward compact, low-voltage designs. Saint-Gobain S.A. leverages its North American crystal growth facilities to dominate domestic supply of sodium iodide and cesium iodide substrates. Hamamatsu Photonics K.K. anchors the photodetector layer through its U.S. distribution network for silicon photomultiplier arrays. Mirion Technologies, Inc. specializes in integrated radiation detection systems that bundle scintillator crystals with proprietary electronics for defense and healthcare end users.
A scintillator is a material that emits ultraviolet or visible light when excited by ionizing radiation, with inorganic variants such as thallium-doped sodium iodide achieving light yields of approximately 38,000 photons per MeV and decay constants near 230 nanoseconds for gamma spectroscopy applications. Organic scintillators compete on timing resolution for high-energy physics experiments, while plastic scintillators extend into large-area radiation portal monitors where cost-per-unit-area governs procurement decisions. Inorganic scintillators occupy the premium tier in nuclear medicine imaging systems, where energy resolution directly determines diagnostic accuracy.
The U.S. Nuclear Regulatory Commission enforces 10 CFR Part 20 standards that mandate calibrated radiation monitoring in nuclear medicine facilities, directly specifying scintillator-based dosimetry equipment. The Department of Energy's National Nuclear Security Administration imposes additional performance specifications on scintillator materials deployed in nonproliferation and safeguards applications. The FDA's 21 CFR Part 1020 regulations for diagnostic x-ray systems indirectly shape scintillator requirements through detector performance standards. Stakeholders must monitor how NRC licensing reforms and DOE national laboratory procurement shifts recalibrate technical specifications before committing to long-term crystal supply agreements.
Market Dynamics
Silicon photomultiplier arrays are collapsing the voltage infrastructure of legacy scintillator systems, forcing detector architectures toward compact, solid-state platforms that eliminate high-voltage power supplies and reduce shielding requirements across defense and medical installations.
Growth Catalysts
- Border Security Procurement:The Department of Homeland Security's Continuous Diagnostics and Mitigation program mandates scintillator-based radiation portal monitors at southwestern ports of entry, creating sustained federal demand for high-sensitivity gamma detectors.
- Nuclear Medicine Mandates:10 CFR Part 20 standards from the U.S. Nuclear Regulatory Commission require calibrated dosimetry in every licensed nuclear medicine facility, embedding scintillator equipment into routine clinical compliance.
- Thallium-Doped Sodium Iodide:This crystal formulation achieves 38,000 photons per MeV light yield, making it indispensable for gamma spectroscopy in national laboratory nonproliferation missions at Los Alamos and Sandia.
Market Restraints
- Cesium Supply Concentration:Domestic cesium iodide substrate production depends on limited North American crystal growth capacity, exposing procurement timelines to single-source bottlenecks.
- Photodetector Import Dependency:Silicon photomultiplier arrays rely heavily on Asian manufacturing nodes, creating tariff exposure and lead-time volatility for U.S. system integrators.
- Decay Constant Limitations:Inorganic scintillator timing resolution near 230 nanoseconds constrains their utility in high-energy physics experiments requiring sub-nanosecond coincidence detection.
Strategic Opportunities
- Southwestern Research Corridor:Los Alamos National Laboratory and Sandia National Laboratories drive specialized procurement for nonproliferation applications, creating premium demand for radiation-hardened detector systems.
- Plastic Scintillator Portals:Large-area radiation monitors at land border crossings favor cost-per-unit-area optimization, opening volume opportunities for extruded plastic scintillator sheet producers.
- Low-Voltage Defense Electronics:Silicon photomultiplier substitution enables battery-operated field deployable systems, matching the Department of Defense's push for reduced logistical footprint in tactical radiation detection.
Industry Challenges
- Crystal Growth Technician Scarcity:The specialized skill set for Bridgman-Stockbarger growth of activated alkali halide crystals has atrophied in domestic universities, constraining production scale-up.
- FDA 21 CFR Part 1020 Compliance:Diagnostic x-ray system detector performance standards impose lengthy premarket notification timelines, delaying revenue recognition for new scintillator-based imaging platforms.
- Legacy PMT Integration Complexity:Fielded military systems built around traditional photomultiplier tubes resist retrofit, forcing parallel supply chains during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Scintillator Market |
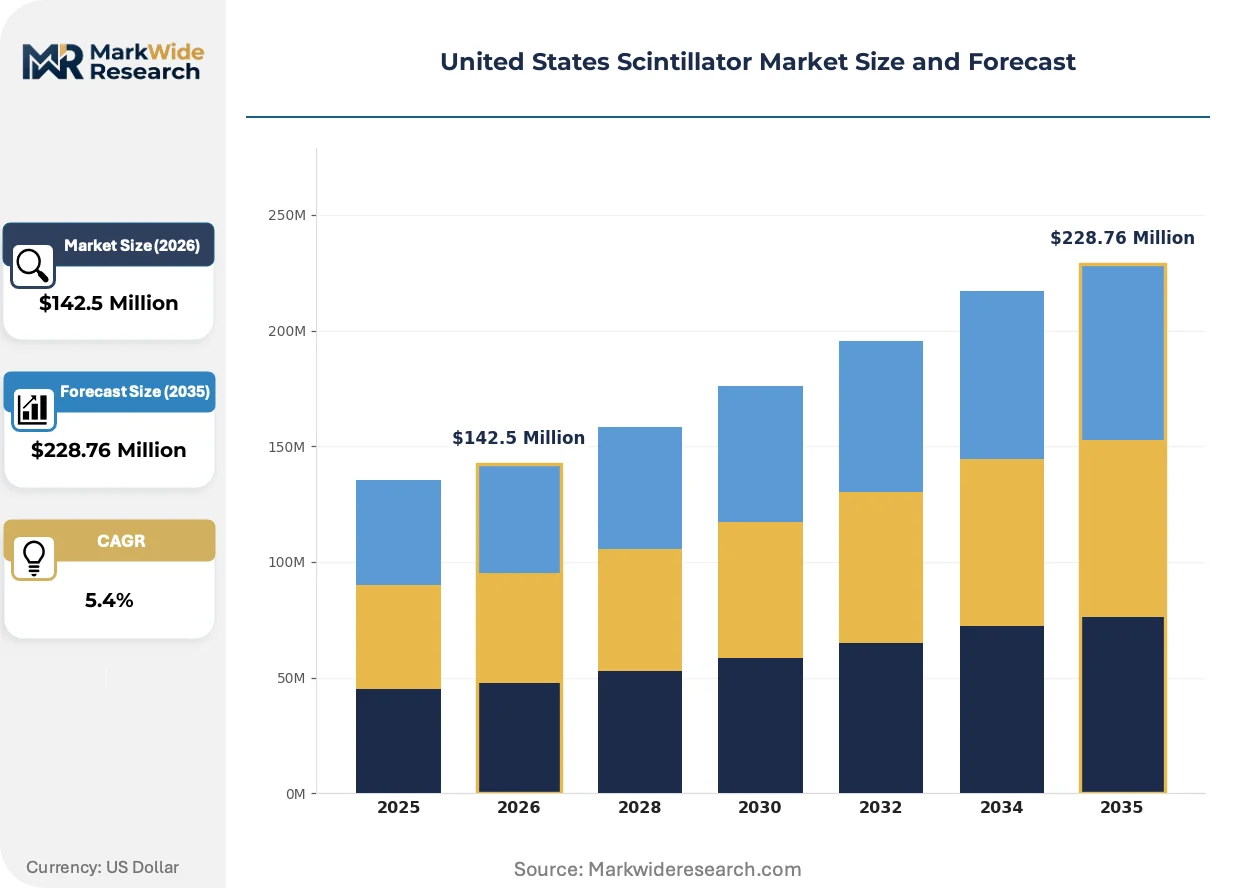
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $228.76 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Scintillators, Inorganic Scintillators, Plastic Scintillators, Liquid Scintillators Application: Nuclear Medicine, Radiation Detection, High-Energy Physics, Industrial Inspection End User: Healthcare Providers, Research Institutions, Defense Agencies, Nuclear Power Plants Technology: CeBr, NaI, CsI, PMT |
| Companies Covered | Saint-Gobain S.A., Hamamatsu Photonics K.K., Mirion Technologies, Inc., Dynasil Corporation of America, Radiation Monitoring Devices, Rexon Components, Inc., Proterial, Ltd., Kromek Group plc, OSI Systems, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Scintillator Market Strategic Shifts & Innovations
Detector miniaturization is compressing system form factors while expanding deployment scenarios. Three converging developments are reconfiguring technical specifications and procurement patterns across defense, healthcare, and research end uses.
Solid-state photodetection is collapsing the high-voltage infrastructure that has dominated scintillator electronics for decades. Silicon photomultiplier arrays operate at bias voltages below 50 volts, eliminating the kilovolt power supplies and magnetic shielding that encumbered photomultiplier tube architectures. Defense contractors are accelerating adoption for man-portable radiation detectors, enabling battery-powered operation in tactical environments where weight and electromagnetic signature constrain mission profiles. This voltage collapse is compressing system volumes by orders of magnitude, opening installation geometries previously inaccessible to scintillator-based detection.
The U.S. Nuclear Regulatory Commission is tightening calibration traceability requirements under 10 CFR Part 20 enforcement guidance issued to regional inspectors. Nuclear medicine facilities must now demonstrate direct NIST-traceable calibration chains for scintillator-based dosimetry equipment, eliminating grandfathered legacy instruments. Hospital radiation safety officers are responding by consolidating vendor relationships with integrated system providers capable of delivering certified calibration services alongside hardware, shifting procurement preference toward bundled equipment-service contracts.
Spec-driven purchasing is displacing component sourcing in Department of Energy national laboratory procurement. Los Alamos and Sandia now issue performance-based specifications for integrated detection systems rather than discrete crystal supply agreements, forcing material suppliers to partner with electronics integrators or develop captive system capabilities. This specification shift is most visible in nonproliferation safeguards applications, where national security mission timelines override pure material cost considerations in vendor selection.
United States Scintillator Market Segmentation
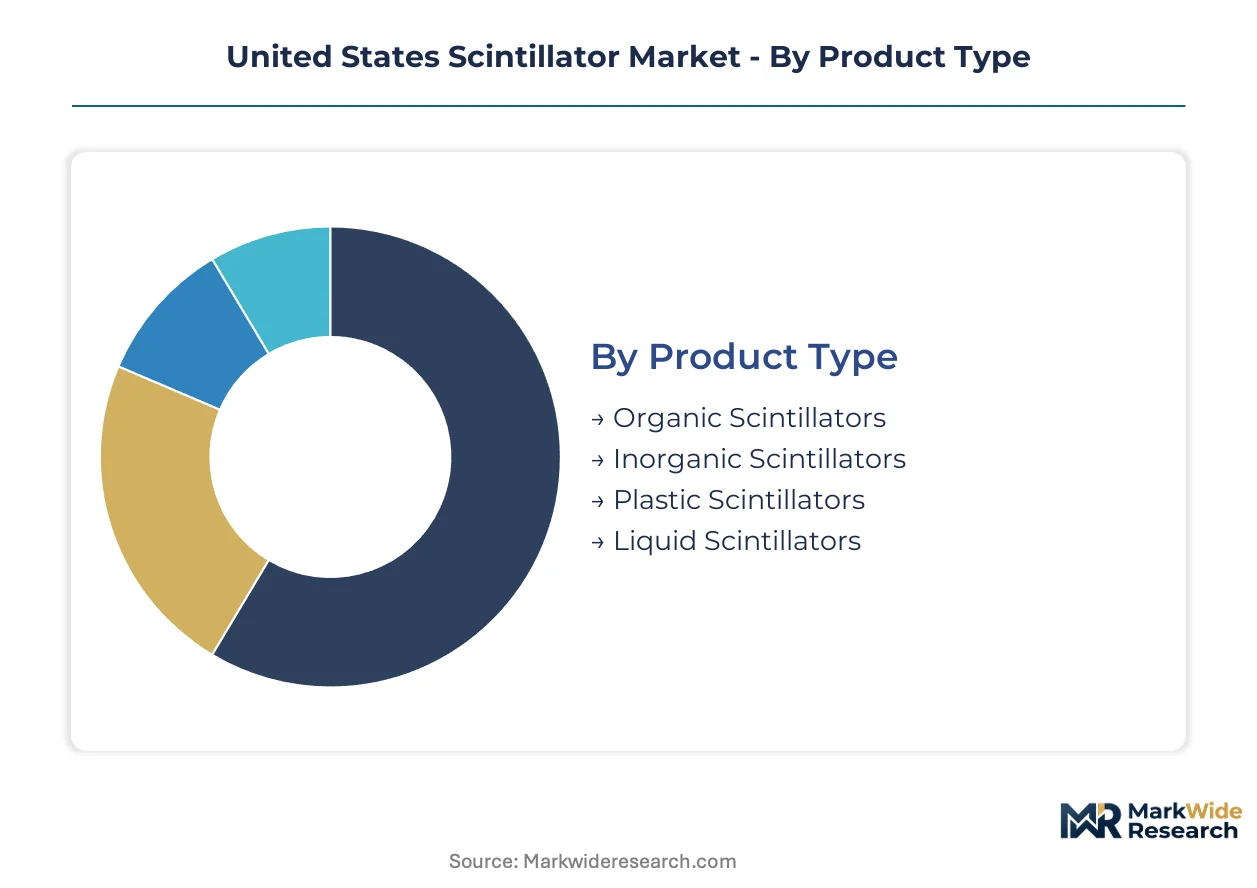
Scintillator procurement patterns diverge sharply across material chemistry, end-use mission requirements, and detection technology architectures. Understanding these segment boundaries clarifies why sodium iodide dominates national laboratory contracts while plastic formulations capture border security volume plays.
Product Type:
Cost tier stratification separates premium crystal growth products from extruded polymer volume plays, with each chemistry commanding distinct manufacturing footprints and margin profiles.
- Inorganic Scintillators:Thallium-doped sodium iodide and cesium iodide crystals grown via Bridgman-Stockbarger methods achieve 38,000 photons per MeV light yield. Los Alamos National Laboratory and Sandia National Laboratories anchor procurement for nonproliferation gamma spectroscopy, where energy resolution mandates override unit cost considerations.
- Plastic Scintillators:Extruded polystyrene sheets doped with fluorescent additives deliver cost-per-unit-area advantages across large-area radiation portal monitors. The Department of Homeland Security's southwestern port of entry deployments favor this format for vehicle screening lanes where geometric coverage dominates sensitivity metrics.
- Organic Scintillators:Anthracene and stilbene crystals provide sub-nanosecond timing resolution for time-of-flight measurements in specialized physics experiments.
- Liquid Scintillators:Organic fluor dissolved in aromatic solvents enables 4π geometry detection for neutrino and dark matter research at underground facilities.
Inorganic formulations command the established base. The steepest expansion trajectory runs through plastic scintillator sheet production for federal border infrastructure.
Application:
Regulatory mandate intensity varies across end uses, with nuclear medicine and safeguards applications embedding scintillator procurement into compliance workflows rather than discretionary capital budgets.
- Nuclear Medicine:10 CFR Part 20 mandates from the U.S. Nuclear Regulatory Commission require calibrated scintillator-based dosimetry in every licensed facility. Hospital radiation safety officers consolidate vendor relationships around bundled equipment-service contracts delivering NIST-traceable calibration chains.
- Radiation Detection:The Department of Homeland Security's Continuous Diagnostics and Mitigation program sustains federal procurement for gamma and neutron portal monitors at land borders and maritime ports.
- High-Energy Physics:Time-of-flight and calorimetry experiments at national user facilities drive demand for fast-timing organic and inorganic formulations.
- Industrial Inspection:Pipeline radiography and weld verification applications favor ruggedized portable scintillator probes for field nondestructive testing crews.
Radiation detection commands the established base. The steepest expansion runs through nuclear medicine as NRC enforcement tightens calibration traceability requirements.
End User:
Customer type determines specification authority, with defense and research end users issuing performance-based system requirements while healthcare providers respond to regulatory compliance mandates.
- Defense Agencies:The Department of Energy's National Nuclear Security Administration imposes performance specifications on scintillator materials for nonproliferation missions, overriding pure material cost in vendor selection.
- Research Institutions:Los Alamos National Laboratory and Sandia National Laboratories drive specialized procurement for radiation-hardened detector systems in nonproliferation applications.
- Healthcare Providers:Hospital radiation safety officers must demonstrate 10 CFR Part 20 compliance through NIST-traceable calibration chains for scintillator-based dosimetry equipment.
- Nuclear Power Plants:Reactor operators deploy area monitors and personnel dosimetry systems incorporating scintillator probes for occupational exposure tracking.
Defense agencies command the established base. The steepest expansion runs through healthcare providers responding to tightened NRC calibration enforcement.
Technology:
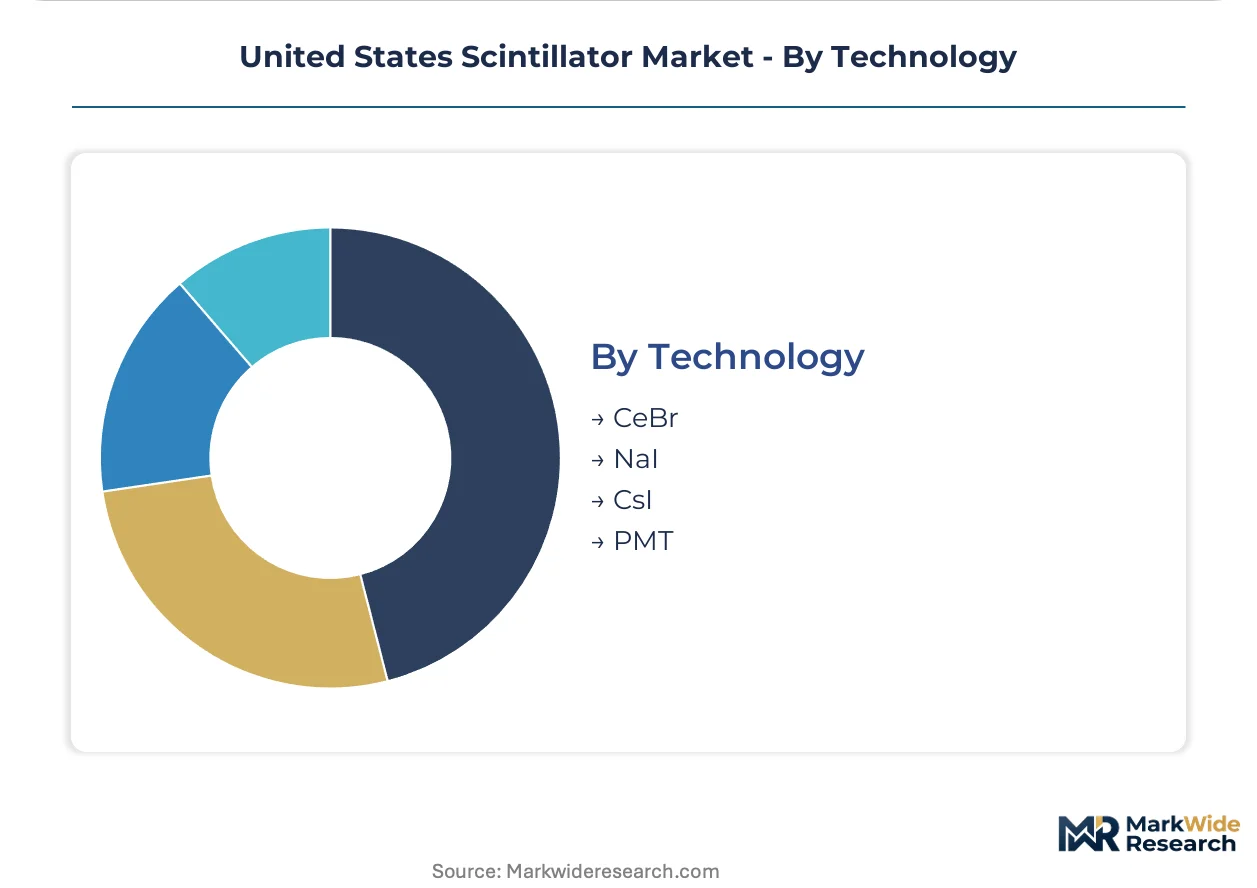
Photodetector substitution is collapsing legacy voltage infrastructure, with silicon photomultiplier arrays displacing traditional photomultiplier tubes across new system architectures.
- NaI:Thallium-doped sodium iodide dominates gamma spectroscopy with 38,000 photons per MeV light yield and 230 nanosecond decay constants, anchoring national laboratory nonproliferation missions.
- SiPM:Silicon photomultiplier arrays operate below 50 volts bias, eliminating kilovolt power supplies and enabling battery-operated tactical radiation detectors for Department of Defense field deployment.
- CsI:Cesium iodide substrates offer higher density and mechanical ruggedness for space-constrained defense and aerospace applications.
- CeBr:Cerium bromide delivers superior energy resolution without hygroscopic handling constraints, gaining traction in next-generation spectroscopy platforms.
- PMT:Traditional photomultiplier tubes persist in legacy military systems resisting retrofit, forcing parallel supply chains during transition periods.
PMT-based systems command the established base. The steepest expansion runs through SiPM architectures enabling low-voltage defense electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scintillator crystal shipments flow from North American growth facilities to southwestern U.S. national laboratories and border security installations, with procurement timelines tied to federal fiscal cycles and Department of Energy mission requirements.
Southwest
Los Alamos National Laboratory and Sandia National Laboratories anchor specialized inorganic scintillator procurement for nuclear research and nonproliferation missions. The Department of Energy's National Nuclear Security Administration imposes performance specifications that override pure material cost in vendor selection. Albuquerque-Santa Fe corridor facilities concentrate Bridgman-Stockbarger crystal growth operations serving federal safeguards applications.
Southeast
Nuclear medicine facilities across Florida and Georgia respond to tightened U.S. Nuclear Regulatory Commission calibration enforcement under 10 CFR Part 20 guidance. Hospital radiation safety officers consolidate vendor relationships around bundled equipment-service contracts delivering NIST-traceable calibration chains. Atlanta and Miami metropolitan areas concentrate imaging equipment distribution networks serving expanding oncology and cardiology departments.
Northeast
Massachusetts and New York research institutions drive demand for fast-timing organic scintillators in particle physics experiments. The Department of Homeland Security's Continuous Diagnostics and Mitigation program sustains federal procurement for radiation portal monitors at maritime ports. Boston-Cambridge corridor startups develop silicon photomultiplier integration for next-generation detector architectures.
West Coast
California defense contractors accelerate silicon photomultiplier adoption for man-portable radiation detectors under Department of Defense tactical electronics programs. Lawrence Livermore National Laboratory specifications shape procurement for radiation-hardened detector systems. San Francisco Bay Area and San Diego clusters concentrate system integrators bundling scintillator crystals with proprietary electronics.
United States Scintillator Market Key Industry Players
On the supply side, the industry is structured around three strategic tiers: multinational material conglomerates with captive crystal growth facilities, specialized photodetector manufacturers with distribution networks, and integrated system providers bundling hardware with compliance services. Dominant competitive moves include strategic partnerships between crystal growers and electronics integrators to meet spec-driven national laboratory procurement, and capacity expansion in plastic scintillator extrusion for border security volume plays.
Among North American and Japanese fabricators, Saint-Gobain S.A. and Hamamatsu Photonics K.K. exemplify the material-photodetector interface that defines system performance, while Mirion Technologies, Inc. occupies a position within the integrated-system tier serving defense and healthcare end users with bundled equipment-service offerings.
| Leading Market Players |
|---|
| Saint-Gobain S.A. |
| Hamamatsu Photonics K.K. |
| Mirion Technologies, Inc. |
| Dynasil Corporation of America |
| Radiation Monitoring Devices |
| Rexon Components, Inc. |
| Proterial, Ltd. |
| Kromek Group plc |
| OSI Systems, Inc. |
| Others |
Cost & Logistics Intelligence
The Albuquerque-Santa Fe logistics corridor channels Bridgman-Stockbarger crystal growth outputs to Los Alamos and Sandia National Laboratories, with freight cost dynamics amplifying supply concentration effects and forcing three-tier pricing stratification across premium spectroscopy-grade, standard medical-imaging, and economy plastic-scintillator tiers.
Pricing Analysis
PMT-to-SiPM generational pricing gaps separate legacy kilovolt systems from sub-50-volt solid-state architectures, with contract-based long-term offtake dominating national laboratory procurement. Price differentiation rests on NIST-traceable certification grade and crystal light-yield performance tier. Cost compression in plastic scintillator sheet production intensifies as extruded polystyrene capacity expands for DHS border infrastructure. Defense agencies exhibit lowest price sensitivity, while industrial inspection crews face acute margin pressure on portable probe procurement.
Supply Chain Analysis
Contract manufacturing concentration in Japanese silicon photomultiplier foundries and North American crystal growth facilities anchors domestic supply. Geographic supply draws from Japan, France, and domestic New Mexico-Albuquerque corridor operations. Raw material dependencies center on thallium-doped sodium iodide substrates, cesium iodide precursors, and polystyrene resin feedstocks. Single-source vulnerability in Asian photodetector arrays creates tariff exposure for U.S. system integrators. Distribution runs through DOE national laboratory procurement offices and DHS Continuous Diagnostics and Mitigation program channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bridgman-Stockbarger crystal growth technician pipelines have atrophied across domestic universities, constraining production scale-up and amplifying acquisition premiums for captive growth capabilities.
For Market Incumbents: Build regulatory-certification moats around NIST-traceable calibration service bundling for hospital radiation safety officers. Consolidate backward integration into thallium-doped sodium iodide crystal growth to offset Asian photodetector import dependency. Defend against SiPM substitution threats by embedding legacy PMT compatibility layers in next-generation system architectures. For New Entrants and Emerging Players: Southeastern nuclear medicine corridors present underpenetrated white space as NRC enforcement tightens 10 CFR Part 20 compliance requirements. Target bundled equipment-service contracts displacing grandfathered legacy dosimetry instruments. Pursue GPO contracting partnerships with expanding Florida and Georgia oncology departments as the fastest vector to hospital system penetration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated system providers with captive crystal supply and certified calibration infrastructure over pure material commodity plays. Long-term viability across the analysis window rests on radiation-hardened detector capabilities for nonproliferation missions. Monitor DOE National Nuclear Security Administration specification shifts as the inflection signal for procurement preference migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystal Growth | Captive Bridgman-Stockbarger capacity insulates against cesium iodide substrate bottlenecks at Saint-Gobain facilities. |
| SiPM Array Manufacturing Partnership | Hamamatsu distribution alliances reduce tariff exposure and lead-time volatility for defense contractors. |
| NIST-Traceable Calibration Service Launch | Hospital radiation safety officers consolidate vendor relationships around bundled equipment-service contracts. |
| Plastic Scintillator Extrusion Scale-Up | DHS southwestern port deployments favor cost-per-unit-area optimization in vehicle screening lanes. |
| Radiation-Hardened Detector System Development | Los Alamos and Sandia performance specifications override pure material cost in nonproliferation vendor selection. |
Research Approach
The analysis maps inorganic crystal, plastic sheet, organic, and liquid scintillator sub-sectors, each validated through primary interviews with crystal growth technicians, radiation safety officers, DHS procurement leads, and national laboratory safeguards engineers. Secondary sources include U.S. Nuclear Regulatory Commission 10 CFR Part 20 enforcement guidance, Department of Energy National Nuclear Security Administration specifications, FDA 21 CFR Part 1020 detector standards, and SEC filings from listed material suppliers. Bottom-up crystal shipment data triangulates against top-down federal procurement budget allocations.
Assumptions hold silicon photomultiplier cost curves, tariff regimes, and NRC calibration enforcement intensity within observed trajectories across the projection horizon. Segmentation dimensions span material chemistry, end-use application, photodetector technology architecture, and federal versus commercial procurement channel. CAGRs derive from installed base replacement cycles, DHS border infrastructure deployment schedules, and hospital capital equipment refresh patterns. Forecast inputs incorporate thallium-doped sodium iodide light-yield specifications and SiPM bias voltage collapse rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian photodetector foundries or domestic startup crystal growers would shift outcomes beyond modeled ranges. Quarterly review of DOE national laboratory RFP releases, DHS CDM program funding allocations, and NRC regional inspection guidance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Lidar Ceilometer Market
Sensors and Controls
Silicon Photomultiplier (Sipm) Market
Sensors and Controls
Advanced Sensor Market
Sensors and Controls
Global Mid-And-High-Level Precision GPS Receiver Market
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
Quantum Sensors Market
Sensors and Controls
MEMS Inertial Sensors Market
Sensors and Controls
Russia Digital Thermometer Market
Sensors and Controls
Americas Sensor Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
Russia Non-Contact Infrared Thermometer Market
Sensors and Controls
Europe Smart Glove Market
Sensors and Controls
Robotic Sensors Market
Sensors and Controls
ECG Sensor Market
Sensors and Controls
Ultrasound Sensors Market
Sensors and Controls
Middle East Robotic Sensors Market