
 China Connector Market | 2026-2036
China Connector Market Size, Share, and Industry Trends Forecast 2026-2036
China Connector Market Insights
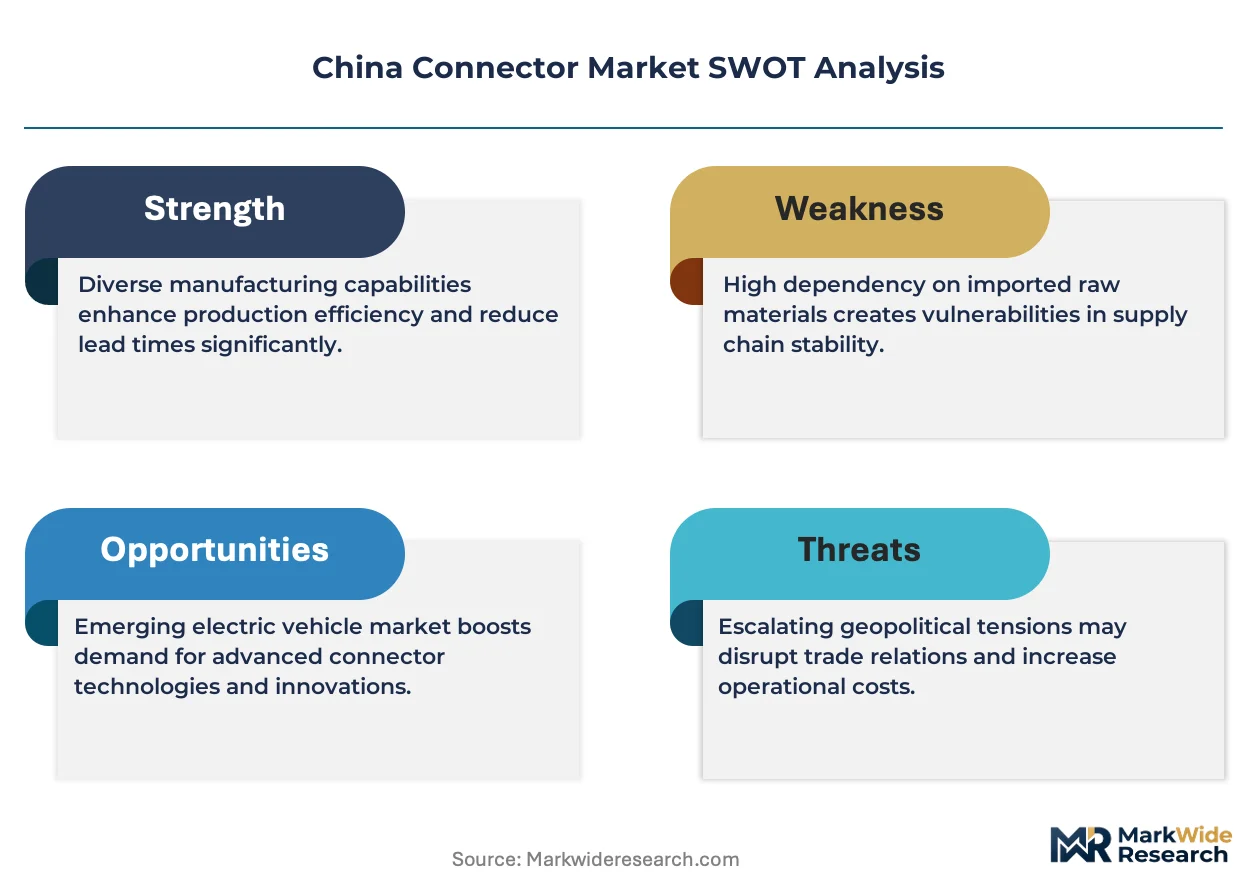
New energy vehicle manufacturing is recalibrating connector demand across China's industrial base. TE Connectivity leverages its automotive-grade high-voltage portfolio to anchor supply relationships with domestic EV platforms. Amphenol Corporation sustains R&D intensity in ruggedized interconnect solutions for industrial automation end users. Molex competes through manufacturing scale advantages across multiple provincial production zones.
Connectors are electromechanical devices engineered to join electrical terminations and create complete circuits, typically specified by contact pitch, current-carrying capacity, and mating-cycle durability for signal or power transmission. Board-to-Board connectors occupy the premium margin tier in telecommunications infrastructure buildouts, while Wire-to-Board formats dominate consumer electronics assembly volumes. Surface Mount technology leads contract manufacturing flows, though Press-Fit methods gain traction in automotive module production for solder-joint reliability.
MIIT establishes connector performance benchmarks for telecommunications and automotive applications, while GB standards govern dimensional interoperability and environmental testing protocols. SAMR enforces product safety certification requirements that condition market access for both domestic producers and imported component lines. Stakeholders must monitor evolving dual carbon goals as MEE tightens material content restrictions affecting plating chemistry and insulator compounds in next-generation designs.
Market Dynamics
MIIT's high-speed data transmission mandates are forcing connector manufacturers to retool certification pipelines while domestic EV platforms scale procurement volumes across the Yangtze River Delta manufacturing corridor.
Growth Catalysts
- New energy vehicle production quotas:Domestic EV platforms are expanding high-voltage connector procurement across battery pack and power distribution module supply chains.
- GB standards harmonization:Dimensional interoperability protocols are reducing qualification friction for suppliers serving telecommunications infrastructure buildouts.
- Yangtze River Delta concentration:Shanghai-Jiangsu-Zhejiang manufacturing clusters are generating scale economies in precision stamping and automated assembly operations.
Market Restraints
- Copper and rare earth price volatility:Contact plating materials and high-performance magnet alloys face input cost swings that compress margin buffers.
- Domestic supply concentration:Specialty polymer compounders for high-temperature insulators cluster in limited coastal zones, creating single-source vulnerability.
- Technical substitution pressure:Wireless power transfer and capacitive coupling architectures are displacing physical interconnects in select consumer electronics applications.
Strategic Opportunities
- Central and Western China expansion:Chongqing and Chengdu automotive electronics corridors remain underpenetrated relative to coastal manufacturing density.
- Dual carbon compliance services:MEE material content restrictions are creating advisory and redesign revenue streams around plating chemistry substitution.
- 5G-A infrastructure deployment:MIIT spectrum allocations for advanced mobile networks are accelerating demand for millimeter-wave capable board-to-board formats.
Industry Challenges
- High-frequency signal integrity engineering:Qualified talent pools for electromagnetic simulation and impedance matching design remain shallow relative to demand.
- SAMR certification timeline compression:Safety approval queues are extending qualification cycles for new product introductions.
- Legacy automotive platform integration:Backward compatibility requirements for 12V and 48V architectures complicate module redesigns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Connector Market |
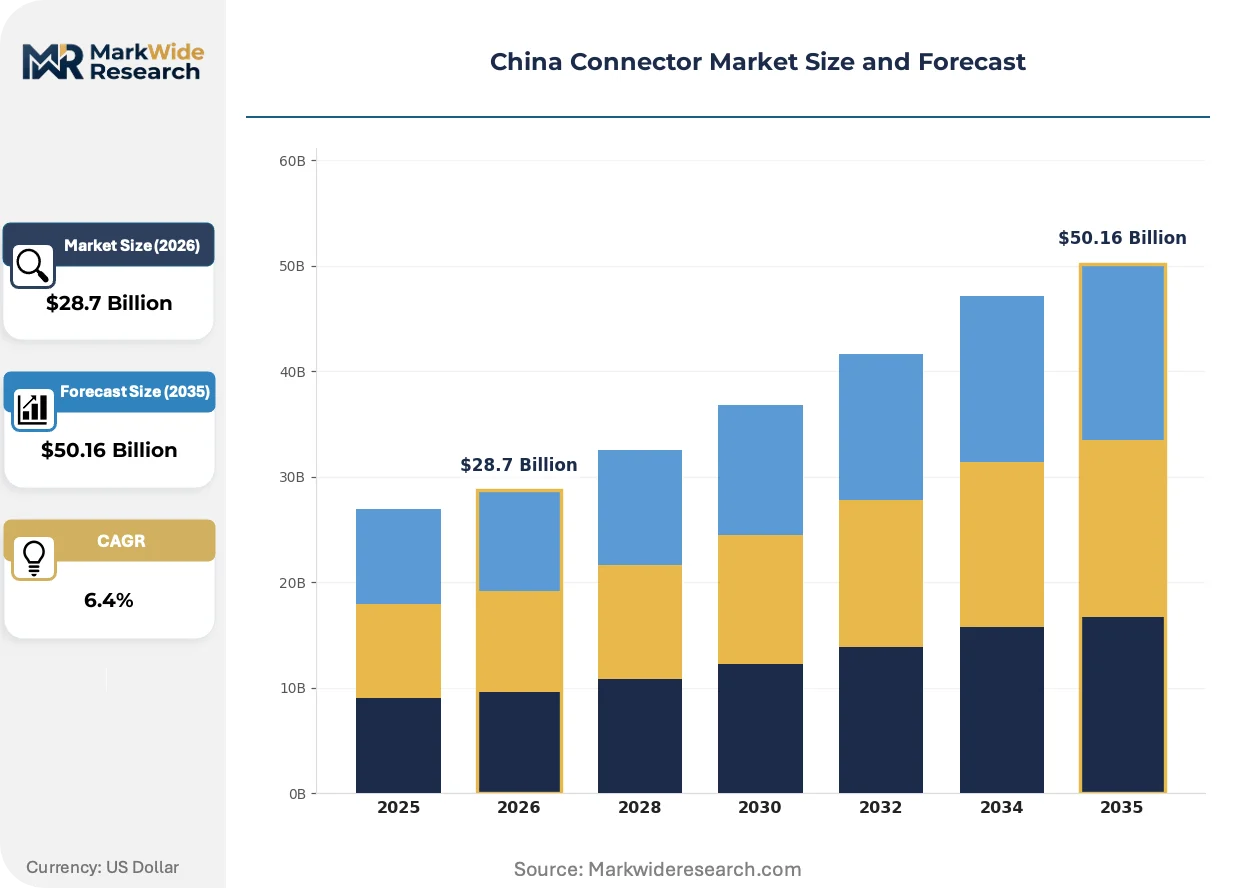
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Board-to-Board, Wire-to-Board, Circular, USB, Coaxial, Card Edge Technology: Surface Mount, Through Hole, Press-Fit, Wire Wrap, Solderless, Crimp Application: Consumer Electronics, Telecommunications, Aerospace & Defense, Medical Devices, Renewable Energy, Industrial Automation End User: OEMs, Contract Manufacturers, System Integrators, Aftermarket Suppliers, Distributors, Repair Centers |
| Companies Covered | Phoenix Contact, DINKLE, TE Connectivity, Suzhou Xinsheng Electronic, Ningbo Hengtong Electronic, Amphenol Corporation, DEGSON, Hangzhou Fuda Electronics, Molex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Connector Market Trends and Innovations
Connector architectures are bifurcating between ultra-miniaturized consumer formats and ruggedized industrial-grade systems, with manufacturing processes adapting to divergent reliability and cost targets.
High-density press-fit termination technology is converging with automotive module assembly workflows to eliminate solder-joint thermal fatigue risks in under-hood environments. Tier-1 suppliers serving domestic OEMs are adopting these methods at accelerating rates for battery management and inverter applications. The structural result is converging with quality assurance protocols that previously separated consumer and automotive certification tracks.
MIIT's electromagnetic compatibility testing protocols are tightening emission thresholds for telecommunications infrastructure connectors. Manufacturers must retest existing product lines against revised specifications before renewal of network equipment access permits. Board-to-board formats deployed in base station radio units face the steepest compliance cost increases.
Direct procurement relationships between EV platform engineering teams and connector specialists are displacing traditional tiered distribution channels. Volume buyers are consolidating supplier panels and negotiating multi-year framework agreements with technical collaboration clauses. This pattern is most visible in Ningbo and Suzhou, where domestic battery pack assemblers maintain resident engineering offices at key supplier facilities.
China Connector Market Segmentation
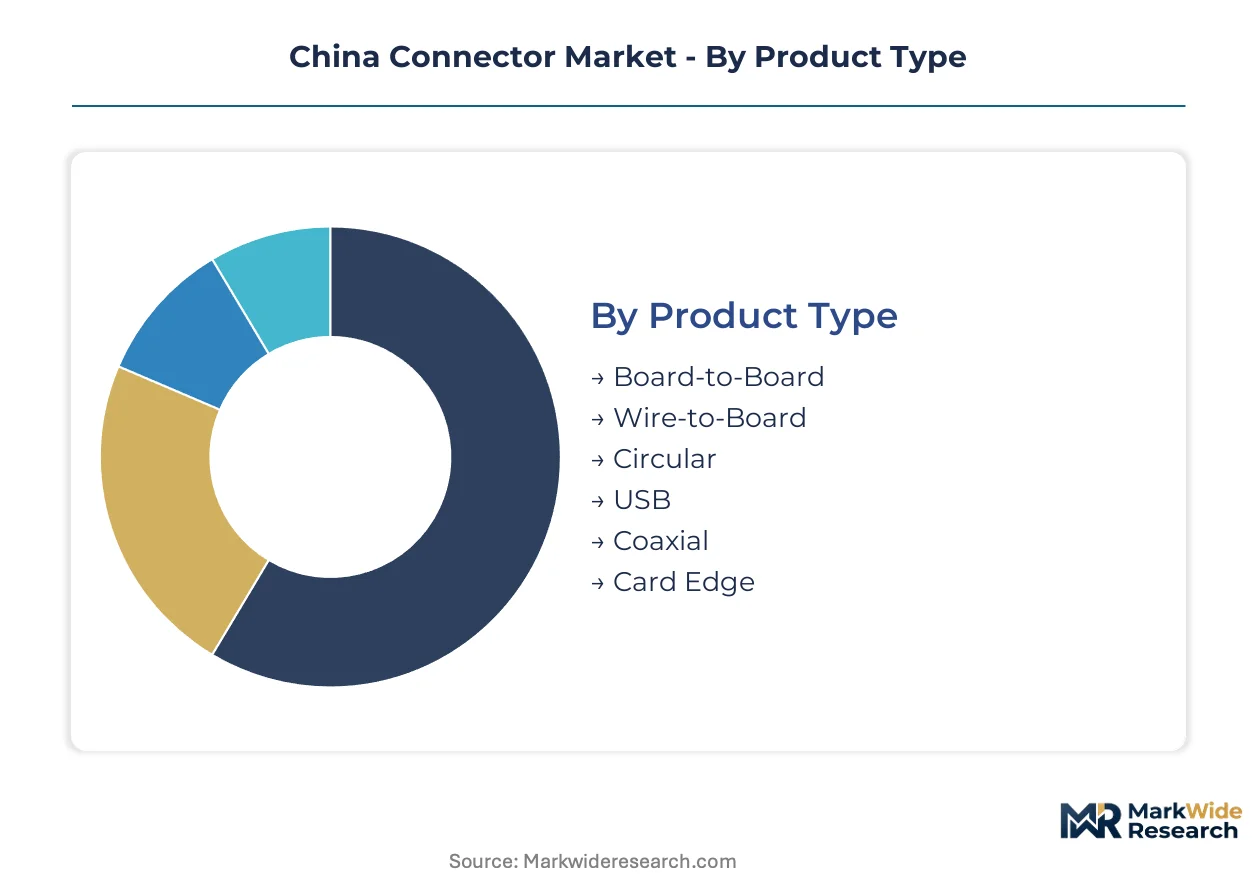
Connector procurement patterns across China's industrial base diverge sharply by voltage rating, signal integrity requirements, and assembly automation compatibility. Understanding these dimensional splits reveals where pricing power concentrates and which technology transitions are accelerating.
Product Type:
Buyers in this category separate by module density requirements and environmental exposure tolerance, with telecommunications infrastructure demanding precision signal paths while automotive applications prioritize vibration resistance.
- Board-to-Board:High-density interconnects with sub-millimeter pitch specifications dominate base station radio unit deployments. MIIT's tightened electromagnetic compatibility thresholds are forcing redesign cycles for existing product lines before network equipment access permit renewal.
- Wire-to-Board:Harness termination formats with integrated locking mechanisms anchor consumer electronics assembly volumes across Shenzhen and Dongguan contract manufacturing corridors. Domestic EV platforms are expanding procurement for battery management system integration.
- Circular:Threaded coupling systems engineered for IP67+ sealing ratings serve industrial automation and military-aerospace end uses requiring moisture and dust ingress protection.
- USB:Standardized rectangular formats with reversible Type-C configurations retain dominance in peripheral device interconnect despite protocol speed tier fragmentation.
- Coaxial:Cylindrical shielded constructions with controlled impedance characteristics support radio frequency signal chains in telecommunications infrastructure.
- Card Edge:Gold-plated contact arrays mating directly with printed circuit board traces persist in legacy computing and storage subsystem applications.
Wire-to-Board leads volumes today; Board-to-Board is gaining share fastest.
Technology:
Assembly method selection tracks customer automation capital intensity and thermal reliability requirements, with high-volume consumer producers favoring speed while automotive module assemblers prioritize joint longevity.
- Surface Mount:Reflow-solderable terminations with gull-wing or J-lead profiles dominate contract manufacturing flows across Yangtze River Delta electronics assembly clusters. Placement speed compatibility with high-speed pick-and-place equipment drives procurement decisions.
- Press-Fit:Compliant pin insertion systems eliminating solder thermal fatigue risks are accelerating adoption in Ningbo and Suzhou automotive electronics corridors for under-hood battery and inverter modules. Tier-1 suppliers are qualifying these methods for 800V high-voltage architectures.
- Through Hole:Leaded terminations requiring wave soldering or selective soldering processes retain foothold in industrial equipment with heavy mechanical loading requirements.
- Wire Wrap:Manual or semi-automatic wrapping of solid wire around terminal posts persists in prototype and low-volume aerospace applications requiring field serviceability.
- Solderless:Insulation displacement and piercing termination methods reduce assembly labor in telecommunications patch panel and building wiring installations.
- Crimp:Compression-based wire barrel connections with strain relief features dominate harness manufacturing for transportation and industrial machinery applications.
Surface Mount maintains dominant share; Press-Fit is climbing the fastest as automotive electrification accelerates.
Application:
End-use demand clusters separate by certification stringency and product lifecycle length, with infrastructure and medical applications commanding margin premiums over high-turnover consumer segments.
- Consumer Electronics:High-volume, short-lifecycle interconnects for smartphones, wearables, and computing peripherals concentrate procurement in Guangdong province contract manufacturers. Miniaturization trends are pushing pitch specifications below 0.35mm for flagship device platforms.
- Telecommunications:Base station and optical transport equipment requiring GB standards compliance for dimensional interoperability. MIIT spectrum allocations for 5G-A networks are accelerating millimeter-wave capable board-to-board format demand.
- Aerospace & Defense:Ruggedized interconnects with extended temperature ranges and shock resistance specifications serving avionics and military communication systems.
- Medical Devices:Sterilization-compatible and biocompatible material constructions for diagnostic and patient monitoring equipment requiring NMPA registration.
- Renewable Energy:High-current, high-voltage connectors for solar inverter and wind turbine power conversion systems exposed to outdoor environmental cycling.
- Industrial Automation:M12 and M8 circular formats with IP67 ratings for factory floor sensor and actuator networks in smart manufacturing deployments.
Consumer Electronics leads volumes today; Telecommunications is expanding most quickly on infrastructure buildout.
End User:
Channel structure determines technical collaboration depth and inventory risk allocation, with direct OEM relationships displacing traditional distribution for strategic component categories.
- OEMs:Original equipment manufacturers with resident engineering teams co-located at supplier facilities in Ningbo and Suzhou are negotiating multi-year framework agreements with technical collaboration clauses for EV platform programs.
- Contract Manufacturers:High-volume electronics assembly services providers across Shenzhen, Dongguan, and Shanghai managing connector procurement as part of turnkey bill-of-materials arrangements.
- System Integrators:Industrial automation and telecommunications infrastructure contractors specifying interconnects as part of subsystem design and installation services.
- Aftermarket Suppliers:Independent distributors serving repair and replacement demand for legacy equipment outside original warranty periods.
- Distributors:Authorized and independent channel partners managing inventory buffers and technical support for mid-volume customers without direct supplier relationships.
- Repair Centers:Service facilities handling warranty and post-warranty connector replacement for consumer electronics and automotive applications.
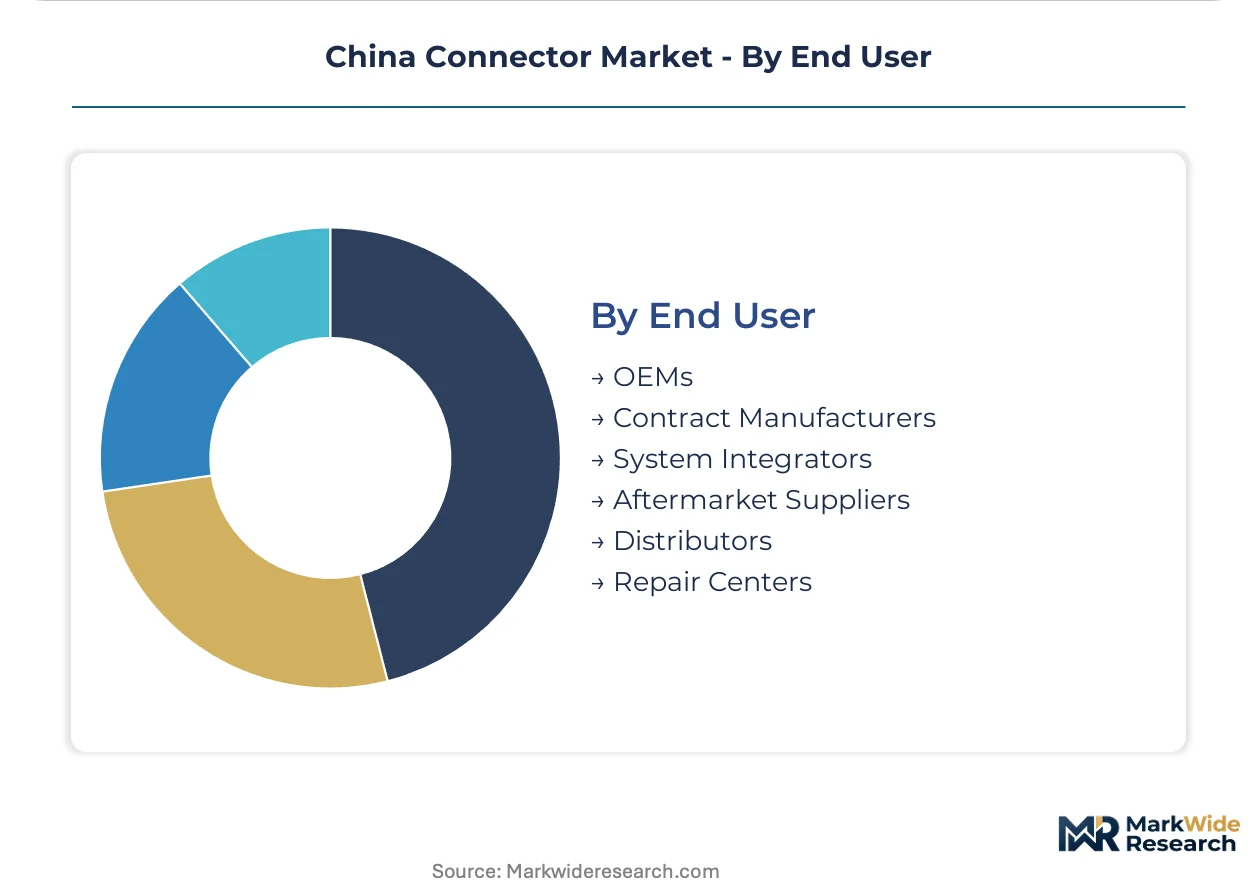
Contract Manufacturers lead volumes today; OEMs are consolidating procurement fastest through direct supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between coastal and interior provinces are redirecting connector manufacturing investments. MIIT certification timelines favor established Yangtze River Delta facilities, while inland tax incentives attract lower-margin production.
Yangtze River Delta
Shanghai-Jiangsu-Zhejiang corridor hosts the densest concentration of precision stamping and automated assembly operations. MIIT high-speed data transmission mandates tighten electromagnetic compatibility testing for base station radio unit connectors. Ningbo and Suzhou automotive electronics clusters see resident engineering offices from domestic EV battery pack assemblers co-located at supplier facilities.
Pearl River Delta
Shenzhen and Dongguan contract manufacturers drive Wire-to-Board format volumes for consumer electronics assembly. SAMR product safety certification requirements condition market access for both domestic producers and imported component lines. Miniaturization trends push pitch specifications below 0.35mm for flagship smartphone device platforms.
Beijing-Tianjin-Hebei
Telecommunications infrastructure procurement concentrates around state-owned carrier headquarters and network equipment vendors. GB standards harmonization on dimensional interoperability reduces qualification friction for suppliers. Tianjin port logistics support import of specialty polymer compounds for high-temperature insulator applications.
Sichuan-Chongqing
Automotive electronics corridors remain underpenetrated relative to coastal manufacturing density. Chongqing-based EV platform engineering teams are expanding direct procurement relationships with connector specialists. Local governments offer tax incentives to attract precision manufacturing investment from coastal relocations.
Shandong Peninsula
Industrial automation end-use demand supports M12 and M8 circular format production for smart manufacturing deployments. Provincial industrial policies prioritize advanced manufacturing equipment localization. Qingdao and Yantai ports facilitate export logistics for automotive-grade connector shipments.
China Connector Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium automotive and telecommunications applications favoring certified brand portfolios while consumer electronics flows through turnkey assembly services. The vendor base organizes around three archetypes: multinational component platforms with automotive-grade certifications, domestic precision fabricators serving regional EV supply chains, and mid-scale specialists in industrial-grade ruggedized formats. Competitive moves concentrate on multi-year framework agreements with technical collaboration clauses and manufacturing scale expansion across provincial production zones.
Within the multinational platform tier, TE Connectivity and Amphenol Corporation occupy positions anchored by automotive-grade high-voltage portfolio breadth and R&D intensity in ruggedized interconnect solutions respectively. Molex exemplifies scale-driven manufacturing advantages across multiple provincial production zones. Among domestic fabricators, Suzhou Xinsheng Electronic and Ningbo Hengtong Electronic represent precision stamping specialists integrated into Yangtze River Delta EV supply chains. Phoenix Contact and DEGSON occupy positions within the industrial automation specialist tier serving factory floor sensor networks.
| Leading Market Players |
|---|
| Phoenix Contact |
| DINKLE |
| TE Connectivity |
| Suzhou Xinsheng Electronic |
| Ningbo Hengtong Electronic |
| Amphenol Corporation |
| DEGSON |
| Hangzhou Fuda Electronics |
| Molex |
| Others |
Pricing and Supply Chain Analysis
Copper contact plating chemistry flows from Jiangxi and Anhui smelters through three distinct pricing tiers before reaching automotive module assemblers in Ningbo and Suzhou. Yangtze River Delta stamping houses capture premium spreads on MIIT-certified high-speed formats while inland fabricators compete on spot-market copper sourcing for standard-grade consumer electronics harnesses.
Pricing Analysis
Distributor markups compress as direct procurement relationships between domestic EV platforms and connector specialists displace traditional tiered channels. Pricing stratifies across automotive-grade high-voltage, telecommunications-certified high-speed, and consumer-grade miniaturized tiers. Cost compression in standard-grade Wire-to-Board formats intensifies because contract manufacturers in Shenzhen and Dongguan consolidate supplier panels. Consumer electronics assemblers exhibit highest price sensitivity; automotive OEMs with resident engineering teams tolerate premium positioning for 800V architecture qualification.
Supply Chain Analysis
Specialty polymer compounding for high-temperature insulators rests on Japanese and German specialty chemical producers with limited qualified alternatives. Precision stamping dies draw from German and Japanese tool steel sources; gold plating salts feed from South Korean refiners. Single-source vulnerability concentrates in coastal polymer compounders serving automotive under-hood specifications. Distribution runs through authorized channels for certified automotive and telecommunications grades, while spot-market brokers handle surplus consumer electronics inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on dual carbon compliance services and 800V high-voltage certification premiums offsetting copper input volatility.
For Market Incumbents: Lock in multi-year framework agreements with technical collaboration clauses before SAMR certification queues extend further. Deepen backward integration into precision stamping die maintenance capabilities to reduce German and Japanese tool steel dependency. Wireless power transfer architectures threaten physical interconnect displacement in consumer electronics; defend through automotive-grade certification moats. For New Entrants and Emerging Players: Begin with Chongqing and Chengdu automotive electronics corridors where direct procurement relationships remain underpenetrated relative to coastal density. Target industrial automation M12 circular formats where Phoenix Contact and DEGSON pricing leaves room for qualified alternatives. Pursue MIIT electromagnetic compatibility pre-certification to accelerate network equipment access permit timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where domestic fabricators lack 800V high-voltage testing infrastructure and automotive-grade quality system certification. Five-to-ten year viability favors specialists with captive plating chemistry expertise and Yangtze River Delta manufacturing scale. Watch MIIT spectrum allocation announcements for 5G-A millimeter-wave board-to-board demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| 800V High-Voltage Certification Investment | MIIT mandates on EV power distribution modules create qualified supplier shortage. |
| Dual Carbon Compliance Advisory Services | MEE material content restrictions generate redesign revenue around plating chemistry substitution. |
| Press-Fit Manufacturing Scale-Up | Automotive module assemblers in Ningbo and Suzhou accelerate adoption for solder-joint reliability. |
| Central and Western China Facility Expansion | Chongqing and Chengdu tax incentives attract precision manufacturing from coastal relocations. |
| 5G-A Millimeter-Wave Product Line Launch | MIIT spectrum allocations accelerate board-to-board demand for base station radio units. |
Research Methodology
Direct dialogue with connector procurement managers at domestic EV battery pack assemblers, MIIT certification laboratory directors, Yangtze River Delta contract manufacturing executives, and specialty polymer compounder technical sales leads grounded this analysis. Secondary validation drew from SAMR product safety certification databases, MIIT electromagnetic compatibility testing protocols, customs records on copper alloy and gold plating salt imports, and GB standards harmonization documentation. Bottom-up segment sizing triangulated against top-down industrial production value estimates.
Bottom-up modeling projected connector procurement volumes across product type, technology, application, and end user dimensions over the projection horizon. CAGRs derived from segment-level growth rate differentials weighted by base-year value shares. Forecast inputs incorporated NEV production quota trajectories, 5G-A infrastructure deployment schedules, and dual carbon policy implementation timelines without specifying individual years.
Caveats apply where copper and rare earth price volatility, SAMR certification timeline extensions, or technical substitution acceleration could materially shift the outlook. A small set of named triggers—MIIT spectrum allocation timing, MEE material restriction enforcement intensity, and wireless power transfer adoption curves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
Cable Connectors and Adapters Market
Connectors
SATA Connector Market
Connectors
IC Socket Market
Connectors
Japan Connector Market
Connectors
Underwater Connectors Market
Connectors
Global Multi Coaxial Connectors Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
USB Type-C Market
Connectors
India Connector Market
Connectors
Magnetic Connector Market
Connectors
DIN Connectors Market
Connectors
Wire-To-Board Connector Market
Connectors
High-Reliability Connectors Market
Connectors
Connector Adapter Kits Market
Connectors
Hazardous Location Connectors Market