
 Asia-Pacific Electric Vehicle Sensor Market | 2026-2036
Asia-Pacific Electric Vehicle Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Electric Vehicle Sensor Market Analytics
Automotive-grade ASIL-D functional safety certification is collapsing the supplier base as only capital-intensive firms survive validation cycles. Bosch leverages captive semiconductor fabrication to sustain margin control across radar and ultrasonic portfolios. Denso Corporation anchors Japanese OEM supply chains with temperature-hardened sensor modules for hybrid platforms. Continental competes through integrated LiDAR-camera fusion systems that reduce ECU count for Chinese EV startups.
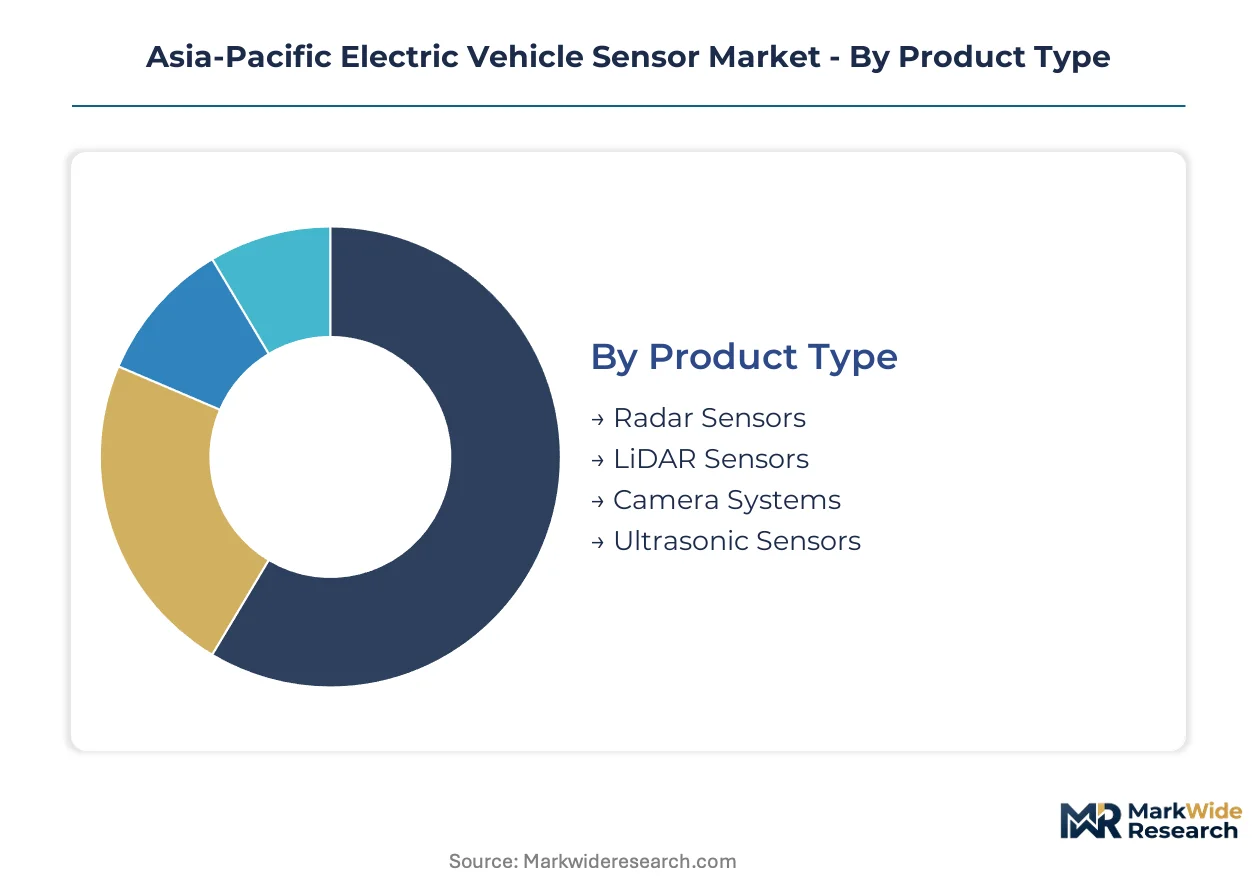
Asia-Pacific electric vehicle sensors comprise electromechanical and solid-state devices measuring position, temperature, current, pressure, and proximity with operating ranges from minus forty to one hundred fifty degrees Celsius and IP6K9K sealing against dust and high-pressure washdown. Their primary purpose is real-time powertrain monitoring and environmental perception to enable safe electrified propulsion and automated maneuvering. Camera systems lead product type revenue as surround-view mandates spread across mid-range Chinese EVs, while LiDAR sensors represent the fastest-growing category as robotaxi fleets in Shenzhen and Beijing scale beyond pilot phases. Smart sensors command premium positioning by embedding edge-processing ASICs that reduce CAN bus bandwidth loads for autonomous driving architectures.
China's MIIT enforces GB/T standards for new energy vehicle electromagnetic compatibility and functional safety that filter out non-compliant imports. Japan's METI coordinates JIS standard harmonization with ISO 26262 to preserve export pathways for domestic suppliers. South Korea's MFDS alignment with UNECE WP.29 cybersecurity regulations shapes product development roadmaps for sensor data encryption modules. Stakeholders must monitor which regulatory convergence path between Chinese national standards and UNECE frameworks gains ASEAN adoption momentum.
Market Dynamics
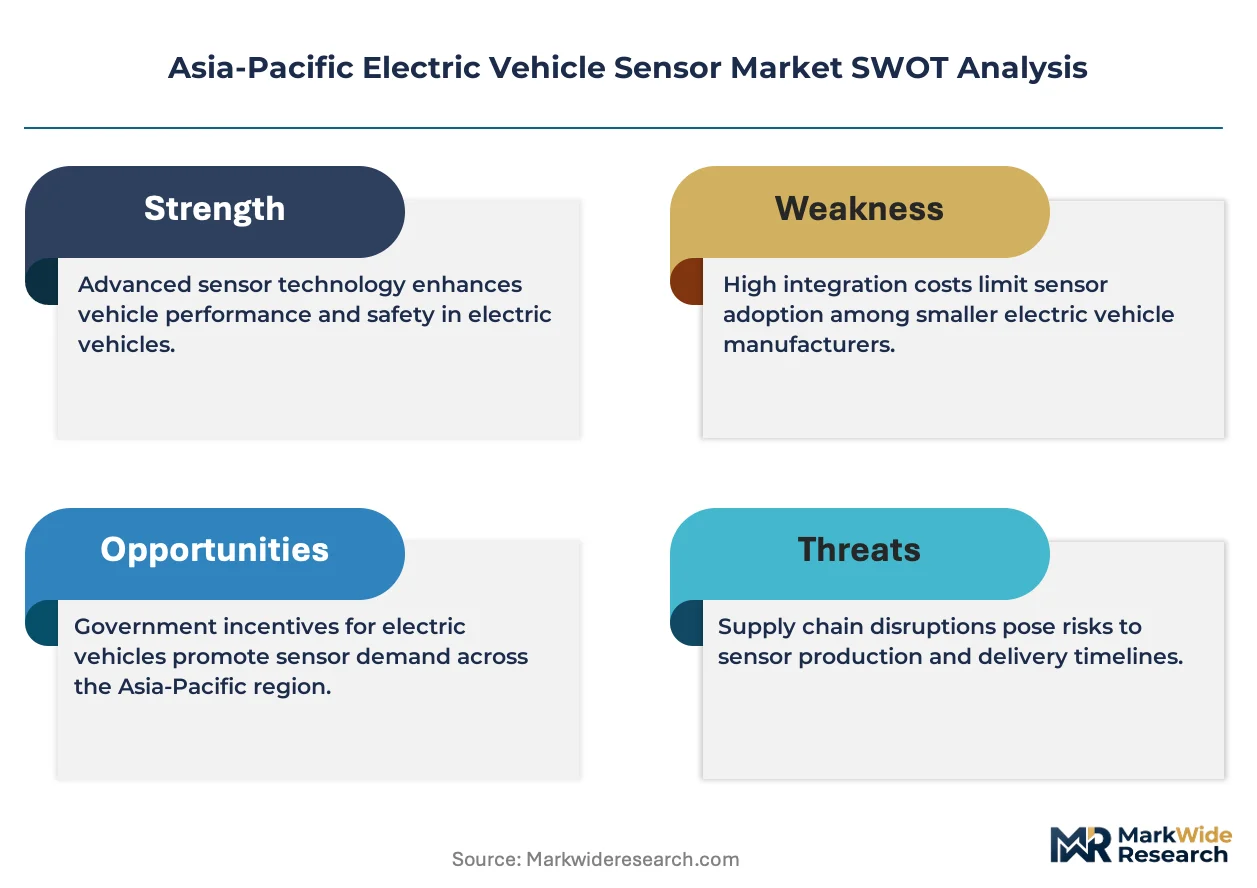
China's MIIT safety mandates for new energy vehicles are compressing supplier qualification timelines while accelerating LiDAR and radar integration into production lines. This regulatory pressure concentrates procurement decisions among ASIL-D certified Tier-1 suppliers capable of validating sensors across temperature extremes and electromagnetic interference conditions.
Growth Catalysts
- MIIT GB/T electromagnetic compatibility mandates:China's enforcement of stringent EMC standards for new energy vehicles filters out non-compliant imports, creating captive demand for domestically certified sensor modules.
- Robotaxi fleet scaling:Commercial autonomous vehicle deployments in Shenzhen and Beijing generate volume orders for solid-state LiDAR units with embedded edge-processing ASICs.
- Yangtze River Delta manufacturing co-location:Tier-1 suppliers clustering near EV assembly plants in Shanghai, Suzhou, and Ningbo compress logistics costs and enable just-in-time sensor module delivery.
Market Restraints
- ASIL-D certification capital intensity:Functional safety validation cycles require dedicated semiconductor fabrication capacity that excludes mid-tier sensor vendors from OEM qualification lists.
- Raw material concentration:Rare earth element processing for magnet-based position sensors concentrates in China's Inner Mongolia region, exposing supply chains to single-source geopolitical risk.
- IP6K9K sealing technical ceiling:Current polymer housing materials face thermal degradation beyond 150°C operating limits, constraining sensor placement near high-density battery packs.
Strategic Opportunities
- Thailand and Indonesia EV manufacturing incentives:ASEAN governments offering tax holidays for local sensor module production attract Chinese Tier-1 suppliers seeking tariff diversification.
- Camera-LiDAR sensor fusion architectures:Integrated perception stacks reducing ECU count present white space for software-defined sensor platforms in Chinese startup EV brands.
- South Korea MFDS cybersecurity alignment:UNECE WP.29 data encryption requirements for sensor telemetry create premium positioning for hardware-security-module-embedded devices.
Industry Challenges
- Functional safety engineer scarcity:ASIL-D certified firmware developers command compensation premiums that strain R&D budgets across Japanese and Korean sensor divisions.
- CAN bus bandwidth bottlenecks:Legacy vehicle network architectures require expensive gateway ECU retrofits to accommodate high-resolution surround-view camera data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Electric Vehicle Sensor Market |
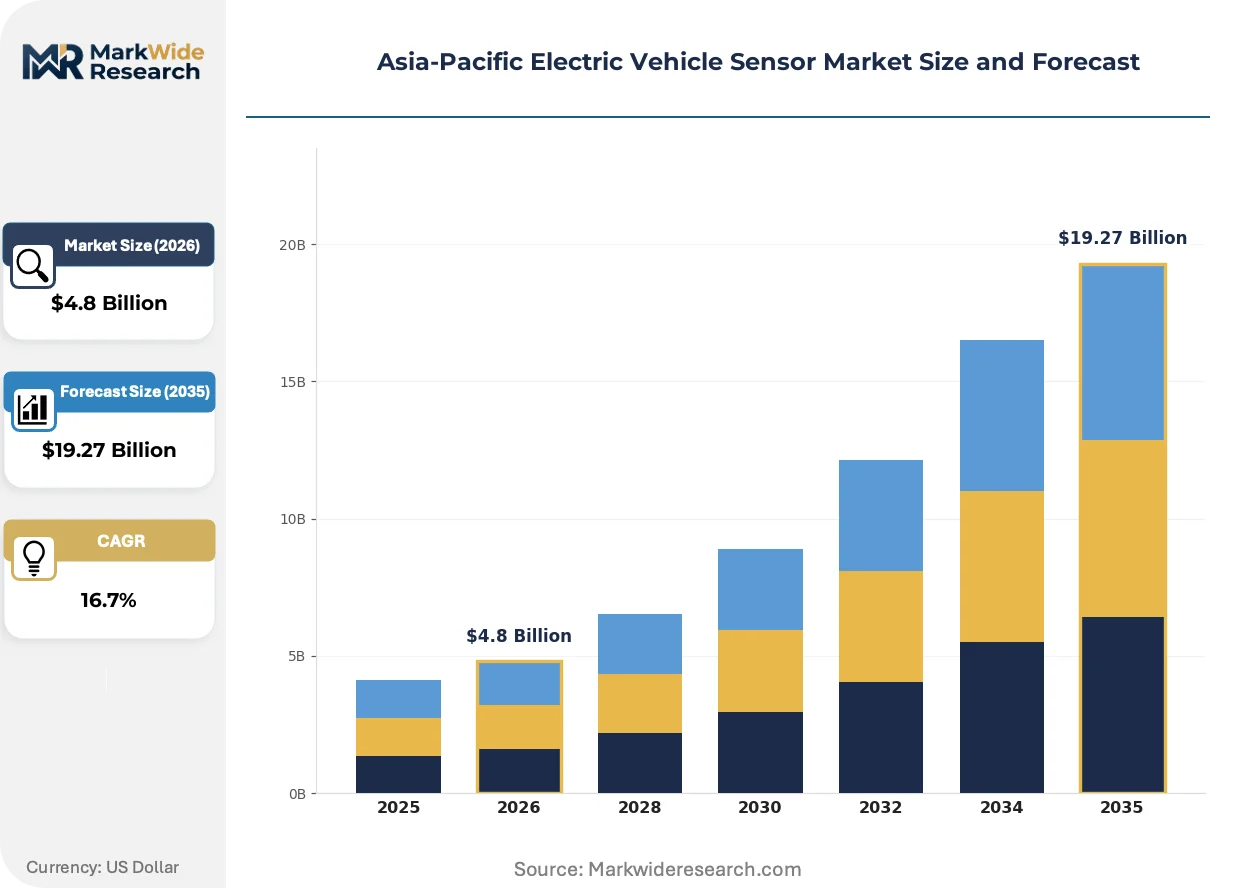
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Sensors, LiDAR Sensors, Camera Systems, Ultrasonic Sensors Application: Autonomous Driving, Advanced Driver Assistance Systems, Fleet Management, Vehicle Safety End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Technology: Active Sensors, Passive Sensors, Smart Sensors, Networked Sensors |
| Companies Covered | Bosch, Continental, Denso Corporation, NXP Semiconductors, Melexis, Valeo, Renesas Electronics, Panasonic, Nanjing Shihua Sensor, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Electric Vehicle Sensor Market Evolving Landscape
Solid-state LiDAR architectures are compressing unit economics while forcing incumbent electromechanical scanning systems into niche applications. Three concurrent developments are restructuring competitive positioning across the Asia-Pacific sensor value chain.
Photonic integrated circuit-based LiDAR is fragmenting the perception hardware landscape. These chip-scale devices eliminate rotating mechanical assemblies while maintaining 200-meter ranging capability. Chinese EV startups in Guangzhou and Hangzhou are qualifying solid-state units for highway pilot-assist systems. The technology is fragmenting procurement patterns as OEMs bypass traditional mechanical LiDAR suppliers for fabless semiconductor partnerships.
METI's coordination of JIS-ISO 26262 harmonization is preserving export pathways for Japanese sensor manufacturers. The alignment reduces redundant certification costs for temperature-hardened modules destined for European OEM supply chains. Hybrid powertrain platforms in Toyota and Honda vehicle lines represent the primary beneficiaries, as dual-standard compliance becomes a procurement prerequisite for Tier-1 contracts.
Direct sensor-to-cloud telemetry architectures are displacing gateway-mediated data flows in premium EV segments. Chinese robotaxi operators in Beijing demand raw perception feeds for fleet-wide algorithm training, bypassing traditional vehicle ECU aggregation. This pattern concentrates in Baidu Apollo and Pony.ai deployment zones, where edge-cloud hybrid processing reduces onboard compute costs while expanding data monetization scope.
Asia-Pacific Electric Vehicle Sensor Market Segmentation
Sensor procurement channels in the Asia-Pacific EV ecosystem diverge sharply by certification burden and integration depth. OEMs with captive semiconductor fabrication favor direct sourcing of ASIL-D modules, while Chinese startups route through Tier-1 integrators to compress validation timelines.
Product Type:
Channel mix splits between direct OEM procurement for perception stacks and Tier-1 bundling for powertrain monitoring modules.
- Camera Systems:Surround-view arrays with 8-megapixel resolution and IP6K9K sealing dominate mid-range Chinese EV configurations. Procurement concentrates in the Yangtze River Delta manufacturing cluster where module suppliers co-locate with vehicle assembly plants to enable just-in-time delivery for BYD and NIO production lines.
- LiDAR Sensors:Solid-state photonic integrated circuit architectures are displacing electromechanical scanning units in robotaxi deployments. Shenzhen and Beijing fleet operators generate volume orders for units with embedded edge-processing ASICs that reduce CAN bus bandwidth loads.
- Radar Sensors:77GHz front-collision warning modules with ASIL-D functional safety certification filter procurement toward Bosch and Continental captive fabrication facilities.
- Ultrasonic Sensors:Park-assist arrays with temperature-hardened polymer housings serve hybrid platforms from Toyota and Honda supply chains.
By volume, Camera Systems leads. By growth pace, LiDAR Sensors is ahead.
Application:
Cost tier stratification separates premium robotaxi perception stacks from economy-grade driver assistance bundles.
- Autonomous Driving:Highway pilot-assist systems in Guangzhou and Hangzhou EV startups demand fused LiDAR-camera-radar perception with redundant sensor paths. MIIT GB/T electromagnetic compatibility mandates filter out non-compliant imports, creating captive demand for domestically certified module architectures.
- Advanced Driver Assistance Systems:Lane-keeping and adaptive cruise control modules represent the volume base across mass-market Chinese EVs. Procurement flows through Tier-1 suppliers Denso and Bosch with established ASIL-D validation pipelines.
- Fleet Management:Telemetry-integrated position and pressure sensors enable predictive maintenance for commercial electric van operators in South Korea.
- Vehicle Safety:Battery thermal runaway detection modules with 150°C operating limits serve high-density pack architectures from CATL and BYD.
Advanced Driver Assistance Systems captures the largest installed base. Autonomous Driving commands the steepest expansion trajectory.
End User:
Customer type determines certification depth, with OEMs demanding full ASIL-D traceability and aftermarket providers accepting lower-tier validation.
- OEMs:Vertical integration into captive semiconductor fabrication enables margin control across radar and ultrasonic portfolios for BYD, Toyota, and Hyundai Motor Group.
- Tier-1 Suppliers:Denso Corporation anchors Japanese OEM supply chains with temperature-hardened modules for hybrid platforms. Continental competes through integrated LiDAR-camera fusion systems that reduce ECU count for Chinese EV startups.
- Fleet Operators:Baidu Apollo and Pony.ai robotaxi deployments in Beijing demand raw perception feeds for fleet-wide algorithm training, bypassing traditional vehicle ECU aggregation.
- Aftermarket Providers:Retrofit surround-view systems for legacy internal combustion fleets concentrate in Thailand and Indonesia conversion workshops.
Tier-1 Suppliers move the highest unit volumes. Fleet Operators are expanding most quickly.
Technology:
Maturity curves separate established electromechanical architectures from emerging solid-state and edge-computing platforms.
- Smart Sensors:ASIC-embedded devices with onboard signal processing reduce gateway ECU bandwidth requirements for autonomous driving architectures. Chinese robotaxi operators in Beijing and Shenzhen specify these units for direct sensor-to-cloud telemetry pipelines.
- Active Sensors:Radar and LiDAR units with emitted signal processing enable 200-meter ranging capability for highway pilot-assist systems.
- Networked Sensors:CAN-FD and Ethernet-connected modules support over-the-air calibration updates for fleet-managed commercial EVs.
- Passive Sensors:Temperature and position transducers without onboard processing serve cost-sensitive powertrain monitoring applications.
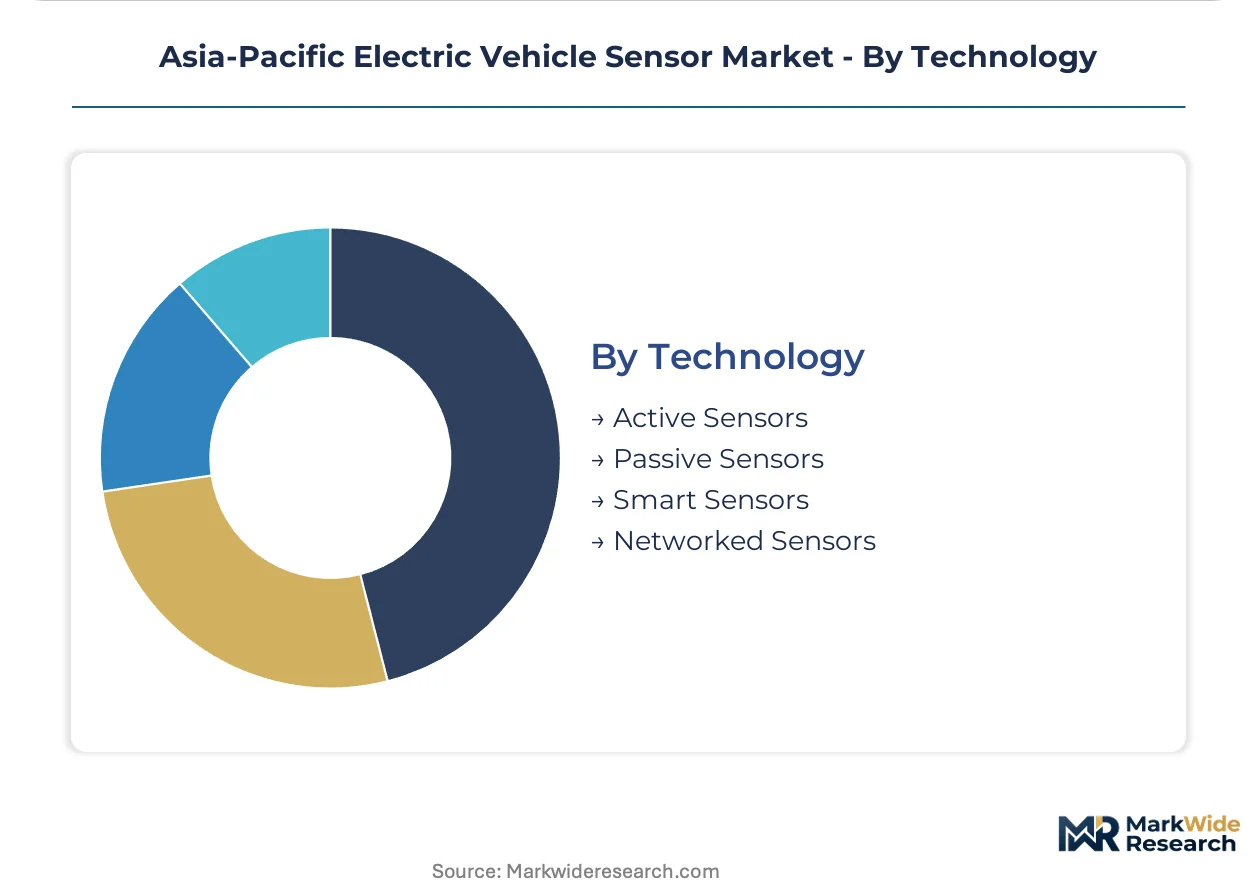
Active Sensors maintains the largest installed footprint. Smart Sensors is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia-Pacific's electric vehicle sensor trade flows reflect divergent national strategies for import substitution versus export platform development. China's dominance in domestic certification creates captive procurement pools, while Japan and South Korea pursue dual-standard compliance to preserve European market access. Southeast Asian manufacturing incentives are redirecting supplier investment toward Thailand and Indonesia assembly corridors.
China
MIIT GB/T electromagnetic compatibility mandates filter non-compliant sensor imports, creating protected demand for domestically certified LiDAR and radar modules. The Yangtze River Delta manufacturing cluster concentrates Tier-1 supplier facilities in Shanghai, Suzhou, and Ningbo to enable just-in-time delivery for BYD and NIO production lines. Shenzhen and Beijing robotaxi fleets generate volume orders for solid-state LiDAR with embedded edge-processing ASICs.
Japan
METI coordinates JIS-ISO 26262 harmonization to reduce redundant certification costs for temperature-hardened sensor modules bound for European OEM supply chains. Toyota and Honda hybrid platforms anchor procurement for Denso Corporation's dual-standard compliant architectures. The Chubu-Nagoya industrial corridor houses precision fabrication facilities serving both domestic automakers and export contracts.
South Korea
MFDS alignment with UNECE WP.29 cybersecurity regulations shapes hardware-security-module development for sensor data encryption in Hyundai Motor Group supply chains. Seoul Capital Area R&D centers concentrate firmware engineering talent for ASIL-D certified autonomous driving stacks. Busan-Ulsan manufacturing zones export radar and camera modules to ASEAN EV assembly plants.
Thailand
Board of Investment tax holidays for local sensor module production attract Chinese Tier-1 suppliers seeking tariff diversification away from direct China-origin exports. Eastern Economic Corridor EV manufacturing zones near Rayong and Chonburi host incoming supplier co-location investments. Domestic content requirements for government fleet procurement accelerate module assembly localization.
Indonesia
Ministry of Industry local content regulations for electric vehicle incentive eligibility drive joint venture formation between Chinese sensor suppliers and domestic automotive component manufacturers. Java-based industrial estates in Bekasi and Karawang receive initial module assembly investments. Nickel processing concentration in Sulawesi and Maluku creates upstream material access for magnet-based position sensor production.
Asia-Pacific Electric Vehicle Sensor Market Competitive Landscape
Concentration sits with diversified automotive electronics conglomerates possessing captive semiconductor fabrication and ASIL-D validation pipelines. Three to five capital-intensive firms control premium perception stack procurement through integrated LiDAR-camera-radar portfolios. Competitive moves center on backward integration into wafer processing and strategic partnerships with Chinese EV startups for software-defined sensor platform co-development. Geographic expansion into ASEAN manufacturing zones represents the secondary vector for tariff diversification and local content compliance.
Among diversified automotive electronics conglomerates, Bosch and Continental exemplify the capital-intensive archetype with in-house semiconductor fabrication sustaining margin control across radar and ultrasonic portfolios. Denso Corporation anchors the Japanese OEM supply chain tier through temperature-hardened module specialization. Within the Chinese domestic supplier vector, Nanjing Shihua Sensor occupies a position representing emerging national champions serving MIIT-certified procurement pools. These three archetypes—European diversified conglomerates, Japanese hybrid-platform specialists, and Chinese domestic champions—structure competitive positioning across certification tiers and geographic markets.
| Leading Market Players |
|---|
| Bosch |
| Continental |
| Denso Corporation |
| NXP Semiconductors |
| Melexis |
| Valeo |
| Renesas Electronics |
| Panasonic |
| Nanjing Shihua Sensor |
| Others |
Value Network & Pricing Analysis
Sixty-day ASIL-D validation cycles compress procurement windows while amplifying pricing power for certified Tier-1 suppliers. This lead-time constraint concentrates sensor module sourcing decisions around Yangtze River Delta fabrication clusters, where geographic proximity to EV assembly plants enables premium capture for just-in-time delivery.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. ASIL-D certification grade and volume scale drive price differentiation, with robotaxi fleet operators commanding discounts through multi-year offtake commitments. Cost compression in mid-range camera modules is intensifying because Chinese startups are bypassing Tier-1 integrators for direct fabless partnerships. Aftermarket retrofit providers exhibit highest price sensitivity, while autonomous driving stack developers prioritize performance over unit economics.
Supply Chain Analysis
Forty-five-day raw material inventory buffers in Shanghai and Suzhou expose procurement to rare earth element supply interruptions. Magnet-based position sensor production draws from China's Inner Mongolia processing corridor, South Korean semiconductor wafer output, and Japanese precision polymer resin supply. Single-source vulnerability concentrates in terbium and dysprosium extraction, where geopolitical friction threatens input cost stability. Distribution runs through Tier-1 bundlers for powertrain modules and direct OEM channels for perception stacks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASIL-D firmware engineering talent scarcity constrains expansion timelines for all competitive positions, with certified developers commanding compensation premiums that reshape capital allocation priorities across Japanese and Korean sensor divisions.
For Market Incumbents: Consolidate backward integration into captive semiconductor fabrication to defend margin control against fabless LiDAR entrants. Expand ASIL-D validation pipeline capacity in Yangtze River Delta corridors to capture robotaxi fleet procurement. Lock in multi-year rare earth element supply agreements before geopolitical friction intensifies input cost volatility. For New Entrants and Emerging Players: Anchor in Thailand's Eastern Economic Corridor manufacturing zones to exploit tax holidays and local content requirements for government fleet procurement. Target aftermarket retrofit segments in Indonesia's conversion workshops where certification burdens relax and price sensitivity dominates. Pursue software-defined sensor platform partnerships with Chinese EV startups seeking ECU reduction architectures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state LiDAR sub-segments as photonic integrated circuit fabrication demands wafer-scale investments. Five-to-ten-year viability favors diversified automotive electronics conglomerates with established OEM qualification pipelines over pure-play perception hardware specialists. Monitor MIIT GB/T standard revision announcements as inflection indicators for domestic supplier preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Pipeline Expansion | MIIT GB/T compliance mandates filter procurement toward validated Tier-1 suppliers with proven temperature-hardened modules. |
| Rare Earth Element Supply Agreement | Inner Mongolia processing concentration creates geopolitical exposure that long-term offtake contracts can mitigate. |
| Thailand Manufacturing Footprint | Board of Investment tax holidays enable tariff diversification for Chinese Tier-1 suppliers serving ASEAN EV assembly. |
| Software-Defined Sensor Platform | Integrated LiDAR-camera fusion reduces ECU count for Chinese startup brands seeking simplified architectures. |
| Direct Sensor-to-Cloud Telemetry | Baidu Apollo and Pony.ai deployments demand raw perception feeds bypassing traditional vehicle gateway aggregation. |
Research Methodology
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and MIIT regulatory affairs specialists provided ongoing calibration throughout the study period. Primary interview findings combined with secondary validation from vehicle production databases, customs and trade flow records, IHS Markit registration data, and GB/T standard documentation. Bottom-up sensor unit demand estimates triangulated against top-down EV production forecasts across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including regional EV sales trajectories and sensor content-per-vehicle assumptions. The analytical framework modeled segmentation dimensions spanning propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from fitted growth curves calibrated to historical adoption patterns and regulatory mandate implementation timelines. Forecast inputs incorporated MIIT safety standard phase-in schedules and robotaxi fleet deployment announcements.
Decision-makers should treat outputs as directional under assumptions of continued MIIT enforcement intensity and stable rare earth element supply; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Exhaust Sensors Market
Sensors and Controls
Shutter Sensors Market
Sensors and Controls
Condition Monitoring System Market
Sensors and Controls
Non-Glass Capacitive Sensors Market
Sensors and Controls
Voltage Sensor Market
Sensors and Controls
Touchless Sensing Market
Sensors and Controls
Consumer Grade Electrochemical CO Sensor Market
Sensors and Controls
Smart Level Probe Market
Sensors and Controls
Global Industrial Temperature Controller Market
Sensors and Controls
France Air Purifier Market
Sensors and Controls
Europe Bulk Acoustic Wave Sensors Market
Sensors and Controls
Marine Sensors Market
Sensors and Controls
Europe Optical Sensors Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
Global Hall Effect Current Sensor Market