
 Global Digital Electronic Thermometers Market | 2026-2036
Global Digital Electronic Thermometers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Electronic Thermometers Market Foresight
The EU MDR is expanding compliance burdens for temperature device manufacturers entering European hospital supply chains. Omron Corporation leverages its Japanese manufacturing base to sustain cost advantages in thermistor-based clinical units. Medline Industries anchors North American hospital procurement through direct distribution contracts. Testo SE competes in industrial crossover segments where precision specifications overlap with pharmaceutical lab requirements.
Digital electronic thermometers measure body or surface temperature through thermistors, infrared sensors, or resistance temperature detectors converting thermal data into digital readouts with typical accuracy ranges of ±0.1°C to ±0.2°C. These devices serve diagnostic monitoring, fever screening, and controlled environment validation across healthcare and industrial settings. Infrared thermometers lead hospital procurement volumes due to non-contact speed and hygiene protocols, while thermistor-based clinical units dominate home care channels where price sensitivity shapes purchasing. Resistance temperature detector variants occupy pharmaceutical lab niches demanding highest precision for compound stability testing.
FDA device classification rules govern accuracy claims and 510(k) clearance pathways for clinical thermometers sold in the United States. The EU MDR and CE marking requirements enforce biocompatibility and electromagnetic compatibility standards across European Economic Area markets. ISO 80601-2-56 specifies clinical thermometer performance testing globally. Stakeholders must monitor evolving cybersecurity guidance for connected temperature devices as Bluetooth-enabled units penetrate home care and remote patient monitoring workflows.
Market Dynamics
Hospital procurement consolidation in the United States is compressing vendor margins while infrared sensor miniaturization opens new point-of-care applications. Japanese and German aging demographics are pulling thermistor-based units into home care channels faster than clinical replacement cycles.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for infrared clinical thermometers are expanding hospital vendor pools in the United States. Device manufacturers leverage predicate device databases to compress regulatory lead times.
- Japan's super-aged society:Home care thermistor demand among adults over 75 is outpacing clinical unit procurement. METI guidelines on self-monitoring devices reinforce this channel shift.
- Infrared sensor cost curves:MEMS-based thermal arrays from semiconductor foundries in Taiwan are reducing bill-of-materials for non-contact units. Hospital infection control protocols favor these sensors for triage throughput.
Market Restraints
- Indium antimonide supply concentration:Infrared detector materials depend on Chinese rare earth processing and Ukrainian indium refining. Geopolitical friction creates input cost volatility for precision sensor manufacturers.
- EU MDR technical documentation burdens:Clinical thermometer notified body reviews now average 18-24 months versus 6-9 months under previous directives. Small manufacturers face capital barriers to European market entry.
- Smartphone temperature app substitution:Consumer-grade fever estimation via thermal camera accessories and algorithmic proxies threatens basic digital thermometer price tiers in home care channels.
Strategic Opportunities
- India's Ayushman Bharat expansion:Primary health center digitization mandates create procurement volume for clinical-grade infrared units. CDSCO streamlined medical device rules reduce import registration friction.
- Bluetooth Low Energy convergence with RPM platforms:Continuous temperature monitoring for oncology and post-surgical patients enables recurring revenue models. Kaiser Permanente and NHS trusts pilot these integrations.
- German pharmacy e-prescription infrastructure:Electronic health record connectivity requirements favor connected thermometer bundling with chronic disease management programs. Apotheken mandate digital device interoperability by 2025.
Industry Challenges
- IEC 62304 software lifecycle certification:Connected thermometer firmware validation for cybersecurity resilience extends development timelines. Engineering teams lack embedded security expertise at mid-tier manufacturers.
- ISO 17025 calibration laboratory capacity:Clinical accuracy traceability requirements outpace accredited testing infrastructure in Brazil and Southeast Asia. Manufacturers face bottlenecks in market entry documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Electronic Thermometers Market |
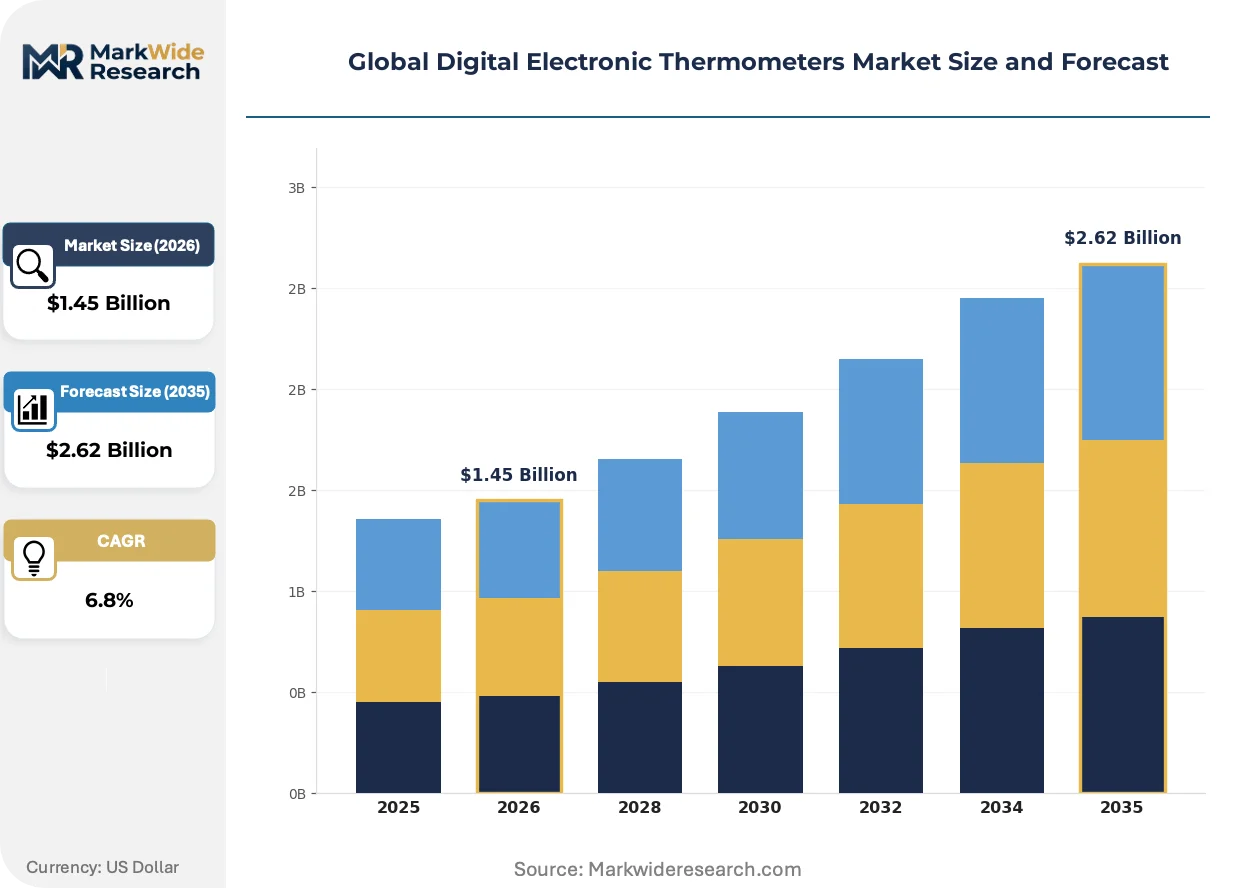
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Thermometers, Infrared Thermometers, Pacifier Thermometers, Ear Thermometers, Forehead Thermometers Technology: Thermistor-Based, Infrared Sensor, Digital Liquid Crystal, Thermocouple, Resistance Temperature Detector Application: Home Care, Pharmaceutical Labs, Veterinary Clinics, Sports Medicine, Research Facilities End User: Hospitals, Diagnostic Centers, Nursing Homes, Pediatric Clinics, Geriatric Centers |
| Companies Covered | Omron Corporation, Terumo Corporation, 3M Company, Medline Industries, Fluke Corporation, Testo SE, Microlife Corporation, Exergen Corporation, Beurer GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Electronic Thermometers Market Shifts & Advancements
Sensor fusion architectures are redefining thermometer functionality beyond single-point temperature capture. Regulatory convergence around cybersecurity and interoperability is reshaping product development roadmaps.
Multi-spectral infrared arrays is integrating thermal imaging with ambient light compensation for forehead measurement accuracy across skin tones. Hospital systems in the United States and United Kingdom are piloting these units in emergency departments to reduce measurement bias. The technology is integrating patient identification workflows through embedded NFC readers, compressing triage data entry steps.
EU MDR post-market surveillance requirements now mandate periodic safety updates and clinical evidence reviews for all Class IIa temperature devices. Manufacturers must maintain European authorized representatives and vigilance systems regardless of production location. German hospital procurement consortiums are demanding MDR certificates as table stakes for tender participation, filtering out non-compliant vendors.
Direct-to-patient subscription models for fever monitoring kits are displacing traditional pharmacy retail in chronic condition management. Dexcom and Abbott continuous glucose monitoring users show willingness to adopt parallel temperature tracking for infection early warning. This pattern concentrates in United States Medicare Advantage plans and Dutch managed care contracts where remote monitoring incentives align reimbursement.
Global Digital Electronic Thermometers Market Segmentation
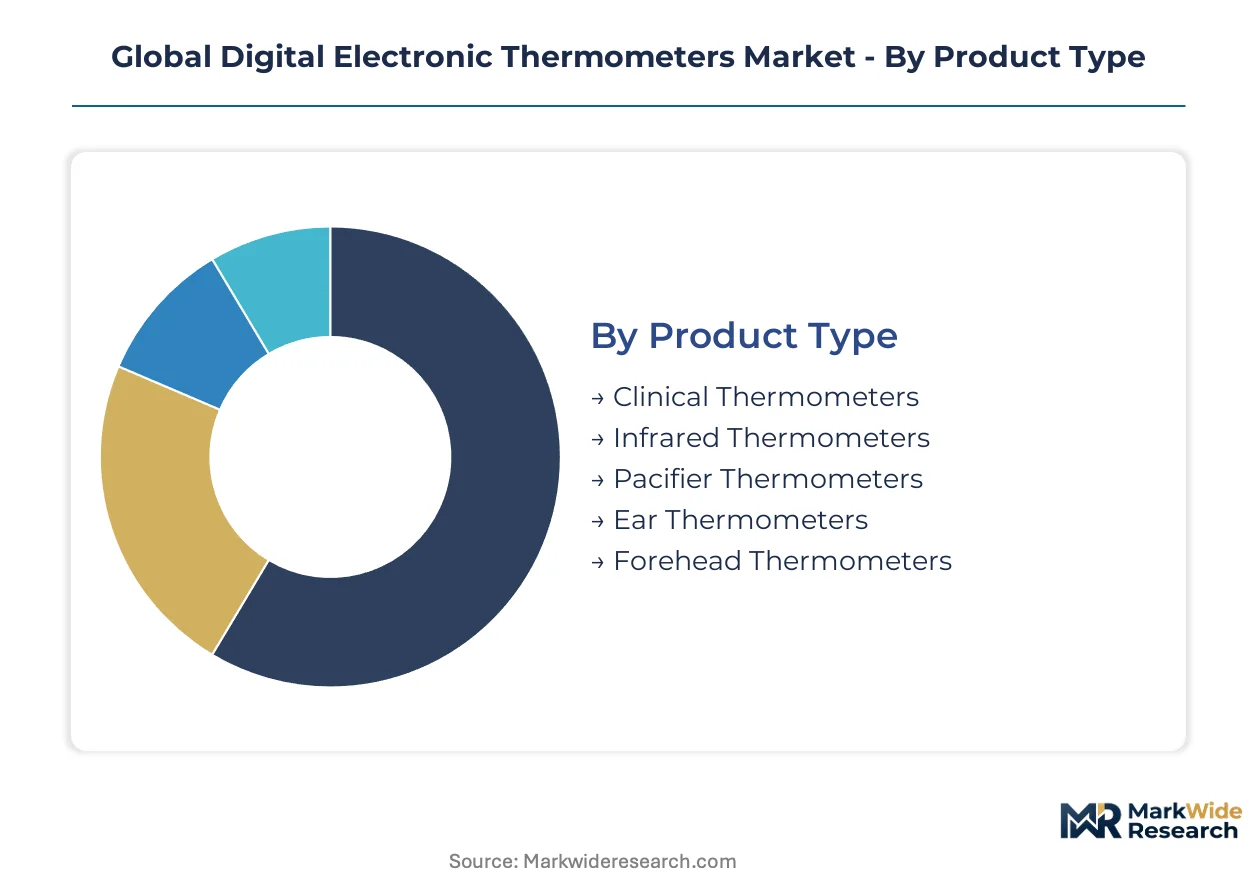
Digital electronic thermometers fragment across four intersecting dimensions that reshape procurement priorities and margin structures. Product type and technology choices determine regulatory pathways and sensor supply chains, while application and end-user specifications dictate accuracy requirements and connectivity features.
Product Type:
Volume concentrates in standardized clinical units, while premium pricing attaches to non-contact infrared formats with MEMS sensor arrays.
- Clinical Thermometers:Thermistor-based oral and axillary devices with ±0.1°C accuracy dominate home care channels in Japan and Germany. Hospital procurement in the United States treats these as commodity replacements with compressed margins.
- Infrared Thermometers:Non-contact forehead and temporal artery units with MEMS thermal sensors command infection control premiums in emergency departments. FDA 510(k) predicate databases accelerate clearance for manufacturers targeting United States hospital vendor pools.
- Pacifier Thermometers:Pediatric-focused thermistor designs integrate comfort features for infant home monitoring in European pharmacy retail.
- Ear Thermometers:Tympanic infrared units with disposable probe covers balance speed and hygiene in United States pediatric clinics.
- Forehead Thermometers:Strip-style liquid crystal variants serve price-sensitive home care segments in emerging markets with minimal regulatory barriers.
Today's leader: Clinical Thermometers. Tomorrow's challenger: Infrared Thermometers.
Technology:
Cost tier separation runs from precision laboratory standards to disposable consumer formats, with semiconductor foundry partnerships determining competitive positioning.
- Thermistor-Based:Ceramic semiconductor beads with negative temperature coefficient dominate home care manufacturing in Japan. METI self-monitoring guidelines reinforce demand for these cost-optimized units among adults over 75.
- Infrared Sensor:MEMS thermal arrays from Taiwan foundries reduce bill-of-materials for non-contact hospital units. Geopolitical friction around indium antimonide supply from Chinese rare earth processing creates input volatility.
- Digital Liquid Crystal:Passive display thermometers serve single-use clinical environments with minimal power requirements.
- Thermocouple:Junction-based sensors with rapid response times occupy industrial crossover applications requiring wide temperature ranges.
- Resistance Temperature Detector:Platinum wire wound elements deliver ±0.01°C precision for pharmaceutical compound stability testing in German and Swiss laboratory networks.
Thermistor-Based technology holds current volume leadership. Infrared Sensor architectures are gaining share fastest in hospital procurement.
Application:
Customer type stratifies between reimbursed clinical workflows and out-of-pocket consumer purchases, with connectivity requirements diverging sharply.
- Home Care:Bluetooth-enabled fever tracking for chronic condition management concentrates in United States Medicare Advantage plans. Dexcom and Abbott CGM user willingness to adopt parallel temperature monitoring enables subscription revenue models.
- Pharmaceutical Labs:ISO 17025 traceability requirements for batch release documentation favor resistance temperature detector precision in Swiss and German manufacturing sites.
- Veterinary Clinics:Large-animal rectal thermometers with reinforced probes serve agricultural veterinary networks in Australia and Brazil.
- Sports Medicine:Core temperature monitoring for heat illness prevention targets elite athletic programs in the United States and United Kingdom.
- Research Facilities:Multi-point thermal mapping for protocol validation demands calibrated sensor arrays in academic medical centers.
Home Care commands present volume. Pharmaceutical Labs offer the steepest expansion trajectory on precision requirements.
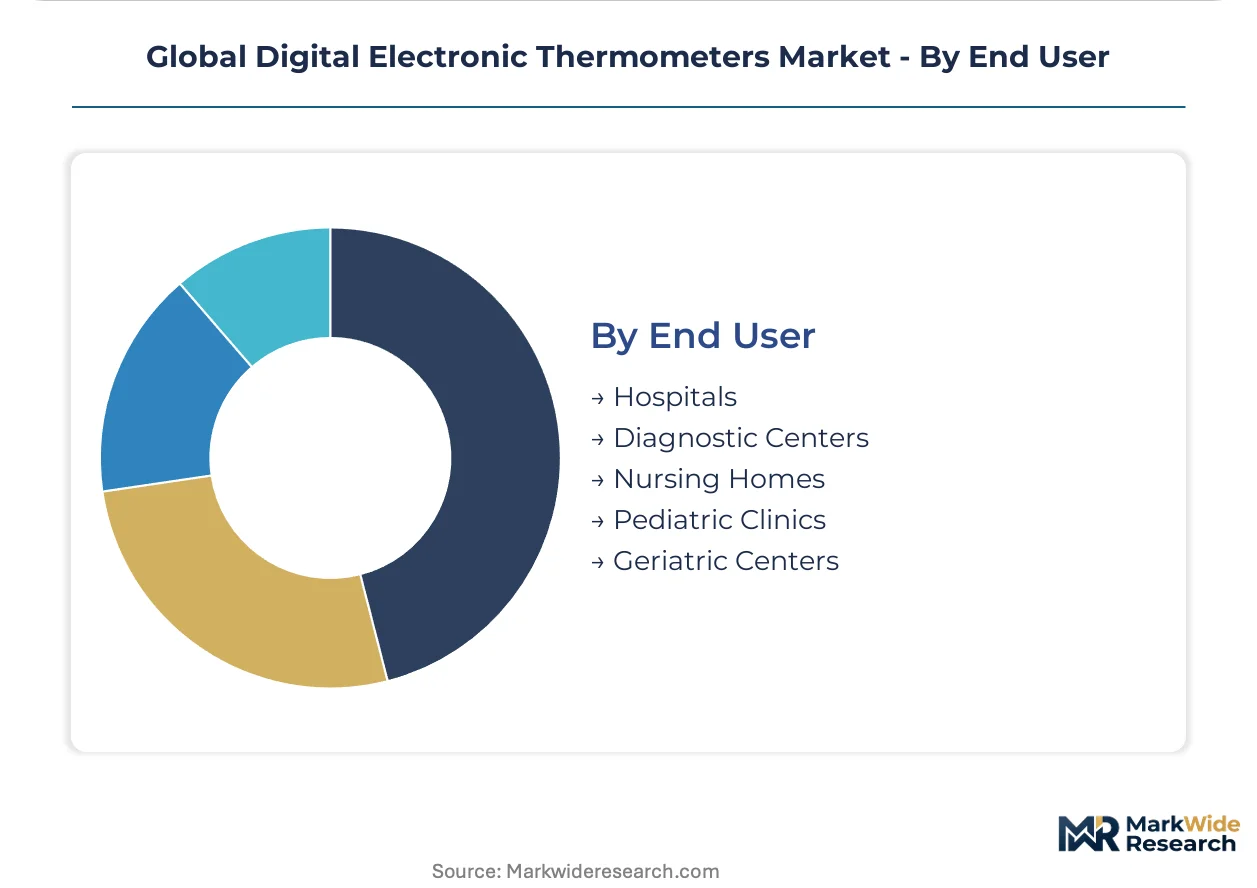
End User:
Procurement consolidation patterns split between integrated health systems with vendor reduction mandates and fragmented independent practices with price sensitivity.
- Hospitals:Infrared triage units with NFC patient identification compress emergency department throughput in United States health systems. Kaiser Permanente pilots Bluetooth Low Energy integration with remote patient monitoring platforms.
- Diagnostic Centers:High-throughput fever screening for occupational health contracts favors non-contact formats in German industrial regions.
- Nursing Homes:Staff efficiency priorities drive demand for rapid-scan infrared units in Japanese elder care facilities.
- Pediatric Clinics:Parent reassurance features and disposable hygiene protocols shape ear and forehead thermometer selection.
- Geriatric Centers:Medication interaction monitoring for infection early warning creates connected thermometer demand in Dutch managed care contracts.
Hospitals anchor current procurement value. Nursing Homes are climbing the fastest on aging demographic tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Digital electronic thermometer manufacturing traces its industrial roots to post-war Japan's precision instrument sector, later diversifying across German sensor engineering and Taiwanese semiconductor foundries. The contemporary market distributes value across distinct national healthcare procurement systems and regulatory environments.
United States
Hospital procurement consolidation drives infrared triage unit demand through Kaiser Permanente and other integrated health systems. FDA 510(k) pathway streamlining accelerates clearance timelines for predicate device filings. Boston and Minneapolis medical device clusters concentrate engineering talent for connected thermometer firmware development.
Germany
Apotheken e-prescription mandates pull Bluetooth-enabled thermometers into chronic disease management programs by 2025. EU MDR technical documentation burdens extend notified body reviews to 18-24 months. Baden-Württemberg precision engineering networks supply resistance temperature detector components for pharmaceutical laboratory applications.
Japan
Adults over 75 propel thermistor-based home care demand faster than clinical replacement cycles. METI self-monitoring device guidelines reinforce this channel shift. Kanto region manufacturing bases sustain Omron Corporation's cost advantages in ceramic semiconductor bead production.
India
Ayushman Bharat primary health center digitization creates procurement volume for clinical-grade infrared units. CDSCO streamlined medical device rules reduce import registration friction. Maharashtra and Karnataka pharmaceutical manufacturing corridors generate laboratory precision thermometer demand for batch release documentation.
China
MEMS thermal array foundries in Taiwan reduce bill-of-materials for non-contact units destined for export markets. Rare earth processing concentration for indium antimonide creates input cost volatility for precision sensor manufacturers. Yangtze River Delta electronics clusters integrate infrared detector assembly for hospital infection control protocols.
Global Digital Electronic Thermometers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the thermometer value chain. Foundry-dependent sensor manufacturers face margin pressure from semiconductor cost curves while clinical brand owners capture infection control premiums. Three archetypes dominate: Japanese precision instrument conglomerates with captive manufacturing, German industrial measurement specialists with laboratory crossover capabilities, and North American hospital supply distributors with procurement consolidation leverage. Competitive moves concentrate on MEMS sensor partnerships and MDR compliance certification racing.
Within the precision instrument tier, Omron Corporation and Terumo Corporation represent Japanese manufacturing scale advantages in thermistor-based clinical units. Beurer GmbH occupies a position among German consumer health device specialists navigating pharmacy retail channel shifts. Medline Industries anchors North American hospital procurement through direct distribution contract concentration.
| Leading Market Players |
|---|
| Omron Corporation |
| Terumo Corporation |
| 3M Company |
| Medline Industries |
| Fluke Corporation |
| Testo SE |
| Microlife Corporation |
| Exergen Corporation |
| Beurer GmbH |
| Others |
Supply & Pricing Matrix
MEMS thermal array miniaturization from Taiwanese semiconductor foundries is compressing bill-of-materials for non-contact units while simultaneously concentrating sensor supply among a handful of wafer fabrication facilities. This dual effect reshapes cost economics for infrared thermometer manufacturers and amplifies pricing power asymmetries between captive producers and fabless designers.
Pricing Analysis
Three-tier pricing structure across premium clinical-grade, standard professional, and economy consumer levels dominates procurement negotiations. Price differentiation hinges on FDA 510(k) clearance tier and ISO 80601-2-56 certification status, with uncertified units trading at steep discounts. Cost compression in the standard tier is intensifying because hospital procurement consolidation in the United States squeezes vendor margins. Home care channels show highest price sensitivity, while pharmaceutical laboratories demonstrate least sensitivity due to precision requirements.
Supply Chain Analysis
Indium antimonide supply rests on Chinese rare earth processing facilities and Ukrainian indium refining operations, creating geopolitical exposure for precision infrared detector manufacturers. Ceramic semiconductor beads for thermistor production draw from Japanese and German specialty material suppliers, while MEMS thermal arrays sources from Taiwan Semiconductor Manufacturing Company and United Microelectronics Corporation foundries. Single-source vulnerability around indium refining generates input cost volatility. Distribution runs through hospital GPO contracts in North America, pharmacy retail networks in Europe, and direct e-commerce channels in Asian home care markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital electronic thermometer market functions as a regulatory compounder where EU MDR technical documentation burdens and FDA 510(k) pathway requirements continuously elevate compliance costs for new entrants, entrenching incumbents with certified product portfolios.
For Market Incumbents: Deepen backward integration into MEMS thermal array sourcing through foundry partnerships or captive wafer capacity in Taiwan to defend against indium antimonide supply volatility. Reinforce hospital GPO contract concentration in the United States to repel emerging Asian manufacturers seeking FDA clearance, while accelerating MDR notified body certification renewals ahead of European tender participation deadlines. For New Entrants and Emerging Players: Capture India's Ayushman Bharat primary health center digitization procurement wave by leveraging CDSCO streamlined import registration rules before incumbent distributors establish local assembly operations. Target Bluetooth-enabled home care subscription models in Dutch managed care contracts and United States Medicare Advantage plans where reimbursement incentives align with remote patient monitoring platform integration. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier thermistor manufacturers lacking infrared sensor transition roadmaps and MDR compliance infrastructure. Long-term viability favors assets with dual FDA-EU regulatory certification, foundry partnerships for MEMS supply security, and software companion development capabilities for RPM platform convergence. Watch indium antimonide spot price movements and EU notified body queue lengths as inflection indicators for input cost pressure and market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Predicate device database leverage compresses clearance timelines for infrared clinical thermometers targeting United States hospital vendor pools. |
| EU MDR Notified Body Certification | Technical documentation preparation for Class IIa temperature devices enables tender participation in German hospital procurement consortiums. |
| MEMS Foundry Partnership | Taiwanese semiconductor fabrication agreements secure thermal array supply volumes and cost predictability for non-contact unit production. |
| Bluetooth Low Energy Platform Integration | Kaiser Permanente and NHS trust pilot programs validate recurring revenue models for continuous temperature monitoring in oncology workflows. |
| ISO 17025 Calibration Laboratory Accreditation | Traceability infrastructure investment removes market entry bottlenecks in Brazil and Southeast Asia certification documentation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs leads at device manufacturers with secondary validation against FDA 510(k) filings, EU MDR notified body certificates, hospital procurement databases, and ISO 80601-2-56 test reports. Bottom-up segment sizing and top-down macro constraint checks ensured cross-verification.
Historical reference periods anchored the projection horizon through documented replacement cycle patterns and regulatory implementation timelines. The analytical framework modeled product type, technology architecture, application setting, and end-user procurement channel dimensions across the forecast period. CAGRs derived from segment-level volume trajectories and value-per-unit trends, incorporating infrared sensor cost curve assumptions and MDR compliance cost pass-through estimates.
Geopolitical friction around indium supply, EU notified body capacity constraints, and smartphone thermal app substitution are the dominant revision risks to modeled demand. Forecasts reflect assumptions about regulatory timeline adherence and foundry capacity expansion. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Latin America Occupancy Sensors Market
Sensors and Controls
Capacitive Ceramic Pressure Sensors Market
Sensors and Controls
Global Industrial Temperature Controller Market
Sensors and Controls
Thermography Condition Monitoring Equipment Market
Sensors and Controls
Thermistor Temperature Sensor Market
Sensors and Controls
Reflective Encoder Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
Photodiode Sensors Market
Sensors and Controls
Digital Angle Gauge Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Middle-East and Africa Nanosensors Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Sensor Hub Market