
 Piezoelectric Sensor Market | 2026-2036
Piezoelectric Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Piezoelectric Sensor Market Outlook
Sensor-as-a-service and predictive maintenance contracts is expanding as a revenue layer that shifts hardware vendors toward recurring income models. TE Connectivity leverages its global distribution network to anchor long-term industrial service agreements. PCB Piezotronics specializes in high-frequency vibration monitoring for aerospace and defense end users. Kistler Group dominates force measurement applications through deep calibration expertise and Swiss manufacturing heritage.
A piezoelectric sensor converts mechanical stress into an electrical charge via crystalline materials such as quartz, lead zirconate titanate (PZT), or aluminum nitride, typically operating across frequency ranges from fractions of a hertz to megahertz for precision measurement tasks. Pressure sensors command the largest installed base across process industries where reliability under extreme temperatures determines procurement decisions. Acceleration sensors represent the fastest-expanding category as automotive OEMs integrate crash detection and structural health monitoring into electric vehicle platforms. Smart sensors are capturing margin pools through embedded signal processing and edge-computing capabilities that reduce downstream analytics costs.
NHTSA crashworthiness standards and the EU Green Deal's industrial emissions tracking requirements are tightening calibration and traceability mandates for sensor suppliers seeking market access. FDA 21 CFR Part 820 quality system regulations govern piezoelectric medical devices in the United States, while China's GB standards and MIIT directives shape certification pathways for components entering Asian manufacturing supply chains. Stakeholders must monitor how evolving cybersecurity frameworks for connected industrial equipment reshape sensor architecture requirements and supplier qualification timelines.
Market Dynamics
The electric vehicle powertrain transition is restructuring procurement patterns as automotive OEMs replace mechanical monitoring systems with solid-state piezoelectric architectures for real-time battery thermal and structural diagnostics.
Growth Catalysts
- EU Green Deal industrial emissions tracking:Manufacturing facilities across Germany and France must install continuous vibration monitoring for rotating equipment, mandating piezoelectric sensor deployment in process industries.
- Aluminum nitride thin-film deposition:MEMS-compatible piezoelectric layers enable wafer-scale manufacturing, cutting unit costs for consumer electronics and medical ultrasound applications.
- NHTSA crashworthiness mandates:Structural health monitoring requirements for electric vehicle battery enclosures drive accelerometer integration into chassis subassemblies.
Market Restraints
- Quartz crystal supply concentration:High-purity synthetic quartz production clusters in Japan and China, creating single-source vulnerability for precision sensor substrates.
- Lead zirconate titanate toxicity thresholds:REACH substance restrictions and RoHS exemptions for piezoelectric ceramics impose compliance costs and reformulation timelines.
- Capacitive MEMS displacement:Low-cost accelerometers for consumer electronics applications sacrifice precision for price, eroding addressable volume in non-critical sensing.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Component localization incentives attract sensor packaging and calibration investments serving domestic automotive and industrial markets.
- Edge-computing sensor fusion:Integration of piezoelectric transducers with onboard DSP architectures enables predictive maintenance at the measurement node, reducing cloud dependency.
- Swissmedic medical device certification pathways:Streamlined quality system recognition for force measurement in surgical robotics accelerates time-to-market for high-margin healthcare applications.
Industry Challenges
- Calibration technician scarcity:Precision force and pressure sensor validation requires specialized metrology expertise concentrated in German and Swiss technical institutes.
- IEC 60751 and IEEE 1451 compliance timelines:Smart transducer interface standard certification delays product launches by six to nine months for multi-protocol industrial networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Piezoelectric Sensor Market |
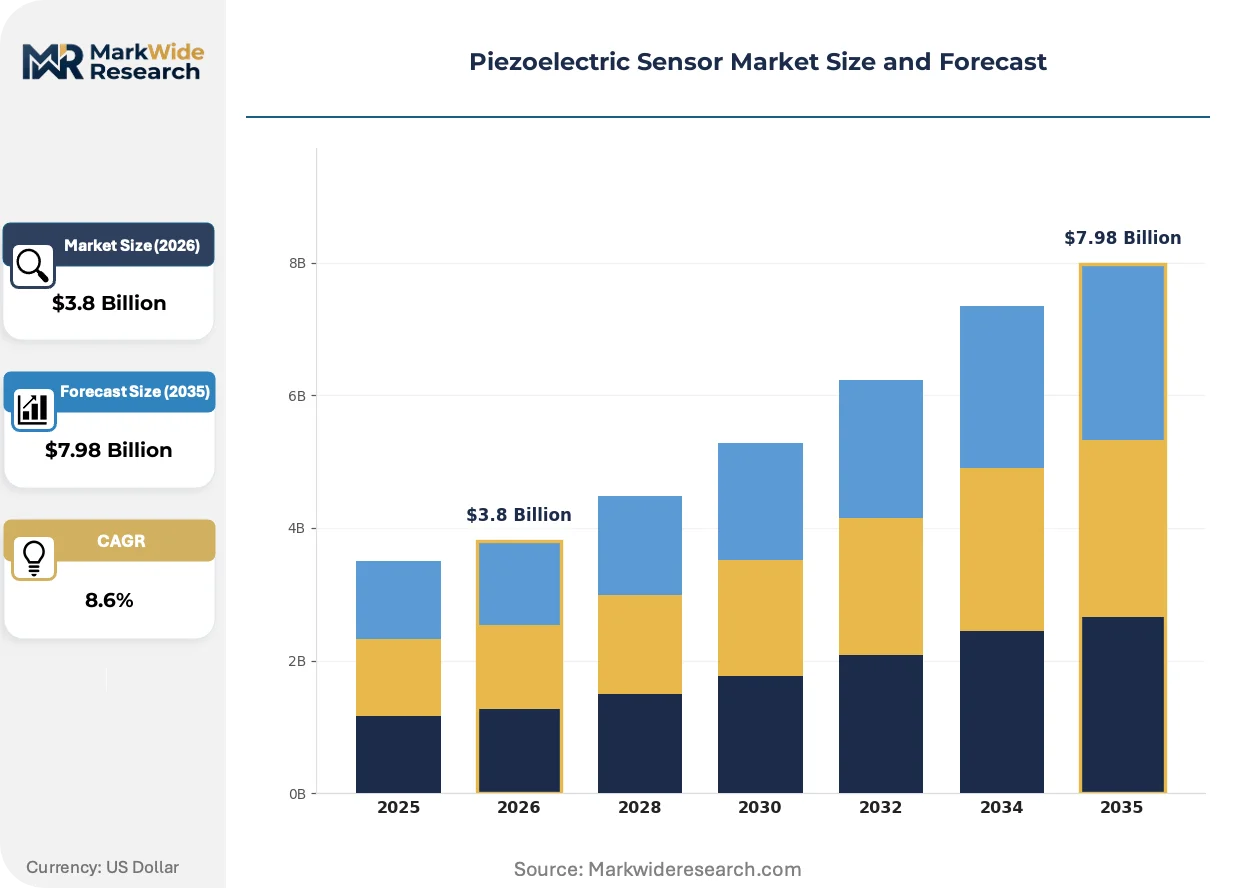
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Pressure Sensors, Acceleration Sensors, Force Sensors, Vibration Sensors Application: Industrial Automation, Consumer Electronics, Medical Devices, Automotive End User: Manufacturers, Healthcare Providers, Automotive OEMs, Aerospace Companies Technology: Active Sensors, Passive Sensors, Wireless Sensors, Smart Sensors |
| Companies Covered | TE Connectivity, APC International Ltd., Honeywell International Inc., Murata Manufacturing Co., Ltd., Morgan Advanced Materials, PCB Piezotronics, CeramTec GmbH, Physik Instrumente, Kistler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Piezoelectric Sensor Market Strategic Shifts
Material science breakthroughs and embedded intelligence architectures are compressing the traditional separation between transducer hardware and signal processing, collapsing system integration costs for end users.
Aluminum nitride thin-film piezoelectric deposition on silicon substrates enables monolithic integration with CMOS readout circuits. Automotive tier-one suppliers in Japan and Germany are adopting these MEMS-compatible processes for tire pressure and engine knock sensors. Solid-state piezoelectric architectures are overtaking bulk ceramic designs in volume applications where miniaturization and batch fabrication economics dominate procurement decisions.
The EU AI Act's risk classification framework for industrial automation systems is mandating traceable sensor data provenance. Manufacturers of safety-critical force measurement equipment must implement embedded cryptographic authentication and audit logging. German automotive suppliers face the steepest compliance ramps as they retrofit existing production lines for algorithmic transparency requirements.
Sensor-as-a-service contracting is displacing capital expenditure models in predictive maintenance verticals. Industrial asset operators in the United States now subscribe to vibration monitoring programs where hardware, calibration, and analytics bundle into per-machine monthly fees. This consumption-pattern shift concentrates vendor selection authority with procurement teams rather than maintenance engineering functions.
Piezoelectric Sensor Market Segmentation
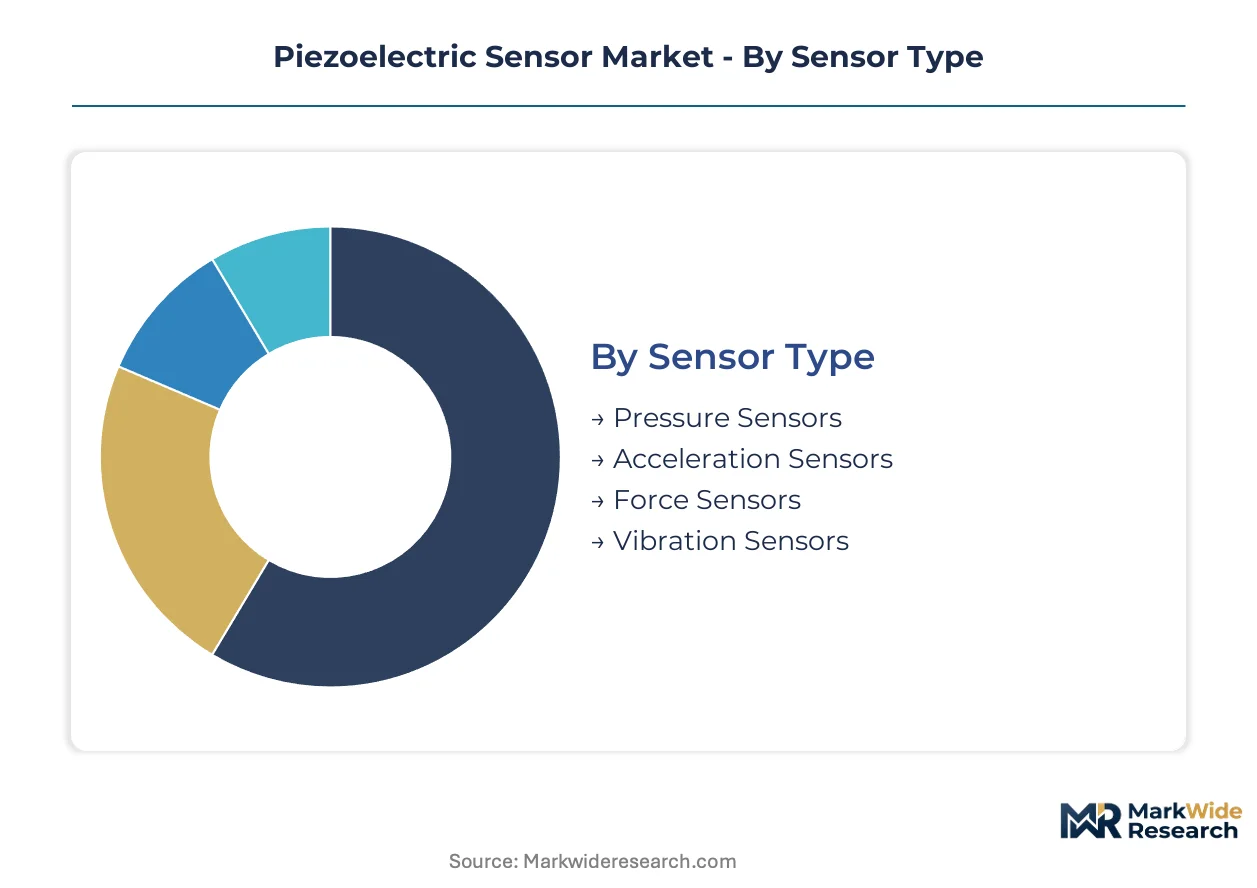
Piezoelectric sensor procurement patterns diverge sharply between standalone measurement instruments and embedded subsystems. Understanding where each segment sits on this integration spectrum reveals margin structures and vendor selection criteria.
Sensor Type:
Pressure sensors dominate standalone industrial installations where calibration traceability commands premium pricing. Acceleration sensors embed most deeply into vehicle chassis and consumer electronics where unit economics favor MEMS-compatible architectures.
- Pressure Sensors:These devices measure fluid and gas pressure through crystalline deflection, typically specified in pascal or bar ranges with temperature compensation circuits. Demand clusters in German process industries where EU Green Deal emissions monitoring mandates continuous validation of rotating equipment seals and vessel integrity.
- Acceleration Sensors:Crash detection and structural health monitoring applications convert mechanical vibration into charge signals across 0.1 Hz to 20 kHz bandwidths. NHTSA battery enclosure standards are accelerating integration into electric vehicle platforms from Detroit to Stuttgart.
- Force Sensors:Load cells and dynamometers for material testing and assembly line feedback.
- Vibration Sensors:Condition monitoring for predictive maintenance in paper mills and steel production.
Pressure sensors lead volumes today; acceleration sensors are gaining share fastest.
Application:
Industrial automation absorbs the highest absolute unit volumes while medical devices extract the steepest per-unit margins. Consumer electronics applications sacrifice precision for miniaturization and cost.
- Industrial Automation:Process control loops and machinery protection systems deploy piezoelectric pressure and vibration transducers in hazardous environments. German automotive suppliers source calibrated force measurement for press-fit assembly verification.
- Medical Devices:Ultrasound imaging transducers and surgical robotics force feedback demand biocompatible packaging and FDA 21 CFR Part 820 quality documentation. Swissmedic certification pathways accelerate time-to-market for high-precision surgical instruments.
- Consumer Electronics:Haptic feedback and microphone arrays in smartphones and wearables.
- Automotive:Tire pressure monitoring and engine knock detection in combustion and electric powertrains.
Industrial automation leads volumes today; medical devices climb the fastest on margin expansion.
End User:
Procurement authority concentrates with engineering teams in aerospace and healthcare, while automotive purchasing departments drive commoditization pressure through consolidated supplier programs.
- Manufacturers:Discrete and process industries specify piezoelectric sensors for quality control and safety interlocks. Japanese precision equipment makers demand sub-micron force resolution for semiconductor wafer handling.
- Automotive OEMs:Battery thermal runaway detection and chassis structural monitoring are restructuring tier-one supplier relationships. Solid-state architectures displace mechanical switches in Detroit and Wolfsburg engineering centers.
- Healthcare Providers:Hospitals and surgical centers specify imaging and therapeutic equipment with embedded piezoelectric arrays.
- Aerospace Companies:Flight test instrumentation and structural health monitoring for composite airframes.
Manufacturers lead volumes today; automotive OEMs are expanding procurement most aggressively.
Technology:
Signal conditioning location—onboard versus external—determines system architecture tradeoffs between power consumption, noise immunity, and calibration stability.
- Smart Sensors:Embedded DSP and edge-computing capabilities enable predictive maintenance at the measurement node. German industrial operators subscribe to sensor-as-a-service contracts bundling hardware, calibration, and analytics into per-machine monthly fees.
- Wireless Sensors:Battery-powered or energy-harvesting architectures eliminate cabling in rotating equipment and remote installations. IEEE 1451 smart transducer interface compliance delays product launches by six to nine months for multi-protocol industrial networks.
- Active Sensors:Externally powered designs with integrated amplifiers for high-fidelity measurement.
- Passive Sensors:Charge-output devices requiring external conditioning electronics.
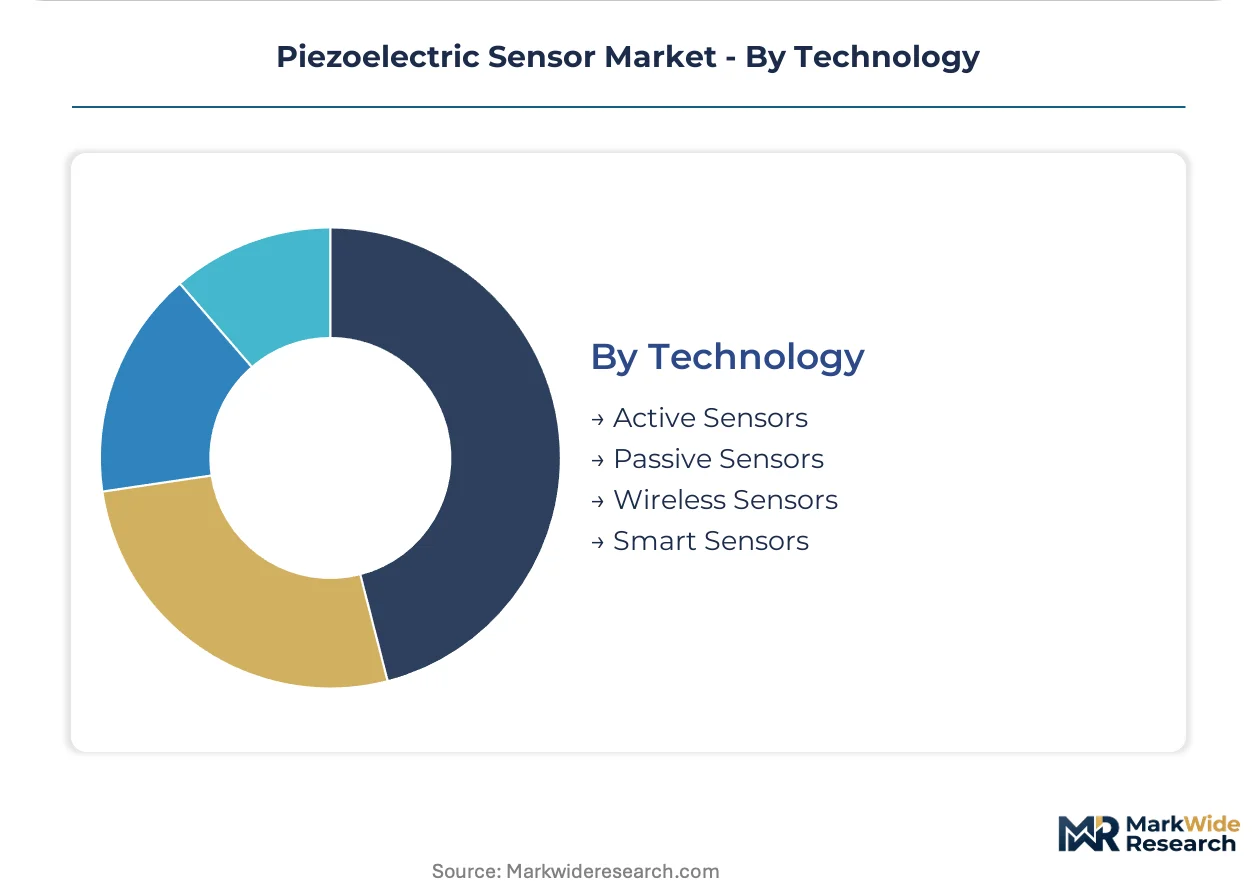
Passive sensors lead volumes today; smart sensors show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting piezoelectric sensor production toward jurisdictions with streamlined certification pathways and localized component ecosystems. Switzerland and Germany maintain calibration-traceability premiums while China and India capture volume manufacturing through cost-advantaged thin-film deposition capacity.
Germany
Automotive OEMs in Stuttgart and Wolfsburg are integrating solid-state piezoelectric architectures for electric powertrain monitoring. EU Green Deal industrial emissions tracking mandates continuous vibration monitoring for rotating equipment across manufacturing facilities. Precision sensor calibration clusters concentrate in Baden-Württemberg where metrology institutes supply certified reference standards.
United States
NHTSA crashworthiness standards are accelerating structural health monitoring integration into electric vehicle battery enclosures. FDA 21 CFR Part 820 quality system regulations govern piezoelectric medical devices entering healthcare supply chains. Detroit engineering centers and Boston-area medical device corridors represent the dominant demand concentrations.
Japan
High-purity synthetic quartz production clusters create substrate supply advantages for precision sensor manufacturers. METI industrial technology roadmaps prioritize MEMS-compatible piezoelectric layer development for automotive tier-one suppliers. Nagoya and Tokyo metropolitan areas host concentrated automotive electronics and precision equipment manufacturing.
China
MIIT directives and GB standards shape certification pathways for components entering domestic manufacturing supply chains. Aluminum nitride thin-film deposition capacity is expanding through wafer-scale fabrication investments serving consumer electronics and medical ultrasound applications. Yangtze River Delta manufacturing hubs concentrate packaging and calibration operations.
Switzerland
Swissmedic medical device certification pathways accelerate time-to-market for high-margin surgical robotics force measurement applications. Deep calibration expertise and metrology heritage sustain premium positioning in force measurement applications. Precision engineering clusters in the Swiss Plateau maintain captive demand from pharmaceutical and medical equipment manufacturers.
Piezoelectric Sensor Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with calibration-intensive applications favoring heritage suppliers and volume electronics tilting toward scale fabricators. The vendor base organizes around three strategic archetypes: Swiss-German precision calibration houses, Japanese ceramic substrate integrators, and diversified connectivity component platforms. Competitive moves concentrate on backward integration into synthetic quartz supply and sensor-as-a-service contracting models that convert capital expenditure into recurring revenue streams.
Within the precision calibration tier, Kistler Group and PCB Piezotronics exemplify heritage-dependent positioning anchored to Swiss and US technical institute relationships. TE Connectivity occupies a position representing diversified platform scale with global distribution infrastructure. CeramTec GmbH and APC International Ltd. sit within ceramic substrate and piezoelectric material supply archetypes respectively. Murata Manufacturing Co., Ltd. represents Japanese volume integration capacity for consumer electronics and automotive MEMS applications.
| Leading Market Players |
|---|
| TE Connectivity |
| APC International Ltd. |
| Honeywell International Inc. |
| Murata Manufacturing Co., Ltd. |
| Morgan Advanced Materials |
| PCB Piezotronics |
| CeramTec GmbH |
| Physik Instrumente |
| Kistler Group |
| Others |
Value Chain & Pricing Dynamics
Family-owned Swiss calibration houses anchor premium pricing through captive metrology relationships, while Japanese ceramic substrate specialists operate on volume-driven contract structures that compress margins for standardized piezoelectric components.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for aluminum nitride thin-film sensors, forcing German precision houses to differentiate through embedded DSP architectures and sensor-as-a-service bundling. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-certified force measurement from Japanese MEMS volume production and Chinese packaging operations. Pricing pressure stems from capacitive MEMS displacement in consumer electronics, where automotive OEMs in Detroit and Wolfsburg drive commoditization through consolidated supplier programs. Tier-one automotive buyers exhibit highest price sensitivity; medical device manufacturers in Swiss and Boston corridors accept premium positioning for FDA 21 CFR Part 820 and Swissmedic certification pathways.
Supply Chain Analysis
Freight cost volatility from Japan's synthetic quartz clusters to European calibration centers is amplifying inventory carrying costs for precision sensor substrates. Supply concentrates in Japan for high-purity quartz, Germany for calibrated force measurement, and China for aluminum nitride thin-film deposition serving consumer electronics and medical ultrasound. Raw material dependencies include synthetic quartz crystals, lead zirconate titanate ceramics, and silicon wafers for MEMS-compatible architectures. Single-source vulnerability in Japanese quartz production creates structural exposure for precision sensor manufacturers. Distribution runs through automotive tier-one supplier networks, industrial automation system integrators, and medical device OEM direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal industrial emissions tracking and NHTSA crashworthiness mandates generate durable demand pull for certified piezoelectric architectures.
For Market Incumbents: Anchor calibration traceability premiums through deeper Swiss and German metrology institute relationships, while accelerating backward integration into synthetic quartz supply to offset Japanese production concentration. Defend against capacitive MEMS displacement by embedding edge-computing capabilities that reduce downstream analytics costs for industrial asset operators. Priority investments center on sensor-as-a-service contracting infrastructure that converts capital expenditure into recurring revenue streams. For New Entrants and Emerging Players: Capture white space in India's PLI scheme for electronics manufacturing, where component localization incentives attract sensor packaging and calibration investments serving domestic automotive and industrial markets. Target surgical robotics force feedback as the most penetrable medical segment, where Swissmedic certification pathways accelerate time-to-market relative to FDA 21 CFR Part 820 timelines. Go-to-market positioning should emphasize MEMS-compatible aluminum nitride architectures that undercut bulk ceramic designs on unit economics. For Investors and Strategic Acquirers: Industrial automation platform companies are the most active acquirer in this space, seeking calibration expertise that differentiates predictive maintenance offerings. Long-term viability hinges on sensor-as-a-service recurring revenue conversion and regulatory certification moats that extend replacement cycles. Acquisition target archetypes include Swiss-German precision calibration houses with captive metrology relationships and Japanese ceramic substrate integrators with MEMS volume capacity. Watch for IEC 60751 and IEEE 1451 smart transducer interface standard adoption as inflection indicator for embedded intelligence architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Quartz Supply | Japanese production concentration creates single-source vulnerability for precision sensor substrates. |
| Sensor-as-a-Service Contracting Infrastructure | Industrial asset operators in the United States now subscribe to bundled vibration monitoring programs. |
| MEMS-Compatible Aluminum Nitride Deposition | Wafer-scale fabrication investments in China serve consumer electronics and medical ultrasound applications. |
| Swissmedic Certification Pathway Investment | Streamlined quality system recognition accelerates time-to-market for surgical robotics force measurement. |
| Edge-Computing Sensor Fusion Development | Onboard DSP architectures enable predictive maintenance at the measurement node, reducing cloud dependency. |
Study Parameters
Direct dialogue with automotive OEM procurement teams, industrial automation system integrators, medical device regulatory affairs leads, and precision sensor calibration technicians grounded the qualitative foundation. Secondary validation drew from NHTSA crashworthiness filings, EU Green Deal implementation directives, FDA 21 CFR Part 820 quality system documentation, and METI industrial technology roadmaps. Bottom-up and top-down triangulation reconciled unit shipment estimates with value aggregation across sensor type, application, and technology segmentation dimensions.
Bottom-up modeling built from named country production clusters and OEM platform content assumptions, while top-down analysis cross-checked against industrial automation capital expenditure patterns and automotive sensor penetration rates. Segmentation dimensions included sensor type, application vertical, end-user procurement authority, and signal conditioning architecture. CAGRs derived from regression analysis of historical shipment trajectories and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated EU AI Act risk classification framework compliance ramps and India PLI scheme localization incentives.
Quartz supply disruption, REACH substance restriction enforcement, and capacitive MEMS technology substitution are the dominant revision risks that could compress precision sensor demand or accelerate architecture transitions. Forecasts reflect documented assumptions about regulatory implementation pacing and OEM platform engineering decisions. Stakeholders should weight assumptions against their own operating context and supply chain exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Optical Sensors Market
Sensors and Controls
Reed Sensor Market
Sensors and Controls
Lighting Control Sensors Market
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
Aeroderivative Sensor Market
Sensors and Controls
Industrial Wireless Sensor Market
Sensors and Controls
IR Emitter and Receiver Market
Sensors and Controls
Speed Sensor Market
Sensors and Controls
United States Pressure Transmitter Market
Sensors and Controls
Frictionless Remote Monitoring Devices Market
Sensors and Controls
Automotive Steering Sensors Market
Sensors and Controls
Window Sensors Market
Sensors and Controls
Battery Module Sensors Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
HVAC Sensor Market