
 Electrochemical Gas Sensor Market | 2026-2036
Electrochemical Gas Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Electrochemical Gas Sensor Market Analysis
The capital-intensity divergence between integrated electrochemical cell fabricators and modular assembly houses is rotating competitive advantage toward players with in-house electrolyte formulation and electrode sintering capabilities. Honeywell International Inc. leverages its captive semiconductor foundry relationships to secure priority allocation of custom ASICs for signal conditioning. Alphasense anchors its position through vertical integration into proprietary polymer membrane casting, reducing lot-to-lot sensitivity variation. MSA Safety Incorporated dominates the North American self-contained breathing apparatus channel, extending its gas sensor reach through captive distribution to fire services and industrial hygiene contractors.
An electrochemical gas sensor converts target gas concentration into an electrical signal through oxidation or reduction at a working electrode bathed in liquid or gel electrolyte, typically achieving detection thresholds in the parts-per-million range with response times under thirty seconds; its primary purpose is continuous, selective monitoring of toxic or combustible gases in environments where human safety or process integrity depends on rapid alarm generation. Fixed gas detectors represent the mature revenue base, sustaining replacement cycles tied to industrial plant refurbishment schedules, while portable and multi-gas detector categories capture faster expansion as confined-space entry protocols tighten across utilities and shipping. Toxic gas sensors command premium positioning where hydrogen sulfide, carbon monoxide, or chlorine detection specificity determines regulatory compliance outcomes.
OSHA permissible exposure limits and EPA emissions standards in the United States, REACH substance restrictions in Europe, and Japan's Industrial Safety and Health Act collectively mandate calibrated gas detection coverage across hazardous work zones, directly conditioning product certification requirements and procurement specifications. The EU AI Act and emerging machine-readable conformity databases will soon require sensor manufacturers to document algorithmic transparency for smart detection systems with predictive maintenance functions. Stakeholders must monitor how rapidly evolving cross-border chemical hazard classifications reshape sensor recalibration obligations and aftermarket service revenue pools.
Market Dynamics
OSHA's tightening permissible exposure limits for hydrogen sulfide and carbon monoxide are forcing industrial operators into accelerated replacement cycles for legacy detection infrastructure, compressing sensor refresh timelines from seven years to four years across petrochemical corridors.
Growth Catalysts
- REACH substance restrictions:European chemical hazard reclassifications mandate recalibrated detection thresholds for chlorine and ammonia, compelling facility upgrades across Rotterdam and Antwerp refining clusters.
- Semiconductor fabrication:East Asian foundries in Hsinchu and Pyeongtaek deploy toxic gas sensor arrays at wafer deposition stations where phosphine and arsine monitoring prevents catastrophic contamination events.
- Battery cell production:Lithium-ion gigafactories in Nevada and Hungary require continuous hydrogen fluoride detection during electrolyte mixing operations, driving sensor density per production line.
Market Restraints
- Precious metal electrode costs:Platinum and rhodium price volatility in South African supply corridors compresses gross margins for three-electrode cell fabricators.
- Electrolyte formulation concentration:Proprietary ionic liquid recipes concentrate among German and Japanese specialty chemical houses, creating supply bottlenecks for second-tier sensor assemblers.
- Optical sensor substitution:Non-dispersive infrared detectors capture share in methane monitoring applications where cross-sensitivity to humidity undermines electrochemical cell reliability.
Strategic Opportunities
- EU AI Act compliance:Smart detection systems with predictive maintenance algorithms require documented algorithmic transparency, creating service revenue pools for calibration documentation specialists.
- India industrial corridor expansion:Petroleum refineries in Jamnagar and Paradip lack adequate hydrogen sulfide coverage, presenting first-mover advantages for certified equipment suppliers.
- MEMS-electrochemical hybrid architectures:Silicon wafer-based microfabricated electrodes converge with traditional liquid electrolyte designs, enabling sub-parts-per-billion detection thresholds for semiconductor cleanrooms.
Industry Challenges
- Electrochemist talent scarcity:Specialized expertise in electrode kinetics and electrolyte stability concentrates among retiring cohorts at German and Japanese research institutes.
- ATEX/IECEx certification timelines:Explosion-proof housing approvals for Zone 0 hazardous locations extend eighteen to twenty-four months, delaying product launches for portable multi-gas detector lines.
- Legacy 4-20mA integration:Brownfield industrial control systems resist digital HART protocol migration, forcing dual-output hardware architectures that inflate unit costs.
Report Scope
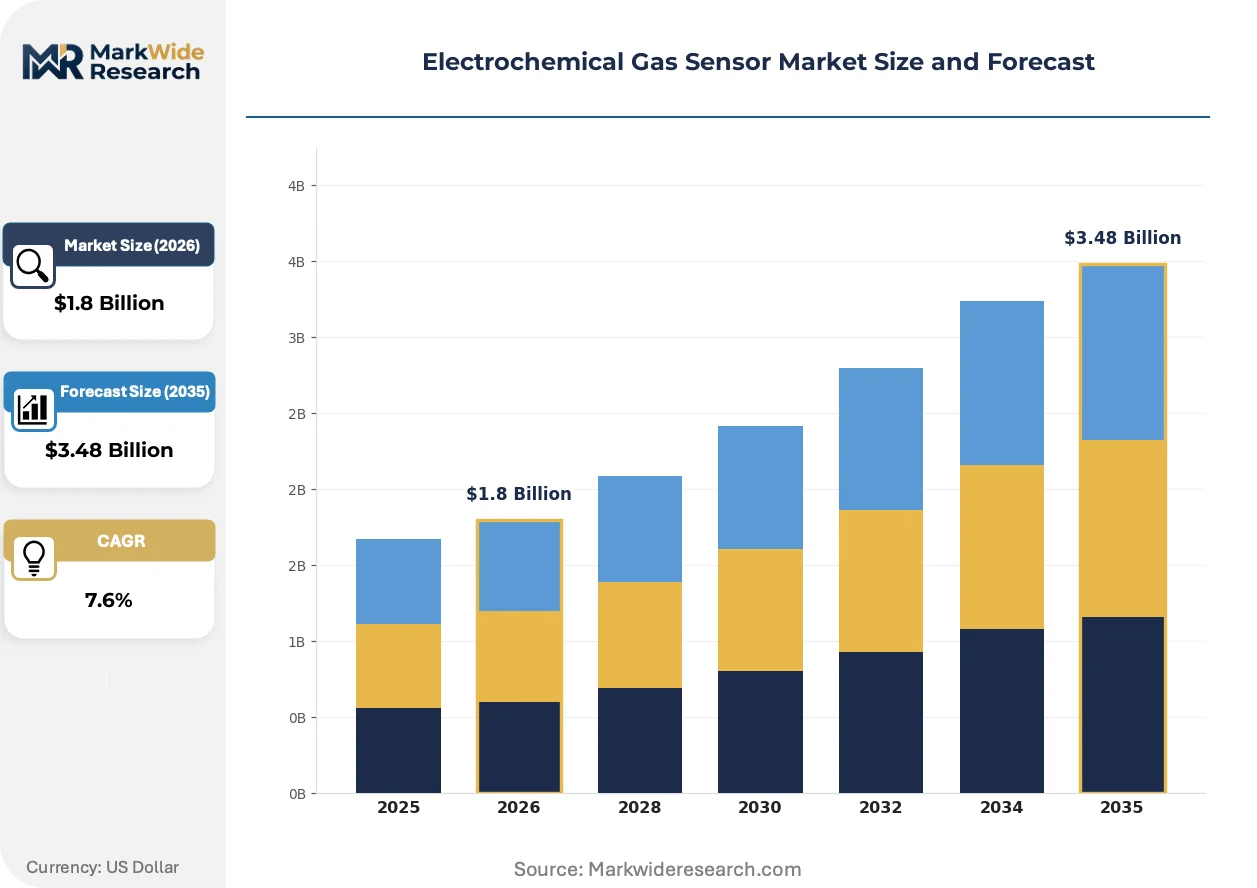
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrochemical Gas Sensor Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
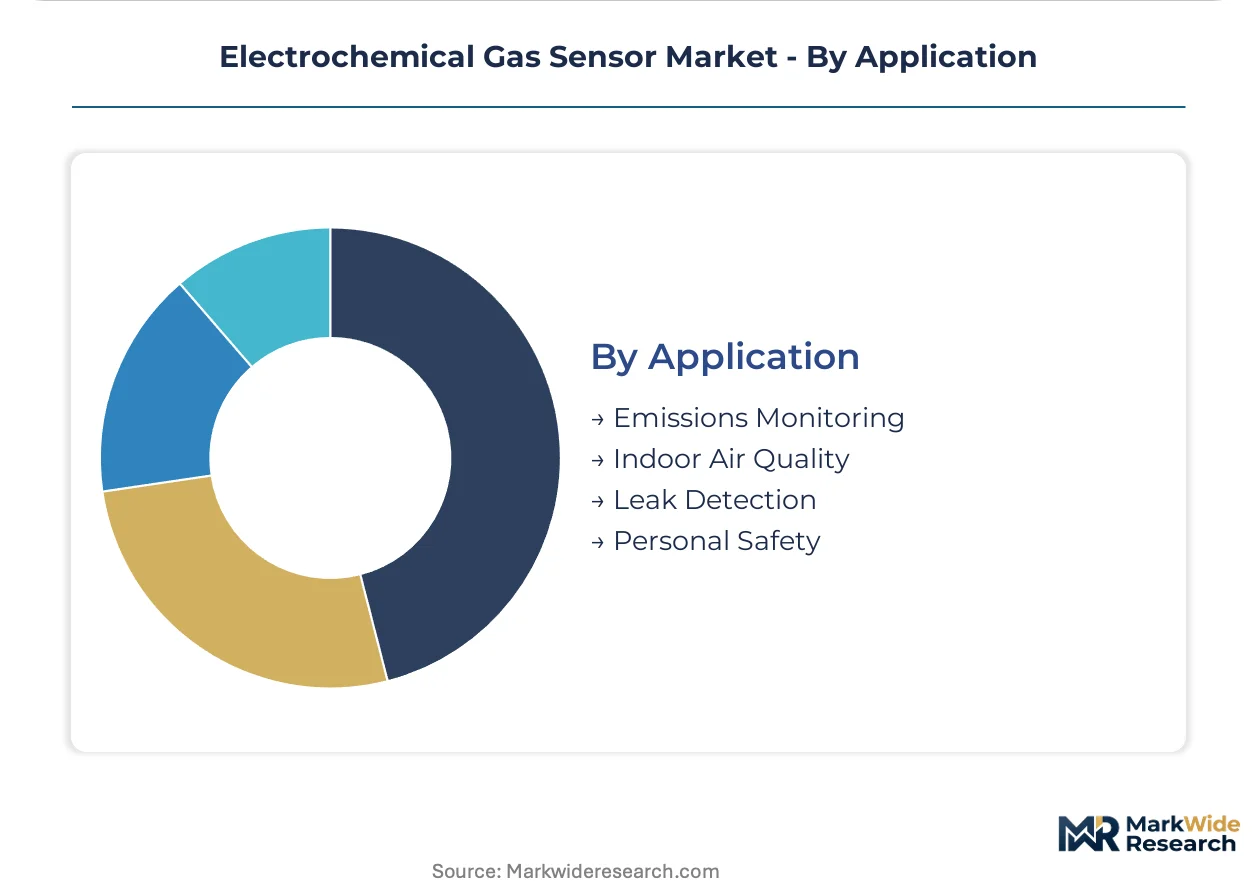
| Segmentation | Product Type: Portable Gas Detectors, Fixed Gas Detectors, Multi-Gas Detectors, Toxic Gas Sensors Technology: Electrochemical, Catalytic, Optical, Infrared End User: Industrial Facilities, Residential, Automotive, Healthcare Application: Emissions Monitoring, Indoor Air Quality, Leak Detection, Personal Safety |
| Companies Covered | Emerson Electric Co., Alphasense, Honeywell International Inc., Figaro Engineering Inc., City Technology Ltd., MSA Safety Incorporated, ABB Ltd., Amphenol Corporation, Drägerwerk AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrochemical Gas Sensor Market Emerging Trajectories
Solid-state polymer electrolyte formulations are displacing liquid-filled cells across portable detector segments, while machine-readable conformity databases under the EU AI Act reshape how manufacturers document sensor algorithm training data.
Solid polymer electrolyte membranes are decomposing the traditional liquid electrolyte cell architecture by eliminating leakage and orientation sensitivity. Mining operators in Western Australia and Chilean copper belts specify these gel-based designs for wearable detectors that withstand inverted mounting during confined-space entry. The technology is decomposing aftermarket service revenue models by extending calibration intervals from six months to eighteen months.
REACH authorization requirements for perfluorinated substances are compressing membrane material options for oxygen sensors, forcing reformulation of fluoropolymer gas-permeable barriers. German chemical manufacturers face substance sunset dates that eliminate established supply chains. Portable detector suppliers serving North Sea offshore platforms accelerate qualification of alternative hydrocarbon-based membrane chemistries.
Calibration gas cylinder procurement is consolidating through third-party gas management services that handle exchange logistics and certificate documentation. Industrial hygiene contractors in the United States Gulf Coast and German Ruhr region outsource cylinder tracking to specialty gas distributors. This unbundling of after-sales service compresses direct manufacturer relationships while shifting recurring revenue toward certified calibration houses.
Electrochemical Gas Sensor Market Segmentation
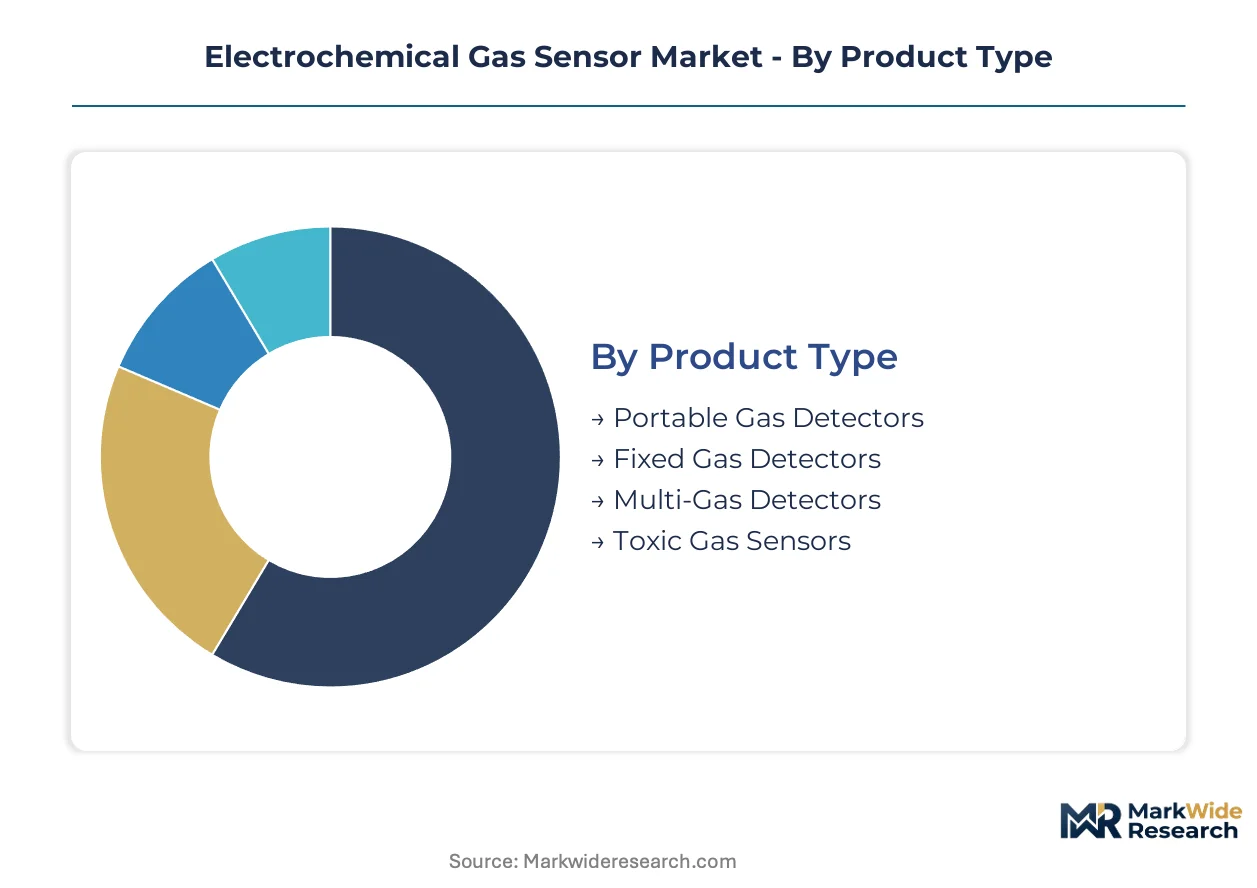
Electrochemical gas sensor procurement patterns diverge sharply between stationary industrial infrastructure and mobile workforce protection, with each segment demanding distinct calibration protocols and certification tiers. Understanding these fault lines clarifies why manufacturers maintain parallel product architectures rather than unified platforms.
Product Type:
Domestic demand concentrates in fixed installations tied to plant refurbishment cycles, while portable and multi-gas categories serve export markets where confined-space regulations are tightening fastest.
- Portable Gas Detectors:Battery-powered units with diffusion or pump-draw sampling achieve sub-30-second response times for H₂S and CO. Mining contractors in Western Australia and Chile specify these for wearable deployment during shaft entry, with calibration intervals stretching to 18 months using solid polymer electrolyte architectures.
- Fixed Gas Detectors:Hardwired 4-20mA or digital HART output devices mount permanently at process vessels and ventilation intakes. Petrochemical operators along the US Gulf Coast refresh these on 4-7 year cycles driven by OSHA permissible exposure limit revisions.
- Multi-Gas Detectors:Simultaneous monitoring of four to six target gases through stacked electrochemical cells. Fire services and industrial hygiene contractors in Germany's Ruhr region favor these for complex hazard zones.
- Toxic Gas Sensors:Single-target specificity for phosgene, arsine, or hydrogen fluoride at parts-per-billion thresholds. Semiconductor fabrication facilities in Hsinchu and Pyeongtaek deploy these arrays at wafer deposition stations.
Fixed Gas Detectors holds the largest share; momentum sits with Portable Gas Detectors.
Technology:
Cost tiers separate commodity catalytic beads from precision electrochemical cells, with optical methods capturing premium positioning in humidity-sensitive methane applications.
- Electrochemical:Three-electrode liquid or gel electrolyte cells achieve ppm-range detection through oxidation-reduction reactions at platinum or rhodium working electrodes. This architecture dominates toxic gas monitoring where regulatory compliance depends on calibration traceability.
- Catalytic:Wheatstone bridge pellistor beads detect combustible gases through catalytic oxidation on heated platinum filaments. These lower-cost units serve methane monitoring in mining and landfill operations where cross-sensitivity to silicones is manageable.
- Optical:Non-dispersive infrared and photoacoustic spectroscopy methods eliminate electrolyte degradation concerns. These systems gain ground in offshore platform applications where humidity extremes undermine electrochemical reliability.
- Infrared:Tunable diode laser absorption spectroscopy enables selective hydrocarbon detection without oxygen dependence. LNG terminal operators in Qatar and Australia specify these for cryogenic leak monitoring.
Electrochemical commands the dominant revenue position; Optical is climbing the fastest as humidity tolerance becomes decisive.
End User:
Volume concentration sits with heavy industry, while margin expansion tracks toward automotive cabin air quality and connected healthcare monitoring.
- Industrial Facilities:Petrochemical refineries, wastewater treatment plants, and battery gigafactories require continuous H₂S, CO, and HF coverage. OSHA enforcement in the United States and Germany's BAuA drive replacement demand across Rotterdam, Antwerp, and Jamnagar refining corridors.
- Residential:Standalone CO alarms and combination smoke-CO units serve landlord compliance mandates. These price-sensitive segments favor catalytic and semiconductor metal oxide alternatives over electrochemical precision.
- Automotive:Cabin air quality sensors for HVAC intake monitoring and battery thermal runaway detection. European OEMs integrate these under REACH substance tracking and EU vehicle emissions frameworks.
- Healthcare:Anesthetic gas monitoring and ventilator oxygen concentration feedback. Japan's PMDA and the US FDA regulate these as medical devices, demanding design history files and clinical validation.
Industrial Facilities generates the dominant revenue pool; Automotive offers the steepest expansion trajectory.
Application:
Customer type stratification separates capital-intensive plant infrastructure from recurring-consumable personal protection, with leak detection bridging both procurement modes.
- Emissions Monitoring:Stack and fenceline continuous emission monitoring systems for EPA and EU Industrial Emissions Directive compliance. These installations demand 24/7 availability with redundant sensor architectures.
- Indoor Air Quality:VOC and CO₂ sensing for commercial building automation. Electrochemical methods compete here with metal oxide and optical alternatives on total cost of ownership.
- Leak Detection:Pipeline and storage vessel surveillance for methane, ammonia, and hydrogen. Utilities in the United States and Germany deploy portable and fixed arrays for LDAR regulatory compliance.
- Personal Safety:Wearable detectors for confined-space entry and emergency response. Fire services and industrial contractors specify ATEX/IECEx certified units with 18-hour battery endurance.
Emissions Monitoring anchors the revenue base; Personal Safety is gaining share fastest as confined-space protocols tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's industrial corridors exhibit acute price sensitivity, while semiconductor fabricators in Taiwan and South Korea prioritize detection precision over unit cost. This elasticity divergence fragments procurement patterns across major demand centers.
United States
Petrochemical operators along the Gulf Coast refresh fixed detector installations on compressed four-year cycles. OSHA's tightened permissible exposure limits for hydrogen sulfide and carbon monoxide mandate infrastructure upgrades across Texas and Louisiana refining clusters. Houston-area process safety contractors drive portable detector demand for confined-space entry protocols.
Germany
Industrial facilities in the Ruhr region and Bavarian chemical belt deploy multi-gas arrays for complex hazard zones. REACH substance restrictions and BAuA enforcement compel recalibrated detection thresholds for chlorine and ammonia. Specialty electrolyte formulators in Ludwigshafen and Leverkusen concentrate proprietary ionic liquid supply.
China
Battery gigafactories in the Yangtze River Delta and Pearl River Delta require continuous hydrogen fluoride monitoring during electrolyte operations. GB standards and MIIT industrial safety directives tighten sensor density mandates. Hsinchu-linked semiconductor foundries in Suzhou and Wuxi deploy toxic gas arrays at wafer deposition stations.
Japan
Automotive OEMs and electronics manufacturers integrate cabin air quality sensors under METI guidance and PMDA medical device frameworks. Kanto region semiconductor cleanrooms specify sub-parts-per-billion detection thresholds. Nagoya-area industrial gas suppliers face JIS certification pressures for calibration documentation.
Australia
Mining contractors in Western Australia specify solid polymer electrolyte designs for wearable detectors during shaft entry. State-level occupational health regulations compress calibration intervals for coal and iron ore operations. Perth-based industrial hygiene contractors consolidate cylinder procurement through third-party gas management services.
Electrochemical Gas Sensor Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision electrochemical fabricators commanding premium positioning while commodity catalytic bead assemblers compete on unit economics. The vendor base stratifies across three tiers: integrated cell fabricators with captive electrolyte formulation, modular assembly houses sourcing electrodes and membranes externally, and diversified industrial conglomerates leveraging distribution scale. Dominant competitive moves include backward integration into polymer membrane casting and strategic partnerships with semiconductor foundries for custom ASIC supply.
Among diversified industrial conglomerates, Emerson Electric Co., Honeywell International Inc., and ABB Ltd. occupy positions spanning process automation and safety systems. These entities exemplify scale-driven archetypes that leverage existing customer relationships in petrochemical and power generation verticals. Specialist sensor fabricators such as Alphasense and City Technology Ltd. sit within focused tiers emphasizing detection specificity and calibration traceability. MSA Safety Incorporated and Drägerwerk AG & Co. KGaA anchor personal safety equipment channels, representing integrated providers that bundle gas detection with respiratory protection and fire service apparatus.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Alphasense |
| Honeywell International Inc. |
| Figaro Engineering Inc. |
| City Technology Ltd. |
| MSA Safety Incorporated |
| ABB Ltd. |
| Amphenol Corporation |
| Drägerwerk AG & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
Solid polymer electrolyte substitution for liquid-filled cells simultaneously shifts membrane sourcing from German and Japanese specialty chemical houses toward polymer casting facilities in South Korea and Taiwan, compressing per-unit electrolyte costs while concentrating formulation IP among captive in-house producers. This substitution dynamic redistributes pricing power toward integrated fabricators with backward control over ionic liquid recipes, forcing modular assemblers into margin erosion or partnership dependence.
Pricing Analysis
After-sales calibration and cylinder exchange services drive lifetime value, with recurring revenue pools expanding faster than hardware sales across industrial hygiene contractor channels. Pricing stratifies across ATEX-certified premium tiers for Zone 0 deployment, standard IECEx-compliant units for general industrial use, and economy-grade catalytic alternatives for methane monitoring in mining. Cost compression in the economy tier intensifies because optical sensor substitution captures share in humidity-sensitive applications. Battery gigafactories and semiconductor foundries exhibit lowest price sensitivity due to regulatory non-negotiability, while residential CO alarm buyers prioritize unit economics over precision.
Supply Chain Analysis
Platinum and rhodium electrode sourcing from South African mining corridors creates single-source vulnerability for three-electrode cell fabricators. Proprietary ionic liquid formulation concentrates among German and Japanese specialty chemical houses, with polymer membrane casting anchoring in South Korea and Taiwan. Tariff exposure runs through rare earth processing dependencies for catalytic bead production. Distribution runs through certified calibration houses and third-party gas management services that consolidate cylinder logistics and documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calibration-as-a-service and predictive maintenance algorithm licensing expand faster than sensor hardware, transforming procurement economics toward outcome-based contracts with industrial hygiene operators.
For Market Incumbents: Consolidate electrolyte formulation capabilities through captive polymer membrane casting or exclusive supply agreements with Ludwigshafen and Leverkusen specialty chemical houses. Deepen backward integration into rhodium and platinum electrode sintering to defend margins against South African supply volatility. Optical sensor substitution in methane monitoring represents the priority threat requiring dual-technology portfolio coverage. For New Entrants and Emerging Players: Lead with solid-state polymer electrolyte architectures targeting Western Australian and Chilean mining contractors seeking 18-month calibration intervals. India's Jamnadar and Paradip refining corridors offer the most penetrable geography for first-mover certified equipment supply. Partner with third-party gas management services for cylinder exchange logistics rather than building direct aftermarket infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed modular assembly houses lacking captive electrolyte formulation, presenting consolidation targets for integrated fabricators seeking geographic expansion. Five-to-ten year viability hinges on algorithmic transparency documentation capabilities under EU AI Act compliance requirements. Monitor REACH perfluorinated substance sunset dates as inflection indicator for membrane material reformulation winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Membrane Casting | Alphasense's proprietary casting reduces lot-to-lot sensitivity variation for semiconductor cleanroom clients. |
| Custom ASIC Foundry Partnerships | Honeywell's captive semiconductor relationships secure priority allocation for signal conditioning chip supply. |
| Predictive Maintenance Algorithm Licensing | EU AI Act documentation requirements create service revenue pools for calibration transparency specialists. |
| MEMS-Electrochemical Hybrid Architecture Development | Silicon wafer microfabrication enables sub-ppb detection thresholds for Hsinchu and Pyeongtaek foundries. |
| Third-Party Gas Management Service Partnership | Industrial hygiene contractors in the US Gulf Coast outsource cylinder tracking, compressing direct manufacturer relationships. |
Methodological Framework
Initial hypotheses were tested against primary input from plant safety managers, industrial hygiene procurement leads, electrochemical R&D directors, and aftermarket service heads, then refined through secondary validation against SEC 10-K filings, OSHA enforcement databases, REACH authorization registers, and customs trade data. Bottom-up sensor shipment estimates from fixed, portable, and multi-gas detector categories were triangulated against top-down industrial facility capital expenditure patterns across petrochemical, semiconductor, and battery production verticals.
Variance decomposition across the projection horizon isolates volume drivers by product architecture, technology tier, end-use industry concentration, and regional regulatory enforcement intensity. Segmentation modeling incorporated detection threshold requirements, certification grade differentiation, and calibration interval specifications as industry-specific dimensions. CAGRs were derived from replacement cycle compression analysis and sensor density mandates at lithium-ion gigafactories and semiconductor wafer deposition stations.
Underlying assumptions cover OSHA permissible exposure limit revision timelines, REACH substance restriction sunset dates, and South African precious metal supply stability, with deviation risk concentrated in optical sensor substitution rates and EU AI Act algorithmic transparency implementation pace. Practitioners should keep alternative scenarios live as semiconductor fabrication capacity expansion and battery cell production localization patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Smart Air Purifier Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
Smartphone Biometric Sensors Market
Sensors and Controls
Middle East and Africa Lidar Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
Japan Sensor Market
Sensors and Controls
Battery Free Sensor Market
Sensors and Controls
Thermal Anemometer Market
Sensors and Controls
Global Wireless Sensors Market
Sensors and Controls
Capacitive Position Sensors Market
Sensors and Controls
Europe Pressure Sensors Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Level Transmitter Market
Sensors and Controls
Oxygen Sensor Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
Global Capacitive Sensor Market