
 Recombinant Plasma Protein Therapeutics Market | 2026-2036
Recombinant Plasma Protein Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Recombinant Plasma Protein Therapeutics Market Intelligence
Prefilled syringe and autoinjector bundling is recalibrating how hemophilia patients and clinics procure coagulation factor therapies. Novo Nordisk A/S dominates the subcutaneous delivery segment with extended half-life recombinant factors. Bayer AG leverages its hemophilia franchise through integrated patient support programs that anchor prescriber loyalty. Takeda Pharmaceutical Company Limited navigates the transition from plasma-derived to recombinant immunoglobulin portfolios across Asian and European markets.
Recombinant plasma protein therapeutics comprise genetically engineered proteins produced in mammalian cell cultures, including Chinese hamster ovary lines, that replicate the functional properties of human plasma-derived proteins without donor blood dependence. These biologics serve therapeutic purposes ranging from clotting factor replacement in hemophilia to enzyme substitution in rare metabolic disorders. Coagulation factors occupy the largest revenue pool due to chronic prophylactic dosing regimens and premium pricing for extended half-life variants. Immunoglobulins represent the fastest-expanding category as subcutaneous delivery modes shift administration from hospital infusion centers to home settings. Albumin sustains mature demand profiles in surgical and critical care applications where volume expansion properties retain clinical utility.
FDA biosimilar guidance and EMA comparability standards shape development costs and market entry timelines for recombinant protein developers. The EU F-Gas Regulation and OSHA process safety mandates constrain manufacturing facility design and cold-chain logistics configurations. Stakeholders must monitor how national health technology assessment bodies weigh recombinant efficacy against plasma-derived cost advantages in reimbursement decisions.
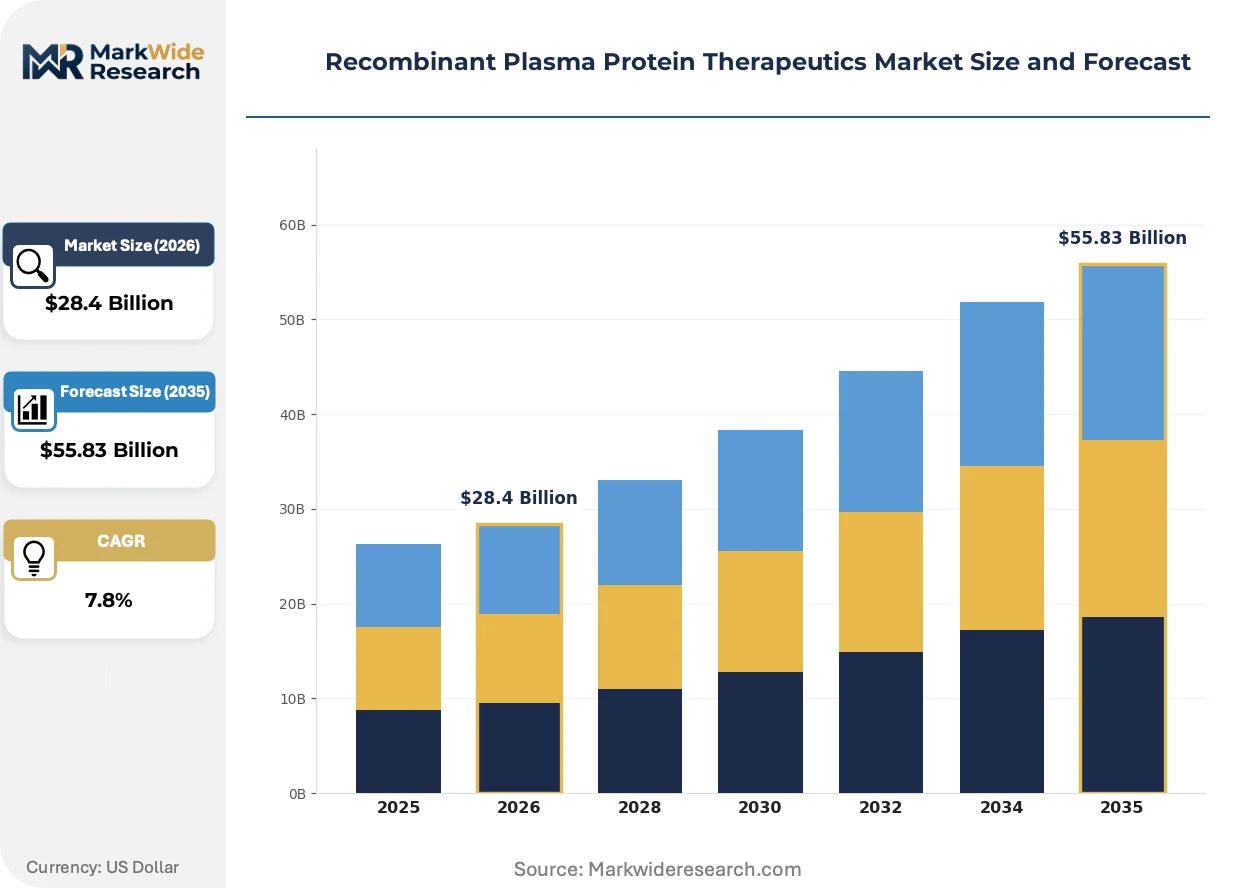
Market Dynamics
Extended half-life recombinant coagulation factors are displacing plasma-derived alternatives through hemophilia treatment centers, while FDA and EMA biosimilar pathways compress development timelines for follow-on biologics and reshape competitive entry economics.
Growth Catalysts
- EMA comparability standards:Streamlined biosimilar approval frameworks reduce clinical trial burdens for recombinant protein developers entering European markets. Follow-on biologics reach patients faster under these harmonized technical guidelines.
- Hemophilia treatment centers:Specialized clinical networks in the United States and Germany drive concentrated demand for prophylactic recombinant factor replacement. These centers favor extended half-life variants that reduce infusion frequency.
- Chinese hamster ovary cell culture:Mammalian expression systems enable scalable production of complex glycoproteins without donor blood dependence. Manufacturing yields improve as perfusion bioreactor technologies mature.
Market Restraints
- EU F-Gas Regulation:Refrigerant restrictions on hydrofluorocarbon use constrain cold-chain logistics configurations for temperature-sensitive biologics. Distribution networks face retrofit costs for compliant transport units.
- Plasma-derived cost advantages:Blood fractionation products retain reimbursement preference in price-sensitive markets where health technology assessment bodies emphasize acquisition cost over clinical differentiation.
- Single-source supplier concentration:Cell culture media and specialty resins for protein purification concentrate among limited vendors. Input scarcity disrupts manufacturing schedules when supply tightens.
Strategic Opportunities
- Home-based subcutaneous immunoglobulin:Administration mode shifts from hospital infusion centers to patient self-injection create service revenue pools for delivery device bundling. Patient training programs anchor recurring prescription loyalty.
- Japan's PMDA regenerative medicine framework:Accelerated review pathways for rare disease biologics compress time-to-market for novel recombinant enzymes. Orphan drug incentives strengthen pricing power.
- Gene therapy convergence:Combination approaches pairing recombinant proteins with viral vector delivery systems address metabolic disorders beyond current replacement therapy limits. Research alliances between protein manufacturers and gene therapy platforms expand addressable indications.
Industry Challenges
- Bioprocess engineering talent scarcity:Cell line development and scale-up manufacturing require specialized expertise that outpaces academic pipeline output. Compensation inflation for experienced fermentation scientists compresses R&D margins.
- OSHA process safety mandates:Biosafety level containment requirements for mammalian cell operations drive facility capital intensity. Multi-product suites demand extensive validation protocols between campaign switches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recombinant Plasma Protein Therapeutics Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $55.83 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulation Factors, Albumin, Immunoglobulins, Enzyme Replacements, Fibrin Sealants Indication: Hemophilia, Immune Deficiency Disorders, Liver Diseases, Enzyme Deficiency Disorders, Bleeding Disorders End User: Specialized Clinics, Biopharmaceutical Companies, Research Institutes, Contract Manufacturing Organizations Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Infusion Pumps, Prefilled Syringes |
| Companies Covered | Hoffmann-La Roche Ltd., CSL Limited, Takeda Pharmaceutical Company Limited, Bayer AG, Novo Nordisk A/S, Pfizer Inc., Sanofi S.A., Octapharma AG, Grifols S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recombinant Plasma Protein Therapeutics Market Strategic Shifts & Innovations
Continuous manufacturing architectures and single-use bioreactor systems are reshaping recombinant protein production economics, while regulatory science advances compress comparability study timelines and patient-administered delivery modes shift care settings.
Perfusion bioreactor technology with integrated online analytics is electrifying upstream process efficiency for extended half-life coagulation factors. Contract manufacturing organizations in Germany and the United States deploy these systems to reduce batch-to-batch variability and facility footprint. The technology is electrifying cost structures for high-dose chronic therapies by collapsing capital requirements per gram of protein output.
EMA's F-Gas Regulation and corresponding national implementing measures are forcing cold-chain infrastructure retrofits across European distribution networks. Logistics providers substitute natural refrigerants for synthetic hydrofluorocarbons in transport containers and warehouse systems. Recombinant albumin and immunoglobulin shipments face the steepest compliance costs given their temperature sensitivity and volume scale.
Patient-administered subcutaneous delivery is displacing intravenous infusion as the default mode for immunoglobulin replacement. Hematology clinics in Japan and the United States reduce chair time allocation as home nursing support programs expand. This shift concentrates purchasing influence with specialty pharmacy intermediaries rather than hospital pharmacy departments.
Recombinant Plasma Protein Therapeutics Market Segmentation
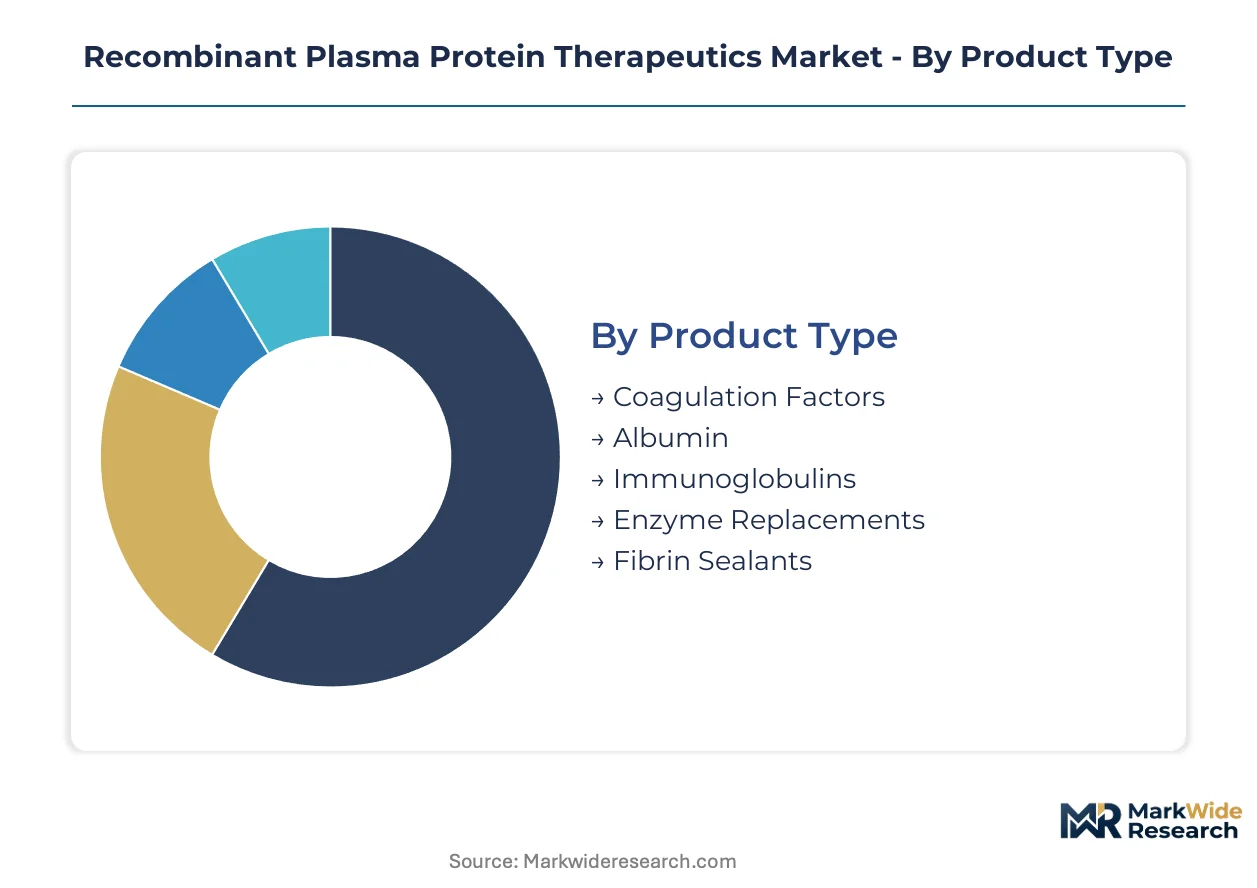
Segmentation in recombinant plasma protein therapeutics reveals how manufacturing scale, clinical setting, and administration complexity create divergent margin structures across the value chain. Product type and delivery mode classifications particularly expose where bioprocess investments concentrate versus where commoditization pressures build.
Product Type:
Supply concentration in mammalian cell culture capacity tilts heavily toward glycoprotein categories with chronic dosing profiles and premium pricing endurance.
- Coagulation Factors:Extended half-life variants fuse recombinant factor VIII or IX with polyethylene glycol or Fc domains to prolong circulation. Hemophilia treatment centers in the United States and Germany drive procurement concentration for prophylactic regimens that reduce bleeding episodes. Manufacturing complexity and patent-protected formulations sustain pricing power against biosimilar erosion.
- Immunoglobulins:Polyclonal antibody preparations replace humoral immune function in primary immunodeficiency. Subcutaneous delivery shifts in Japan and the United States are compressing hospital infusion volumes while expanding home nursing service bundling. The category climbs fastest as patient self-administration programs mature.
- Albumin:Colloid oncotic pressure maintenance for surgical and critical care volume expansion.
- Enzyme Replacements:Recombinant enzymes address lysosomal storage disorders through lifelong intravenous supplementation.
- Fibrin Sealants:Topical hemostasis applications in cardiovascular and spinal surgical procedures.
Coagulation factors absorb the bulk of installed capacity; immunoglobulins are expanding most quickly.
Indication:
Cost tier stratification separates rare disease categories with orphan pricing protection from higher-volume indications facing reimbursement compression.
- Hemophilia:Congenital factor deficiency requiring lifelong replacement creates the deepest chronic therapy pools. Prophylactic dosing in specialized hemophilia treatment centers locks in recurring revenue streams. Gene therapy convergence threatens long-term demand trajectories for recombinant factors.
- Immune Deficiency Disorders:Primary and secondary humoral defects drive immunoglobulin consumption. Home-based subcutaneous programs in the United States reduce institutional infusion dependency. Patient training investments anchor prescription loyalty against switching.
- Liver Diseases:Albumin replacement in hepatic synthetic failure sustains mature demand.
- Enzyme Deficiency Disorders:Lysosomal storage conditions with ultra-orphan prevalence and premium pricing.
- Bleeding Disorders:Acquired coagulopathies and surgical prophylaxis with episodic dosing patterns.
Hemophilia commands the steepest pricing tiers; immune deficiency disorders gain share fastest as subcutaneous delivery matures.
End User:
Customer type determines whether procurement flows through concentrated institutional buyers or fragmented specialty pharmacy channels.
- Specialized Clinics:Hemophilia treatment centers and immunology practices concentrate demand for high-value biologics. Integrated care models in Germany and the United States bundle drug procurement with nursing services. These sites negotiate directly with manufacturers for extended half-life factor contracts.
- Biopharmaceutical Companies:In-house recombinant protein portfolios require captive manufacturing or strategic contract manufacturing organization partnerships. Cell line development capabilities differentiate internal versus outsourced production economics.
- Research Institutes:Preclinical and clinical trial material supply for academic rare disease programs.
- Contract Manufacturing Organizations:Third-party bioprocess capacity for developers lacking mammalian cell culture infrastructure.
Specialized clinics anchor volume concentration; contract manufacturing organizations are scaling fastest as pipeline biologics advance.
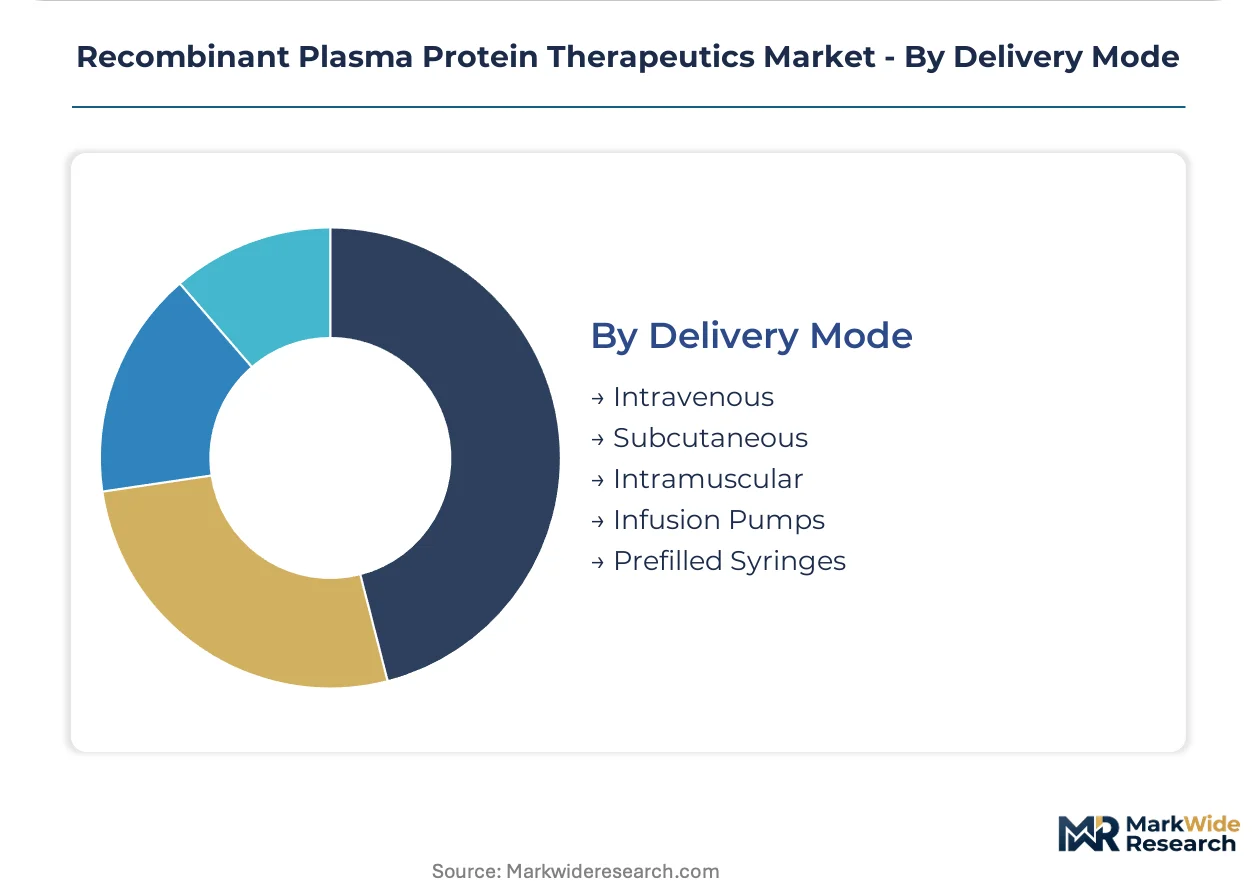
Delivery Mode:
Administration technology selection reshapes cold-chain requirements, patient compliance economics, and competitive differentiation through device bundling.
- Intravenous:Hospital and infusion center administration dominates coagulation factor and enzyme replacement delivery. Chair time costs and nursing supervision requirements sustain institutional reimbursement premiums. Perfusion pump compatibility demands specific formulation viscosity profiles.
- Subcutaneous:Patient self-injection of immunoglobulins displaces intravenous infusion in Japan and the United States. Prefilled syringe and autoinjector formats reduce training burdens and dosing errors. Novo Nordisk A/S and Takeda Pharmaceutical Company Limited compete through delivery device ecosystems.
- Intramuscular:Limited applications for specific immunoglobulin formulations and emergency bleeding control.
- Infusion Pumps:Programmable delivery for extended half-life factors requiring precise rate control.
- Prefilled Syringes:Single-dose convenience formats for home administration programs.
Intravenous retains the largest installed base; subcutaneous delivery is accelerating fastest as patient-administered models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Germany and the United States, while consumption tilts toward Japan and specialized treatment networks in Western Europe. Manufacturing investments favor mammalian cell culture clusters with established cold-chain infrastructure.
United States
Hemophilia treatment centers drive concentrated procurement of extended half-life coagulation factors. FDA biosimilar guidance streamlines approval pathways for follow-on recombinant proteins. Boston and San Francisco biotech corridors anchor cell line development and perfusion bioreactor manufacturing scale-up.
Germany
Integrated patient support programs lock in prescriber loyalty for prophylactic factor replacement regimens. EMA comparability standards and F-Gas Regulation shape facility design and distribution logistics. Bavaria and North Rhine-Westphalia host contract manufacturing organizations deploying single-use bioreactor systems.
Japan
Home-based subcutaneous immunoglobulin programs displace hospital infusion volumes fastest among developed markets. PMDA's regenerative medicine framework accelerates rare disease biologic reviews. The Kanto region around Tokyo concentrates specialty pharmacy intermediaries handling patient-administered delivery.
Switzerland
Orphan drug pricing frameworks sustain premium tiers for enzyme replacement therapies. Swissmedic alignment with EMA technical standards reduces regulatory duplication for European market access. Basel and Zurich anchor bioprocess engineering talent pools for mammalian cell culture optimization.
United Kingdom
Health technology assessment bodies weigh recombinant efficacy against plasma-derived cost advantages in reimbursement decisions. NHS specialized commissioning frameworks concentrate procurement through hemophilia comprehensive care centers. London and the Southeast corridor dominate import logistics for temperature-sensitive biologics.
Recombinant Plasma Protein Therapeutics Market Key Industry Players
The competitive structure tilts toward integrated pharmaceutical conglomerates with captive mammalian cell culture infrastructure. Consolidation around extended half-life factor portfolios and delivery device ecosystems defines the upper tier, while regional plasma fractionators defend positions through hybrid recombinant-plasma portfolios. Three archetypes dominate: diversified biopharma majors with hemophilia franchises, specialized coagulation factor developers, and contract manufacturing organizations scaling perfusion technologies. Capacity expansion and strategic partnerships for gene therapy convergence represent the dominant competitive moves.
Among diversified biopharma conglomerates, Hoffmann-La Roche Ltd., Takeda Pharmaceutical Company Limited, and Bayer AG occupy positions exemplifying integrated therapeutic franchises. Roche's Basel-based structure represents the large-cap archetype combining diagnostic and therapeutic capabilities. Takeda anchors the Asia-Pacific to Western bridge with Japanese regulatory expertise and European manufacturing assets. Bayer AG exemplifies the German industrial model with deep hemophilia treatment center relationships and patient support program infrastructure. These three entities sit within the premium-tier vector where extended half-life formulations and delivery device bundling sustain pricing power against biosimilar erosion.
| Leading Market Players |
|---|
| Hoffmann-La Roche Ltd. |
| CSL Limited |
| Takeda Pharmaceutical Company Limited |
| Bayer AG |
| Novo Nordisk A/S |
| Pfizer Inc. |
| Sanofi S.A. |
| Octapharma AG |
| Grifols S.A. |
| Others |
Cost & Logistics Intelligence
Perfusion bioreactor adoption in mammalian cell culture operations simultaneously collapses capital requirements per gram of protein output and concentrates manufacturing capacity among German and United States facilities with validated containment infrastructure. This technological transition reshapes cost economics for extended half-life coagulation factors while tightening supply concentration around contract manufacturing organizations with single-use system expertise.
Pricing Analysis
Margin tightening in standard immunoglobulin tiers reflects biosimilar entry under FDA and EMA streamlined pathways. Three-tier pricing structure across premium extended half-life formulations, standard recombinant factors, and economy plasma-derived alternatives dominates procurement negotiations. Price differentiation hinges on glycoengineering complexity and cold-chain certification grade. Hemophilia treatment centers in the United States exhibit lowest price sensitivity due to bundled patient support programs, while Asian hospital systems facing health technology assessment scrutiny show highest sensitivity.
Supply Chain Analysis
EMA F-Gas Regulation certification requirements for natural refrigerant cold-chain systems gate European distribution network participation. Manufacturing concentrates in Germany, the United States, and Switzerland where mammalian cell culture infrastructure clusters. Production rests on Chinese hamster ovary cell lines, specialty protein A resins, and single-use bioreactor consumables. Single-source vulnerability in cell culture media formulation creates disruption exposure. Distribution runs through specialty pharmacy intermediaries for patient-administered subcutaneous products and direct-to-clinic channels for hospital-based intravenous therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recombinant plasma protein therapeutics represents a consolidation play where biosimilar pathway compression and manufacturing scale requirements force sub-scale developers toward strategic exit or acquisition.
For Market Incumbents: Deepen vertical integration into perfusion bioreactor manufacturing capacity in Bavaria and North Rhine-Westphalia to defend margin position against contract manufacturing organization cost competition. Lock in prescriber loyalty through integrated patient support programs that bundle extended half-life factor delivery with home nursing services, creating switching costs that biosimilar entrants struggle to replicate. For New Entrants and Emerging Players: Launch via Japan's PMDA regenerative medicine accelerated review pathway for rare disease enzyme replacements, exploiting orphan drug pricing protection and compressed time-to-market. Target home-based subcutaneous immunoglobulin segments in United States specialty pharmacy channels where patient training investments anchor prescription loyalty and institutional infusion center relationships remain underdeveloped. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap recombinant factor developers with validated mammalian cell lines but lacking commercial infrastructure. Long-term viability over the analysis window favors platforms with gene therapy convergence capabilities and captive bioprocess engineering talent pools. Watch FDA biosimilar approval velocity for extended half-life factors as the inflection signal for pricing power erosion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Perfusion Bioreactor Scale-Up | Reduces capital intensity per gram for high-dose chronic therapies in German CMO facilities. |
| Subcutaneous Delivery Device Partnership | Captures patient-administered immunoglobulin growth through prefilled syringe ecosystem bundling. |
| EMA Biosimilar Pathway Navigation | Compresses clinical trial burdens for follow-on recombinant proteins entering European markets. |
| Gene Therapy Platform Alliance | Expands addressable indications beyond replacement therapy limits through viral vector combination approaches. |
| Specialty Pharmacy Channel Control | Concentrates purchasing influence for home-based administration programs displacing hospital infusion. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this recombinant plasma protein therapeutics analysis. Primary interviews with bioprocess engineering directors, regulatory affairs leads at EMA and FDA, hemophilia treatment center pharmacy directors, and specialty pharmacy procurement managers combined with FDA biosimilar guidance documents, EMA comparability assessment reports, ClinicalTrials.gov entries, and cold-chain logistics customs records. Bottom-up patient population modeling and top-down manufacturer capacity triangulation validated volume estimates.
Reconciliation of patient registry data, treatment center procurement records, and manufacturer disclosed capacity expansions informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, indication severity tier, delivery mode, end-user channel, and regional regulatory cluster. CAGRs derived from longitudinal pricing trajectory analysis and dosing regimen evolution patterns. Forecast inputs incorporated perfusion technology adoption curves and biosimilar entry timing assumptions.
Gene therapy clinical advancement, EMA F-Gas Regulation enforcement intensity, and hemophilia treatment center formulary consolidation are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on dosing frequency shifts and reimbursement framework stability. A model refresh is warranted upon material change in FDA extended half-life biosimilar approval velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Narcotic Analgesics Market
Pharmaceuticals
Alectinib Drugs Market
Pharmaceuticals
Celiac Disease Drugs Market
Pharmaceuticals
Dermatitis Drugs Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Global Respiratory Drug Market
Pharmaceuticals
China Opioids Market
Pharmaceuticals
Wujibaifeng Pills Market
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Global Acetazolamide Market
Pharmaceuticals
Ampicillin Drugs Market
Pharmaceuticals
Oral Contraceptive Pills Market
Pharmaceuticals
Polypill Products Market