
 Rare Hematology Market | 2026-2036
Rare Hematology Market Size, Share, and Industry Trends Forecast 2026-2036
Rare Hematology Market Intelligence
The divergence in capital allocation between novel gene therapies and established biologic treatments is reorganizing the competitive landscape. Niche innovators like bluebird bio specialize in high-cost, curative genetic medicines. In contrast, established players such as CSL Behring sustain market position through large-scale manufacturing of factor concentrates and immunoglobulins. Pfizer competes with a diversified portfolio spanning both traditional and next-generation therapies.
Rare hematology encompasses a group of inherited or acquired disorders affecting blood components like coagulation factors. These conditions, including Hemophilia B and Von Willebrand Disease, require therapies designed to replace missing proteins or correct underlying genetic defects. While Factor Concentrates still command a significant market share, newer immunoglobulins and gene therapies are gaining traction. Treatment administration is increasingly concentrated in Specialized Treatment Centers due to the complexity of intravenous delivery and patient monitoring requirements.
Regulatory pathways for orphan drugs, governed by agencies like the U.S. FDA and the European Medicines Agency (EMA), provide critical incentives for development. These frameworks, alongside specific reimbursement policies in countries like Germany and Japan, directly influence therapeutic availability and commercial viability. Future market dynamics will be shaped by the ability of healthcare systems to finance one-time curative gene therapies versus long-term protein replacement treatments.
Market Dynamics
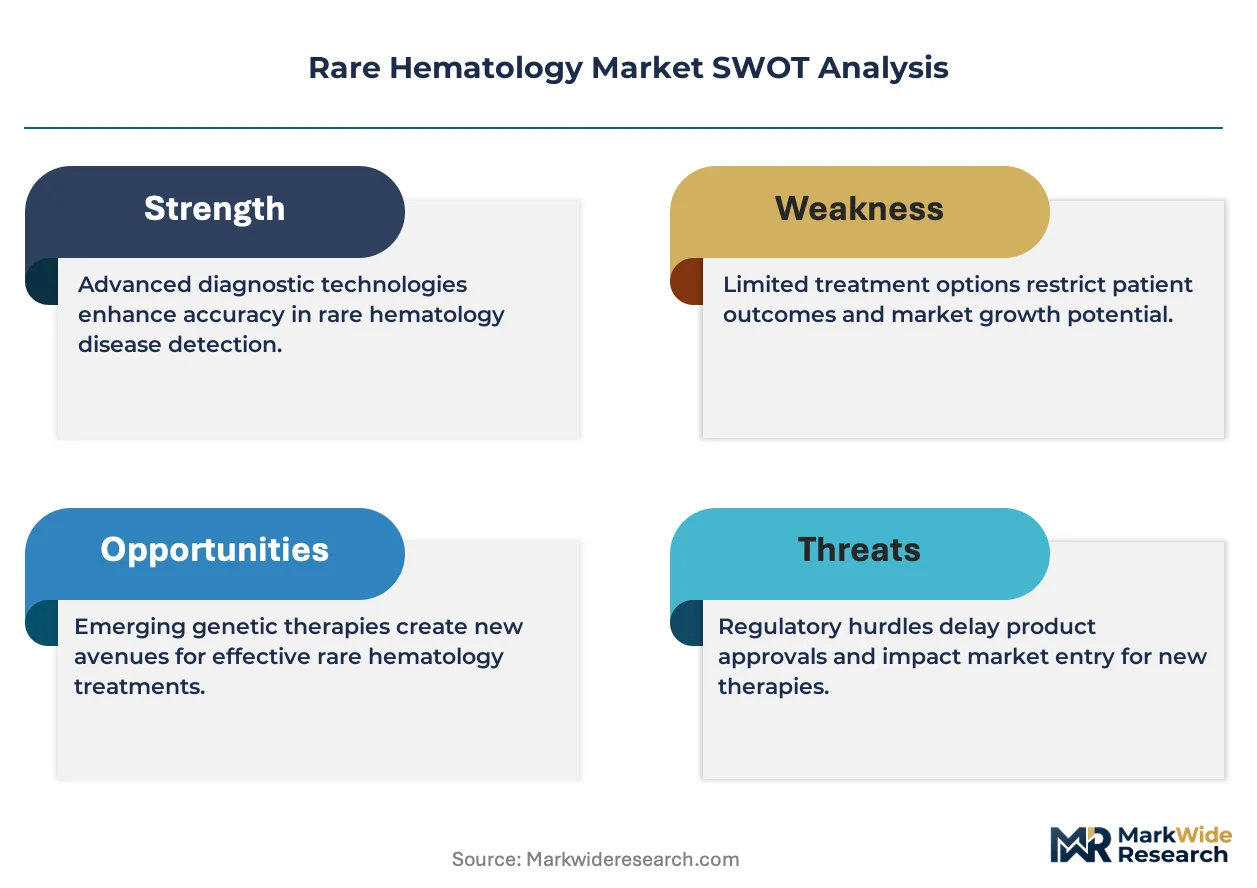
The central dynamic is the financial and logistical tension between high-cost, one-time curative gene therapies and established long-term protein replacement treatments. This dichotomy influences healthcare system planning and investment priorities across developed markets.
Growth Catalysts
- Orphan Drug Incentives:Regulatory frameworks from the FDA and EMA, such as market exclusivity and tax credits, stimulate research and development investment into therapies for rare conditions like Hemophilia B.
- Diagnostic Advancements:The application of next-generation sequencing improves the diagnostic accuracy for inherited blood disorders, expanding the identifiable patient population eligible for targeted treatments.
- Care Concentration:The growth of Specialized Treatment Centers centralizes expertise and patient volume, which improves outcomes and facilitates the administration of complex intravenous therapies.
Market Restraints
- Reimbursement Hurdles:The multi-million dollar price of single-administration gene therapies creates significant access and reimbursement challenges for payers in the United States and key European markets.
- Manufacturing Bottlenecks:Production of cell and gene therapies requires specialized facilities and expertise, leading to supply constraints and high cost of goods that limit scalability.
- Durability Concerns:A lack of extensive long-term efficacy and safety data for novel genetic medicines results in cautious adoption by some clinicians pending further evidence.
Strategic Opportunities
- Geographic Expansion:Japan's specific reimbursement policies for innovative drugs and its advanced healthcare infrastructure present an opportunity for introducing novel therapies for conditions like Von Willebrand Disease.
- Non-Viral Vectors:Developing alternative gene delivery systems, such as lipid nanoparticles, could address immunogenicity concerns associated with viral vectors and potentially lower manufacturing costs.
- Telehealth Integration:Using remote monitoring and telehealth platforms to manage patients receiving intravenous therapies can reduce the logistical burden on both patients and Specialized Treatment Centers.
Industry Challenges
- Talent Scarcity:A shortage of technicians and scientists skilled in viral vector manufacturing for gene therapies creates a critical operational bottleneck for developers across the industry.
- Complex Logistics:Maintaining the integrity of cell-based therapies through stringent cold-chain distribution from the manufacturing site to the patient presents significant logistical hurdles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rare Hematology Market |
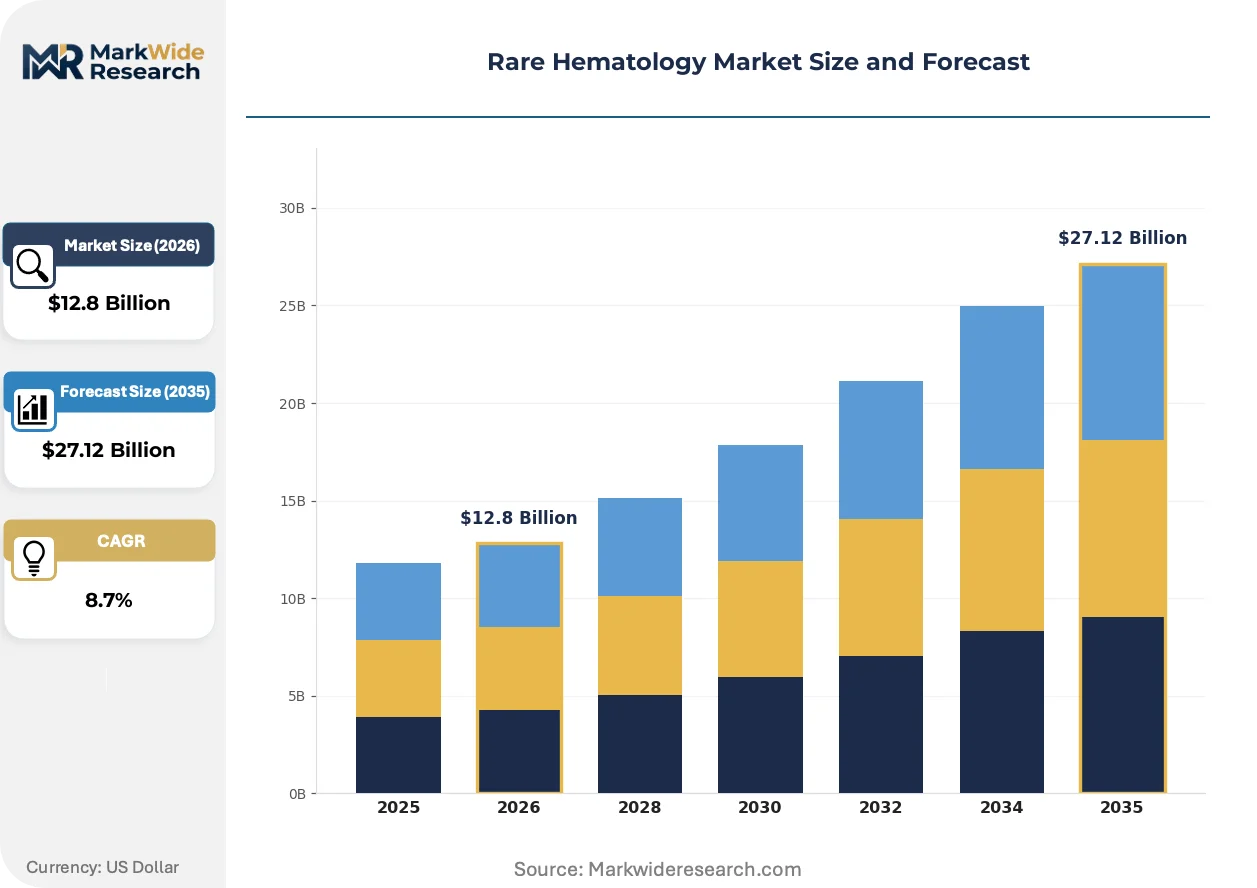
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Factor Concentrates, Immunoglobulins, Erythropoiesis Stimulating Agents, Hematopoietic Growth Factors, Iron Chelators Therapy Area: Hemophilia A, Hemophilia B, Thalassemia, Von Willebrand Disease, Aplastic Anemia End User: Specialized Treatment Centers, Ambulatory Care Clinics, Blood Banks, Research Laboratories, Home Care Settings Delivery Mode: Intravenous, Subcutaneous, Oral, Intra-articular, Transfusion |
| Companies Covered | AstraZeneca, Novartis, Pfizer, Bayer, Sanofi, CSL Behring, bluebird bio, Bristol Myers Squibb, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rare Hematology Market Strategic Shifts & Innovations
The market's evolution pivots from chronic symptom management toward the pursuit of curative treatments. This shift alters technology roadmaps, regulatory pathways for orphan drugs, and the financial models supporting patient access.
Point-of-care coagulation monitors provide immediate feedback on blood clotting status. Patients with conditions like Hemophilia A adopt these devices for home use, enabling real-time treatment adjustments. This technology is miniaturizing complex lab diagnostics into user-friendly handheld formats, reducing reliance on Specialized Treatment Centers for routine monitoring.
The European Medicines Agency's PRIority MEdicines (PRIME) scheme provides enhanced support for innovative treatments. This framework accelerates development and review for therapies addressing unmet medical needs. Gene therapy developers are most affected, gaining early dialogue with regulators to streamline authorization.
A transition toward value-based reimbursement is altering payment for high-cost therapies. Instead of fee-for-service, payers explore contracts where payment is tied to patient outcomes like reduced bleeding events. This shift is most prominent within integrated healthcare networks in the United States and Germany.
Rare Hematology Market Segmentation
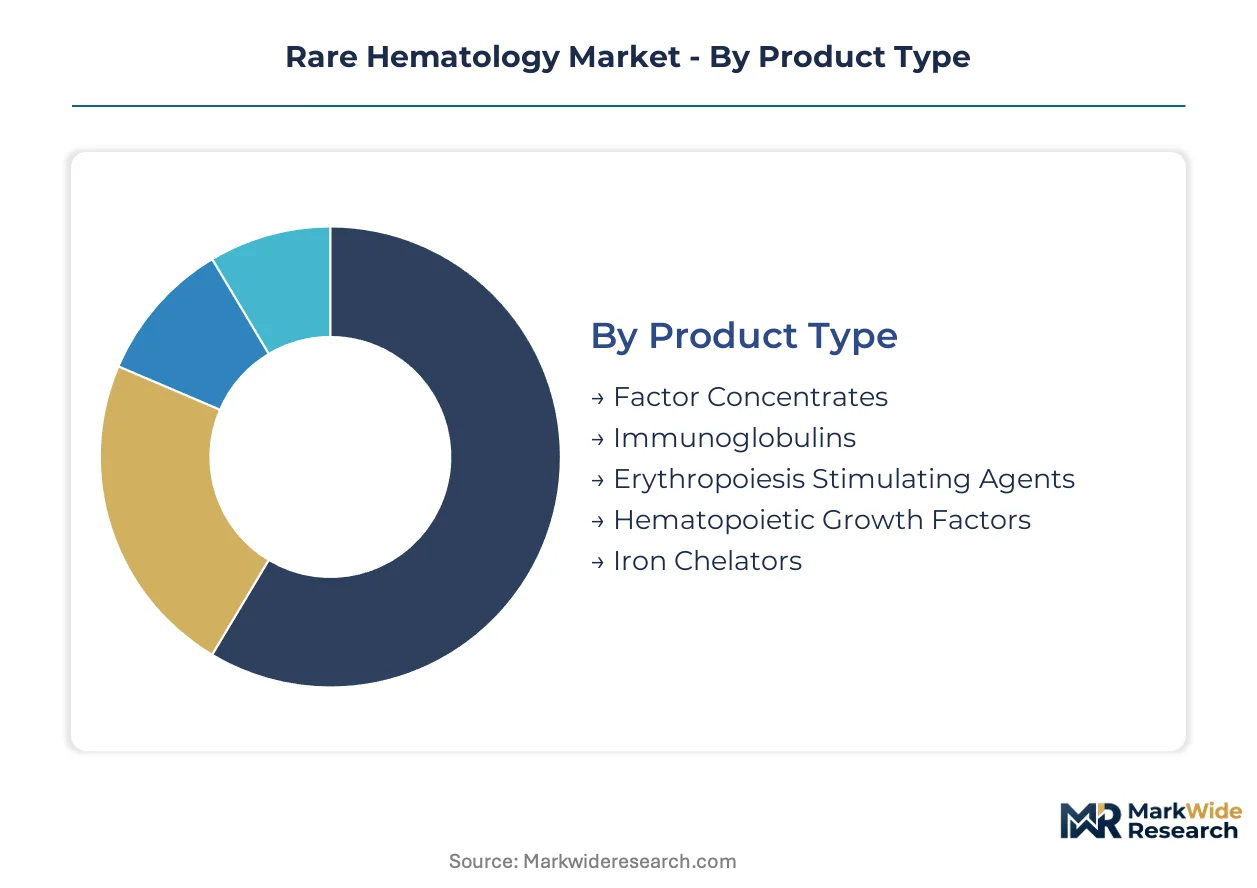
Segmentation analysis within the rare hematology market provides a granular understanding of where clinical needs are most acute and where investment yields the highest therapeutic impact. This breakdown clarifies the diverse treatment modalities and patient care settings that characterize this complex medical field.
Product Type:
Margin pools within the product type category are heavily concentrated in novel, high-cost therapies, particularly those offering potential curative outcomes.
- Immunoglobulins:These protein preparations contain antibodies derived from human plasma, used to treat immunodeficiencies or autoimmune conditions in rare hematology. Demand is growing in European markets for conditions requiring immune modulation, driven by increasing diagnostic rates.
- Factor Concentrates:These purified or recombinant protein products replace missing clotting factors in patients with hemophilia or Von Willebrand Disease. Utilization remains high in specialized treatment centers globally, supported by established reimbursement pathways.
- Erythropoiesis Stimulating Agents:These agents stimulate red blood cell production, primarily used for anemia associated with chronic kidney disease or chemotherapy.
- Hematopoietic Growth Factors:These proteins stimulate the production of blood cells, crucial for patients undergoing chemotherapy or bone marrow transplantation.
- Iron Chelators:These medications remove excess iron from the body, a common complication in patients with chronic transfusions like those for thalassemia.
Factor Concentrates holds installed capacity. Immunoglobulins is rotating up the share rankings.
Therapy Area:
The therapy area segmentation highlights the diverse clinical applications that drive demand across the rare hematology market.
- Hemophilia A:This inherited bleeding disorder results from a deficiency in clotting Factor VIII, requiring lifelong replacement therapy or gene therapy. Advanced treatments are gaining traction in the United States, driven by regulatory approvals for novel gene therapies.
- Hemophilia B:Characterized by a deficiency in clotting Factor IX, this condition also benefits from factor replacement and emerging gene therapy options. Germany shows significant investment in specialized care for these patients, facilitating access to innovative treatments.
- Thalassemia:This inherited blood disorder involves abnormal hemoglobin production, often requiring regular blood transfusions and iron chelation.
- Von Willebrand Disease:This common inherited bleeding disorder affects blood clotting due to a deficiency or defect in von Willebrand factor.
- Aplastic Anemia:This rare condition occurs when the body stops producing enough new blood cells, often requiring immunosuppressants or bone marrow transplant.
Value is concentrating in Hemophilia A. Hemophilia B is expanding most quickly.
End User:
The end user category reflects where patient volume and specialized expertise converge for the administration of complex rare hematology treatments.
- Specialized Treatment Centers:These facilities offer comprehensive care for complex blood disorders, centralizing expertise for diagnosis, treatment, and ongoing patient management. They remain critical for intravenous delivery and monitoring of advanced therapies.
- Home Care Settings:Patients self-administer therapies or receive care from visiting nurses in their homes, reducing reliance on hospital visits for routine treatments. Telehealth integration supports remote monitoring, enhancing convenience for stable patients.
- Ambulatory Care Clinics:These outpatient facilities provide diagnostic and therapeutic services for less complex cases or follow-up care.
- Blood Banks:These facilities collect, store, and process blood components, supplying essential products like plasma-derived therapies and transfusions.
- Research Laboratories:These institutions conduct studies on rare hematological disorders, focusing on disease mechanisms, diagnostics, and new therapeutic targets.
Specialized Treatment Centers drive the majority of treatment volume. Home Care Settings are gaining share fastest.
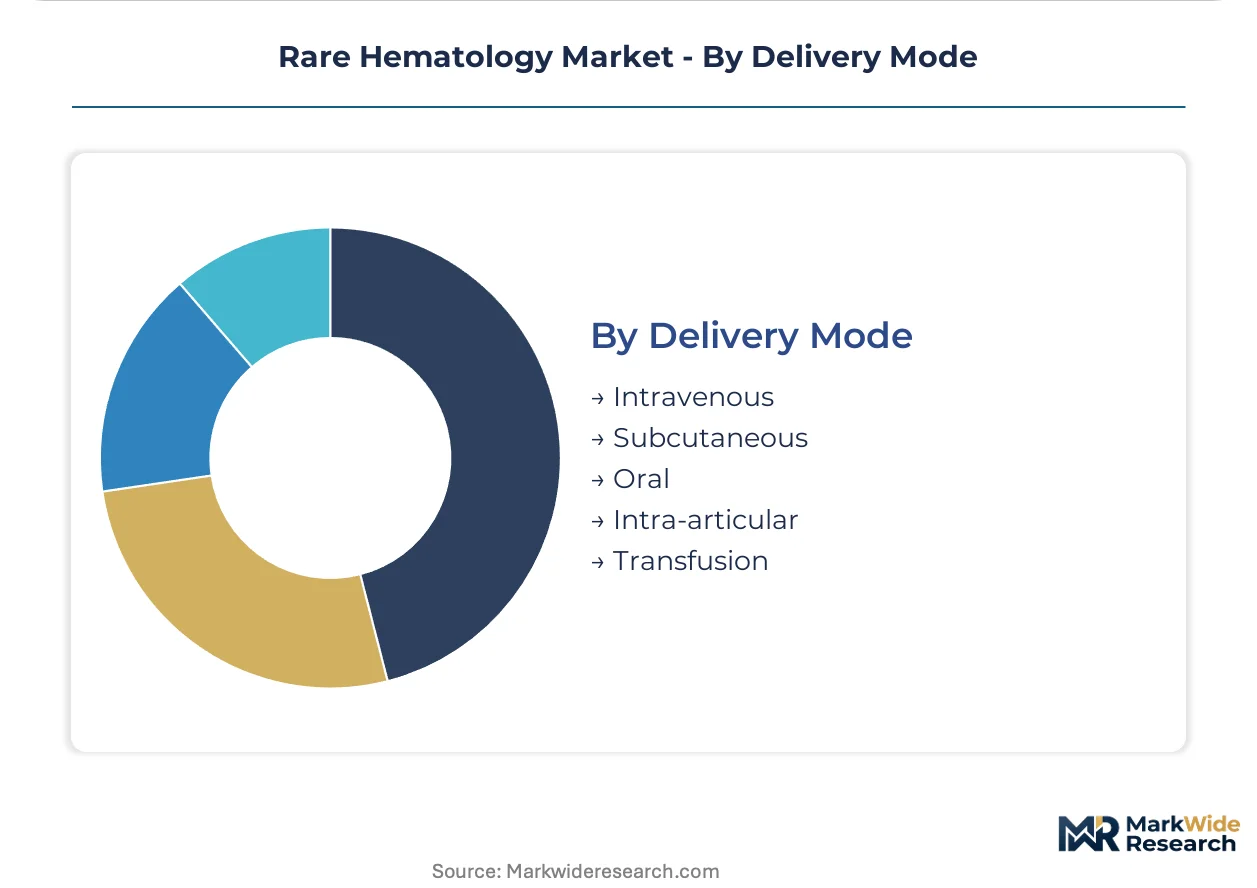
Delivery Mode:
The delivery mode segmentation reflects varying patient convenience and associated costs, influencing treatment adherence and healthcare resource allocation.
- Intravenous:Therapies are administered directly into the bloodstream, ensuring rapid onset and high bioavailability, but often requiring clinical supervision. This mode is prevalent for high-dose factor replacement and gene therapies in specialized centers.
- Subcutaneous:Medications are injected under the skin, offering greater patient independence and home administration for chronic conditions. This method reduces the need for frequent clinic visits, improving patient quality of life.
- Oral:Medications are taken by mouth, representing the least invasive and most convenient delivery method for certain rare hematology treatments.
- Intra-articular:Therapies are injected directly into a joint space, primarily used for localized treatment of joint bleeds in hemophilia patients.
- Transfusion:Blood components or whole blood are transferred into a patient's circulatory system, a critical intervention for severe anemia or bleeding disorders.
Intravenous administration remains the gold standard for acute care. Subcutaneous delivery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The rare hematology market exhibits varying import-export dynamics across key regions, reflecting differences in manufacturing capabilities and access to advanced therapies. Developed economies often import specialized treatments while developing nations focus on establishing local production. This balance influences market access and pricing strategies for novel therapeutics.
United States
Demand for gene therapies is high, driven by a large patient population and advanced healthcare infrastructure. The FDA's orphan drug designation provides significant incentives for developers. Biopharmaceutical clusters in Boston and San Francisco lead research and commercialization efforts for cutting-edge treatments.
Germany
Germany's healthcare system supports specialized treatment centers, fostering high utilization of factor concentrates and immunoglobulins. Specific reimbursement policies from the Federal Joint Committee (G-BA) ensure access to innovative rare disease therapies. Munich and Berlin are hubs for biotech firms developing new hematology solutions.
Japan
Japan presents a strategic opportunity due to specific reimbursement policies for innovative drugs and a strong focus on advanced medical care. The Pharmaceuticals and Medical Devices Agency (PMDA) accelerates review processes for therapies addressing unmet needs. Pharmaceutical research parks in Tokyo and Osaka drive R&D in rare blood disorders.
United Kingdom
The United Kingdom's National Health Service (NHS) prioritizes cost-effectiveness for high-cost rare disease treatments. The Medicines and Healthcare products Regulatory Agency (MHRA) streamlines approvals for orphan drugs. Biotech centers around Cambridge and London foster innovation in genetic medicines.
France
French healthcare emphasizes patient access to specialized care for rare conditions like hemophilia. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) supports early access programs for novel therapies. Paris and Lyon host significant pharmaceutical research and development activities.
Rare Hematology Market Key Industry Players
Concentration sits with established pharmaceutical giants leveraging extensive R&D and global distribution networks. The market exhibits a tiered structure, with large diversified players alongside specialized niche innovators. Strategic archetypes include integrated biopharmaceutical companies with broad portfolios and agile gene therapy developers. Companies pursue portfolio diversification through M&A and strategic partnerships to expand their market presence and technology base.
Among the integrated global biopharmaceutical companies, Pfizer and CSL Behring represent firms with diversified portfolios spanning traditional and next-generation therapies. Meanwhile, bluebird bio exemplifies a niche innovator specializing in high-cost, curative genetic medicines. These companies occupy distinct positions within the market, reflecting varied approaches to product development and commercialization. Their strategies often involve balancing established product lines with significant investment in novel therapeutic modalities. Such firms contribute to the dynamic shifts observed in capital allocation and competitive positioning.
| Leading Market Players |
|---|
| AstraZeneca |
| Novartis |
| Pfizer |
| Bayer |
| Sanofi |
| CSL Behring |
| bluebird bio |
| Bristol Myers Squibb |
| Roche |
| Others |
Cost & Logistics Intelligence
The U.S. FDA and European Medicines Agency (EMA) orphan drug designations gate supply qualification for novel rare hematology treatments, simultaneously enabling premium price differentiation for these specialized therapies. This interplay significantly impacts market access and commercial viability for advanced medicines.
Pricing Analysis
Value-based reimbursement models, particularly for one-time curative gene therapies, represent the dominant pricing structure. Price differentiation stems from the novelty of gene therapies and the complexity of their administration in Specialized Treatment Centers. Pricing pressure stems from the multi-million dollar cost of single-administration gene therapies, creating access challenges for payers. Payers and integrated healthcare networks exhibit high price sensitivity, while patients with life-threatening conditions demonstrate lower sensitivity for effective treatments.
Supply Chain Analysis
Port congestion and specialized cold-chain logistics for cell-based therapies significantly impact inbound costs and supply integrity. Geographic supply concentrates in the United States, Germany, and Japan for advanced biopharmaceuticals. Raw material dependencies include human plasma for immunoglobulins and viral vectors for gene therapies. Manufacturing bottlenecks for cell and gene therapies present a structural risk due to specialized facility requirements. Distribution runs through Specialized Treatment Centers, with increasing direct-to-patient models for home care settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a significant service-attach opportunity, with patient monitoring and data-driven support services expanding faster than the core therapeutic products.
For Market Incumbents:Fortify established market positions by investing in large-scale manufacturing capabilities for factor concentrates and immunoglobulins. Diversify portfolios through strategic R&D into next-generation therapies, including non-viral gene delivery systems, to counter niche innovators. Leverage existing channel control through Specialized Treatment Centers to integrate new diagnostic and patient management solutions, addressing emerging competitive threats from agile biotech firms.
For New Entrants and Emerging Players:Anchor in unmet clinical needs within less common rare hematological conditions, developing targeted gene therapies. The Japanese market, with its specific reimbursement policies for innovative drugs, offers a penetrable segment for novel therapies like those for Von Willebrand Disease. Pursue early regulatory engagement through programs like EMA PRIME to streamline authorization and secure patient advocacy group partnerships for market entry.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with specialized biotech firms developing advanced gene therapy platforms. The market demonstrates long-term viability driven by continuous innovation in rare disease treatment over the next decade. Target acquisition profiles include contract development and manufacturing organizations (CDMOs) specializing in viral vector production. The signal to watch for inflection is the consistent demonstration of long-term efficacy and safety data for novel genetic medicines.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market access for novel gene therapies addressing unmet needs. |
| Manufacturing Scale-Up | Addresses supply constraints for complex cell and gene therapies globally. |
| Regulatory Approval Pathway | Streamlines market entry for orphan drugs in key regions like the US and EU. |
| Hospital System Partnership | Enhances patient access and administration of complex treatments efficiently. |
| Telehealth Integration | Improves patient monitoring and reduces logistical burdens for home care therapies. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, clinical trial registries, and healthcare expenditure reports. Primary interviews engaged hematologists, specialized treatment center administrators, regulatory affairs leads, and payer access specialists. This approach allowed for robust bottom-up and top-down triangulation of market data and insights.
Segmentation dimensions modeled include product type, therapy area, end-user, delivery mode, and regional regulatory clusters across the analysis window. Forecasted Compound Annual Growth Rates were derived from historical trends, projected market shifts, and expert consensus. Key industry-specific forecast inputs included anticipated gene therapy approval timelines and the impact of orphan drug designations on market penetration.
Decision-makers should treat outputs as directional under assumptions of stable regulatory landscapes and sustained R&D investment; material deviation would warrant model refresh. Unforeseen long-term safety issues for novel gene therapies or significant shifts in reimbursement policies represent key risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Blood Screening Market
Hematology
Transfusion Dependent Thalassaemia Management Market
Hematology
Radiation-Induced Myelosuppression Treatment Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Global Hematology Market
Hematology
Polycythemia Vera Market
Hematology
AL Amyloidosis Therapeutics Market
Hematology
Hemoglobin Testing Systems Market
Hematology
Small Lymphocytic Lymphoma Market
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Hemoglobin Analyzer Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Lymphoma Treatment Market
Hematology
Neutropenia Treatment Market
Hematology
Allogeneic Stem Cell Therapy Market
Hematology
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market