
 IV Infusion Gravity Bags Market | 2026-2036
IV Infusion Gravity Bags Market Size, Share, and Industry Trends Forecast 2026-2036
IV Infusion Gravity Bags Market Outlook
Asset-light leasing models for infusion equipment is reconfiguring competitive dynamics, enabling smaller regional distributors to challenge established manufacturers without capital-intensive manufacturing investments. Baxter International Inc. leverages its integrated plasma and pharmaceuticals portfolio to sustain captive demand for proprietary bag systems. Fresenius Kabi AG anchors European hospital supply contracts through direct channel control over compounding pharmacy workflows. ICU Medical, Inc. differentiates via needlefree connector compatibility that locks gravity bag purchasers into extended consumable ecosystems.
IV infusion gravity bags are flexible polymer containers designed for passive fluid delivery using hydrostatic pressure, typically manufactured from PVC, EVA, or polypropylene films ranging from 50 mL to 3000 mL capacity, with integrated ports for spike insertion and medication injection. These devices serve as the primary delivery mechanism for crystalloid solutions, blood products, and parenteral nutrition in settings lacking electronic pump infrastructure. Large volume bags dominate procurement volumes in acute care due to standardized hydration protocols, while specialty bags carrying dual-chamber designs for antibiotic reconstitution command premium positioning. The material dimension reveals accelerating displacement of PVC formulations by EVA and polypropylene alternatives as hospitals confront phthalate exposure liability and incineration disposal restrictions.
FDA approval requirements for 510(k) clearance of novel bag materials impose multi-year validation timelines that entrench incumbent suppliers with established biocompatibility dossiers. ISO 15747 standards for plastic containers for parenteral solutions and EU MDR technical documentation mandates collectively elevate compliance costs for market entry, particularly for Asian manufacturers targeting Western health systems. CE marking under the EU Medical Device Regulation now requires notified body involvement for all gravity bag classifications, narrowing the field of European-authorized suppliers. Stakeholders must monitor evolving state-level restrictions on PVC in healthcare procurement, as California's environmental purchasing criteria and similar frameworks in Germany and France are beginning to encode material preferences into binding tender specifications.
Market Dynamics
Material transition pressure from phthalate-free mandates is compressing PVC bag margins while accelerating EVA and polypropylene qualification programs across hospital procurement networks.
Growth Catalysts
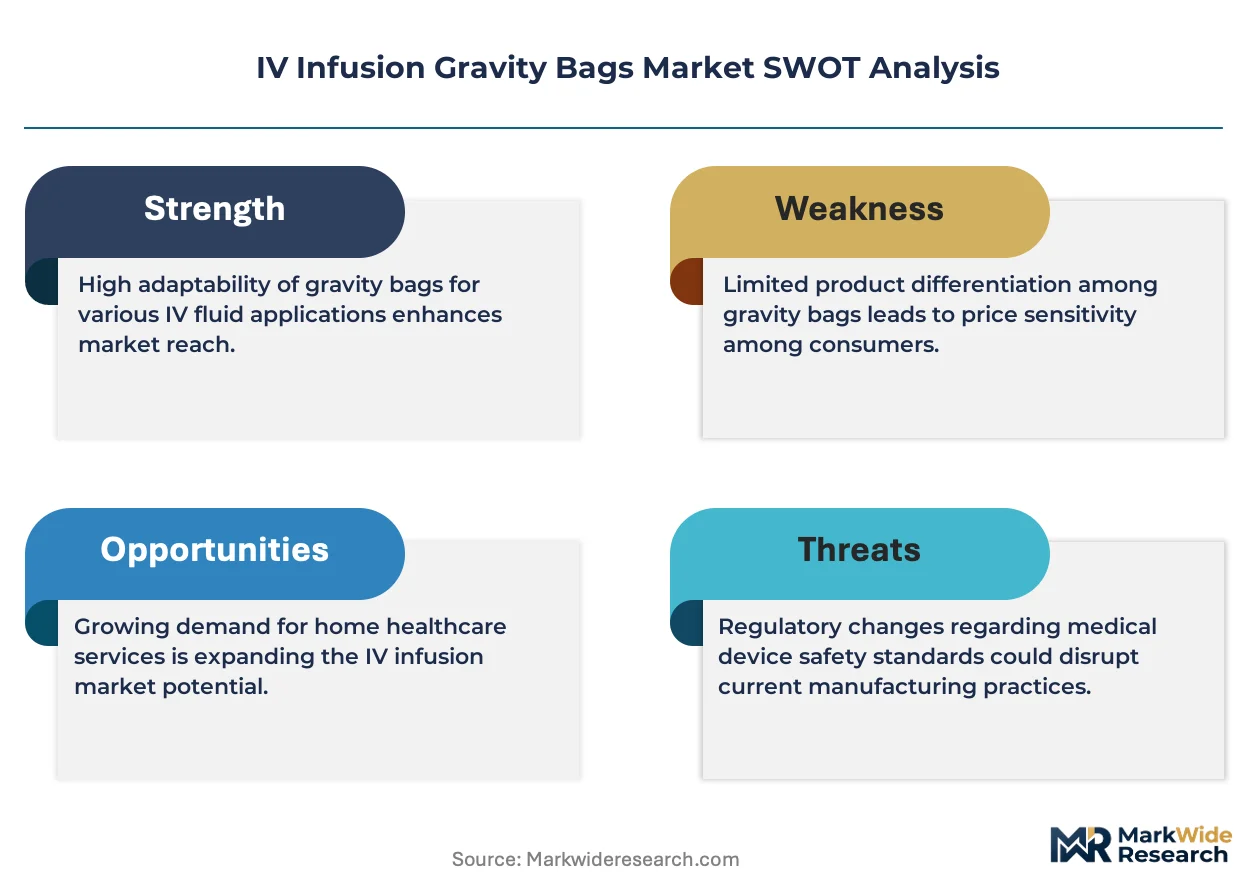
- EU MDR compliance deadlines:European hospitals are consolidating supplier relationships ahead of full technical documentation enforcement, favoring established manufacturers with notified body relationships.
- Tier-2 and tier-3 Indian cities:Government health infrastructure schemes are extending parenteral administration access beyond metropolitan hospital networks.
- Incineration disposal restrictions:Chlorinated polymer bans in healthcare waste management are forcing material specification changes in tender documents.
Market Restraints
- 510(k) validation timelines:FDA multi-year clearance requirements for novel bag materials entrench incumbent suppliers with established biocompatibility dossiers.
- Asian manufacturer concentration:Western health system entry costs for ISO 15747 compliance and EU MDR technical documentation narrow the authorized supplier field.
- Electronic pump substitution:Precision infusion requirements in oncology and critical care are displacing gravity-dependent delivery in high-acuity settings.
Strategic Opportunities
- Asset-light leasing models:Regional distributors are challenging established manufacturers through equipment rental without capital-intensive manufacturing investments.
- Dual-chamber antibiotic reconstitution bags:Specialty designs for immediate-use antimicrobial preparation command premium positioning in infection control protocols.
- California environmental purchasing criteria:State-level PVC restrictions in healthcare procurement are encoding material preferences into binding tender specifications.
Industry Challenges
- Polymer formulation expertise:EVA and polypropylene film processing requires distinct extrusion and sealing competencies absent from legacy PVC manufacturing workforces.
- Legacy spike port incompatibility:Needlefree connector standardization delays are creating integration friction with existing hospital inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IV Infusion Gravity Bags Market |
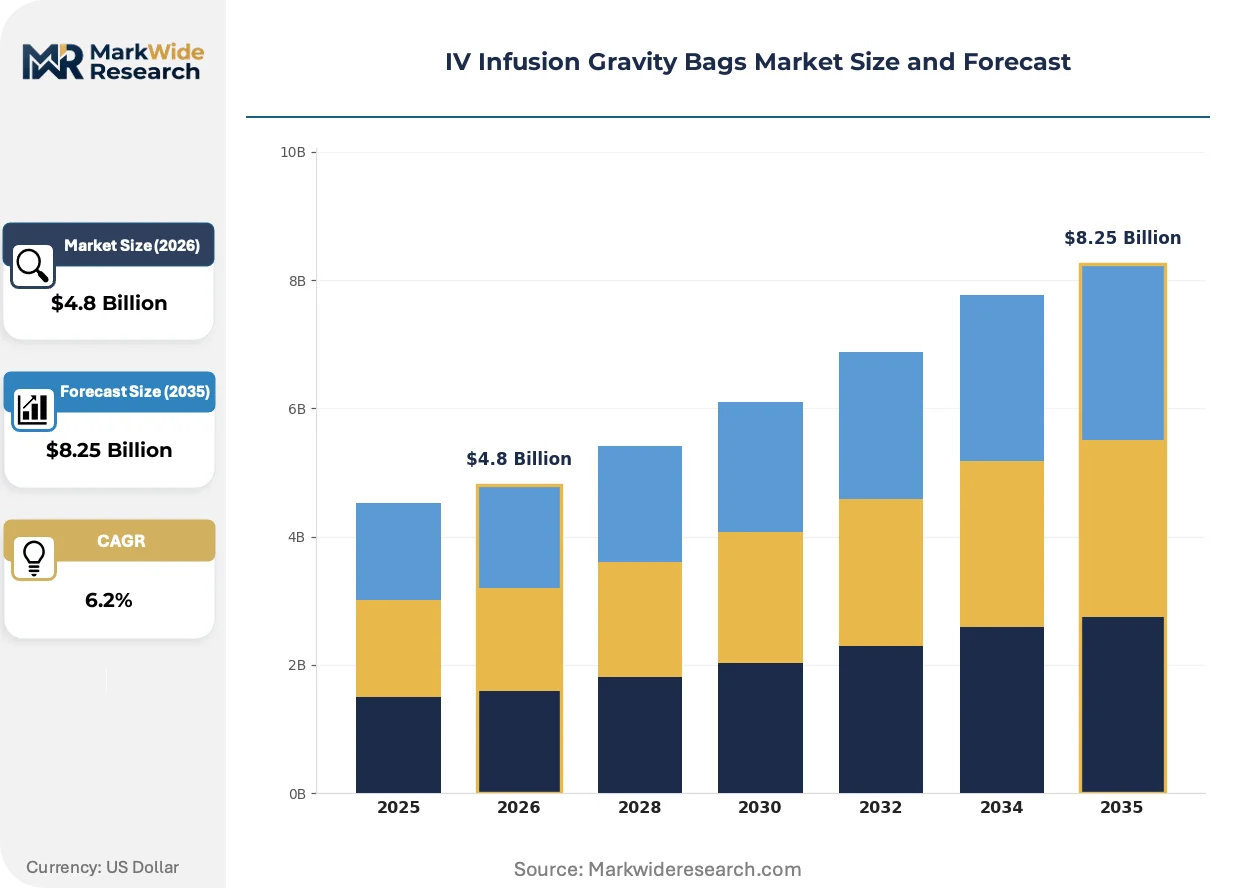
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bags, Pediatric Bags, Large Volume Bags, Specialty Bags Material: PVC, EVA, Polypropylene, Polyethylene End User: Hospitals, Clinics, Home Care, Ambulatory Surgical Centers Regulatory Compliance: ISO Standards, CE Marking, FDA Approval, GMP Compliance |
| Companies Covered | Baxter International Inc., ICU Medical, Inc., Terumo BCT Ltd., B. Braun Melsungen AG, Fresenius Kabi AG, Sippex IV Bag, GVS, Kraton Corporation, Renolit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IV Infusion Gravity Bags Market Strategic Shifts
Passive fluid delivery systems are undergoing material reconstruction as regulatory toxicity thresholds tighten and hospital sustainability mandates harden into procurement rules.
EVA film formulations are migrating from niche pediatric applications toward mainstream adult hydration protocols. Academic medical centers in Germany and France are piloting phthalate-free standardization across all crystalloid administration. This technology is migrating from specialty positioning to volume procurement, compressing PVC-dependent supplier margins while opening qualification pathways for polymer converters with pharmaceutical-grade extrusion capabilities.
REACH restrictions on phthalate plasticizers are accelerating PVC displacement timelines in European healthcare procurement. The ECHA authorization process for DEHP alternatives is forcing reformulation investments across legacy manufacturing lines. German university hospitals are responding fastest, embedding material compliance into GPO contract renewal clauses ahead of 2027 enforcement milestones.
Hospital buying consortia are consolidating supplier panels around integrated fluid management ecosystems rather than standalone bag procurement. Regional GPOs in the United States are unbundling gravity bag contracts from pump consumable agreements, creating direct channel openings for specialty polymer manufacturers. This pattern is most visible in the southeastern states, where health system mergers have compressed vendor counts by half since 2022.
IV Infusion Gravity Bags Market Segmentation
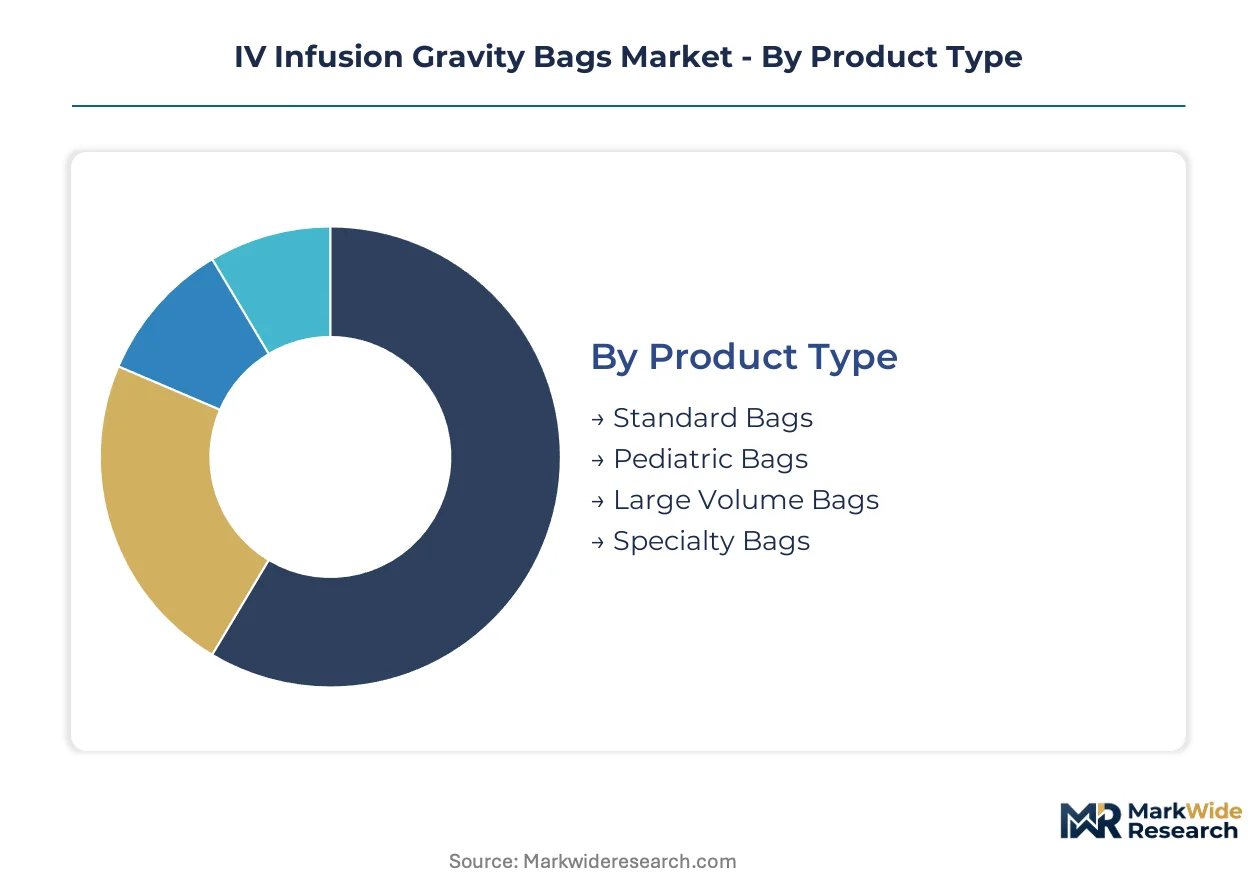
IV infusion gravity bags demand heterogeneous technical specifications across clinical settings, with material composition and volume capacity driving procurement differentiation. Segmentation reveals how regulatory compliance tiers and end-use infrastructure shape supplier positioning and margin structures.
Product Type:
After-sales service intensity varies sharply across bag formats, with specialty designs requiring technical training support while standard formats rely on volume logistics.
- Large Volume Bags:These 500 mL to 3000 mL containers dominate acute care hydration protocols with standardized crystalloid delivery. Demand concentrates in Indian government hospital expansion programs across tier-2 and tier-3 cities, where pump infrastructure remains limited and passive delivery suffices for volume resuscitation.
- Specialty Bags:Dual-chamber configurations enable immediate-use antibiotic reconstitution through separated drug and diluent compartments. German university hospitals are embedding these into infection control procurement clauses, commanding premium positioning through reduced contamination risk and compounding pharmacy workflow integration.
- Standard Bags:Single-chamber designs for routine crystalloid administration serve cost-sensitive procurement networks.
- Pediatric Bags:Reduced-volume formats with precision graduated markings address neonatal and pediatric fluid management requirements.
Large Volume Bags holds the largest share; momentum sits with Specialty Bags.
Material:
Cost tier stratification separates legacy polymer investments from next-generation qualification programs, with premium formulations capturing share in regulated health systems.
- EVA:Ethylene-vinyl acetate films deliver phthalate-free flexibility with superior cold-temperature performance for blood product storage. REACH restrictions on DEHP plasticizers are accelerating qualification timelines across European hospital networks, particularly in France where environmental purchasing criteria now encode material preferences.
- Polypropylene:This polymer offers incineration-compliant disposal with no chlorine content, satisfying healthcare waste management bans in Germany and California. Extrusion and sealing competencies differ fundamentally from PVC manufacturing, creating capability scarcity among legacy converters.
- PVC:Chlorinated polymer formulations face margin compression from phthalate exposure liability and disposal restrictions.
- Polyethylene:Lower-cost alternative with limited flexibility for complex port integration and specialized clinical applications.
PVC retains volume dominance; EVA is climbing the fastest as regulatory toxicity thresholds tighten.
End User:
Application intensity determines bag specification complexity, with high-acuity settings demanding integrated safety features versus basic hydration in community settings.
- Hospitals:Acute care networks drive procurement standardization across crystalloid, blood product, and parenteral nutrition administration. India's government health infrastructure schemes are extending access beyond metropolitan centers, creating volume concentration in emerging economy hospital expansion.
- Home Care:Ambulatory patients receiving long-term parenteral nutrition or hydration require simplified spike interfaces and portable formats. This segment is expanding most quickly as early discharge protocols and palliative care networks mature in Western health systems.
- Clinics:Outpatient facilities prioritize cost-efficient standard bags for routine infusion therapies.
- Ambulatory Surgical Centers:Same-day procedure volumes drive demand for pre-filled and immediate-use configurations.
Hospitals command the largest share; Home Care shows steepest expansion trajectory.
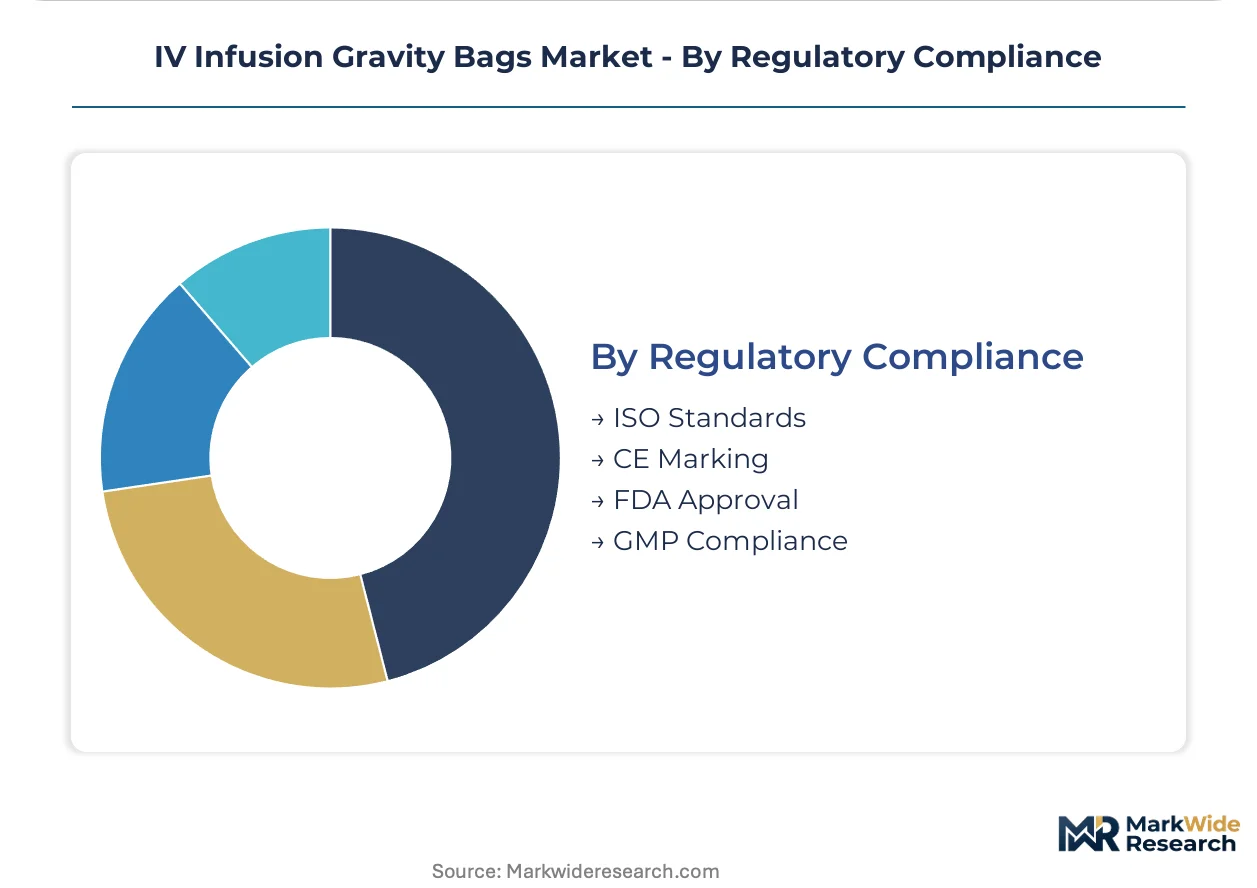
Regulatory Compliance:
Margin tier separation is pronounced, with notified body relationships and biocompatibility dossiers creating sustainable competitive moats.
- FDA Approval:510(k) clearance requirements for novel bag materials impose multi-year validation timelines that entrench incumbent suppliers. Established dossiers for EVA and polypropylene alternatives provide defensive positioning against Asian manufacturers lacking U.S. regulatory infrastructure.
- CE Marking:EU MDR technical documentation mandates and notified body involvement for all gravity bag classifications have narrowed the European-authorized supplier field. Consolidation of hospital supplier relationships ahead of full enforcement is favoring established manufacturers with existing relationships.
- ISO Standards:ISO 15747 compliance for plastic containers for parenteral solutions elevates entry costs for market participation.
- GMP Compliance:Pharmaceutical-grade manufacturing standards govern contract manufacturing relationships and private label supply.
FDA Approval represents the highest barrier; CE Marking is gaining strategic weight fastest as European technical documentation enforcement hardens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government health infrastructure schemes are redirecting procurement volumes toward emerging economies while REACH restrictions and FDA scrutiny reshape material specifications in established markets. Hospital expansion programs in tier-2 and tier-3 cities are creating new demand centers outside traditional metropolitan networks.
United States
California's environmental purchasing criteria now encode PVC restrictions into binding tender specifications for state-funded healthcare facilities. The FDA maintains multi-year 510(k) validation timelines for novel bag materials, entrenching suppliers with established biocompatibility dossiers. The southeastern states exhibit compressed vendor counts following health system mergers since 2022.
Germany
University hospitals are embedding phthalate-free standardization into GPO contract renewal clauses ahead of 2027 REACH enforcement milestones. The ECHA authorization process for DEHP alternatives forces reformulation investments across legacy manufacturing lines. The Baden-Württemberg industrial corridor hosts polymer converters developing pharmaceutical-grade extrusion capabilities for EVA migration.
India
Central government health infrastructure schemes extend parenteral administration access beyond metropolitan hospital networks into tier-2 and tier-3 cities. The CDSCO regulates medical device imports while domestic manufacturing incentives accelerate local production qualification. Maharashtra and Gujarat host expanding polymer film processing clusters serving government procurement contracts.
France
Environmental purchasing criteria now encode material preferences into hospital tender specifications, accelerating EVA qualification timelines. The ANSM oversees medical device vigilance for plasticizer exposure liability in neonatal and pediatric settings. The Île-de-France academic medical center cluster pilots phthalate-free standardization across crystalloid administration protocols.
China
The NMPA implements stricter biocompatibility documentation requirements for imported polymer containers while domestic manufacturers scale EVA and polypropylene production. Provincial hospital procurement consortia in Jiangsu and Zhejiang consolidate supplier relationships around integrated fluid management ecosystems. The Yangtze River Delta concentration of polymer converters is expanding pharmaceutical-grade film extrusion capacity.
IV Infusion Gravity Bags Market Competitive Environment
Channel-controlling players compete with product-specialist players across divergent margin structures. The market exhibits tiered consolidation with integrated healthcare conglomerates anchoring hospital supply contracts while regional distributors exploit asset-light leasing models. Two strategic archetypes dominate: plasma-pharmaceutical integrators sustaining captive demand for proprietary systems, and polymer converters with pharmaceutical-grade extrusion capabilities capturing material transition premiums. Competitive moves center on backward integration into polymer film production and direct channel control over compounding pharmacy workflows.
Among integrated healthcare conglomerates, Baxter International Inc., Fresenius Kabi AG, and ICU Medical, Inc. occupy positions exemplifying divergent competitive strategies. Baxter represents the plasma-pharmaceutical integrator archetype with cross-portfolio captive demand generation. Fresenius Kabi anchors European positioning through hospital supply contract density. ICU Medical exemplifies the consumable ecosystem approach with needlefree connector compatibility creating extended purchaser relationships. These three entities collectively illustrate how channel control, material qualification, and workflow integration serve as distinct vectors for competitive differentiation in a market undergoing regulatory-driven material reconstruction.
| Leading Market Players |
|---|
| Baxter International Inc. |
| ICU Medical, Inc. |
| Terumo BCT Ltd. |
| B. Braun Melsungen AG |
| Fresenius Kabi AG |
| Sippex IV Bag |
| GVS |
| Kraton Corporation |
| Renolit |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European EVA film extrusion is tightening supplier pricing power while compressing PVC-dependent margins across hospital procurement networks. This utilization imbalance drives divergent behavior: established polymer converters command premium positioning for phthalate-free formulations, while legacy PVC manufacturers absorb cost compression to retain volume relationships.
Pricing Analysis
Certification level creates the primary spread across procurement tiers, with FDA-grade EVA formulations commanding substantial premiums over CE-marked standard bags and unregistered economy alternatives. Three-tier pricing structure separates premium phthalate-free specialty bags from standard crystalloid containers and basic hydration formats. Pricing pressure stems from REACH-driven material transition costs accelerating faster than procurement budget adjustments. Government hospital buyers in emerging economies exhibit highest price sensitivity, while German university hospital GPOs prioritize material compliance over unit cost.
Supply Chain Analysis
Upstream polymer feedstock availability centers on petrochemical complexes in Germany, the United States, and Saudi Arabia for EVA and polypropylene resin supply. Film extrusion capacity concentrates in the Baden-Württemberg corridor, Massachusetts industrial belt, and Maharashtra polymer clusters. Raw material dependencies include ethylene-vinyl acetate copolymer, polypropylene homopolymer, and medical-grade plasticizers. Single-source vulnerability sits with European notified body relationships for EU MDR compliance. Distribution runs through hospital GPO contracts, regional medical distributors, and direct channel relationships with compounding pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IV infusion gravity bags occupy an early-cycle expansion phase as material transition mandates create replacement demand across installed hospital infrastructure. India's government health infrastructure schemes represent the most visible penetration tailwind, extending parenteral administration access into previously underserved urban tiers.
For Market Incumbents: Insulate core hospital supply contracts through backward integration into pharmaceutical-grade polymer film production and accelerated EU MDR technical documentation completion. Electronic pump substitution in oncology and critical care segments threatens gravity-dependent volume; defend positioning via integrated fluid management ecosystem bundling that locks purchasing committees into extended consumable relationships. For New Entrants and Emerging Players: Tier-2 and tier-3 Indian cities represent the most penetrable entry point, where government procurement expansion outpaces established supplier capacity allocation. Asset-light leasing models for infusion equipment enable regional distributors to challenge capital-intensive manufacturers without extrusion infrastructure investment. Target qualification pathway acceleration through CDSCO domestic manufacturing incentives and partnership with Maharashtra polymer converters. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EVA and polypropylene film extrusion as pharmaceutical-grade cleanroom requirements and notified body relationship investments reshape competitive economics. Acquisition targets should emphasize polymer converters with existing biocompatibility dossiers and European hospital GPO contract density. Monitor CDSCO import regulation tightening and California environmental purchasing criteria expansion as signals for material transition acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Notified body relationships narrow the European-authorized supplier field ahead of enforcement milestones. |
| Backward Integration into Polymer Film Production | Captive EVA extrusion capabilities capture material transition premiums from REACH-driven PVC displacement. |
| Hospital System Partnership | Direct channel control over compounding pharmacy workflows anchors European supply contract renewal. |
| Dual-Chamber Antibiotic Reconstitution Bag Launch | Immediate-use antimicrobial preparation commands premium positioning in German infection control protocols. |
| Asset-Light Equipment Leasing Model | Regional distributors challenge established manufacturers without capital-intensive manufacturing investments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and polymer converter plant managers. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, CDSCO medical device registration records, hospital procurement contract disclosures, and REACH authorization timelines. Bottom-up volume estimates from individual hospital network expansion programs were triangulated against top-down polymer film production capacity assessments.
Calibration against historical material transition patterns in medical device markets informed projection elasticity assumptions across the analysis window. Segmentation modeling spanned product type, material composition, end-user setting, and regulatory compliance tier. CAGRs were derived from weighted average of adoption curve penetration and replacement cycle dynamics. Forecast inputs incorporated REACH enforcement milestone phasing, Indian government health infrastructure expenditure allocations, and FDA validation timeline distributions for novel bag materials.
Practitioners should monitor CDSCO domestic manufacturing incentive expansion and California environmental purchasing criteria adoption for early signals of procurement specification hardening. Forecasts reflect assumptions regarding regulatory enforcement consistency and hospital capital expenditure continuity. Cross-checking against ECHA authorization process timelines and Indian government health budget disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Surgical Dressings and Disposables Market
Medical Supplies
Anesthesia Syringes and Needles Market
Medical Supplies
Global Sterilization Wrap Market
Medical Supplies
South America Syringe Market
Medical Supplies
Plasma Separation Tubes Market
Medical Supplies
US Hospital Consumables Market
Medical Supplies
Surgical Tapes Market
Medical Supplies
Sterilization Box Market
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Western Europe Sterile Gloves Market
Medical Supplies
Ear and Nasal Packing Market
Medical Supplies
Global Medical Elastomers Market
Medical Supplies
Latex Medical Disposables Market
Medical Supplies
Glass Pasteur Pipettes Market
Medical Supplies
Global Respiratory and Anesthesia Disposables Market
Medical Supplies
Global Biohazard Bag Market