
 Celiac Disease Drugs Market | 2026-2036
Celiac Disease Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Celiac Disease Drugs Market Analysis
Combination therapy bundling of oral medications with nutritional supplements is repositioning patient adherence strategies in celiac disease management. Takeda Pharmaceutical Company Limited leverages its gastrointestinal therapeutic expertise to anchor development pipelines for immune-modulating candidates. ImmunogenX sustains specialized R&D focus on enzymatic approaches to gluten degradation. Cour Pharmaceuticals competes through nanoparticle-based immune tolerance platforms targeting the underlying autoimmune mechanism.
Celiac disease drugs comprise pharmaceutical agents designed to modulate immune response, reduce intestinal inflammation, or enzymatically neutralize gluten peptides in patients with gluten-sensitive enteropathy. These formulations typically target HLA-DQ2 or HLA-DQ8 mediated T-cell activation pathways and require demonstration of mucosal healing endpoints in clinical evaluation. Biological agents command the highest development investment intensity due to their potential to address refractory cases unresponsive to strict gluten-free diet adherence. Oral medications occupy the broadest prescriptive base among route-of-administration categories, though subcutaneous delivery formats are gaining traction in biologic segments where patient self-administration drives preference. Tablet formulations lead current dispensing volumes, while powder formats expand in pediatric and dysphagia populations where swallowing compliance presents barriers.
The FDA maintains stringent efficacy benchmarks for celiac disease therapeutics through its Center for Drug Evaluation and Research, while the EMA's Committee for Medicinal Products for Human Use evaluates novel immunomodulators under centralized European procedures. These frameworks shape trial design requirements and prolong development timelines, filtering market entry to well-capitalized developers capable of sustained clinical investment. Stakeholders must monitor regulatory precedent for surrogate endpoint acceptance, as biomarker-based approval pathways would fundamentally alter competitive economics for late-stage candidates.
Market Dynamics
The FDA's orphan drug designation pathway is compressing clinical trial timelines and redistributing R&D capital toward immune-modulating biologics, fundamentally altering how developers prioritize pipeline candidates against strict gluten-free diet alternatives.
Growth Catalysts
- EMA centralized procedures:The Committee for Medicinal Products for Human Use accelerates immunomodulator evaluation timelines, reducing regulatory friction for novel celiac therapeutics entering European markets.
- Hospital-based gastroenterology expansion:Specialist diagnostic infrastructure in tertiary care centers enables earlier pharmaceutical intervention and expands addressable patient populations for biologic therapies.
- Enzymatic gluten degradation:Oral enzyme formulations targeting HLA-DQ2 and HLA-DQ8 peptide neutralization offer adjunctive therapeutic pathways beyond strict dietary management.
Market Restraints
- Mucosal healing endpoint requirements:The FDA's Center for Drug Evaluation and Research mandates stringent efficacy benchmarks that prolong development timelines and filter market entry to well-capitalized developers.
- Biologic manufacturing concentration:Contract development and manufacturing organizations cluster in limited geographic zones, creating supply vulnerability for immune-modulating candidates.
- Gluten-free diet substitution:Zero-cost dietary elimination remains the clinical standard, compressing reimbursement willingness for premium pharmaceutical alternatives.
Strategic Opportunities
- Biomarker-based approval pathways:Surrogate endpoint acceptance by the FDA would fundamentally alter competitive economics and accelerate late-stage candidate commercialization.
- Pediatric powder formulations:Dysphagia-compliant delivery formats address unmet needs in pediatric populations where tablet adherence presents barriers.
- Subcutaneous self-administration:Patient-managed biologic delivery reduces hospital dependency and expands prescriptive flexibility in outpatient gastroenterology settings.
Industry Challenges
- Specialized immunology talent scarcity:Celiac-specific T-cell pathway expertise concentrates in limited academic medical centers, constraining trial design capabilities.
- Legacy gluten detection integration:Pharmaceutical efficacy measurement requires alignment with existing histological assessment protocols, complicating endpoint standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Celiac Disease Drugs Market |
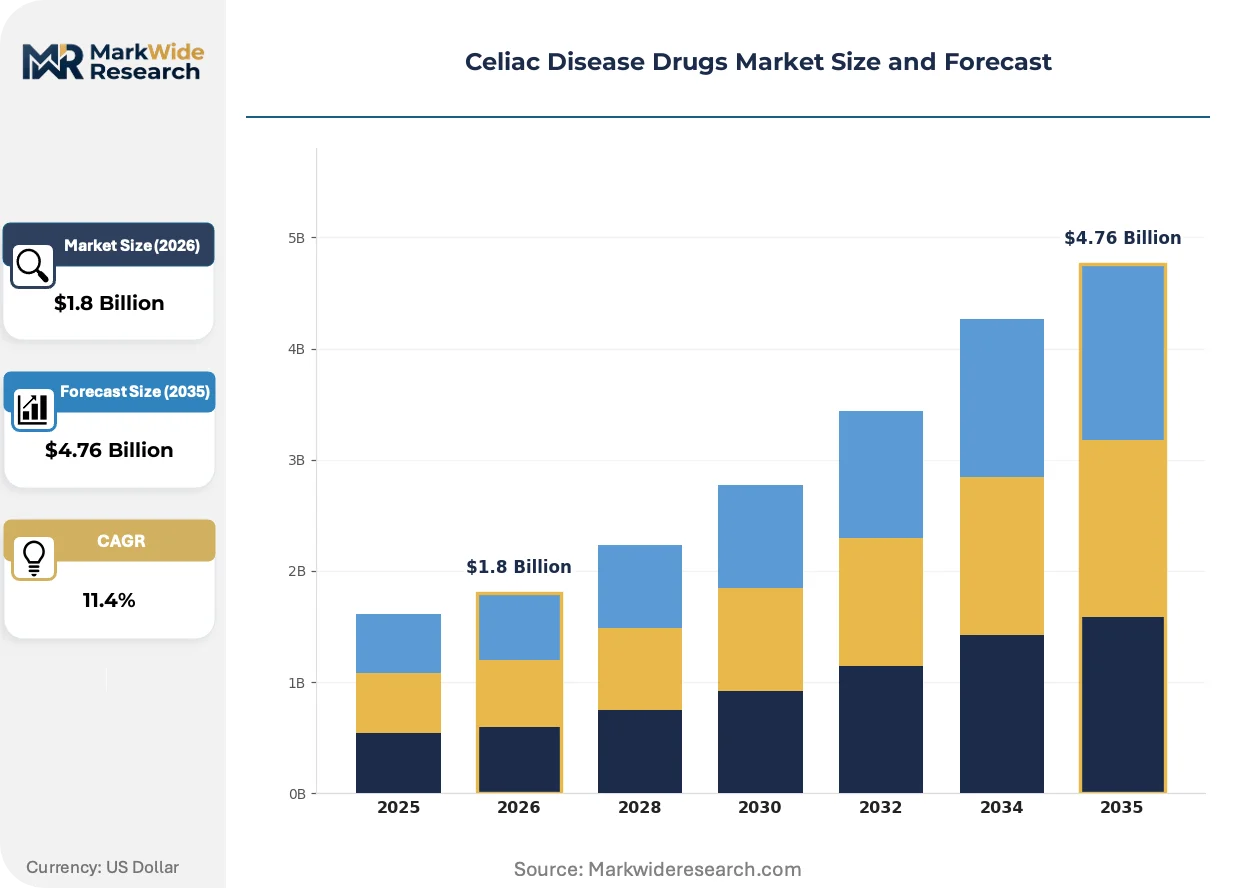
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Oral Medications, Topical Treatments, Nutritional Supplements, Biological Agents Formulation: Tablets, Powders, Capsules, Liquid Solutions Route of Administration: Oral, Subcutaneous, Intravenous, Transdermal End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Takeda Pharmaceutical Company Limited, Teva Pharmaceutical Industries Ltd, ImmunogenX, Cour Pharmaceuticals, Amgen, BioLineRx Ltd, Anokion SA, F. Hoffmann-La Roche Ltd, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Celiac Disease Drugs Market Emerging Trajectories
Oral enzymatic therapies and nanoparticle immune tolerance platforms are actively displacing monotherapy approaches, while regulatory frameworks on both sides of the Atlantic recalibrate approval velocity for autoimmune gastrointestinal indications.
Biologic agents targeting refractory celiac disease are consolidating development investment intensity as hospital-based specialists prioritize immune-modulating candidates over nutritional adjuncts. Gastroenterology departments in tertiary care centers accelerate adoption of subcutaneous delivery formats. This technology compression is narrowing the competitive field to developers with sustained clinical capital reserves.
REACH registration requirements for novel immunomodulator excipients are extending European formulation timelines and forcing developers to qualify alternative delivery vehicle chemistries. The EMA's centralized evaluation procedures absorb these compliance costs into pre-submission phases. Biologic segments bear the heaviest documentation burden, with several candidates reformulating to exclude REACH-flagged stabilizers.
Patient self-administration preferences are fragmenting the prescriptive base between oral enzymatic therapies and injectable biologics, with switching cycles compressing as real-world efficacy data accumulates. Gastroenterology practices in the United States unbundle after-care monitoring from initial prescription decisions. This behavioral rotation is most visible in specialist networks where electronic health record integration enables rapid outcome feedback loops.
Celiac Disease Drugs Market Segmentation
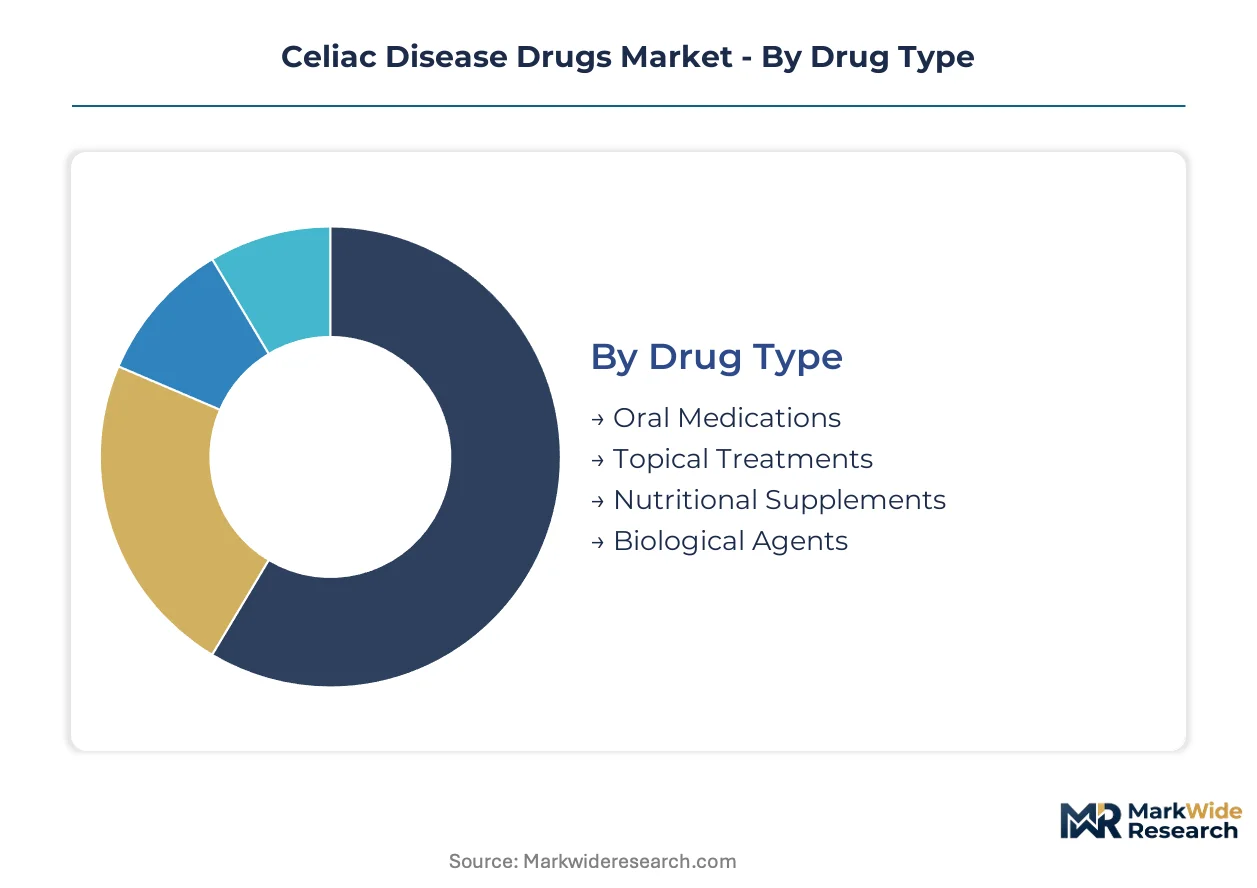
Celiac disease therapeutics fragment across delivery mechanisms, molecular architectures, and care settings that each impose distinct development economics. Segmentation reveals where formulation investments concentrate and which patient populations command premium pricing.
Drug Type:
Customization intensity spans from commoditized nutritional adjuncts to precision-engineered biologics requiring dedicated manufacturing suites.
- Biological Agents:Monoclonal antibodies and fusion proteins targeting IL-15 or CD3 pathways dominate late-stage pipelines. Hospital-based gastroenterology departments in the United States prioritize these for refractory cases where mucosal healing fails under dietary management alone.
- Oral Medications:Small-molecule immunomodulators and tight junction regulators occupy the broadest prescriptive base. Demand concentrates in outpatient settings where patient self-management drives preference for non-injectable alternatives.
- Nutritional Supplements:Gluten-free vitamin and mineral formulations address micronutrient deficiencies secondary to malabsorption.
- Topical Treatments:Dermatological preparations manage cutaneous manifestations of celiac disease including dermatitis herpetiformis.
Most installed capacity flows through Oral Medications. Expansion is steepest in Biological Agents.
Formulation:
Cost tier differentiation separates high-volume solid dosages from specialized formats serving pediatric and geriatric compliance needs.
- Tablets:Immediate-release and enteric-coated solid dosages lead current dispensing volumes. Manufacturing scale economies at CDMOs in Ireland and Switzerland anchor supply for European markets.
- Powders:Sachet and bulk powder formats address dysphagia populations and weight-based pediatric dosing. Demand is climbing fastest in homecare settings where caregivers require flexible administration options.
- Capsules:Hard-shell and soft-gel encapsulation protects acid-labile enzymatic therapies through gastric transit.
- Liquid Solutions:Oral suspensions and emulsions serve patients with severe mucosal damage affecting tablet disintegration.
Tablet production absorbs the majority of active pharmaceutical ingredient throughput. Powder capacity is scaling fastest to serve pediatric expansion.
Route of Administration:
Patient autonomy preferences fragment the prescriptive base between clinic-dependent infusion and self-managed delivery.
- Oral:Gastrointestinal luminal delivery dominates enzymatic and small-molecule categories. The FDA's bioequivalence requirements for modified-release formulations extend development timelines.
- Subcutaneous:Prefilled syringes and autoinjector devices for biologic therapies reduce hospital dependency. Germany's outpatient gastroenterology networks accelerate adoption of patient-administered formats.
- Intravenous:Hospital-based infusion centers administer high-potency immunosuppressants requiring monitoring.
- Transdermal:Patch-based delivery remains experimental for celiac-specific indications.
Oral routes capture the majority of prescription volume. Subcutaneous delivery is gaining share fastest among biologic-eligible patients.
End User:
Care setting determines reimbursement architecture and dictates whether pharmaceutical or dietary interventions dominate therapeutic protocols.
- Hospitals:Tertiary care centers manage refractory cases and biologic initiation. The United Kingdom's NHS specialist referral pathways concentrate complex celiac management in designated gastroenterology units.
- Homecare:Self-administered therapies and nutritional management shift care outside institutional settings. France's reimbursement reforms expand home nursing support for injectable biologics.
- Clinics:Community gastroenterology practices handle diagnosis and maintenance therapy.
- Pharmacies:Retail dispensing supports over-the-counter nutritional supplements and prescription renewals.
Hospital procurement channels handle the majority of biologic value. Homecare is expanding most quickly as self-administration formats proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Celiac disease therapeutic development originated in European academic medical centers during the 1990s, with subsequent commercial scaling concentrated in North American and Western European pharmaceutical clusters. The current geographic distribution reflects this bifurcated heritage between European immunology research and US-based biologics commercialization infrastructure.
United States
The FDA's orphan drug designation pathway and specialist gastroenterology networks in Boston and San Francisco drive biologic therapy adoption. Hospital-based tertiary care centers in these metropolitan areas manage refractory case volumes that justify premium therapeutic investment. The National Institutes of Health maintains celiac disease research consortia that channel academic discovery toward commercial developers.
Germany
Outpatient gastroenterology networks and statutory health insurance reimbursement frameworks create favorable conditions for patient-administered biologics. Munich and Heidelberg host specialized T-cell immunology research institutes that supply talent to pharmaceutical development programs. The country's national pharmaceutical regulator evaluates novel immunomodulators through centralized European procedures that accelerate market access.
United Kingdom
NHS specialist referral pathways concentrate complex celiac management in designated gastroenterology units in London and Manchester. The National Institute for Health and Care Excellence issues technology appraisals that determine reimbursement eligibility for biologic therapies. Academic medical centers in Oxford and Cambridge contribute mucosal healing endpoint expertise to international clinical trial design.
Switzerland
Contract development and manufacturing organizations in Basel and Zurich anchor European supply chains for immune-modulating candidates. Swissmedic maintains stringent efficacy benchmarks that align with FDA standards, facilitating parallel regulatory submissions. The country's pharmaceutical cluster specializes in biologic manufacturing scale-up for autoimmune indications.
Japan
PMDA accelerated approval pathways for orphan diseases compress development timelines for celiac-specific candidates. Tokyo and Osaka gastroenterology departments participate in multinational clinical trials that include Asian patient populations. The Pharmaceuticals and Medical Devices Agency's harmonization with FDA standards enables integrated Pacific Rim development strategies.
Celiac Disease Drugs Market Vendor Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with gastrointestinal therapeutic expertise. Development intensity concentrates among developers capable of sustaining decade-long clinical investment against stringent mucosal healing endpoints. Two strategic archetypes dominate: established biopharmaceutical firms leveraging existing immunology platforms, and specialized biotechnology ventures pursuing mechanistically novel approaches. Competitive moves center on strategic partnerships for T-cell pathway expertise and portfolio diversification into adjacent autoimmune gastrointestinal indications.
Within the diversified pharmaceutical tier, Takeda Pharmaceutical Company Limited and F. Hoffmann-La Roche Ltd occupy positions anchored by broad immunology development infrastructure. Among specialized biotechnology ventures, ImmunogenX and Cour Pharmaceuticals exemplify mechanistic differentiation through enzymatic and nanoparticle platforms respectively. These four entities represent the competitive spectrum from scale-driven commercialization to novel mechanism validation, with each archetype demanding distinct capital deployment profiles and regulatory risk tolerance.
| Leading Market Players |
|---|
| Takeda Pharmaceutical Company Limited |
| Teva Pharmaceutical Industries Ltd |
| ImmunogenX |
| Cour Pharmaceuticals |
| Amgen |
| BioLineRx Ltd |
| Anokion SA |
| F. Hoffmann-La Roche Ltd |
| Sanofi |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up CDMO specialists in Ireland and Switzerland anchor biologic manufacturing capacity, translating concentrated supply control into premium pricing power for immune-modulating therapies while compressing margins for oral enzymatic formulations facing gluten-free diet substitution.
Pricing Analysis
Three-tier pricing structure across premium biologics, standard small-molecules, and economy nutritional segments stratifies the celiac therapeutics market. Price differentiation hinges on mucosal healing endpoint certification and hospital formulary tier placement. Pricing pressure stems from zero-cost dietary elimination as the clinical standard, squeezing reimbursement willingness for pharmaceutical alternatives. Pediatric populations and homecare settings demonstrate highest price sensitivity, while refractory case specialists in tertiary centers exhibit lowest sensitivity due to limited therapeutic alternatives.
Supply Chain Analysis
Cold-chain logistics costs for biologic therapies concentrate manufacturing investment in Basel, Zurich, and Boston metropolitan clusters. Active pharmaceutical ingredient sourcing draws from Swiss and German immunology specialty suppliers, with excipient dependencies on REACH-compliant stabilizer producers. Single-source vulnerability pervades T-cell pathway expertise concentration in Oxford and Cambridge academic centers. Distribution runs through hospital procurement channels for biologics and retail pharmacy networks for oral medications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between FDA orphan drug incentives and EMA centralized procedures creates cost-efficient development pathways, with Boston-San Francisco corridor offering accelerated timelines against Heidelberg-Munich immunology talent access.
For Market Incumbents: Cement pipeline dominance through backward integration into T-cell pathway R&D capabilities at Oxford and Cambridge institutes, while expanding manufacturing footprint in Swiss CDMO clusters to offset REACH compliance cost inflation. Biologic capacity additions in Basel-Zurich corridor defend against emerging nanoparticle platform entrants. For New Entrants and Emerging Players: Pediatric dysphagia populations represent the most penetrable white-space segment, with powder formulation gaps in homecare settings enabling rapid share capture. Target France's expanded home nursing reimbursement reforms for subcutaneous biologic delivery, leveraging patient self-administration preference shifts against hospital-dependent incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among enzymatic platform specialists with late-stage gluten-degradation candidates, offering mechanistic diversification from crowded biologic segments. Long-term viability favors developers with demonstrated mucosal healing endpoints and parallel FDA-EMA submission capabilities. The signal to watch is surrogate endpoint acceptance precedent that would compress commercialization timelines for biomarker-validated candidates.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Mucosal healing endpoint validation accelerates FDA priority review designation for refractory celiac candidates. |
| Regulatory Approval Pathway | Orphan drug designation unlocks tax credits and waived fees for immunomodulator development programs. |
| Manufacturing Scale-Up | Swiss CDMO capacity expansion secures supply continuity for subcutaneous biologic autoinjector formats. |
| Pipeline Diversification | Adjacent autoimmune gastrointestinal indications leverage shared T-cell pathway expertise and regulatory dossiers. |
| Licensing Agreement | Academic medical center partnerships in Boston and Heidelberg transfer specialized immunology talent to commercial developers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling and top-down therapeutic category sizing were triangulated to anchor market estimates.
Comparable historical periods spanning pre-pandemic baselines through recent orphan drug designation accelerations anchored the projection framework across the analysis window. Segmentation dimensions included treatment line, dosage form, administration route, patient population, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating clinical trial progression rates, reimbursement policy shifts, and biologic adoption elasticity in tertiary care settings.
Inputs from regulatory filings and hospital procurement databases were available through the study window; gaps in real-world adherence data for oral enzymatic therapies introduce uncertainty bands around patient persistence assumptions. Forecasts reflect documented clinical trial milestones and reimbursement decisions, with biomarker validation breakthroughs and REACH regulatory amendments representing specific revision risks. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
Pregabalin Market
Pharmaceuticals
Oncology Small Molecule Drugs Market
Pharmaceuticals
Gemcitabine Hydrochloride Market
Pharmaceuticals
Global Controlled Release Drug Delivery Market
Pharmaceuticals
Fucosidosis Therapeutics Market
Pharmaceuticals
Teriflunomide Market
Pharmaceuticals
Unfractionated Heparin Market
Pharmaceuticals
Veterinary Active Pharmaceutical Ingredients Manufacturing Market
Pharmaceuticals
Middle East and Africa Biguanide Market
Pharmaceuticals
Fibroblast Growth Factor Receptor Inhibitor Market
Pharmaceuticals
Warts Therapeutics Market
Pharmaceuticals
Global Compounding Pharmacy Market
Pharmaceuticals
Tetanus Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Global Liver Diseases Therapeutics Market