
 Global Respiratory Drug Market | 2026-2036
Global Respiratory Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Global Respiratory Drug Market Outlook
Pulmonology specialist availability is collapsing across rural health networks in India, Brazil, and the United States, forcing pharmaceutical companies to rethink direct-to-patient digital engagement models. GlaxoSmithKline plc leverages its inhaled corticosteroid manufacturing footprint to sustain supply chain control across European distribution channels. AstraZeneca plc anchors its respiratory portfolio through biologic specialization in severe asthma and eosinophilic indications. Boehringer Ingelheim International GmbH dominates the COPD maintenance segment with long-acting muscarinic antagonist formulations.
Respiratory drugs comprise pharmaceutical agents engineered to modulate airway caliber, mucus secretion, and inflammatory cascades through precise molecular targeting of beta-2 adrenergic receptors, glucocorticoid pathways, or cystic fibrosis transmembrane conductance regulators. These compounds are formulated as pressurized metered-dose inhalers, dry powder systems, nebulized solutions, or intravenous infusions to achieve local pulmonary deposition or systemic immunomodulation in obstructive and restrictive lung diseases. Bronchodilators and corticosteroids administered via inhalation routes command the deepest margin pools due to device-drug combination complexity and formulation patents. The homecare end-user segment is expanding fastest as portable nebulizers and connected inhalers enable chronic disease management outside institutional settings. Asthma and COPD therapeutic areas remain structurally mature with biosimilar pressure building on legacy monoclonal antibodies.
The FDA's Breakthrough Therapy designation and the EMA's Priority Medicines scheme are accelerating market access for novel respiratory biologics while tightening post-marketing surveillance requirements. China's NMPA has aligned its inhaled product bioequivalence standards with ICH guidelines, reshaping generic entry dynamics for multinational patent holders. India's CDSCO is implementing strengthened good manufacturing practice inspections for metered-dose inhaler propellant transitions. Stakeholders must monitor regulatory divergence on hydrofluoroalkane phase-out timelines across the United States, Europe, and China to anticipate manufacturing conversion costs and portfolio prioritization shifts.
Market Dynamics
Pharmaceutical manufacturers face mounting pressure to convert hydrofluoroalkane propellant systems ahead of divergent phase-out timelines across the United States, Europe, and China, forcing simultaneous reformulation and device revalidation investments.
Growth Catalysts
- FDA Breakthrough Therapy designation:The accelerated approval pathway compresses development timelines for novel respiratory biologics targeting severe asthma and eosinophilic indications.
- Homecare end-user expansion:Portable nebulizers and connected inhaler devices enable chronic disease management outside institutional settings across aging populations.
- China tier-one city demand:Air quality-linked respiratory disease burdens in Beijing, Shanghai, and Guangzhou continue driving specialist visit volumes and prescription intensity.
Market Restraints
- Propellant transition costs:Hydrofluoroalkane phase-out mandates under the EPA Significant New Alternatives Policy and EU F-Gas Regulation impose simultaneous manufacturing line conversions.
- Specialist availability collapse:Pulmonologist shortages across rural India, Brazil, and the United States constrain patient access and prescription fulfillment.
- Biosimilar pressure:Generic monoclonal antibody entrants are eroding margin pools for legacy asthma and COPD biologics in European and North American markets.
Strategic Opportunities
- Direct-to-patient digital engagement:Telehealth platforms and remote monitoring tools offer pharmaceutical companies bypass channels where specialist shortages limit traditional detailing.
- India CDSCO manufacturing incentives:Strengthened good manufacturing practice inspections for metered-dose inhaler production create first-mover advantages for compliant facilities.
- Connected inhaler ecosystems:Integration of dose counters, adherence sensors, and mobile applications opens subscription revenue streams alongside drug sales.
Industry Challenges
- Device-drug combination complexity:Formulation patents and proprietary inhaler designs require simultaneous IP navigation across multiple jurisdictions.
- Post-marketing surveillance tightening:The FDA and EMA are expanding safety monitoring requirements for accelerated-approval respiratory biologics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Respiratory Drug Market |
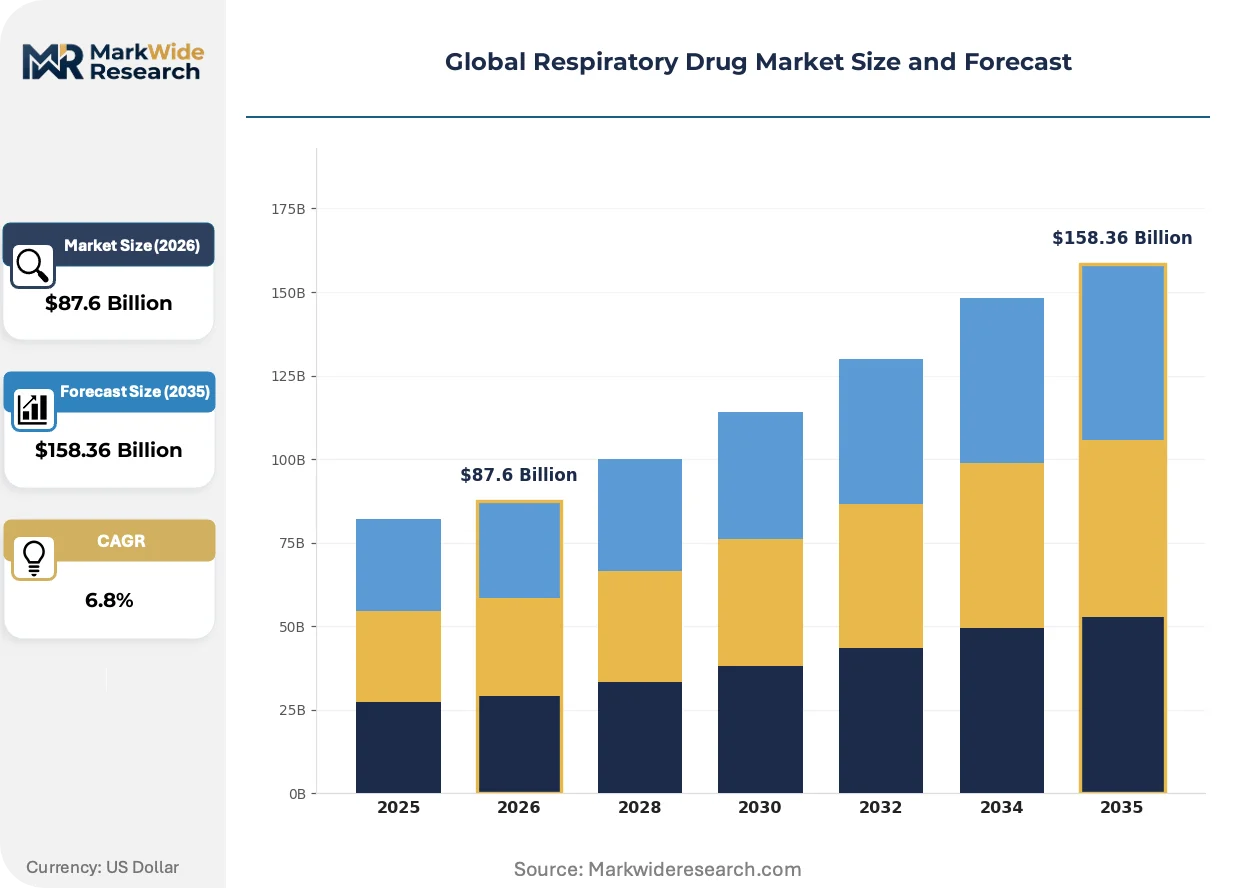
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Bronchodilators, Corticosteroids, Antihistamines, Leukotriene Modifiers Administration Route: Inhalation, Oral, Intravenous, Subcutaneous End User: Hospitals, Clinics, Homecare, Pharmacies Therapeutic Area: Asthma, COPD, Allergic Rhinitis, Cystic Fibrosis |
| Companies Covered | GlaxoSmithKline plc, AstraZeneca plc, Boehringer Ingelheim International GmbH, Novartis AG, Sanofi S.A., Teva Pharmaceutical Industries Ltd., Merck & Co., Inc., Roche, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Respiratory Drug Market Strategic Shifts
Dry powder inhaler platforms and nebulized biologic delivery systems are reshaping competitive positioning through improved pulmonary deposition efficiency and patient adherence monitoring capabilities.
Smart inhaler technology with embedded sensors and Bluetooth connectivity is supplanting conventional mechanical devices in severe asthma management protocols. Hospital systems in Germany and the United Kingdom are piloting these connected devices for real-time adherence tracking. The technology is compressing the feedback loop between patient behavior and clinical intervention, enabling pharmaceutical companies to demonstrate outcome improvements to payers.
The EU F-Gas Regulation and its national implementing measures are accelerating propellant transitions toward lower-global-warming-potential alternatives in pressurized metered-dose inhalers. Manufacturers must reformulate products while maintaining bioequivalence under tightened EMA guidance. European distribution channels are prioritizing suppliers with certified sustainable propellant systems in procurement decisions.
Specialist-led prescription models are fragmenting as primary care physicians and nurse practitioners assume greater respiratory disease management responsibilities. Retail pharmacy chains in the United States and United Kingdom are deploying in-clinic spirometry and diagnostic services to capture patient flows. This channel expansion is most visible in urban markets where pulmonologist appointment wait times exceed eight weeks.
Global Respiratory Drug Market Segmentation
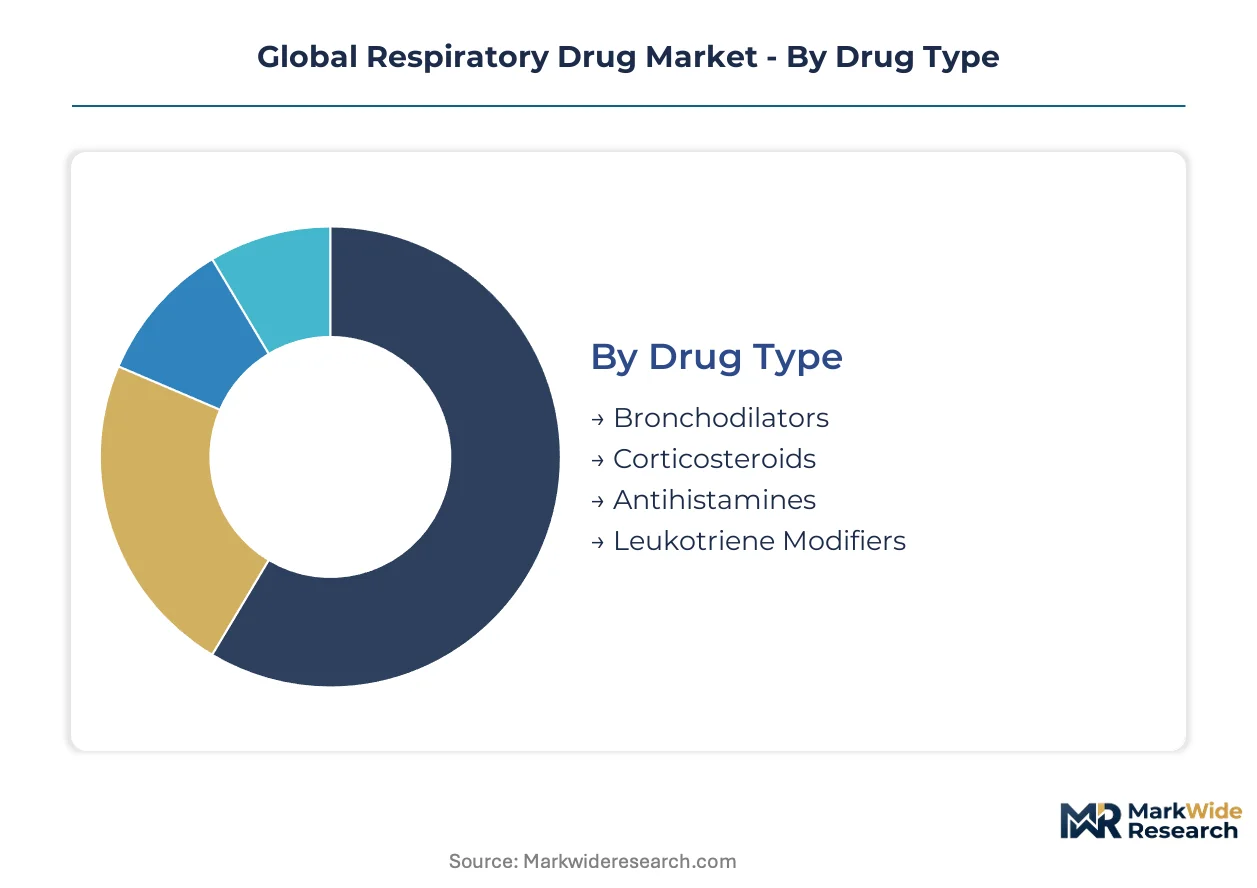
Respiratory drug segmentation reveals distinct substitution pressures across therapeutic modalities, with inhalation routes and biologic formulations commanding premium positioning while oral generics erode legacy margins. Device-drug combinations create defendable niches, whereas commodity formulations face accelerating price compression.
Drug Type:
Bronchodilators and corticosteroids confront the sharpest biosimilar substitution threat, while leukotriene modifiers and antihistamines maintain stronger formulation moats through delivery complexity.
- Bronchodilators:Beta-2 adrenergic receptor agonists and anticholinergic compounds relax airway smooth muscle through distinct molecular pathways. Demand clusters in China's tier-one cities where COPD prevalence drives specialist prescribing, though long-acting formulations face mounting generic competition across European markets.
- Corticosteroids:Inhaled glucocorticoid formulations suppress inflammatory cascades through nuclear receptor modulation. Hospital systems in the United States are expanding formulary access for high-potency inhaled variants, while propellant transition costs compress manufacturing margins for legacy metered-dose products.
- Antihistamines:H1-receptor antagonists block histamine-mediated bronchoconstriction and rhinorrhea.
- Leukotriene Modifiers:Cysteinyl leukotriene receptor antagonists interrupt inflammatory lipid signaling in persistent asthma.
Bronchodilators retain volume leadership; leukotriene modifiers hold the steepest expansion curve.
Administration Route:
Cost tier stratification separates device-dependent inhalation systems from commoditized oral and injectable alternatives, with reimbursement differentials widening across payers.
- Inhalation:Pressurized metered-dose inhalers, dry powder systems, and nebulized solutions achieve localized pulmonary deposition with minimized systemic exposure. Germany's hospital networks are piloting connected inhaler platforms for real-time adherence monitoring, while India's CDSCO strengthens manufacturing inspections for propellant transitions.
- Oral:Tablet and liquid formulations deliver systemic corticosteroid and leukotriene modifier therapy through gastrointestinal absorption. Retail pharmacy chains across the United States capture patient flows through in-clinic spirometry services that channel prescriptions toward maintenance oral regimens.
- Intravenous:Hospital-administered biologic infusions target severe eosinophilic asthma and acute exacerbations.
- Subcutaneous:Prefilled autoinjector devices enable home administration of monoclonal antibody therapies.
Inhalation dominates prescription value; subcutaneous delivery is climbing fastest as biologic self-administration expands.
End User:
Customer type fragmentation accelerates as institutional purchasing consolidates while homecare channels disintermediate traditional pharmacy distribution.
- Hospitals:Acute care institutions manage severe exacerbations through nebulized bronchodilators and intravenous corticosteroids. The United Kingdom's National Health Service is centralizing respiratory biologic procurement through regional formularies that favor suppliers with outcome-based contracting capabilities.
- Homecare:Portable nebulizers and connected inhaler devices enable chronic disease management outside institutional settings. Japan's aging population is driving demand for subscription-based medication adherence platforms that integrate dose counters with mobile applications.
- Clinics:Outpatient facilities provide specialist-directed maintenance therapy and diagnostic services.
- Pharmacies:Retail dispensaries handle prescription fulfillment for maintenance inhaler refills and oral formulations.
Hospitals retain volume leadership; homecare holds the steepest expansion curve.
Therapeutic Area:
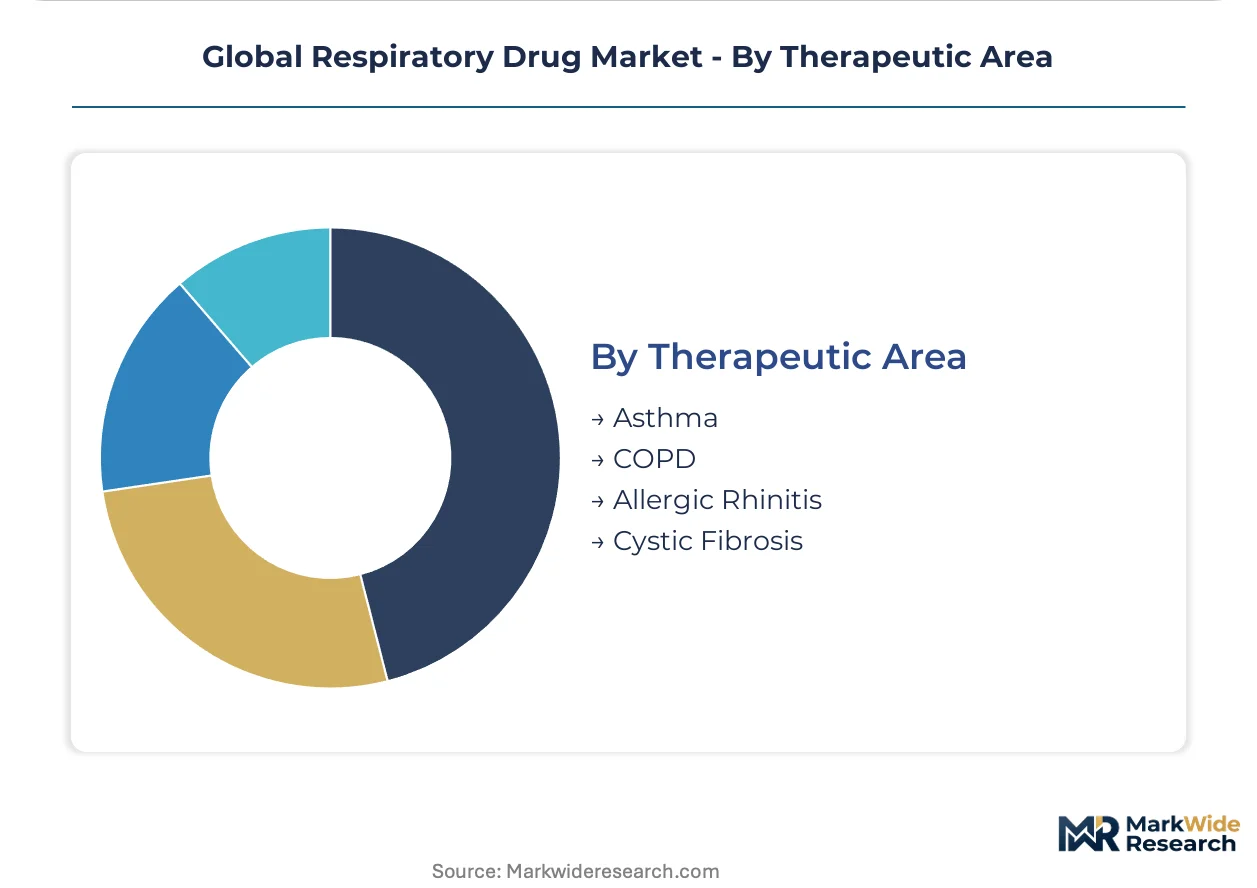
Maturity gradients separate structurally saturated asthma and COPD markets from emerging opportunities in rare respiratory indications with orphan drug pricing power.
- Asthma:Chronic airway inflammation characterized by reversible bronchoconstriction and hyperresponsiveness. Severe eosinophilic phenotypes in the United States are shifting toward biologic specialization, though primary care physicians now manage mild-to-moderate cases with standardized step-therapy protocols.
- COPD:Progressive airflow limitation driven by small airway remodeling and parenchymal destruction. China's air quality-linked disease burdens in Beijing and Shanghai sustain prescription intensity for long-acting muscarinic antagonist combinations despite generic erosion in European markets.
- Allergic Rhinitis:IgE-mediated nasal mucosa inflammation with seasonal and perennial variants.
- Cystic Fibrosis:CFTR dysfunction causing thick mucus accumulation and recurrent pulmonary infections.
COPD retains volume leadership; cystic fibrosis holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies. China's tier-one cities prioritize inhaled biologics for severe asthma phenotypes, while India's rural networks rely on oral corticosteroid generics due to specialist shortages. Germany and the United States lead connected inhaler adoption, whereas Brazil's public procurement channels favor nebulized bronchodilators.
United States
Hospital systems in Boston and Houston are expanding formulary access for severe eosinophilic asthma biologics. The FDA's Breakthrough Therapy designation compresses development timelines for novel respiratory therapies. California's Kaiser Permanente networks pilot real-time adherence monitoring through connected inhaler platforms.
Germany
Bavaria's hospital networks concentrate demand for dry powder inhaler systems with embedded dose counters. The EU F-Gas Regulation accelerates propellant transitions toward lower-global-warming-potential alternatives. North Rhine-Westphalia's pharmaceutical clusters host manufacturing facilities undergoing simultaneous reformulation and device revalidation investments.
China
Beijing and Shanghai sustain prescription intensity for long-acting muscarinic antagonist combinations linked to air quality disease burdens. The NMPA aligned inhaled product bioequivalence standards with ICH guidelines, reshaping generic entry dynamics. Guangzhou's specialist hospitals drive biologic adoption for treatment-resistant asthma phenotypes.
India
Maharashtra's urban centers face collapsing pulmonologist availability, forcing digital engagement models for chronic disease management. The CDSCO implements strengthened good manufacturing practice inspections for metered-dose inhaler propellant transitions. Gujarat's pharmaceutical clusters attract first-mover investment for compliant inhaler manufacturing facilities.
Brazil
São Paulo's public health networks manage COPD exacerbations through nebulized bronchodilator protocols. ANVISA maintains accelerated review pathways for respiratory generics while tightening post-marketing surveillance. Rio de Janeiro's retail pharmacy chains deploy in-clinic spirometry to capture patient flows amid specialist shortages.
Global Respiratory Drug Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with consolidation pressures intensifying around device-drug combination patents. The upper tier commands supply chain control through captive manufacturing of inhaled corticosteroid formulations and proprietary inhaler designs. Mid-tier specialists compete on biologic specialization in severe asthma and eosinophilic indications. Dominant competitive moves include portfolio diversification into connected inhaler ecosystems and strategic partnerships for propellant transition technologies.
Within the integrated pharmaceutical tier, GlaxoSmithKline plc and AstraZeneca plc exemplify archetypes of supply chain control and biologic specialization respectively. GlaxoSmithKline plc represents the manufacturing-anchored model with European distribution channel dominance. AstraZeneca plc occupies a position emphasizing severe asthma and eosinophilic indication focus. Boehringer Ingelheim International GmbH sits within the maintenance therapy segment, anchoring long-acting muscarinic antagonist positioning.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Boehringer Ingelheim International GmbH |
| Novartis AG |
| Sanofi S.A. |
| Teva Pharmaceutical Industries Ltd. |
| Merck & Co., Inc. |
| Roche |
| Pfizer Inc. |
| Others |
Value Chain & Pricing Dynamics
Hydrofluoroalkane propellant substitution simultaneously redraws manufacturing geography across India, China, and Germany while compressing margin structures for legacy metered-dose inhaler portfolios. This forced transition concentrates pricing power with suppliers possessing certified sustainable propellant systems and validated device revalidation capabilities.
Pricing Analysis
Long-term offtake contracts dominate procurement between hospital systems and inhaled biologic manufacturers, insulating premium tiers from spot-market volatility while exposing commodity bronchodilators to tender-based price compression. Price differentiation rests on device-drug combination complexity and FDA Breakthrough Therapy certification status. Pricing pressure intensifies in European markets as biosimilar monoclonal antibodies erode legacy asthma biologic margins. Retail pharmacy chains exhibit highest price sensitivity due to formulary compliance mandates, whereas severe eosinophilic asthma specialists prioritize clinical outcome guarantees over unit cost.
Supply Chain Analysis
Active pharmaceutical ingredient synthesis for inhaled corticosteroids hinges on concentrated manufacturing clusters across Gujarat, Shanghai, and North Rhine-Westphalia, creating single-source vulnerability during environmental compliance inspections. Propellant feedstocks draw from specialty chemical producers in China and India, while device components source from precision molding facilities in Germany and Switzerland. Tariff exposure on hydrofluoroalkane alternatives threatens margin stability during regulatory transition periods. Distribution runs through hospital procurement consortiums in the United States and Germany, with direct-to-patient channels expanding fastest in Japan's homecare markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected inhaler ecosystems are redefining this market as a platform-economics play, where pharmaceutical manufacturers must orchestrate hardware, software, and service interoperability to capture recurring revenue beyond drug sales alone.
For Market Incumbents: Compound device-drug patent thickets through proprietary dry powder inhaler designs and embedded sensor integration to defend against biosimilar erosion in severe asthma. Prioritize backward integration into sustainable propellant manufacturing ahead of EU F-Gas Regulation deadlines, securing supply continuity while competitors face reformulation bottlenecks. For New Entrants and Emerging Players: FDA Breakthrough Therapy designation fast-tracks market access for novel biologics targeting treatment-resistant eosinophilic phenotypes, creating white-space entry around severe asthma segments where specialist shortages limit incumbent detailing reach. India's CDSCO manufacturing incentives offer compliant facility advantages for first-mover propellant transitions. Deploy telehealth-integrated adherence platforms to bypass pulmonologist availability constraints in rural Brazil and Maharashtra. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors vertically integrated manufacturers with captive propellant supply and validated device platforms over pure-play biologic developers. Acquisition targets should demonstrate EU F-Gas Regulation compliance certification and connected inhaler FDA clearance pathways. Monitor NMPA bioequivalence alignment with ICH guidelines as the inflection signal reshaping generic entry dynamics in China's tier-one cities.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Inhaler Ecosystem Development | Integration of Bluetooth-enabled adherence sensors with mobile applications opens subscription revenue streams alongside traditional drug sales. |
| Sustainable Propellant Manufacturing Scale-Up | Certified hydrofluoroalkane alternative production secures procurement preference from European hospital systems under tightened EMA guidance. |
| Direct-to-Patient Digital Platform Launch | Telehealth channels bypass specialist shortages constraining traditional pharmaceutical detailing in rural India and Brazil. |
| Severe Eosinophilic Asthma Biologic Advancement | FDA Breakthrough Therapy designation compresses development timelines for novel monoclonal antibodies targeting treatment-resistant phenotypes. |
| Regional Formulary Partnership Expansion | Outcome-based contracting capabilities with United Kingdom NHS regional procurement centralizes biologic purchasing decisions. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with respiratory drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists; and secondary validation through FDA 510(k) filings, EMA marketing authorization applications, ClinicalTrials.gov protocol registries, and hospital procurement database extracts. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical manufacturer revenue disclosures.
Across the projection horizon, the analytical framework segmented respiratory drug demand by administration route, therapeutic area, end-user setting, and regional regulatory cluster. CAGRs were derived from patient prevalence epidemiology, treatment penetration curves, and pricing trajectory assumptions specific to biosimilar substitution dynamics and propellant transition cost pass-through. Forecast inputs incorporated NMPA bioequivalence standard alignment, CDSCO manufacturing inspection intensification, and connected inhaler reimbursement pathway evolution.
Decision-makers should treat outputs as directional under base assumptions of sustained regulatory divergence on hydrofluoroalkane phase-out timelines; material deviation in EPA Significant New Alternatives Policy enforcement or EU F-Gas Regulation national implementation would warrant model refresh. Practitioners should keep alternative scenarios live as specialist availability collapse rates and direct-to-patient channel regulatory clarity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Histone Deacetylase Inhibitors Market
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Demerol (Meperidine) Market
Pharmaceuticals
Apalutamide API Market
Pharmaceuticals
Tapentadol Market
Pharmaceuticals
Montelukast Market
Pharmaceuticals
Global Autogenous Vaccines Market
Pharmaceuticals
Hepatocellular Carcinoma Drugs Market
Pharmaceuticals
Inhalation and Nasal Spray Generic Drugs Market
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
Europe Veterinary Pharmaceuticals Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
Prescription Transdermal Patches Market
Pharmaceuticals
Toxoid Vaccines Market