
 Etomidate Market | 2026-2036
Etomidate Market Size, Share, and Industry Trends Forecast 2026-2036
Etomidate Market Analysis
Ambulatory surgical centers is rebalancing toward a larger share of etomidate procurement as hospitals streamline elective procedures to outpatient settings. Pfizer leverages its injectable manufacturing scale to supply bulk hospital contracts across North America. Johnson & Johnson anchors its position through sterile packaging infrastructure that supports pre-filled syringe formats. Zydus competes on cost-optimized vial production for emerging market tenders.
Etomidate is an imidazole-derived intravenous hypnotic agent formulated as a propylene glycol solution or lipid emulsion, inducing anesthesia within one arm-brain circulation due to its rapid GABA-A receptor modulation. Injectable solution formats dominate current volume due to established compounding workflows and lower unit cost, while pre-filled syringes capture expanding margin pools as surgical centers prioritize ready-to-administer dosing accuracy. Emergency services delivery through intravenous routes sustains the largest end-user segment, though intramuscular applications in field trauma settings are gaining protocol adoption.
FDA anesthetic drug safety standards, EMA Good Manufacturing Practice guidelines, and USP sterile compounding requirements collectively elevate barriers for new entrants while mandating stability data for lipid-based formulations. These frameworks push manufacturers toward documented cold-chain integrity and endotoxin-controlled production environments. Stakeholders must monitor evolving pharmacovigilance reporting obligations for hemodynamic suppression profiles as regulatory scrutiny intensifies on short-acting induction agents.
Market Dynamics
The migration of elective surgeries from inpatient hospitals to ambulatory surgical centers is restructuring etomidate procurement patterns, with outpatient facility networks capturing volume previously concentrated in acute-care institutions.
Growth Catalysts
- Outpatient procedural expansion:Ambulatory surgical centers in the United States are consolidating elective cases that previously required hospital admission, expanding the addressable base for induction agents.
- FDA safety monitoring mandates:Updated anesthetic drug surveillance requirements are standardizing hemodynamic monitoring protocols, reinforcing demand for short-acting agents with predictable cardiovascular profiles.
- Lipid emulsion formulation advances:Improved stability data for oil-in-water emulsions is reducing propylene glycol-associated adverse events, broadening clinical acceptance across patient risk categories.
Market Restraints
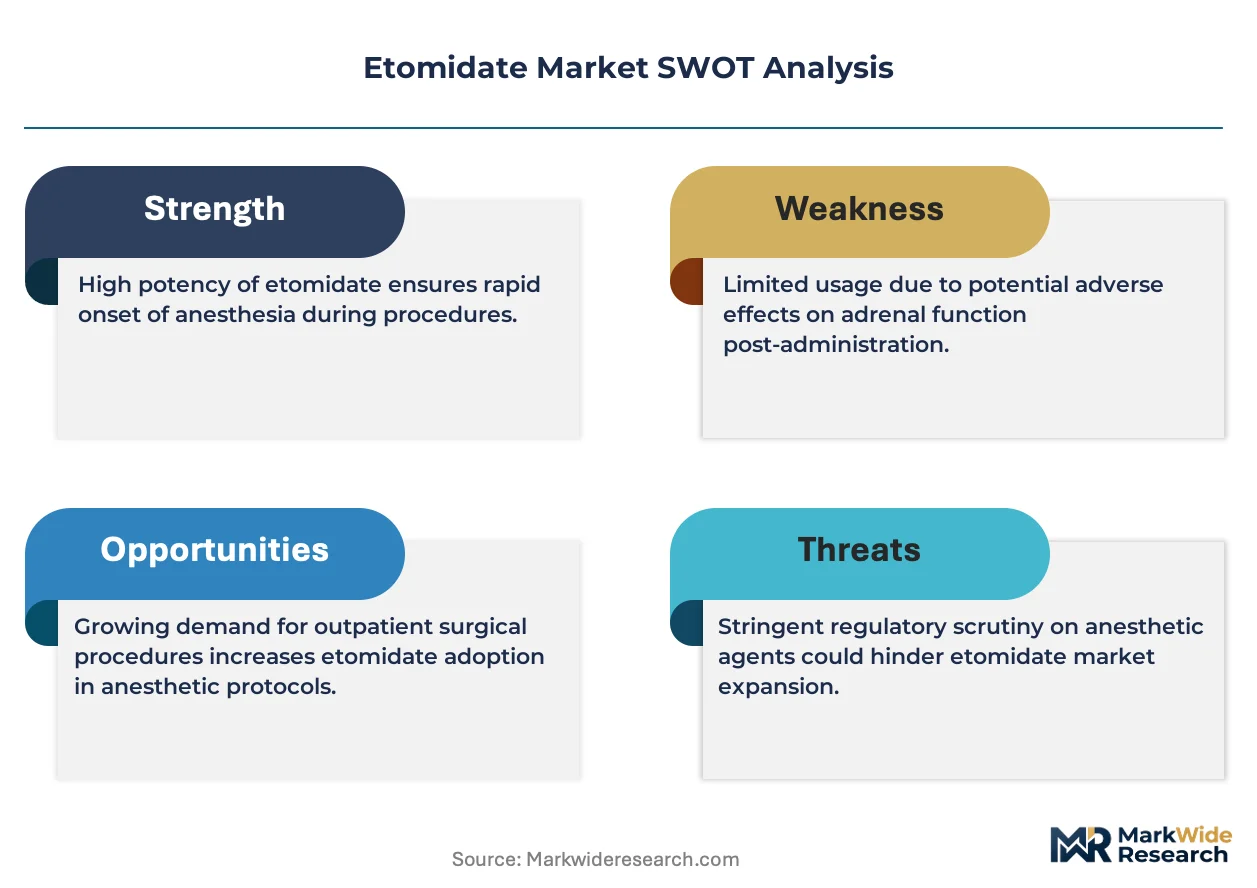
- Active pharmaceutical ingredient concentration:Bulk etomidate synthesis capacity clusters among a limited set of contract manufacturers in India and China, creating supply vulnerability.
- Propylene glycol supply volatility:Fluctuations in industrial solvent markets affect cost structures for conventional solution formulations.
- Emerging induction agent competition:Ketamine and newer hypnotic alternatives are gaining protocol share in specific trauma and geriatric populations.
Strategic Opportunities
- Pre-filled syringe penetration:Ready-to-administer formats address dosing accuracy priorities in United States surgical centers, commanding premium positioning against conventional vials.
- Emergency medical services expansion:Field anesthesia protocols for trauma stabilization are creating new intramuscular application demand outside traditional operating theater settings.
- EMA pharmacovigilance harmonization:Streamlined adverse event reporting across European member states is reducing regulatory friction for multi-market product registrations.
Industry Challenges
- Sterile compounding workforce scarcity:Qualified pharmacy technicians capable of aseptic handling per USP requirements remain concentrated in major metropolitan hospital systems.
- Cold-chain infrastructure capex:Lipid emulsion formulations require validated temperature-controlled distribution networks that strain capital deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Etomidate Market |
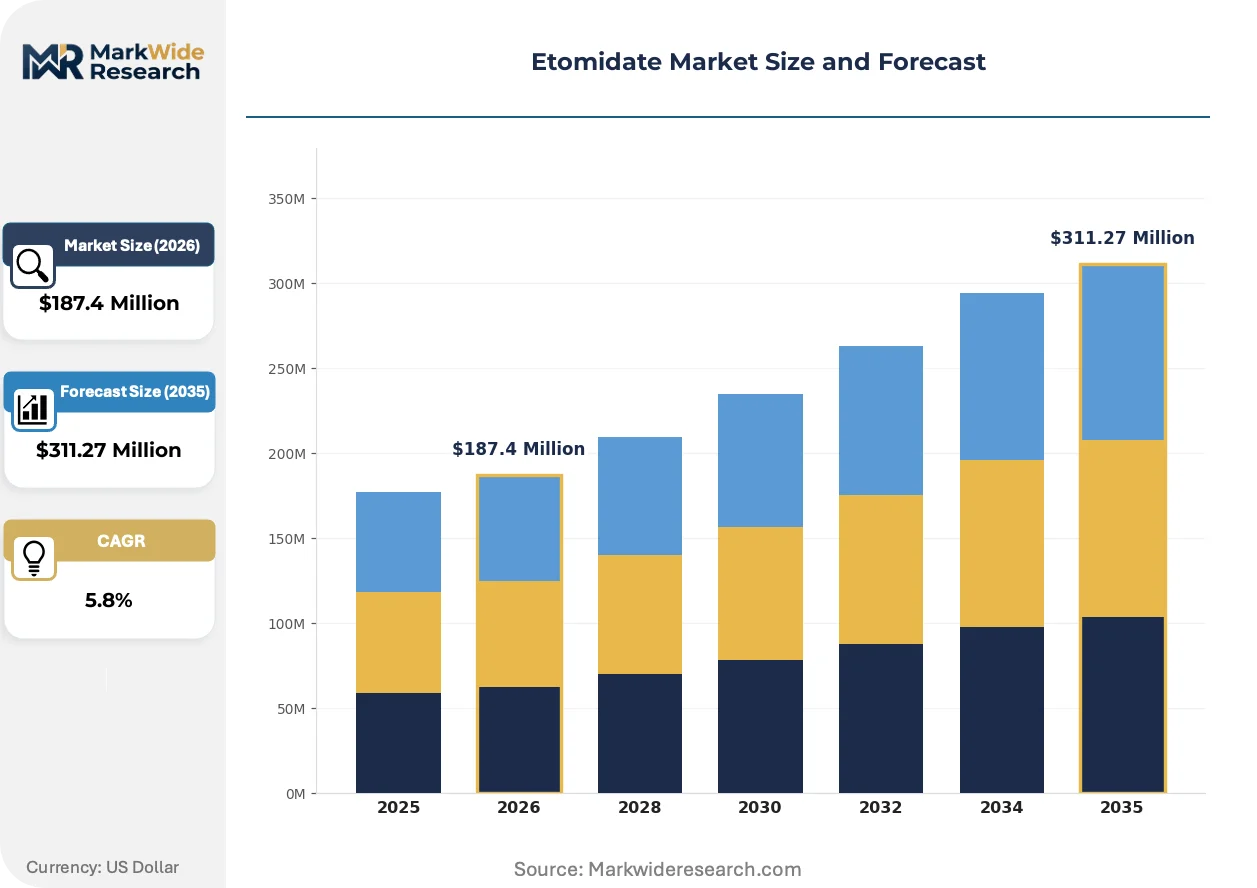
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Solution, Dry Powder, Pre-filled Syringes, Ampoules End User: Hospitals, Surgical Centers, Clinics, Emergency Services Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Inhalation Packaging Type: Vials, Bottles, Blisters, Cartridges |
| Companies Covered | Teva, Johnson & Johnson, Pfizer, AbbVie, Mylan, Esteve Pharma, Zydus, Jiangsu Hengrui Medicine, Par Sterile Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Etomidate Market Emerging Trajectories
Formulation chemistry, regulatory surveillance frameworks, and point-of-care delivery models are converging to reshape how etomidate reaches clinical endpoints.
Lipid emulsion carrier systems are rewriting the risk-benefit calculus for etomidate administration. These oil-in-water formulations eliminate propylene glycol solvent exposure, reducing injection pain and thrombophlebitis incidence. United States ambulatory surgical centers are adopting emulsion products at accelerated rates for outpatient procedures. The technology is compressing differentiation between etomidate and alternative induction agents in patient satisfaction metrics.
EMA Good Manufacturing Practice Annex 1 revisions are mandating enhanced environmental monitoring for sterile injectable production. Manufacturers must demonstrate continuous viable particle surveillance and rapid microbial detection capabilities. European production facilities are retrofitting isolator technology and single-use systems to maintain compliance. The regulatory pressure is elevating capital requirements for new market entrants while consolidating advantage among established sterile infrastructure holders.
Consolidated purchasing organizations are aggregating etomidate demand across multi-facility health systems. These entities negotiate formulary commitments that displace fragmented distributor relationships. Surgical center chains and hospital networks in the United States are centralizing anesthesia drug procurement through group purchasing structures. The concentration is compressing price negotiation leverage for standalone facilities and regional distributors.
Etomidate Market Segmentation
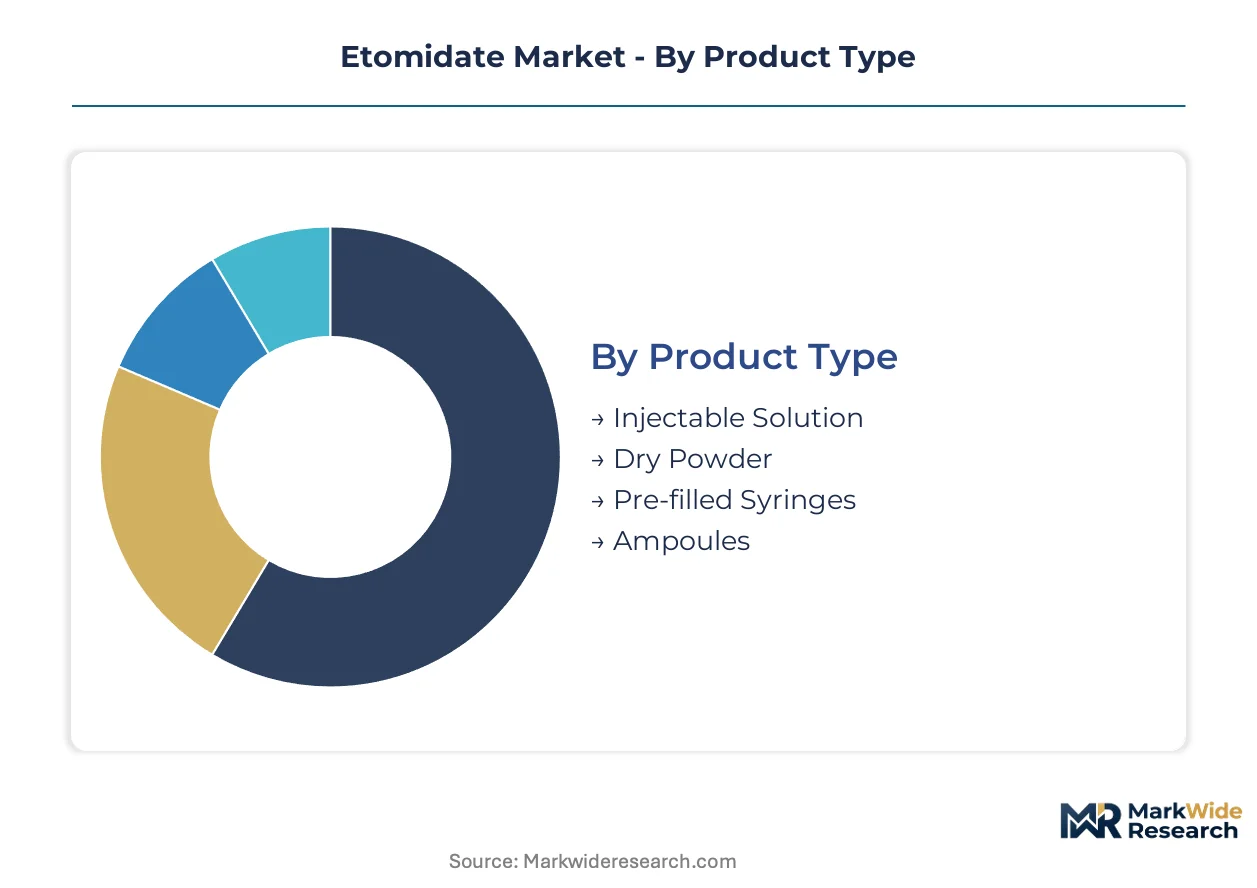
Etomidate's clinical utility fragments across delivery technologies, care settings, and packaging formats that each impose distinct manufacturing and distribution requirements. Procurement patterns diverge sharply between acute-care institutions and ambulatory networks, creating parallel demand curves within the same molecule class.
Product Type:
Standalone liquid formulations dominate high-volume hospital contracts, while pre-filled and unit-dose formats embed into surgical center workflows requiring minimal compounding infrastructure.
- Injectable Solution:Propylene glycol or lipid emulsion carriers in multi-dose vials support anesthesia induction in operating theaters. Hospital pharmacy compounding workflows in the United States sustain demand despite emulsion alternatives gaining protocol share for outpatient sensitivity.
- Pre-filled Syringes:Ready-to-administer units eliminate dose-calculation errors and aseptic handling steps. Surgical center chains prioritize these for rapid room turnover and liability reduction, commanding premium positioning against conventional vials.
- Dry Powder:Lyophilized formulations extend shelf stability for emergency stockpiles and military medical kits. Cold-chain independence suits field deployment scenarios where liquid stability cannot be guaranteed.
- Ampoules:Single-use glass containers serve cost-sensitive institutional tenders and emerging market procurement. Breakage rates and disposal complexity limit adoption in high-throughput settings.
Volume placements concentrate in Injectable Solution; the faster expansion belongs to Pre-filled Syringes.
End User:
Procurement authority clusters differently across facility types, with consolidated purchasing organizations reshaping how manufacturers access surgical center and emergency services demand.
- Hospitals:Integrated delivery networks negotiate formulary contracts covering induction agents across surgical, emergency, and intensive care departments. Bulk vial procurement persists despite outpatient migration.
- Surgical Centers:Freestanding ambulatory facilities prioritize pre-filled formats and rapid-acting profiles to maximize procedural throughput. United States certificate-of-need relaxation is densifying facility networks in suburban markets.
- Clinics:Office-based procedural suites require smaller lot sizes and flexible ordering cadences. Diagnostic sedation protocols drive intermittent rather than continuous consumption.
- Emergency Services:Pre-hospital trauma stabilization creates demand for intramuscular administration outside controlled environments. Protocol adoption for field anesthesia is expanding addressable use cases.
Revenue concentration sits with Hospitals; Surgical Centers are climbing the fastest in procurement volume.
Delivery Mode:
Route selection determines pharmacokinetic profiles and clinical staffing requirements, with intravenous administration embedding into controlled settings while alternative routes enable decentralized care.
- Intravenous:Direct vascular access produces rapid onset for controlled induction. Operating theater protocols mandate IV placement, sustaining dominant share despite peripheral route advances.
- Intramuscular:Deltoideus or vastus lateralis injection supports pre-hospital trauma care where vascular access is compromised. Emergency medical services expansion in the United States is validating field anesthesia protocols.
- Subcutaneous:Slower absorption limits utility for induction but finds niche applications in pediatric or compromised vascular access scenarios. Clinical evidence accumulation remains limited.
- Inhalation:No established etomidate vapor formulation exists; theoretical exploration only. Research-stage delivery concepts have not reached investigational protocols.
Clinical validation concentrates in Intravenous; Intramuscular is gaining share fastest through emergency services protocol expansion.
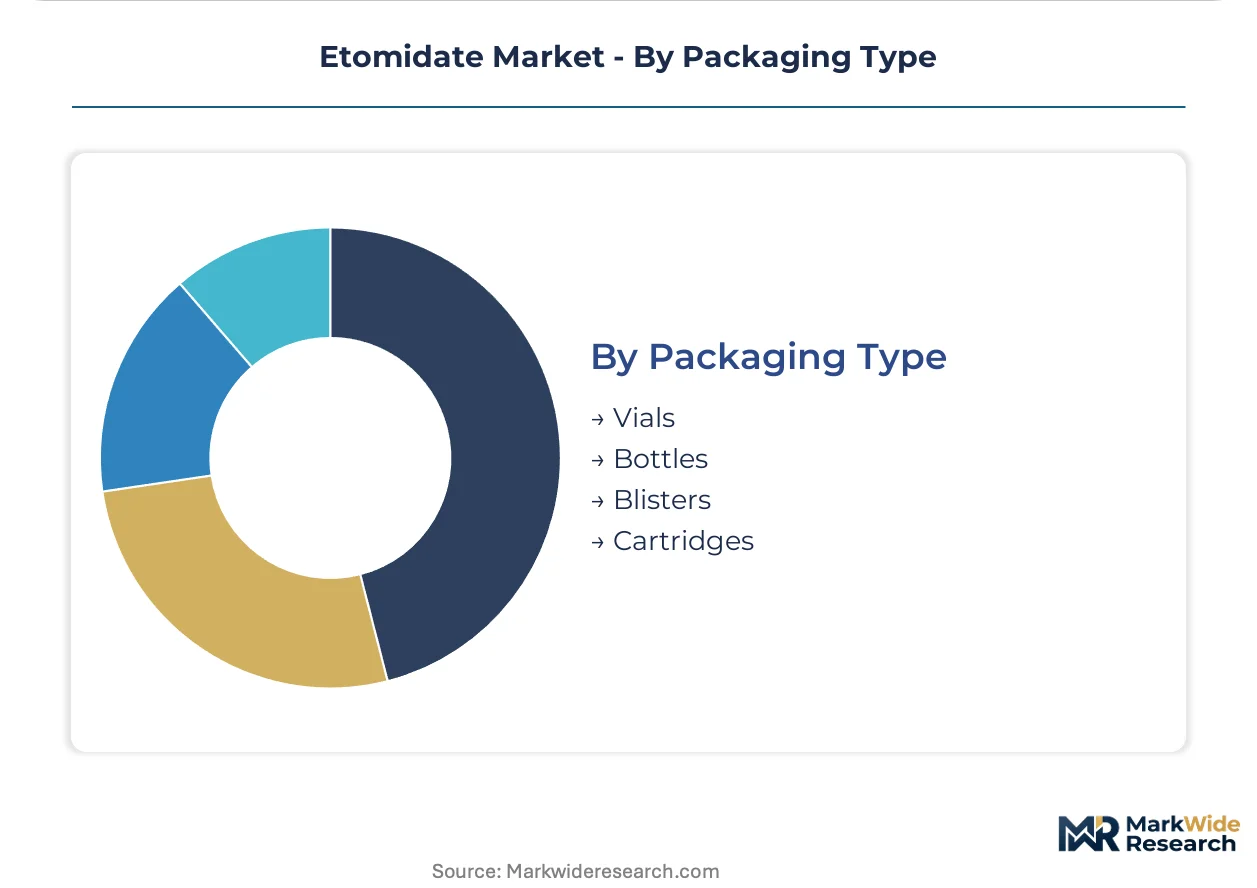
Packaging Type:
Container selection interfaces directly with compounding workflows, cold-chain requirements, and waste management protocols that vary by facility infrastructure maturity.
- Vials:Multi-dose glass or polymer containers support pharmacy bulk preparation and aliquoting. Hospital central sterile supply departments favor vial formats for cost efficiency at scale.
- Bottles:Larger-volume containers serve compounding pharmacy operations preparing batch sterile preparations. USP sterile compounding requirements elevate handling complexity for this format.
- Blisters:Unit-dose barrier packaging protects pre-filled syringes from environmental exposure. Surgical center preference for ready-to-administer formats is normalizing blister presentation.
- Cartridges:Pen-injector compatible reservoirs enable automated dosing devices in research or specialized clinical settings. Commercial anesthesia applications remain minimal.
Procurement volume clusters in Vials; Blisters are expanding most quickly alongside pre-filled syringe adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Gujarat and Shenzhen concentrate active pharmaceutical ingredient synthesis for etomidate, attracting contract manufacturers through tax holidays and streamlined customs processing.
United States
Ambulatory surgical centers in Texas and Florida are densifying their networks as certificate-of-need restrictions ease. FDA updated anesthetic drug surveillance requirements mandate enhanced hemodynamic monitoring protocols for induction agents. The Dallas-Fort Worth metroplex anchors procurement consolidation through multi-facility health system purchasing organizations.
Germany
EMA Good Manufacturing Practice Annex 1 revisions drive retrofit investments in isolator technology across sterile injectable facilities. The country's national pharmaceutical regulator enforces continuous viable particle surveillance standards. The Rhine-Main region around Frankfurt hosts specialized logistics providers validating cold-chain integrity for lipid emulsion formulations.
India
CDSCO bulk drug manufacturing licenses cluster in Hyderabad and Ahmedabad production corridors. The country's national pharmaceutical regulator harmonizes stability data requirements with ICH guidelines for export-oriented facilities. Gujarat's special economic zones offer 15-year tax exemptions that concentrate etomidate API synthesis capacity.
China
NMPA priority review pathways accelerate registration for lipid-based formulation variants. The national medical products administration mandates endotoxin-controlled production environments per revised sterile drug guidelines. Jiangsu province's chemical industrial parks integrate backward into propylene glycol supply for conventional solution formats.
Etomidate Market Vendor Landscape
Top-tier vendors anchor hospital formulary contracts, while mid-scale specialists compete on cost-optimized vial production for emerging market tenders. The vendor base stratifies across three tiers: multinational injectable manufacturers with sterile packaging infrastructure, regional API-to-finish integrators, and niche pre-filled syringe assemblers. Two strategic archetypes dominate: scale-driven bulk suppliers leveraging manufacturing volume, and precision-format specialists capturing surgical center premium positioning. Competitive moves concentrate on pre-filled syringe portfolio expansion and lipid emulsion formulation licensing.
Among North American-based pharmaceutical manufacturers, Pfizer and Johnson & Johnson occupy positions anchoring bulk hospital contracts and sterile pre-filled infrastructure respectively. Zydus represents the cost-optimized manufacturing archetype competing for emerging market tenders. Jiangsu Hengrui Medicine exemplifies vertically integrated API-to-finish producers in Asia-Pacific supply corridors.
| Leading Market Players |
|---|
| Teva |
| Johnson & Johnson |
| Pfizer |
| AbbVie |
| Mylan |
| Esteve Pharma |
| Zydus |
| Jiangsu Hengrui Medicine |
| Par Sterile Products |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up surgical center chains concentrate procurement authority through group purchasing organizations, compressing price negotiation leverage for standalone facilities while rewarding scale-driven suppliers with volume commitments and formulary anchoring positions.
Pricing Analysis
Short lead-time premiums apply to pre-filled syringe formats demanded by United States ambulatory surgical centers seeking rapid room turnover, while spot inventory discounts characterize conventional vial transactions in hospital pharmacy compounding workflows. Three-tier pricing structure across premium, standard, and economy levels stratifies by packaging sophistication, with blistered pre-filled units commanding highest positioning against multi-dose vials and ampoules. Cost compression in economy tiers intensifies because Indian and Chinese API producers compete on bulk tenders. Surgical center chains exhibit lowest price sensitivity due to liability reduction priorities, while standalone clinics in emerging markets remain most price-sensitive.
Supply Chain Analysis
Cold-chain freight costs for lipid emulsion formulations elevate landed costs in European and North American markets, necessitating validated temperature-controlled distribution networks that strain capital deployment timelines. Active pharmaceutical ingredient synthesis concentrates in India, China, and selected European contract manufacturing sites. Finished formulation draws from propylene glycol industrial solvent markets and sterile packaging components. Single-source vulnerability clusters among limited etomidate API producers in Gujarat and Jiangsu province corridors. Distribution runs through hospital system central warehouses, surgical center chain consolidated purchasing organizations, and emergency medical services regional depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream API control and downstream sterile packaging infrastructure determine margin capture, with players pursuing captive supply of lipid emulsion carrier systems to secure formulation differentiation.
For Market Incumbents: To counter ketamine and alternative hypnotic agents gaining protocol share in trauma and geriatric populations, Pfizer and Johnson & Johnson should deepen backward integration into lipid emulsion manufacturing and expand pre-filled syringe capacity in United States surgical center corridors. FDA anesthetic safety monitoring mandates reward documented cold-chain integrity investments.
For New Entrants and Emerging Players: Enter via emergency medical services intramuscular application protocols, the most penetrable segment where field anesthesia guidelines are expanding outside traditional operating theater settings. Target cost-optimized vial production for emerging market tenders through CDSCO-licensed facilities in Hyderabad and Ahmedabad. Pursue EMA pharmacovigilance harmonization to reduce multi-market registration friction.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale sterile injectable specialists with isolator technology retrofit completion in Germany and United States production corridors. Five-to-ten year viability hinges on lipid emulsion formulation licensing portfolios and surgical center chain formulary anchoring. Monitor EMA Annex 1 compliance certification timelines as inflection indicator for European market access viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Lipid Emulsion Licensing | Secures formulation differentiation against propylene glycol alternatives in United States outpatient settings. |
| Pre-filled Syringe Manufacturing Scale-Up | Captures surgical center premium positioning through ready-to-administer dosing accuracy requirements. |
| EMA Annex 1 Compliance Retrofit | Maintains European market access via isolator technology and continuous viable particle surveillance. |
| Group Purchasing Organization Partnership | Locks formulary commitments across multi-facility health system networks in Texas and Florida. |
| API-to-Finish Vertical Integration | Reduces supply vulnerability from concentrated Indian and Chinese bulk synthesis corridors. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with anesthesia department directors, hospital pharmacy procurement managers, ambulatory surgical center operations leads, and sterile compounding technicians. FDA 483 inspection observations, EMA GMP inspection reports, CDSCO manufacturing license databases, and United States import records provided quantitative grounding. Bottom-up demand modeling across delivery modes and packaging formats reconciled with top-down market sizing from pharmaceutical trade flows.
Data-stream reconciliation across volume placements, pricing benchmarks, and regulatory approval timelines informed the analytical framework over the projection horizon. Segmentation dimensions modeled encompass product type, end-user facility category, delivery mode, and packaging format, with regional regulatory clusters capturing FDA, EMA, CDSCO, and NMPA jurisdiction effects. CAGRs derived from trend extrapolation of outpatient procedural migration rates and lipid emulsion adoption curves, calibrated against sterile injectable production capacity expansion announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under API supply disruption scenarios or accelerated ketamine protocol substitution in emergency medicine. Forecasts reflect assumptions regarding certificate-of-need relaxation continuity and propylene glycol industrial solvent market stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Nicorandil Market
Pharmaceuticals
Intranasal Migraine Drugs Market
Pharmaceuticals
Smart Pills Market
Pharmaceuticals
Finland Pharmaceutical Market
Pharmaceuticals
Acetaminophen Market
Pharmaceuticals
Dental Medication Market
Pharmaceuticals
Alectinib Drugs Market
Pharmaceuticals
Gamma-Hydroxybutyric Acid Market
Pharmaceuticals
Polypill Products Market
Pharmaceuticals
Opioids Market
Pharmaceuticals
Intravitreal (IVT) Injectables Market
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
Guaifenesin Market
Pharmaceuticals
Global Anti-Suicide Drugs Market
Pharmaceuticals
Oral Antiviral Market
Pharmaceuticals
Radiopharmaceutical (Oral Route) Market