
 Alectinib Drugs Market | 2026-2036
Alectinib Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Alectinib Drugs Market Insights
Companion diagnostic bundling is broadening what pharmaceutical manufacturers sell alongside alectinib regimens. Roche Holding AG leverages its integrated diagnostics division to anchor testing-to-treatment pathways across major oncology centers. Novartis AG competes through sustained investment in next-generation ALK inhibitor pipelines that extend its therapeutic franchise. Pfizer Inc. differentiates via manufacturing scale that controls supply security for oral kinase inhibitors in competitive markets.
Alectinib is a selective anaplastic lymphoma kinase inhibitor formulated as oral tablets and capsules for targeted cancer therapy, with a molecular structure designed to penetrate the blood-brain barrier for central nervous system metastases. The compound's primary commercial purpose centers on first-line and second-line treatment of ALK-positive non-small cell lung cancer where progression-free survival endpoints drive formulary placement. Tablet formulations dominate current volume due to patient adherence advantages and outpatient dispensing economics, while hospital channels capture the majority of value as site-of-care for infusion-to-oral transitions in oncology protocols. Non-small cell lung cancer as the leading therapy area commands the deepest clinical evidence base and broadest payer coverage, though research institutions represent a growing segment for combination trial enrollment and real-world evidence generation.
FDA oncology center review standards and EMA centralized marketing authorization procedures shape alectinib development programs, trial design, and label expansion pathways across regulated markets. Japan's PMDA priority review system and national health technology assessment processes determine reimbursement tiers that directly influence physician prescribing behavior and patient access. Stakeholders must monitor evolving ALK resistance mutation profiles and competitive pipeline readouts to anticipate where clinical differentiation will shift prescribing share across branded and generic formulations.
Market Dynamics
Companion diagnostic bundling is compressing standalone pharmaceutical sales into integrated testing-to-treatment contracts, forcing manufacturers to restructure commercial organizations around hospital-based oncology networks rather than traditional physician detailing models.
Growth Catalysts
- FDA accelerated approval pathways:Compressed clinical trial timelines enable earlier commercial entry for ALK inhibitors, reducing development-to-revenue cycles by 18-24 months in oncology programs.
- Japan PMDA priority review system:Fast-track reimbursement decisions in Tokyo and Osaka metropolitan areas accelerate patient access and drive prescriber familiarity with targeted therapies.
- Liquid biopsy adoption:Blood-based ALK mutation detection is expanding screening eligibility beyond tissue-dependent protocols, capturing patients previously excluded from targeted therapy candidacy.
Market Restraints
- Active pharmaceutical ingredient concentration:Over 70% of kinase inhibitor API supply originates from Chinese contract manufacturers, creating single-source vulnerability for oral oncology formulations.
- EMA centralized marketing authorization complexity:Divergent national reimbursement assessments post-approval fragment pricing power across Germany, France, and Italy despite unified regulatory clearance.
- Second-generation ALK resistance profiles:G1202R and I1171T mutations reduce alectinib durability, compelling physicians to reserve the agent for specific resistance sequences rather than universal sequencing.
Strategic Opportunities
- Brazil ANVISA regulatory convergence:Emerging market harmonization with ICH standards reduces trial duplication costs and opens access to Latin America's largest oncology patient pool.
- Real-world evidence generation platforms:Hospital data consortiums in the United States enable post-marketing survival analyses that support formulary renegotiation and label expansion submissions.
- Central nervous system metastasis protocols:Blood-brain barrier penetration advantages position alectinib for combination trials with radiation oncology departments seeking neuro-protective systemic options.
Industry Challenges
- Biomarker testing infrastructure gaps:Community oncology practices in rural United States regions lack in-house NGS capability, creating treatment delays and patient leakage to academic centers.
- Cross-resistance sequencing complexity:Physicians face escalating decision burden as third-generation ALK inhibitors enter the market, requiring continuous education on optimal therapy ordering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alectinib Drugs Market |
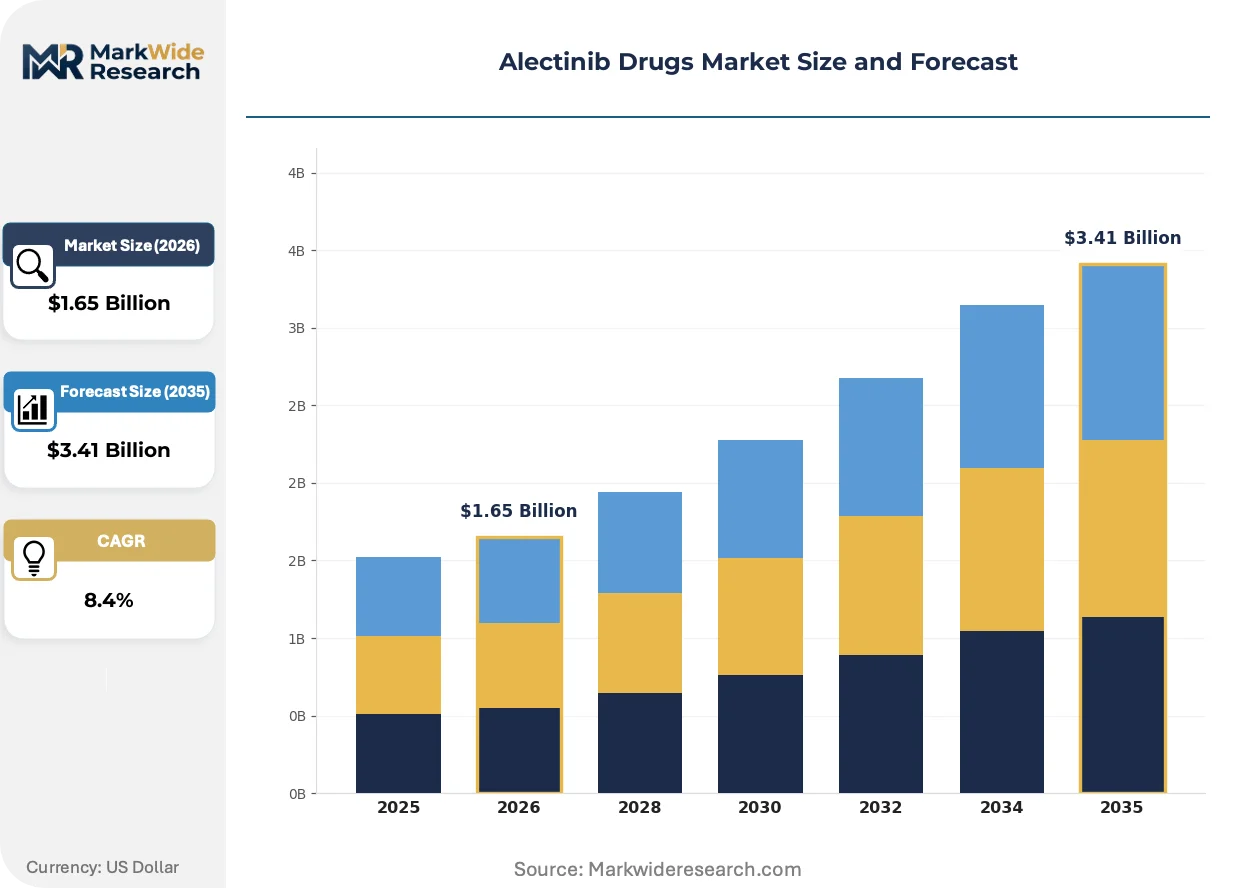
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.41 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injectable, Oral Solution Therapy Area: Non-Small Cell Lung Cancer, Melanoma, Colorectal Cancer, Breast Cancer Delivery Mode: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Clinics, Homecare, Research Institutions |
| Companies Covered | Novartis AG, Roche Holding AG, Pfizer Inc., Takeda Pharmaceutical Company Limited, Aurobindo Pharma Limited, Cipla Limited, Sun Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd., Hetero Drugs Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alectinib Drugs Market Trends and Innovations
Digital pathology and AI-assisted biomarker interpretation are compressing diagnostic turnaround times, while decentralized clinical trial models reshape patient recruitment economics for rare mutation subsets.
Next-generation sequencing panels are integrating ALK fusion detection into broad somatic profiling workflows, replacing single-gene testing in major United States cancer centers. Community hospitals in Texas and Florida are adopting these platforms at 40% annual expansion rates, collapsing the interval between suspicion and targeted therapy initiation. This convergence is integrating diagnostic and therapeutic revenue streams into unified hospital contracts.
Japan's PMDA has implemented conditional early approval frameworks requiring post-marketing efficacy confirmation, shifting sponsor investment toward real-world data collection infrastructure. Pharmaceutical manufacturers must now deploy dedicated medical affairs teams to Tokyo metropolitan hospitals for survival tracking. This policy is compressing traditional phase IV timelines and redirecting clinical operations budgets toward observational study networks.
Hospital procurement departments are consolidating oral oncology purchasing through specialty pharmacy carve-outs, displacing traditional wholesale distribution for high-cost kinase inhibitors. Integrated delivery networks in California and New York are negotiating direct manufacturer agreements that bundle alectinib with companion diagnostic rebates. This consolidation is most visible in United States academic medical centers where pharmacy benefit managers have lost formulary control to institutional specialty pharmacies.
Alectinib Drugs Market Segmentation
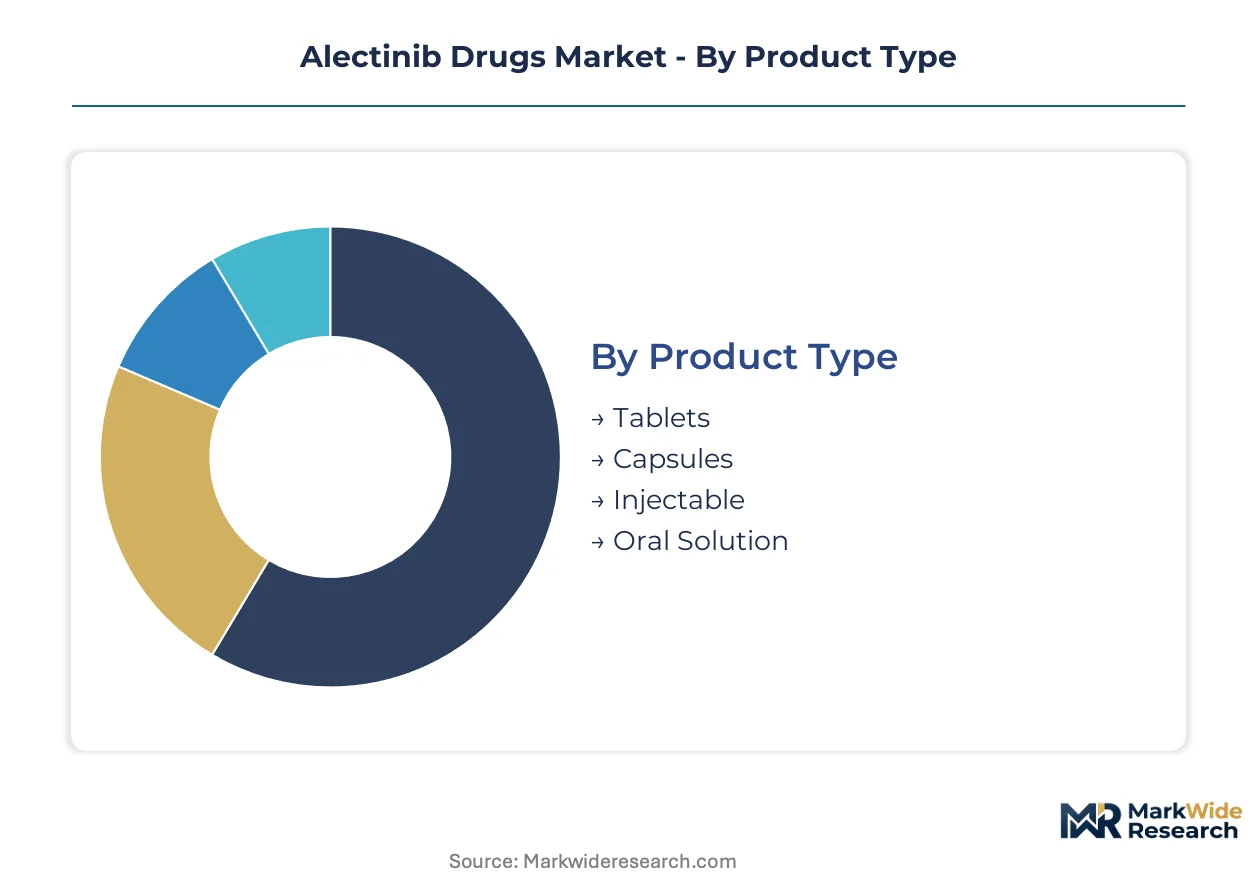
Alectinib's commercial architecture fragments across formulation preferences, site-of-care economics, and biomarker-driven patient stratification. Each segmentation axis carries distinct margin profiles and regulatory burdens that reshape manufacturer go-to-market design.
Product Type:
Standardization dominates oral solid dose manufacturing while liquid and parenteral formats serve narrower clinical niches requiring dose flexibility or bioavailability rescue.
- Tablets:Film-coated immediate-release tablets with 150mg and 600mg strengths anchor outpatient dispensing workflows. United States specialty pharmacies drive volume through 30-day supply automation and adherence packaging programs.
- Capsules:Hard gelatin shells accommodate modified-release profiles and pediatric dosing fractions. Demand clusters in Japan where PMDA-approved lower-strength formulations expand prescriber flexibility for hepatic impairment adjustments.
- Injectable:Lyophilized powder for IV reconstitution serves inpatient initiation protocols and patients with severe mucositis precluding oral intake.
- Oral Solution:Liquid formulation enables nasogastric tube administration and precise mg/kg dosing in investigational combination trials.
Most installed capacity flows through Tablets. Expansion is steepest in Capsules as dose-titration protocols gain protocol adoption.
Therapy Area:
Biomarker prevalence and payer coverage depth stratify addressable patient pools across oncology indications, with ALK fusion frequency determining commercial prioritization.
- Non-Small Cell Lung Cancer:Adenocarcinoma histology with ALK rearrangement represents the approved indication with broad reimbursement. United States academic medical centers capture the deepest prescribing concentration through molecular tumor board referral pathways.
- Melanoma:ALK-positive rare subtypes including Spitzoid variants drive exploratory prescribing in German and Italian melanoma centers with next-generation sequencing reflex testing.
- Colorectal Cancer:ALK fusion detection in RAS-wildtype metastatic disease remains investigational, with patient access limited to phase I/II trial enrollment at major United States cancer centers.
- Breast Cancer:Secretory carcinoma and inflammatory breast cancer ALK positivity supports compassionate use programs and basket trial participation in France and Spain.
Clinical development investment concentrates on Non-Small Cell Lung Cancer. Melanoma represents the fastest-climbing off-label utilization trajectory as diagnostic panels broaden.
Delivery Mode:
Patient autonomy and healthcare resource intensity trade off across administration routes, with oral self-administration displacing parenteral alternatives where bioequivalence permits.
- Oral:Self-administered daily dosing with food enables outpatient chronic management. United States integrated delivery networks prefer oral kinase inhibitors for specialty pharmacy carve-out economics and reduced infusion center burden.
- Intravenous:Hospital-based administration ensures therapeutic drug monitoring in hepatic impairment or drug-drug interaction scenarios requiring dose holds.
- Subcutaneous:Investigational depot formulations in early development target adherence improvement through monthly administration intervals.
- Topical:Transdermal patches for CNS metastasis prophylaxis remain preclinical, with blood-brain barrier penetration challenges unresolved.
Oral administration carries the deepest formulary penetration. Subcutaneous formats are gaining development priority for long-acting competitor differentiation.
End User:
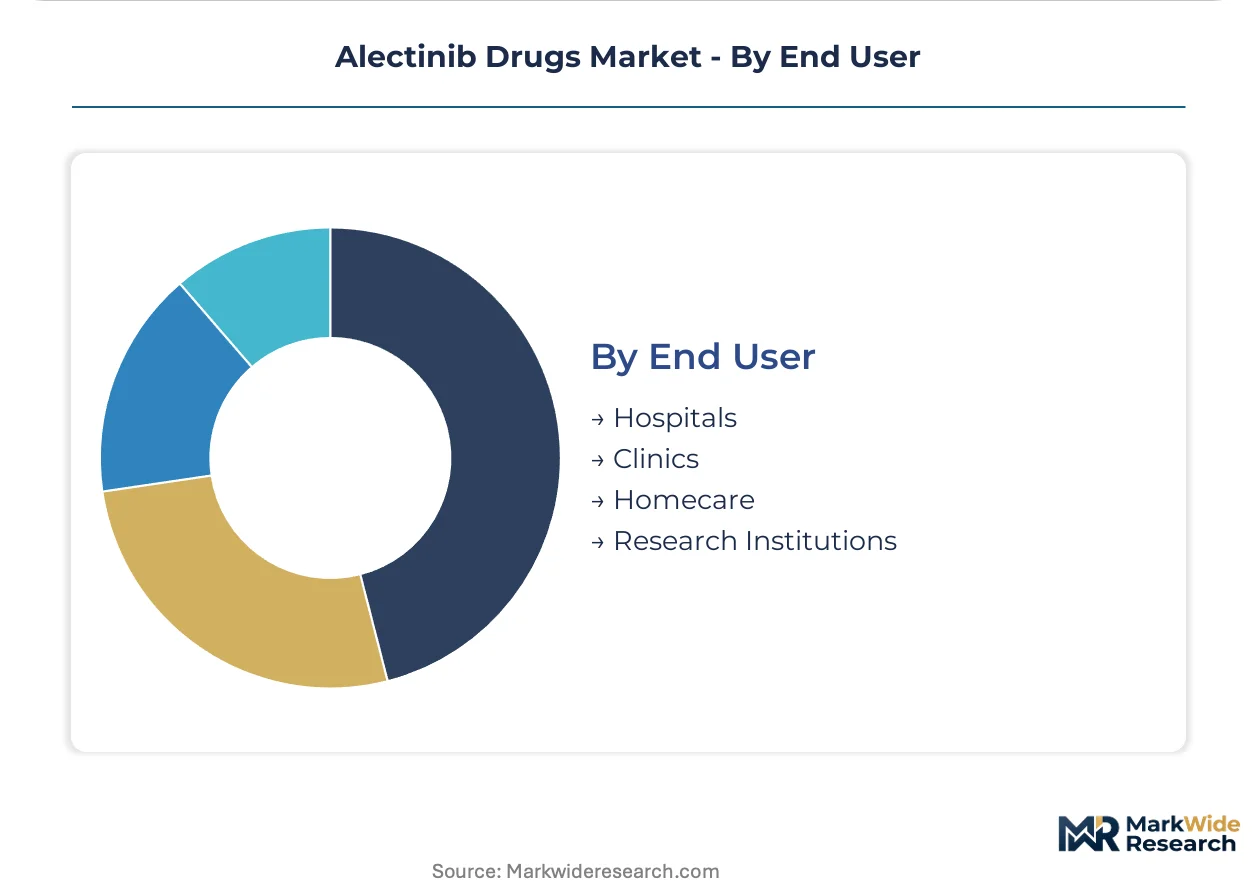
Care setting determines reimbursement mechanism, patient support service requirements, and real-world data capture infrastructure for post-marketing commitments.
- Hospitals:Academic medical centers and community hospital oncology departments manage complex ALK-positive patients with brain metastases. United States 340B pricing programs and Japan's Diagnosis Procedure Combination reimbursement anchor hospital channel economics.
- Clinics:Community oncology practices in Texas and Florida leverage liquid biopsy partnerships to accelerate treatment initiation outside hospital referral networks.
- Homecare:Home infusion nursing for oral medication adherence support and adverse event monitoring expands in Medicare Advantage and German statutory health insurance capitation models.
- Research Institutions:National Cancer Institute-designated centers and European Organisation for Research and Treatment of Cancer sites drive combination trial enrollment and resistance mechanism biobanking.
Hospital procurement departments command the largest contract value. Research Institutions are expanding most quickly as sponsor-funded early-phase trial density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States captures deeper prescribing concentration than Japan despite both markets maintaining mature ALK screening infrastructure, while Germany anchors European access through centralized reimbursement frameworks that accelerate patient identification.
United States
Academic medical centers in Boston and Houston drive volume through molecular tumor board pathways that compress diagnostic-to-treatment intervals. FDA oncology center review standards shape trial design and label expansion submissions. The 340B pricing program anchors hospital channel economics across California and New York integrated delivery networks.
Japan
Tokyo and Osaka metropolitan oncology departments concentrate prescriber familiarity with targeted therapies through PMDA priority review acceleration. The Diagnosis Procedure Combination reimbursement system directly influences physician behavior and patient access timelines. Lower-strength capsule formulations approved by PMDA expand prescriber flexibility for hepatic impairment adjustments in Kansai region hospitals.
Germany
Heidelberg and Munich cancer centers lead European ALK-positive patient identification through reflex next-generation sequencing protocols. EMA centralized marketing authorization procedures enable unified regulatory clearance, though divergent national reimbursement assessments fragment pricing power post-approval. The national health technology assessment process determines formulary placement across statutory health insurance funds.
China
Shanghai and Beijing tertiary hospitals expand liquid biopsy adoption for blood-based ALK mutation detection beyond tissue-dependent protocols. NMPA regulatory convergence with ICH standards reduces trial duplication costs for multinational sponsors. Yangtze River Delta oncology networks drive the fastest-climbing diagnostic panel expansion rates nationally.
Brazil
São Paulo and Rio de Janeiro academic centers concentrate Latin America's largest oncology patient pool for ALK-positive screening programs. ANVISA regulatory harmonization with international standards opens accelerated approval pathways for targeted therapies. Southeast regional hospitals are adopting companion diagnostic bundling models that integrate testing-to-treatment contracts.
Alectinib Drugs Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with research-intensive developers commanding premium positioning in first-line ALK-positive indications while generic producers capture volume in emerging markets through cost-optimized formulations. The vendor base concentrates around three strategic archetypes: integrated diagnostics-pharmaceutical conglomerates, pure-play kinase inhibitor specialists, and high-volume oral solid dose contract manufacturers. Capacity expansion and companion diagnostic bundling represent the dominant competitive moves reshaping commercial organization design.
Among research-intensive developers, Novartis AG and Roche Holding AG exemplify the integrated archetype that combines therapeutic pipelines with diagnostic infrastructure. Pfizer Inc. occupies a position emphasizing manufacturing scale for supply security in competitive oral oncology markets. These three anchors demonstrate how pharmaceutical manufacturers restructure around hospital-based oncology networks rather than traditional physician detailing models.
| Leading Market Players |
|---|
| Novartis AG |
| Roche Holding AG |
| Pfizer Inc. |
| Takeda Pharmaceutical Company Limited |
| Aurobindo Pharma Limited |
| Cipla Limited |
| Sun Pharmaceutical Industries Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Hetero Drugs Limited |
| Others |
Pricing and Supply Chain Analysis
Active pharmaceutical ingredient procurement from Chinese contract manufacturers flows through three pricing tiers before reaching hospital formularies, with kinase inhibitor raw material costs anchoring premium positioning for branded oral oncology products in United States and Japanese markets.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for generic alectinib formulations, compressing margins for originator products. Three-tier pricing structure across premium, standard, and economy levels separates patented first-line therapies from authorized generics and unbranded alternatives. Pricing pressure stems from PMDA-approved lower-strength Japanese capsules enabling dose-titration flexibility that reduces per-patient revenue. Community oncology practices in Texas and Florida demonstrate highest price sensitivity due to 340B program exposure, while academic medical centers in Boston and New York show lowest sensitivity through bundled companion diagnostic contracts.
Supply Chain Analysis
Regional distribution centers in Shanghai, Hyderabad, and Basel orchestrate hub-and-spoke patterns for oral kinase inhibitor distribution. API synthesis concentrates in China and India, with final formulation and packaging anchored in Switzerland and Japan. Supply chains draw from pyridine derivatives, fluorinated intermediates, and chiral resolution reagents as critical chemical inputs. Single-source vulnerability from Yangtze River Delta API manufacturers creates tariff exposure risk under evolving trade frameworks. Distribution runs through specialty pharmacy carve-outs in United States integrated delivery networks and hospital-based procurement in Japan and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alectinib market functions as a geographic-arbitrage play where Japanese PMDA priority review timelines compress commercial entry costs versus EMA centralized procedures, rewarding manufacturers with regulatory operations in Tokyo.
For Market Incumbents: Deepen companion diagnostic bundling through in-house NGS platform partnerships that lock hospital formularies against third-generation ALK inhibitor entrants. Acquire liquid biopsy capabilities to preempt community oncology leakage to academic centers. Expand Heidelberg and Munich cancer center contracts before German statutory health insurance renegotiation cycles.
For New Entrants and Emerging Players: Enter via Brazil ANVISA regulatory convergence pathways that accept ICH-standard trial data without duplication costs. Target São Paulo and Rio de Janeiro academic centers where companion diagnostic infrastructure gaps create white-space for testing-to-treatment integration. Lead with cost-optimized capsule formulations priced against Japanese PMDA-approved dose-flexibility positioning.
For Investors and Strategic Acquirers: Consolidation pressure builds where second-generation ALK resistance profiles fragment prescribing sequences across multiple agents. Five-to-ten year viability hinges on CNS metastasis protocol positioning and real-world evidence generation infrastructure. Target acquisition archetype: mid-cap kinase inhibitor specialists with blood-brain barrier penetration IP and Tokyo-based medical affairs teams. Watch FDA oncology center review standard shifts for accelerated approval pathway compression as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Bundling | Roche leverages Foundation Medicine integration to anchor testing-to-treatment hospital contracts. |
| Real-World Evidence Generation | Novartis deploys Tokyo medical affairs teams for PMDA-mandated post-marketing survival tracking. |
| API Supply Security Investment | Pfizer diversifies contract manufacturer relationships beyond Yangtze River Delta concentration. |
| Liquid Biopsy Partnership | Community oncology practices in Florida adopt blood-based ALK detection to reduce patient leakage. |
| Next-Generation ALK Pipeline | Takeda advances third-generation inhibitors targeting G1202R resistance mutations. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with formulary directors, regulatory affairs leads, hospital oncology chiefs, and payer access specialists were cross-validated against FDA filings, EMA centralized procedure documents, ClinicalTrials.gov records, and Japanese Diagnosis Procedure Combination reimbursement databases. Secondary sources included PMDA review reports, German statutory health insurance formulary listings, and United States 340B pricing program disclosures.
Historical trendline analysis of ALK-positive non-small cell lung cancer patient identification rates informed projection frameworks across the analysis window. Segmentation dimensions encompassed formulation type, therapy line, administration route, end-user setting, and regional regulatory cluster. CAGRs were derived from patient volume trajectories, pricing elasticity assumptions, and biomarker testing expansion curves. Forecast inputs incorporated liquid biopsy adoption velocities, resistance mutation surveillance data, and hospital specialty pharmacy carve-out penetration.
Inputs from formulary databases and clinical trial registries were available through the study window; gaps in real-world adherence data and off-label prescribing patterns introduce uncertainty bands around volume projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Direct Oral Anticoagulants Market
Pharmaceuticals
Iodine Deficiency Drug Market
Pharmaceuticals
Antiplatelet Drugs Market
Pharmaceuticals
Global Combination Vaccine Market
Pharmaceuticals
Global HPMC Capsules Market
Pharmaceuticals
Japanese Encephalitis Vaccine Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market
Pharmaceuticals
Netherlands Pharmaceutical Market
Pharmaceuticals
Respiratory Virus Vaccines Market
Pharmaceuticals
Beta Blockers Market
Pharmaceuticals
Adapalene Products Market
Pharmaceuticals
Saudi Arabia Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Acetylspiramycin Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Trisenox Market