
 Global Acetazolamide Market | 2026-2036
Global Acetazolamide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acetazolamide Market Foresight
Generic sulfonamide chemistry is pivoting toward cost-optimized active pharmaceutical ingredient sourcing as acetazolamide manufacturing shifts from traditional batch synthesis to continuous flow processing. Lannett Company leverages vertical integration across API-to-finished-dose capabilities to protect margin structures. Teva Pharmaceutical Industries Ltd anchors European hospital supply through centralized procurement contracts. Sun Pharmaceutical Industries Ltd dominates emerging market tenders with localized production footprints.
Acetazolamide is a carbonic anhydrase inhibitor with the chemical formula C4H6N4O3S2, functioning through reversible inhibition of the enzyme carbonic anhydrase to reduce bicarbonate formation and lower intraocular pressure. Tablet formulations occupy the largest revenue share due to chronic glaucoma maintenance protocols, while injectable presentations capture premium pricing in acute mountain sickness and perioperative edema settings. The therapy area segmentation shows glaucoma sustaining mature volume bases as epilepsy and altitude sickness applications attract neurology and travel-medicine investment.
The FDA enforces Current Good Manufacturing Practice standards for acetazolamide production under 21 CFR 211, while the EMA's revised Annex 1 guidelines on sterile manufacture reshape injectable supply chain validation requirements. India's CDSCO accelerates bioequivalence scrutiny for generic acetazolamide filings under its revised 2019 New Drugs and Clinical Trials Rules. Stakeholders must monitor how carbonic anhydrase inhibitor class labeling updates and pharmacovigilance obligations in major markets reshape portfolio prioritization decisions.
Market Dynamics
Continuous flow chemistry is displacing batch synthesis as the dominant acetazolamide production paradigm, compressing manufacturing timelines from weeks to hours while tightening impurity profiles to meet FDA and EMA bioequivalence thresholds.
Growth Catalysts
- Hospital pharmacy centralization:Bulk procurement contracts across US and EU acute care networks are consolidating order volumes and extending contract durations for carbonic anhydrase inhibitors.
- EMA Annex 1 sterile manufacturing guidelines:The 2022 revision mandates enhanced environmental monitoring for injectable acetazolamide, favoring manufacturers with validated isolator technology and automated filling lines.
- Altitude tourism infrastructure:Expanding commercial trekking and mining operations above 3,000 meters in Peru, Nepal, and Tanzania are creating predictable demand cycles for prophylactic acetazolamide.
Market Restraints
- API supply concentration:Over 70% of acetazolamide active pharmaceutical ingredient originates from Chinese manufacturers concentrated in Zhejiang and Jiangsu provinces, creating single-source vulnerability.
- Thiazide diuretic substitution:Hydrochlorothiazide and chlorthalidone retain formulary preference for uncomplicated hypertension and mild edema in cost-constrained health systems.
- Sulfonamide hypersensitivity liability:Cross-reactivity with antibacterial sulfonamides limits prescribing confidence among primary care physicians and emergency medicine specialists.
Strategic Opportunities
- CDSCO accelerated approval pathway:India's 2019 New Drugs and Clinical Trials Rules enable faster generic acetazolamide registration for domestic manufacturers meeting bioequivalence standards.
- Epilepsy adjunct therapy positioning:Refractory seizure protocols in pediatric neurology are expanding off-label utilization beyond established glaucoma and altitude sickness indications.
- Direct-to-clinic distribution:Specialty pharmaceutical distributors are bypassing wholesale intermediaries to serve ophthalmology practices with consignment inventory and just-in-time replenishment.
Industry Challenges
- Continuous flow engineering talent scarcity:Pharmaceutical process chemists with microreactor design and real-time process analytical technology expertise command premium compensation and limited availability.
- Legacy batch facility stranded assets:Converting stainless steel reactor trains to continuous processing requires complete production line replacement rather than incremental retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acetazolamide Market |
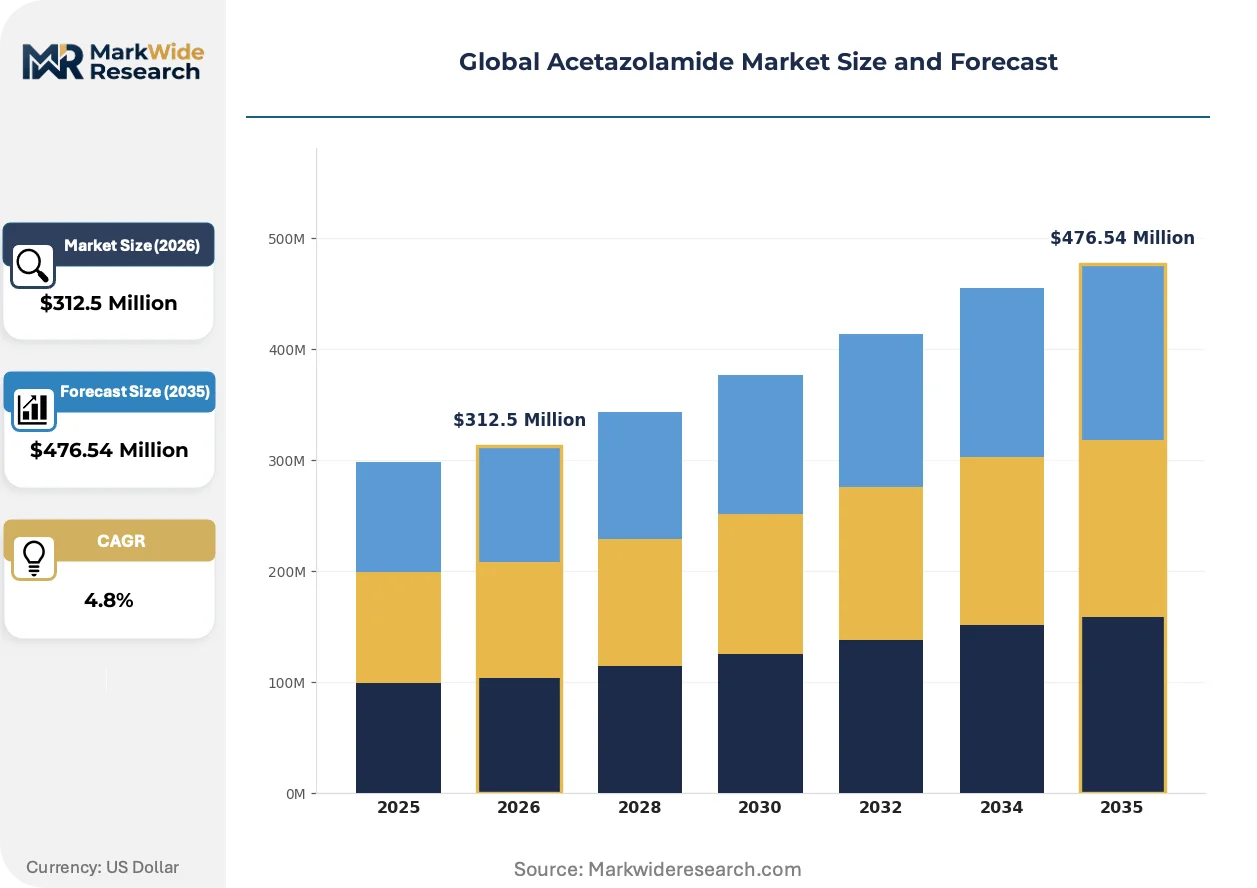
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Injectable, Oral Suspension, Extended Release Capsule Therapy Area: Glaucoma, Epilepsy, Altitude Sickness, Edema, Neurological Disorders End User: Hospitals, Specialty Clinics, Ambulatory Care Centers, Diagnostic Laboratories Distribution Channel: Hospital Pharmacy, Retail Pharmacy, Online Pharmacy, Institutional Purchase |
| Companies Covered | Lannett Company, Inc., Heritage Pharmaceuticals Inc., Teva Pharmaceutical Industries Ltd, Accord Healthcare Ltd, Nostrum Laboratories Inc., Taro Pharmaceutical Industries Ltd, Sun Pharmaceutical Industries Ltd, Strides Pharma Science Limited, Zydus Lifesciences Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acetazolamide Market Shifts & Advancements
Process intensification and regulatory science are converging to reshape how acetazolamide reaches end-users, with implications stretching from API synthesis through final-mile hospital delivery.
Microreactor-based continuous flow synthesis is modularizing acetazolamide production by enabling distributed manufacturing footprints closer to formulation sites. European contract manufacturers are piloting containerized production units that slash solvent volumes and crystallization times. This architecture is compressing supply chain exposure to geopolitical disruption and customs delays.
FDA's Quality Management Maturity program is elevating inspection intensity for foreign acetazolamide API facilities, with India and China sites facing extended approval timelines for new drug master file submissions. The agency's risk-based site selection model prioritizes facilities with prior warning letter history. Generic sponsors are responding by pre-positioning alternative supply sources and accelerating Type II active substance master file amendments.
Consignment inventory arrangements are displacing traditional purchase-order cycles in US hospital pharmacy procurement, with ophthalmology clinics and surgery centers accepting vendor-managed stock for high-turnover acetazolamide tablets. Distributors bear carrying costs and obsolescence risk in exchange for exclusive supply relationships. This model is most visible in the southeastern and southwestern United States where ambulatory surgical center networks concentrate.
Global Acetazolamide Market Segmentation
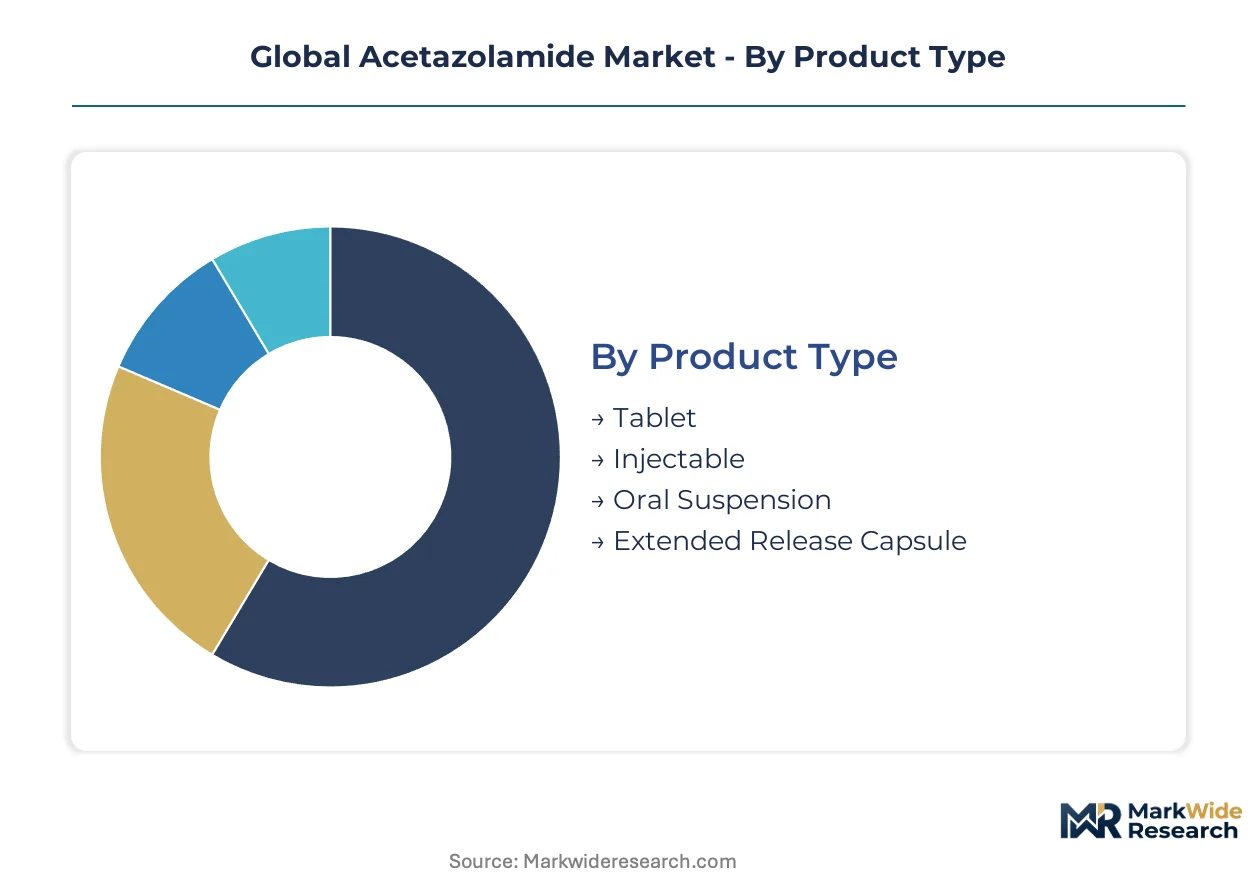
Acetazolamide's therapeutic versatility fragments demand across four distinct classification systems. Each segmentation layer carries unique regulatory burdens, pricing power, and channel access requirements that shape manufacturer portfolio decisions.
Product Type:
Tablet and injectable presentations face divergent approval pathways under FDA 21 CFR 211 and EMA Annex 1, while oral suspensions and extended-release formats trigger additional bioequivalence scrutiny.
- Tablet:Compressed solid dosage forms containing acetazolamide as the active moiety dominate chronic glaucoma maintenance protocols. US hospital pharmacies consolidate procurement through multi-year tenders with Lannett Company and Teva Pharmaceutical Industries, while India's CDSCO accelerates domestic generic approvals under 2019 rules.
- Injectable:Sterile parenteral solutions for acute mountain sickness and perioperative edema command premium pricing in emergency medicine settings. EMA's revised Annex 1 guidelines mandate isolator technology and automated filling lines, favoring manufacturers with validated aseptic processing capabilities.
- Oral Suspension:Liquid formulations accommodate pediatric and geriatric populations with swallowing difficulties, requiring stability testing under ICH Q1A conditions.
- Extended Release Capsule:Modified-release technology reduces dosing frequency for refractory epilepsy protocols, though development costs limit sponsor participation.
Leading the category by volume: Tablet. Growing fastest: Injectable.
Therapy Area:
Cost tier stratification separates mature glaucoma maintenance from emerging neurological applications, with altitude sickness occupying a premium niche tied to adventure tourism infrastructure.
- Glaucoma:Chronic open-angle and angle-closure management sustains baseline demand through ophthalmology clinics in the United States, Germany, and Japan. Medicare Part D and statutory health insurance reimbursement frameworks lock in predictable volume, though thiazide diuretic substitution pressures formulary placement.
- Epilepsy:Adjunct therapy for refractory seizures in pediatric neurology protocols is expanding utilization beyond labeled indications. Academic medical centers in Boston, London, and Melbourne pilot off-label protocols with institutional review board oversight.
- Altitude Sickness:Prophylactic use among commercial trekking operations in Nepal, Peru, and Tanzania creates seasonal demand spikes. Travel medicine clinics in Denver and Zurich stock inventory ahead of Himalayan and Andean climbing seasons.
- Edema:Perioperative fluid management in cardiac and hepatic surgery settings competes with loop diuretic preference in cost-constrained health systems.
- Neurological Disorders:Investigational applications in idiopathic intracranial hypertension and periodic paralysis attract specialty pharmacy distribution.
Volume concentration: Glaucoma. Steepest expansion trajectory: Epilepsy.
End User:
Customer type determines procurement modality, with hospitals demanding consignment inventory while ambulatory centers prefer just-in-time replenishment through specialty distributors.
- Hospitals:Acute care networks in the United States and European Union centralize carbonic anhydrase inhibitor procurement through group purchasing organizations. Bulk contracts extend to 36-month durations with price protection clauses and minimum volume commitments.
- Specialty Clinics:Ophthalmology and neurology practices in São Paulo, Mumbai, and Shanghai generate high-margin prescription volume through direct-to-clinic distribution models bypassing wholesale intermediaries.
- Ambulatory Care Centers:Freestanding surgical facilities in Texas, Florida, and Arizona accept vendor-managed stock for high-turnover tablet presentations.
- Diagnostic Laboratories:Limited acetazolamide utilization in provocative testing for cerebrospinal fluid leak detection supports niche reagent demand.
Procurement scale leader: Hospitals. Fastest channel growth: Specialty Clinics.
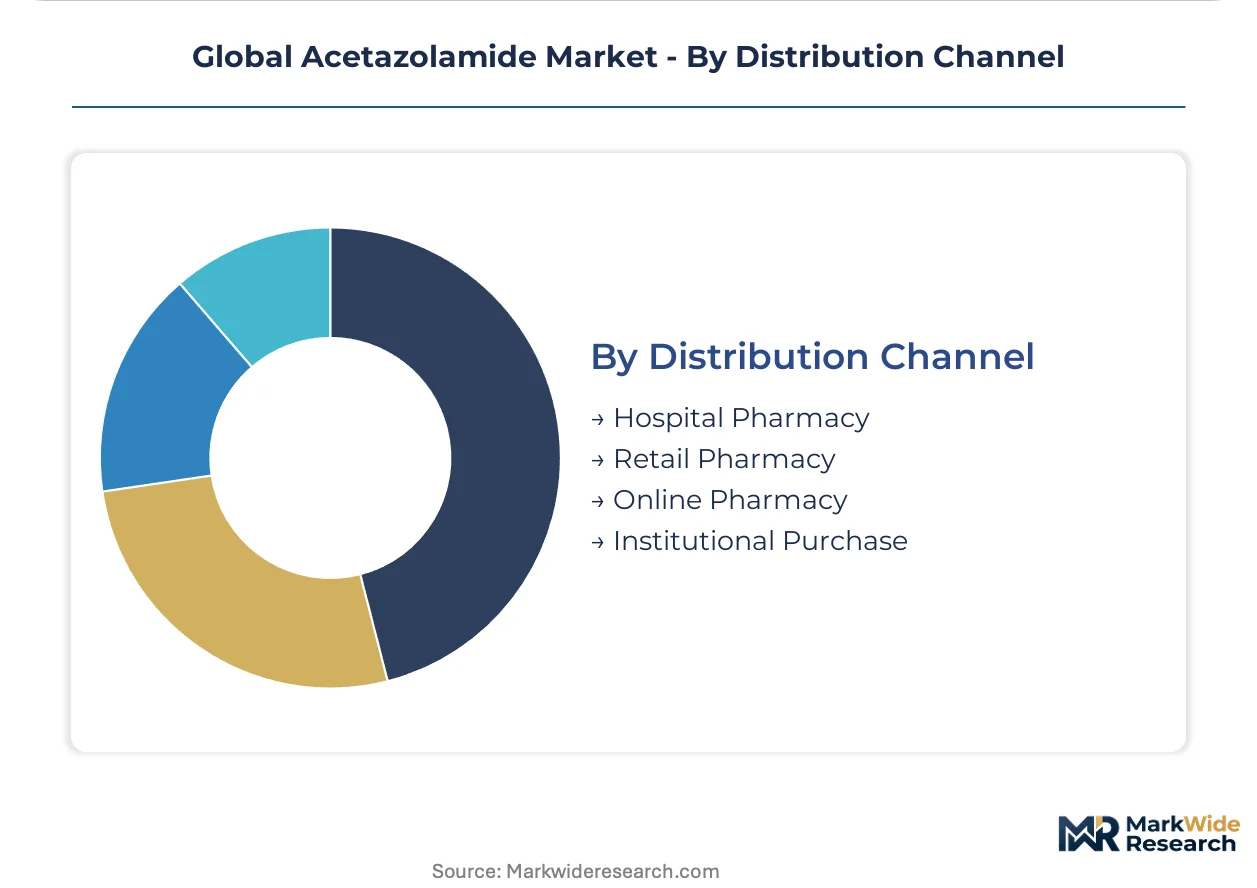
Distribution Channel:
Supply concentration in Chinese API manufacturing clusters shapes channel economics, with institutional purchase and hospital pharmacy capturing margin through volume aggregation.
- Hospital Pharmacy:Centralized dispensing within acute care networks controls inventory for inpatient injectable and outpatient tablet protocols. US health systems in the Southeast and Southwest deploy automated dispensing cabinets with real-time usage tracking.
- Retail Pharmacy:Community-based dispensing for chronic glaucoma maintenance faces generic substitution pressure and preferred network restrictions under Medicare Part D.
- Online Pharmacy:Direct-to-consumer platforms in India and Brazil expand access for altitude sickness prophylaxis among recreational trekkers, though cold-chain integrity concerns limit injectable penetration.
- Institutional Purchase:Government tenders in China, India, and Brazil concentrate procurement through local manufacturing incentives and domestic preference policies.
Dominant volume channel: Hospital Pharmacy. Gaining share fastest: Online Pharmacy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical special economic zones in Hyderabad and Ahmedabad concentrate acetazolamide API manufacturing through tax holidays and export-processing incentives. These zones attract contract manufacturers serving European and North American formulation sites.
United States
Hospital pharmacy centralization across the Southeast and Southwest drives bulk procurement contracts for carbonic anhydrase inhibitors. FDA's Quality Management Maturity program extends inspection timelines for foreign API facilities, prompting sponsors to pre-position domestic finishing capacity. The Research Triangle Park corridor in North Carolina hosts formulation development labs serving ophthalmology clinics.
Germany
EMA Annex 1 sterile manufacturing guidelines reshape injectable acetazolamide validation requirements for hospital networks. The country's statutory health insurance reimbursement frameworks lock in predictable volume for chronic glaucoma maintenance. Bavaria's pharmaceutical cluster around Munich concentrates aseptic processing expertise for premium parenteral presentations.
India
CDSCO's 2019 New Drugs and Clinical Trials Rules accelerate generic acetazolamide registration for domestic manufacturers. Government tenders in Maharashtra and Gujarat concentrate procurement growth through local manufacturing incentives. Hyderabad's API manufacturing belt supplies intermediates to formulation sites across Telangana and Andhra Pradesh.
China
Over 70% of acetazolamide active pharmaceutical ingredient originates from Zhejiang and Jiangsu province manufacturers. NMPA's revised drug master file requirements extend approval timelines for export-oriented facilities. The Yangtze River Delta chemical corridor hosts continuous flow chemistry pilot programs for sulfonamide API production.
Brazil
Government tenders through ANVISA's domestic preference policies concentrate procurement for hospital pharmacy networks. Altitude tourism infrastructure in Minas Gerais and São Paulo states creates seasonal demand for prophylactic acetazolamide. São Paulo's specialty clinic corridor generates high-margin prescription volume through direct-to-clinic distribution models.
Global Acetazolamide Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital pharmacy procurement favoring established suppliers while emerging markets open entry points for regional players. The vendor base organizes around three tiers: multinational generics with vertical API-to-finished-dose capabilities, mid-size specialty pharmaceutical companies with therapeutic focus, and emerging market contract manufacturers serving government tenders. Consolidation pressure operates through strategic partnerships for continuous flow technology access and geographic expansion into underserved hospital networks.
Among North American-based suppliers, Lannett Company, Inc. and Heritage Pharmaceuticals Inc. occupy positions within the specialty generic tier, representing manufacturers with captive API sourcing and hospital contracting expertise. Teva Pharmaceutical Industries Ltd anchors the multinational segment through centralized European supply relationships. Sun Pharmaceutical Industries Ltd exemplifies the emerging market contract manufacturing archetype with localized production footprints serving tender-driven procurement systems.
| Leading Market Players |
|---|
| Lannett Company, Inc. |
| Heritage Pharmaceuticals Inc. |
| Teva Pharmaceutical Industries Ltd |
| Accord Healthcare Ltd |
| Nostrum Laboratories Inc. |
| Taro Pharmaceutical Industries Ltd |
| Sun Pharmaceutical Industries Ltd |
| Strides Pharma Science Limited |
| Zydus Lifesciences Limited |
| Others |
Supply & Pricing Matrix
Acetazolamide API feedstock costs from Zhejiang and Jiangsu province manufacturers cascade through three pricing tiers downstream, with hospital pharmacy procurement contracts absorbing volatility through volume commitments while specialty clinics pay premiums for just-in-time injectable delivery.
Pricing Analysis
Short lead-time premiums for sterile injectable acetazolamide command 40-60% markups over standard tablet contracts in US emergency medicine settings. Three-tier pricing structure across premium isolator-certified, standard aseptic, and economy batch-processed levels separates EMA Annex 1-compliant manufacturers from cost-optimized tender suppliers. Cost compression in the economy tier is intensifying because Indian CDSCO accelerated approvals are flooding government procurement channels with bioequivalent generics. Hospital group purchasing organizations exhibit lowest price sensitivity due to formulary lock-in, while independent ophthalmology practices in Brazil and India negotiate aggressively on tablet presentations.
Supply Chain Analysis
Acetazolamide production rests on Chinese sulfonamide intermediate supply concentrated in the Yangtze River Delta chemical corridor, with secondary API finishing capacity in Hyderabad and Ahmedabad pharmaceutical special economic zones. Key inputs span 4-acetamidobenzenesulfonyl chloride, ammonia feedstock, and crystallization solvents governed by REACH and TSCA environmental thresholds. Single-source vulnerability from Zhejiang province concentration creates exposure to NMPA export license delays and customs inspection backlogs. Distribution runs through hospital pharmacy centralized procurement in the US and EU, with emerging market government tenders bypassing wholesale intermediaries entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acetazolamide manufacturing is becoming a vertical-integration race, with API-to-finished-dose control emerging as the decisive margin-protection lever as Chinese feedstock volatility intensifies.
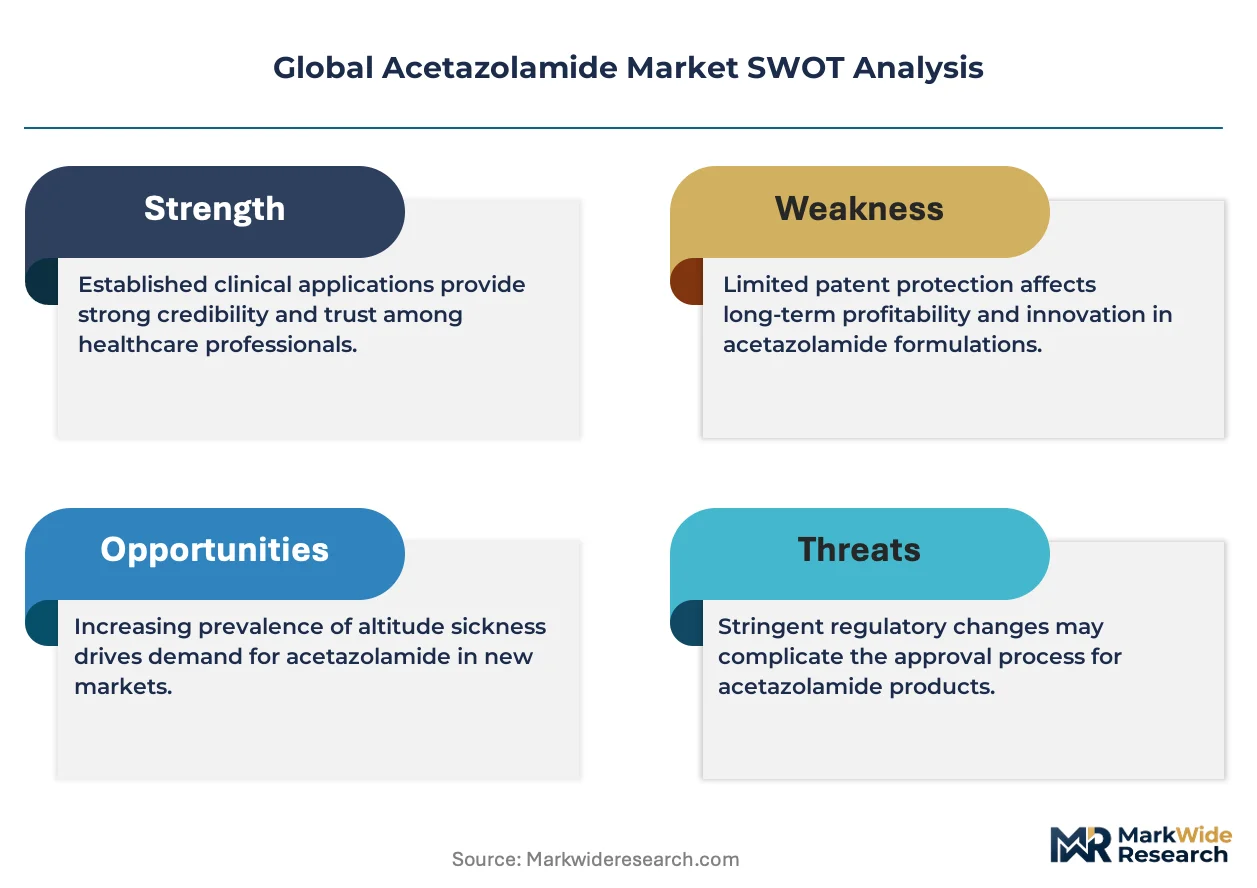
For Market Incumbents: Lock in multi-year sulfonamide intermediate supply agreements with Zhejiang province producers before NMPA environmental compliance deadlines tighten export availability. Convert legacy batch facilities to continuous flow processing through modular microreactor partnerships, as EMA Annex 1 sterile manufacturing guidelines are raising validation barriers for competitors without isolator technology. For New Entrants and Emerging Players: Enter via CDSCO accelerated approval pathway for domestic Indian manufacturing, targeting Maharashtra and Gujarat government tenders with localized production footprints. The most penetrable white-space sits in direct-to-clinic distribution for altitude tourism clinics in Nepal, Peru, and Tanzania, bypassing hospital pharmacy intermediaries through consignment inventory models. For Investors and Strategic Acquirers: FDA Quality Management Maturity program enforcement delays at Chinese API facilities is the leading indicator that domestic US finishing capacity will command scarcity premiums. Long-term viability hinges on acquiring mid-scale manufacturers with validated continuous flow chemistry expertise and existing hospital GPO contracts. Watch for CDSCO bioequivalence rejection spikes as the inflection signal for regulatory-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Manufacturing Transition | Microreactor adoption compresses acetazolamide synthesis timelines from weeks to hours while tightening impurity profiles for FDA bioequivalence thresholds. |
| EMA Annex 1 Compliance Investment | Isolator technology and automated filling line validation secures premium injectable positioning in German and French hospital networks. |
| CDSCO Accelerated Registration Pathway | Domestic Indian manufacturers leveraging 2019 New Drugs and Clinical Trials Rules capture government tender volume through local production incentives. |
| Direct-to-Clinic Distribution Model | Specialty pharmaceutical distributors bypass wholesale intermediaries to serve ophthalmology practices with consignment inventory in Texas and Florida. |
| API Supply Pre-Positioning | Alternative sulfonamide intermediate sourcing from Indian Hyderabad belt reduces single-source dependency on Zhejiang province concentration. |
Research Methodology
FDA 21 CFR 211 filings, EMA Annex 1 regulatory updates, and Indian CDSCO approval databases formed the secondary backbone, cross-referenced with primary interviews spanning hospital pharmacy procurement directors, carbonic anhydrase inhibitor regulatory affairs leads, and contract manufacturing organization process chemists. Bottom-up volume estimates from hospital dispensing data and tender awards were triangulated against top-down pharmaceutical market sizing frameworks.
Historical trendline analysis of acetazolamide prescription volumes across glaucoma, epilepsy, and altitude sickness therapy areas established baseline growth trajectories over the projection horizon. Segmentation modeling incorporated product type, therapy area, end user archetype, and distribution channel dimensions. CAGRs were derived from regression-weighted consensus across primary stakeholder demand forecasts and secondary epidemiological projections for target indications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA export restriction scenarios or EMA sterile manufacturing guideline enforcement spikes. Forecasts reflect assumptions documented in primary interview transcripts and secondary regulatory filings. API supply disruption from Chinese environmental compliance actions, CDSCO bioequivalence standard tightening, and thiazide diuretic formulary substitution represent specific revision triggers. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Powder-Filled Hard Gelatin Capsules Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Lamotrigine API Market
Pharmaceuticals
Meningococcal Vaccines Market
Pharmaceuticals
Laxatives Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market
Pharmaceuticals
Large Volume Parenteral (LVP) Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Anti-Infective Vaccines Market
Pharmaceuticals
Cholinesterase Inhibitors Market
Pharmaceuticals
Global Thyroid Cancer Drugs Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Australia Pharmaceuticals Market
Pharmaceuticals
Thrombosis Drugs Market