
 Dermatitis Drugs Market | 2026-2036
Dermatitis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Dermatitis Drugs Market Intelligence
The capital-intensity gap between biologic R&D and topical corticosteroid manufacturing is unwinding traditional market structures. Regeneron Pharmaceuticals leverages its leadership in monoclonal antibody development for atopic dermatitis. Sanofi competes through a broad portfolio spanning both biologics and established topical treatments. Smaller players like LEO Pharma specialize in specific dermatological niches, focusing on topical formulations.
Dermatitis drugs are pharmaceutical agents designed to manage inflammatory skin conditions by modulating the immune response or providing symptomatic relief. These compounds, ranging from small-molecule corticosteroids to large-molecule biologics, aim to reduce inflammation, pruritus, and skin barrier dysfunction. While topical corticosteroids remain a high-volume segment, injectable immunomodulators for severe atopic dermatitis command the highest price points. Demand across dermatology clinics and specialty hospitals is shifting towards these newer, more targeted therapies over traditional emollients.
Market access and clinical trial requirements are governed by agencies such as the US FDA, the European Medicines Agency (EMA), and China's NMPA. These bodies set stringent efficacy and safety standards for new drug approvals, particularly for novel biologics. Navigating the divergent reimbursement policies for high-cost therapies across different national healthcare systems remains a critical strategic challenge for manufacturers.
Market Dynamics
The fundamental market dynamic is the value-volume divergence between traditional high-volume topical corticosteroids and new high-cost, low-volume biologics. This shift is reconfiguring R&D investment priorities, clinical practice, and reimbursement frameworks across the healthcare system.
Growth Catalysts
- Advanced Immunomodulators:The development of targeted therapies, including Janus kinase (JAK) inhibitors and monoclonal antibodies, provides superior efficacy for severe atopic dermatitis, expanding treatment options beyond conventional topicals.
- Rising Disease Prevalence:An increasing incidence and diagnosis of atopic and contact dermatitis, particularly in industrialized nations like the United States and Germany, enlarges the addressable patient population for pharmaceutical intervention.
- Favorable Reimbursement:Payer coverage for high-cost biologics in key markets, supported by frameworks within the US healthcare system, facilitates patient access and encourages physician prescription of these advanced treatments.
Market Restraints
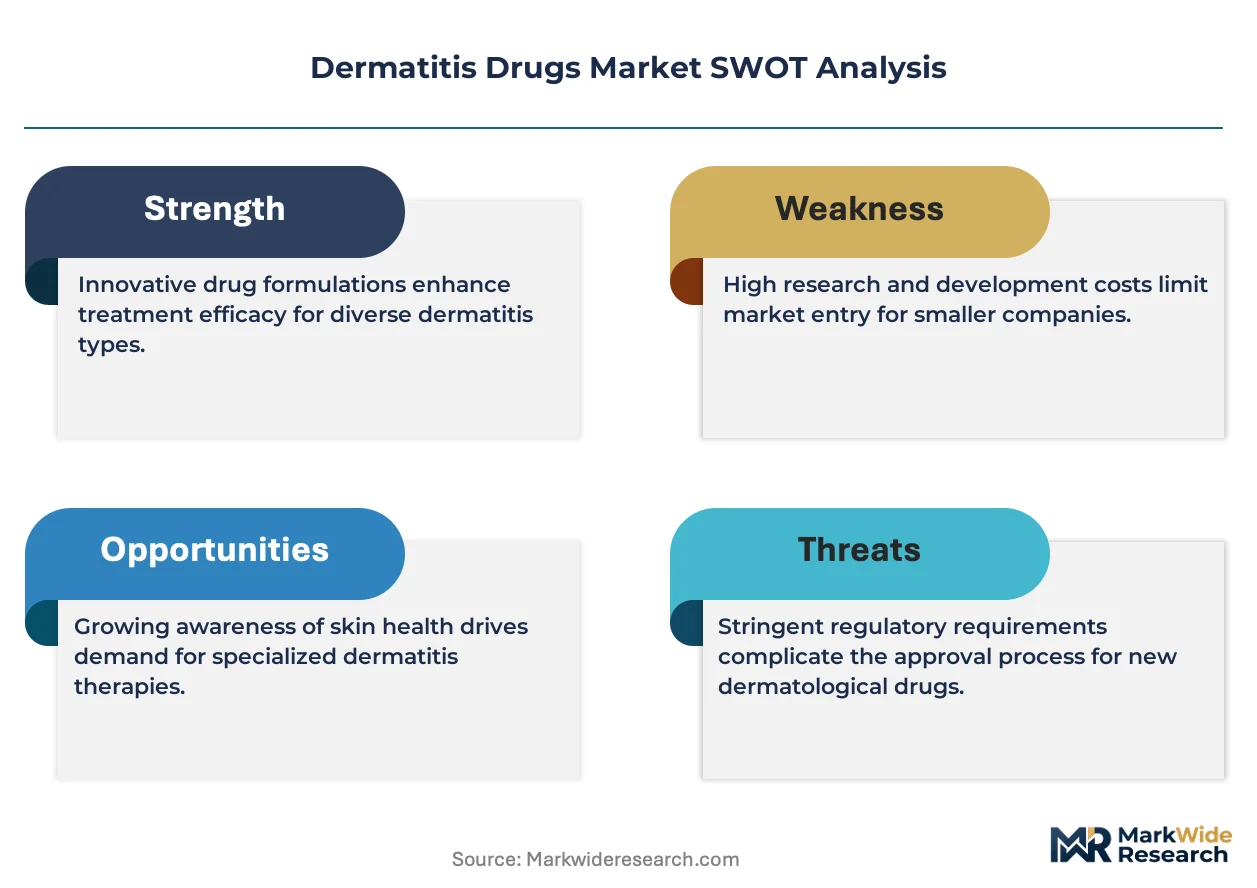
- High Development Costs:The significant capital investment required for biologic drug discovery, clinical trials, and specialized manufacturing presents a substantial barrier to entry and constrains the pipeline of smaller innovators.
- Stringent Regulatory Hurdles:Navigating complex and disparate approval pathways set by the US FDA, EMA in Europe, and China's NMPA for novel drugs delays market entry and increases compliance costs.
- Generic Competition:The widespread availability and low cost of generic topical corticosteroids for mild-to-moderate dermatitis limits the market penetration of premium-priced branded therapies in first-line treatment settings.
Strategic Opportunities
- Emerging Market Expansion:Underpenetrated patient populations in countries like Brazil and India represent significant growth avenues as healthcare infrastructure improves and access to dermatological care broadens.
- Pipeline Diversification:Focusing R&D on underserved dermatitis subtypes, such as dyshidrotic eczema or nummular dermatitis, allows for the creation of niche products with clear clinical differentiation.
- AI in Drug Discovery:Applying artificial intelligence and machine learning algorithms to analyze genomic and proteomic data can accelerate the identification of novel therapeutic targets and predict compound efficacy.
Industry Challenges
- Payer Negotiation Complexity:Securing favorable pricing and reimbursement status from national health authorities and private insurers, especially in Europe's single-payer systems, remains a critical and resource-intensive challenge.
- Clinical Trial Execution:The lengthy timelines and high costs associated with conducting global Phase III trials that meet the stringent evidence standards of regulators like Japan's PMDA create operational burdens.
- Cold Chain Logistics:Maintaining the integrity of the cold chain for temperature-sensitive injectable biologics from manufacturing facilities to specialty pharmacies and clinics requires specialized and costly infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermatitis Drugs Market |
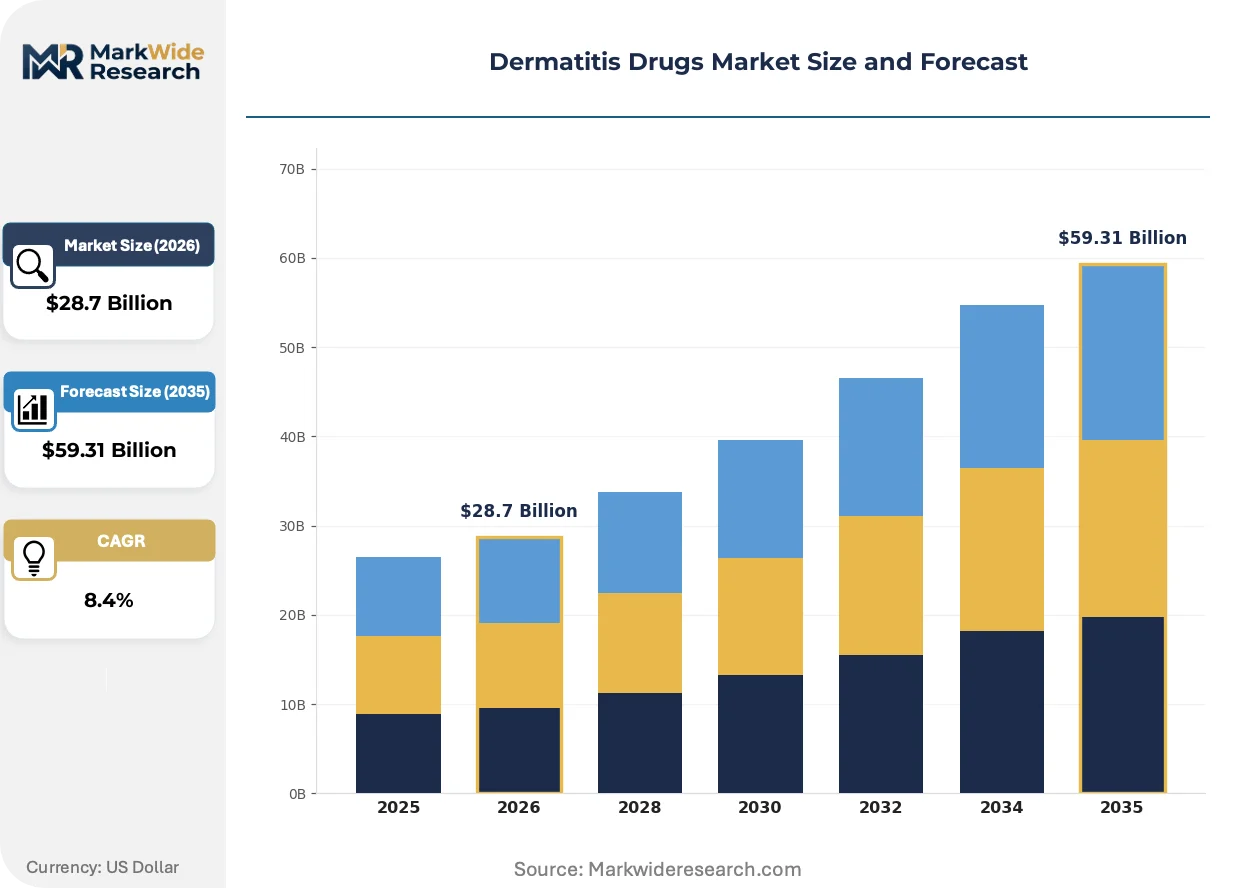
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Calcineurin Inhibitors, Antihistamines, Emollients, Immunomodulators Application: Atopic Dermatitis, Contact Dermatitis, Seborrheic Dermatitis, Nummular Dermatitis, Stasis Dermatitis End User: Dermatology Clinics, Specialty Hospitals, Pharmacies, Outpatient Facilities, Home Care Settings Delivery Mode: Topical Creams, Ointments, Oral Tablets, Injectable Solutions, Lotions |
| Companies Covered | Regeneron Pharmaceuticals, Sanofi, AbbVie, Pfizer, Eli Lilly and Company, Incyte Corporation, LEO Pharma, Novartis, Galderma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermatitis Drugs Market Strategic Shifts & Innovations
A transition toward precision medicine is reshaping the therapeutic landscape, moving away from broad-spectrum anti-inflammatory agents to targeted treatments that address specific molecular drivers of disease. This evolution is driven by a deeper understanding of dermatitis pathophysiology at a cellular level.
Janus kinase (JAK) inhibitors are a class of oral and topical small molecules that modulate key inflammatory signaling pathways inside the cell. Dermatologists are increasingly prescribing these agents for patients with moderate-to-severe atopic dermatitis who have had an inadequate response to other systemic therapies. This oral or topical administration route is displacing the need for injectable biologics in certain patient cohorts, altering established treatment algorithms.
Regulatory frameworks are evolving to incorporate post-market evidence. The European Medicines Agency's (EMA) increasing emphasis on real-world data requires manufacturers to track long-term drug performance outside of controlled clinical trials. This mandate most directly impacts novel biologics and immunomodulators, forcing companies to invest in patient registries and data analytics to validate safety and efficacy across diverse populations in countries like France and Spain.
Patient expectations for convenience and safety are altering treatment selection criteria. A clear preference is emerging for non-steroidal topical agents and biologics with favorable long-term side effect profiles over the chronic use of potent topical corticosteroids. This behavioral shift is particularly evident in pediatric dermatology and among patients in the United States seeking proactive management strategies that minimize cumulative toxicity.
Dermatitis Drugs Market Segmentation
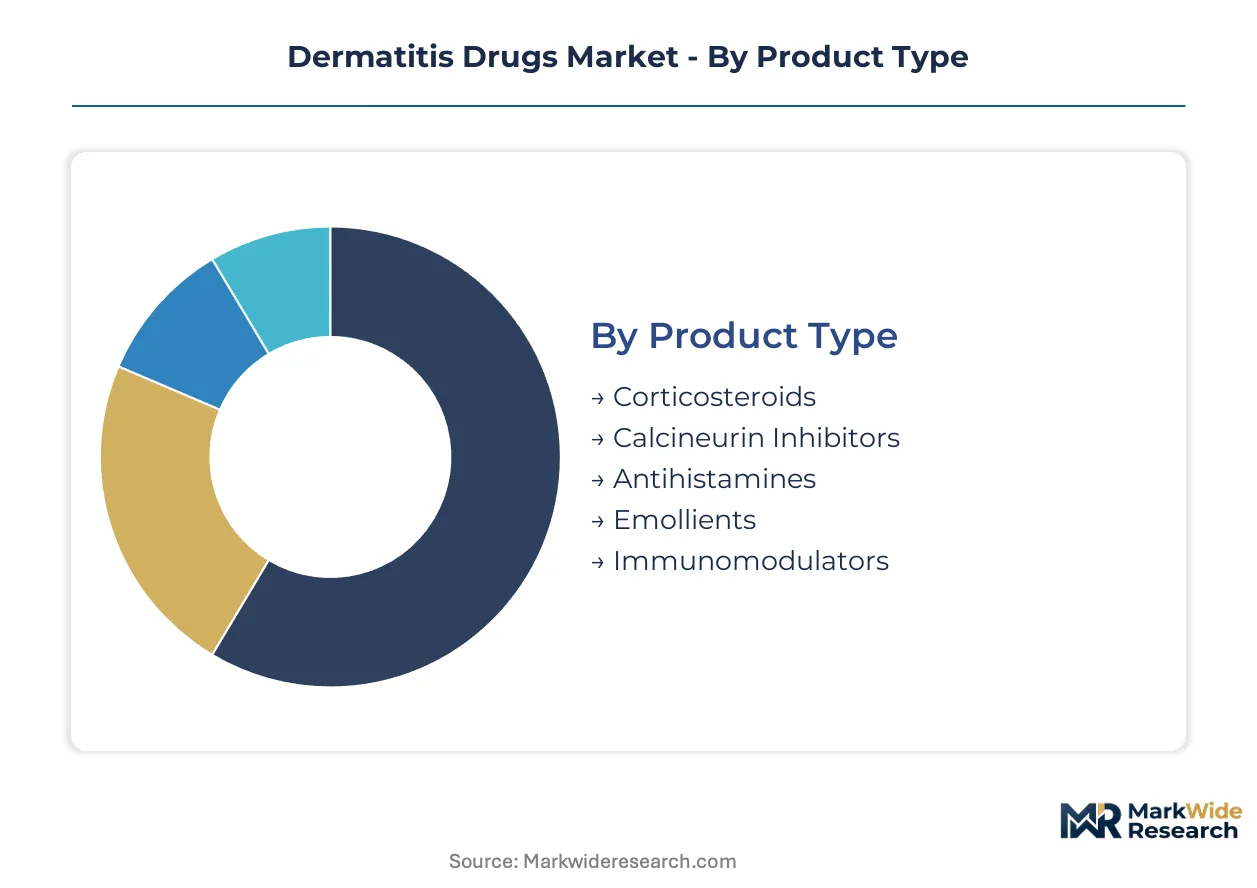
The Dermatitis Drugs Market segments reflect the diverse pathophysiology of inflammatory skin conditions and the varied therapeutic approaches employed for patient management. Understanding these distinct segments is critical for pharmaceutical companies to align product development with specific clinical needs and market demands.
Product Type:
The product type segmentation highlights the ongoing tension between established, broad-spectrum treatments and novel, highly targeted therapies facing direct substitution pressure.
- Immunomodulators:These advanced biologics and small molecules, such as Janus kinase (JAK) inhibitors, modulate specific immune pathways to reduce inflammation in conditions like severe atopic dermatitis. Demand for these high-value therapies is concentrating in specialized dermatology clinics in the United States, driven by superior efficacy and favorable reimbursement policies.
- Corticosteroids:These anti-inflammatory agents, available in various potencies and formulations, remain a cornerstone of dermatitis treatment for their rapid symptom relief. The high-volume segment of topical corticosteroids experiences significant generic competition, particularly for mild-to-moderate cases across global markets.
- Calcineurin Inhibitors:These non-steroidal topical agents suppress immune responses in the skin, offering an alternative for sensitive areas or long-term use in patients with atopic dermatitis.
- Antihistamines:Primarily used to alleviate pruritus associated with dermatitis, these oral medications provide symptomatic relief for various inflammatory skin conditions.
- Emollients:These moisturizing creams and ointments are foundational for restoring skin barrier function and reducing dryness across all types of dermatitis.
Corticosteroids retains volume leadership; Immunomodulators holds the steepest expansion curve.
Application:
The application segments reveal where patient volume and R&D investment are most concentrated across different dermatitis types.
- Atopic Dermatitis:This chronic, immune-mediated inflammatory skin condition affects a large global patient population, particularly in industrialized nations, driving significant demand for both topical and systemic therapies. The increasing incidence in countries like Germany fuels the need for advanced treatments.
- Contact Dermatitis:Characterized by an inflammatory reaction to an allergen or irritant, this common condition requires precise diagnosis and often responds well to topical treatments and allergen avoidance. Effective management often involves patient education in regions with high industrial exposure.
- Seborrheic Dermatitis:This chronic inflammatory condition primarily affects areas rich in sebaceous glands, such as the scalp and face, and is managed with antifungals and topical corticosteroids.
- Nummular Dermatitis:Appearing as coin-shaped lesions, this subtype often requires targeted topical therapies and addresses specific inflammatory pathways.
- Stasis Dermatitis:Associated with venous insufficiency, this condition primarily affects the lower legs and requires treatments that address both inflammation and underlying circulatory issues.
The largest patient cohorts reside within Atopic Dermatitis, while Nummular Dermatitis presents significant unmet needs.
End User:
The end-user segmentation illustrates the varied access points for dermatitis treatments and the evolving care delivery models.
- Dermatology Clinics:These specialized facilities serve as primary points of diagnosis and prescription for a wide range of dermatitis conditions, including initial consultations for biologic therapies in the US.
- Specialty Hospitals:These institutions manage severe and complex cases of dermatitis, often requiring advanced diagnostic capabilities and the administration of injectable immunomodulators across European healthcare systems.
- Pharmacies:Community pharmacies serve as essential access points for over-the-counter and prescription topical medications, facilitating patient adherence to treatment regimens.
- Outpatient Facilities:These settings provide convenient access to dermatological consultations and follow-up care for less severe or chronic dermatitis conditions.
- Home Care Settings:Patients increasingly manage chronic dermatitis conditions at home with prescribed topical treatments and emollients, supported by telehealth services.
Specialty Hospitals drives the majority of high-value prescriptions, as Home Care Settings expands access for routine care.
Delivery Mode:
The delivery mode segmentation highlights the balance between localized and systemic treatment approaches, impacting patient convenience and therapeutic efficacy.
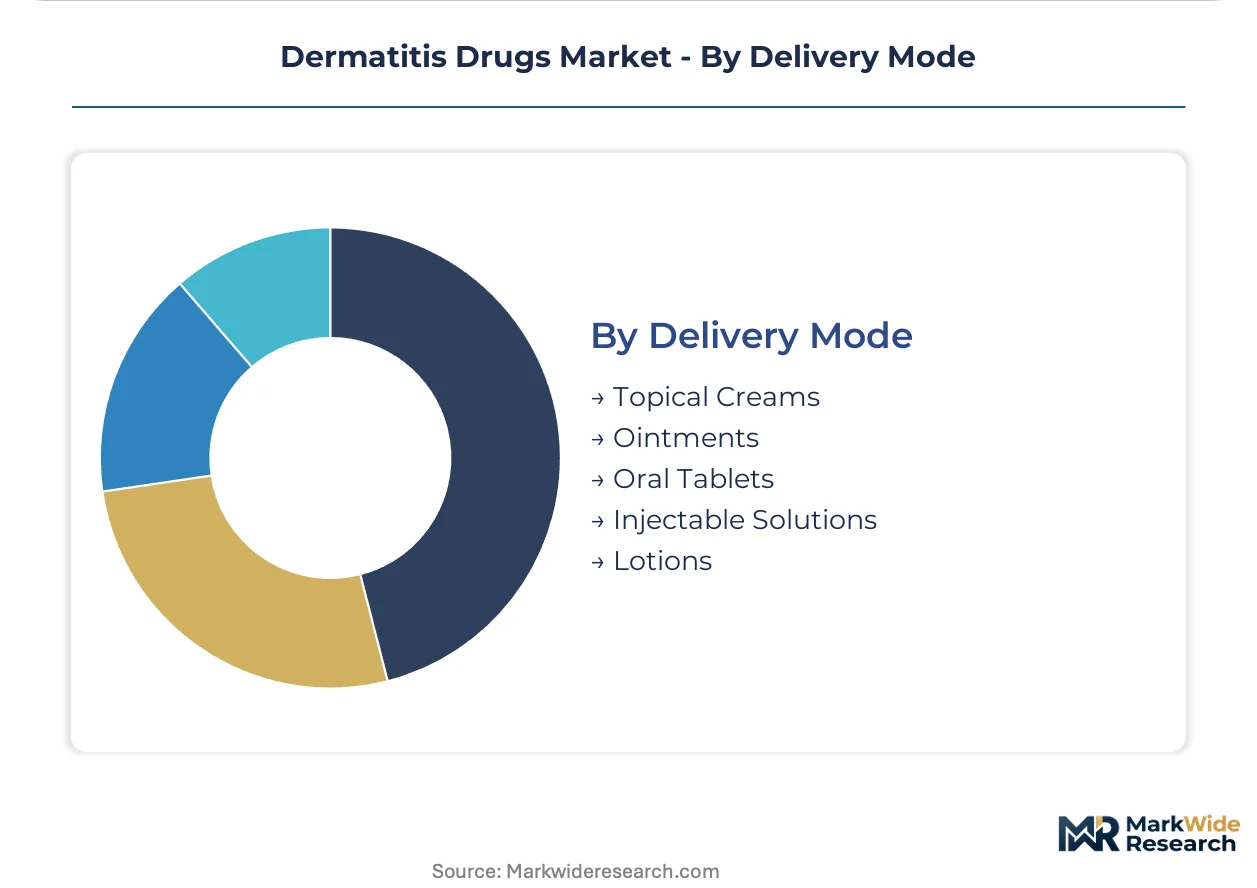
- Injectable Solutions:These formulations, primarily for biologics and immunomodulators, deliver systemic therapy for severe atopic dermatitis, requiring specialized administration and cold chain logistics. These high-cost treatments are gaining share in countries like Japan.
- Topical Creams:Widely used for localized inflammation and symptom relief, these formulations include corticosteroids and calcineurin inhibitors, providing a primary treatment option for mild-to-moderate cases. Their ease of application supports widespread use.
- Oral Tablets:Systemic treatments like JAK inhibitors and antihistamines are administered orally, offering convenience for patients with widespread or severe dermatitis.
- Ointments:These occlusive topical formulations provide intensive moisturization and medication delivery, often preferred for very dry or thickened skin lesions.
- Lotions:Lighter in consistency than creams, lotions are suitable for hairy areas or larger body surface areas, offering a less greasy application.
The shift towards systemic treatments is elevating Injectable Solutions, while Oral Tablets remains fundamental for patient adherence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for dermatitis drugs varies significantly across global regions, reflecting diverse healthcare systems and patient needs. While traditional topical corticosteroids maintain broad usage, demand for high-cost, targeted immunomodulators is concentrating in developed markets. This shift influences R&D priorities and market access strategies for pharmaceutical manufacturers.
United States
High prevalence of atopic dermatitis and favorable reimbursement policies drive substantial demand for advanced biologics. The US FDA's expedited approval pathways for novel therapies encourage pharmaceutical innovation. Biotech clusters in Boston and the San Francisco Bay Area lead the development of next-generation immunomodulators.
Germany
Increasing incidence of atopic dermatitis, coupled with a robust healthcare infrastructure, fuels demand for both established and advanced treatments. The European Medicines Agency (EMA) sets stringent safety and efficacy standards for new drug approvals in the region. Pharmaceutical research hubs in Munich and Frankfurt are active centers for clinical trials and dermatological innovation.
Japan
A notable shift towards systemic treatments, particularly high-cost injectable solutions, is observed for severe dermatitis cases. Japan's PMDA enforces rigorous clinical trial requirements before market authorization. Specialized dermatology clinics in Tokyo and Osaka are primary access points for these advanced therapies.
Brazil
Underpenetrated patient populations represent a significant growth avenue as healthcare infrastructure continues to improve and access to dermatological care broadens. ANVISA, Brazil's health surveillance agency, manages drug approval processes and market access. Expanding specialty hospital networks in São Paulo and Rio de Janeiro facilitate the uptake of new treatments.
India
Broadening access to dermatological care and a large patient base contribute to the market's expansion, particularly for cost-effective generic options. The Central Drugs Standard Control Organization (CDSCO) regulates drug manufacturing and distribution within the country. Pharmaceutical production centers in Hyderabad and Bengaluru are key for both domestic supply and global exports.
Dermatitis Drugs Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure of the dermatitis drugs market. This market exhibits a tiered structure, with large pharmaceutical companies dominating the high-value biologics segment. Strategic archetypes include diversified pharmaceutical giants, specialized dermatology firms, and innovative biotech companies. R&D investment in next-generation immunomodulators and portfolio diversification remain dominant competitive moves.
Within the diversified pharmaceutical giants, Regeneron Pharmaceuticals exemplifies leadership in monoclonal antibody development for atopic dermatitis, driving innovation in targeted therapies. Sanofi occupies a position with a broad portfolio spanning both biologics and established topical treatments, reflecting a comprehensive market approach across various patient needs. LEO Pharma sits within the specialized dermatology firms, focusing on specific topical formulations and niche dermatological segments, thereby carving out distinct market shares.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals |
| Sanofi |
| AbbVie |
| Pfizer |
| Eli Lilly and Company |
| Incyte Corporation |
| LEO Pharma |
| Novartis |
| Galderma |
| Others |
Cost & Logistics Intelligence
Large-scale biologic manufacturing economies of scale concentrate production capabilities among a few pharmaceutical giants. This concentration of advanced production capacity directly influences pricing power and establishes high price floors for novel immunomodulators.
Pricing Analysis
Patient adherence programs and long-term support services drive significant lifetime value for biologic dermatitis drugs. The dominant pricing structure for these advanced therapies is value-based, reflecting superior efficacy and improved quality of life. Price differentiation stems from clinical efficacy data and market access negotiation success in countries like the United States. Pricing pressure stems from payer demands for cost-effectiveness, particularly within Europe's single-payer systems. Specialty hospitals and dermatology clinics are less price-sensitive for biologics, while pharmacies and home care settings prioritize cost-effective generic topical corticosteroids.
Supply Chain Analysis
Cold chain logistics costs for temperature-sensitive injectable biologics present a significant inbound challenge, particularly for global distribution. Pharmaceutical API production concentrates in India, China, and the United States. Raw material dependencies include specialized cell culture media and purified proteins for biologic synthesis. Single-source vulnerability for key active pharmaceutical ingredients represents a structural supply chain risk. Distribution runs through specialized pharmacy networks and hospital procurement systems globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dermatitis drugs market presents a fragmentation opportunity as patient expectations for convenience and safety create distinct therapeutic niches. This demand-side shift supports specialized product development beyond broad-spectrum treatments.
For Market Incumbents: Secure intellectual property for next-generation immunomodulators to counter generic competition in established topical segments. Diversify portfolios into underserved dermatitis subtypes, such as nummular dermatitis, leveraging existing R&D capabilities. The increasing emphasis on real-world data by regulators like the European Medicines Agency (EMA) requires significant investment in post-market surveillance. Strengthen channel control through strategic partnerships with specialty hospitals in the United States.
For New Entrants and Emerging Players: Patient education and adherence support for chronic dermatitis conditions represent a service-layer gap where incumbents under-serve. Target niche dermatological conditions, such as dyshidrotic eczema, with novel topical formulations that offer clear clinical differentiation. The pediatric dermatology segment in the United States offers a penetrable market due to high patient preference for non-steroidal options. A direct-to-consumer digital health platform can facilitate patient access and build brand loyalty.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotech companies specializing in targeted biologics and advanced immunomodulators. Long-term viability over the next 5-10 years hinges on pipeline diversification into novel mechanisms of action for inflammatory skin diseases. Acquisition targets should be innovative small-to-mid-cap firms with promising Phase II/III assets. The signal to watch is successful clinical trial completion for first-in-class therapies addressing unmet needs in severe atopic dermatitis.
| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Diversification | Expanding R&D into niche dermatitis subtypes addresses unmet patient needs and creates new revenue streams. |
| Clinical Trial Advancement | Progressing novel immunomodulators through Phase III trials validates efficacy for regulatory approval by the US FDA. |
| Manufacturing Scale-Up | Increasing production capacity for biologics meets rising demand from specialty hospitals in Germany. |
| Digital Health Platform Launch | Offering patient support and education via digital channels improves adherence for chronic conditions. |
| Strategic Partnership with Payer | Collaborating with private insurers in the United States ensures favorable reimbursement for high-cost therapies. |
Research Approach
Desk research of regulatory filings, clinical trial registries, and medical journals preceded structured interviews with drug development executives, regulatory affairs leads, and hospital procurement managers. This primary research was validated against secondary sources including national health agency reports, pharmaceutical industry associations, and academic publications. Bottom-up data collection from key market participants was triangulated with top-down market sizing approaches. This comprehensive methodology ensures robust data integrity and market understanding.
Variance decomposition analysis informed the quantitative modeling framework across the analysis window. Segmentation dimensions modeled include product type, application, end-user, delivery mode, and regional regulatory clusters. Compound annual growth rates were derived from historical trends and projected future market dynamics. Key industry-specific inputs included disease prevalence rates and drug approval timelines.
Underlying assumptions cover stable regulatory environments and consistent reimbursement policies, with deviation risk concentrated in unforeseen clinical trial failures. Forecasts reflect these documented assumptions, but significant shifts in healthcare policy or new therapeutic breakthroughs could alter market trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Antiandrogens Market
Pharmaceuticals
Levothyroxine Sodium Market
Pharmaceuticals
Blood Clotting Accelerant Market
Pharmaceuticals
Malaysia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Mouth Ulcers Treatment Market
Pharmaceuticals
Contract Pharmaceutical Fermentation Services Market
Pharmaceuticals
Latin America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
North America Adenomyosis Drugs Market
Pharmaceuticals
Buprenorphine and Naloxone Market
Pharmaceuticals
Spain Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Global Diphenhydramine Market
Pharmaceuticals
Acetaminophen Injection Market
Pharmaceuticals
Digital Pharmaceutical Supply Chain Management Market
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market
Pharmaceuticals
Hydroxyzine Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market