
 Energy-Based Therapeutics Market | 2026-2036
Energy-Based Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Energy-Based Therapeutics Market Intelligence
Class III medical device certification is rotating upward as the baseline threshold for commercial viability in energy-based therapeutics. Johnson & Johnson leverages its surgical robotics infrastructure to integrate laser and radiofrequency platforms into hospital workflows. Medtronic sustains technology leadership through deep R&D investment in minimally invasive electromagnetic treatment systems. Boston Scientific Corporation competes aggressively in cardiac ablation, where radiofrequency and cryotherapy convergence defines product strategy.
Energy-based therapeutics employ controlled delivery of laser, radiofrequency, ultrasound, or electromagnetic energy to achieve tissue modification, pain modulation, or cellular regeneration at specified power densities and pulse durations. These modalities serve clinical goals ranging from dermatological resurfacing to deep tissue healing, with device classification depending on energy penetration depth and thermal dose control. Laser therapy occupies the largest revenue pool due to mature reimbursement codes across aesthetic and surgical applications, while ultrasound therapy represents the fastest-expanding segment driven by musculoskeletal rehabilitation demand. Minimally invasive technology captures premium pricing through reduced recovery protocols, whereas non-invasive systems dominate volume in clinic and home care settings where operator certification requirements remain lower.
FDA Class II and Class III device pathways govern market entry timelines and clinical evidence requirements for manufacturers targeting the United States. EMA MDR compliance and CE marking obligations shape European commercialization strategy, particularly for radiofrequency and hybrid systems with novel energy delivery mechanisms. Stakeholders must monitor evolving reimbursement decisions from CMS and national health technology assessment bodies, as coverage determinations for emerging indications will dictate which technology platforms achieve scalable adoption.
Market Dynamics
FDA clearance pathway compression for Class II medical devices is accelerating hospital procurement cycles for radiofrequency and laser platforms, while reimbursement code expansion for non-invasive pain management procedures is redirecting capital toward outpatient clinic deployment.
Growth Catalysts
- CMS reimbursement expansion:New Category III codes for laser-assisted wound healing procedures are unlocking hospital budget allocation for capital equipment purchases across dermatology and surgical departments.
- Electromagnetic therapy maturation:Pulsed electromagnetic field devices are penetrating orthopedic rehabilitation protocols as clinical evidence accumulates for bone fracture acceleration applications.
- Germany aesthetic demand concentration:Private clinic networks in Berlin and Munich are driving radiofrequency device orders for body contouring and skin tightening procedures.
Market Restraints
- High-purity optical fiber cost volatility:Supply constraints for medical-grade silica fibers are compressing margins on diode laser system manufacturing.
- Single-source crystal dependency:Yttrium aluminum garnet crystal production concentrates in three East Asian suppliers, creating vulnerability for solid-state laser manufacturers.
- Deep tissue penetration limitation:Ultrasound energy attenuation in adipose tissue restricts therapeutic efficacy for obesity-related musculoskeletal conditions.
Strategic Opportunities
- Home care channel emergence:Lower-power LED and low-level laser therapy devices are migrating through direct-to-consumer e-commerce platforms for chronic pain self-management.
- EU MDR regulatory tailwind:Stricter clinical evidence requirements for legacy devices are creating replacement demand for next-generation platforms with robust technical documentation.
- Cardiac ablation convergence:Integration of pulsed field ablation with radiofrequency energy delivery is opening electrophysiology catheter upgrade cycles in tertiary hospitals.
Industry Challenges
- Clinical operator certification gaps:Shortage of certified laser safety officers is delaying device commissioning timelines in ambulatory surgery centers.
- FDA 510(k) predicate device erosion:Substantial equivalence pathway narrowing for novel wavelength configurations is extending premarket notification preparation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy-Based Therapeutics Market |
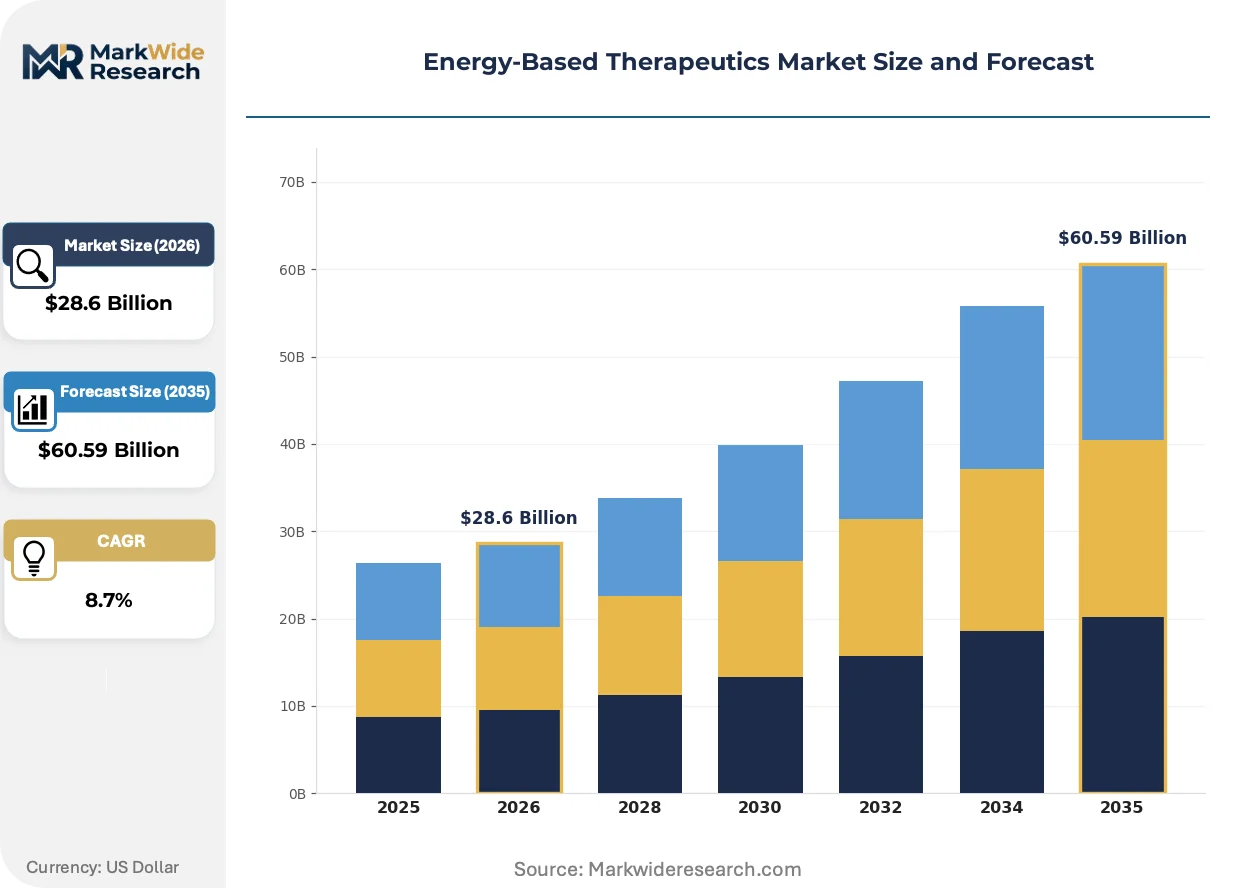
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Therapy, Radiofrequency Treatment, Ultrasound Therapy, Electromagnetic Treatment Application: Pain Management, Wound Healing, Tissue Regeneration, Aesthetic Procedures End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Technology: Non-invasive, Minimally Invasive, Invasive, Hybrid Systems |
| Companies Covered | Johnson & Johnson, Medtronic, Boston Scientific Corporation, Abbott Laboratories, Lumenis, Stryker Corporation, Hologic, Cynosure, AngioDynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy-Based Therapeutics Market Strategic Shifts & Innovations
Device form factor reduction and energy delivery precision are converging to expand point-of-care deployment beyond traditional hospital settings, with software-defined treatment protocols displacing hardware-centric platform architectures.
Portable diode laser systems for veterinary and sports medicine applications are miniaturizing through fiber-coupled microchip laser integration, enabling field-deployable pain management. Equine therapy clinics and professional sports team medical staffs are adopting these platforms for acute injury intervention. The technology is miniaturizing capital requirements and expanding addressable settings beyond fixed-installation surgical suites.
EU MDR Article 10 post-market clinical follow-up obligations are mandating systematic device registry participation for radiofrequency ablation systems, forcing manufacturers to build prospective data collection infrastructure. This surveillance framework is elevating evidence generation costs while differentiating compliant suppliers from legacy device holders. German notified bodies are processing technical documentation reviews with extended timelines, compressing commercialization schedules for hybrid energy platforms.
Hospital procurement committees are unbundling capital equipment acquisitions from mandatory service contracts, shifting toward time-and-materials maintenance arrangements or third-party servicing. This disintermediation pressures original equipment manufacturer recurring revenue streams while opening independent service organization market entry. The pattern is most visible in United States health system consolidation, where centralized supply chain functions negotiate stripped-down warranty terms.
Energy-Based Therapeutics Market Segmentation
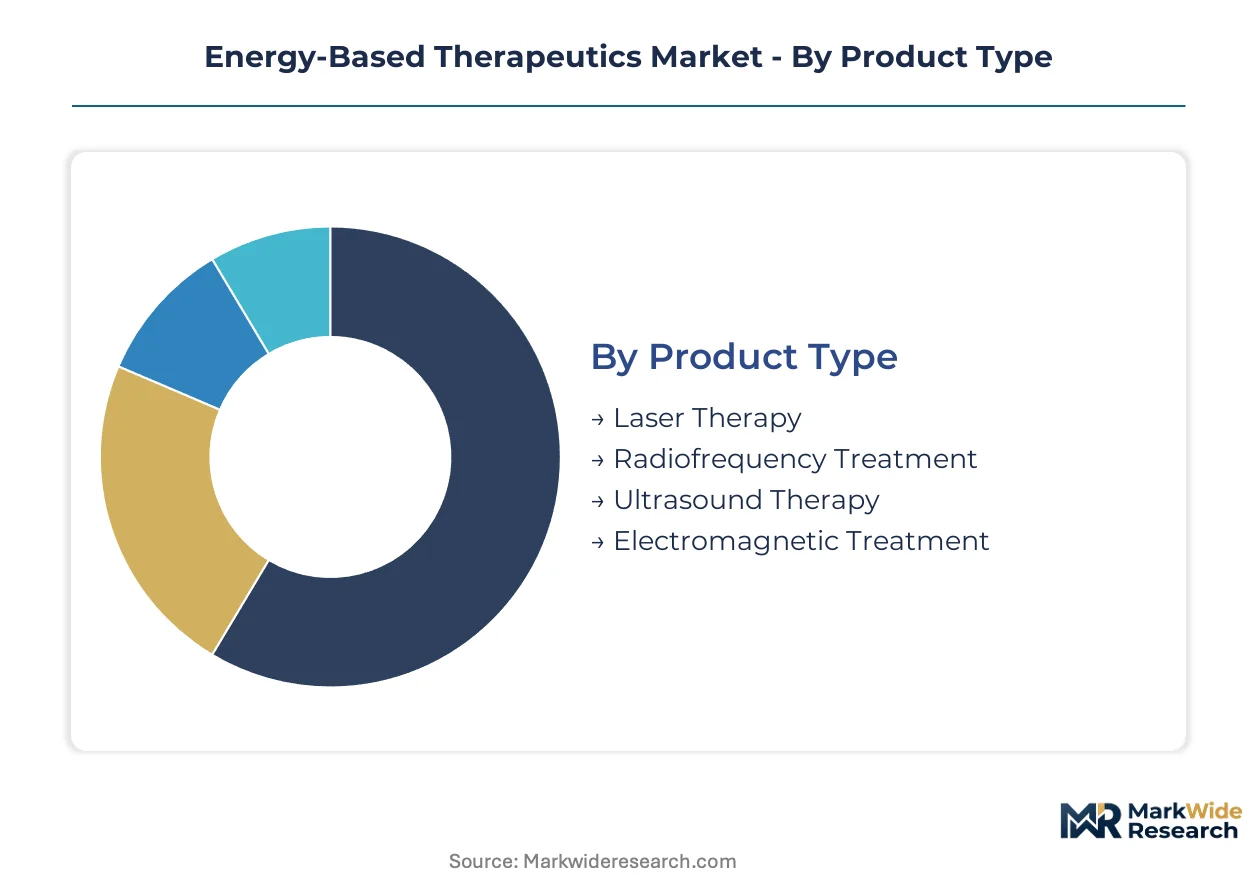
Device classification thresholds and reimbursement eligibility vary sharply across energy modalities, creating divergent commercialization timelines for manufacturers. Segmentation reveals where regulatory burden concentrates versus where clinical evidence requirements remain lighter.
Product Type:
FDA Class II versus Class III pathways split manufacturing economics across laser, radiofrequency, ultrasound, and electromagnetic platforms.
- Laser Therapy:Solid-state and diode configurations dominate hospital capital budgets through established CPT reimbursement codes for surgical and dermatological applications. Mature optical fiber supply chains and predicate device availability compress 510(k) preparation cycles for wavelength iterations within existing therapeutic windows.
- Radiofrequency Treatment:Thermal and pulsed delivery modes capture premium pricing in cardiac ablation and aesthetic body contouring where temperature monitoring requirements trigger Class III PMA pathways. German private clinic networks in Berlin and Munich concentrate orders for multipolar skin tightening systems.
- Ultrasound Therapy:Focused and unfocused transducer arrays penetrate musculoskeletal rehabilitation protocols with lighter regulatory burden than thermal ablation modalities.
- Electromagnetic Treatment:Pulsed field devices for bone fracture acceleration accumulate clinical evidence under orthopedic surgeon supervision in United States hospital systems.
Established volume favors laser platforms; emerging adoption favors electromagnetic systems.
Application:
Reimbursement code density determines addressable market size more than clinical efficacy alone.
- Pain Management:Non-invasive laser and ultrasound modalities expand through CMS Category III code assignments for chronic lower back and neuropathic conditions. Outpatient clinic deployment accelerates where operator certification requirements stay below surgical thresholds.
- Wound Healing:Photobiomodulation protocols for diabetic foot ulcers attract hospital wound care center investment through Medicare coverage determinations. United States health system consolidation concentrates procurement through centralized supply chain functions negotiating stripped-down service contracts.
- Tissue Regeneration:Electromagnetic field applications in orthopedic healing remain investigational outside established bone fracture indications.
- Aesthetic Procedures:Radiofrequency body contouring and skin tightening drive private pay revenue streams insulated from reimbursement volatility.
Reimbursement-dependent segments concentrate in hospital systems; cash-pay aesthetics expand fastest through clinic networks.
End User:
Capital intensity and regulatory oversight scale inversely with care setting migration.
- Hospitals:Tertiary cardiac centers in the United States deploy hybrid ablation platforms combining radiofrequency and pulsed field energy under electrophysiology catheter upgrade cycles. FDA Class III PMA requirements and service contract unbundling reshape procurement committee negotiations.
- Clinics:Dermatology and pain management practices in Germany drive radiofrequency device orders where MDR technical documentation timelines compress commercialization schedules for hybrid energy platforms.
- Home Care:Lower-power LED and low-level laser therapy devices migrate through direct-to-consumer channels for chronic pain self-management.
- Rehabilitation Centers:Ultrasound and electromagnetic modalities penetrate orthopedic protocols under physical therapist supervision.
Acute intervention concentrates in hospitals; chronic condition management shifts toward home settings.
Technology:
Penetration depth and thermal dose control determine classification tier and clinical evidence burden.
- Non-invasive:Surface energy delivery without skin breach dominates clinic and home care volumes where laser safety officer certification shortages delay commissioning in ambulatory surgery centers.
- Minimally Invasive:Catheter-based and percutaneous approaches capture premium pricing through reduced recovery protocols in United States hospital systems.
- Invasive:Surgical laser and radiofrequency integration into open procedures retains niche application in oncology and ophthalmology.
- Hybrid Systems:Convergence of pulsed field ablation with radiofrequency energy delivery opens electrophysiology upgrade cycles requiring systematic device registry participation under EU MDR Article 10 obligations.
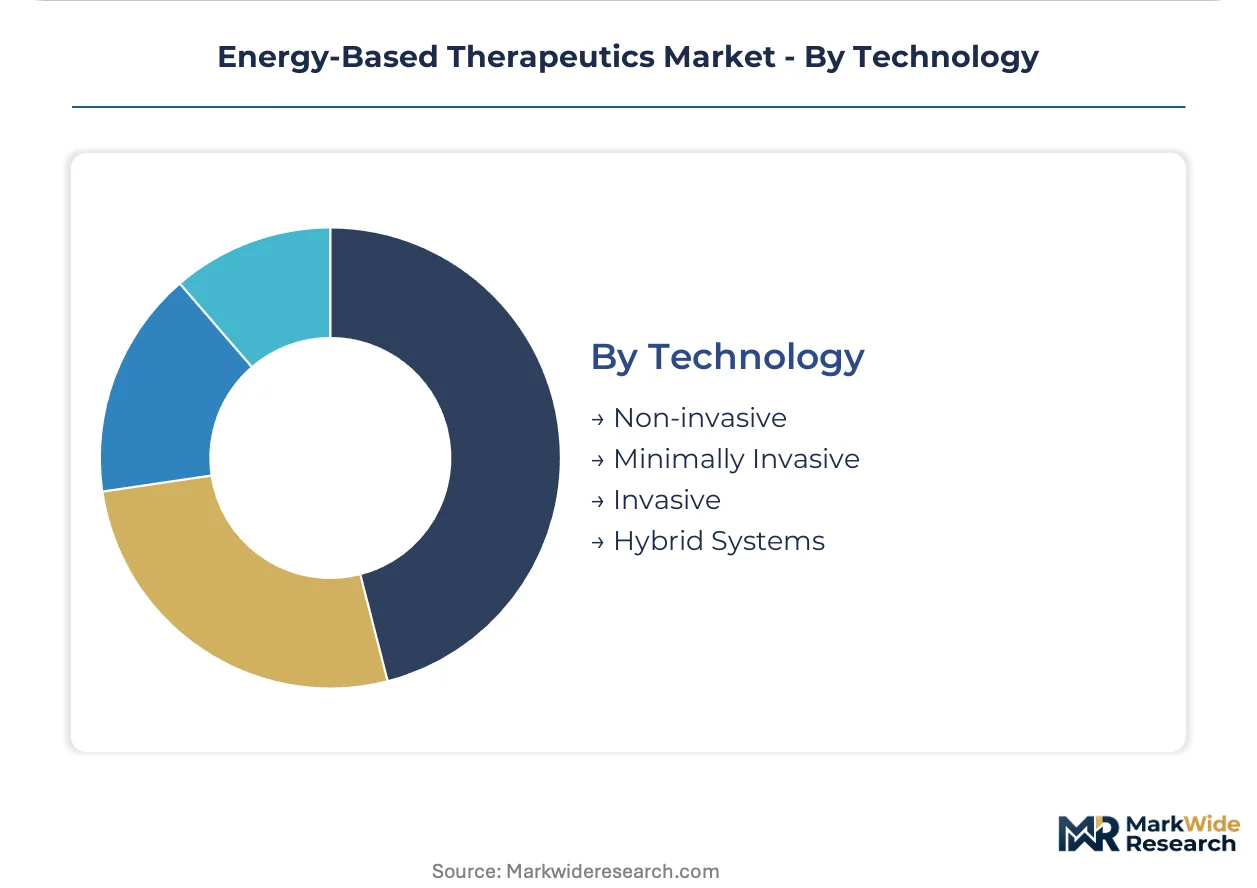
Non-invasive platforms dominate unit volumes; hybrid configurations command highest average selling prices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export radiofrequency and laser platforms to United States hospital systems, while East Asian suppliers dominate optical component supply chains serving device assembly operations across multiple buyer geographies.
United States
Tertiary cardiac centers in Cleveland and Houston deploy hybrid ablation catheters combining radiofrequency with pulsed field energy. FDA PMA pathway compression for Class III devices accelerates electrophysiology upgrade cycles. CMS reimbursement expansion for laser-assisted wound healing concentrates procurement authority through consolidated health system supply chains in Texas and Ohio.
Germany
Private clinic networks in Berlin and Munich drive concentrated orders for multipolar radiofrequency body contouring systems. EMA MDR Article 10 post-market surveillance obligations mandate systematic device registry participation for ablation manufacturers. Baden-Württemberg precision engineering clusters supply temperature monitoring subassemblies to Class III device assemblers.
Japan
PMDA streamlined review pathways for regenerative medical devices accelerate electromagnetic bone fracture healing platform approvals. METI funding for minimally invasive surgical technology redirects R&D investment toward catheter-based energy delivery. Osaka-based medical device trading houses facilitate Korean and Chinese manufacturer market entry.
China
NMPA innovation device approval channels shorten time-to-market for domestic diode laser manufacturers targeting dermatology clinics. SAMR pricing surveillance on imported radiofrequency systems pressures multinational premium positioning. Yangtze River Delta contract manufacturers scale optical fiber coupling capacity for export-oriented device assembly.
India
CDSCO medical device rules harmonization with IMDRF standards attracts Korean and German manufacturers seeking alternate assembly locations to East Asian supply chains. PLI scheme incentives for high-value medical electronics concentrate diode laser module production in Gujarat and Karnataka. Mumbai specialty hospitals pilot ultrasound therapy protocols for diabetic foot complications.
Energy-Based Therapeutics Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and regulatory certification depth. The vendor base stratifies into three tiers: diversified health technology conglomerates with surgical robotics infrastructure, pure-play energy device specialists with focused R&D pipelines, and regional contract manufacturers with component-level expertise. Dominant competitive moves include M&A to capture electrophysiology catheter technology and strategic partnerships to secure optical fiber supply.
Among diversified health technology conglomerates, Johnson & Johnson, Medtronic, and Boston Scientific Corporation exemplify the integrated platform archetype. Johnson & Johnson occupies a position leveraging surgical robotics infrastructure to embed laser and radiofrequency systems into hospital workflows. Medtronic anchors technology leadership through sustained investment in minimally invasive electromagnetic treatment architectures. Boston Scientific sits within the cardiac ablation specialization tier where radiofrequency and cryotherapy convergence shapes product portfolio composition.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Medtronic |
| Boston Scientific Corporation |
| Abbott Laboratories |
| Lumenis |
| Stryker Corporation |
| Hologic |
| Cynosure |
| AngioDynamics |
| Others |
Cost & Logistics Intelligence
FDA Class III PMA certification gates both supplier qualification and price tier separation in energy-based therapeutics, with manufacturers bearing clinical evidence costs that filter through to hospital procurement committees as premium positioning or stripped-down service unbundling.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations through service contract unbundling, shifting toward time-and-materials arrangements. Three-tier pricing structure across premium, standard, and economy levels separates hybrid ablation platforms with systematic registry participation from legacy radiofrequency systems and entry-level diode lasers. Cost compression in Class II laser manufacturing is intensifying because optical fiber supply constraints compress margins. Ambulatory surgery centers exhibit highest price sensitivity due to capital intensity limits, while tertiary cardiac centers in Cleveland and Houston demonstrate lowest sensitivity for electrophysiology catheter upgrade cycles.
Supply Chain Analysis
Extended lead times for Yttrium aluminum garnet crystals and medical-grade silica fibers are stretching device assembly schedules across German and United States manufacturing facilities. Supply concentrates in China, South Korea, and Japan for optical component fabrication, with Baden-Württemberg precision engineering clusters supplying temperature monitoring subassemblies. Raw material dependencies center on high-purity optical fibers, solid-state laser crystals, and electromagnetic field generation coils. Single-source crystal vulnerability creates structural risk for solid-state laser manufacturers. Distribution runs through hospital procurement committees in consolidated United States health systems and private clinic networks in Berlin and Munich.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified laser safety officer scarcity constrains device commissioning velocity, creating a bottleneck that separates manufacturers with training infrastructure from competitors facing delayed revenue recognition.
For Market Incumbents: Fortify control over optical fiber supply through backward integration or long-term offtake agreements with East Asian suppliers. Expand captive training academy capacity to address certified laser safety officer shortages delaying ambulatory surgery center commissioning. Electromagnetic therapy specialists represent an emerging entrant threat in orthopedic rehabilitation protocols. For New Entrants and Emerging Players: Differentiate on software-defined treatment protocols that displace hardware-centric architectures in outpatient pain management clinics. Target home care channels for lower-power LED and low-level laser therapy devices where regulatory burden stays below clinical thresholds. Pursue direct-to-consumer e-commerce distribution with chronic pain self-management positioning. For Investors and Strategic Acquirers: EU MDR Article 10 post-market surveillance obligations reshape the acquisition landscape toward manufacturers with robust technical documentation and prospective data collection infrastructure. Long-term viability favors electrophysiology catheter technology holders with pulsed field ablation integration capability. Watch FDA 510(k) predicate device erosion as an inflection signal extending premarket notification preparation cycles for novel wavelength configurations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA PMA Pathway Navigation | Class III certification unlocks premium pricing in cardiac ablation where temperature monitoring requirements apply. |
| Optical Fiber Supply Agreement | Long-term offtake with East Asian suppliers defends margin position against medical-grade silica cost volatility. |
| Hospital System Partnership | Direct relationships with Cleveland and Houston tertiary centers secure electrophysiology catheter upgrade cycles. |
| Software Companion Development | Software-defined protocols displace hardware-centric architectures in outpatient clinic deployment. |
| Reimbursement Strategy | CMS Category III code capture redirects capital toward laser-assisted wound healing equipment purchases. |
Research Approach
A standing panel of electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) and PMA filings, CMS reimbursement determinations, hospital procurement databases, and EMA MDR technical documentation reviews. Bottom-up device shipment modeling and top-down healthcare capital expenditure triangulation anchored value estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include energy modality, device classification tier, application indication, end-user setting, and geographic regulatory cluster. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns and clinical evidence accumulation timelines. Forecast inputs incorporated pulsed electromagnetic field clinical trial readouts and EU MDR notified body processing timeline extensions.
Material uncertainties — reimbursement coverage reversals, optical fiber supply disruptions, and predicate device pathway narrowing — sit outside the modeled envelope. Forecasts reflect assumptions about clinical evidence accumulation and regulatory clearance velocity. Revision becomes warranted when FDA 510(k) substantial equivalence determination rates for novel wavelength configurations cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Global Thyroid Cancer Drugs Market
Pharmaceuticals
PD-1/PD-L1 Inhibitor Market
Pharmaceuticals
Quinolones Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
Mail Order Pharmacy Market
Pharmaceuticals
Nefopam Hydrochloride Injection Market
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Anti-Infective Vaccines Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Global Genitourinary Drugs Market
Pharmaceuticals
Short-Acting Insulin Market
Pharmaceuticals
Croatia Pharmaceutical Market
Pharmaceuticals
Veterinary Active Pharmaceutical Ingredients Manufacturing Market
Pharmaceuticals
Diphtheria Tetanus Pertussis Vaccine Market