
 Cough Suppressant Drugs Market | 2026-2036
Cough Suppressant Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Cough Suppressant Drugs Market Analysis
Good Manufacturing Practice certification for active pharmaceutical ingredients is collapsing the supplier base for dextromethorphan and codeine raw materials. Pfizer Inc. leverages captive API production to secure supply continuity for its branded suppressant portfolio. GSK plc anchors its competitive position through dominance in multi-symptom cold and flu combinations that bundle suppressants with expectorants. Sanofi competes via pharmacy-led distribution networks across European markets where pharmacist counsel shapes purchase decisions.
Cough suppressant drugs function as centrally acting antitussives that inhibit the medullary cough center through NMDA receptor antagonism or peripheral vagal afferent numbing, with dextromethorphan requiring hepatic CYP2D6 metabolism to its active metabolite dextrorphan for efficacy. These agents serve primarily to reduce nonproductive cough frequency in upper respiratory infections, chronic bronchitis, and post-viral syndromes where sleep preservation and quality of life justify pharmacologic intervention. Dextromethorphan formulations command the largest revenue pool due to OTC accessibility and favorable safety profiles across age groups, while benzonatate capsules represent the fastest-expanding prescription segment as physicians avoid controlled-substance scheduling. Oral delivery mode sustains absolute volume leadership, though sublingual formats gain traction in pediatric and dysphagic populations seeking rapid onset without swallowing difficulty.
FDA scheduling oversight for codeine-containing products and EMA pediatric contraindications reshape prescription patterns toward non-narcotic alternatives. The US Controlled Substances Act and DEA manufacturing quotas constrain codeine syrup supply, pushing formulary preference to dextromethorphan and benzonatate. Stakeholders must monitor evolving pharmacovigilance signals and regional scheduling decisions to align R&D pipelines with accessible, compliant therapeutic options.
Market Dynamics
FDA and EMA restrictions on codeine-containing pediatric products are forcing wholesale reformulation toward non-narcotic alternatives, collapsing legacy supply chains and redistributing market power toward dextromethorphan and benzonatate producers.
Growth Catalysts
- Pediatric OTC expansion:Retail pharmacy chains in the United States and Germany are broadening shelf access for dextromethorphan-based pediatric syrups as pharmacist counsel replaces physician gatekeeping for mild respiratory symptoms.
- REACH compliance restructuring:European API manufacturers investing in green chemistry pathways for dextromethorphan synthesis are capturing preferential supply contracts from formulation houses seeking reduced regulatory exposure.
- Geriatric dysphagia demand:Sublingual and orally disintegrating tablet formats are penetrating nursing home and long-term care channels in Japan where swallowing difficulty affects medication adherence.
Market Restraints
- API supply concentration:Good Manufacturing Practice certification failures have reduced qualified dextromethorphan precursor suppliers to a handful of Chinese and Indian facilities, creating single-source vulnerability.
- Hepatic metabolism variability:CYP2D6 polymorphism causes therapeutic failure in poor metabolizers, limiting dextromethorphan efficacy consistency and driving physician preference for benzonatate despite higher cost.
- DEA quota constraints:US Controlled Substances Act manufacturing limits on codeine continue to compress syrup availability, forcing inventory allocation decisions that disadvantage smaller regional distributors.
Strategic Opportunities
- Underpenetrated Southeast Asian pharmacy modernization:Indonesia and Vietnam retail chains are adopting self-service cough-cold sections where Western OTC suppressant formats remain nascent.
- Combination therapy bundling:Fixed-dose pairings of dextromethorphan with antihistamines or decongestants are capturing multi-symptom purchasing occasions previously served by separate transactions.
- Digital therapeutics integration:Smartphone-based cough monitoring apps paired with suppressant dosing algorithms are creating adherence-linked subscription models in German and Japanese insured populations.
Industry Challenges
- Analytical method transfer complexity:Migrating dextromethorphan purity testing from HPLC to UHPLC platforms requires revalidation across multiple QC laboratories, delaying batch release timelines.
- Pharmacovigilance signal management:Emerging case reports linking high-dose dextromethorphan to serotonin syndrome in antidepressant co-users demand proactive risk mitigation dossier updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cough Suppressant Drugs Market |
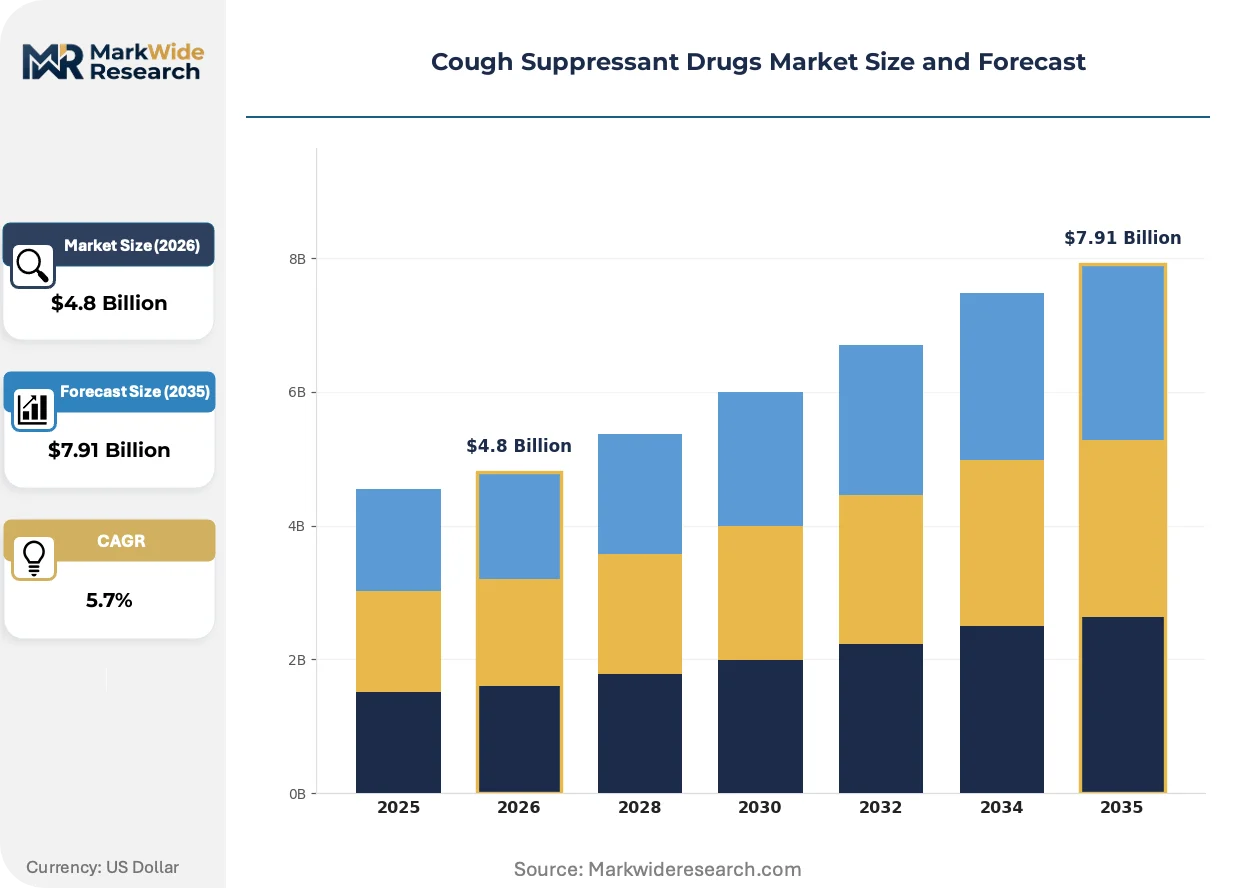
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dextromethorphan, Benzonatate, Codeine, Diphenhydramine Delivery Mode: Oral, Injectable, Inhalation, Sublingual End User: Hospitals, Retail Pharmacies, Clinics, Homecare Formulation: Tablet, Syrup, Capsule, Solution |
| Companies Covered | Pfizer Inc., Johnson & Johnson Services, Inc., GSK plc, Sanofi, Reckitt, Novartis AG, Teva Pharmaceutical Industries Ltd., Bayer AG, Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cough Suppressant Drugs Market Emerging Trajectories
Formulation science and distribution digitization are converging to reshape how cough suppressants reach patients, with regulatory chemistry driving API sourcing decisions and patient-facing technology altering adherence patterns.
Sustained-release polymer matrix technology for dextromethorphan is displacing immediate-release syrups in chronic bronchitis management. Pulmonologists in US academic medical centers are adopting these 12-hour formulations to reduce nocturnal dosing interruptions. The technology is displacing traditional four-times-daily regimens and compressing pharmacy refill frequency while improving sleep quality metrics in patient-reported outcomes.
EMA's pediatric investigation plan requirements for new cough-cold indications are mandating age-stratified efficacy trials that add 18-24 months to development timelines. Formulators are responding by repositioning existing approved actives into novel delivery formats rather than pursuing new molecular entities. Benzonatate capsule manufacturers are capturing the resulting development gap as physicians seek prescription alternatives with established adult safety profiles.
Pharmacy benefit managers in the United States are implementing step-therapy protocols that require documented dextromethorphan failure before authorizing benzonatate reimbursement. This utilization management is compressing brand prescription volume and redirecting patient flow toward preferred generic dextromethorphan products in managed Medicaid populations. Independent pharmacies in Texas and Florida are responding with cash-pay benzonatate pricing to retain physician-directed prescription traffic.
Cough Suppressant Drugs Market Segmentation
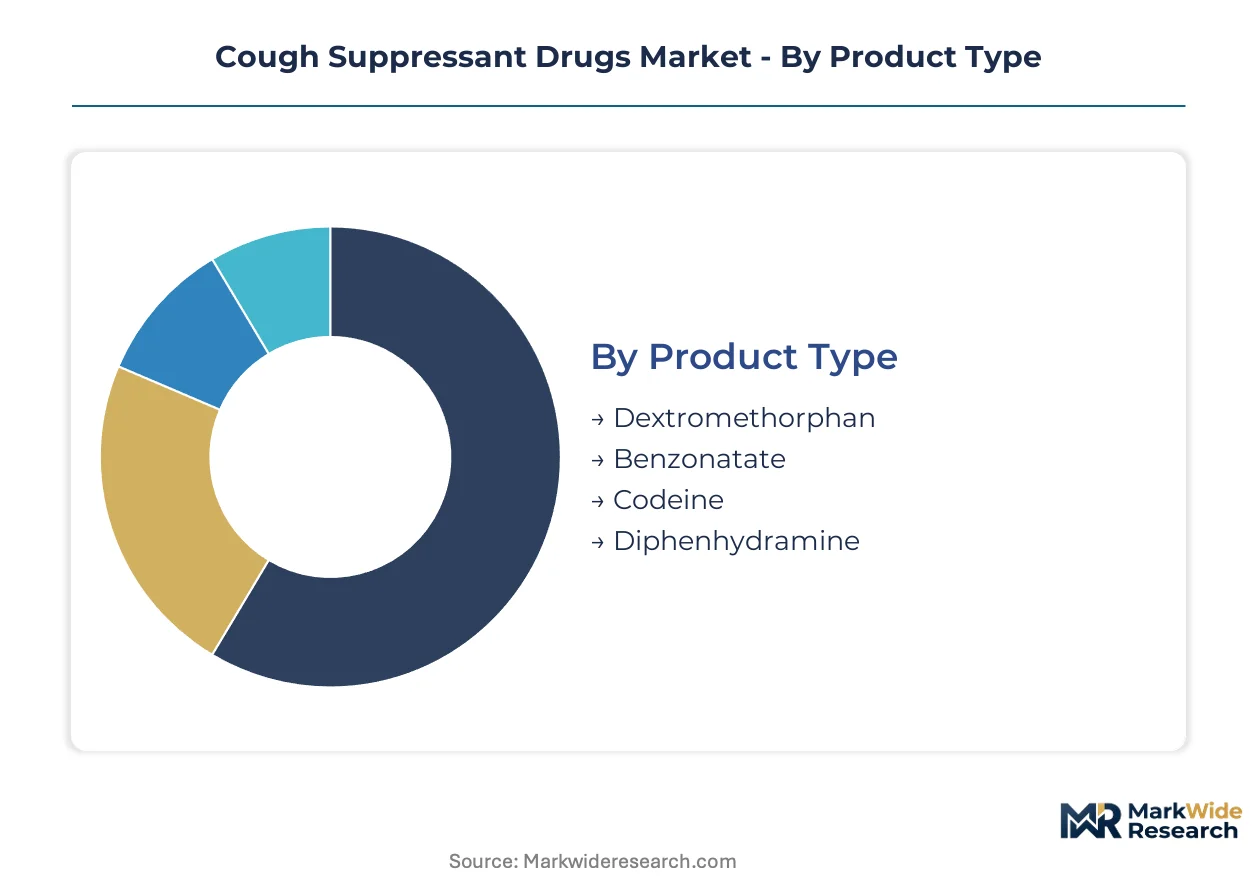
Segmentation in cough suppressants reveals divergent margin structures across formulation complexity and regulatory exposure. Product type stratification shows narcotic versus non-narcotic chemistry driving fundamentally different pricing power and channel access.
Product Type:
Margin pools concentrate in prescription-only segments where controlled-substance scheduling creates supply scarcity and pricing leverage.
- Dextromethorphan:The NMDA receptor antagonist requires hepatic CYP2D6 metabolism to dextrorphan for antitussive effect. Demand concentrates in United States retail pharmacy chains where OTC accessibility and favorable pediatric safety profiles sustain volume leadership against prescription alternatives.
- Benzonatate:Peripheral vagal afferent numbing via sodium channel blockade in bronchial tissues delivers prescription-grade efficacy without controlled-substance scheduling. Physician prescribing in Texas and Florida is rotating toward this segment as DEA quotas constrain codeine syrup availability and formulary managers implement step-therapy requirements.
- Codeine:Opioid-class centrally acting suppressant facing FDA pediatric restrictions and EMA contraindications for children under 12.
- Diphenhydramine:First-generation antihistamine with incidental antitussive properties bundled in multi-symptom cold formulations.
Dextromethorphan holds installed capacity across API synthesis and finished dose manufacturing. Benzonatate is rotating up the share rankings as clinicians seek non-scheduled prescription alternatives.
Delivery Mode:
Volume distribution reflects patient population swallowing capability and onset urgency requirements across care settings.
- Oral:Dominant delivery route encompassing syrups, tablets, and capsules with established bioequivalence pathways. Geriatric nursing facilities in Japan are adopting this mode for chronic bronchitis management where medication adherence programs support scheduled dosing.
- Sublingual:Orally disintegrating formats bypass hepatic first-pass metabolism for rapid systemic absorption. Dysphagic populations in German long-term care channels are driving adoption of this delivery mode where swallowing difficulty previously compromised treatment initiation.
- Injectable:Reserved for perioperative and intensive care settings where oral route contraindicated.
- Inhalation:Localized delivery targeting bronchial receptors with limited systemic exposure.
Oral delivery commands manufacturing scale economies across multi-product filling lines. Sublingual formats are gaining share fastest in pediatric and geriatric specialty channels.
End User:
Channel economics diverge sharply between institutional procurement and consumer self-selection environments.
- Retail Pharmacies:Primary volume channel where pharmacist counsel substitutes for physician gatekeeping in mild respiratory symptom management. United States chain pharmacies are expanding self-service cough-cold sections to capture multi-symptom purchasing occasions.
- Hospitals:Acute care settings prioritizing parenteral formulations and combination therapies for postoperative and infectious disease management.
- Clinics:Outpatient prescribing concentrated in urgent care and pulmonology practices seeking rapid symptom control.
- Homecare:Post-acute and hospice channels emphasizing caregiver-administered dosing and adherence packaging.
Retail pharmacies hold patient touchpoint density. Hospital formulary positioning is rotating up the influence rankings as integrated delivery networks consolidate purchasing.
Formulation:
Manufacturing complexity and stability requirements create tiered margin structures across solid and liquid dosage forms.
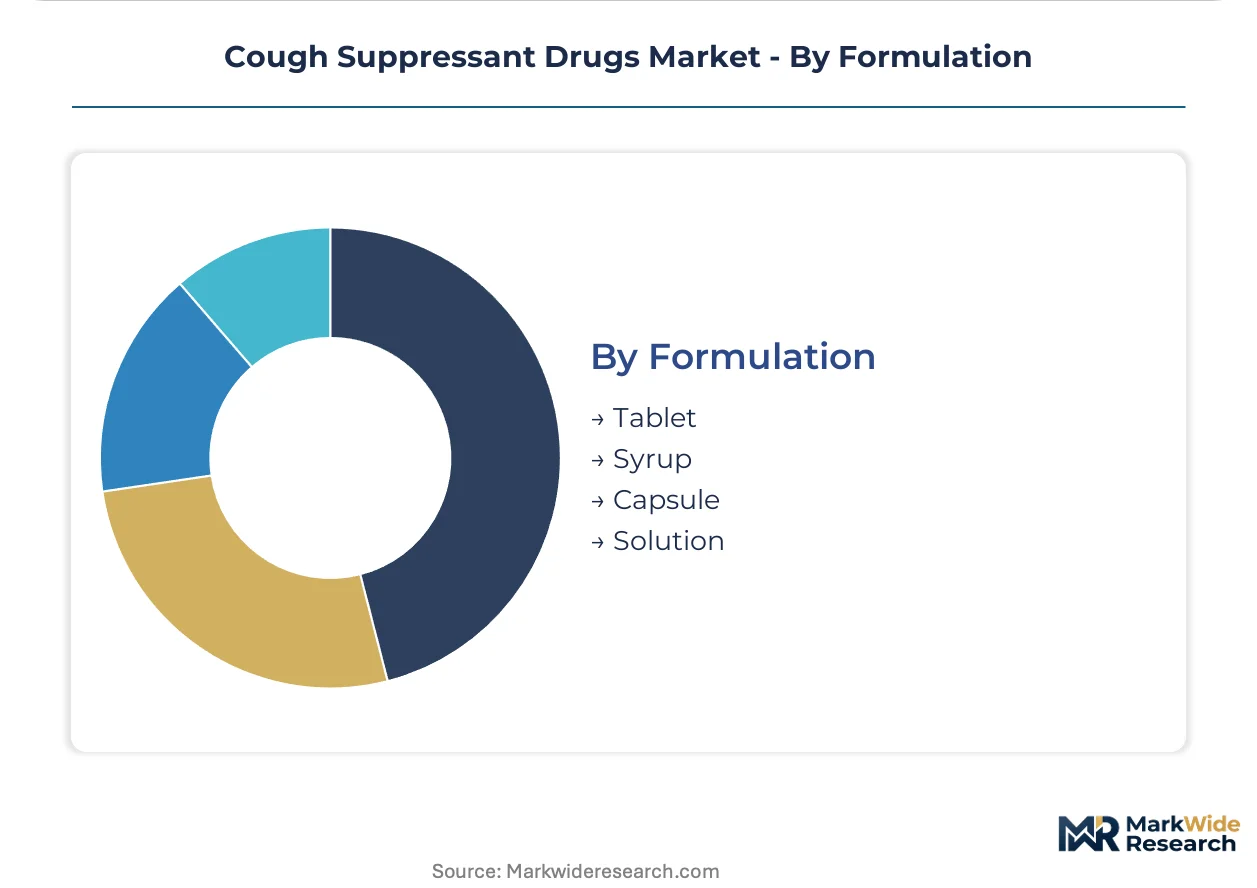
- Syrup:Liquid formulations dominating pediatric segments where dose titration by weight and palatability determine compliance. German pharmacy chains are maintaining syrup shelf space despite higher logistics costs versus solid doses.
- Capsule:Hard-shell gelatin and soft-gel formats for benzonatate and dextromethorphan extended-release matrices. United States specialty pharmacies are capturing capsule dispensing volume as physicians avoid controlled-substance documentation requirements.
- Tablet:Compressed solid dose with coating technologies for taste masking and moisture protection.
- Solution:Ready-to-use liquid formats for institutional bulk dispensing and enteral administration.
Syrup maintains installed capacity across multi-product liquid manufacturing suites. Capsule formats are climbing the fastest in prescription volume as tablet formulations face generic commoditization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pediatric restrictions on codeine and EMA contraindications are redirecting formulation investment toward non-narcotic alternatives across major pharmaceutical markets. Retail pharmacy expansion and self-medication cultures sustain volume concentration in developed economies while Southeast Asian pharmacy modernization opens new channel opportunities.
United States
Seasonal respiratory illness burdens and pharmacist-led counsel drive dextromethorphan volume through retail chains. DEA manufacturing quotas under the Controlled Substances Act compress codeine syrup availability, forcing formulary preference shifts. Texas and Florida specialty pharmacies capture benzonatate dispensing volume as physicians avoid controlled-substance documentation requirements.
Germany
Pharmacy-led distribution networks anchor suppressant access where pharmacist counsel shapes purchase decisions for mild respiratory symptoms. REACH compliance investments in green chemistry API synthesis are capturing preferential supply contracts from formulation houses. Berlin and Munich pharmacy chains maintain syrup shelf space despite higher logistics costs versus solid doses.
Japan
Geriatric dysphagia prevalence in nursing home and long-term care channels drives sublingual and orally disintegrating tablet adoption. METI standards guide manufacturing quality while smartphone-based cough monitoring apps create adherence-linked subscription models in insured populations. Tokyo and Osaka academic medical centers adopt sustained-release polymer matrix formulations for chronic bronchitis management.
United Kingdom
Self-medication culture and OTC accessibility sustain dextromethorphan volume leadership against prescription alternatives. MHRA pediatric guidance aligns with EMA contraindications for codeine-containing products in children under 12. London and Manchester retail chains are expanding self-service cough-cold sections to capture multi-symptom purchasing occasions.
Indonesia
Retail pharmacy modernization is adopting self-service cough-cold sections where Western OTC suppressant formats remain nascent. The national pharmaceutical regulator is harmonizing import standards with ASEAN common technical dossier requirements. Jakarta and Surabaya pharmacy chains represent the primary expansion targets for dextromethorphan-based pediatric syrup formats.
Cough Suppressant Drugs Market Vendor Landscape
Player mix skews toward diversified pharmaceutical conglomerates with captive API production and branded OTC portfolios. Market structure concentrates revenue among five to seven entities with vertically integrated supply chains and multi-symptom combination franchises. Two strategic archetypes dominate: conglomerates leveraging backward integration into active pharmaceutical ingredient synthesis, and consumer health specialists optimizing pharmacy channel relationships. Competitive moves center on portfolio diversification into non-narcotic alternatives and geographic expansion through pharmacy-led distribution networks in European and Southeast Asian markets.
Among diversified pharmaceutical conglomerates, Pfizer Inc., GSK plc, and Sanofi exemplify distinct strategic positioning within the suppressant landscape. Pfizer anchors the API-integrated archetype through captive production securing supply continuity. GSK occupies the multi-symptom bundling position where cold and flu combinations dominate shelf presence. Sanofi represents the pharmacy-channel specialization archetype with European network density. Johnson & Johnson Services, Inc. and Novartis AG sit within the consumer health tier, while Teva Pharmaceutical Industries Ltd. and Sun Pharmaceutical Industries Ltd. represent the generic prescription segment.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson Services, Inc. |
| GSK plc |
| Sanofi |
| Reckitt |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Bayer AG |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between dextromethorphan API producers and formulation houses lock in supply access and price visibility across the forecast horizon. These arrangements insulate branded portfolio holders from spot-market volatility in Chinese and Indian precursor supply while compressing margin flexibility for generic manufacturers exposed to quarterly price resets.
Pricing Analysis
Certification level (FDA-grade versus non-GMP) creates the primary spread between premium and economy tier dextromethorphan raw materials. Per-unit transactional pricing dominates API procurement, with quality-grade differentiation widening as GMP certification failures collapse the qualified supplier base. Pricing pressure stems from REACH compliance investments in European green chemistry synthesis pathways. Retail pharmacy chains exhibit highest price sensitivity in OTC finished doses, while hospital formularies prioritize supply assurance over unit cost in parenteral segments.
Supply Chain Analysis
Indian API synthesis hubs and Chinese precursor chemical corridors constitute the dominant geographic supply concentration for dextromethorphan and benzonatate actives. The supply chain draws from 4-methoxyphenylacetic acid, cyclohexanone derivatives, and sodium channel modulator intermediates as critical inputs. Single-source vulnerability concentrates risk as GMP certification failures reduce qualified facilities to a handful of sites. Distribution runs through pharmacy-led networks in Europe and retail chain direct procurement in the United States, with institutional tenders anchoring hospital volume allocation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified API manufacturing capacity is contracting faster than formulation demand expands, creating a capability-scarcity dynamic where backward-integrated producers capture disproportionate margin pools. This gap favors incumbents with captive synthesis assets and disadvantages pure-play distributors exposed to supply interruption.
For Market Incumbents: Secure captive dextromethorphan precursor production through acquisition of distressed Indian API facilities or long-term capacity reservation agreements with surviving GMP-certified suppliers. Diversify formulation portfolios toward benzonatate capsules and sustained-release matrices to offset codeine volume compression from DEA quota constraints and pediatric prescribing restrictions. For New Entrants and Emerging Players: Sublingual and orally disintegrating tablet formats for dysphagic populations represent the most penetrable white-space segment, with Japanese long-term care channels and German nursing facilities underserved by incumbent liquid-dose portfolios. Target Southeast Asian pharmacy modernization in Indonesia and Vietnam through pediatric syrup formats adapted to tropical stability requirements and local taste preferences. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap API manufacturers with validated GMP status and existing dextromethorphan or benzonatate synthesis capabilities, positioned as consolidation platforms in a collapsing supplier base. Watch FDA pediatric pharmacovigilance signals and EMA scheduling decisions as inflection indicators that would accelerate non-narcotic formulation demand and revalue target assets.| Strategic Initiative | Industry Significance |
|---|---|
| API Manufacturing Scale-Up | Captive dextromethorphan synthesis secures supply continuity against GMP certification attrition in Chinese and Indian facilities. |
| Regulatory Approval Pathway | EMA pediatric investigation plan submission accelerates age-stratified efficacy positioning for novel delivery formats. |
| Pipeline Diversification | Benzonatate capsule capacity expansion captures physician prescribing rotation away from DEA-scheduled codeine alternatives. |
| Distribution Channel Expansion | Pharmacy-led network penetration in Germany and France leverages pharmacist counsel influence over purchase decisions. |
| Sustainability Repositioning | REACH-compliant green chemistry synthesis pathways capture preferential supply contracts from ESG-focused formulation houses. |
Methodological Framework
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions driving this analysis. Primary field engagement combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases established the evidentiary foundation. Bottom-up patient-flow modeling and top-down pharmaceutical market sizing were triangulated to reconcile volume and value estimates.
Segmentation dimensions modeled span product type chemistry, delivery mode, end-user channel, and formulation complexity across the projection horizon. CAGRs were derived from fitted growth curves applied to base-year estimates, with patient demographic trends and seasonal respiratory illness incidence patterns informing trajectory assumptions. Regulatory scheduling decisions and pharmacovigilance signal evolution were incorporated as scenario variables rather than fixed inputs.
Forecasts assume regulatory continuity in FDA pediatric codeine restrictions and EMA contraindication frameworks; material policy shifts would require re-modeling of prescription pattern assumptions. Practitioners should keep alternative scenarios live as DEA manufacturing quota allocations and GMP certification enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
RAS-Acting Agents Market
Pharmaceuticals
US Plasma Fractionation Market
Pharmaceuticals
Thin Film Drug Manufacturing Market
Pharmaceuticals
Adapalene Market
Pharmaceuticals
Intranasal Migraine Drugs Market
Pharmaceuticals
Cannabinoid Drugs Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Atorvastatin Diepoxide Calcium Salt Market
Pharmaceuticals
Plasma Protein Therapeutics Market
Pharmaceuticals
Chronic Obstructive Pulmonary Disease Drugs Market
Pharmaceuticals
Nasal Vaccines Market
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Congestive Heart Failure Drugs Market
Pharmaceuticals
Acetaminophen Injection Market
Pharmaceuticals
Telmisartan Market