
 Polypill Products Market | 2026-2036
Polypill Products Market Size, Share, and Industry Trends Forecast 2026-2036
Polypill Products Market Analytics
The capability gap between large-scale API manufacturers and pure-formulation specialists is collapsing as integrated producers consolidate control over polypill supply chains. Dr Reddy's Laboratories leverages backward integration into active pharmaceutical ingredients to sustain cost leadership in cardiovascular combinations. Cadila Pharmaceuticals anchors its position through dedicated manufacturing scale for fixed-dose therapies across Indian and African markets. AstraZeneca competes via technology leadership in sustained-release formulation platforms that extend dosing intervals for chronic disease management.
Polypill products are fixed-dose combination pharmaceuticals containing two or more active ingredients in a single dosage form, typically manufactured through direct compression or granulation processes to ensure uniform drug distribution and bioequivalence with individual component therapies. Their primary purpose is to improve medication adherence in chronic disease management by reducing pill burden for patients with cardiovascular risk, diabetes, or hypertension. Cardiovascular polypills dominate current revenue pools due to established clinical evidence from trials such as UMPIRE and Kanyini-GAP, while anti-diabetic combinations represent the fastest-growing category as physicians adopt intensified early intervention protocols. Tablets occupy the largest share by form factor, though capsules are gaining traction for combinations requiring enteric protection or modified release profiles.
The FDA maintains stringent bioequivalence requirements for abbreviated new drug applications covering fixed-dose combinations, while the EMA's Committee for Medicinal Products for Human Use evaluates polypill submissions under centralized procedures with emphasis on clinical interaction data. India's CDSCO aligns with WHO prequalification standards for essential medicine combinations, accelerating market access for domestic manufacturers. Stakeholders must monitor evolving pharmacovigilance requirements for polypharmacy interactions as regulatory bodies tighten post-market surveillance frameworks for multi-ingredient therapies.
Market Dynamics
Fixed-dose combination therapies are consolidating chronic disease management protocols, compressing the historical preference for sequential monotherapy into simultaneous multi-agent treatment paradigms that reshape prescribing behavior across cardiovascular and metabolic care pathways.
Growth Catalysts
- WHO Essential Medicines Listing:The WHO Model List inclusion of cardiovascular polypills normalizes reimbursement pathways across national health systems in emerging economies, accelerating physician acceptance of combination protocols.
- Hyderabad API Clusters:Concentrated active pharmaceutical ingredient manufacturing in India's pharmaceutical corridors reduces input cost volatility for formulation specialists, enabling competitive pricing for fixed-dose therapies.
- Sustained-Release Platforms:Modified-release formulation technologies extend dosing intervals from daily to weekly administration, directly addressing adherence failures in elderly polypharmacy populations.
Market Restraints
- API Supply Concentration:Dependence on Indian and Chinese active pharmaceutical ingredient suppliers creates vulnerability to export restriction policies and geopolitical trade friction.
- Bioequivalence Burden:FDA abbreviated new drug application requirements for fixed-dose combinations mandate extensive pharmacokinetic interaction studies, extending development timelines and capital requirements.
- Physician Skepticism:Cardiologist preference for individualized dose titration of separate agents resists standardized combination protocols, particularly in academic medical centers with research mandates.
Strategic Opportunities
- Sub-Saharan Africa:Underpenetrated cardiovascular prevention markets with high hypertension prevalence and limited specialist infrastructure create demand for simplified single-pill regimens distributed through community health workers.
- Diabetes-Metabolic Convergence:Triple-combination therapies integrating SGLT2 inhibitors with statins and ACE inhibitors address overlapping cardiovascular-renal risk in type 2 diabetes populations.
- Direct-to-Clinic Procurement:Hospital pharmacy consignment models bypass wholesale distribution markups, capturing margin for manufacturers while reducing stockout risk in high-volume cardiac centers.
Industry Challenges
- Pharmacovigilance Complexity:Attributing adverse events to specific active ingredients within multi-component formulations complicates signal detection and regulatory reporting obligations.
- Formulation Stability:Chemical incompatibility between acid-labile and moisture-sensitive APIs within single dosage forms demands specialized excipient engineering and packaging investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polypill Products Market |
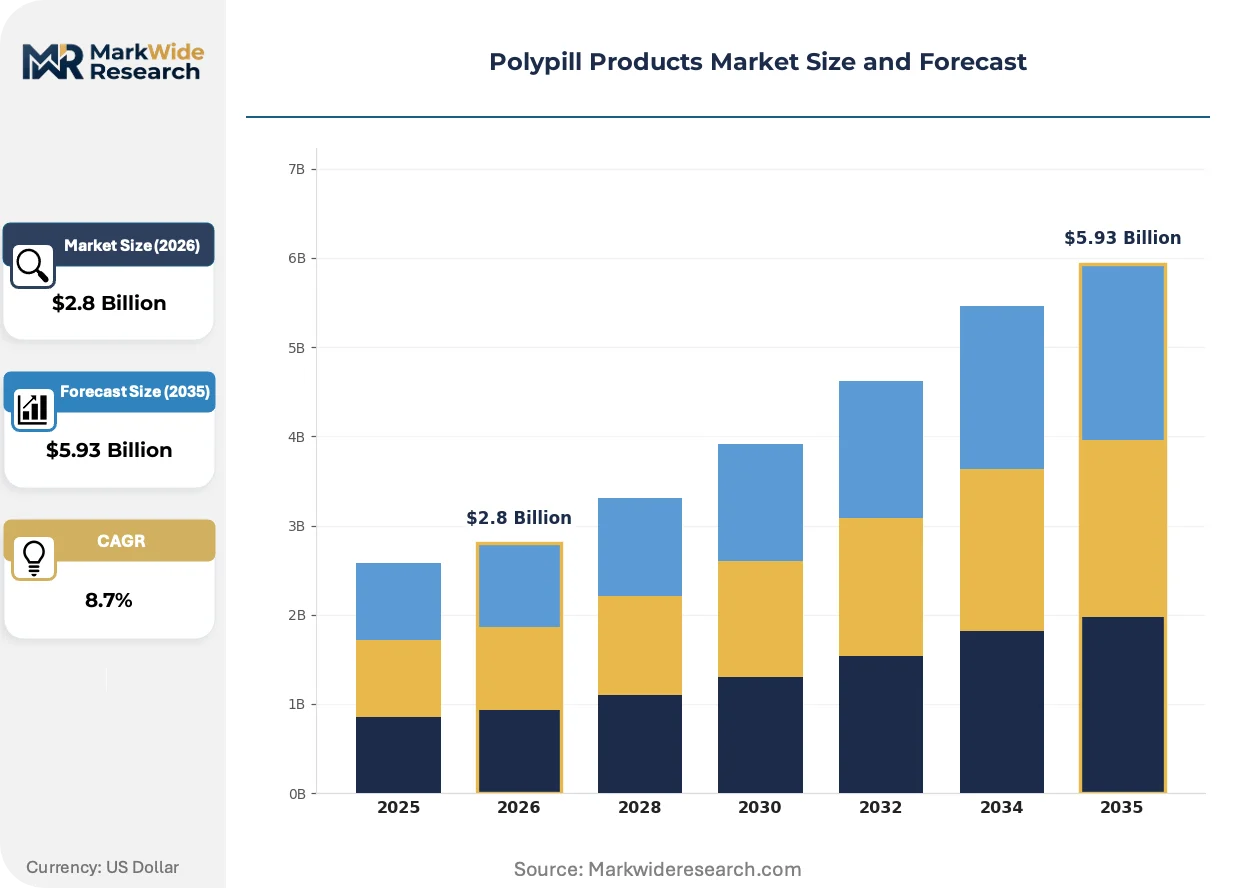
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiovascular, Anti-diabetic, Cholesterol-lowering, Hypertension End User: Pharmacies, Hospitals, Clinics, Healthcare Providers Form: Tablets, Capsules, Powders, Liquids Distribution Channel: Online, Retail, Wholesalers, Distributors |
| Companies Covered | Dr Reddy's Laboratories, Cadila Pharmaceuticals, AstraZeneca, Takeda Pharmaceutical Company Limited, Merck & Co, Pfizer Inc, Cipla Inc, Grupo Ferrer Internacional S.A, Janssen Global Services LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polypill Products Market Evolving Landscape
Polypill development is pivoting from cardiovascular-dominated portfolios toward metabolic and renal combination therapies, while manufacturing processes adopt continuous production technologies that alter scale economics for mid-volume specialty batches.
Oral thin-film and orally disintegrating tablet technologies are fragmenting the traditional tablet monopoly in fixed-dose combinations, enabling administration for dysphagic and geriatric populations that previously required liquid formulations or crushing protocols. Long-term care facilities and home health nursing services in Japan and Western Europe are accelerating procurement of these alternative dosage forms. The structural consequence is compressing the addressable market for conventional compressed tablets in adherence-critical patient segments.
EMA's Committee for Medicinal Products for Human Use has tightened evidentiary standards for clinical interaction data in fixed-dose combination submissions, requiring dedicated drug-drug interaction trials rather than extrapolated monotherapy data. This regulatory elevation extends development timelines and elevates trial costs for sponsors. Smaller European biotechnology developers are responding by prioritizing cardiovascular-metabolic combinations with established safety profiles over novel mechanism pairings.
Hospital procurement committees are consolidating vendor relationships for chronic disease medication categories, replacing multi-source purchasing with single-source or dual-source contracts that bundle polypill supply with adherence monitoring services. This concentration is displacing traditional pharmaceutical distribution intermediaries in high-volume cardiac and diabetes care pathways. The shift is most pronounced in integrated delivery networks across the United States and National Health Service trusts in England.
Polypill Products Market Segmentation
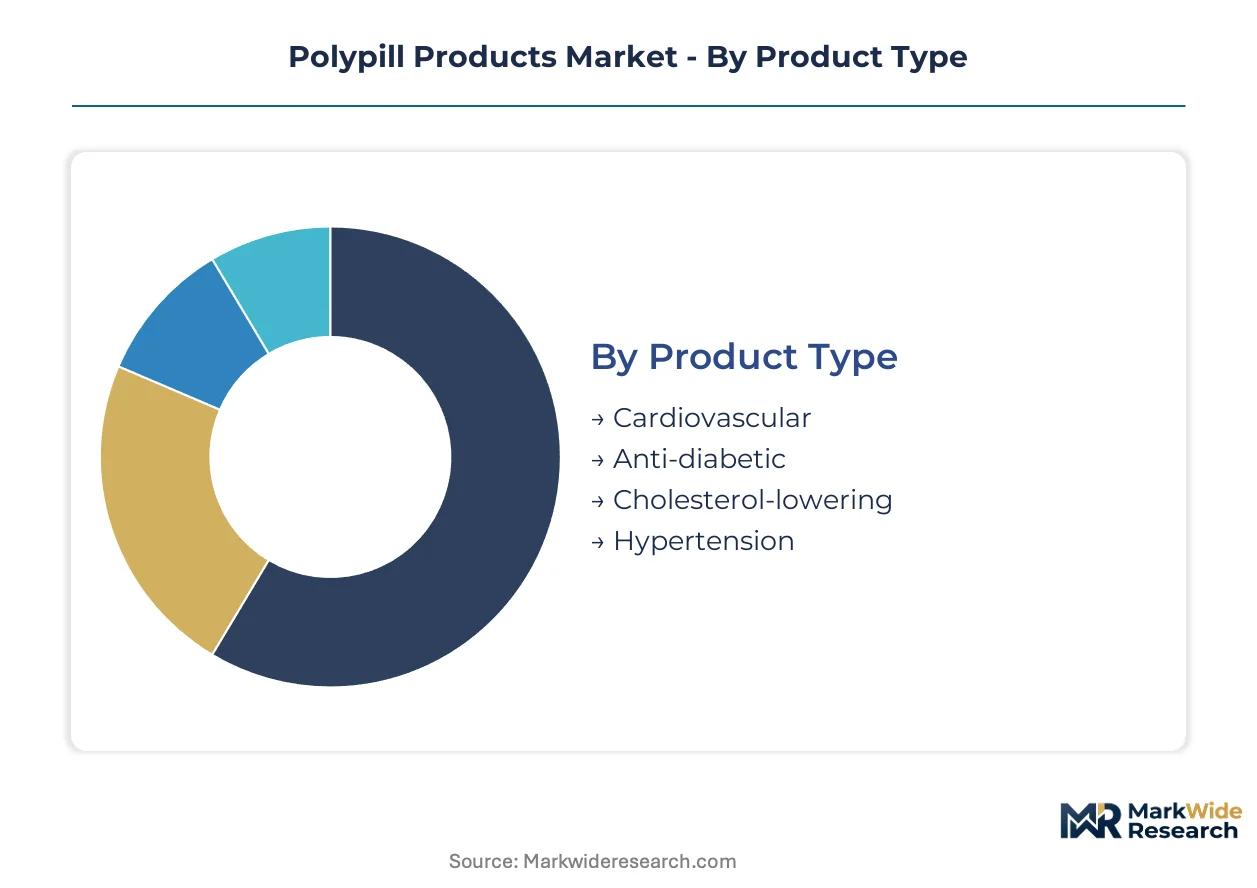
Polypill segmentation determines manufacturing scale economics and regulatory pathway selection. Product type and form factor choices cascade through distribution channel viability and end-user procurement protocols.
Product Type:
Hospital procurement committees and pharmacy chains source different therapeutic categories through divergent contract structures, with cardiovascular portfolios commanding volume-based tenders while metabolic combinations move through specialty distribution.
- Cardiovascular:Fixed-dose combinations of antihypertensives, statins, and antiplatelet agents dominate hospital formularies across India, Brazil, and South Africa. WHO Essential Medicines listing normalizes bulk procurement through centralized tenders in emerging health systems.
- Anti-diabetic:Triple-therapy combinations integrating SGLT2 inhibitors with metformin and DPP-4 inhibitors are climbing the fastest as physicians adopt intensified early intervention protocols. Demand concentrates in outpatient clinics managing type 2 diabetes with overlapping cardiovascular risk.
- Cholesterol-lowering:Statin-fibrate and statin-ezetimibe pairings serve residual cardiovascular risk populations with mixed dyslipidemia patterns.
- Hypertension:Dual and triple antihypertensive combinations address resistant hypertension through simplified single-pill adherence protocols.
Cardiovascular dominates installed base. Anti-diabetic is where expansion concentrates.
End User:
Cost tier stratification separates institutional purchasers from retail dispensers, with tender-based hospital systems extracting price concessions unavailable to independent pharmacies.
- Pharmacies:Community and chain pharmacies handle the majority of chronic disease prescription volume for stable outpatients. Inventory turns favor high-volume cardiovascular combinations with established physician prescribing habits.
- Hospitals:Integrated delivery networks and cardiac centers negotiate direct manufacturer contracts that bundle polypill supply with adherence monitoring services. CDSCO-registered suppliers in Hyderabad and Ahmedabad clusters capture these high-volume tenders through competitive API-backed pricing.
- Clinics:Physician-owned and community health clinics serve as initiation points for combination therapy in resource-limited settings.
- Healthcare Providers:Accountable care organizations and managed care entities influence formulary placement through outcomes-based contracting mechanisms.
Pharmacies move the highest prescription volume. Hospitals deliver the steepest contract concentration.
Form:
Patient population characteristics dictate dosage form selection, with geriatric and dysphagic populations driving alternative format adoption beyond conventional compressed tablets.
- Tablets:Direct-compression and granulation processes yield the cost-efficient standard for high-volume cardiovascular combinations. EMA bioequivalence requirements and FDA abbreviated new drug application standards govern tablet submissions across European and North American markets.
- Capsules:Enteric protection and modified-release profiles for acid-labile APIs expand addressable populations. Long-term care facilities in Japan and Western Europe accelerate procurement of capsule formats for residents with swallowing difficulties.
- Powders:Reconstitutable formulations serve pediatric and geriatric populations requiring dose flexibility.
- Liquids:Oral solutions remain essential for patients with severe dysphagia or enteral feeding requirements.
Tablets anchor manufacturing scale. Capsules are gaining share fastest in adherence-critical segments.
Distribution Channel:
Margin structure varies sharply across channel types, with direct-to-clinic procurement bypassing traditional wholesale markups while retail and online channels absorb multi-tier distribution costs.
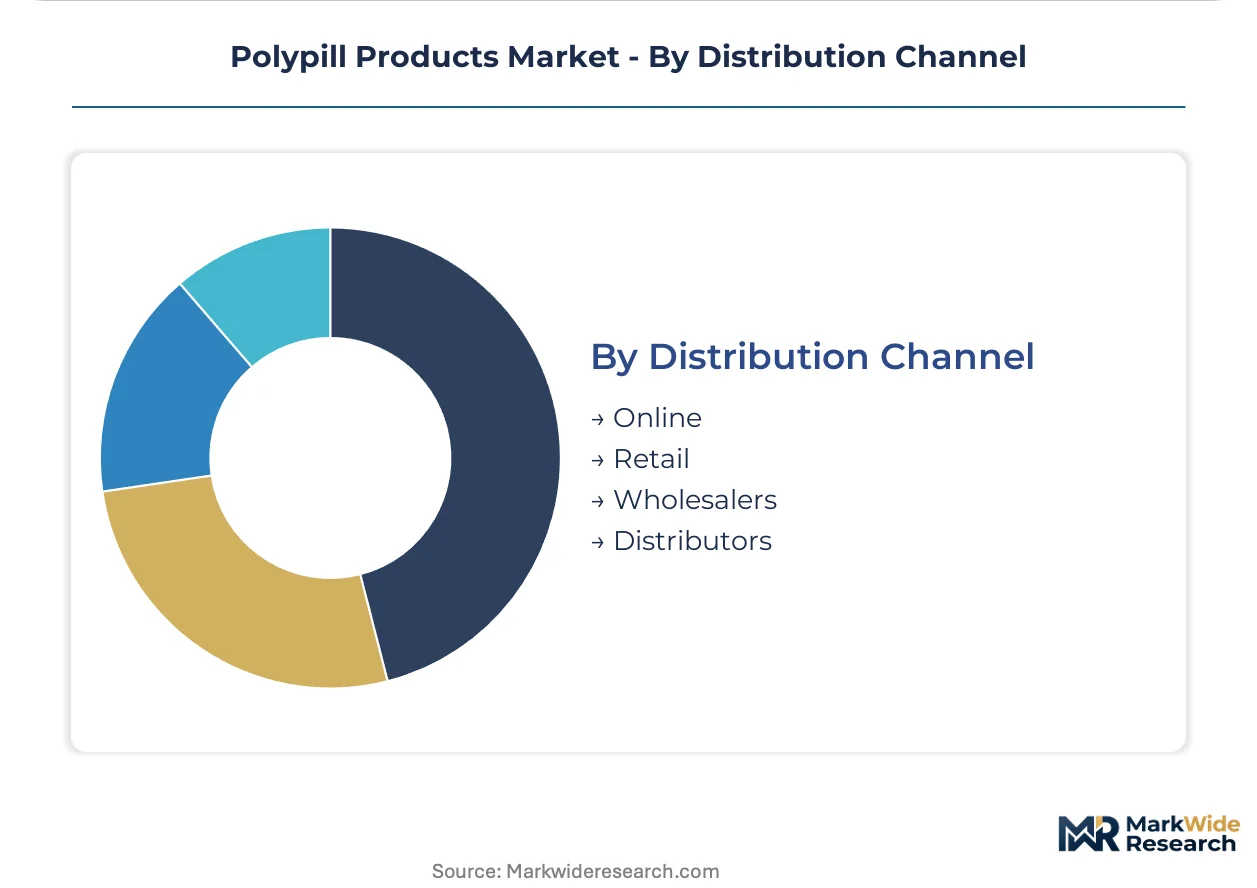
- Online:E-pharmacy platforms and direct-to-patient subscription models expand in markets with established digital health infrastructure. Regulatory frameworks from FDA drug marketing standards to India's CDSCO e-pharmacy guidelines shape permissible promotional content.
- Retail:Brick-and-mortar pharmacy chains maintain formulary influence through purchasing consortiums and preferred vendor agreements.
- Wholesalers:Traditional pharmaceutical distributors face displacement as hospital systems consolidate vendor relationships and manufacturers pursue direct contracts.
- Distributors:Regional and specialty distributors retain relevance in fragmented markets with underdeveloped cold chain infrastructure for temperature-sensitive formulations.
Retail handles the broadest geographic reach. Online is where channel investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for polypill procurement varies sharply across health systems, with tender-driven emerging markets extracting maximum cost concessions while reimbursed European markets absorb premium pricing for sustained-release formulations. Buyers in South Asia and Sub-Saharan Africa prioritize API-backed cost leadership, whereas Japanese and German hospital systems emphasize formulation technology and adherence outcomes.
United States
Integrated delivery networks consolidate cardiovascular polypill procurement through single-source contracts bundling medication supply with adherence monitoring services. FDA abbreviated new drug application requirements for fixed-dose combinations mandate extensive pharmacokinetic interaction studies, extending development timelines for domestic sponsors. The Cleveland Clinic and Mayo Clinic cardiac centers anchor high-volume demand for triple-combination therapies in resistant hypertension populations.
India
Hyderabad and Ahmedabad pharmaceutical clusters supply active pharmaceutical ingredients to multinational and domestic formulation producers, enabling competitive pricing for WHO Essential Medicines-listed cardiovascular combinations. CDSCO alignment with WHO prequalification standards accelerates market access for fixed-dose therapies targeting community health worker distribution. Maharashtra and Gujarat states concentrate manufacturing scale for export-oriented polypill production.
Germany
EMA centralized procedures govern polypill submissions with tightened evidentiary standards for clinical interaction data, requiring dedicated drug-drug interaction trials rather than extrapolated monotherapy data. Bavaria and Baden-Württemberg anchor pharmaceutical R&D concentration for sustained-release formulation platforms. Hospital pharmacy consignment models in North Rhine-Westphalia bypass wholesale distribution markups for high-volume cardiac centers.
Brazil
ANVISA regulatory frameworks for fixed-dose combinations support simplified registration pathways for cardiovascular polypills addressing hypertensive populations in underserved regions. São Paulo and Rio de Janeiro states concentrate specialist cardiology infrastructure driving prescription initiation for combination protocols. The SUS national health system normalizes bulk procurement through centralized tenders for essential medicine combinations.
Japan
PMDA evaluation of fixed-dose combination submissions emphasizes geriatric pharmacokinetic data and drug interaction profiles for elderly polypharmacy populations. Kanto and Kansai regions concentrate long-term care facility demand for orally disintegrating tablet and oral thin-film alternatives to conventional compressed tablets. METI industrial policy supports domestic formulation technology development for modified-release cardiovascular combinations.
Polypill Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with sustained-release formulation specialists competing against API-integrated volume producers for distinct contract tiers. The market structures around three strategic archetypes: backward-integrated Indian pharmaceutical conglomerates commanding tender markets, European-Japanese innovators licensing modified-release platforms, and multinational corporations bundling polypill supply with adherence services. Dominant competitive moves include hospital procurement committee consolidation displacing traditional distributors, and continuous manufacturing technology adoption altering scale economics for mid-volume specialty batches.
Among API-integrated Indian manufacturers, Dr Reddy's Laboratories and Cadila Pharmaceuticals exemplify the cost-leadership archetype through captive active pharmaceutical ingredient production. AstraZeneca occupies a position representing technology-driven competition via sustained-release formulation platforms. These three entities anchor the competitive spectrum from commoditized tender supply to premium adherence-optimized therapies.
| Leading Market Players |
|---|
| Dr Reddy's Laboratories |
| Cadila Pharmaceuticals |
| AstraZeneca |
| Takeda Pharmaceutical Company Limited |
| Merck & Co |
| Pfizer Inc |
| Cipla Inc |
| Grupo Ferrer Internacional S.A |
| Janssen Global Services LLC |
| Others |
Value Network & Pricing Analysis
Hospital pharmacy consignment models lock in multi-year supply access for cardiovascular polypill manufacturers while anchoring price visibility through volume-commitment tiers that bypass traditional wholesale markups in high-volume cardiac centers.
Pricing Analysis
Adherence monitoring service bundles drive lifetime value beyond unit sales in the polypill market. Three-tier pricing structure across premium sustained-release formulations, standard immediate-release tablets, and economy generic combinations separates AstraZeneca's technology-backed offerings from API-integrated Indian producers. Pricing pressure stems from tender-driven emerging markets extracting maximum concessions through centralized procurement. Hospital systems in Brazil and South Africa exhibit highest price sensitivity, while Japanese long-term care facilities absorb premiums for geriatric-optimized dosage forms.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient production for polypill formulations, with Hyderabad and Ahmedabad clusters supplying statin and antihypertensive inputs to multinational and domestic producers alike. Formulation specialists draw from concentrated API sources while facing dependencies on imported excipients for modified-release technologies. Single-source vulnerability concentrates in Chinese suppliers of specialty coating materials for sustained-release platforms. Distribution runs through hospital procurement committees consolidating vendor relationships, displacing traditional pharmaceutical wholesalers in high-volume cardiovascular care pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polypill market functions as a service-attach opportunity where adherence monitoring and patient outcome tracking expand faster than pharmaceutical unit sales, creating recurring revenue layers that extend contract duration and deepen manufacturer-provider relationships.
For Market Incumbents: Consolidate control over hospital procurement committee relationships through bundled adherence service contracts that displace distributor intermediaries. Deepen backward integration into Hyderabad API clusters to defend margin position against emerging Indian competitors. Prioritize CDSCO and WHO prequalification investments to lock in emerging market tender access before regulatory pathways tighten. For New Entrants and Emerging Players: Anchor in Sub-Saharan Africa's underpenetrated cardiovascular prevention markets where community health worker distribution models favor simplified single-pill regimens. Target triple-combination diabetes-metabolic therapies as the fastest-expanding category with lower incumbent saturation. Pursue direct-to-clinic procurement partnerships that bypass established wholesale networks in high-volume cardiac centers. For Investors and Strategic Acquirers: Capital is best deployed toward API-integrated formulation specialists with captive supply chains and established WHO prequalification status. Long-term viability hinges on regulatory alignment across multiple emerging market jurisdictions rather than single-territory dominance. Watch EMA pharmacovigilance tightening for multi-ingredient therapies as the inflection signal for consolidation pressure on smaller European developers.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | Alters scale economics for mid-volume cardiovascular batches at Hyderabad and Ahmedabad facilities. |
| WHO Prequalification Pathway | Accelerates tender access across SUS Brazil and national health systems in Sub-Saharan Africa. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic cardiac centers anchor demand for triple-combination hypertension therapies. |
| Sustained-Release Platform Licensing | Extends dosing intervals for elderly polypharmacy populations in Japanese long-term care facilities. |
| Direct-to-Clinic Procurement Model | Bypasses wholesale markups while capturing margin in high-volume integrated delivery networks. |
Research Methodology
The analysis maps cardiovascular, anti-diabetic, cholesterol-lowering and hypertension polypill segments, each validated through formulary directors, hospital procurement managers, regulatory affairs leads and API manufacturing executives. Primary interview data triangulates against FDA abbreviated new drug application filings, EMA centralized procedure submissions, CDSCO registration databases and WHO prequalification records. Bottom-up prescription volume modeling and top-down pharmaceutical expenditure analysis cross-validate market sizing across the projection horizon.
Consistency checks against external benchmarks validate volume and value outputs throughout the forecast period. Segmentation dimensions include therapeutic category, dosage form, distribution channel and regional regulatory cluster. CAGRs derive from fitted growth curves applied to prescription volume trajectories and pricing evolution patterns. Industry-specific inputs encompass WHO Essential Medicines listing status, API cost indices from Indian pharmaceutical clusters and hospital procurement tender databases.
Underlying assumptions cover regulatory pathway stability, API supply continuity and physician acceptance of combination protocols, with deviation risk concentrated in export restriction policies affecting Indian and Chinese active pharmaceutical ingredient suppliers. Forecasts reflect these conditions with acknowledgment that pharmacovigilance tightening for multi-ingredient therapies could accelerate consolidation timelines. Recalibration cycles align with material shifts in WHO Essential Medicines revisions, EMA evidentiary standard updates and major hospital system procurement consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Latin America Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Global Bronchodilators Market
Pharmaceuticals
Global Gastroparesis Drug Market
Pharmaceuticals
Bone Degeneration Therapeutics Market
Pharmaceuticals
Topical Drugs CDMO Market
Pharmaceuticals
OX40 Receptor Agonist Market
Pharmaceuticals
Lidocaine Ointment Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market
Pharmaceuticals
Dyslipidemia Therapeutics Market
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Rheumatology Therapeutics Market
Pharmaceuticals
Spain Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Periodontal Therapeutics Market
Pharmaceuticals
South Africa Diabetes Drugs Market
Pharmaceuticals
Sweden Pharmaceutical Market
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market