
 Narcotic Analgesics Market | 2026-2036
Narcotic Analgesics Market Size, Share, and Industry Trends Forecast 2026-2036
Narcotic Analgesics Market Analytics
Hospital and specialty pharmacy procurement is tilting toward tamper-resistant and abuse-deterrent formulations as institutional buyers tighten compliance protocols. Pfizer Inc. leverages its manufacturing scale to supply extended-release morphine sulfate tablets across integrated delivery networks. Teva Pharmaceuticals competes through generic oxycodone and hydrocodone portfolios that anchor its pain-management franchise in North American retail and institutional channels. Janssen Pharmaceuticals, Inc. differentiates via transdermal fentanyl patch technology that sustains its position in palliative care settings.
Narcotic analgesics comprise semisynthetic and synthetic opioid compounds that bind mu-opioid receptors to modulate pain perception, with formulations specified by active pharmaceutical ingredient purity, dissolution profiles, and DEA Schedule II-V classification. These agents serve primary commercial purpose in acute post-surgical recovery, cancer-related pain, and chronic non-malignant conditions where non-opioid therapies prove inadequate. Oxycodone and morphine product lines command the largest revenue pools due to entrenched prescriber familiarity and broad reimbursement coverage, while transdermal delivery modes represent the fastest-expanding segment as clinicians seek steady plasma levels with reduced breakthrough-dose requirements. Injectable formulations dominate perioperative and emergency settings where rapid onset proves clinically essential.
FDA, DEA, and state-level prescription drug monitoring programs collectively shape product standards, manufacturing quotas, and dispensing access for narcotic analgesics across the United States. The Controlled Substances Act and Risk Evaluation and Mitigation Strategies mandate abuse-deterrent packaging, prescriber certification, and patient counseling protocols that elevate compliance costs while restricting market entry. Stakeholders must monitor evolving REMS modifications and state litigation settlements that could abruptly reshape distribution channel economics and formulation investment priorities.
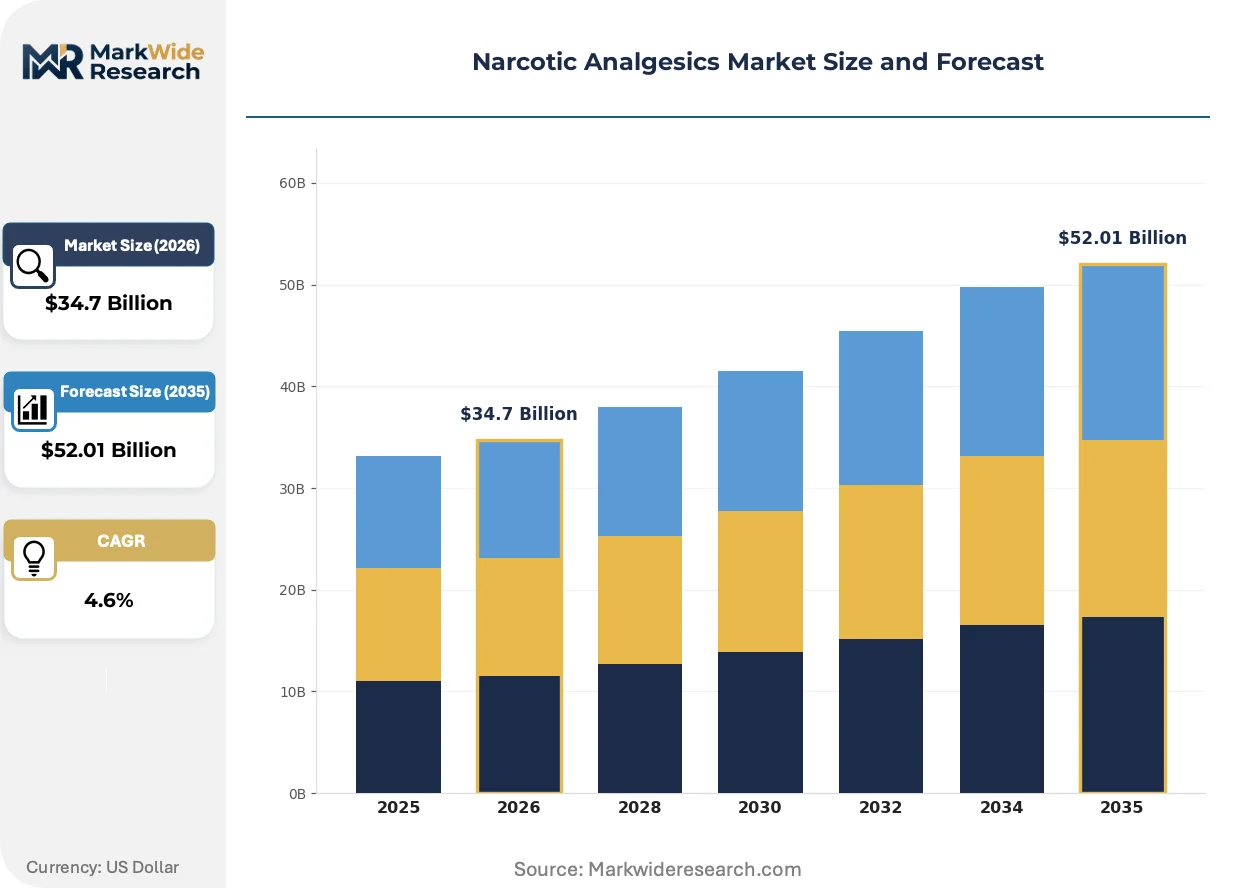
Market Dynamics
Abuse-deterrent formulation mandates from the FDA and DEA are compressing demand for conventional immediate-release opioids while redirecting R&D investment toward tamper-resistant polymer matrices and prodrug technologies. This regulatory pivot is restructuring manufacturing priorities across the entire supply base.
Growth Catalysts
- Palliative Care Expansion:Aging demographics in the United States and Germany are expanding hospice admissions where transdermal fentanyl and extended-release morphine dominate formularies. Hospital systems are standardizing these protocols across oncology and chronic pain units.
- Risk Evaluation and Mitigation Strategies:FDA-mandated REMS certification programs for extended-release and long-acting opioids are creating compliance barriers that favor established manufacturers with dedicated regulatory affairs infrastructure.
- Injectable Demand:Ambulatory surgical centers are consolidating procurement of rapid-onset fentanyl and hydromorphone for same-day discharge procedures, concentrating volume with GPO-affiliated distributors.
Market Restraints
- API Quota Volatility:DEA aggregate production quotas for oxycodone and hydrocodone create supply uncertainty that forces manufacturers to carry excess raw material inventory and idle capacity.
- Litigation Exposure:State-level opioid settlement frameworks in the United States are imposing channel-specific distribution restrictions and funding mandates that erode margin structures for legacy product lines.
- Non-Opioid Substitution:Peripheral nerve stimulators and cryoablation systems are capturing select chronic pain indications previously managed with Schedule II oral formulations.
Strategic Opportunities
- Suboxone Adjunct Protocols:Medication-assisted therapy expansion under Medicaid creates parallel demand for buprenorphine-naloxone combinations in addiction treatment settings.
- Japan Palliative Care:METI reimbursement reforms are accelerating hospice facility construction where transdermal patches face less stigma than oral opioids.
- Blockchain Track-and-Trace:DSCSA compliance deadlines are forcing wholesale distributors to upgrade serialization infrastructure, creating service revenue for technology-integrated suppliers.
Industry Challenges
- Formulation Chemistry Talent:Polymer science expertise for abuse-deterrent matrix development is concentrated at a handful of contract research organizations, extending development timelines.
- Cold Chain Complexity:Fentanyl citrate injectable stability requirements demand validated refrigerated distribution networks that small regional wholesalers cannot maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Narcotic Analgesics Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $52.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Codeine, Morphine, Hyrocodone, Oxycodone Delivery Mode: Oral, Injectable, Transdermal, Rectal End User: Hospitals, Clinics, Home Care, Palliative Care Application: Cancer Pain Management, Post-Surgical Pain, Chronic Pain, Acute Pain |
| Companies Covered | Pfizer Inc., Teva Pharmaceuticals, Endo Pharmaceuticals Inc., Janssen Pharmaceuticals, Inc., Abbott Laboratories, Sun Pharmaceutical Industries, Inc., Mallinckrodt Pharmaceuticals, Purdue Pharma L.P., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Narcotic Analgesics Market Evolving Landscape
Formulation chemistry and digital distribution controls are converging to reshape how narcotic analgesics reach end-users. The dominant trajectory favors technologies that harden products against diversion while streamlining legitimate clinical access.
Multiparticulate capsule technologies with crush-resistant properties are collapsing the clinical viability of conventional tablet formulations in institutional procurement. Hospital pharmacy committees are embedding these specifications into mandatory tender requirements. The shift is compressing residual demand for legacy immediate-release oxycodone products to narrow acute rescue indications.
DEA electronic prescribing mandates for Schedule II substances are eliminating paper prescription workflows across the United States. Retail pharmacies are integrating two-factor authentication and real-time prescription monitoring to comply. The transition is most disruptive in independent community pharmacies lacking IT infrastructure, accelerating consolidation into chain and health-system-owned networks.
Integrated delivery networks are unbundling pain management from surgical episode payments and carving out separate pharmacy benefit categories. GPOs are negotiating direct manufacturer contracts for extended-release morphine that bypass traditional wholesale markups. This restructuring is most advanced in Medicare Advantage–dominated markets where vertical health system control over specialty pharmacy operations is deepest.
Narcotic Analgesics Market Segmentation
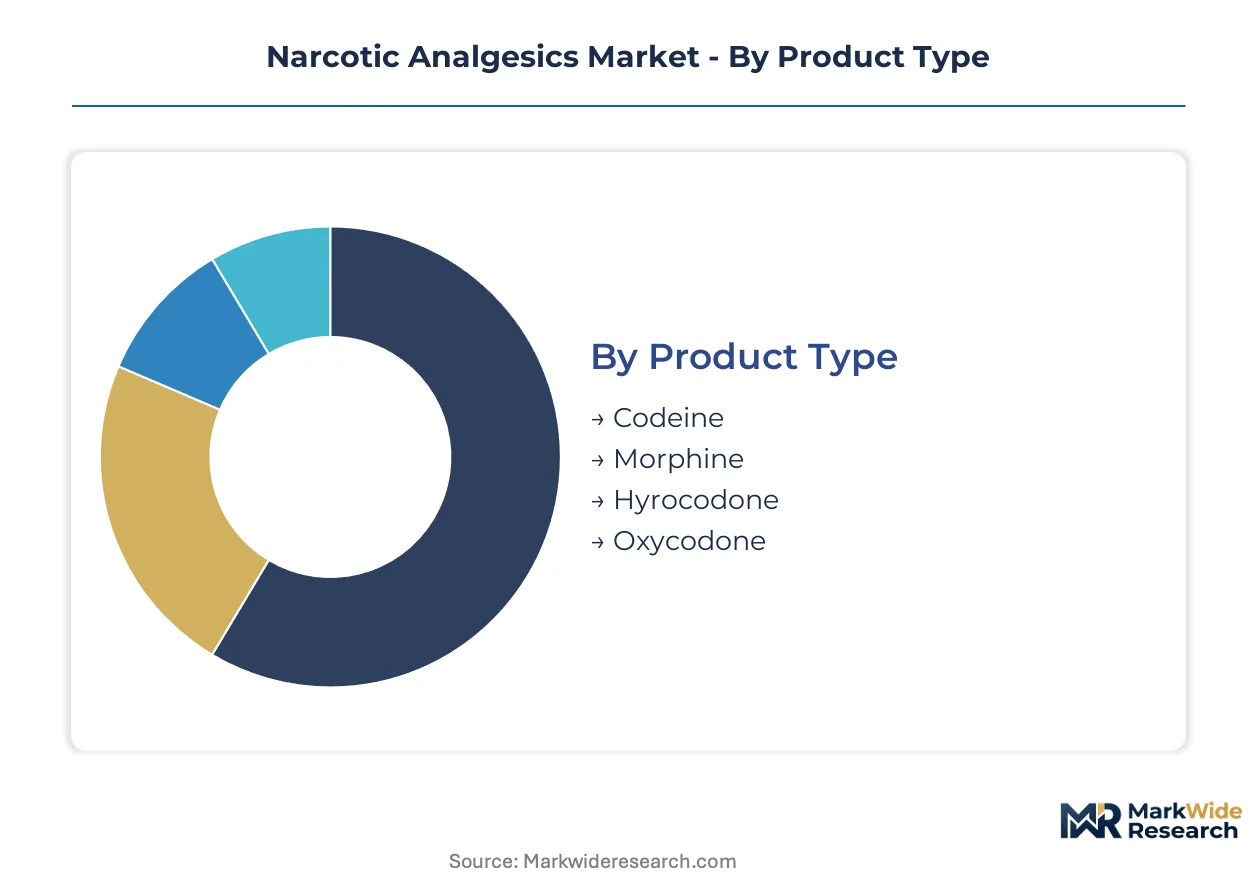
Narcotic analgesics exhibit sharp performance divergence across formulation chemistry and care setting, with reimbursement pathways and DEA scheduling creating distinct margin profiles. Procurement committees now weight abuse-deterrent specifications and cold-chain reliability as heavily as clinical efficacy in vendor selection.
Product Type:
After-sales service intensity varies dramatically across opioid API classes, with controlled-substance compliance support and REMS program administration demanding specialized field teams.
- Oxycodone:Semisynthetic thebaine derivative formulated in both immediate-release and abuse-deterrent extended-release matrices. Demand concentrates in United States hospital systems and specialty pharmacies where prescriber certification requirements and state PDMP integration create high switching costs for institutional buyers.
- Morphine:Gold-standard opiate alkaloid with century-long clinical familiarity, supplied as sulfate and hydrochloride salts across oral, injectable, and intrathecal routes. Palliative care units in Germany and Japan standardize extended-release morphine as first-line therapy, with hospice reimbursement protocols locking in formulary placement against newer alternatives.
- Hydrocodone:Semisynthetic opioid historically compounded with acetaminophen or ibuprofen in oral formulations. Retail pharmacy dispensing dominates, with DEA rescheduling to Schedule II elevating documentation burdens.
- Codeine:Naturally occurring opiate with ceiling effect limiting efficacy in severe pain, retained primarily in pediatric and geriatric populations where metabolic variability requires cautious titration.
By volume, morphine leads across institutional channels. By growth pace, oxycodone's abuse-deterrent reformulations are climbing the fastest.
Delivery Mode:
Cost tier stratification separates commodity oral generics from premium transdermal and injectable formats requiring validated manufacturing and distribution infrastructure.
- Transdermal:Matrix and reservoir patch technologies delivering fentanyl or buprenorphine through rate-controlled skin permeation. Palliative care expansion in Japan and steady-state plasma concentration advantages drive formulary adoption against oral breakthrough dosing.
- Injectable:Parenteral fentanyl citrate, morphine sulfate, and hydromorphone hydrochloride for perioperative and emergency settings. Ambulatory surgical centers in the United States consolidate procurement through GPO-affiliated distributors demanding lot-level traceability.
- Oral:Tablets, capsules, and liquid formulations comprising the volume base, with immediate-release hydrocodone-acetaminophen combinations facing sharpest demand compression from non-opioid substitution.
- Rectal:Suppository and enema formats reserved for dysphagic patients and terminal care where enteral absorption is compromised.
By volume, oral formulations dominate dispensing counts. By growth pace, transdermal patches are gaining share fastest.
End User:
Customer type determines compliance architecture, with hospital systems requiring enterprise-level REMS integration and home care demanding patient-facing education infrastructure.
- Hospitals:Integrated delivery networks and academic medical centers with centralized pharmacy and therapeutics committees. Abuse-deterrent specifications and tamper-resistant packaging are now mandatory tender requirements across United States health systems.
- Palliative Care:Hospice facilities and dedicated pain units where transdermal fentanyl and extended-release morphine anchor protocol-driven therapy. METI reimbursement reforms in Japan are accelerating facility construction and formulary standardization.
- Clinics:Outpatient pain management and oncology practices with mixed prescribing authority across Schedule II-V substances.
- Home Care:Discharge planning and long-term administration where caregiver training and diversion risk mitigation require specialized nursing support.
By volume, hospitals lead procurement. By growth pace, palliative care facilities are expanding most quickly.
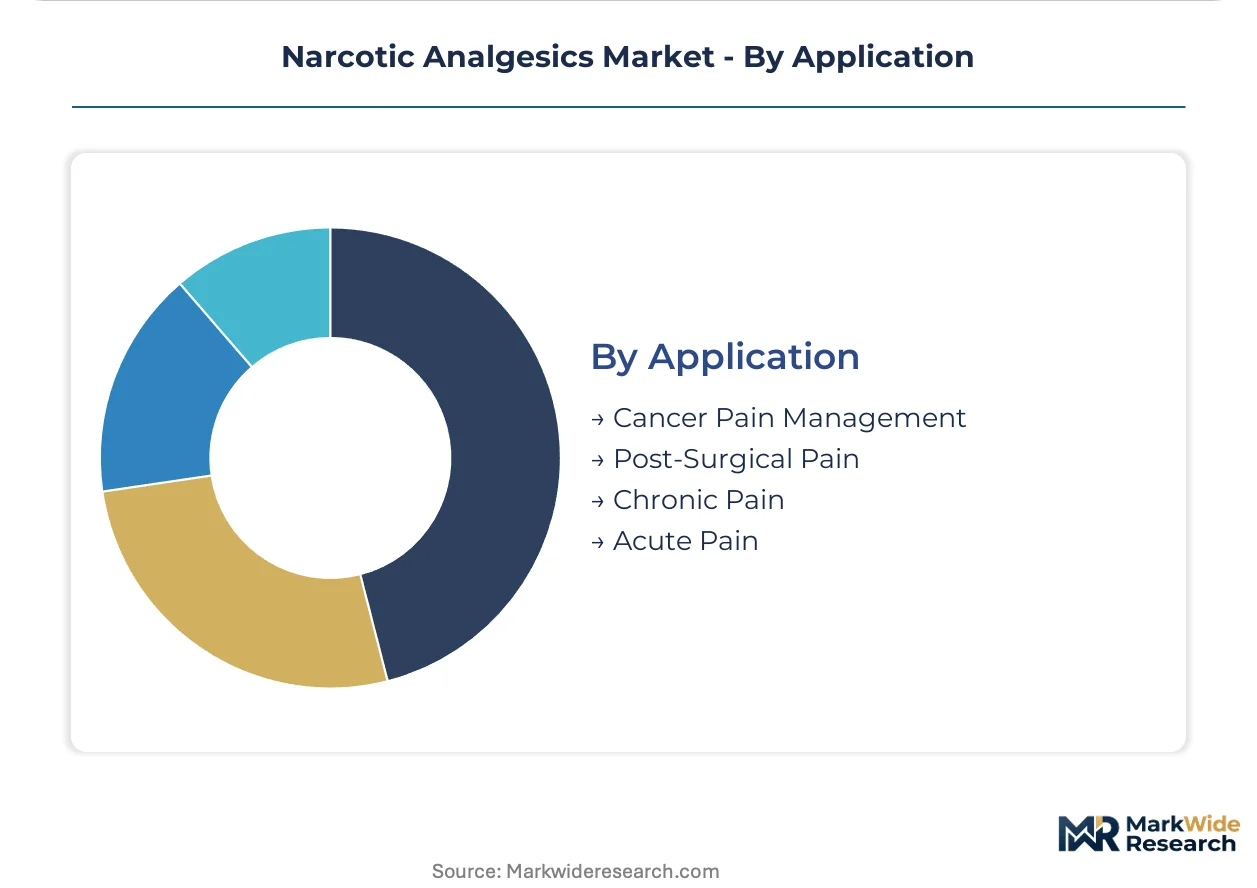
Application:
Maturity gradients separate well-established cancer pain protocols from contested chronic non-malignant indications where regulatory and litigation pressures are reshaping access.
- Cancer Pain Management:WHO analgesic ladder compliance and hospice reimbursement certainty sustain demand for strong opioids across disease stages. Extended-release formulations with rescue dosing protocols dominate oncology formularies.
- Post-Surgical Pain:Perioperative and discharge prescribing with accelerating shift toward multimodal protocols limiting opioid exposure. Ambulatory surgery growth concentrates rapid-onset injectable demand.
- Chronic Pain:Non-malignant conditions including lower back and osteoarthritis where CDC prescribing guidelines and state litigation settlements have compressed long-term opioid therapy.
- Acute Pain:Trauma, renal colic, and breakthrough episodes where immediate-release oral and injectable formats retain rescue indication despite broader demand decline.
By volume, cancer pain management leads therapeutic consumption. By growth pace, post-surgical applications are climbing the fastest amid ambulatory procedure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DEA production quotas and FDA REMS mandates in the United States are reshaping procurement patterns across hospital systems and specialty pharmacies. Germany's palliative care reimbursement protocols and Japan's METI hospice construction incentives are accelerating transdermal formulation demand in aging populations.
United States
Hospital procurement committees now mandate abuse-deterrent specifications in opioid tenders, compressing demand for conventional immediate-release tablets. FDA Risk Evaluation and Mitigation Strategies require prescriber certification that elevates compliance costs for institutional buyers. Purdue Pharma's historical market presence in Stamford, Connecticut shaped prescriber habits that now face intensifying state litigation settlement frameworks.
Germany
Aging demographics are expanding hospice admissions where extended-release morphine dominates formularies under statutory health insurance reimbursement. The country's national pharmaceutical regulator maintains strict manufacturing standards that favor established European suppliers. The Baden-Württemberg pharmaceutical cluster around Stuttgart hosts specialized polymer science contract research organizations developing tamper-resistant matrix technologies.
Japan
METI reimbursement reforms are accelerating hospice facility construction where transdermal fentanyl patches face less stigma than oral opioids. PMDA approval pathways for abuse-deterrent formulations are creating compliance barriers that favor manufacturers with dedicated regulatory affairs infrastructure. The Kansai region around Osaka concentrates palliative care unit expansion with standardized transdermal protocol adoption.
India
CDSCO manufacturing standards and export-oriented production quotas are positioning domestic suppliers as API sources for controlled-release formulations. The country's national pharmaceutical regulator enforces Good Manufacturing Practice compliance that shapes contract manufacturing relationships. The Hyderabad-Visakhapatnam pharmaceutical corridor concentrates active pharmaceutical ingredient production for morphine sulfate and oxycodone derivatives.
Canada
Health Canada prescription drug monitoring programs and provincial formulary restrictions are redirecting demand toward abuse-deterrent alternatives. The national pharmaceutical regulator coordinates with DEA-aligned scheduling that affects cross-border distribution economics. The Ontario-Quebec corridor concentrates hospital system procurement through group purchasing organizations with direct manufacturer contracting authority.
Narcotic Analgesics Market Competitive Landscape
On the supply side, the industry is consolidating around manufacturers with dedicated regulatory affairs infrastructure capable of navigating DEA quota volatility and REMS compliance mandates. The competitive terrain separates scale-driven pharmaceutical conglomerates from specialized abuse-deterrent formulation developers. Three archetypes dominate: integrated delivery network suppliers with GPO-affiliated distribution, generic portfolio anchors competing on oxycodone and hydrocodone volume, and transdermal technology specialists serving palliative care protocols. Dominant competitive moves include strategic partnerships with contract research organizations for polymer matrix development and geographic expansion into Japan's hospice construction wave.
Within the scale-driven tier, Pfizer Inc. and Teva Pharmaceuticals exemplify manufacturers leveraging manufacturing breadth across extended-release morphine and generic oxycodone portfolios. Janssen Pharmaceuticals, Inc. occupies a distinct position as a transdermal technology anchor in palliative care settings. These three entities represent the archetype spectrum: conglomerate scale, generic volume competition, and specialized delivery mode innovation.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Teva Pharmaceuticals |
| Endo Pharmaceuticals Inc. |
| Janssen Pharmaceuticals, Inc. |
| Abbott Laboratories |
| Sun Pharmaceutical Industries, Inc. |
| Mallinckrodt Pharmaceuticals |
| Purdue Pharma L.P. |
| Novartis AG |
| Others |
Value Network & Pricing Analysis
DEA aggregate production quota volatility functions as the central pricing determinant, compressing margin spreads between abuse-deterrent formulations and commodity immediate-release tablets while forcing manufacturers toward dual-sourcing strategies that reshape procurement networks. This regulatory chokepoint simultaneously elevates inventory carrying costs and creates tiered pricing power for API holders with secured quota allocations.
Pricing Analysis
Certification level creates the primary spread between FDA REMS-compliant extended-release formulations and non-certified legacy products. Three-tier pricing structure across premium abuse-deterrent, standard extended-release, and economy immediate-release levels stratifies hospital procurement committees. Pricing pressure stems from state litigation settlement frameworks imposing distribution restrictions. Retail pharmacy chains exhibit highest price sensitivity due to thin dispensing margins, while integrated delivery networks prioritize compliance reliability over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized polymer science CROs in Germany's Baden-Württemberg cluster and API producers along India's Hyderabad-Visakhapatnam corridor. Active pharmaceutical ingredient supply draws from Indian thebaine processing facilities, Chinese chemical intermediates, and domestic DEA-registered manufacturers. Single-source vulnerability concentrates in tamper-resistant matrix polymer feedstocks. Distribution runs through GPO-affiliated wholesalers serving hospital systems and specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA abuse-deterrent formulation mandates are accelerating market disruption, creating structural advantages for manufacturers with dedicated REMS infrastructure and polymer matrix capabilities.
For Market Incumbents: Build regulatory affairs moats through REMS certification depth and state PDMP integration partnerships. Consolidate position by acquiring specialized polymer science contract research organizations in Germany. Expand manufacturing footprint in India to secure API quota flexibility against DEA volatility. For New Entrants and Emerging Players: Japan's METI hospice construction wave represents the most penetrable entry point for transdermal patch specialists. Palliative care units in Kansai region facilities face less formulary lock-in than US hospital systems. Partner with established Japanese distributors to navigate PMDA approval pathways. For Investors and Strategic Acquirers: DEA electronic prescribing mandates for Schedule II substances reshape the acquisition landscape toward technology-integrated distributors. Long-term viability centers on compliance automation capabilities over pure manufacturing scale. Target wholesale distributors with validated cold-chain infrastructure. Monitor state litigation settlement implementation pace as inflection indicator for channel restriction severity.| Strategic Initiative | Industry Significance |
|---|---|
| Abuse-Deterrent Formulation Development | Polymer matrix R&D investment secures hospital formulary placement against REMS mandates. |
| REMS Certification Infrastructure | Dedicated regulatory affairs teams create compliance barriers favoring established manufacturers. |
| Japan Hospice Market Entry | METI reimbursement reforms accelerate facility construction with standardized transdermal protocols. |
| API Quota Diversification | Dual-sourcing from Indian CDSCO-registered suppliers mitigates DEA production volatility exposure. |
| Blockchain Track-and-Trace Integration | DSCSA compliance deadlines force wholesale distributor serialization upgrades creating service revenue. |
Research Methodology
A spread of perspectives from formulary directors, hospital procurement managers, regulatory affairs leads, and pain management clinicians converged on the working assumptions governing demand trajectories. Primary field engagement with GPO contract administrators and specialty pharmacy operators supplemented secondary validation through FDA REMS program documentation, DEA aggregate production quota filings, state prescription drug monitoring program disclosures, and CMS Medicare Part D claims patterns. Bottom-up patient-flow modeling and top-down therapeutic category spend analysis were cross-referenced to establish volume baselines.
Demand-supply balance dynamics across the analysis window were assessed through segmented modeling of formulation chemistry, delivery mode, and care setting interactions. Segmentation dimensions included API class, administration route, DEA scheduling tier, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical dispensing volumes adjusted for policy inflection points. Forecast inputs incorporated palliative care admission projections and ambulatory surgical center construction pipelines.
Practitioners should monitor DEA quota modification announcements, state litigation settlement implementation timelines, and non-opioid substitution technology adoption curves for early signals of trajectory revision. Quarterly review of REMS program modification notices and PDMP integration mandates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Neurological Disorder Drugs Market
Pharmaceuticals
Antibiotic-Associated Diarrhea Treatment Market
Pharmaceuticals
Methylphenidate Hydrochloride Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
US Pharmaceutical CMO Market
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
US Emergency Contraceptive Pills Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
Global Acyclovir Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Extended Oral Antibiotics Market
Pharmaceuticals
Ramipril Market
Pharmaceuticals
Energy-Based Therapeutics Market
Pharmaceuticals
Asia-Pacific Vaccines Market
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
Organ Transplant Rejection Medications Market