
 Recloser Control Market | 2026-2036
Recloser Control Market Size, Share, and Industry Trends Forecast 2026-2036
Recloser Control Market Intelligence
The distinction between premium, feature-rich recloser controls and basic, functional units is hardening. Schneider Electric leads in the high-end segment with advanced analytics and communication capabilities. Siemens differentiates through its integration with broader digital grid management platforms. Meanwhile, specialists like NOJA Power compete effectively by offering robust, application-specific solutions for challenging environments.
A recloser control is an intelligent electronic device that commands a circuit breaker to automatically restore power after a temporary fault on a distribution line. It operates based on pre-programmed sequences, monitoring current and voltage to distinguish between temporary and permanent faults. Microprocessor-based controls dominate new installations, driven by electric utilities' demand for enhanced grid reliability. The smart grids application represents the fastest-growing segment, requiring controls with sophisticated communication protocols for automated network management.
International Electrotechnical Commission (IEC) standards, particularly the IEC 61850 protocol, define communication and interoperability requirements for substation automation. In the United States, FERC orders encourage grid resilience, while China's dual carbon goals push for efficient grid management, both boosting demand for advanced controls. Vendor selection increasingly depends on a control's ability to support distributed energy resources and future-proof the grid against evolving cyber threats.
Market Dynamics
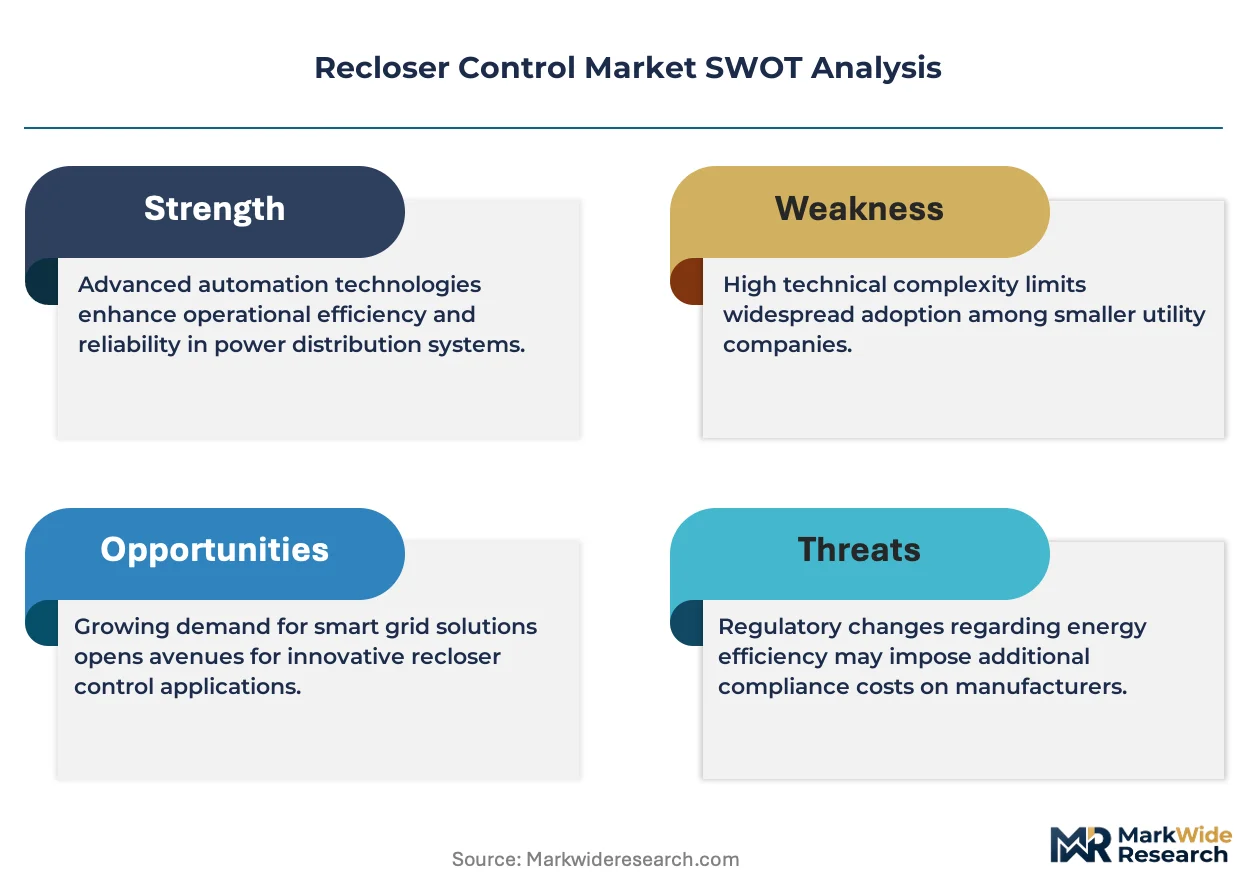
The central dynamic shaping the recloser control market is the accelerating modernization of electrical distribution networks. This force is driven by the dual pressures of integrating intermittent renewable energy sources and enhancing grid resilience against physical and cyber threats.
Growth Catalysts
- Grid Resilience Mandates:Regulatory actions, such as FERC orders in the United States, compel electric utilities to invest in technologies that improve grid reliability and reduce outage durations, directly benefiting recloser control adoption.
- Interoperability Standards:The widespread adoption of the IEC 61850 communication protocol provides a standardized framework for substation automation, simplifying integration and encouraging utilities to upgrade to more advanced, interoperable control systems.
- Modernization Programs:National initiatives in countries like India aimed at upgrading aging power distribution infrastructure and reducing transmission and distribution losses create sustained demand for microprocessor-based recloser controls.
Market Restraints
- High Capital Costs:The significant upfront investment required for electric utilities to replace legacy electromechanical devices and upgrade associated communication infrastructure across vast distribution networks can slow the pace of adoption.
- Integration with Legacy Systems:Utilities face considerable technical hurdles and costs when integrating new, sophisticated recloser controls with older, often proprietary SCADA systems and communication networks, creating compatibility issues.
- Component Supply Chain Risks:The reliance on a concentrated global market for specific microprocessors and power electronic components exposes recloser control manufacturers to potential supply disruptions and price volatility.
Strategic Opportunities
- Microgrid Applications:There is a growing opportunity for specialized recloser controls designed for microgrid management, offering advanced functionalities for islanding, black start capabilities, and seamless reconnection to the main grid.
- Predictive Analytics Integration:Incorporating AI and machine learning algorithms into control software enables predictive maintenance and pre-emptive fault detection, offering a new value proposition to utilities focused on asset management.
- Expansion in Southeast Asia:Rapid economic growth and electrification programs in countries across Southeast Asia present an underpenetrated market for advanced grid automation technologies, including modern recloser controls.
Industry Challenges
- Cybersecurity Vulnerabilities:Protecting recloser controls, as critical network access points, from an increasing volume and sophistication of cyberattacks requires continuous software updates, rigorous testing, and advanced security protocols.
- Skilled Workforce Shortage:A deficit of power systems engineers and technicians with combined expertise in protection engineering, modern communication protocols, and cybersecurity threatens the effective deployment and maintenance of advanced control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recloser Control Market |
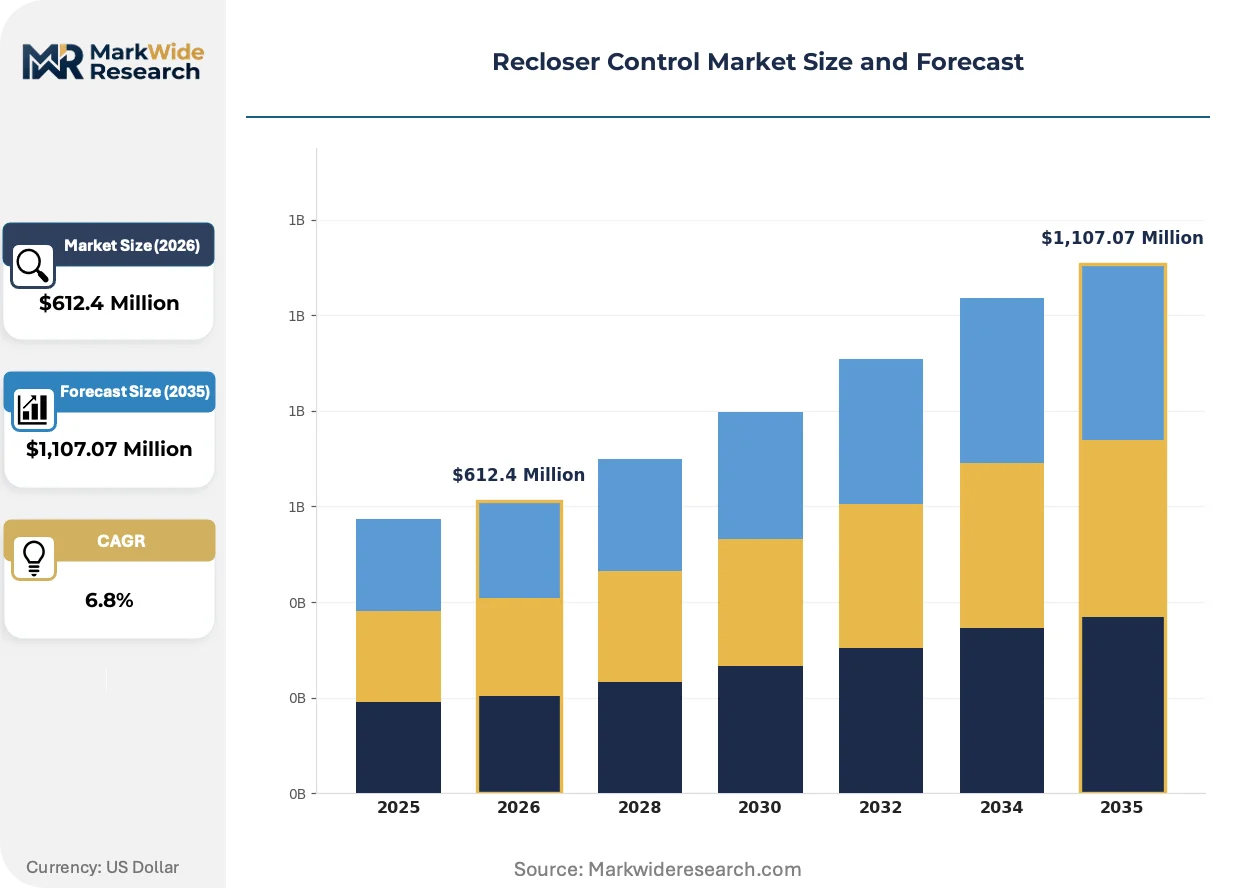
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical, Solid State, Microprocessor-Based, Hybrid Technology: Remote Monitoring, Automated Switching, Fault Detection, Load Management, Communication Protocols, Self-Healing Networks Application: Electric Utilities, Renewable Energy Networks, Smart Grids, Microgrids End User Industry: Power Distribution Companies, Grid Operators, Industrial Power Plants, Commercial Facilities |
| Companies Covered | ABB, Eaton, Schneider Electric, Siemens, General Electric, NOJA Power Switchgear, S&C Electric Company, Hubbell, G&W Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recloser Control Market Strategic Shifts & Innovations
The fundamental role of the recloser control is evolving from a standalone protective device into an intelligent, data-rich node within the digital grid. This transition is defined by on-device intelligence, stringent security requirements, and new software-centric business models.
Edge computing integrated into the recloser control allows for localized, real-time data processing and automated decision-making. Electric utilities are adopting these intelligent controls to better manage the inherent volatility of distributed energy resources like local solar installations. This on-device intelligence is rewriting the traditional, centralized model of grid command, enabling faster fault isolation and greater network autonomy.
The European Union's Network and Information Systems (NIS) Directive mandates strict cybersecurity measures for operators of essential services, including electricity distribution. This regulation forces utilities to procure recloser controls with certified, hardened security features and verifiable software integrity. The smart grids application is most affected, with vendors now needing to prove compliance with standards like IEC 62443 to secure contracts.
A shift from one-time hardware sales to subscription-based models for advanced software features and analytics is gaining traction among utilities. This approach unbundles core protection from premium capabilities like fault location diagnostics, allowing for more flexible and scalable technology investments. This trend is most prominent in North America and Europe, where utilities seek to maximize the lifecycle value of their intelligent grid assets.
Recloser Control Market Segmentation
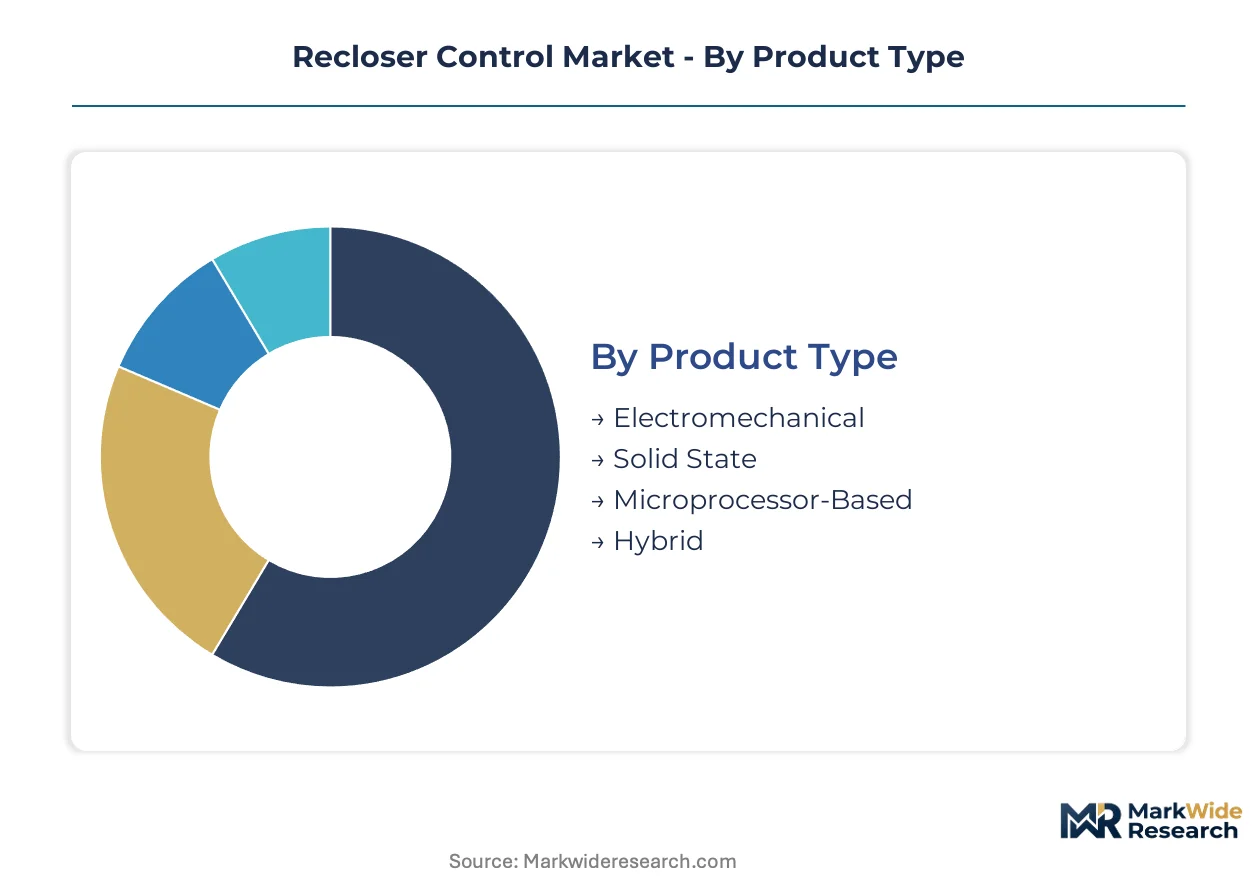
The Recloser Control Market segmentation provides a granular view of the diverse product offerings, technological advancements, and varied applications driving demand across the global electrical infrastructure. Understanding these distinct segments is crucial for assessing market dynamics and strategic positioning within the evolving grid modernization landscape.
Product Type:
The product type segmentation highlights the evolution from standalone, less integrated devices to advanced, embedded systems within the grid infrastructure.
- Microprocessor-Based:These controls utilize advanced digital processors for precise fault detection, automated switching, and sophisticated communication capabilities, meeting electric utilities' demand for enhanced grid reliability in countries like the United States.
- Solid State:Employing power electronics, solid state recloser controls offer extremely fast operation, high precision, and extended lifespan, making them suitable for critical applications requiring rapid fault isolation and minimal power interruption.
- Electromechanical:These are older, mechanically operated devices providing basic overcurrent protection and automatic reclosing functions for distribution lines.
- Hybrid:Combining elements of both electromechanical and microprocessor-based designs, hybrid controls often offer a balance of cost-effectiveness and enhanced functionality for specific grid requirements.
Volume placements concentrate in Electromechanical units due to legacy installations; the faster expansion belongs to Microprocessor-Based controls.
Technology:
This segmentation delineates recloser control capabilities based on their operational functions within modern distribution networks.
- Communication Protocols:These technologies, such as IEC 61850, enable seamless data exchange and interoperability between recloser controls and broader grid management systems, facilitating automated network management in smart grids.
- Self-Healing Networks:This advanced technology allows the distribution grid to automatically detect faults, isolate affected sections, and restore power to healthy segments without human intervention, significantly improving grid resilience.
- Remote Monitoring:This capability allows utilities to gather real-time operational data from recloser controls, providing insights into grid performance and enabling proactive maintenance strategies.
- Automated Switching:Recloser controls use automated switching to open and close circuits in response to fault conditions, restoring power quickly after temporary disturbances.
- Fault Detection:This fundamental function identifies the presence and location of electrical faults on distribution lines, triggering protective actions to prevent equipment damage and outages.
- Load Management:Integrated load management features enable recloser controls to help balance power demand and supply, supporting grid stability and efficiency, particularly with distributed energy resources.
Advanced functionalities like Self-Healing Networks are gaining traction, while foundational capabilities such as Fault Detection remain universally critical.
Application:
The market applications reflect distinct grid architectures and operational objectives for recloser control deployment.
- Smart Grids:This application segment represents the fastest-growing demand, requiring recloser controls with sophisticated communication protocols and on-device intelligence for automated network management and integration of distributed energy resources.
- Electric Utilities:These entities represent the core market for recloser controls, utilizing them extensively for upgrading distribution networks, enhancing reliability, and complying with regulatory mandates like FERC orders in the United States.
- Renewable Energy Networks:Recloser controls are crucial for managing the inherent volatility and intermittency of renewable energy sources, ensuring grid stability and protection for solar and wind power integration.
- Microgrids:Specialized recloser controls support microgrid operations by enabling islanding capabilities, black start functionalities, and seamless reconnection to the main grid for localized power resilience.
Smart Grids represent the steepest expansion trajectory for recloser controls, while Electric Utilities continue to form the largest deployment base.
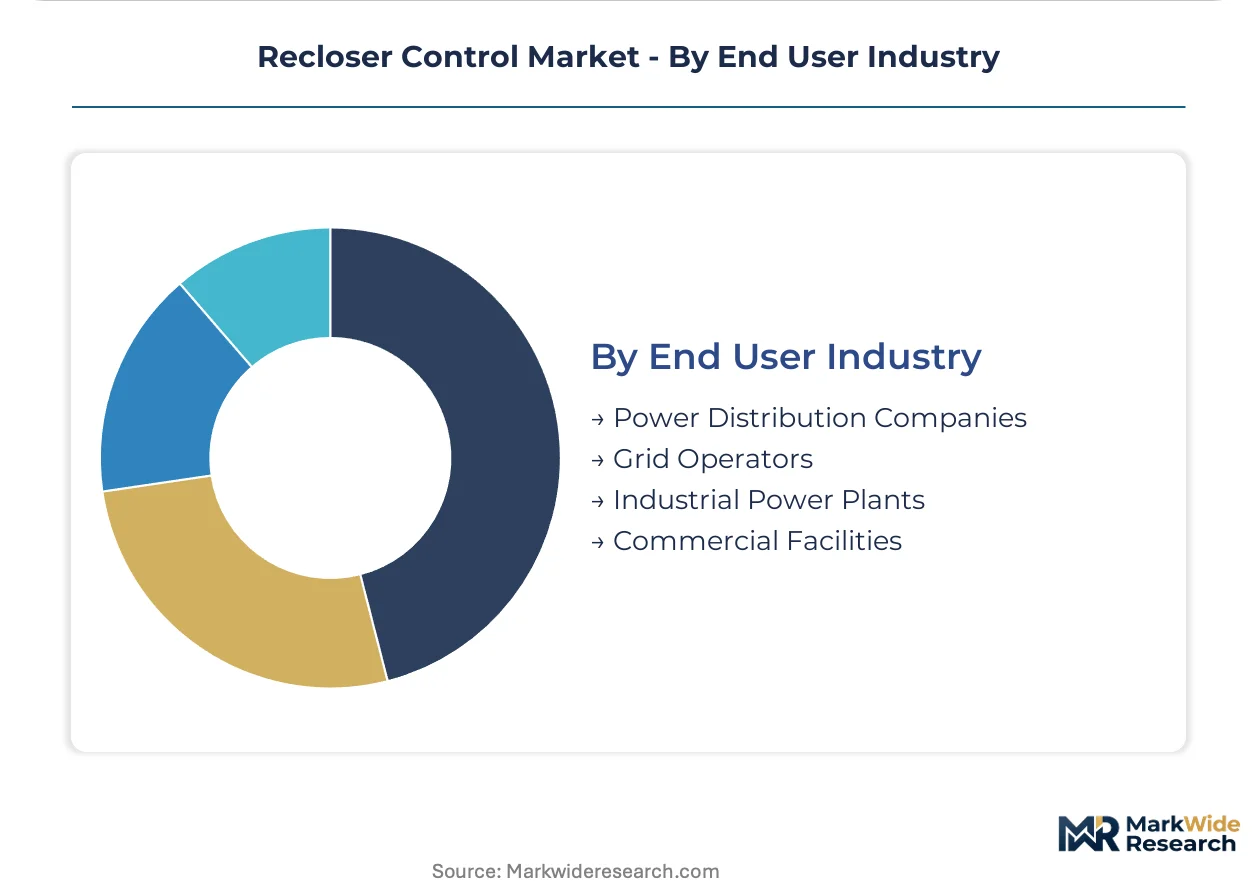
End User Industry:
This segmentation differentiates end-users based on their operational control and scale of electrical infrastructure.
- Power Distribution Companies:These companies are primary purchasers, investing in recloser controls to modernize aging infrastructure, reduce transmission and distribution losses, and improve service reliability for their customer bases.
- Grid Operators:Responsible for the overall stability and management of electrical grids, grid operators increasingly specify advanced recloser controls that integrate with broader digital grid management platforms and support resilience against threats.
- Industrial Power Plants:These facilities utilize recloser controls for internal network protection, ensuring continuous power supply to critical industrial processes and safeguarding high-value equipment.
- Commercial Facilities:Large commercial complexes and campuses deploy recloser controls to enhance localized power quality, minimize downtime, and protect their electrical infrastructure from faults.
Power Distribution Companies collectively represent the primary demand, with Grid Operators increasingly influencing advanced control specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metropolitan area exemplifies concentrated demand for advanced recloser controls, driven by extensive utility infrastructure upgrades and smart grid initiatives. This regional activity reflects a broader global trend where specific urban and industrial centers lead in adopting new grid technologies. Localized investments in grid resilience and renewable energy integration further stimulate market expansion across diverse geographies.
United States
The United States sees significant demand for recloser controls as electric utilities upgrade aging distribution networks and enhance grid reliability. FERC orders compel investments in technologies that reduce outage durations. California's Silicon Valley drives smart grid innovation, requiring controls with sophisticated communication protocols for automated network management.
Germany
Germany's energy transition initiatives and high renewable energy penetration drive demand for recloser controls that ensure grid stability. The EU Green Deal encourages efficient grid management and modernization. Bavaria's industrial centers invest in advanced grid automation, integrating recloser controls for robust protection and control functions.
India
National initiatives in India aimed at upgrading aging power distribution infrastructure create sustained demand for microprocessor-based recloser controls. The country's focus on reducing transmission and distribution losses directly benefits recloser control adoption. Maharashtra's energy sector drives demand for microprocessor-based controls to enhance service reliability.
China
China's dual carbon goals push for efficient grid management and substantial renewable energy integration, boosting demand for advanced recloser controls. Government policies support smart grid development and grid resilience against evolving threats. The Yangtze River Delta region implements advanced grid automation projects, requiring intelligent control systems.
Vietnam
Rapid economic growth and extensive electrification programs in Vietnam present an underpenetrated market for advanced grid automation technologies. Government-led infrastructure development plans prioritize modernizing the power distribution network. Hanoi and Ho Chi Minh City drive infrastructure upgrades, integrating recloser controls for improved grid performance.
Recloser Control Market Key Industry Players
Premium-margin players sit above commodity-margin players across technological sophistication and service integration within the recloser control market. The competitive landscape is tiered, with global conglomerates offering comprehensive solutions alongside specialized firms providing application-specific devices. Strategic partnerships for smart grid integration and portfolio diversification into software services represent dominant competitive moves.
On the premium-tier vector, Schneider Electric, a global technology conglomerate, exemplifies leadership in advanced analytics and communication capabilities. Siemens, another industrial powerhouse, represents companies differentiating through integration with broader digital grid management platforms. NOJA Power Switchgear, an Australian-based specialist, anchors the segment for robust, application-specific solutions designed for challenging environments.
| Leading Market Players |
|---|
| ABB |
| Eaton |
| Schneider Electric |
| Siemens |
| General Electric |
| NOJA Power Switchgear |
| S&C Electric Company |
| Hubbell |
| G&W Electric |
Cost & Logistics Intelligence
Global technology conglomerates and specialized firms influence recloser control supply behavior, directly impacting pricing discipline across the market. Their investment in R&D for advanced features and robust manufacturing capabilities shapes the cost structure and market value of these critical grid assets.
Pricing Analysis
Pricing for recloser controls anchors on the enhanced grid reliability and uptime they deliver to electrical distribution networks. The market employs a hybrid pricing model, combining per-unit transactional sales for hardware with subscription-based models for advanced software features like fault location diagnostics. Price differentiation stems from the level of integrated analytics and communication capabilities, alongside adherence to stringent standards such as IEC 62443 certification. Pricing pressure stems from the significant upfront investment required by utilities for new installations, particularly when replacing legacy systems. Power Distribution Companies and Electric Utilities are generally price-sensitive regarding large-scale upgrades, while specialized applications like Smart Grids prioritize advanced functionality over initial cost.
Supply Chain Analysis
Logistics and freight costs are significant considerations for recloser control manufacturers, particularly for high-value components sourced globally. The supply chain for recloser controls draws heavily from a concentrated global market for specific microprocessors and power electronic components, primarily from countries like China and Taiwan. Raw material dependencies include specialized semiconductors and high-grade electrical insulation materials. Component supply chain risks represent a structural vulnerability, exposing manufacturers to potential disruptions and price volatility. Distribution runs primarily through direct sales channels to Electric Utilities and Power Distribution Companies, often supported by system integrators for complex grid modernization projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recloser control market presents a supply-constrained story, with a deficit of power systems engineers and technicians creating a bottleneck for effective deployment and maintenance, thereby propping pricing for advanced services.
For Market Incumbents: Lock in long-term contracts with major Electric Utilities by emphasizing advanced cybersecurity features compliant with NIS Directive mandates. Invest in R&D for AI and machine learning algorithms to offer predictive maintenance and pre-emptive fault detection capabilities, countering the threat of specialized software-centric entrants. Deepen integration with broader digital grid management platforms to offer comprehensive solutions, reinforcing market position against niche competitors.
For New Entrants and Emerging Players: Launch via specialized, application-specific solutions tailored for microgrid management or challenging environmental conditions, particularly in underpenetrated markets like Southeast Asia. Target the Smart Grids application segment, which represents the fastest-growing demand for sophisticated communication protocols and on-device intelligence. Focus go-to-market strategies on demonstrating superior interoperability with existing grid infrastructure through adherence to IEC 61850 standards.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized firms with strong intellectual property in AI/ML-driven grid analytics or robust cybersecurity features in countries undergoing rapid grid modernization. The long-term viability for recloser controls over the next 5-10 years is strong due to persistent grid modernization and renewable energy integration needs. Watch for regulatory shifts, such as new FERC orders or EU Green Deal initiatives, as an inflection indicator for increased utility investment in advanced control systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in AI/ML Integration | Enhances predictive maintenance capabilities for Electric Utilities managing complex grids. |
| Expand Cybersecurity Offerings | Secures critical network access points against evolving cyber threats for Grid Operators. |
| Develop Microgrid-Specific Controls | Supports localized power resilience and islanding capabilities for Commercial Facilities. |
| Strengthen Supply Chain Resilience | Mitigates risks from component supply disruptions for recloser control manufacturers. |
| Target Southeast Asia Market Entry | Captures demand from rapid economic growth and electrification programs in Vietnam. |
Research Approach
Document review covered IEC standards documents, FERC orders, national energy agency reports, and company annual reports, complemented by interviews with industry stakeholders. Primary interviews were conducted with utility engineers, grid operators, recloser control manufacturers, and distribution network managers. This approach enabled a robust understanding of market dynamics, segment-specific trends, and technological advancements, validated through bottom-up and top-down triangulation processes.
The analytical framework cross-referenced historical market performance against expert panel input to project future growth across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional grid modernization stage. Compound annual growth rates were derived through a proprietary model incorporating macroeconomic indicators and sector-specific growth drivers. Grid modernization budgets and renewable energy deployment targets served as key industry-specific forecast inputs.
Cybersecurity threats, component supply volatility, and regulatory policy changes are the dominant revision risks for market forecasts. These forecasts reflect assumptions regarding sustained investment in grid modernization and renewable energy integration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Colombia Power Market
Power
Power Capacitors Market
Power
Middle-East and Africa Power Rental Market
Power
Oxy-Hydrogen Generators Market
Power
Single-Phase Microinverter Market
Power
Saudi Arabia Power Market
Power
China Power Market
Power
Asia-Pacific Microturbine Market
Power
Statcom Market
Power
Modified Sine Wave Home Inverters Market
Power
Vietnam Power Market
Power
Compact Substation Market
Power
Wireless Power Receiver Market
Power
Denmark Power Market
Power
Japan Uninterrupted Power Supply (UPS) Market
Power
Europe Frequency Converter Market