
 Japan Uninterrupted Power Supply (UPS) Market | 2026-2036
Japan Uninterrupted Power Supply (UPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Uninterrupted Power Supply (UPS) Market Foresight
Japan's amended Energy Conservation Act is consolidating compliance costs for UPS suppliers serving industrial and data center clients. Schneider Electric SE leverages its global service network to sustain large-scale deployment capabilities across Honshu. Mitsubishi Electric Corporation anchors domestic manufacturing through in-house power semiconductor production. Omron Corporation differentiates via precision control integration in factory automation UPS applications.
A Japan Uninterrupted Power Supply is an electrical apparatus that conditions incoming AC power and delivers seamless backup energy through battery or kinetic storage when utility feeds drop below 85% of nominal voltage or fail entirely; units range from sub-1kVA desktop units to multi-megawatt parallel systems for semiconductor fabrication. Online UPS configurations dominate mission-critical deployments because their double-conversion architecture eliminates transfer-time gaps that disrupt server operations. Lithium-ion battery technology is displacing lead-acid alternatives in data center installations where floor space constraints and cycle-life economics favor higher energy density. Critical Power Systems applications command premium pricing due to zero-tolerance uptime requirements in financial clearing and medical imaging environments.
METI enforces efficiency benchmarks under the Top Runner program, while JIS standards govern electrical safety and electromagnetic compatibility for UPS equipment sold domestically. These frameworks compel manufacturers to redesign inverter topologies and thermal management systems to maintain market access. PMDA guidelines for healthcare power continuity create additional certification layers for suppliers targeting hospital infrastructure. Stakeholders must weigh battery chemistry transitions against existing service infrastructure and recycling obligations as regulatory thresholds tighten.
Market Dynamics
Japan's UPS market is restructuring around lithium-ion battery chemistry transitions and METI's tightening efficiency mandates, which are forcing inverter redesigns and compressing legacy lead-acid service margins.
Growth Catalysts
- Top Runner efficiency mandates:METI's escalating standby power benchmarks compel data center operators to upgrade legacy UPS systems, creating replacement cycles across Greater Tokyo hyperscale facilities.
- Semiconductor fabrication expansion:Kyushu and Tohoku cleanroom construction is driving procurement of multi-megawatt parallel UPS configurations with zero-transfer-time specifications.
- Cloud computing workload densification:Rack power densities exceeding 30kW per cabinet in Osaka and Nagoya facilities are necessitating modular UPS architectures with scalable battery strings.
Market Restraints
- Lithium supply concentration:Cathode material dependence on East Asian processing networks exposes Japanese UPS manufacturers to input cost volatility and geopolitical supply disruptions.
- Power semiconductor bottlenecks:SiC and GaN wafer fabrication capacity constraints limit inverter switching frequency improvements for high-efficiency designs.
- Lead-acid infrastructure lock-in:Existing service technician networks and recycling obligations tied to VRLA batteries create switching friction for lithium-ion adoption.
Strategic Opportunities
- Healthcare infrastructure electrification:PMDA guidelines for medical imaging power continuity are opening certified UPS segments in regional hospital networks beyond Tokyo.
- Edge computing distributed architectures:Prefectural 5G base station rollouts are creating demand for compact outdoor-rated UPS units with extended temperature tolerance.
- Factory automation integration:Precision control convergence with robotics power quality requirements is expanding UPS attach rates in automotive and electronics manufacturing.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent for high-frequency inverter design and thermal management is concentrated among legacy industrial equipment suppliers.
- JIS certification timeline compression:Electromagnetic compatibility testing queues and documentation requirements are extending product launch cycles for new topologies.
- Legacy SCADA integration complexity:Brownfield manufacturing facilities require protocol translation layers between modern UPS monitoring systems and existing building management infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Uninterrupted Power Supply (UPS) Market |
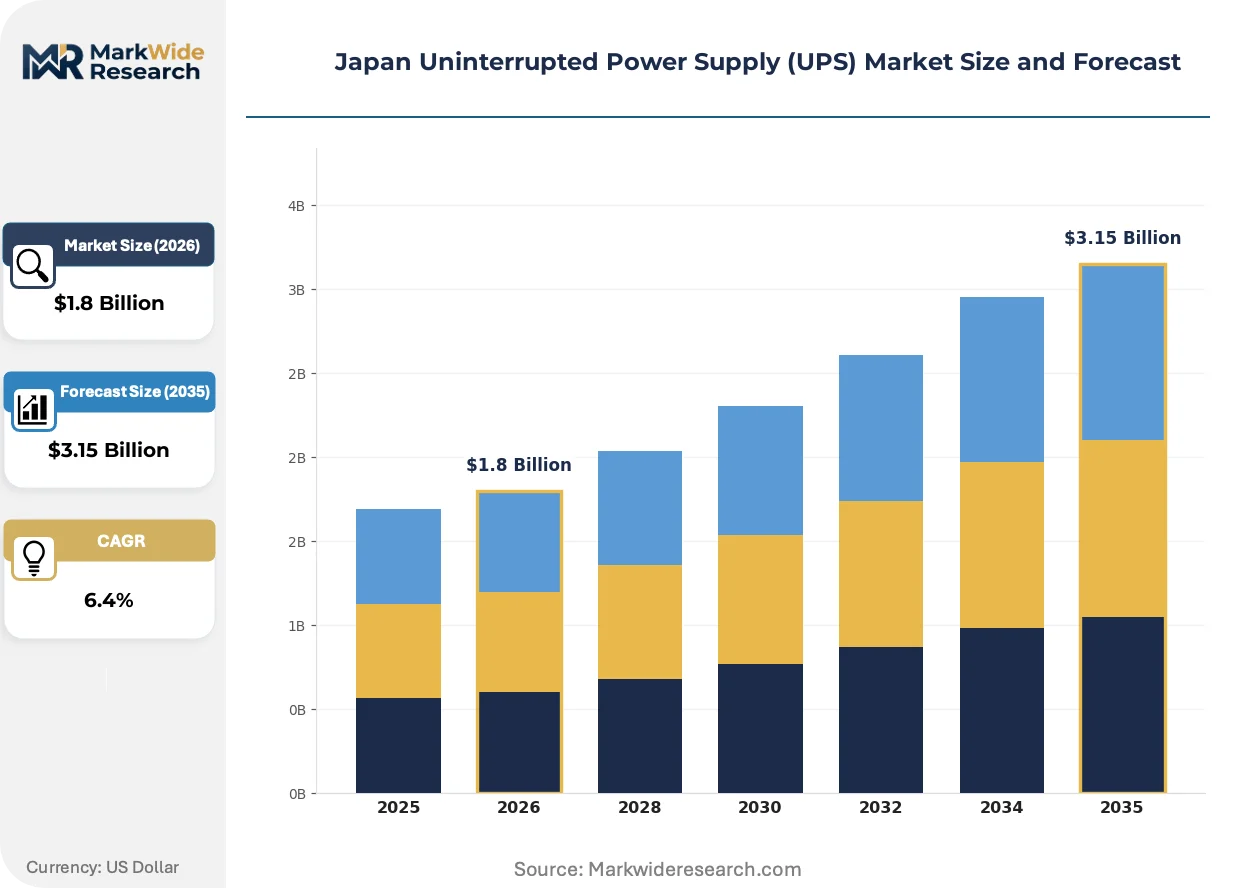
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standby UPS, Online UPS, Line-Interactive UPS, Delta Conversion UPS End User: Data Centers, Industrial Facilities, Healthcare Organizations, Telecommunications Technology: Lead-Acid Batteries, Lithium-Ion Batteries, Flywheel Energy Storage, Supercapacitors Application: Telecom Infrastructure, IT Equipment, Retail Operations, Critical Power Systems |
| Companies Covered | Schneider Electric SE, Omron Corporation, Mitsubishi Electric Corporation, ABB Ltd, Yaskawa Electric Corporation, Fuji Electric Co., Ltd., Sanyo Denki Co., Ltd., Delta Electronics Inc., Toshiba Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Uninterrupted Power Supply (UPS) Market Shifts & Advancements
Lithium-ion battery chemistry is actively restructuring Japan's UPS procurement calculus, compressing total cost-of-ownership models and enabling footprint reductions that reshape facility power architecture planning.
Modular UPS architectures with decentralized power modules are decentralizing traditional monolithic system designs. Data center operators in Saitama and Chiba prefectures are deploying 50-250kW frame-based units that allow incremental capacity additions without full system shutdowns. This topology is decentralizing capital deployment patterns and reducing stranded asset risk for colocation providers with uncertain tenant growth trajectories.
METI's 2024 amendments to the Energy Conservation Act are mandating standby loss thresholds that eliminate conventional double-conversion inefficiencies. Equipment suppliers must now integrate silicon carbide semiconductors and adaptive eco-mode algorithms to maintain market access. Medical imaging and financial clearing segments are absorbing premium pricing for certified high-efficiency configurations that satisfy both PMDA continuity requirements and Top Runner benchmarks.
Facility managers are consolidating vendor relationships through lifecycle service bundling that unbundles traditional equipment-only procurement. Tokyo-based hyperscale operators are negotiating ten-year total-cost contracts encompassing battery replacement, thermal management, and remote monitoring. This restructuring is visible in RFP specifications that weight service capability scores above capital expenditure line items.
Japan Uninterrupted Power Supply (UPS) Market Segmentation
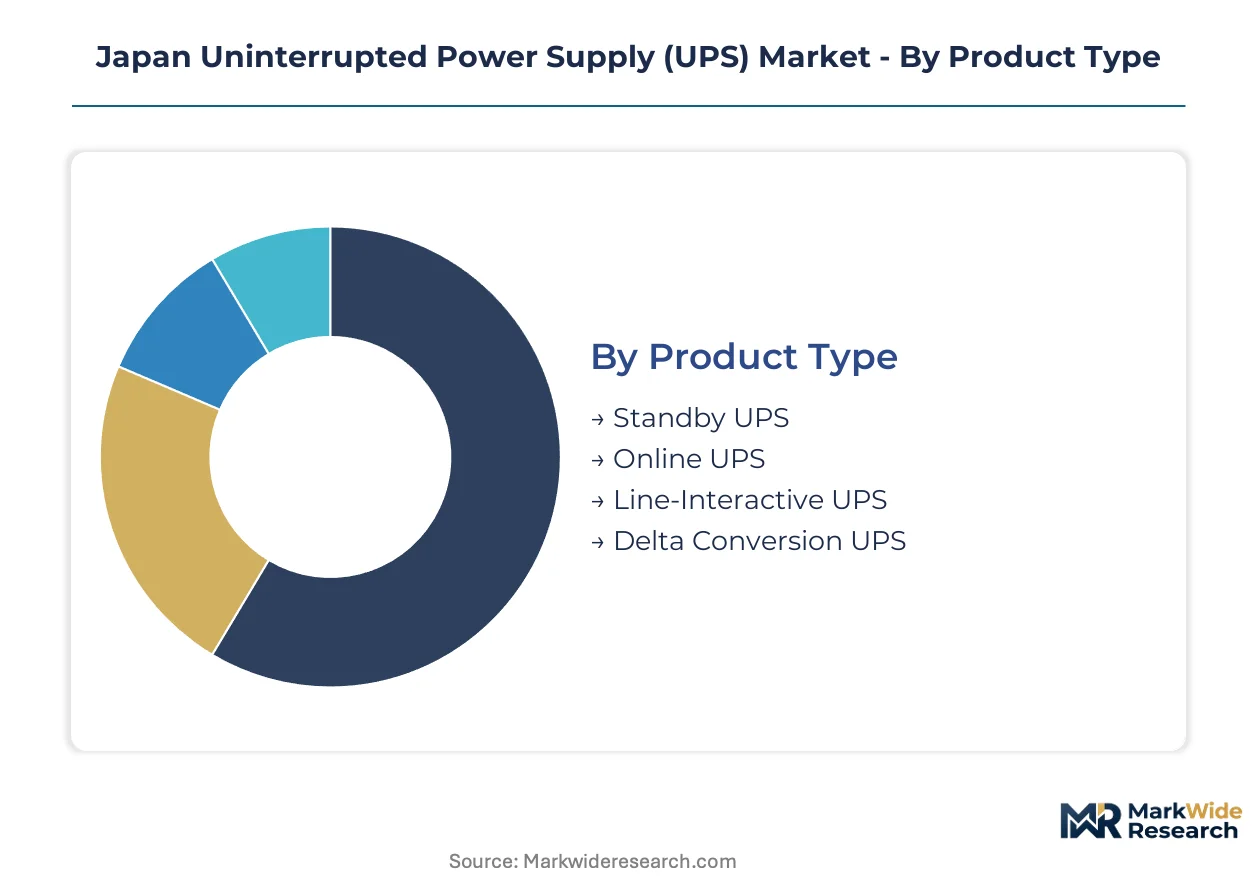
UPS procurement in Japan fragments across power architecture specifications, end-use criticality thresholds, and energy storage chemistries. Facility managers align topology selections with METI efficiency mandates and PMDA continuity requirements. Each segmentation axis carries distinct certification burdens and lifecycle cost profiles that reshape vendor positioning.
Product Type:
Double-conversion architectures dominate mission-critical deployments where transfer-time gaps disrupt semiconductor fabrication and financial clearing operations.
- Standby UPS:Basic offline units switch to battery during voltage sags below 85% nominal, introducing 4-8 millisecond transfer delays. Small offices in regional prefectures deploy these for desktop protection where downtime tolerance exceeds server-grade requirements.
- Online UPS:Continuous AC-DC-AC conversion eliminates transfer gaps entirely, making this topology mandatory for hyperscale data centers across Greater Tokyo. METI's standby loss thresholds are forcing silicon carbide inverter redesigns to maintain certification access.
- Line-Interactive UPS:Voltage regulation through tap-switching transformers handles moderate sags without battery drainage. Retail banking branches in Osaka and Nagoya favor these for ATM networks with intermediate uptime requirements.
- Delta Conversion UPS:Partial power processing through delta transformers reduces conversion losses while maintaining online-mode protection. Industrial automation lines in automotive manufacturing clusters are testing these for robotics power quality compliance.
Online UPS leads on scale; Delta Conversion UPS leads on momentum.
End User:
Facility criticality tiers determine procurement budgets and certification stringency across Japan's UPS installed base.
- Data Centers:Hyperscale operators in Saitama and Chiba prefectures demand modular 50-250kW frame systems with scalable battery strings. Rack power densities exceeding 30kW per cabinet are compressing footprint requirements and accelerating lithium-ion transitions.
- Industrial Facilities:Semiconductor cleanrooms in Kyushu and Tohoku require multi-megawatt parallel configurations with zero-transfer-time specifications. Power quality sensitivity in lithography equipment tolerates no voltage waveform distortion.
- Healthcare Organizations:PMDA guidelines for MRI and CT continuity create certified segments in regional hospital networks beyond Tokyo. Medical imaging power requirements command premium pricing for double-conversion systems with extended battery autonomy.
- Telecommunications:Prefectural 5G base station rollouts demand compact outdoor-rated units with extended temperature tolerance. NTT and KDDI infrastructure expansions are driving procurement of IP65-enclosure systems for rooftop and pole-mounted installations.
Data Centers anchor procurement volume; Healthcare Organizations are climbing the fastest.
Technology:
Energy storage chemistry selection reshapes total cost-of-ownership calculations and facility power architecture planning.
- Lead-Acid Batteries:Mature VRLA technology dominates legacy installed base with established recycling infrastructure and technician training networks. Floor space abundance in older industrial facilities sustains demand despite cycle-life limitations.
- Lithium-Ion Batteries:Higher energy density and 3-5x cycle life compress lifecycle costs for data center operators facing Tokyo real estate constraints. Cathode material dependence on East Asian processing networks introduces supply volatility risks.
- Flywheel Energy Storage:Kinetic storage systems deliver 15-30 seconds of ride-through without chemical degradation, suiting applications with reliable backup generator coverage. Financial clearing floors in central Tokyo deploy these for high-cycling duty.
- Supercapacitors:Ultra-fast charge-discharge cycles handle transient voltage sags in precision manufacturing where millisecond response matters. Electronics assembly lines in Aichi Prefecture integrate these for robotics power quality buffering.
Lead-Acid Batteries retain installed base dominance; Lithium-Ion Batteries gain share fastest.
Application:
Workload characteristics determine topology selection and service bundling requirements across deployment scenarios.
- Telecom Infrastructure:Outdoor-rated systems with wide temperature operating ranges support base station continuity across mountainous terrain and coastal exposure. Remote monitoring capabilities reduce truck-roll frequency for distributed assets.
- IT Equipment:Server-grade power conditioning demands online-mode protection with harmonic filtering for switch-mode power supplies. Colocation providers negotiate ten-year total-cost contracts bundling battery replacement and thermal management.
- Retail Operations:Point-of-sale continuity requirements vary by transaction volume, with flagship stores in Ginza and Shibuya demanding higher-tier protection than convenience store chains.
- Critical Power Systems:Zero-tolerance uptime environments in securities trading and medical imaging absorb premium pricing for certified configurations satisfying both PMDA and Top Runner requirements.
IT Equipment drives procurement scale; Critical Power Systems command margin leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized power electronics engineers cluster in Greater Tokyo and Osaka, anchoring Japan's UPS design capabilities and creating regional differentiation in technical service depth.
Greater Tokyo Area
Hyperscale data center construction in Saitama and Chiba prefectures drives modular UPS procurement with scalable battery architectures. METI's Top Runner efficiency mandates force silicon carbide inverter upgrades across colocation facilities. Financial clearing floors in central Tokyo deploy flywheel systems for high-cycling duty alongside chemical battery backups.
Kansai Region
Osaka and Nagoya manufacturing clusters demand precision power quality for robotics and semiconductor equipment. Factory automation integration expands UPS attach rates in automotive electronics supply chains. JIS electromagnetic compatibility testing facilities in Kyoto create certification bottlenecks for new topology launches.
Kyushu
Semiconductor cleanroom construction in Kumamoto and Fukuoka requires multi-megawatt parallel UPS configurations with zero-transfer-time specifications. TSMC's fab expansion anchors procurement volume for 2025-2027. Local governments offer infrastructure incentives to attract power-sensitive advanced manufacturing.
Tohoku
Industrial recovery programs post-2011 disaster reconstruction prioritize resilient power infrastructure for medical device manufacturing in Miyagi Prefecture. PMDA-certified UPS segments expand in Sendai regional hospital networks. Battery recycling obligations under prefectural environmental codes complicate lithium-ion transitions.
Hokkaido
Cold climate data center projects leverage natural cooling for hyperscale facilities near Sapporo, driving outdoor-rated UPS demand with extended temperature tolerance. Renewable energy intermittency from wind farms necessitates grid-stabilizing battery storage integration. Sparse service technician density increases remote monitoring requirements.
Japan Uninterrupted Power Supply (UPS) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Japan's UPS market, creating tiered procurement options based on service network depth versus technology customization. The vendor base concentrates among electrical equipment manufacturers with captive power semiconductor production or global service infrastructures. Three archetypes dominate: integrated industrial conglomerates with in-house component fabrication, global infrastructure specialists leveraging cross-border service networks, and precision control specialists targeting factory automation niches. Competitive moves center on lifecycle service bundling that unbundles equipment-only procurement, and silicon carbide inverter redesigns to satisfy METI efficiency thresholds.
Within the integrated conglomerate tier, Mitsubishi Electric Corporation and Toshiba Corporation anchor domestic manufacturing capabilities through captive power semiconductor production. Fuji Electric Co., Ltd. occupies a position bridging industrial equipment and energy infrastructure. Among precision control specialists, Omron Corporation and Yaskawa Electric Corporation exemplify factory automation integration strategies. Schneider Electric SE represents global infrastructure specialists leveraging service network scale for hyperscale deployment. Delta Electronics Inc. and Sanyo Denki Co., Ltd. sit within the component-to-systems vertical, while ABB Ltd anchors European-origin industrial electrification expertise in the Japanese market.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Omron Corporation |
| Mitsubishi Electric Corporation |
| ABB Ltd |
| Yaskawa Electric Corporation |
| Fuji Electric Co., Ltd. |
| Sanyo Denki Co., Ltd. |
| Delta Electronics Inc. |
| Toshiba Corporation |
| Others |
Supply & Pricing Matrix
Silicon carbide inverter redesigns for METI compliance are compressing manufacturing cost curves while concentrating procurement leverage among domestic power semiconductor fabricators. Battery chemistry transitions from lead-acid to lithium-ion are simultaneously reshaping total cost-of-ownership calculations and supplier qualification requirements across Greater Tokyo data center deployments.
Pricing Analysis
Bundled lifecycle service contracts are displacing equipment-only procurement across hyperscale operator RFPs in Saitama and Chiba prefectures. Three-tier pricing structure across premium certified, standard efficiency, and economy standby levels differentiates by JIS electromagnetic compatibility tier and PMDA medical continuity certification. Cost compression in standard-efficiency segments is intensifying because METI's 2024 standby loss thresholds eliminate legacy double-conversion designs. Regional hospital networks beyond Tokyo exhibit highest price sensitivity due to constrained capital budgets, while financial clearing floors absorb premium pricing for zero-transfer-time configurations.
Supply Chain Analysis
JIS certification timelines and electromagnetic compatibility testing queues in Kyoto function as supply-side gating mechanisms for new topology market entry. Cathode material processing concentrates in China and South Korea, exposing Japanese UPS manufacturers to input cost volatility and geopolitical supply disruptions. Silicon carbide and gallium nitride wafers draw from Taiwan, Japan, and USA fabrication networks. Single-source vulnerability in East Asian lithium processing creates structural supply risk. Distribution runs through electrical equipment distributors and direct OEM relationships with hyperscale data center operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
METI's amended Energy Conservation Act functions as a regulatory compounder, mandating standby loss thresholds that force replacement cycles across legacy installed bases and compress service margins for non-compliant suppliers.
For Market Incumbents: Hedge against lithium supply concentration by securing long-term cathode material offtake agreements with South Korean and Japanese processors. Deepen backward integration into captive silicon carbide wafer production to insulate inverter redesign costs from Taiwan foundry bottlenecks. Prioritize certification investment in PMDA medical continuity segments where premium pricing persists.
For New Entrants and Emerging Players: Modular UPS architectures with decentralized power modules offer technology-first wedge positioning against monolithic incumbents. Target prefectural 5G base station rollouts in mountainous terrain where compact outdoor-rated units face limited domestic competition. Pursue factory automation integration partnerships with automotive electronics suppliers in Aichi Prefecture seeking precision power quality compliance.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play lithium-ion battery service specialists lacking silicon carbide inverter capabilities. Long-term viability centers on suppliers with METI-certified high-efficiency topologies and ten-year total-cost contracting relationships with hyperscale operators. Watch for inflection when TSMC's Kumamoto fab expansion accelerates multi-megawatt parallel UPS procurement beyond current capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Redesign | METI Top Runner compliance secures market access for data center and medical segments. |
| Lithium-Ion Battery Service Network Buildout | Ten-year total-cost contracts with hyperscale operators in Saitama reduce customer churn. |
| PMDA Certification Investment | Medical imaging continuity requirements in regional hospitals open premium pricing tiers. |
| Prefectural 5G Infrastructure Partnership | NTT and KDDI base station rollouts create distributed edge computing UPS demand. |
| Factory Automation Integration Development | Robotics power quality convergence in automotive manufacturing expands attach rates. |
Research Methodology
Direct dialogue with data center facility managers, power electronics procurement leads, electrical equipment distributors, and METI regulatory affairs specialists grounded qualitative insights. Secondary validation drew from METI efficiency benchmark publications, JIS standards documentation, PMDA medical device guidelines, and hyperscaler capital expenditure disclosures. Bottom-up and top-down triangulation cross-referenced facility-level procurement patterns against aggregate market sizing.
Bottom-up modeling segmented volume and value across product type, end user, energy storage technology, and application dimensions throughout the forecast period. CAGRs derived from weighted average of historical replacement cycle analysis and projected hyperscale construction pipelines. Key inputs included rack power density trajectories exceeding 30kW per cabinet and lithium-ion cycle-life economics compressing total cost-of-ownership.
The model holds under stable METI regulatory enforcement and continued hyperscale data center construction in Greater Tokyo; deviation in lithium supply chain disruptions or semiconductor fabrication capacity constraints would shift replacement cycle timing. Forecasts reflect documented assumptions regarding efficiency mandate compliance timelines and battery chemistry transition rates. A model refresh is warranted upon material change in METI standby loss threshold amendments or TSMC fab expansion schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Qatar Power Market
Power
India Power Market
Power
Global Marine Power Systems Market
Power
Power Capacitors Market
Power
Asia-Pacific Power Purchase Agreement Market
Power
Water Turbine Market
Power
Europe Microturbine Market
Power
Substation Automation System Market
Power
Electric Arc Furnaces Market
Power
Vietnam Power Market
Power
Residential Portable Inverter Generator Market
Power
Italy Power Market
Power
Rotating Phase Converter Market
Power
North America Microturbine Market
Power
Controllable Shunt Reactor for UHV Market
Power
Asia-Pacific Microturbine Market