
 Colombia Power Market | 2026-2036
Colombia Power Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Power Market Insights
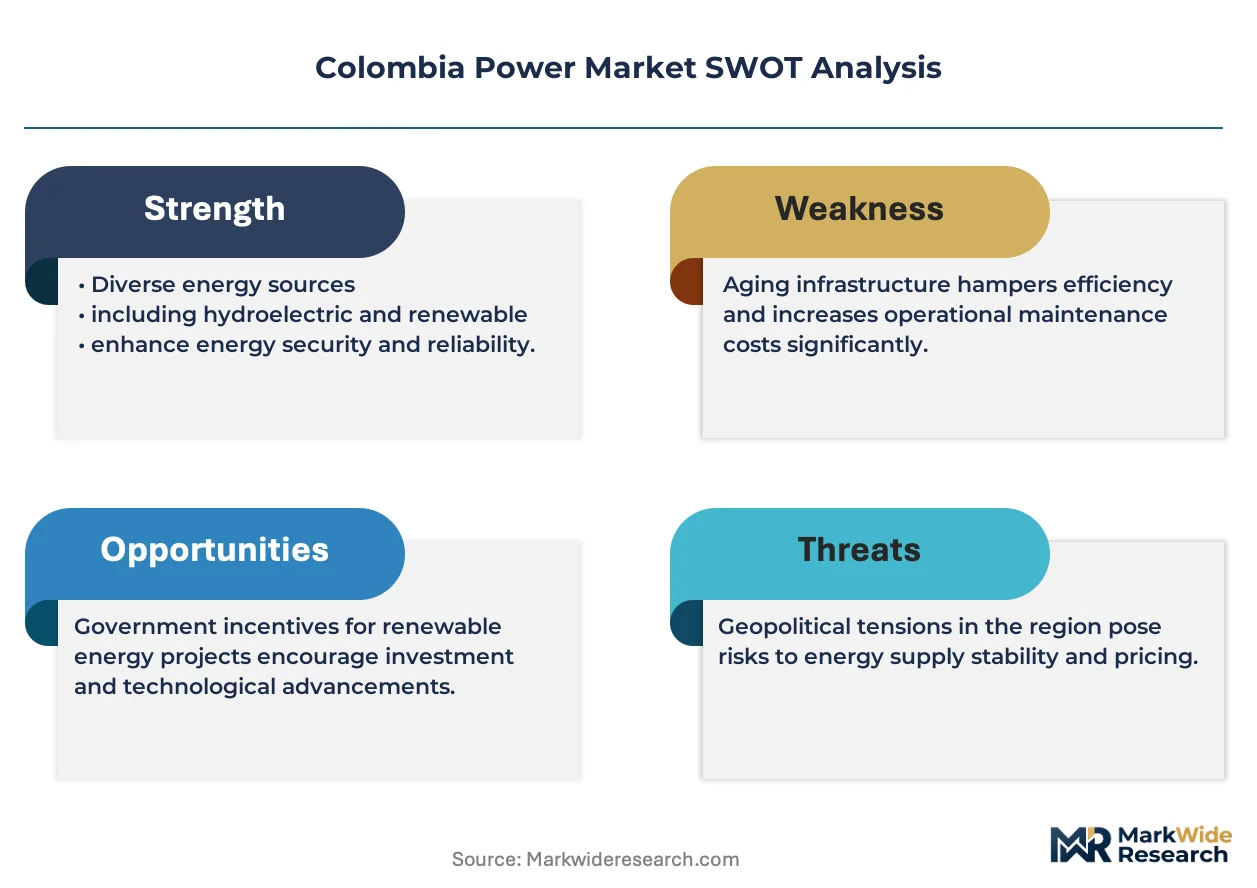
The wholesale electricity market is tilting toward bilateral contracting as large industrial buyers bypass spot volatility. EPM leverages its integrated utility model across generation, transmission, and distribution to sustain captive demand in Antioquia. Enel Colombia anchors its position through renewable-heavy portfolio diversification. Isagen competes primarily through hydropower dominance on the Magdalena River basin.
Colombia power encompasses electricity production, transmission, and distribution infrastructure spanning voltages from 110 kV bulk transfer to 220 V residential delivery, with grid frequency standardized at 60 Hz. Hydropower retains structural leadership, supplying the majority of installed capacity, while solar and wind segments attract the fastest-growing capital allocation. On the service dimension, transmission and distribution capture stable regulated returns, whereas generation and retail face margin compression from auction-based pricing and demand-side competition.
Colombia's Ministry of Mines and Energy, the Energy and Gas Regulatory Commission (CREG), and the National Planning Department shape market access through renewable auction schedules, transmission expansion mandates, and rural electrification targets. CREG's tariff methodologies directly influence distribution utility revenue recovery and investor return expectations. Stakeholders must monitor auction clearing prices and transmission bottleneck resolution in the Caribbean corridor.
Market Dynamics
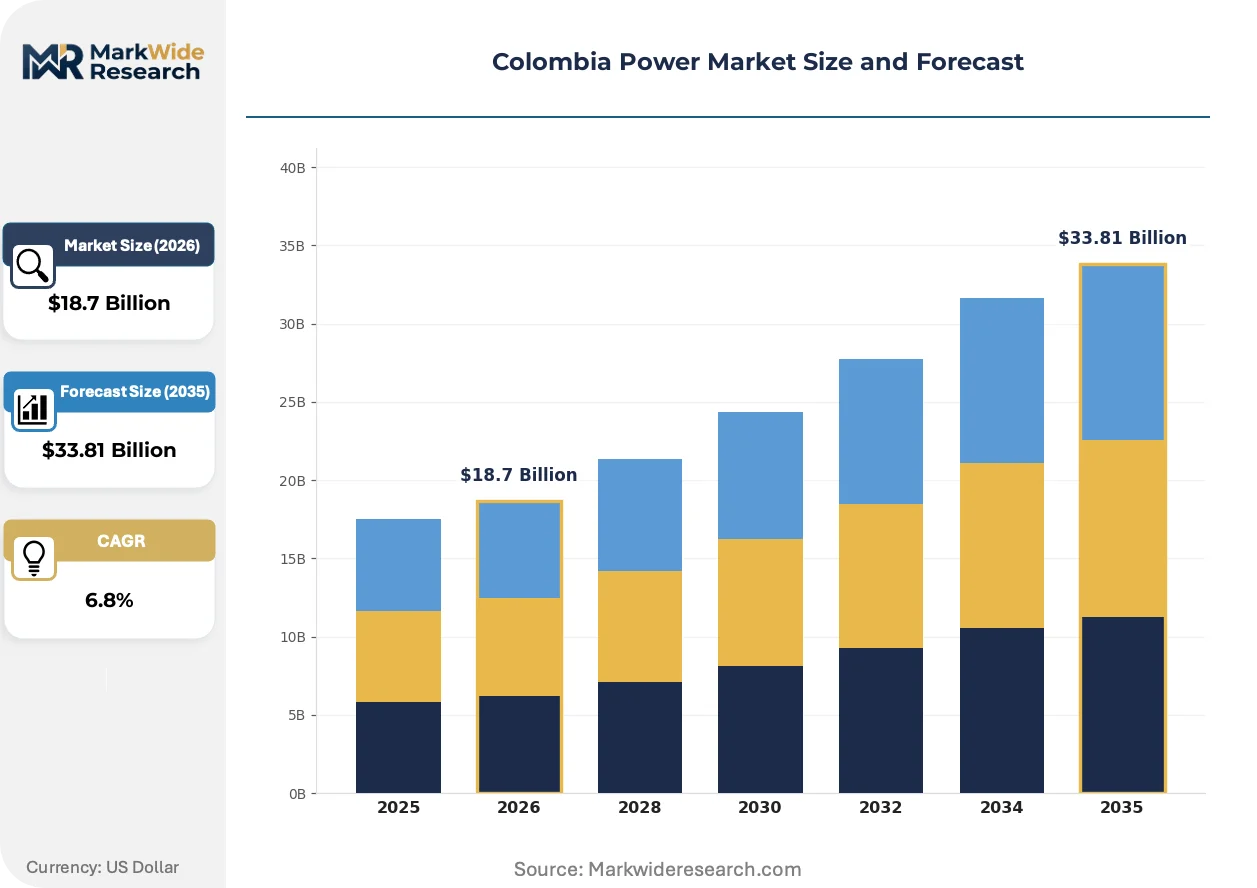
The Colombia power sector is pivoting from hydro-dependent baseload toward auction-driven renewable procurement, with CREG's tariff methodologies compressing generator margins while transmission expansion lags behind generation capacity additions in the Caribbean corridor.
Growth Catalysts
- Renewable Energy Auctions:Colombia's Ministry of Mines and Energy schedules regular capacity auctions that guarantee offtake for solar and wind projects, redirecting capital from conventional thermal development.
- Mining Electrification:Andean mining operations are expanding electricity consumption as copper and gold extraction intensifies, creating captive demand clusters in Antioquia and Boyacá.
- Grid Frequency Stabilization:Battery energy storage systems address intermittency from variable renewable sources, enabling higher penetration of non-hydro generation without compromising 60 Hz grid stability.
Market Restraints
- Hydrological Volatility:El Niño cycles reduce reservoir levels at Isagen's Magdalena River facilities, forcing spot market reliance and price spikes during dry seasons.
- Transmission Bottlenecks:The Caribbean corridor lacks 220 kV and 500 kV trunk lines to evacuate wind power from La Guajira, stranding generation assets.
- Gas Import Dependency:Thermal backup plants rely on imported liquefied natural gas through Cartagena terminals, exposing dispatch costs to dollar-denominated fuel price swings.
Strategic Opportunities
- Rural Electrification Zones:The National Planning Department targets off-grid communities in Chocó and Amazonas for distributed solar microgrids, bypassing transmission buildout requirements.
- Green Hydrogen Piloting:Caribbean wind surplus can feed electrolyzer installations for export-oriented hydrogen production, leveraging Colombia's free trade agreements with industrial importers.
- Bilateral Contracting Expansion:Large industrial buyers in the Bogotá-Cundinamarca corridor are negotiating direct power purchase agreements with renewable developers, bypassing wholesale spot exposure.
Industry Challenges
- Interconnection Queue Congestion:CREG's approval timelines for grid connection studies stretch 18-24 months, delaying project commissioning beyond construction completion.
- Legacy SCADA Integration:Distribution utilities in secondary cities operate aging control systems that resist interoperability with smart metering and distributed energy resource management platforms.
- Land Acquisition Complexity:Renewable developers face community consultation requirements and indigenous territory protocols that extend site permitting by 12-36 months in wind-rich regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Power Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hydropower, Thermal, Wind, Solar End User: Residential, Industrial, Commercial, Agricultural Service Type: Generation, Transmission, Distribution, Retail Technology: Smart Grids, Energy Storage, Biomass, Geothermal |
| Companies Covered | Empresas Públicas de Medellín (EPM), Enel Colombia, Isagen, Celsia, Grupo Energía Bogotá (GEB), AES Colombia, Interconexión Eléctrica (ISA), TermoCandelaria Power Limited, Enel Green Power Colombia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Power Market Trends and Innovations
Digitalization and modular generation architectures are compressing project development cycles while regulatory pressure accelerates decarbonization commitments across the value chain.
String inverter technology paired with bifacial photovoltaic modules is collapsing levelized cost thresholds for utility-scale solar installations in Colombia's northern departments. Project developers in Cesar and La Guajira are deploying these configurations at 150 MW+ scales, eroding the cost advantage that combined-cycle gas turbines held for firm capacity procurement.
CREG's Resolution 030 of 2022 mandates time-of-use tariff structures for regulated customers, forcing distribution utilities to deploy advanced metering infrastructure. EPM and Enel Colombia are retrofitting residential and commercial endpoints in Medellín and Bogotá, converting flat-rate billing into dynamic price signals that flatten peak demand curves.
Corporate buyers in the food processing and cement sectors are abandoning traditional utility procurement for sleeved renewable contracts with hourly matching requirements. This behavior concentrates in Antioquia's industrial belt, where manufacturing associations negotiate aggregated demand pools to improve contract terms with generator portfolios.
Colombia Power Market Segmentation
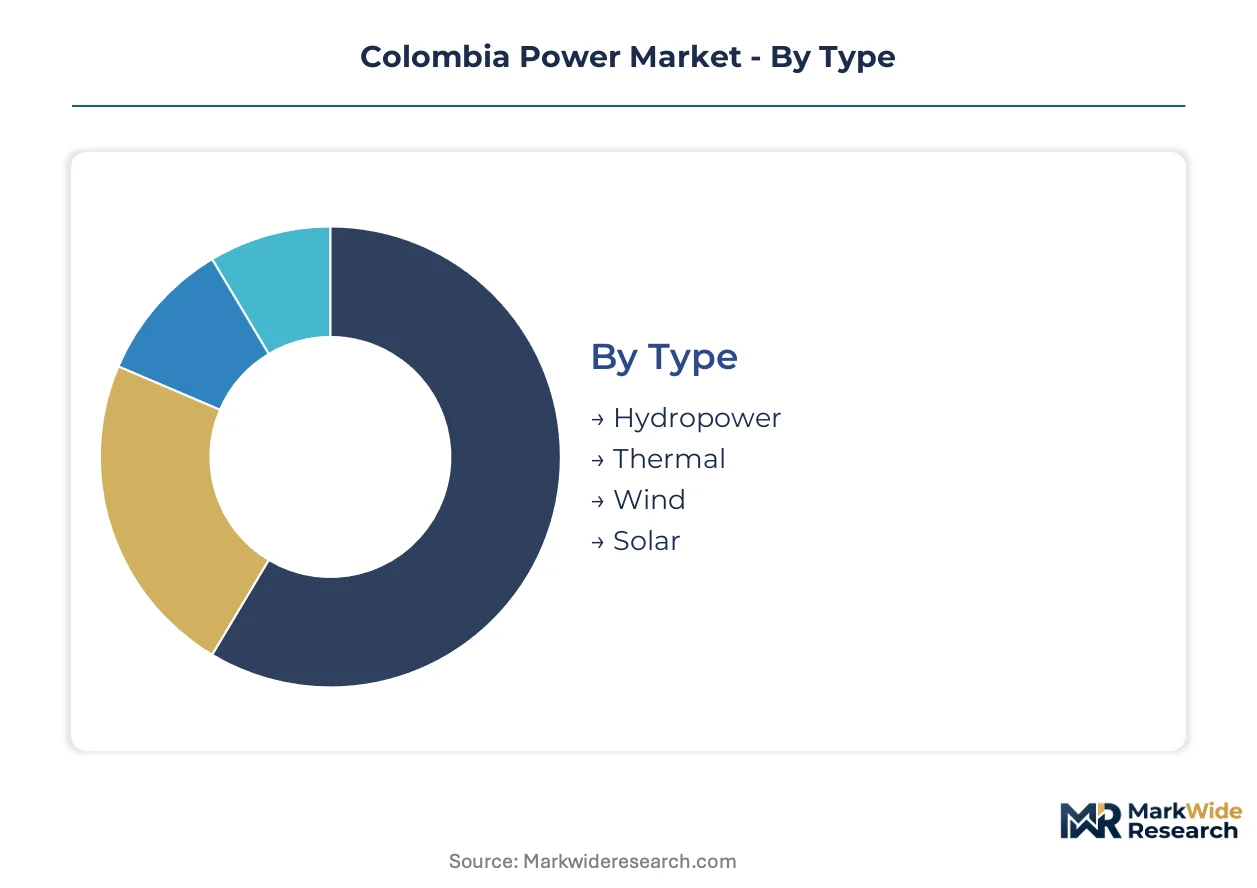
The Colombia power market fragments across generation technologies, end-use sectors, and grid services. Each segmentation layer reveals distinct investment patterns and regulatory exposure that shape competitive positioning.
Type:
The use-case spectrum spans baseload reliability to intermittent renewable supply, with each technology commanding different dispatch priorities and auction eligibility.
- Hydropower:Reservoir and run-of-river facilities provide frequency regulation and spinning reserves for the 60 Hz grid. Isagen's Magdalena River complex anchors capacity in the Andean region, though El Niño cycles force spot market exposure during drought periods.
- Solar:Utility-scale photovoltaic installations in Cesar and La Guajira exploit irradiance levels exceeding 5.5 kWh/m² daily. CREG's renewable auctions guarantee offtake, redirecting capital from conventional thermal projects toward bifacial module deployments.
- Thermal:Combined-cycle and combustion turbine plants provide firm backup capacity, relying on LNG imports through Cartagena terminals.
- Wind:Onshore turbines in the Caribbean corridor face evacuation constraints until 220 kV and 500 kV trunk lines reach La Guajira.
The dominant share belongs to hydropower, while solar is closing the gap fastest.
End User:
Cost tier differentiation separates price-sensitive mass consumption from premium reliability contracts.
- Industrial:Mining operations in Antioquia and Boyacá negotiate bilateral contracts bypassing spot volatility. Copper and gold extraction drives captive demand clusters with 24/7 baseload requirements.
- Residential:CREG's time-of-use tariff mandates force dynamic pricing adoption across Medellín and Bogotá distribution networks.
- Commercial:Food processing and cement manufacturers pursue sleeved renewable contracts with hourly matching requirements.
- Agricultural:Irrigation pumping and cold chain operations in the Cundinamarca corridor face margin pressure from regulated tariff structures.
Industrial offtake commands premium contract terms, while residential volume is expanding most quickly under rural electrification targets.
Service Type:
Margin stability varies sharply between regulated infrastructure and competitive merchant activities.
- Generation:Merchant producers face auction-based price compression and hydrological volatility exposure.
- Transmission:Regulated returns on 110 kV to 500 kV trunk lines provide revenue certainty, though Caribbean corridor buildout lags behind generation additions.
- Distribution:EPM and Enel Colombia capture stable tariff recovery in Antioquia and Bogotá-Cundinamarca, respectively.
- Retail:Competitive supply faces margin erosion as large industrial buyers migrate to direct bilateral contracting.
Transmission and distribution retain the most predictable returns, while generation margins face the steepest compression trajectory.
Technology:
Maturity curves separate proven grid solutions from emerging pilot deployments.
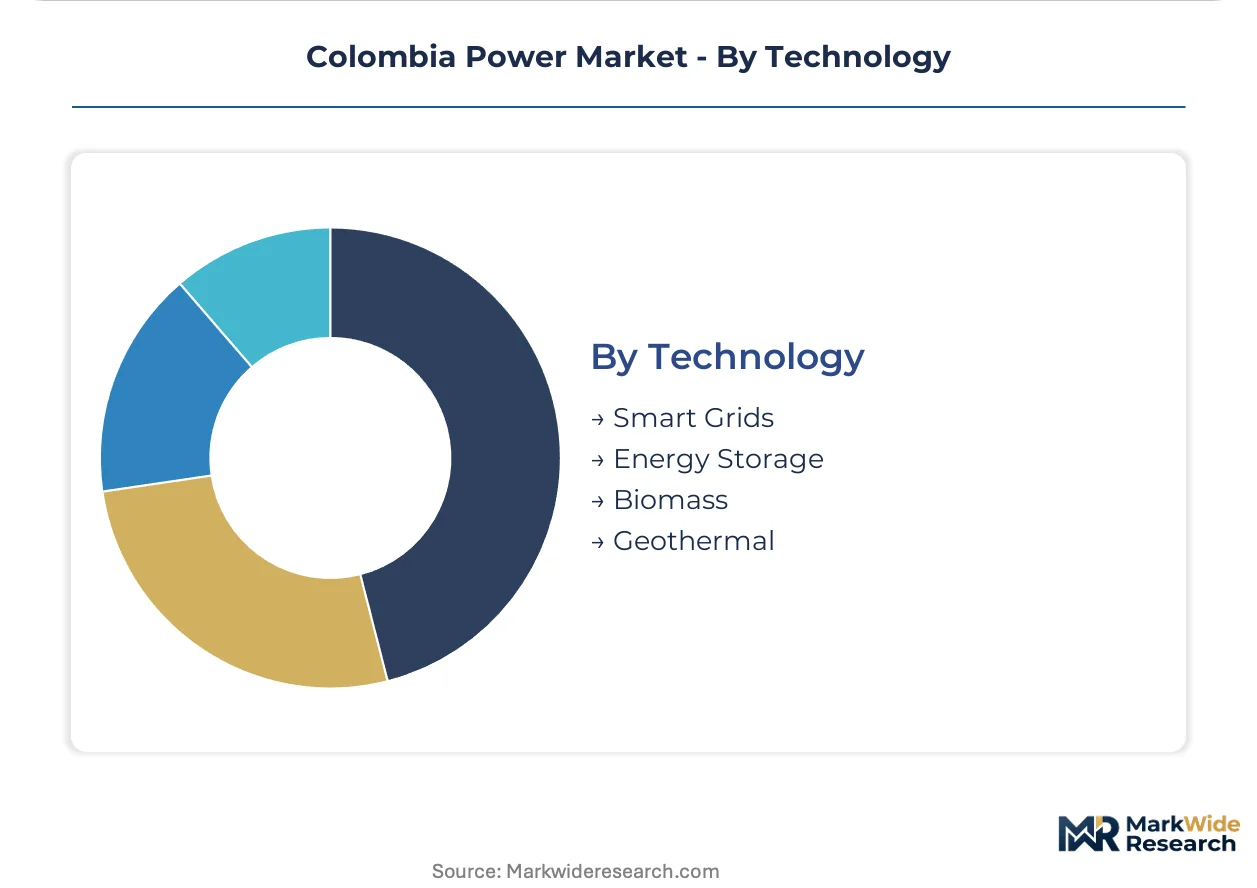
- Smart Grids:Advanced metering infrastructure retrofits convert flat-rate billing to dynamic price signals under CREG Resolution 030.
- Energy Storage:Battery systems address renewable intermittency and stabilize 60 Hz frequency as non-hydro penetration rises.
- Biomass:Agricultural residue and bagasse cofiring offers dispatchable renewable capacity in sugarcane regions.
- Geothermal:Volcanic zone exploration in the Andean belt remains pre-commercial, awaiting resource confirmation drilling.
Smart grid deployment holds the dominant implementation share, while energy storage is gaining share fastest on renewable integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
La Guajira commands pricing premiums for wind generation that Bogotá-Cundinamarca industrial buyers cannot match, creating a geographic arbitrage that transmission bottlenecks sustain. Antioquia's integrated utility model captures value across the vertical chain that Caribbean generators forfeit to evacuation constraints.
Andean Region
Antioquia and Boyacá host expanding copper and gold mining operations that drive 24/7 baseload electricity demand. The Ministry of Mines and Energy channels rural electrification subsidies toward off-grid communities in Chocó. EPM leverages its integrated generation-transmission-distribution position across Medellín and surrounding municipalities.
Caribbean Corridor
La Guajira's wind resource exceeds 9 m/s average velocity, yet 220 kV and 500 kV trunk lines remain insufficient for full evacuation. CREG's transmission expansion mandates prioritize this corridor, though approval timelines lag project completion. Developers cluster near Uribia and Maicao, awaiting interconnection queue resolution.
Bogotá-Cundinamarca
Food processing and cement manufacturers in this industrial belt negotiate sleeved renewable contracts with hourly matching requirements. CREG Resolution 030 mandates time-of-use tariffs that force dynamic pricing adoption. Enel Colombia retrofits advanced metering infrastructure across residential and commercial endpoints.
Magdalena River Basin
Isagen's reservoir complex anchors hydropower capacity, though El Niño cycles force spot market exposure during drought periods. The basin's run-of-river facilities provide frequency regulation for the 60 Hz grid. Celsia operates alongside Isagen, competing for dispatch priority during high-water periods.
Valle del Cauca
Sugarcane bagasse cofiring offers dispatchable renewable capacity for thermal backup needs. The region's agricultural residue supply supports biomass generation that complements variable solar and wind. AES Colombia maintains thermal assets that provide firm capacity when hydrological conditions deteriorate.
Colombia Power Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying generation equipment and grid infrastructure to integrated utilities. The market structure concentrates around three vertically integrated holding groups that span generation, transmission, and regulated distribution. Strategic archetypes include hydro-dominant incumbents with river-basin concessions, renewable-focused developers auctioning solar-wind portfolios, and transmission specialists capturing regulated returns on trunk-line expansion. Competitive moves center on bilateral contracting expansion with industrial offtakers and portfolio diversification beyond hydro-dependent baseload.
Among Colombian integrated utilities, Empresas Públicas de Medellín (EPM) and Grupo Energía Bogotá (GEB) exemplify the multi-utility archetype that captures value across the vertical chain. Enel Colombia occupies a position as the renewable-heavy portfolio diversifier, while Isagen represents hydro-dominant generation anchored to the Magdalena River basin.
| Leading Market Players |
|---|
| Empresas Públicas de Medellín (EPM) |
| Enel Colombia |
| Isagen |
| Celsia |
| Grupo Energía Bogotá (GEB) |
| AES Colombia |
| Interconexión Eléctrica (ISA) |
| TermoCandelaria Power Limited |
| Enel Green Power Colombia |
| Others |
Pricing and Supply Chain Analysis
CREG's tariff methodology exposure determines both auction clearing price spreads and supply chain configuration across generation equipment procurement. The regulator's time-of-use mandates compress margins for standardized capacity while rewarding customized bilateral contracts with industrial offtakers.
Pricing Analysis
The customization-premium spread separates auction-standard renewable supply from sleeved bilateral contracts with hourly matching requirements. Pricing stratifies across premium, standard, and economy tiers based on dispatch priority and contract duration. Cost compression in standardized auction capacity is intensifying because CREG's guaranteed offtake mechanisms attract capital inflows that depress clearing prices. Mining operations in Antioquia exhibit the least price sensitivity due to 24/7 baseload requirements, while agricultural pumping in Cundinamarca faces acute margin pressure from regulated tariff structures.
Supply Chain Analysis
Equipment manufacturing concentration rests on Chinese and South Korean suppliers for photovoltaic modules and inverters, with Spanish and German firms dominating grid infrastructure. Raw material dependencies include polysilicon, rare earth magnets for turbines, and copper for transmission cabling. Single-source vulnerability concentrates in lithium-ion battery cells for grid stabilization projects. Distribution runs through EPC contractors that bundle engineering, procurement, and construction services for utility-scale developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities concentrate in advanced metering infrastructure retrofits and energy management software subscriptions, both expanding faster than generation hardware deployment. The recurring-revenue layer from dynamic pricing platforms and demand-response aggregation commands superior margin stability.
For Market Incumbents: Harden bilateral contracting relationships with Antioquia mining clusters to defend against renewable-focused developers auctioning solar-wind portfolios. Anchor captive demand through integrated utility models spanning generation, transmission, and distribution. Prioritize certification investment in CREG's interconnection queue to accelerate project commissioning timelines. For New Entrants and Emerging Players: Caribbean corridor wind projects awaiting 220 kV and 500 kV trunk line completion represent the most penetrable entry point for independent power producers. Rural electrification zones in Chocó and Amazonas offer distributed solar microgrid deployment with bypassed transmission requirements. Pursue aggregated demand pool negotiations with manufacturing associations in Bogotá-Cundinamarca as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a transmission-constrained phase that favors vertically integrated holding groups with captive distribution networks. Long-term viability over the next decade hinges on portfolio diversification beyond hydro-dependent baseload exposure. Acquisition targets should demonstrate renewable auction track records and bilateral contract backlogs. Watch CREG's interconnection queue resolution velocity as the primary inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Expansion | Direct bilateral contracts with mining operations in Antioquia lock in 24/7 baseload offtake. |
| Transmission Capacity Buildout | 220 kV and 500 kV trunk lines in the Caribbean corridor unlock stranded wind assets in La Guajira. |
| Advanced Metering Infrastructure Deployment | EPM and Enel Colombia retrofit Medellín and Bogotá endpoints under CREG Resolution 030 mandates. |
| Energy Storage Integration | Battery systems address renewable intermittency and stabilize 60 Hz frequency regulation. |
| Green Certification Program | Corporate buyers in food processing and cement sectors demand hourly-matched renewable supply. |
Research Methodology
A standing panel of utility planning officers, IPP project developers, EPC contractors, and grid operators provided ongoing calibration across primary interviews and secondary validation. Bottom-up project development databases and top-down regulatory filings from Colombia's Ministry of Mines and Energy, CREG resolutions, and National Planning Department rural electrification targets were triangulated. Trade data from customs records and interconnection queue filings supplemented field intelligence.
Scenario-bracketing framed analytical outputs across the projection horizon, with segmentation modeled by fuel source, generation capacity tier, project scale, and regional grid type. CAGRs were derived from auction clearing price trajectories, transmission expansion timelines, and mining electrification demand curves. Hydrological volatility indices and El Niño cycle patterns informed capacity factor assumptions for Magdalena River basin facilities.
Practitioners should monitor CREG auction schedules, interconnection queue resolution velocity, and Caribbean corridor transmission commissioning for early signals of forecast revision. Quarterly review of auction clearing prices, hydrological reservoir levels, and bilateral contract announcement volume is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Substation Automation System Market
Power
Existent Gum Steam Generator Market
Power
Asia-Pacific Package Substation Market
Power
Kuwait Power Market
Power
Spain Power Market
Power
Wind Alarm Controller Market
Power
Green UPS Market
Power
China Power Market
Power
Denmark Power Market
Power
Solar UPS Market
Power
Asia-Pacific Alternating Current (AC) Drive Market
Power
Power Rental Market
Power
Brazil Power Market
Power
Asia-Pacific Microturbine Market
Power
Electric Power Sports Market
Power
Water Turbine Market