
 China Power Market | 2026-2036
China Power Market Size, Share, and Industry Trends Forecast 2026-2036
China Power Market Analysis
Industrial buyer concentration is broadening as steelmakers and petrochemical complexes pool procurement through provincial energy trading platforms. State Grid Corporation of China leverages its ultra-high voltage transmission monopoly to anchor cross-province power allocation. China Energy Investment Corp sustains the largest thermal fleet while navigating coal capacity controls. China Three Gorges Corporation dominates hydroelectric generation and extends into Yangtze River basin pumped-storage development.
China power encompasses electricity generation, transmission, and distribution infrastructure spanning thermal plants above 600 MW supercritical ratings, hydroelectric dams with Francis turbine configurations, and grid-connected photovoltaic arrays. Its primary purpose is converting primary energy into alternating current for industrial motor drives, residential cooling loads, and commercial facility operations. Thermal generation retains the largest installed base though margin pools are shifting toward grid services as frequency regulation contracts expand. Wind and solar segments are capturing the fastest capacity additions driven by coastal offshore zones and western desert solar parks. Hydroelectric occupies a mature position with limited greenfield sites remaining in southwestern canyon terrain.
MIIT governs power equipment manufacturing standards while MEE enforces emissions intensity caps under dual carbon targets, tightening coal plant utilization permits and accelerating renewable portfolio obligations. GB standards mandate grid-code compliance for inverter-connected resources, shaping technology procurement across project developers. Stakeholders must monitor how provincial carbon accounting rules interact with national dispatch reforms to anticipate merit-order shifts between baseload thermal and variable renewable assets.
Market Dynamics
Beijing's dual carbon mandates are compressing coal plant dispatch priority while accelerating renewable portfolio obligations, forcing asset owners to reconfigure generation mixes and secure grid service contracts to preserve margin pools.
Growth Catalysts
- Steelmaker electrification:Heavy industrial complexes in Hebei and Jiangsu provinces are replacing coal-fired furnaces with electric arc systems, pulling baseload demand onto provincial grids and expanding peak shaving requirements.
- MIIT inverter standards:Revised GB grid-code compliance rules for utility-scale photovoltaic arrays are standardizing frequency response capabilities, enabling broader renewable participation in ancillary service markets.
- Coastal offshore wind clusters:Turbine deployment along Fujian and Guangdong shorelines is concentrating generation capacity within ultra-high voltage transmission reach of Yangtze River Delta load centers.
Market Restraints
- Polysilicon supply concentration:Xinjiang-based ingot production dominates photovoltaic upstream material flows, creating geographic concentration risk for western solar park developers dependent on long-haul logistics.
- Pumped-storage site scarcity:Southwestern canyon terrain suitable for reservoir pairing is approaching saturation, limiting grid-scale storage additions needed to balance variable renewable output.
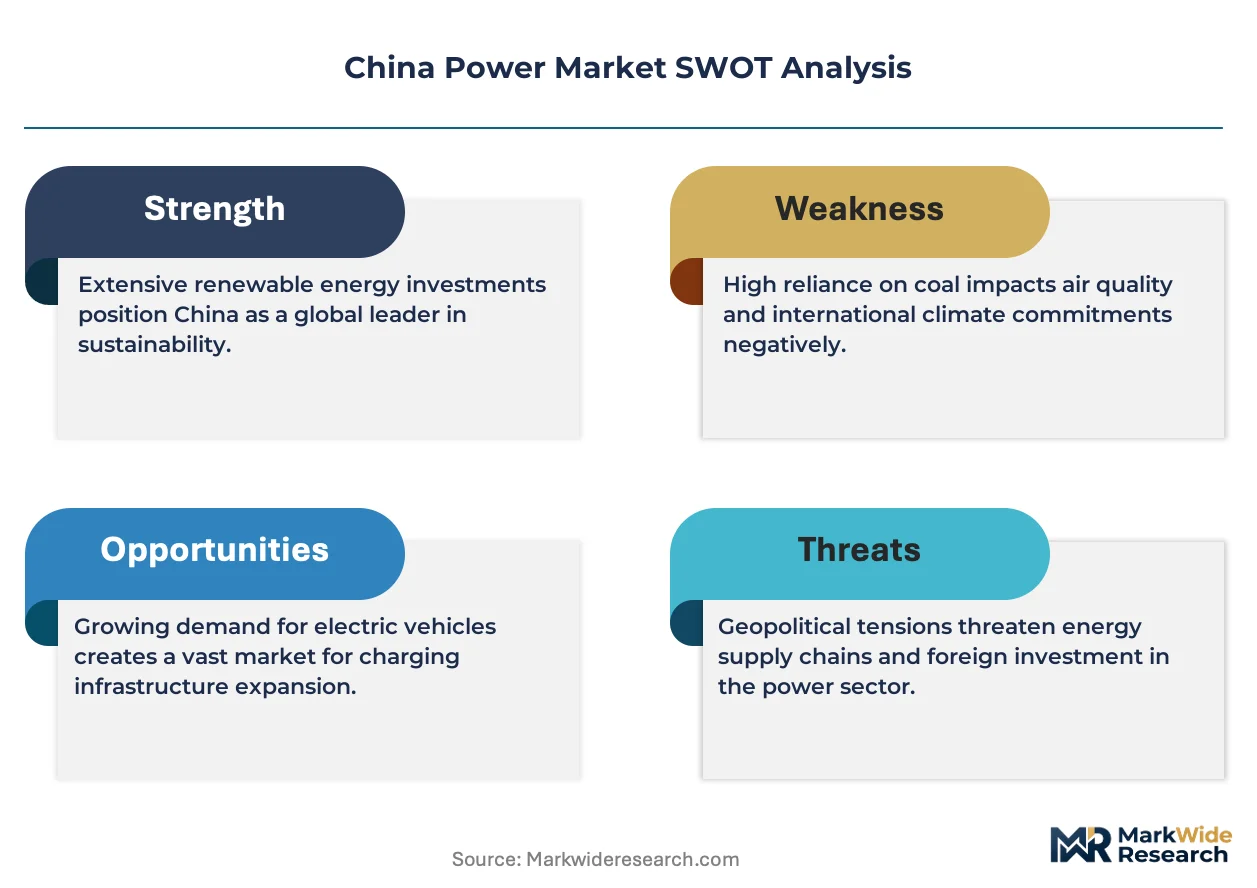
- Coal capacity lock-in:Existing supercritical thermal units carry sunk capital burdens and grid stability obligations that delay full decommissioning despite MEE emissions intensity permit tightening.
Strategic Opportunities
- Provincial energy trading platforms:Aggregated procurement pools for steel and chemical complexes in Shandong and Zhejiang are opening direct power purchase agreement channels bypassing traditional dispatch hierarchies.
- Green hydrogen offtake:Electrolyzer installations tied to western desert solar parks are creating new demand anchors for curtailed renewable generation during midday oversupply periods.
- Frequency regulation contracts:Battery energy storage systems and pumped-hydro assets are capturing expanding grid service revenue streams as coal plants lose spinning reserve priority.
Industry Challenges
- Ultra-high voltage technician shortage:Specialized commissioning and maintenance expertise for 800 kV and 1100 kV transmission corridors remains concentrated within State Grid Corporation training pipelines, constraining project ramp rates.
- Legacy SCADA integration:Centralized dispatch centers require protocol translation layers to coordinate inverter-connected resources with existing thermal plant control systems, introducing latency and cybersecurity exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Power Market |
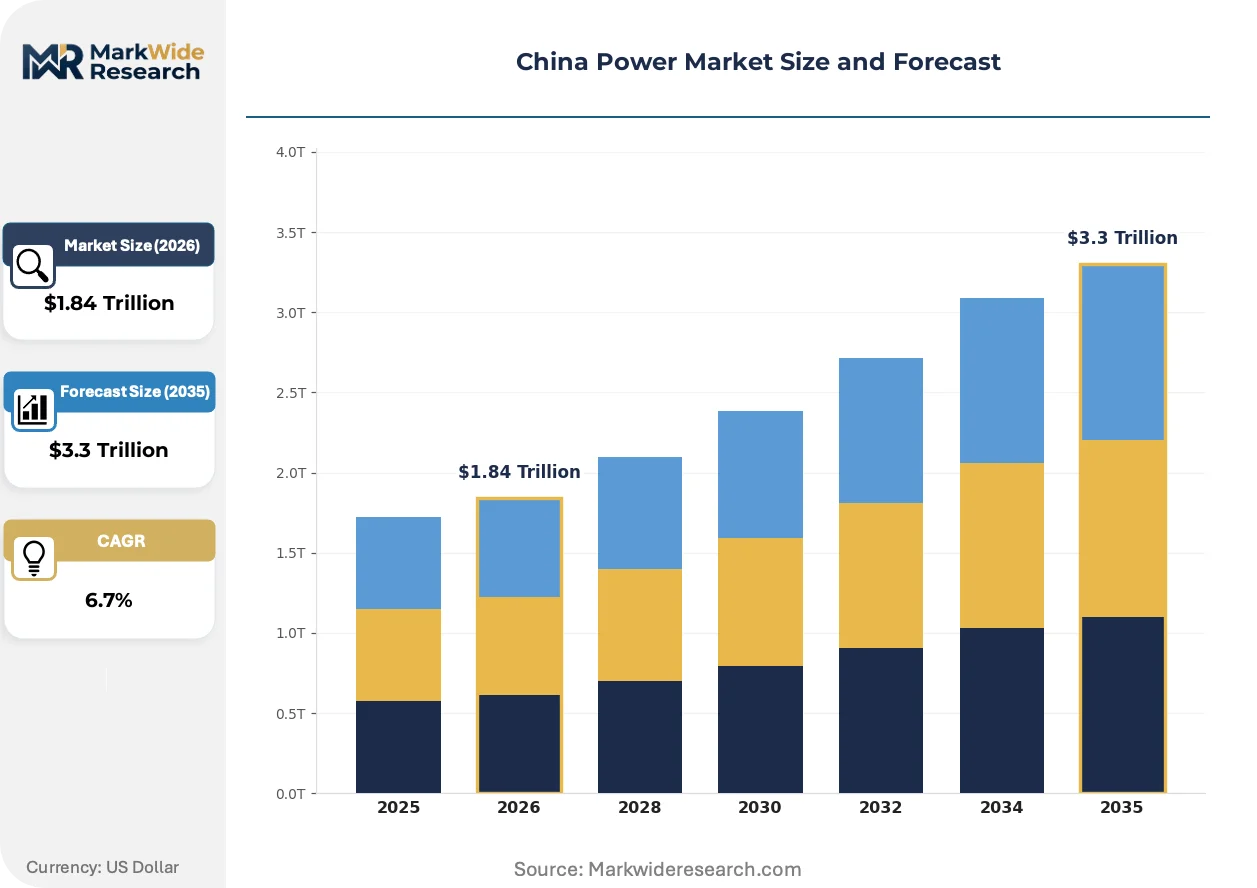
| Market Size in 2026 | $1.84 Trillion |
| Market Size in 2035 | $3.3 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Thermal, Hydroelectric, Wind, Solar Technology: Fossil Fuel, Biomass, Geothermal, Tidal Application: Industrial, Residential, Commercial, Grid Services End User: Utilities, Corporations, Households, Government |
| Companies Covered | State Grid Corporation of China, China Southern Power Grid, China Energy Investment Corp, China Huaneng Group, State Power Investment Corp, China Datang Corporation, China Huadian Group, China Three Gorges Corporation, Power Construction Corporation of China, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Power Market Emerging Trajectories
Digital dispatch optimization and hardware cost compression are converging to reshape competitive positioning between baseload thermal operators and variable renewable developers across China's provincial power markets.
Solid-state inverter architectures with silicon carbide power modules are overtaking conventional insulated-gate bipolar transistor designs in utility-scale photovoltaic installations. Western desert solar park developers in Qinghai and Inner Mongolia are specifying these units for 1500 volt DC string configurations. The technology is overtaking incumbent thermal plant economics by enabling higher DC-to-AC ratios and reducing levelized cost of energy calculations that inform provincial auction outcomes.
MEE emissions intensity caps under dual carbon targets are tightening coal plant utilization permits while accelerating renewable portfolio obligations for grid-connected generators. Industrial buyers in coastal provinces now face carbon accounting audits that penalize thermal-heavy supply contracts. Steelmakers and chemical complexes are responding by pooling procurement through provincial energy trading platforms to secure green power certificates and meet Scope 2 reduction commitments.
Aggregated corporate procurement through provincial energy trading platforms is displacing bilateral utility contracts as the dominant offtake mechanism for large industrial consumers. Steelmakers in Hebei and petrochemical complexes in Jiangsu are negotiating directly with renewable developers, bypassing traditional State Grid dispatch intermediaries. This pattern is most visible in the Yangtze River Delta where buyer concentration and offshore wind availability converge to support direct power purchase agreement structures.
China Power Market Segmentation
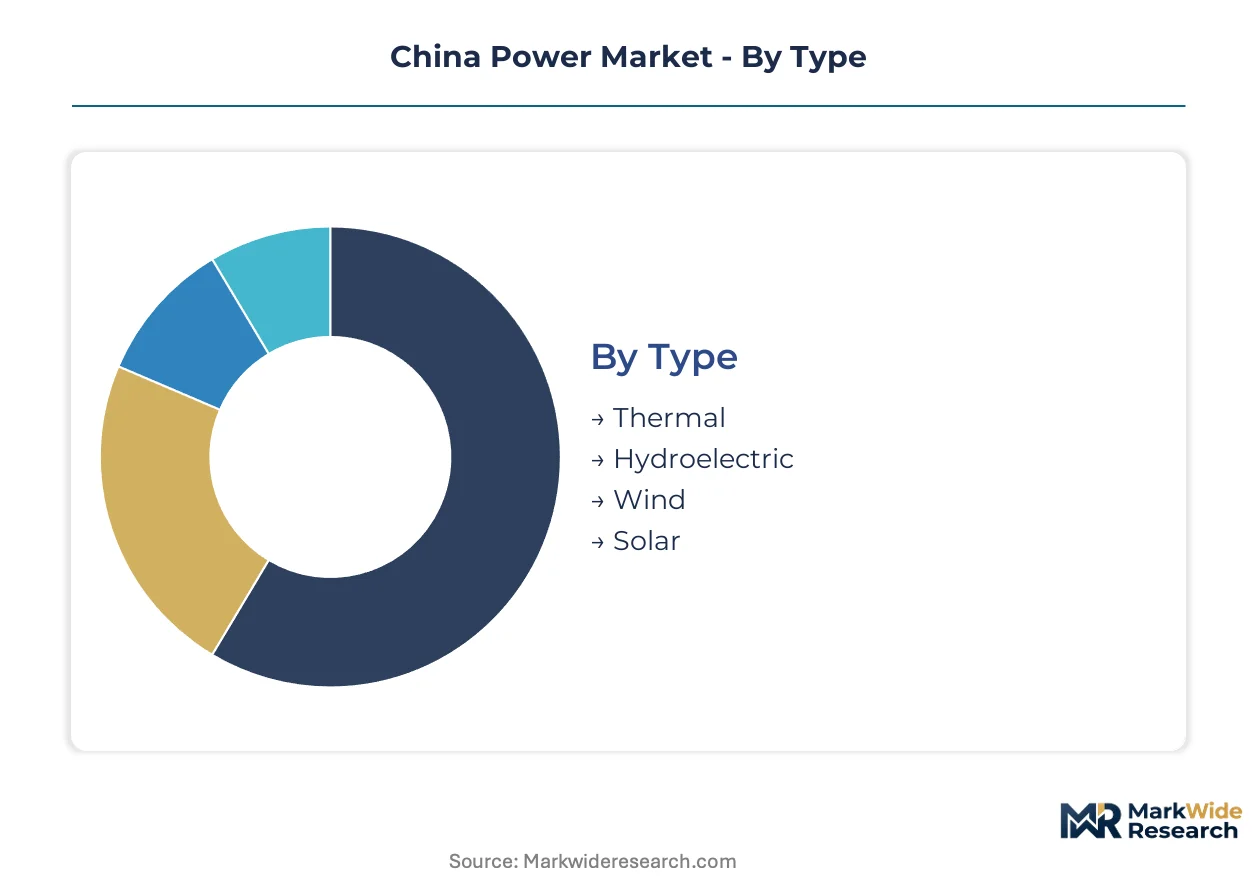
China's power market segmentation reveals how generation technologies, procurement channels, and end-use applications interact under dual carbon mandates. Understanding these dimensions exposes where margin pools are shifting from baseload thermal toward grid services and variable renewable assets.
Type:
Cost tiers separate segments by capital intensity and dispatch economics under provincial auction mechanisms.
- Thermal:Supercritical coal units above 600 MW retain the largest installed base but face compressed utilization permits under MEE emissions intensity caps. Steelmakers in Hebei and petrochemical complexes in Jiangsu still anchor baseload demand, though carbon accounting audits now penalize thermal-heavy procurement.
- Solar:Utility-scale photovoltaic arrays with 1500 volt DC string configurations dominate western desert parks in Qinghai and Inner Mongolia. Solid-state silicon carbide inverters are overtaking conventional designs, enabling higher DC-to-AC ratios that reshape provincial auction outcomes.
- Wind:Coastal offshore clusters along Fujian and Guangdong shorelines concentrate capacity within ultra-high voltage transmission reach of Yangtze River Delta load centers.
- Hydroelectric:Francis turbine configurations in southwestern canyon terrain hold mature positioning with limited greenfield sites remaining.
Thermal leads volumes today; solar is gaining share fastest.
Technology:
Supply concentration determines competitive dynamics, with upstream material flows creating geographic dependencies for project developers.
- Fossil Fuel:Coal and natural gas combustion systems carry sunk capital burdens and grid stability obligations that delay full decommissioning despite tightening permits.
- Biomass:Agricultural residue-fired units serve distributed heating loads in rural provinces where grid extension costs exceed decentralized generation economics.
- Geothermal:Sedimentary basin resources in North China Plain provide direct heat for greenhouse agriculture and district heating networks.
- Tidal:Estuarine turbine installations in Hangzhou Bay exploit reversing current patterns for predictable generation profiles.
Fossil fuel anchors current capacity; tidal offers the steepest expansion trajectory among emerging technologies.
Application:
Volume concentration varies by load profile predictability and peak shaving requirements across coastal and interior provinces.
- Industrial:Steelmaker electrification in Hebei and Jiangsu provinces pulls baseload demand onto provincial grids, expanding peak shaving requirements as electric arc furnaces replace coal-fired systems.
- Grid Services:Frequency regulation contracts and spinning reserve obligations are shifting from thermal plants toward battery energy storage systems and pumped-hydro assets as coal loses dispatch priority.
- Residential:Cooling loads concentrate in Yangtze River Delta urban centers during summer peak periods, driving seasonal demand volatility.
- Commercial:Facility operations in coastal cities face Scope 2 reduction commitments that redirect procurement toward green power certificates.
Industrial applications dominate consumption; grid services are expanding most quickly as ancillary markets mature.
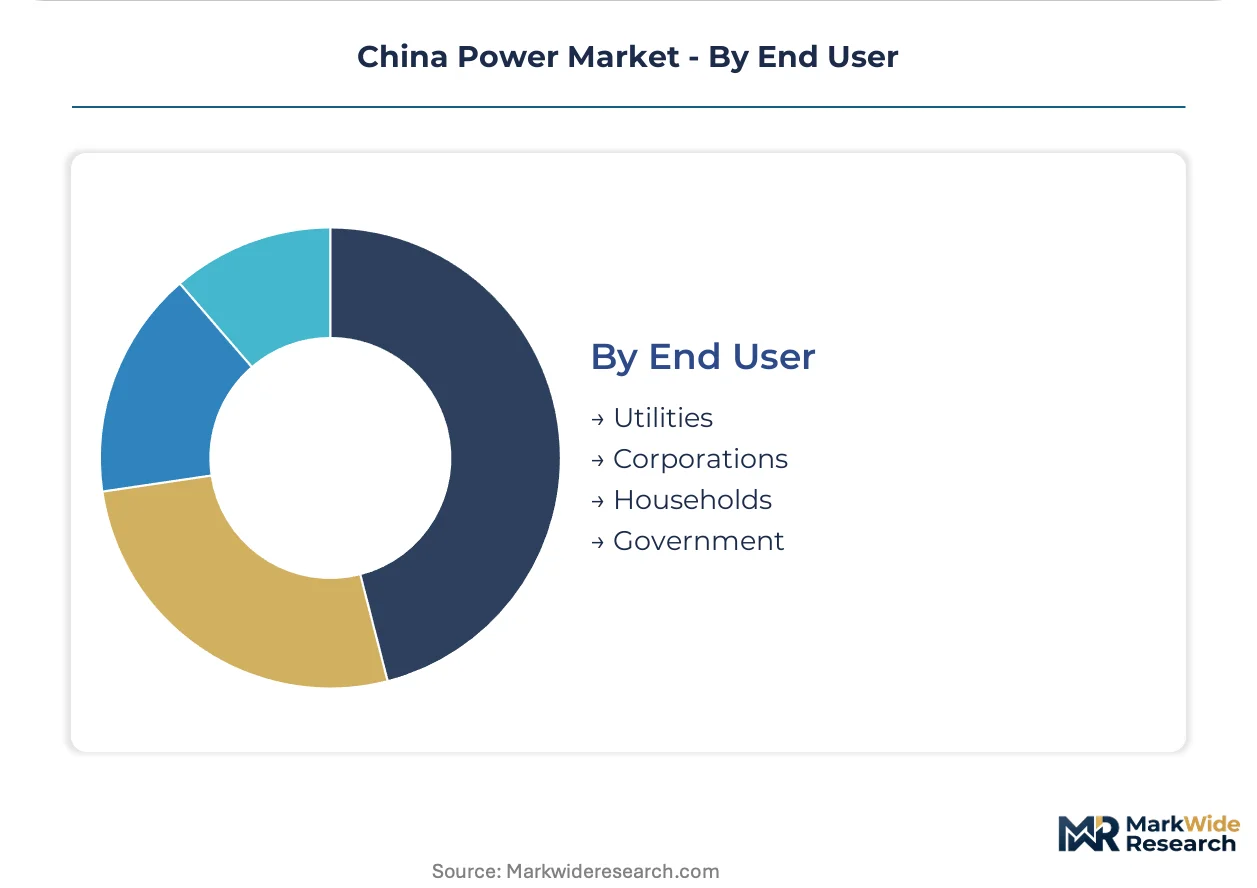
End User:
Procurement authority separates segments by contract structure complexity and direct market access under provincial trading platform reforms.
- Corporations:Steel and chemical complexes in Shandong and Zhejiang negotiate direct power purchase agreements through aggregated procurement pools, bypassing traditional State Grid dispatch intermediaries.
- Utilities:State Grid Corporation and China Energy Investment Corp anchor cross-province allocation through ultra-high voltage transmission monopolies, though their merchant exposure to renewable portfolio obligations is intensifying.
- Government:Municipal facilities and public infrastructure projects procure through centralized tenders that prioritize local content requirements under MIIT equipment standards.
- Households:Distributed rooftop photovoltaic installations in eastern provinces participate in net metering schemes with standardized feed-in tariffs.
Utilities retain volume leadership; corporate procurement is climbing the fastest as direct market access expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's installed capacity dwarfs India's by roughly five-fold, yet both nations face parallel grid modernization pressures as variable renewable penetration climbs. Provincial fragmentation within China creates sharper dispatch disparities than India's unified national grid architecture permits.
Guangdong
Offshore wind clusters along the Pearl River Delta shoreline feed ultra-high voltage corridors terminating at Shenzhen load centers. MIIT grid-code standards for 1500 volt DC string configurations accelerate utility-scale solar deployment in western prefectures. State Grid Corporation anchors cross-province allocation through 800 kV transmission infrastructure serving Foshan manufacturing complexes.
Inner Mongolia
Western desert solar parks in Ordos and Hohhot exploit high irradiance levels for gigawatt-scale photovoltaic arrays. Polysilicon supply concentration in Xinjiang creates geographic dependency for ingot flows reaching these installations. China Energy Investment Corp sustains thermal fleet operations while navigating coal capacity controls imposed by MEE emissions intensity caps.
Jiangsu
Steelmaker electrification across Suzhou and Nanjing pulls baseload demand onto provincial grids as electric arc furnaces replace coal-fired systems. Aggregated procurement pools on provincial energy trading platforms enable direct power purchase agreements bypassing traditional dispatch hierarchies. Coastal offshore wind availability supports corporate renewable offtake commitments.
Sichuan
Francis turbine hydroelectric configurations in southwestern canyon terrain hold mature positioning with limited greenfield sites remaining. China Three Gorges Corporation dominates generation and extends into pumped-storage development along Yangtze River basin tributaries. Frequency regulation contracts shift margin pools from thermal plants toward grid services as ancillary markets mature.
Shandong
Chemical complexes in Qingdao and Yantai negotiate green hydrogen offtake from electrolyzer installations tied to curtailed renewable generation. Provincial carbon accounting audits penalize thermal-heavy supply contracts, redirecting procurement toward green power certificates. State Power Investment Corp and China Huadian Group anchor merchant exposure to renewable portfolio obligations.
China Power Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across generation, transmission, and grid services segments. State-owned enterprises retain dominant positions in ultra-high voltage transmission and baseload thermal capacity, while provincial energy trading platforms open channels for corporate direct procurement. Strategic archetypes span transmission monopolists, integrated thermal-renewable operators, and pure-play renewable developers. Competitive moves concentrate on securing grid service contracts and aggregating industrial offtake through trading platform participation.
Among state-owned generation and transmission enterprises, State Grid Corporation of China, China Energy Investment Corp, and China Three Gorges Corporation occupy positions representing distinct strategic archetypes. State Grid Corporation exemplifies the transmission monopoly model leveraging ultra-high voltage infrastructure for cross-province allocation. China Energy Investment Corp represents the integrated thermal-renewable operator navigating coal capacity controls while expanding renewable portfolios. China Three Gorges Corporation anchors the hydroelectric-pumped storage specialist tier with Yangtze River basin dominance.
| Leading Market Players |
|---|
| State Grid Corporation of China |
| China Southern Power Grid |
| China Energy Investment Corp |
| China Huaneng Group |
| State Power Investment Corp |
| China Datang Corporation |
| China Huadian Group |
| China Three Gorges Corporation |
| Power Construction Corporation of China |
| Others |
Supply Flow & Price Mechanics
Steel and chemical complexes pooling procurement through provincial energy trading platforms anchor pricing power in China's power market, with aggregated industrial buyers negotiating long-term offtake contracts that compress merchant thermal margins while elevating renewable certificate premiums.
Pricing Analysis
Capacity additions in western desert solar parks are reshaping price floors across provincial auction mechanisms. Contract-based long-term offtake agreements dominate, with price differentiation driven by carbon accounting grade and volume scale commitments. Pricing pressure stems from silicon carbide inverter cost compression in Qinghai and Inner Mongolia installations. State-owned utilities show least price sensitivity; distributed industrial buyers exhibit highest.
Supply Chain Analysis
Long-haul freight costs from Xinjiang polysilicon ingot production to western solar parks create geographic dependency for photovoltaic developers. Supply concentrates in China for turbine components, South Korea for power semiconductors, and Japan for high-voltage switchgear. Raw material flows hinge on rare earth magnet supply, copper busbar availability, and transformer core steel access. Single-source vulnerability runs through Xinjiang polysilicon concentration. Distribution runs through State Grid ultra-high voltage corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's power market functions as a stable compounder, with dual carbon mandates ensuring sustained capital deployment toward renewable capacity and grid modernization regardless of macroeconomic cycles.
For Market Incumbents: Cement ultra-high voltage transmission corridor control through accelerated technician training pipelines, countering the specialized commissioning expertise shortage that constrains project ramp rates. Secure frequency regulation contracts ahead of coal plant spinning reserve displacement. Prioritize backward integration into silicon carbide inverter manufacturing to capture hardware cost compression benefits.
For New Entrants and Emerging Players: The premium-economy price gap in corporate renewable procurement opens white-space for mid-scale developers aggregating industrial offtake through Shandong and Zhejiang trading platforms. Target green hydrogen electrolyzer installations tied to curtailed midday solar generation in western desert parks. Pursue direct power purchase agreement structures bypassing State Grid dispatch intermediaries.
For Investors and Strategic Acquirers: Provincial energy investment platforms are the most active acquirer in this space, consolidating distributed renewable assets to meet portfolio obligation mandates. Long-term viability centers on grid service revenue streams displacing merchant generation exposure. Monitor pumped-storage site scarcity in southwestern canyon terrain as inflection indicator for battery energy storage system valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Ultra-High Voltage Corridor Expansion | State Grid Corporation anchors cross-province allocation monopoly through 800 kV and 1100 kV infrastructure serving Yangtze River Delta load centers. |
| Green Hydrogen Offtake Agreement | Electrolyzer installations in Shandong create demand anchors for curtailed renewable generation during midday oversupply periods. |
| Solid-State Inverter Technology Licensing | Silicon carbide power modules enable higher DC-to-AC ratios that reshape provincial auction economics in Qinghai solar parks. |
| Pumped-Storage Joint Venture | China Three Gorges Corporation extends Yangtze River basin dominance through reservoir pairing development for frequency regulation services. |
| Provincial Trading Platform Integration | Aggregated procurement pools in Jiangsu bypass traditional dispatch hierarchies for steelmaker electrification projects. |
Methodological Framework
Multiple input streams — utility planning officer interviews, IPP project developer assessments, EPC contractor cost databases, and grid operator dispatch records — were reconciled against MIIT equipment standards filings and MEE emissions permit registries. Secondary validation drew from China Electricity Council statistical yearbooks, National Energy Administration capacity databases, and provincial trading platform transaction logs. Bottom-up project pipelines and top-down provincial demand forecasts underwent cross-triangulation.
Data-stream reconciliation across generation technology type, capacity tier, and regional grid configuration shaped the analytical framework over the projection horizon. CAGRs were derived from segmented capacity addition trajectories and utilization rate assumptions. Forecast inputs incorporated dual carbon mandate implementation pace and ultra-high voltage transmission commissioning schedules.
The model assumes a particular technology adoption path; alternative pathways for solid-state silicon carbide inverter penetration would alter the outlook for thermal plant displacement timing. Forecasts reflect assumptions regarding MIIT grid-code enforcement consistency and MEE emissions intensity cap tightening trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Power Rental Market
Power
Japan Uninterrupted Power Supply (UPS) Market
Power
Australia Power Market
Power
Russian Federation Power Market
Power
Doubly Fed Induction Generator (DFIG) Market
Power
Middle-East and Africa Power Rental Market
Power
Modified Sine Wave Home Inverters Market
Power
Oxy-Hydrogen Generators Market
Power
Power Shelf Market
Power
Asia-Pacific Package Substation Market
Power
Existent Gum Steam Generator Market
Power
Asia-Pacific Turbomachinery Control Systems Market
Power
North America Micro CHP Market
Power
Europe Frequency Converter Market
Power
Water Turbine Market
Power
Telecom Power Rental Market