
 Compact Substation Market | 2026-2036
Compact Substation Market Size, Share, and Industry Trends Forecast 2026-2036
Compact Substation Market Analytics
Utility procurement channels is tilting toward prefabricated, factory-tested packages that compress project timelines and reduce on-site civil works. ABB leverages its global manufacturing footprint to deliver modular substations with integrated digital monitoring. Siemens sustains technology leadership through its portfolio of gas-insulated and air-insulated compact designs. Schneider Electric anchors its position with EcoStruxure-ready architectures that bridge operational technology and grid management software.
A compact substation integrates power transformers, switchgear, busbars, and protection equipment within an enclosed, weatherproof housing rated for outdoor or indoor installation, typically serving ratings from low voltage through high voltage. The assembly functions as a self-contained distribution node that steps down transmission voltages for industrial, commercial, or residential consumption. Transformer packages dominate value capture due to copper and magnetic steel content, while switchgear segments are gaining structural weight as arc-flash containment and SF6-alternative insulation become design priorities. Data centers represent the fastest-growing end-user channel, with renewable energy installations following closely as solar and wind farms require modular grid-connection assets.
ANSI/IEEE C57.12.00 and IEC 62271-202 govern dielectric withstand, thermal performance, and enclosure integrity for compact substations in North American and European markets. India's Central Electricity Authority mandates minimum energy efficiency indices for distribution transformers under its Standards of Performance regulations. India's Bureau of Indian Standards enforces IS 2026 for transformer construction, while state electricity boards in Maharashtra, Gujarat, and Tamil Nadu specify compact substation configurations for urban underground distribution. Stakeholders must monitor evolving SF6-phaseout timelines and solid-insulation qualification protocols as these standards reshape product roadmaps and supplier qualification criteria.
Market Dynamics
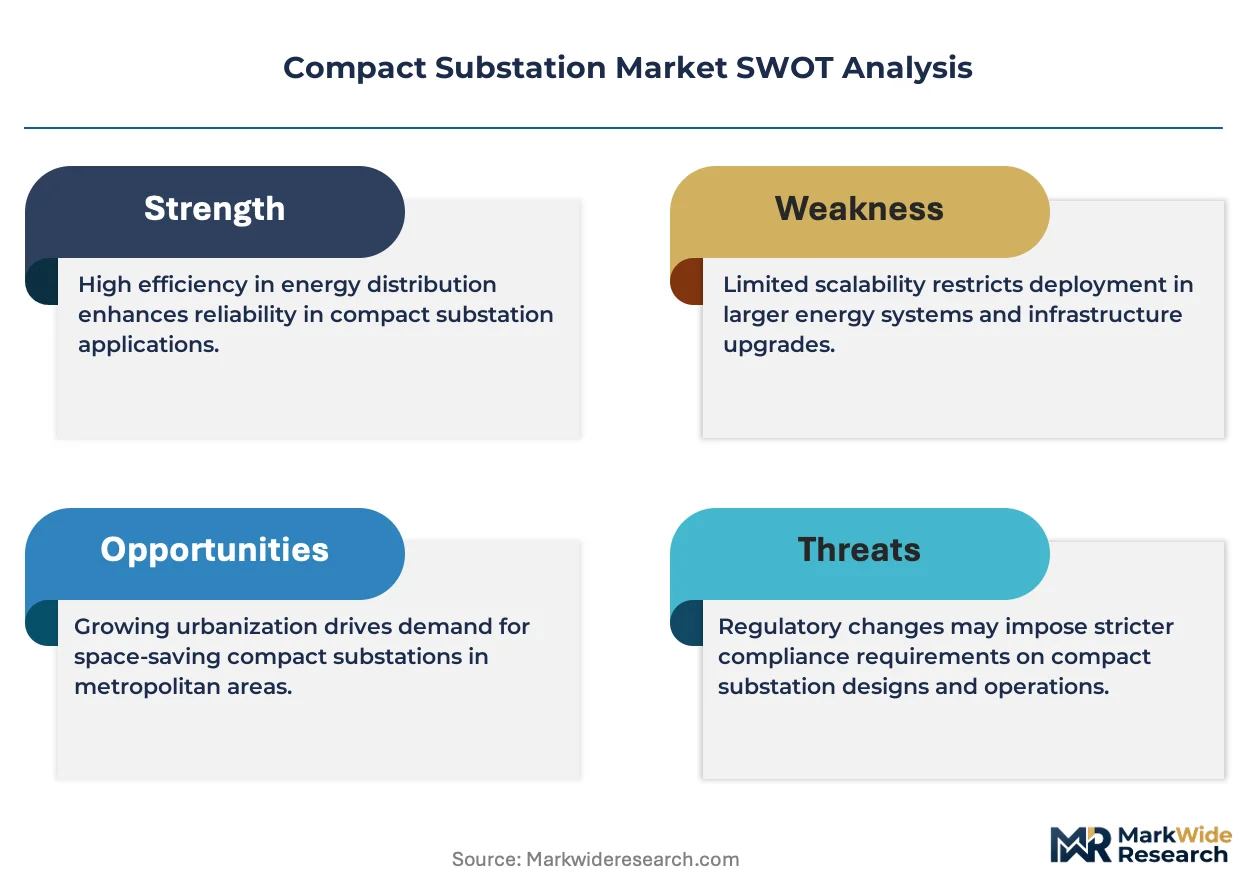
Factory-tested prefabrication is compressing substation deployment timelines from months to weeks, eliminating on-site civil works and rewiring procurement criteria toward integrated package suppliers rather than component vendors.
Growth Catalysts
- AI data center load expansion:Hyperscale operators in the United States and Germany are procuring pad-mounted compact substations to handle 50-100 MW incremental power blocks for GPU clusters.
- India's urban underground distribution mandate:State electricity boards in Maharashtra and Tamil Nadu specify kiosk substations for congested metro corridors, accelerating standardized procurement.
- Solid-insulation switchgear qualification:IEC 62271-202 revisions on vacuum interrupters and dry-air insulation are opening retrofit pathways for SF6-dependent utilities.
Market Restraints
- Copper and grain-oriented electrical steel volatility:Transformer cores and windings comprise 40-50% of unit cost, exposing margins to commodity swings.
- SF6 phaseout timeline uncertainty:Europe's F-Gas Regulation and draft EPA rules in the United States create stranded asset risk for gas-insulated switchgear inventories.
- Skilled field technician scarcity:Medium-voltage commissioning requires certified specialists whose training pipelines lag deployment demand in India and Southeast Asia.
Strategic Opportunities
- Offshore wind grid connection:North Sea and Baltic projects in Germany and Denmark need marine-rated compact substations for turbine string aggregation.
- Digital twin integration:Converging transformer monitoring sensors with grid management software enables predictive maintenance contracts.
- Rural electrification in sub-Saharan Africa:Containerized substations bypass weak logistics infrastructure for mining and agricultural loads.
Industry Challenges
- Legacy SCADA protocol fragmentation:Utilities operate mixed DNP3, IEC 61850, and proprietary networks, complicating unified monitoring deployment.
- Multi-standard certification timelines:Simultaneous IEEE C57.12.00 and IEC 62271-202 qualification extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compact Substation Market |
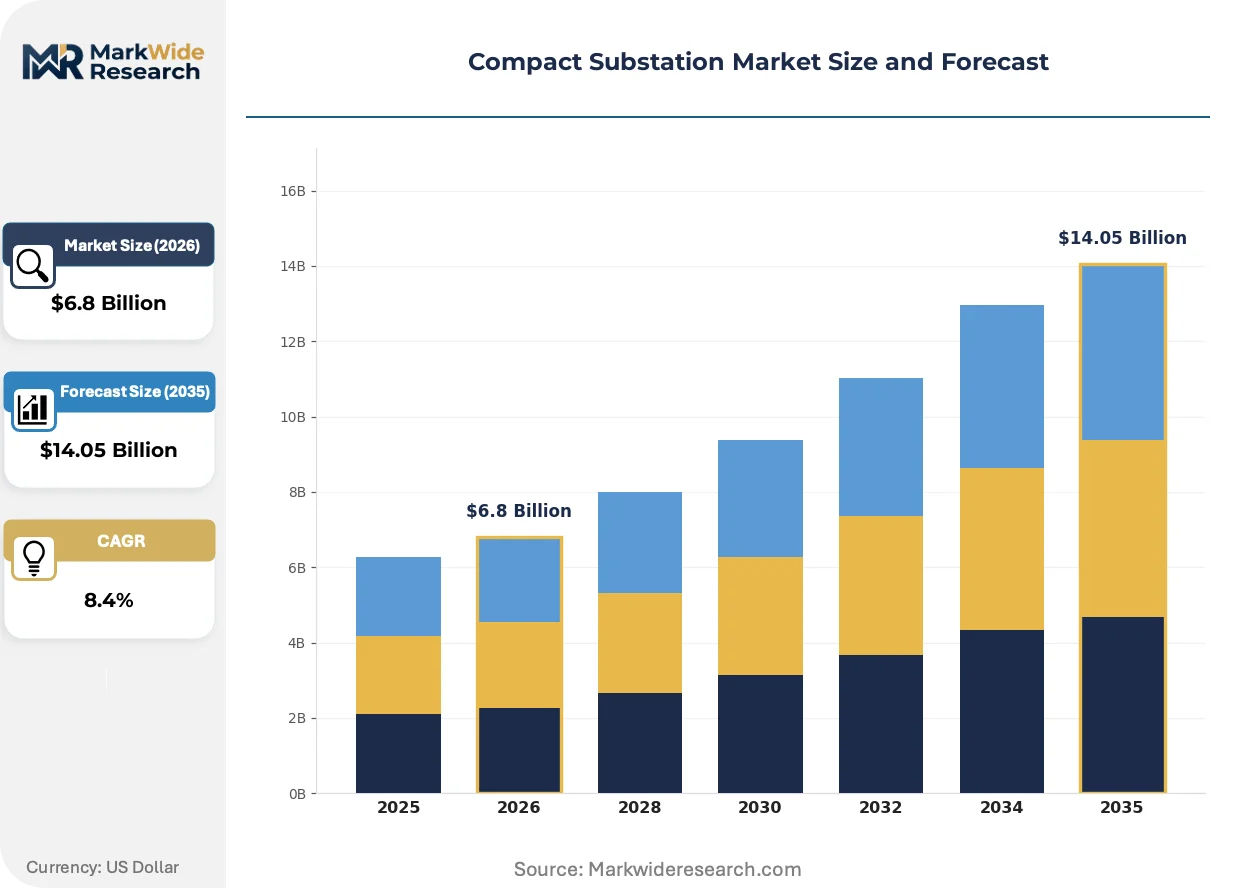
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transformer, Switchgear, Busbar, Circuit Breaker Installation Type: Indoor, Outdoor, Transportable, Fixed End User: Utilities, Industrial, Renewable Energy, Data Centers Capacity: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage |
| Companies Covered | ABB, Siemens, Schneider Electric, Eaton, General Electric, Toshiba Corporation, Hitachi, CG Power, Aktif Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compact Substation Market Evolving Landscape
Insulation chemistry and digital instrumentation are converging to redefine compact substation architecture, shifting competitive advantage from hardware fabrication to systems integration and software-enabled services.
Dry-type and solid-cast resin transformers are migrating from niche indoor applications to outdoor pad-mounted installations. Data center operators in Northern Virginia and Frankfurt are specifying these units for fire-safety compliance in dense campus layouts. The technology is migrating from premium segments toward standard procurement specifications as OEMs qualify 36 kV class designs for harsh climate exposure.
The European Union's F-Gas Regulation is accelerating SF6-alternative switchgear development by banning new medium-voltage equipment using the gas after 2030. Manufacturers are scaling vacuum interrupter production and dry-air insulation systems to meet compliance deadlines. German utilities are front-loading procurement to secure transitional inventory before supply constraints emerge.
Integrated energy-as-a-service contracts are displacing traditional equipment purchase models for commercial and industrial buyers. Siemens, ABB, and regional specialists now offer 10-15 year performance guarantees bundling hardware, maintenance, and efficiency optimization. This shift concentrates in Germany and the United States where energy volatility drives risk transfer preferences.
Compact Substation Market Segmentation
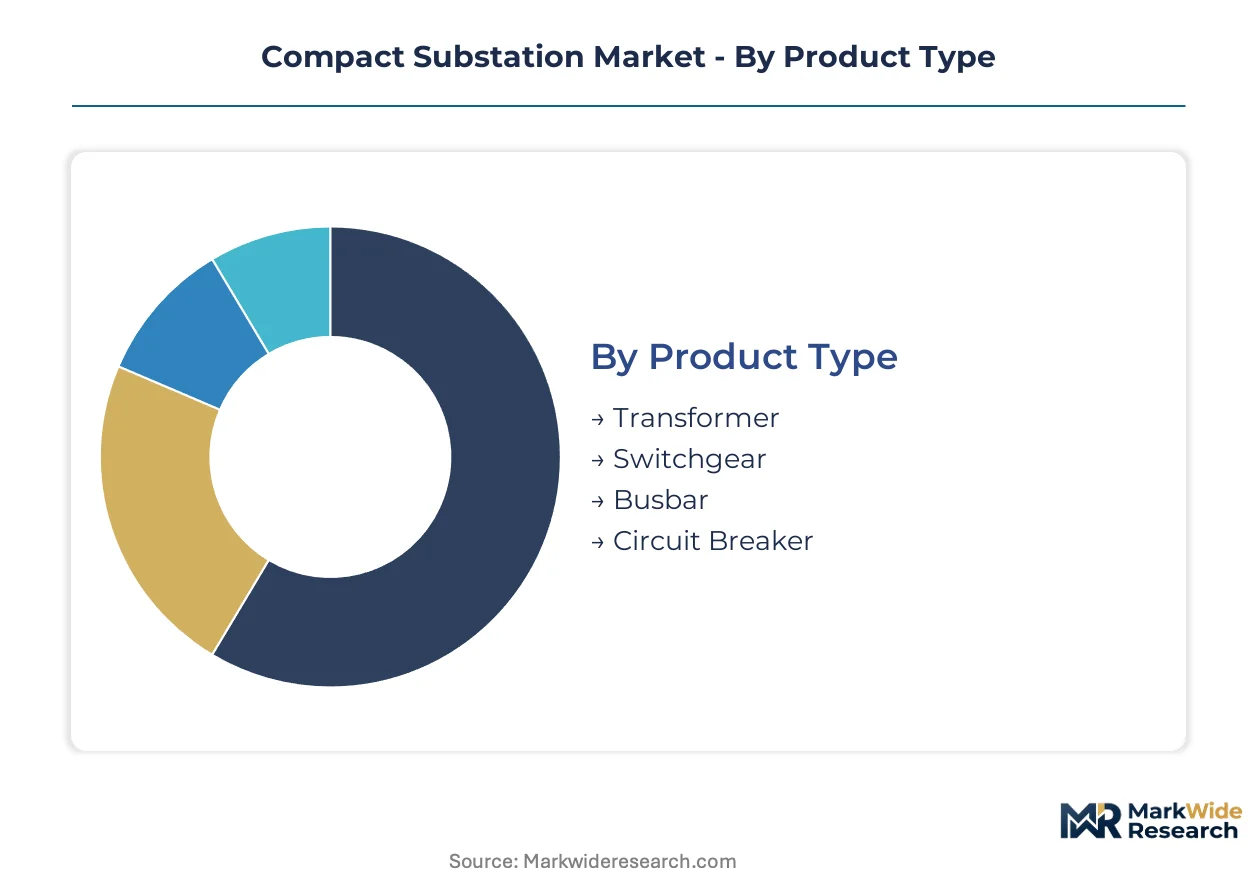
Compact substation segmentation reveals how technology specialization and deployment context reshape procurement economics. Product architecture and installation constraints determine supplier qualification criteria, while end-use intensity and voltage class govern margin structures and contract duration.
Product Type:
Mature transformer packages coexist with emerging solid-insulation switchgear as utilities phase out SF6-dependent designs.
- Transformer:Oil-immersed and dry-type units containing copper windings and grain-oriented electrical steel cores dominate unit economics. Data center operators in Northern Virginia and Frankfurt specify dry-type designs for fire-safety compliance in dense campus layouts, though commodity price volatility in copper and magnetic steel compresses OEM margins.
- Switchgear:Vacuum interrupters and dry-air insulation systems are displacing gas-insulated alternatives under Europe's F-Gas Regulation deadlines. German utilities front-load procurement of SF6-free designs ahead of 2030 supply constraints, creating transitional inventory demand.
- Busbar:Aluminum and copper conductor assemblies rated for thermal cycling and short-circuit withstand.
- Circuit Breaker:Spring-operated and magnetic-actuated mechanisms integrated with protection relays.
Transformer packages handle the majority of throughput; switchgear is the fastest mover on share.
Installation Type:
Cost tier separation runs from premium transportable units with integrated monitoring to economy fixed installations requiring extensive civil preparation.
- Outdoor:Pad-mounted and kiosk enclosures rated for weatherproof operation in urban underground distribution corridors. State electricity boards in Maharashtra and Tamil Nadu mandate these configurations for congested metro corridors, standardizing procurement specifications across Indian cities.
- Transportable:Containerized skid-mounted packages enabling rapid deployment to remote mining and agricultural loads in sub-Saharan Africa. These units bypass weak logistics infrastructure while supporting modular capacity expansion.
- Indoor:Compact designs for building-integrated substations in commercial and industrial facilities.
- Fixed:Permanent foundation-mounted installations with extended service intervals.
Outdoor configurations anchor volume deployment; transportable designs are expanding most quickly in frontier markets.
End User:
Application intensity varies from baseload utility networks to intermittent renewable integration and hyperscale compute loads.
- Data Centers:Hyperscale operators in the United States and Germany procure pad-mounted compact substations in 50-100 MW incremental blocks to serve GPU cluster power density. Fire-safety compliance and rapid deployment timelines compress procurement toward factory-tested packages with integrated digital monitoring.
- Renewable Energy:Solar and wind farms require modular grid-connection assets for turbine string aggregation and inverter step-up. North Sea and Baltic offshore projects in Germany and Denmark drive demand for marine-rated compact substations.
- Utilities:Distribution network operators upgrading urban infrastructure and rural electrification programs.
- Industrial:Manufacturing facilities and process plants requiring reliable medium-voltage supply.
Data centers command premium pricing; renewable energy installations are climbing the fastest on deployment share.
Capacity:
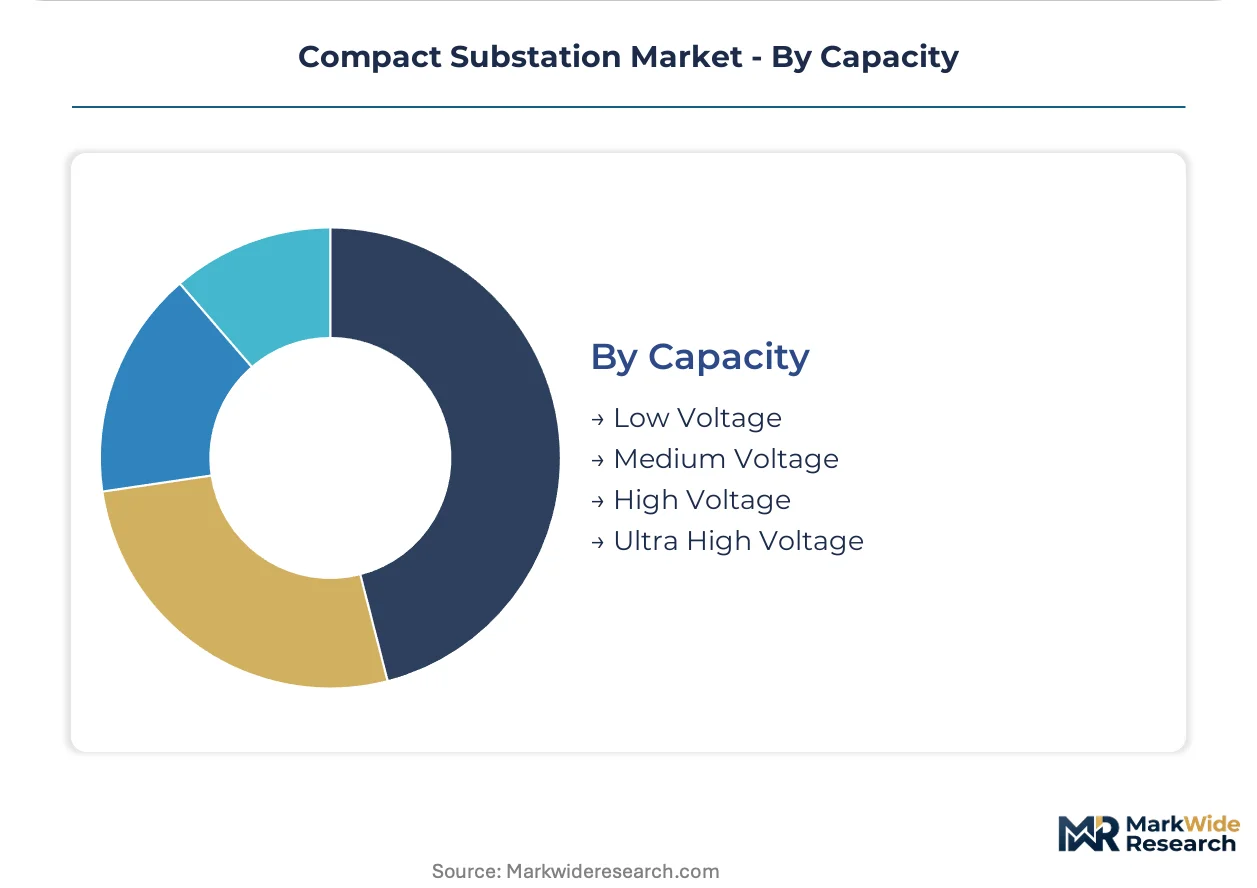
Voltage class determines insulation complexity, safety clearances, and regulatory jurisdiction across utility and industrial networks.
- Medium Voltage:Ratings from 1 kV to 52 kV serving distribution substations and industrial interconnections. IEC 62271-202 and IEEE C57.12.00 govern dielectric withstand and thermal performance, with simultaneous qualification extending product launch cycles.
- Low Voltage:Secondary distribution and final service connections in commercial and residential applications.
- High Voltage:Transmission interface and bulk power transfer applications.
- Ultra High Voltage:Specialized grid backbone connections requiring advanced insulation coordination.
Medium voltage segments absorb the dominant share of procurement volume; low voltage applications show steepest expansion trajectory in distributed generation integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea offshore grid interconnect underwrites Germany's central role in marine-rated compact substation demand, while India's urban distribution corridors and the United States' hyperscale data center clusters anchor three distinct procurement geographies.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth procure pad-mounted compact substations in 50-100 MW blocks for GPU cluster power density. FERC interconnection standards govern medium-voltage grid integration timelines. Loudoun County's data center alley compresses deployment toward factory-tested packages with integrated digital monitoring.
Germany
North Sea and Baltic offshore wind projects drive demand for marine-rated compact substations in turbine string aggregation. The EU F-Gas Regulation bans new SF6-dependent medium-voltage equipment after 2030, front-loading procurement of dry-air insulation systems. Hamburg and Bremerhaven anchor manufacturing and logistics for offshore grid connection assets.
India
State electricity boards in Maharashtra and Tamil Nadu mandate kiosk substations for congested metro underground distribution corridors. The Central Electricity Authority enforces minimum energy efficiency indices for distribution transformers under Standards of Performance regulations. Mumbai and Chennai standardize procurement specifications across urban infrastructure upgrades.
China
Dual carbon goals accelerate renewable integration requiring modular grid-connection assets for solar and wind farms. GB standards govern transformer construction and switchgear dielectric performance. The Yangtze River Delta and Pearl River Delta concentrate manufacturing capacity for export-oriented compact substation packages.
Denmark
Baltic offshore wind expansion creates demand for marine-rated substations in Kriegers Flak and adjacent lease areas. National energy policy mandates 100% renewable electricity by 2030, compressing deployment timelines. Esbjerg anchors North Sea logistics infrastructure for turbine aggregation and grid export capacity.
Compact Substation Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying copper windings, vacuum interrupters, and cast-resin insulation systems. The vendor base organizes around three strategic archetypes: diversified electrical conglomerates with global manufacturing footprints, regional specialists focused on prefabricated package assembly, and niche suppliers of solid-insulation switchgear. Competitive positioning hardens through backward integration into transformer core production and strategic partnerships for digital twin software integration.
Among diversified electrical conglomerates, ABB and Siemens exemplify platform-scale positioning across integrated hardware and grid management software. Schneider Electric occupies a position bridging operational technology architectures with energy-as-a-service contract structures. These three anchors represent distinct geographic and technological vectors: Swiss-Swedish manufacturing breadth, German engineering depth in gas-insulated and air-insulated designs, and French-digital integration capabilities.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Eaton |
| General Electric |
| Toshiba Corporation |
| Hitachi |
| CG Power |
| Aktif Group |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta anchors global manufacturing capacity for compact substation packages, with clustered transformer and switchgear production feeding pricing power to integrated OEMs serving data center and renewable energy procurement channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and after-sales service bundling. Premium tiers command position through IEC 62271-202 and IEEE C57.12.00 dual qualification, while economy tiers serve price-sensitive Indian state electricity boards. Cost compression in standard-tier transformer packages is intensifying because copper and grain-oriented electrical steel volatility now comprises 40-50% of unit economics. Data center operators in Northern Virginia show least price sensitivity, prioritizing fire-safety compliance and rapid deployment timelines over upfront capital.
Supply Chain Analysis
Export-control regimes on advanced vacuum interrupter technology limit flows from German and Japanese specialists to Chinese assemblers, fragmenting procurement channels for SF6-alternative switchgear. Manufacturing concentrates in China, India, and Germany, with the Yangtze River Delta, Gujarat industrial corridors, and Hamburg-Bremerhaven anchoring distinct supply nodes. Raw material dependencies center on Chilean copper, Ukrainian grain-oriented electrical steel, and Japanese magnetic core laminations. Single-source vulnerability in vacuum interrupter supply creates bottleneck risk as Europe's F-Gas Regulation deadlines approach. Distribution runs through utility procurement frameworks, EPC contractor specifications, and direct OEM relationships with hyperscale data center operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compact substation demand sits in early-cycle expansion, with AI data center load growth and India's urban underground distribution mandate together representing underpenetrated infrastructure upgrade pathways.
For Market Incumbents: Pre-empt margin erosion in transformer packages by securing captive supply of grain-oriented electrical steel through backward integration into core lamination production. Accelerate IEC 62271-202 qualification timelines for dry-air insulation switchgear before 2030 F-Gas Regulation supply constraints strand SF6-dependent inventories. Channel control through prefabricated package assembly partnerships with Indian state electricity boards defends position against regional specialists. For New Entrants and Emerging Players: Establish a beachhead in containerized transportable substations for sub-Saharan African mining and agricultural loads, where weak logistics infrastructure creates white-space demand bypassing established utility procurement channels. Target marine-rated compact substations for North Sea and Baltic offshore wind aggregation, where German and Danish project pipelines outpace incumbent capacity expansion. Lead with digital twin integration capabilities to differentiate from hardware-centric OEMs in energy-as-a-service contract structures. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors solid-insulation switchgear specialists with proven vacuum interrupter production and dry-air insulation qualification. Long-term viability hinges on exposure to data center and renewable energy end-use channels rather than legacy utility replacement cycles. The signal to watch is front-loading procurement velocity by German utilities ahead of F-Gas Regulation deadlines, which would indicate supply constraint pricing power and acquisition premium justification for qualified manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Alternative Switchgear Scale-Up | Vacuum interrupter production expansion secures compliance with EU F-Gas Regulation deadlines. |
| Digital Twin Platform Integration | Converging transformer monitoring with grid management software enables predictive maintenance contracts. |
| Backward Integration into Core Steel | Captive grain-oriented electrical steel supply insulates margins from commodity volatility. |
| Prefabricated Package Partnerships | Factory-tested assemblies compress deployment timelines for Indian state electricity board mandates. |
| Marine-Rated Certification Investment | Offshore wind grid connection qualification opens North Sea and Baltic project pipelines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and project development databases to establish market size and growth trajectory. Primary interviews engaged utility planning officers, EPC contractors, data center infrastructure heads, and switchgear procurement leads across North America, Europe, and Asia-Pacific. Secondary validation drew from FERC interconnection standards documentation, EU F-Gas Regulation implementation guidance, Indian Central Electricity Authority performance regulations, and IEC technical committee draft revisions. Bottom-up segment sizing triangulates against top-down macroeconomic overlays.
Forecast inputs span product architecture, installation constraints, voltage class, end-use intensity, and regional regulatory frameworks across the projection horizon. Segmentation modeling incorporates transformer type, switchgear insulation technology, deployment context, and buyer procurement channel. CAGRs derive from installed base replacement cycles, capacity expansion pipelines, and technology substitution curves. Specific inputs include hyperscale data center power density specifications, offshore wind turbine aggregation scaling, and Indian urban distribution underground conversion mandates.
Macroeconomic conditions sit as an overlay; deviation in copper and electrical steel pricing, interest rate sensitivity for infrastructure capital deployment, or grid interconnection queue timelines would shift the trajectory. Forecasts reflect documented assumptions on technology adoption rates, regulatory phaseout timelines, and supply chain qualification durations. Material shifts in SF6-alternative switchgear supply availability or data center load growth trajectories would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Power Capacitors Market
Power
United States Power Market
Power
Sudan Power Market
Power
Asia-Pacific Alternating Current (AC) Drive Market
Power
Power Purchase Agreement Market
Power
Smart PV Inverters Market
Power
Asia-Pacific Package Substation Market
Power
Marine Thermal Fluid Heaters Market
Power
Asia-Pacific Power Market
Power
Green UPS Market
Power
Sudan Power EPC Market
Power
Combined Heat and Power (CHP) Systems Market
Power
Middle-East and Africa Power Market
Power
Portugal Power Market
Power
Italy Power EPC Market
Power
Middle East and Africa Combined Heat & Power Market