
 Denmark Power Market | 2026-2036
Denmark Power Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Power Market Outlook
The capital-intensity divergence between offshore wind developers and conventional generators is rotating strategic investment toward integrated renewable platforms. Ørsted A/S leverages its North Sea project pipeline to sustain long-term offtake agreements. Vestas Wind Systems A/S anchors domestic turbine supply through manufacturing scale in Jutland. Better Energy A/S differentiates via distributed solar and storage hybrids that compete against centralized fossil assets.
Denmark power encompasses electricity generation, transmission, and distribution infrastructure operating at 50 Hz with 230 V residential delivery, primarily serving industrial automation, district heating integration, and electrified transport networks. Renewable Energy leads generation mix expansion while Fossil Fuels segments face structural margin compression under carbon pricing. Wind Turbines technology dominates capacity additions, though Solar Photovoltaics segments accelerate fastest in distributed commercial Application. Grid Storage application categories capture emerging value pools as intermittency management becomes critical for Utility Companies and Government Agencies end users.
The Danish Energy Agency enforces offshore site licensing under the Climate Act framework, while Energinet coordinates grid codes that mandate frequency response standards for interconnectors to Germany and Sweden. EU Green Deal alignment through ETS carbon pricing mechanisms shapes dispatch economics, pushing residual coal and gas plants toward early retirement. Stakeholders must monitor auction design evolution for near-shore wind zones and the pace of electrolyzer scale-up that will determine whether power-to-X demand materializes as a credible offtake alternative.
Market Dynamics
The Danish Climate Act's 2045 carbon neutrality mandate is forcing a wholesale reconfiguration of generation assets, with offshore wind procurement cycles compressing as developers race to secure turbine supply ahead of queue bottlenecks at North Sea lease rounds.
Growth Catalysts
- EU Green Deal alignment:The EU Emissions Trading System carbon price floor eliminates residual coal dispatch economics, accelerating baseload retirement schedules.
- Copenhagen district heating networks:Municipal heat pump integration creates synchronized electricity demand that stabilizes renewable intermittency through thermal storage coupling.
- Interconnector expansion:New HVDC links to Germany and Sweden enable Danish wind exports during oversupply hours, improving project financeability.
Market Restraints
- Offshore turbine supply concentration:European nacelle assembly capacity constraints limit annual installation velocity regardless of lease award pace.
- Copper and rare earth input volatility:Generator winding materials face price swings that distort levelized cost assumptions for 15-year power purchase agreements.
- Grid code synchronization delays:Energinet frequency response mandates for new interconnectors extend commissioning timelines by 8-14 months.
Strategic Opportunities
- Zealand industrial cluster electrification:Pharmaceutical and food processing facilities in the Copenhagen corridor seek direct renewable supply contracts bypassing utility intermediaries.
- Power-to-X electrolyzer scale-up:Green hydrogen offtake agreements for ammonia and e-fuel production create alternative revenue streams for offshore wind farms.
- Jutland distributed solar-storage hybrids:Agricultural landowners deploy commercial PV with lithium-ion buffering to arbitrage spot price volatility.
Industry Challenges
- High-voltage cable installation vessel scarcity:Specialized marine construction fleets face 24-month booking backlogs that delay project energization.
- Legacy CHP plant workforce transition:Copenhagen's coal-to-biomass conversions require retraining programs for boiler operators and grid dispatchers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Power Market |
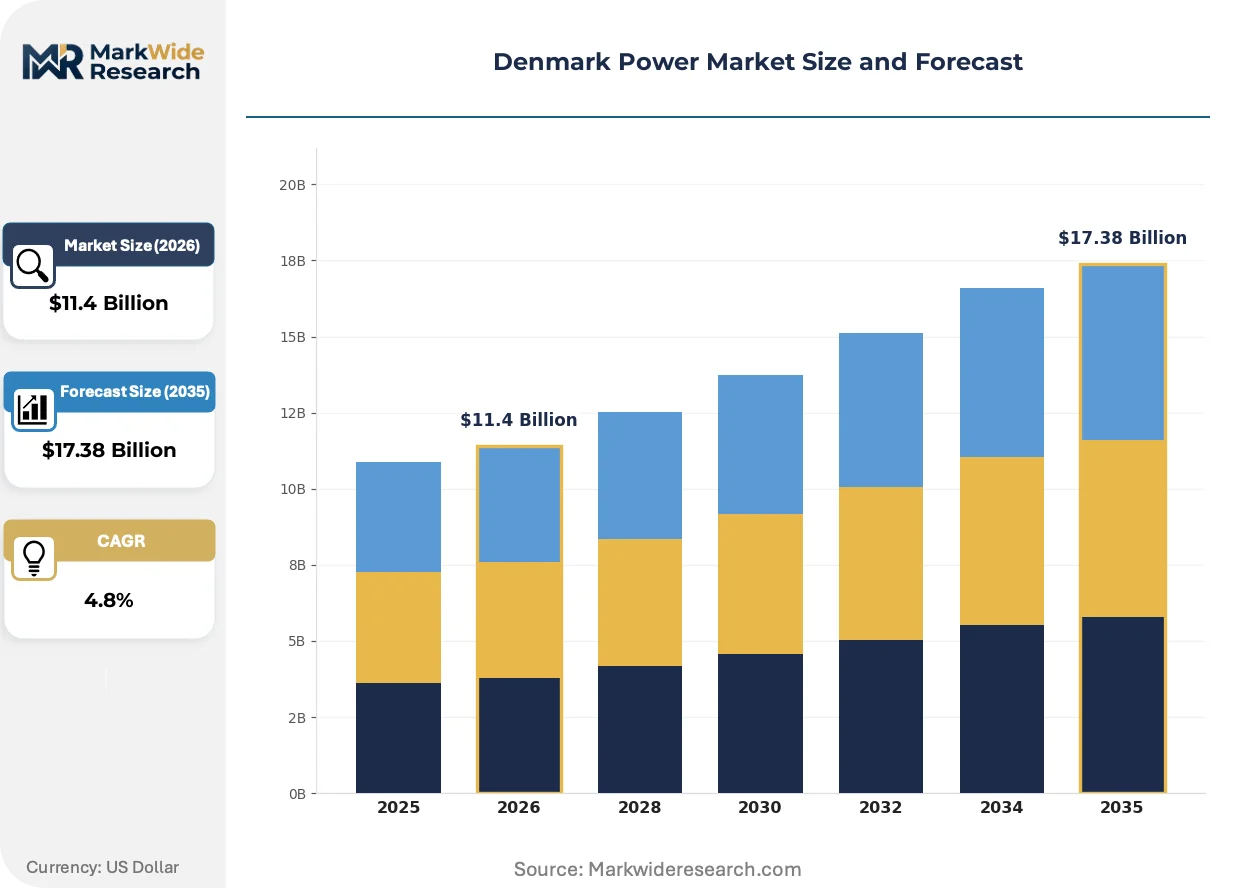
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable Energy, Fossil Fuels, Nuclear Power, Hydropower Technology: Wind Turbines, Solar Photovoltaics, Combined Cycle Gas Turbines, Biomass Conversion Application: Residential Use, Commercial Use, Industrial Use, Grid Storage End User: Utility Companies, Manufacturers, Government Agencies, Consumers |
| Companies Covered | Energinet, Better Energy A/S, Ørsted A/S, Siemens Gamesa Renewable Energy SA, Centrica Energy Trading A/S, Vattenfall A/S, European Energy A/S, NKT A/S, Vestas Wind Systems A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Power Market Strategic Shifts
Technology convergence between offshore wind and electrolyzer manufacturing is redefining project economics, while regulatory tightening around carbon accounting pushes asset owners toward real-time monitoring systems.
Modular offshore substation design is fragmenting the traditional integrated platform procurement model. Danish developers now source transformer modules, switchgear enclosures, and control systems from separate specialist suppliers. This decomposition reduces single-source dependency but introduces interface risk during North Sea commissioning campaigns.
The EU Green Deal's Carbon Border Adjustment Mechanism tightens emissions disclosure requirements for imported steel and cement used in turbine foundations. Danish project developers now mandate Environmental Product Declarations from foundation fabricators. Baltic Sea supply chains face particular scrutiny as Polish and German component sources fall under new reporting thresholds.
Corporate buyers in Zealand's pharmaceutical corridor now contract directly with offshore wind farms through sleeved power purchase agreements, bypassing traditional utility intermediaries. Novo Nordisk and Lundbeck facilities negotiate 10-15 year fixed-price structures that transfer volume risk to developers. This disintermediation compresses utility retail margins while expanding developer origination teams.
Denmark Power Market Segmentation
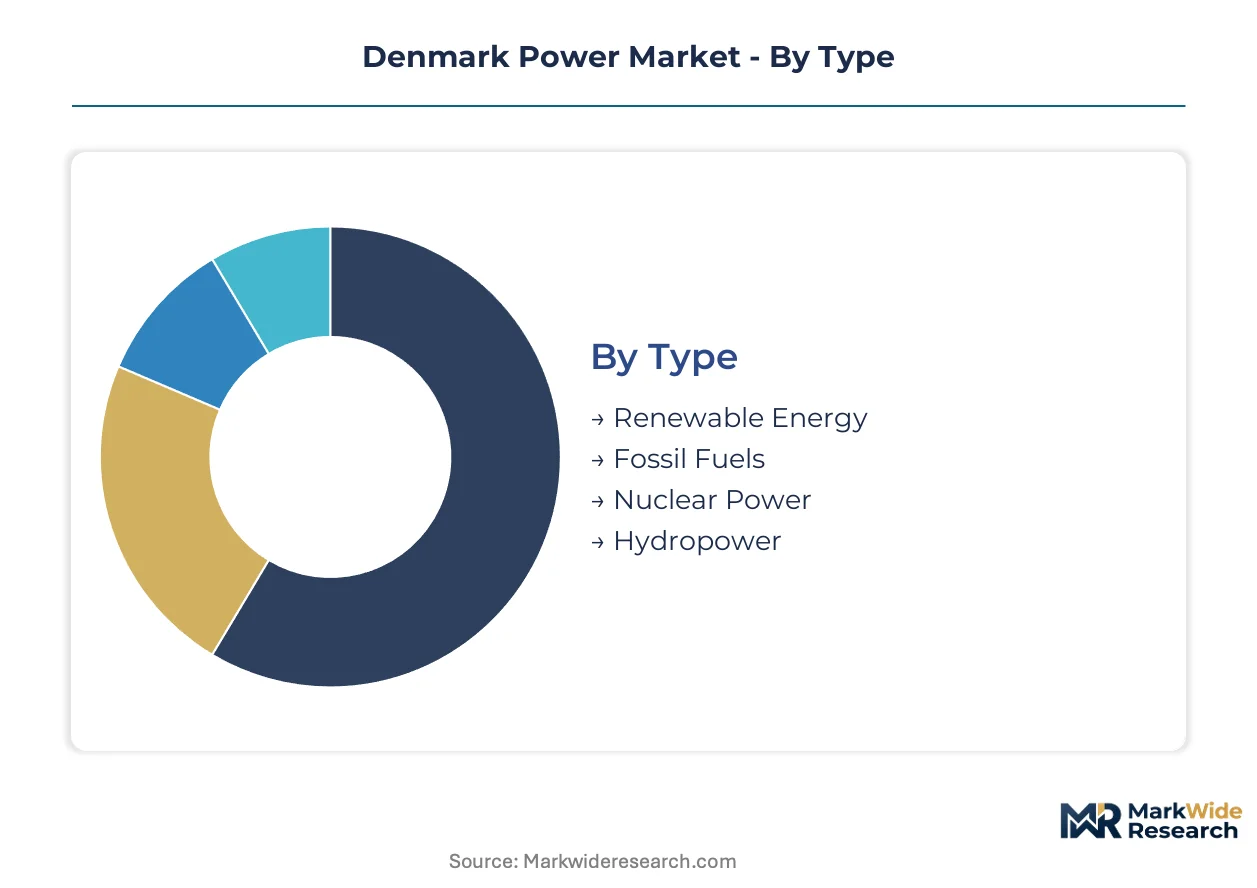
Denmark's power market segmentation reflects the Danish Energy Agency's enforcement priorities under the Climate Act, where regulatory licensing frameworks differentiate treatment across generation types and grid connection tiers. Understanding these segment boundaries clarifies how carbon pricing mechanisms and offshore permitting timelines reshape competitive positioning.
Type:
The Danish Energy Agency applies divergent permitting timelines across generation categories, with offshore wind receiving accelerated environmental review while fossil fuel extensions face mandatory carbon neutrality alignment assessments.
- Renewable Energy:Wind, solar, and biomass generation dominate capacity additions under EU Green Deal alignment. Zealand industrial clusters and Copenhagen district heating networks drive procurement of bundled renewable supply contracts.
- Fossil Fuels:Residual coal and natural gas plants face structural margin compression from EU ETS carbon pricing floors. Early retirement schedules accelerate as dispatch economics deteriorate against renewable baseload.
- Nuclear Power:Denmark maintains a legislative prohibition on nuclear generation. No commercial capacity operates; policy debates remain peripheral to mainstream energy planning.
- Hydropower:Limited domestic potential constrains deployment to minor run-of-river installations. Norwegian interconnectors effectively substitute for indigenous hydro capacity.
Established volume favors Renewable Energy; emerging adoption favors Fossil Fuels transition pathways.
Technology:
Cost tier differentiation separates mature offshore wind platforms from emerging solar-storage hybrids competing on distributed commercial applications.
- Wind Turbines:Offshore installations at 15 MW+ capacity ratings anchor generation expansion. North Sea lease rounds and Jutland manufacturing scale sustain domestic supply chain density.
- Solar Photovoltaics:Commercial rooftop and agricultural ground-mount deployments accelerate fastest in distributed applications. Zealand pharmaceutical facilities and Jutland farming cooperatives drive procurement.
- Combined Cycle Gas Turbines:Peaking and grid balancing roles persist for residual gas infrastructure. Flexible dispatch contracts face shortening tenors under carbon pricing pressure.
- Biomass Conversion:Copenhagen CHP plant retrofits sustain district heating supply. Forestry residue sourcing and carbon accounting verification dominate operational economics.
Capital intensity concentrates in Wind Turbines; margin expansion potential concentrates in Solar Photovoltaics.
Application:
Customer type fragmentation distinguishes synchronized municipal heating demand from price-sensitive industrial procurement.
- Residential Use:Single-family electrification and heat pump adoption drive distributed consumption growth. Energinet tariff structures incentivize demand response participation.
- Commercial Use:Office and retail facilities seek sleeved renewable supply agreements. Copenhagen corporate buyers bypass utility intermediaries through direct developer contracts.
- Industrial Use:Pharmaceutical and food processing clusters in Zealand require high-availability power quality. Direct offshore wind offtake agreements transfer volume risk from buyers to developers.
- Grid Storage:Lithium-ion and emerging flow battery installations manage intermittency for Utility Companies. Frequency response markets and arbitrage revenue streams determine project financeability.
Revenue stability favors Industrial Use; technology innovation favors Grid Storage.
End User:
Procurement authority and risk tolerance separate centralized utility buyers from fragmented consumer segments.
- Utility Companies:Energinet and regional distributors manage transmission infrastructure and balancing markets. Long-term power purchase agreement origination teams expand to capture corporate buyer demand.
- Manufacturers:Industrial facilities with captive generation assets seek behind-the-meter solar and storage optimization. Novo Nordisk and Lundbeck operations exemplify direct renewable contracting.
- Government Agencies:Municipal heating authorities and transport electrification programs coordinate demand aggregation. Danish Energy Agency auction design shapes procurement timelines.
- Consumers:Household and small commercial buyers face regulated retail tariff structures. Limited switching options constrain price elasticity.
Contract sophistication favors Manufacturers; volume scale favors Utility Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Zealand-Jutland pricing asymmetry concentrates procurement authority in Copenhagen's industrial corridor while peripheral regions absorb transmission congestion costs. This geographic split shapes developer origination strategies and utility portfolio rebalancing.
Zealand
Pharmaceutical manufacturing clusters and district heating networks drive synchronized electricity demand. The Danish Energy Agency prioritizes offshore lease rounds in the Øresund strait. Copenhagen's corporate buyers negotiate direct renewable supply contracts that bypass traditional utility intermediaries.
Jutland
Onshore wind manufacturing supply chains and agricultural solar deployment dominate capacity additions. Energinet grid codes mandate frequency response standards for interconnectors to Germany. Aarhus industrial facilities seek behind-the-meter storage optimization for price arbitrage.
North Sea Offshore Zones
High-capacity turbine procurement cycles compress as developers queue for foundation installation vessels. EU Green Deal carbon pricing mechanisms improve project financeability against fossil baseload. Kriegers Flak and Thor lease areas anchor generation expansion through 2030.
Funen
Biomass conversion retrofits sustain district heating supply for mid-sized municipalities. Forestry residue sourcing constraints and carbon accounting verification dominate operational economics. Odense manufacturing clusters require high-availability power quality for automation systems.
Bornholm
Island grid isolation creates unique storage and balancing market opportunities. Rønne port infrastructure supports offshore construction logistics for Baltic Sea developments. The Danish Energy Agency designates the island as a testbed for power-to-X electrolyzer integration.
Denmark Power Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Danish power market. The structure concentrates around integrated offshore developers with project pipeline depth, turbine manufacturers with domestic supply chain scale, and distributed renewable specialists competing on commercial solar-storage hybrids. Three archetypes dominate: vertically integrated North Sea developers, Jutland-anchored manufacturing scale players, and agile distributed generation platforms. Competitive moves center on direct corporate offtake origination and electrolyzer partnership structures for power-to-X revenue diversification.
Among integrated offshore developers, Ørsted A/S and Vattenfall A/S occupy positions that exemplify pipeline-led origination strategies. Vestas Wind Systems A/S anchors the manufacturing-scale archetype with Jutland-based production density. These three entities represent the dominant competitive vectors: project development at scale, domestic supply chain capture, and technology platform integration.
| Leading Market Players |
|---|
| Energinet |
| Better Energy A/S |
| Ørsted A/S |
| Siemens Gamesa Renewable Energy SA |
| Centrica Energy Trading A/S |
| Vattenfall A/S |
| European Energy A/S |
| NKT A/S |
| Vestas Wind Systems A/S |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month foundation installation vessel booking backlogs concentrate pricing power among specialized marine construction fleets, compressing developer margins while amplifying cost pass-through to long-term power purchase agreements. This lead-time tension shapes how Danish offshore wind projects absorb copper and rare earth volatility through contract escalation clauses.
Pricing Analysis
Configured-to-order turbine supply contracts command 12-18% premiums over standardized platform procurement, reflecting nacelle customization for 15 MW+ offshore ratings and site-specific foundation engineering. Price differentiation rests on IEC 61400 certification tiers and Danish Energy Agency permitting timelines, with premium tiers bundling extended warranty and remote monitoring services. Cost compression in standardized onshore wind components intensifies as Vestas and Siemens Gamesa scale Jutland manufacturing. Utility Companies exhibit lowest price sensitivity through 20-year offtake structures, while agricultural solar buyers in Jutland arbitrage spot volatility with lithium-ion buffering.
Supply Chain Analysis
Inventory cycles for generator windings and power electronics extend to 90-120 days, exposing developers to rare earth price swings from Chinese and Vietnamese processing facilities. The supply chain draws from Germany for transformer modules, Poland for steel foundations, and South Korea for HVDC cable insulation. Single-source vulnerability concentrates in European nacelle assembly capacity, where queue bottlenecks limit annual installation velocity regardless of lease award pace. Distribution runs through Energinet-coordinated grid codes mandating frequency response standards for German and Swedish interconnectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
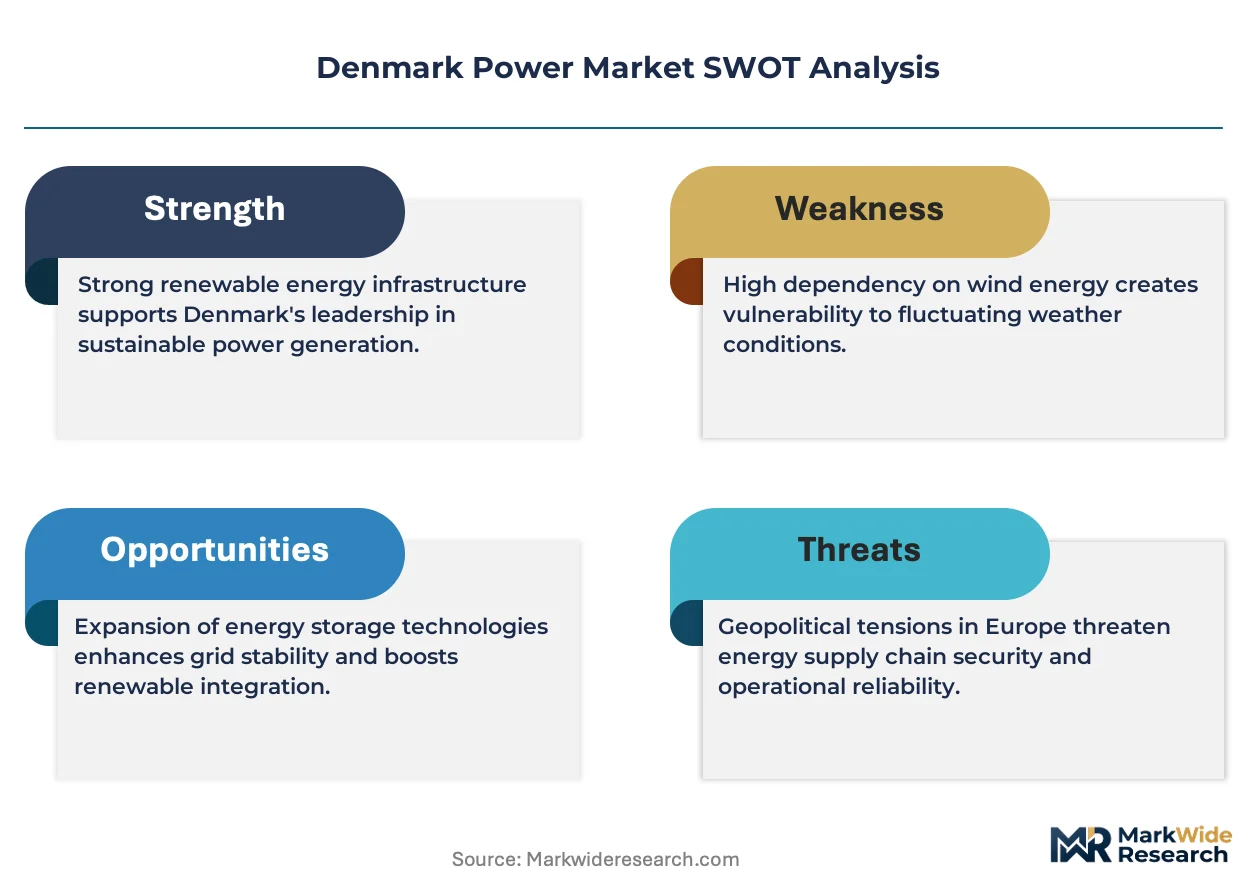
The Denmark Power Market functions as a regulatory-moat arena where Danish Energy Agency licensing entrenchment and Energinet grid code compliance create switching costs that protect incumbent positions against disruptive entry.
For Market Incumbents: Secure long-term turbine supply agreements ahead of North Sea lease round acceleration, locking in nacelle allocation before European assembly capacity constraints worsen. Deepen backward integration into foundation fabrication through Baltic Sea steel partnerships, insulating project economics from EU Carbon Border Adjustment Mechanism disclosure requirements. Prioritize electrolyzer joint ventures to capture power-to-X revenue streams before green hydrogen offtake standardizes. For New Entrants and Emerging Players: Behind-the-meter storage optimization for Zealand pharmaceutical facilities represents the most penetrable service-layer gap, where Novo Nordisk and Lundbeck operations seek direct renewable supply bypassing utility intermediaries. Target Jutland agricultural cooperatives with solar-storage hybrid offerings that arbitrage Energinet spot price volatility through lithium-ion buffering. Deploy sleeved power purchase agreement origination teams to disintermediate traditional utility retail margins. For Investors and Strategic Acquirers: Long-term, this sits as a contracted-cash-flow infrastructure play because 15-20 year offtake structures with investment-grade corporate buyers insulate revenue streams from merchant price exposure. Acquisition targets should display pipeline depth in Danish Energy Agency lease rounds and electrolyzer partnership traction. The signal to watch is auction design evolution for near-shore wind zones, which will determine whether power-to-X demand materializes as credible offtake alternative.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Origination | Direct corporate contracting with Zealand pharmaceutical clusters transfers volume risk to developers. |
| Electrolyzer Joint Venture Formation | Green hydrogen offtake for ammonia production diversifies revenue beyond merchant electricity sales. |
| Foundation Fabrication Backward Integration | Baltic Sea steel partnerships reduce EU Carbon Border Adjustment Mechanism compliance exposure. |
| Modular Offshore Substation Sourcing | Decomposed procurement of transformer modules and switchgear reduces single-source dependency. |
| District Heating Network Electrification | Copenhagen municipal heat pump integration creates synchronized demand stabilizing renewable intermittency. |
Study Parameters
A standing panel of utility planning officers, offshore wind project developers, EPC contractors, and grid operators provided ongoing calibration across primary fieldwork, with secondary validation drawing from Danish Energy Agency licensing databases, Energinet transmission data, EU ETS carbon price records, and North Sea lease round filings. Bottom-up project economics modeling triangulated against top-down capacity deployment trajectories.
Consistency checks against IEA renewable capacity forecasts and European wind industry association installation statistics validated volume and value outputs across the projection horizon. Segmentation modeling incorporated generation source, project scale tier, regulatory framework, and regional grid interconnection type. CAGRs derived from compounded annual capacity addition assumptions, with electrolyzer scale-up pace and corporate offtake penetration serving as critical sensitivity inputs.
Material uncertainties — turbine supply queue bottlenecks, rare earth price volatility, and power-to-X demand materialization — sit outside the modeled envelope. Forecasts reflect documented assumptions about Danish Energy Agency auction timing and Energinet grid code evolution. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Middle East and Africa Combined Heat & Power Market
Power
Equatorial Guinea Power Market
Power
Brazil Power Market
Power
Asia-Pacific Power Market
Power
Electric Arc Furnaces Market
Power
Global Advanced Marine Power Supply Market
Power
Recloser Control Market
Power
Qatar Power Market
Power
LNG Power Barge Market
Power
Power Rental Market
Power
Residential Portable Inverter Generator Market
Power
Colombia Power Market
Power
Asia-Pacific Alternating Current (AC) Drive Market
Power
Russian Federation Power Market
Power
Gas Freeing Fan Market
Power
HVDC Capacitor Market