
 Single-Phase Microinverter Market | 2026-2036
Single-Phase Microinverter Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Phase Microinverter Market Insights
Project finance and third-party leasing arrangements for residential solar installations is narrowing the competitive field to vendors with balance-sheet capacity or banking partnerships. Enphase Energy leverages its integrated energy management platform to sustain premium positioning across North American installer networks. Hoymiles anchors its expansion through module-level electronics specialization that competes aggressively on cost-per-watt metrics. APsystems differentiates via dual-module architecture that controls manufacturing complexity while extending product reach into European and Asia-Pacific markets.
A single-phase microinverter converts direct current from individual photovoltaic modules into grid-synchronous alternating current using maximum power point tracking at the panel level, typically handling power ratings between 250 and 500 watts with efficiency thresholds exceeding 96 percent. Grid-tied configurations dominate unit shipments as net metering policies sustain homeowner economics, while hybrid architectures represent the fastest-growing product category as battery storage attachment rates climb across residential installations. Rooftop deployment leads installation-type demand, though building-integrated photovoltaics command margin premiums where aesthetic constraints drive specification decisions.
FERC Order 2222 enables aggregated distributed energy resources to participate in wholesale electricity markets, reshaping revenue stacking opportunities for microinverter-equipped residential systems. California's Title 24 building code mandates solar readiness on new construction, while the EU Green Deal performance standards and Australia's Clean Energy Council accreditation framework collectively tighten efficiency and safety certification requirements. Stakeholders must monitor how evolving interconnection standards and inverter grid-support functionalities reshape product roadmaps and regional market access conditions.
Market Dynamics
Module-level power electronics mandates from California's Title 24 building code are compressing product development cycles and forcing certification investments that favor scaled manufacturers over emerging entrants.
Growth Catalysts
- California Title 24 Solar Readiness Mandate:New construction requirements in the United States' largest residential market are embedding microinverter specifications into building plans before homeowner purchase decisions occur.
- Feed-in Tariff Structures:Germany's renewable energy remuneration framework sustains homeowner investment calculus by guaranteeing long-term revenue streams from rooftop generation assets.
- Maximum Power Point Tracking:Panel-level optimization technology extracts incremental energy yield from partial shading conditions that string inverters cannot address, improving system economics in mature solar markets.
Market Restraints
- Semiconductor Component Volatility:Power MOSFET and IGBT pricing fluctuations strain manufacturing cost structures for electronics-integrated hardware vendors.
- East Asian Manufacturing Concentration:Contract electronics assembly gravity in Taiwan and mainland China creates geopolitical exposure and logistics vulnerability for brands without diversified sourcing.
- String Inverter Substitution:Three-phase string architectures with rapid shutdown devices capture cost-sensitive commercial rooftop segments that might otherwise adopt microinverter technology.
Strategic Opportunities
- Battery Storage Convergence:Hybrid microinverter architectures integrating DC-coupled battery management open attachment revenue from residential storage retrofit demand.
- Building-Integrated Photovoltaics:Aesthetic-driven rooftop specifications in premium suburban developments command margin premiums for compact, low-profile inverter form factors.
- Aggregator Platform Integration:FERC Order 2222 compliance enables virtual power plant participation, creating software-enabled revenue stacking beyond hardware sales.
Industry Challenges
- Grid-Code Certification Velocity:Evolving IEEE 1547 and UL 1741-SA standards require continuous firmware validation that extends product launch timelines.
- Installer Network Training Burden:Module-level commissioning complexity demands field technician upskilling that strains distributor support infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Phase Microinverter Market |
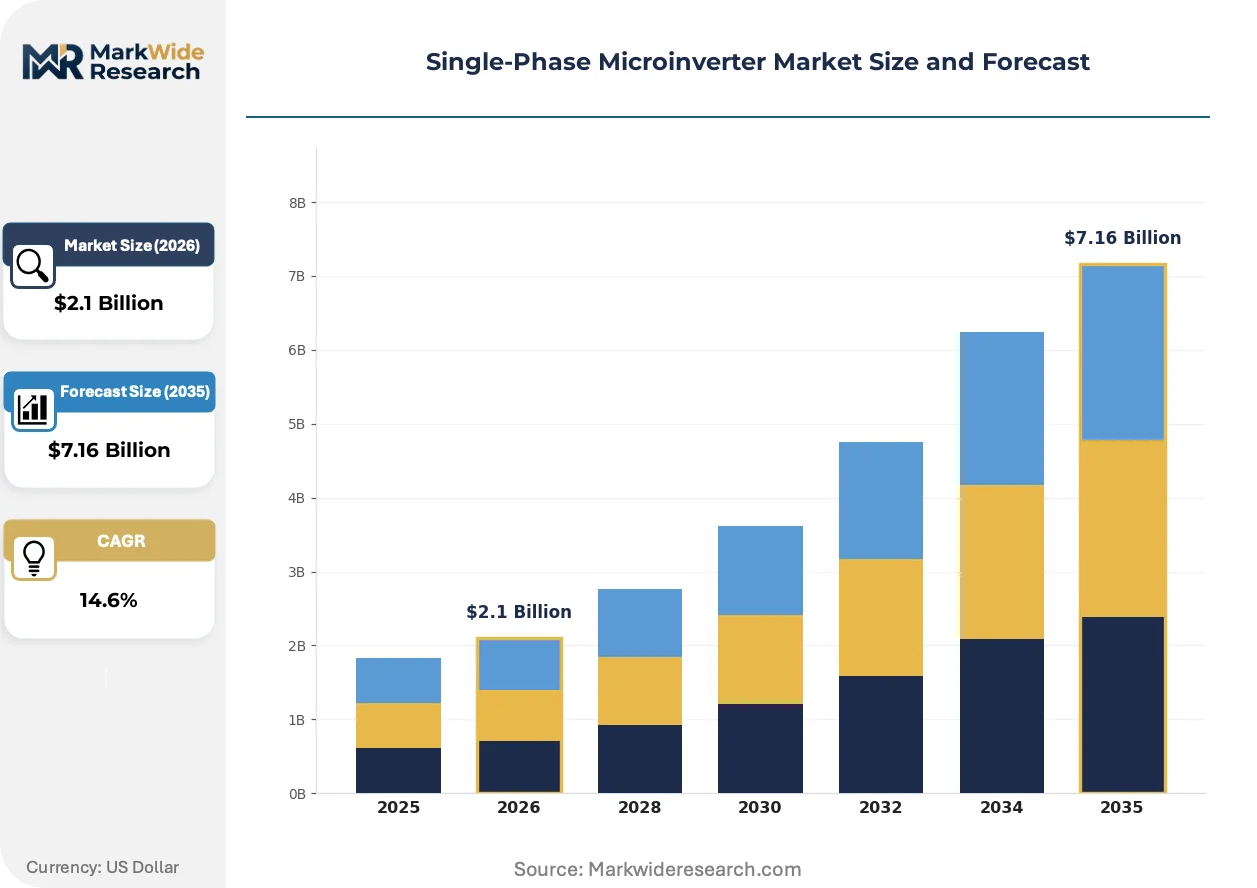
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grid-Tied, Off-Grid, Hybrid, Standalone Technology: Centralized, Distributed, Wireless, Firmware End User: Residential, Commercial, Industrial, Utility Installation Type: Rooftop, Ground-Mounted, Building-Integrated, Others |
| Companies Covered | Enphase Energy, Hoymiles, APsystems, Growatt New Energy, Altenergy Power Systems, Zhejiang Beny Electric, Sparq Systems, Deye Inverter, Chilicon Power, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Phase Microinverter Market Trends and Innovations
Silicon carbide power semiconductors and software-defined inverter control are compressing hardware differentiation windows while elevating firmware and energy management platform competition.
Silicon carbide MOSFETs replace traditional silicon IGBTs in next-generation microinverter designs, cutting switching losses and enabling higher power density in sub-500-watt form factors. Residential installers in California and Australia are specifying these units for space-constrained rooftop configurations. This semiconductor transition is collapsing the thermal management cost advantage that previously separated premium and standard product tiers.
The EU Green Deal performance standards and Australia's Clean Energy Council accreditation framework are tightening efficiency and safety certification requirements simultaneously across multiple jurisdictions. Manufacturers must maintain parallel testing protocols for electromagnetic compatibility and grid-support functionality. Small-scale vendors without dedicated compliance teams face exclusion from these regulated procurement channels.
Homeowner purchasing behavior is fragmenting between third-party leasing arrangements and direct system ownership, bifurcating installer sales motions and support requirements. The leasing channel concentrates procurement decisions among finance-integrated national installers, while cash buyers favor local contractors with established service relationships. This channel polarization is most pronounced in the United States, where tax credit monetization complexity favors lease structures for credit-constrained households.
Single-Phase Microinverter Market Segmentation
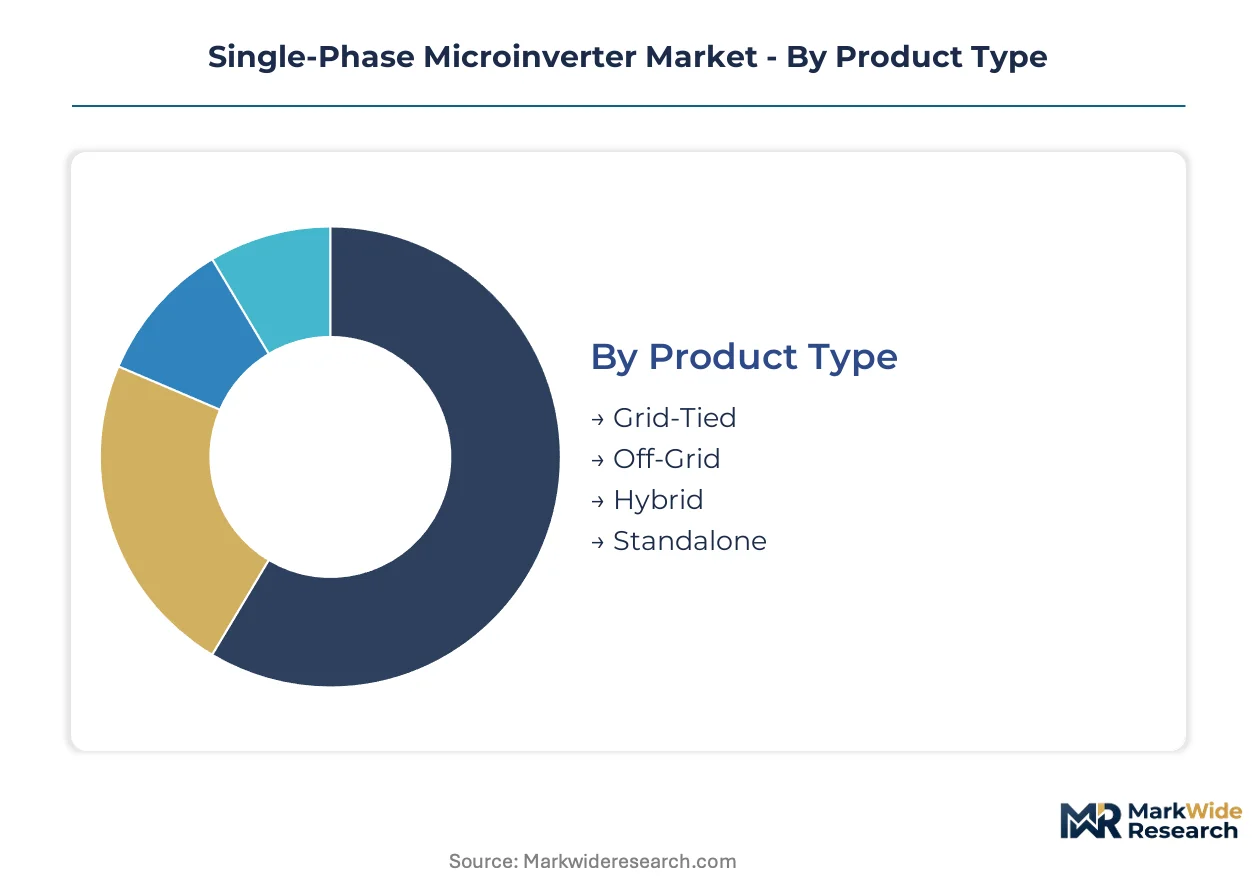
Single-phase microinverter procurement patterns diverge sharply across installation contexts and buyer sophistication levels. Segmentation reveals how grid-code mandates, battery attachment preferences, and mounting constraints reshape vendor product roadmaps and distribution priorities.
Product Type:
Grid-synchronization requirements and storage integration ambitions split the product landscape into four distinct hardware configurations.
- Grid-Tied:Direct AC coupling to utility infrastructure without battery buffering dominates unit shipments across net metering jurisdictions. California installer networks specify these units for standard rooftop retrofits where export compensation sustains homeowner payback calculations.
- Hybrid:DC-coupled battery management integration enables storage retrofit attachment and backup power functionality. Australian and German residential markets are driving specification shifts toward these architectures as blackout resilience and self-consumption optimization climb buyer priority lists.
- Off-Grid:Standalone battery-charging configurations serve remote installations beyond utility reach. Rural Australian properties and mountain cabins in the Alps represent concentrated demand pockets.
- Standalone:Modular AC generation units without grid-export capability power dedicated loads in agricultural and recreational applications.
The dominant share belongs to Grid-Tied configurations, while Hybrid architectures are closing the gap fastest.
Technology:
Power electronics topology choices determine thermal performance, monitoring granularity, and firmware update pathways.
- Distributed:Panel-integrated semiconductor packages with dedicated MPPT circuits maximize energy harvest under partial shading. Suburban California installations with complex roof geometries and tree coverage patterns specify these units most heavily.
- Firmware:Software-defined control platforms enable remote grid-code compliance updates and predictive maintenance alerts. German utilities mandate these capabilities for aggregated residential fleet participation.
- Centralized:Shared power stage architectures reduce per-watt manufacturing costs for cost-sensitive multi-module arrays.
- Wireless:Mesh-networked monitoring eliminates DC conduit runs and simplifies commissioning in historic building retrofits.
Distributed technology holds the largest installed base, though Firmware-enabled platforms are expanding most quickly as grid-support requirements tighten.
End User:
Buyer scale and financing sophistication reshape procurement channel structures and service expectations.
- Residential:Single-family homeowners purchasing through installer networks or third-party lease arrangements constitute the volume anchor. Net metering policy stability in the United States and feed-in tariff structures in Germany sustain investment visibility for this segment.
- Commercial:Small business rooftop arrays under 100kW face string inverter competition but adopt microinverters where rapid shutdown compliance and monitoring granularity justify premium positioning.
- Industrial:On-site generation for manufacturing facilities rarely specifies single-phase units given three-phase load requirements.
- Utility:Distributed generation portfolios aggregate residential fleets rather than deploying dedicated single-phase hardware.
Residential deployment commands overwhelming volume concentration, while Commercial applications are gaining share fastest as code compliance complexity rises.
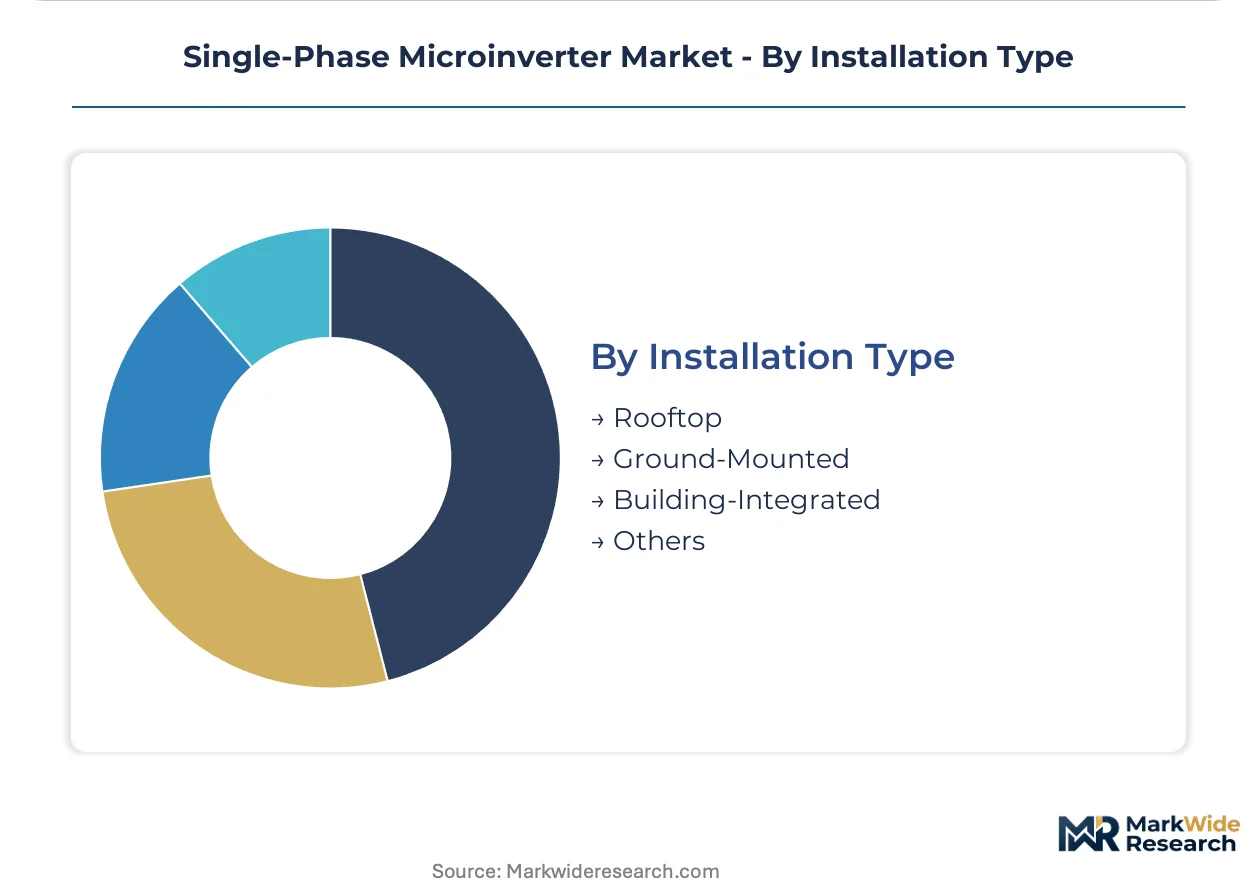
Installation Type:
Mounting constraints and aesthetic requirements segment hardware form factor and thermal management specifications.
- Rooftop:Sloped residential roof planes with standard rail mounting dominate unit consumption across suburban United States developments. Space-constrained configurations favor compact silicon carbide designs with reduced heat sink mass.
- Building-Integrated:Façade and skylight-embedded photovoltaics demand ultra-low-profile inverter housings that preserve architectural lines. Premium German and Swiss residential markets accept substantial cost premiums for these specifications.
- Ground-Mounted:Backyard and garden array configurations for detached rural properties use standard rooftop-rated hardware with weatherized enclosures.
- Others:Carport, pergola, and awning installations represent niche applications with custom mounting adaptations.
Rooftop deployment maintains the dominant position, yet Building-Integrated specifications are climbing the fastest as aesthetic constraints tighten in premium housing markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from East Asian electronics manufacturing hubs supply microinverter hardware to residential solar markets across North America and Europe. Import dependency for power semiconductors and contract assembly services shapes procurement risk profiles for brands without diversified sourcing footprints.
United States
California's Title 24 solar readiness mandate embeds microinverter specifications into new construction permits before homeowner purchase decisions occur. FERC Order 2222 enables aggregated distributed energy resources to participate in wholesale electricity markets, creating revenue stacking opportunities for residential systems. Installer networks in the Los Angeles Basin and San Francisco Bay Area concentrate procurement volume for silicon carbide-enabled compact designs.
Germany
Feed-in tariff structures sustain homeowner investment calculus by guaranteeing long-term revenue streams from rooftop generation assets. The EU Green Deal performance standards tighten efficiency certification requirements for module-level power electronics entering the single-family housing market. Bavarian and Baden-Württemberg suburban developments drive specification shifts toward firmware-enabled grid-support functionality.
Australia
Blackout resilience and self-consumption optimization climb buyer priority lists as grid instability concerns spread across eastern states. The Clean Energy Council accreditation framework mandates electromagnetic compatibility and rapid shutdown compliance for all residential solar installations. Queensland and New South Wales distributed generation clusters anchor procurement volume for hybrid architectures with DC-coupled battery management.
China
Domestic module production scale creates captive demand for cost-optimized microinverter hardware in distributed solar programs. MIIT efficiency standards and GB certification requirements govern grid-tied inverter deployment across residential rooftop initiatives. Yangtze River Delta contract electronics assembly capacity supplies component sourcing for brands targeting export markets.
Japan
Space-constrained urban rooftops in dense metropolitan areas favor compact, high-efficiency inverter form factors with reduced heat sink mass. METI grid-code requirements mandate remote firmware update capabilities and predictive maintenance alerts for residential fleet participation. Kanto region installer networks specify distributed MPPT technology to address partial shading from adjacent buildings.
Single-Phase Microinverter Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on cost-per-watt metrics. The vendor base organizes around three strategic archetypes: energy management platform operators, module-level electronics pure-plays, and dual-module architecture specialists. Consolidation pressure concentrates among scaled manufacturers with balance-sheet capacity for certification investments. Geographic expansion and strategic partnerships represent the dominant competitive moves as regulatory fragmentation tightens.
Among North American platform operators, Enphase Energy exemplifies the integrated energy management archetype. Hoymiles occupies a position within the module-level electronics specialization tier. APsystems represents the dual-module architecture approach that controls manufacturing complexity while extending geographic reach.
| Leading Market Players |
|---|
| Enphase Energy |
| Hoymiles |
| APsystems |
| Growatt New Energy |
| Altenergy Power Systems |
| Zhejiang Beny Electric |
| Sparq Systems |
| Deye Inverter |
| Chilicon Power |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta contract electronics assembly capacity shapes downstream pricing power for microinverter brands targeting export markets. Manufacturing concentration in this cluster compresses unit economics for scaled players while forcing smaller vendors toward premium positioning or exit.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on silicon carbide semiconductor grade and UL 1741-SA certification tier, with California installer networks least sensitive to premium positioning. Cost compression in standard-tier hardware is intensifying because power MOSFET sourcing volatility strains contract manufacturers. Cash-constrained residential lease channels exhibit highest price sensitivity, while firmware-enabled grid-support platforms command sustained premiums.
Supply Chain Analysis
Hon Hai Precision Industry and Delta Electronics hold dominant contract-manufacturing capacity for power electronics assembly. Component sourcing draws from Taiwan wafer fabrication, mainland China PCB lamination, and South Korea passive component supply. Single-source vulnerability concentrates in silicon carbide substrate supply where Wolfspeed and Coherent control merchant capacity. Distribution runs through national installer networks in the United States, specialized solar distributors in Germany, and utility-integrated channels in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-phase microinverter deployment sits in early-cycle expansion as module-level power electronics mandates embed hardware specifications into new construction codes ahead of homeowner purchase decisions.
For Market Incumbents: Harden firmware update infrastructure against evolving IEEE 1547 grid-code requirements that demand continuous validation cycles. Deepen backward integration into silicon carbide semiconductor sourcing to insulate margin structures from power device volatility. Prioritize installer network certification investments that lock out emerging entrants lacking balance-sheet capacity for parallel testing protocols.
For New Entrants and Emerging Players: Building-integrated photovoltaic retrofits in premium Swiss and German suburban developments represent the most penetrable entry point for compact form-factor specialists. Hybrid microinverter architectures with DC-coupled battery management in Australian eastern states offer second-mover attachment revenue from storage retrofit demand. Partner with regional EPC contractors lacking direct supplier relationships with scaled platform operators.
For Investors and Strategic Acquirers: Long-term, this sits as a grid-services infrastructure play because FERC Order 2222 and equivalent aggregation frameworks transform residential hardware into wholesale market participation assets. Acquisition targets should display firmware-enabled fleet management capabilities and compliance velocity across multiple jurisdictional certifications. Monitor California Title 24 amendment velocity and EU Green Deal implementation rigor as inflection indicators for standard-tier margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Semiconductor Transition | Collapses thermal management cost tiers while enabling higher power density in space-constrained rooftop configurations. |
| Firmware-Defined Grid-Support Platform | Enables remote IEEE 1547 compliance updates that extend product lifecycle and reduce field service costs. |
| Hybrid Architecture Battery Integration | Captures residential storage retrofit attachment revenue as blackout resilience climbs buyer priority lists. |
| Building-Integrated Photovoltaic Form Factor | Commands margin premiums in premium housing markets where aesthetic constraints override cost optimization. |
| Virtual Power Plant Aggregator Partnership | Unlocks software-enabled revenue stacking beyond hardware sales through wholesale market participation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with residential installer network managers, utility distributed resource planners, EPC procurement leads, and power electronics contract manufacturing executives. Secondary validation drew from FERC interconnection filings, California Energy Commission Title 24 compliance databases, EU Green Deal implementation guidance, and Clean Energy Council accreditation records. Bottom-up unit shipment modeling and top-down addressable market sizing were triangulated against contract manufacturer capacity disclosures.
Calibration against historical penetration curves in net metering jurisdictions anchored projection logic across the analysis window. Segmentation dimensions modeled include product architecture grid-tied versus hybrid, power electronics topology distributed versus centralized, end-user residential versus commercial, and installation type rooftop versus building-integrated. CAGRs were derived from installer survey pipeline data and regulatory mandate implementation schedules. Forecast inputs incorporated semiconductor cost curve trajectories and evolving grid-code certification velocity.
Practitioners should monitor silicon carbide substrate supply allocation shifts and IEEE 1547 revision timing for early signals of margin structure change. Forecasts reflect assumptions around net metering policy stability and feed-in tariff continuity that material regulatory rollback would invalidate. Quarterly review of California Title 24 permit data and EU member state transposition progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Critical Power Market
Power
Resonant Power Converters Market
Power
Canada Power Market
Power
Direct Current Power System Market
Power
Argentina Power Market
Power
Oxy-Hydrogen Generators Market
Power
Sudan Power EPC Market
Power
Asia-Pacific Package Substation Market
Power
Europe Frequency Converter Market
Power
Existent Gum Steam Generator Market
Power
Power Rental Market
Power
North America Power Market
Power
Global Power Line Communication (PLC) Systems Market
Power
Equatorial Guinea Power Market
Power
HVDC Capacitor Market
Power
Gas Freeing Fan Market