
 Asia-Pacific Microturbine Market | 2026-2036
Asia-Pacific Microturbine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Microturbine Market Insights
Power purchase agreements and equipment leasing is fragmenting competitive dynamics across the Asia-Pacific microturbine sector. Capstone Green Energy Corporation leverages its distributed service network to sustain aftermarket revenue in remote Australian installations. Mitsubishi Power, Ltd. anchors large-scale cogeneration bids through integrated project finance structures. IHI Power Systems Co., Ltd. competes on compact unit designs optimized for Japanese building codes.
Asia-Pacific microturbines are compact gas turbines typically rated below 500 kW, employing recuperated Brayton cycles with single-shaft radial compressor-expanders to achieve electrical efficiencies of 25-35 percent. These systems serve commercial and industrial facilities requiring on-site power with optional heat recovery. Natural gas configurations dominate current deployments due to established pipeline infrastructure across Japan, South Korea, and eastern China. Cogeneration applications command premium margins where thermal loads align with electrical demand profiles. Off-grid installations in Indonesia's island provinces and Australia's Pilbara region represent the fastest-growing addressable pocket.
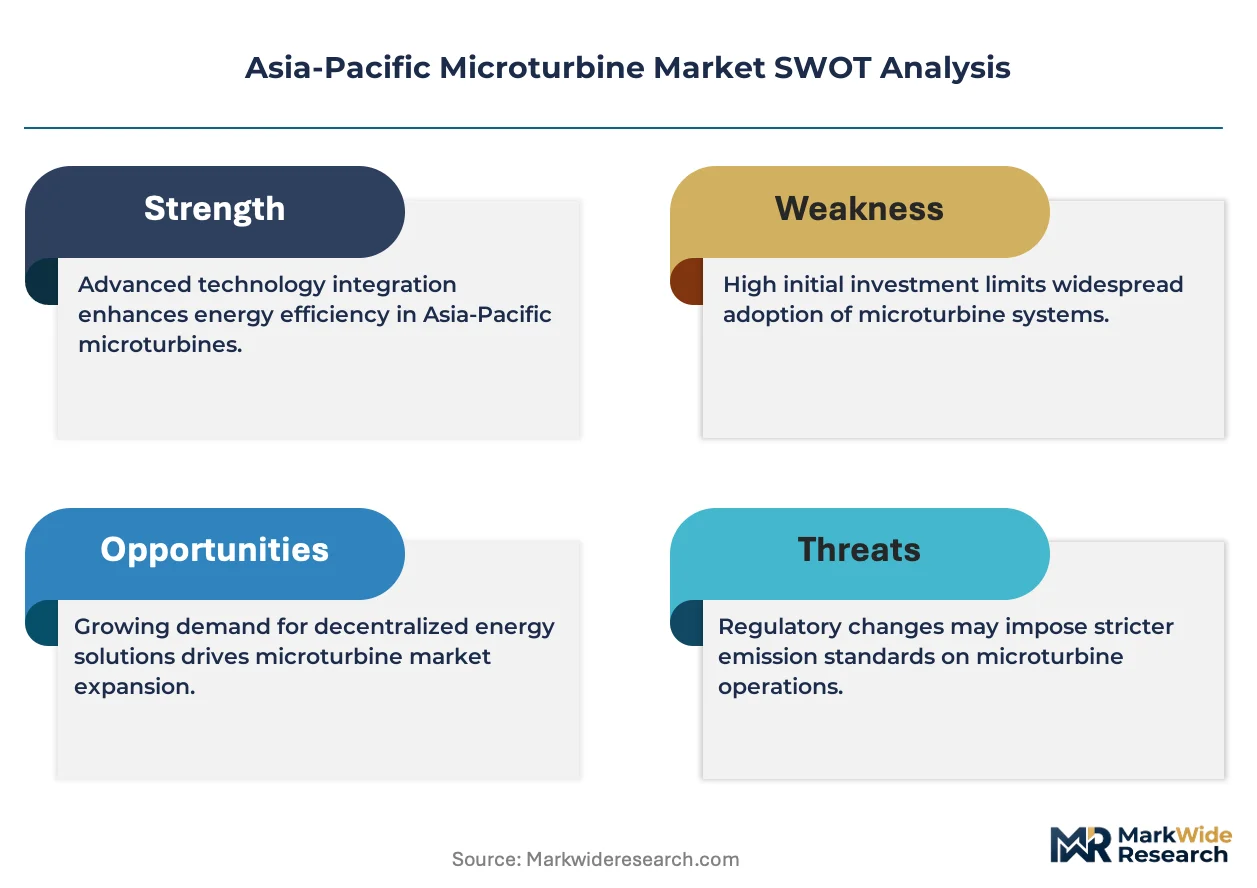
Japan's METI enforces efficiency standards under its Top Runner program that elevate minimum performance thresholds for distributed generation equipment. India's CEA grid interconnection regulations determine whether microturbine assets qualify for net metering tariffs or must island during utility outages. China's MIIT GB standards for gas-fired distributed energy equipment shape import certification requirements for foreign suppliers. Stakeholders must track evolving hydrogen blending specifications across Australian state jurisdictions to assess fuel-flexible product roadmaps.
Market Dynamics
Japan's METI Top Runner efficiency mandates are compressing equipment replacement cycles across commercial building portfolios, forcing suppliers to accelerate recuperator material upgrades and control system iterations to maintain certification eligibility.
Growth Catalysts
- Remote Mining Electrification:Australia's Pilbara and Queensland mining corridors are retiring diesel gensets for natural gas microturbines to satisfy Scope 1 emissions targets and reduce fuel logistics costs.
- India's PLI Clean Energy Incentive:The Production Linked Incentive scheme for advanced chemistry cell and component manufacturing is lowering balance-of-system costs for distributed gas turbine installations.
- Hydrogen Fuel Flexibility:Australian state-level hydrogen blending roadmaps are accelerating demand for fuel-flexible microturbine architectures capable of 30% H2 co-firing without hardware retrofits.
Market Restraints
- Recuperator Alloy Cost Volatility:Inconel and Haynes alloy prices for high-temperature heat exchangers fluctuate with nickel mining output concentrated in Indonesia and the Philippines.
- Grid Interconnection Friction:India's CEA regulations create permitting delays for net-metered distributed generation assets, forcing project developers into island-only configurations.
- Lithium-Ion Substitution Threat:Battery energy storage systems paired with solar PV are capturing commercial peak-shaving applications previously served by natural gas cogeneration.
Strategic Opportunities
- Indonesian Archipelago Off-Grid:Java-Bali grid extension gaps and Sumatran industrial parks present unserved demand for containerized microturbine packages with LNG vaporization skids.
- Waste Heat-to-Cooling Convergence:Absorption chiller integration with microturbine exhaust streams is opening district cooling contracts in Singapore's commercial precincts and Bangkok hospitals.
- Power Purchase Agreement Innovation:Energy-as-a-service contracts with 10-15 year terms are displacing capital sales in Australian remote resource camps and Japanese hotel chains.
Industry Challenges
- Turbomachinery Specialist Scarcity:Radial compressor design and high-speed bearing engineering expertise concentrates in Japan's IHI, Mitsubishi, and Kawasaki supply chains, constraining regional service expansion.
- MIIT GB Certification Timelines:China's import type-testing for gas-fired distributed energy equipment extends 14-18 months, freezing foreign suppliers out of fast-track industrial park developments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Microturbine Market |
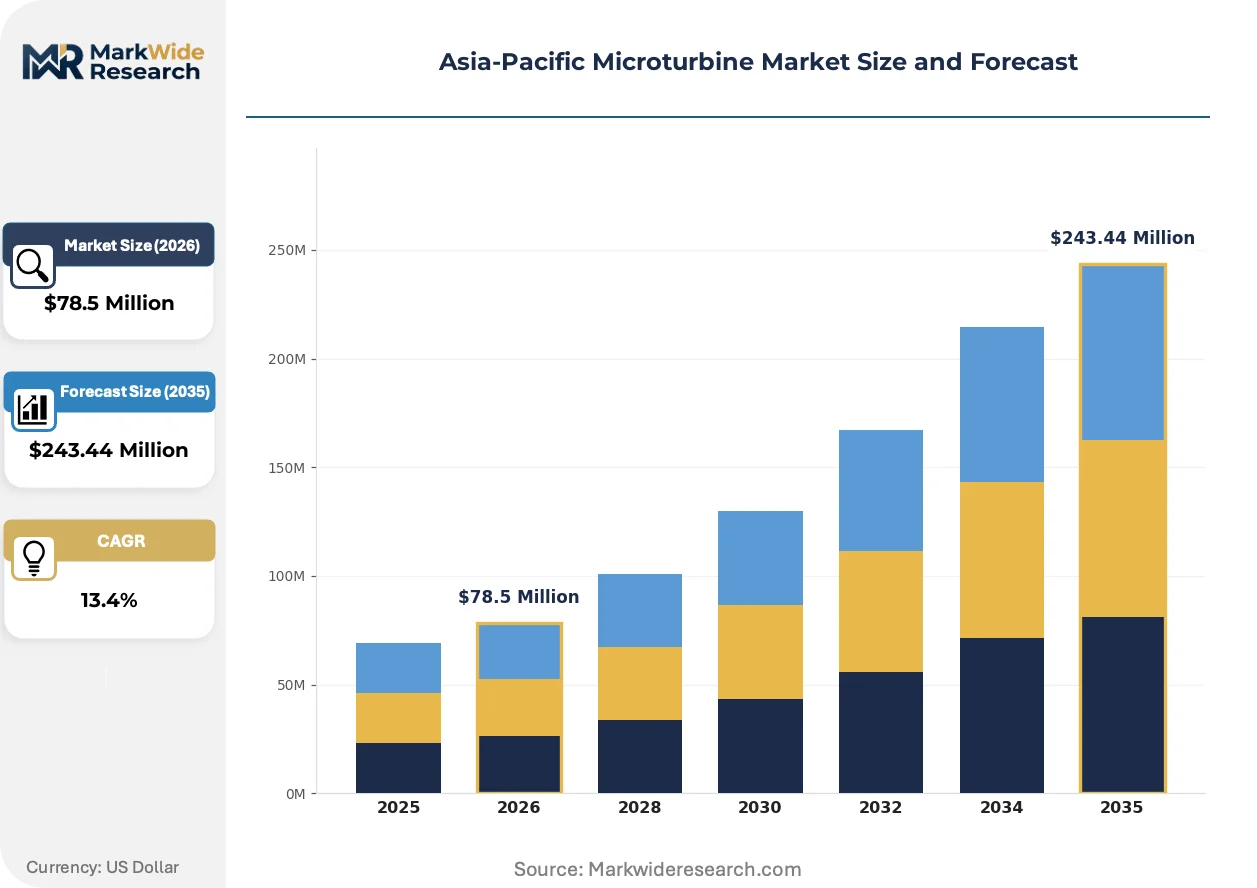
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $243.44 Million |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Gas, Diesel, Biogas, Hydrogen Application: Cogeneration, Remote Power Generation, Backup Power, Stationary Power Generation End User: Industrial, Commercial, Institutional, Residential Installation: On-Grid, Off-Grid, Microgrid, Combined Heat and Power |
| Companies Covered | Mitsubishi Power, Ltd., Kawasaki Heavy Industries, Ltd., Capstone Green Energy Corporation, Ansaldo Energia S.p.A., Shanghai Electric Gas Turbine Co., Ltd., Bharat Heavy Electricals Limited, Toyota Turbine & Systems Inc., IHI Power Systems Co., Ltd., FlexEnergy Solutions, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Microturbine Market Trends and Innovations
Recuperated Brayton cycle architectures are converging with solid oxide fuel cell stacks and battery buffers to create dispatchable hybrid prime movers. This reconfiguration is altering project finance structures and O&M contracting models across the Asia-Pacific distributed generation sector.
Capstone's C200 and C1000 series microturbines are hybridizing with lithium-ion storage and solar inverters to form microgrids for Australian mining camps and Indonesian island resorts. Rio Tinto and BHP are piloting these configurations at Western Australia iron ore sites to displace diesel during daylight hours. The technology is compressing payback periods for remote power assets while complicating warranty liability allocation between turbine, battery, and inverter OEMs.
Japan's METI has tightened Top Runner program efficiency thresholds for sub-500kW gas turbines effective fiscal year 2026, requiring minimum 32% electrical efficiency at ISO conditions. Equipment suppliers must redesign recuperator surface area-to-volume ratios and combustor residence times to qualify for commercial building subsidies. Mitsubishi Power and IHI Power Systems are accelerating ceramic matrix composite testing to meet the new thermal performance envelope without unit footprint expansion.
Japanese commercial real estate investment trusts are consolidating building energy procurement under centralized asset managers, shifting purchasing authority from individual facility managers to portfolio-level sustainability officers. These officers specify equipment based on 15-year total cost of ownership models rather than upfront capital cost. The shift is visible in Tokyo's Marunouchi and Osaka's Umeda districts, where bundled microturbine-cogeneration contracts now outnumber single-site sales three to one.
Asia-Pacific Microturbine Market Segmentation
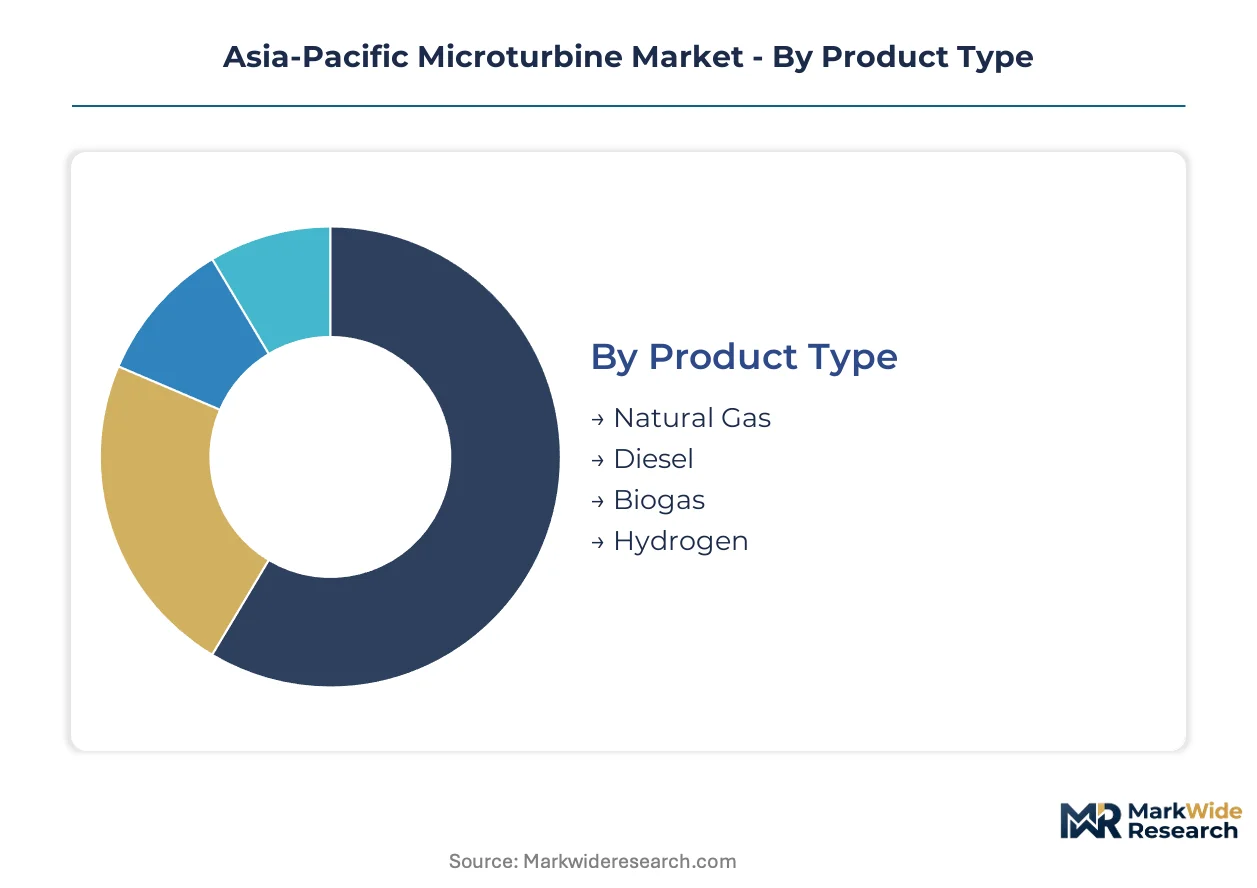
Microturbine deployment patterns across the Asia-Pacific region diverge sharply by fuel availability, grid infrastructure maturity, and thermal load profiles. Segmentation reveals where technology substitution is occurring versus where incumbent systems retain structural advantages.
Product Type:
Mature pipeline infrastructure favors established fuels, while hydrogen blending roadmaps are forcing architectural flexibility into new procurement specifications.
- Natural Gas:Configurations rated 30-500 kW dominate current installations, leveraging existing distribution networks across Japan, South Korea, and eastern Australia. Tokyo commercial REITs and Queensland mining camps specify these units for 15-year total cost of ownership contracts, though nickel alloy recuperator costs create margin pressure.
- Hydrogen:Fuel-flexible architectures capable of 30% H2 co-firing without hardware retrofits are capturing pilot tenders in Western Australia and South Australia. State-level blending mandates are accelerating OEM roadmaps, with ceramic matrix composite combustor testing underway to handle higher flame temperatures.
- Diesel:Remains specified for Indonesian archipelago installations lacking gas pipeline access, though Pilbara mining operators are actively retiring these assets.
- Biogas:Agricultural waste and landfill gas applications concentrate in Thailand's industrial estates and Vietnam's rice processing corridors.
Natural Gas handles the majority of throughput; Hydrogen is expanding most quickly on share.
Application:
Revenue concentration aligns with thermal load continuity, creating divergent margin structures across use cases.
- Cogeneration:Combined heat and power configurations achieve premium pricing where thermal demand profiles match electrical output, particularly in Singapore district cooling contracts and Bangkok hospital installations. Absorption chiller integration with microturbine exhaust streams is opening multi-year service agreements.
- Remote Power Generation:Containerized packages with LNG vaporization skids serve Java-Bali grid extension gaps and Sumatran industrial parks, displacing diesel gensets at Australian iron ore sites under Scope 1 emissions targets.
- Backup Power:Critical facility specifications in Osaka's Umeda district and Seoul commercial precincts require sub-10 minute start capability.
- Stationary Power Generation:Base-load configurations for continuous industrial process power in Japan's chemical manufacturing clusters.
Cogeneration commands the steepest margin premiums; Remote Power Generation is climbing the fastest on deployment volume.
End User:
Procurement authority consolidation is shifting specification criteria from capital cost to lifecycle performance modeling.
- Commercial:Japanese building portfolio managers now centralize energy procurement decisions, bundling microturbine-cogeneration contracts across Tokyo Marunouchi and Osaka Umeda districts. These officers specify equipment based on 15-year total cost of ownership rather than upfront capital cost.
- Industrial:Australian mining operators including Rio Tinto and BHP are piloting hybrid microturbine-battery-solar configurations to displace diesel during daylight hours, compressing payback periods while complicating warranty liability allocation.
- Institutional:Hospital and university campuses in Bangkok and Singapore specify waste heat-to-cooling convergence for district cooling contracts.
- Residential:Limited to high-end distributed generation in Japan's single-building commercial-residential hybrids.
Commercial segment anchors current revenue; Industrial buyers are gaining share fastest on project scale.
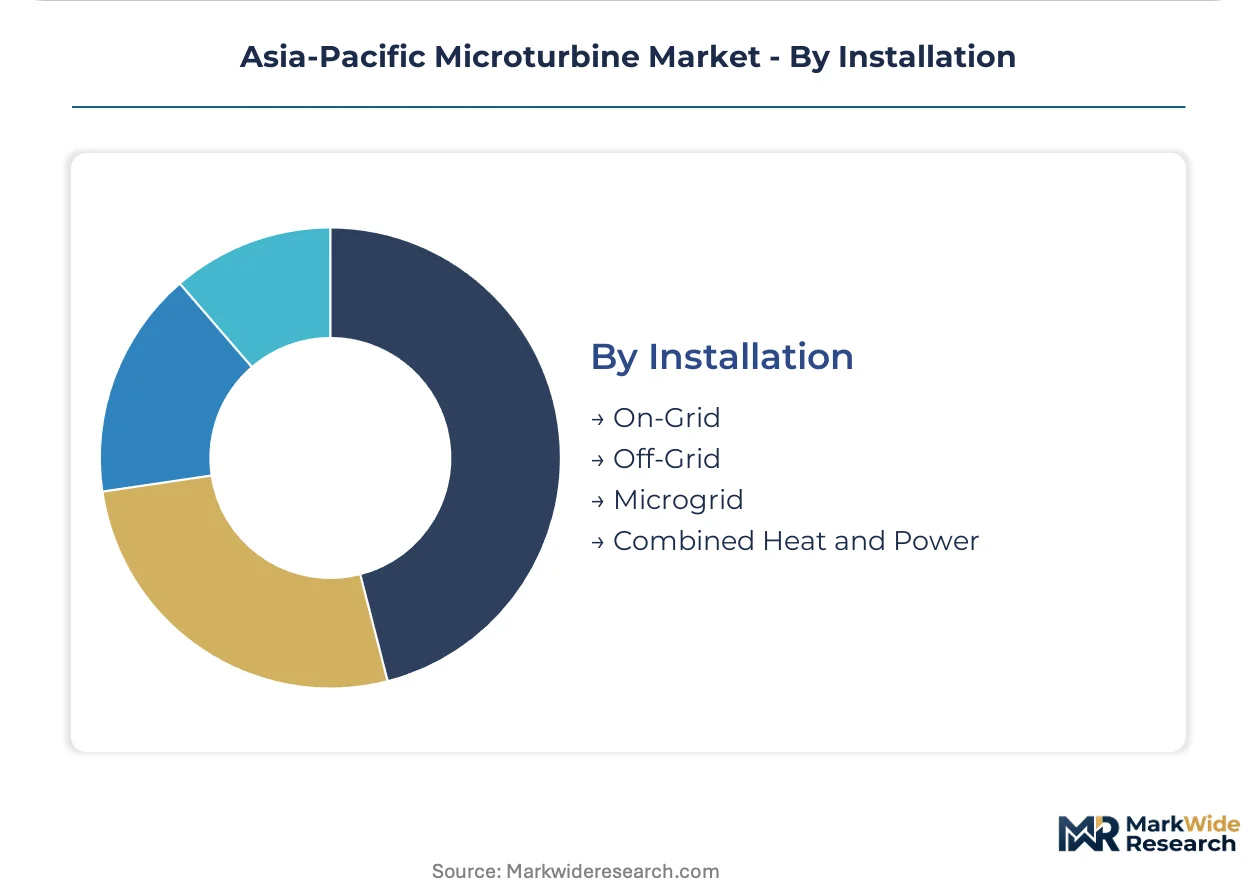
Installation:
Grid interconnection regulations determine configuration economics, with island-capable systems commanding hardware premiums.
- Off-Grid:Standalone installations in Indonesia's island provinces and Australia's Pilbara region represent the fastest-growing addressable pocket, requiring containerized packages with integrated LNG vaporization.
- Microgrid:Hybrid configurations combining microturbines with lithium-ion storage and solar inverters are forming dispatchable prime movers at remote resource camps, altering project finance structures and O&M contracting models.
- On-Grid:Net-metered installations face permitting friction under India's CEA regulations, forcing developers into island-only configurations.
- Combined Heat and Power:Thermal integration specifications dominate Japanese commercial building tenders under METI Top Runner efficiency mandates.
Off-Grid configurations absorb the largest deployment volume; Microgrid installations are expanding most rapidly on technology convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portfolio-level sustainability officers at Japanese commercial REITs and Australian mining procurement teams drive specification authority across the region. These buyer archetypes prioritize 15-year total cost of ownership over upfront capital expenditure. Grid interconnection friction and hydrogen blending mandates reshape deployment economics.
Japan
Tokyo's Marunouchi and Osaka's Umeda districts concentrate bundled microturbine-cogeneration contracts under centralized asset managers. METI's Top Runner program enforces 32% minimum electrical efficiency for sub-500kW gas turbines from fiscal year 2026. Mitsubishi Power and IHI Power Systems accelerate ceramic matrix composite testing to meet thermal performance thresholds without footprint expansion.
Australia
Rio Tinto and BHP pilot hybrid microturbine-battery-solar configurations at Pilbara iron ore sites to displace diesel during daylight hours. Western Australian and South Australian state jurisdictions advance hydrogen blending roadmaps requiring 30% H2 co-firing capability. Containerized packages with integrated LNG vaporization serve Queensland mining corridors retiring diesel gensets for Scope 1 compliance.
India
Maharashtra and Gujarat industrial estates evaluate distributed gas turbine installations under the PLI scheme for advanced chemistry cell manufacturing. The CEA grid interconnection regulations create permitting delays for net-metered assets, forcing developers into island-only configurations. Bharat Heavy Electricals Limited anchors domestic fabrication capacity for captive power applications.
China
The Yangtze River Delta and Pearl River Delta industrial parks drive import demand for gas-fired distributed energy equipment. MIIT GB standards extend 14-18 month type-testing timelines, freezing foreign suppliers out of fast-track developments. Shanghai Electric Gas Turbine Co., Ltd. occupies the domestic supplier position for cogeneration tenders.
Indonesia
Java-Bali grid extension gaps and Sumatran industrial parks present unserved demand for containerized microturbine packages. LNG vaporization skids enable fuel access in archipelago provinces lacking pipeline infrastructure. Biogas applications concentrate in agricultural processing corridors where thermal loads align with electrical demand profiles.
Asia-Pacific Microturbine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement bundling and technology licensing vectors. The vendor base organizes around three archetypes: integrated project finance providers, compact unit design specialists, and distributed service network operators. Consolidation pressure concentrates in aftermarket revenue capture and remote installation service capability. Strategic moves center on hybrid system integration partnerships and hydrogen-ready product roadmaps.
Within the integrated project finance tier, Mitsubishi Power, Ltd. and IHI Power Systems Co., Ltd. occupy positions anchored to large-scale cogeneration bids and METI certification compliance. Capstone Green Energy Corporation represents the distributed service network archetype, sustaining aftermarket revenue through remote Australian installation coverage. These three entities exemplify divergent competitive positioning across bundled contracts, compact design optimization, and geographic service density.
| Leading Market Players |
|---|
| Mitsubishi Power, Ltd. |
| Kawasaki Heavy Industries, Ltd. |
| Capstone Green Energy Corporation |
| Ansaldo Energia S.p.A. |
| Shanghai Electric Gas Turbine Co., Ltd. |
| Bharat Heavy Electricals Limited |
| Toyota Turbine & Systems Inc. |
| IHI Power Systems Co., Ltd. |
| FlexEnergy Solutions |
| Others |
Pricing and Supply Chain Analysis
Nickel mining concentration in Indonesia and the Philippines directly determines margin pools for recuperator manufacturers serving Australian mining and Japanese commercial REITs. Inconel and Haynes alloy price volatility compresses equipment margins while elevating total cost of ownership premiums for fuel-flexible architectures.
Pricing Analysis
Certification level under Japan's METI Top Runner program creates the primary spread between premium and standard equipment tiers. Project-based contract pricing dominates, with 15-year energy-as-a-service agreements displacing capital sales in Australian remote camps and Japanese hotel chains. Cost compression in standard natural gas units is intensifying because ceramic matrix composite R&D expenses concentrate in premium hydrogen-ready product lines. Commercial building portfolio managers show least price sensitivity due to centralized sustainability procurement authority, while Indonesian island developers face acute capital constraints.
Supply Chain Analysis
Extended payment terms from Japanese trading houses and supply-chain finance facilities anchored to Mitsubishi and IHI project structures shape working capital dynamics for component suppliers. Manufacturing concentration rests on Japan for radial compressor assemblies, the United States for power electronics, and China for balance-of-plant fabrication. Raw material dependencies center on Indonesian nickel for recuperator alloys, Australian LNG for fuel supply infrastructure, and South Korean battery cells for hybrid configurations. Single-source vulnerability in high-temperature alloy supply creates exposure to mining export restrictions. Distribution runs through integrated EPC contractors for large cogeneration bids and OEM-direct service networks for remote Australian installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific microturbine sector sits in early-cycle expansion as hydrogen blending mandates and remote mining electrification accelerate penetration beyond traditional cogeneration strongholds.
For Market Incumbents: Pre-empt lithium-ion substitution by accelerating hybrid microturbine-battery-solar integration partnerships before battery energy storage systems capture peak-shaving applications entirely. Deepen backward integration into ceramic matrix composite supply to defend margin position against nickel alloy cost volatility and METI efficiency threshold compliance pressures. For New Entrants and Emerging Players: Indonesian archipelago grid extension gaps present the most penetrable white-space, with Java-Bali and Sumatran industrial parks lacking pipeline infrastructure and established service coverage. Target containerized LNG vaporization package configurations for unserved demand. Pursue equipment leasing partnerships with Indonesian state-owned energy distributors as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Australian remote power specialists holding contracted offtake with Rio Tinto and BHP mining camps. Long-term viability hinges on hydrogen-ready technology roadmaps and hybrid system integration capabilities. Watch Western Australian state hydrogen blending mandate implementation timelines as the inflection indicator for fuel-flexible architecture demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Product Roadmap | Ceramic matrix composite combustor testing positions OEMs for Australian state blending mandates. |
| Hybrid System Integration Partnership | Microturbine-battery-solar configurations compress payback periods at Pilbara iron ore sites. |
| Energy-as-a-Service Contract Expansion | 15-year bundled agreements displace capital sales across Japanese commercial REIT portfolios. |
| Backward Integration into Recuperator Supply | In-house nickel alloy sourcing mitigates Indonesia mining export restriction exposure. |
| Indonesian Archipelago Service Network Buildout | LNG vaporization skid integration captures unserved demand in Java-Bali grid gaps. |
Research Methodology
Desk research of METI regulatory filings, CEA grid interconnection guidelines, and Australian state hydrogen roadmaps preceded structured interviews with microturbine OEM product managers, mining camp energy procurement officers, Japanese commercial REIT sustainability directors, and Indonesian IPP project developers. Secondary validation drew from IEA distributed generation databases, customs trade data for gas turbine components, and EPC contractor project announcements. Bottom-up installation forecasts triangulated against top-down regional energy demand projections.
Assumptions held fixed include METI Top Runner efficiency thresholds, Australian state hydrogen blending timelines, and PLI scheme incentive structures, while fuel price trajectories and nickel alloy cost curves were varied across sensitivity scenarios. Segmentation modeling spanned fuel type, application, end user, and installation configuration across the projection horizon. CAGRs derived from installed base growth rates and replacement cycle compression under efficiency mandates. Forecast inputs incorporated hybrid system adoption curves and remote mining electrification commitments.
Macroeconomic conditions sit as an overlay; deviation in LNG pricing, nickel mining export policies, or Japanese commercial real estate investment cycles would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance timelines and technology cost reduction curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Solar UPS Market
Power
High Voltage DC Power System Market
Power
Europe Power Market
Power
Malaysia Power EPC Market
Power
Europe Submarine Power Cables Market
Power
Direct Current Power System Market
Power
HVDC Capacitor Market
Power
Nigeria Power Market
Power
Middle-East and Africa Power Market
Power
Power Rental Market
Power
Brazil Power Market
Power
Brunei Power Market
Power
Controllable Shunt Reactor for UHV Market
Power
Recloser Control Market
Power
Single-Phase Microinverter Market
Power
Angola Power EPC Market