
 Wireless Power Receiver Market | 2026-2036
Wireless Power Receiver Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Power Receiver Market Outlook
Asian semiconductor foundry capacity is restructuring the supply base for coil arrays and power management ICs. Texas Instruments sustains R&D intensity across multi-mode receiver architectures. NXP Semiconductors anchors European automotive qualification pipelines with AEC-Q100-grade chipsets. Qualcomm dominates smartphone-integrated receiver designs through its licensing ecosystem.
A wireless power receiver converts time-varying magnetic or electric fields into regulated DC output, typically operating at frequencies between 110-205 kHz for inductive systems or 6.78 MHz for magnetic resonance configurations, with efficiency targets exceeding 85% at rated load. Low-power receivers occupy the highest shipment volumes in smartphones and wearable devices, while high-power receivers for electric vehicle charging pads command the largest margin pools due to thermal management complexity and safety certification requirements. Inductive coupling leads in commercial deployment, though magnetic resonance is gaining traction in multi-device and spatially flexible charging scenarios.
The FCC in the United States governs RF exposure limits and spectrum allocation for wireless power transmission, while the EU's CE marking and RoHS directives enforce electromagnetic compatibility and material restriction standards for receiver modules sold in Europe. China's MIIT and GB standards dictate domestic electromagnetic emission thresholds and interoperability testing protocols. Stakeholders must monitor evolving interoperability standards between the Wireless Power Consortium's Qi specification and competing AirFuel protocols to avoid stranded technology investments.
Market Dynamics
The EU Green Deal and F-Gas Regulation are systematically dismantling wired charging infrastructure in public spaces, forcing receiver deployment into automotive cabins, retail furniture, and municipal transit systems as standard rather than premium configuration.
Growth Catalysts
- EV cabin integration mandate:Automotive OEMs embed inductive pads as factory-standard convenience features, eliminating aftermarket friction and normalizing consumer expectations across vehicle segments.
- China's MIIT interoperability protocols:Domestic smartphone and EV manufacturers accelerate receiver embedding at manufacturing scale, compressing deployment timelines for magnetic resonance architectures.
- Qi specification dominance:The Wireless Power Consortium's interoperability standard consolidates design investment, reducing stranded technology risk and concentrating R&D toward efficiency optimization above 85% at rated load.
Market Restraints
- Copper coil array cost volatility:Raw material price swings in LME copper futures directly compress margin pools for high-power receiver manufacturers serving EV charging pad segments.
- Asian foundry concentration:Taiwan and South Korean semiconductor fabrication capacity bottlenecks create single-source dependency for power management ICs and coil driver architectures.
- AirFuel protocol fragmentation:Competing magnetic resonance standards delay consumer confidence and retail inventory commitment, forcing dual-mode receiver complexity that inflates bill-of-materials costs.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Production-linked incentives attract coil winding and PCB assembly capacity, creating regional supply alternatives to East Asian concentration.
- Healthcare device sterilization requirements:Enclosed, contactless charging eliminates connector corrosion risks in implantable and wearable medical monitors, opening FDA 510(k) pathway expansion.
- FCC Part 18 RF exposure relaxation:Updated field strength thresholds for 6.78 MHz magnetic resonance systems enable spatially flexible multi-device charging in commercial furniture and hospitality fixtures.
Industry Challenges
- AEC-Q100 automotive qualification timelines:Extended thermal cycling and EMC validation periods delay chipset vendor revenue recognition by 18-24 months from tape-out to production release.
- Patent thicket navigation:Dense overlapping claims in magnetic resonance coil geometries and foreign object detection algorithms inflate licensing costs and litigation exposure for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Power Receiver Market |
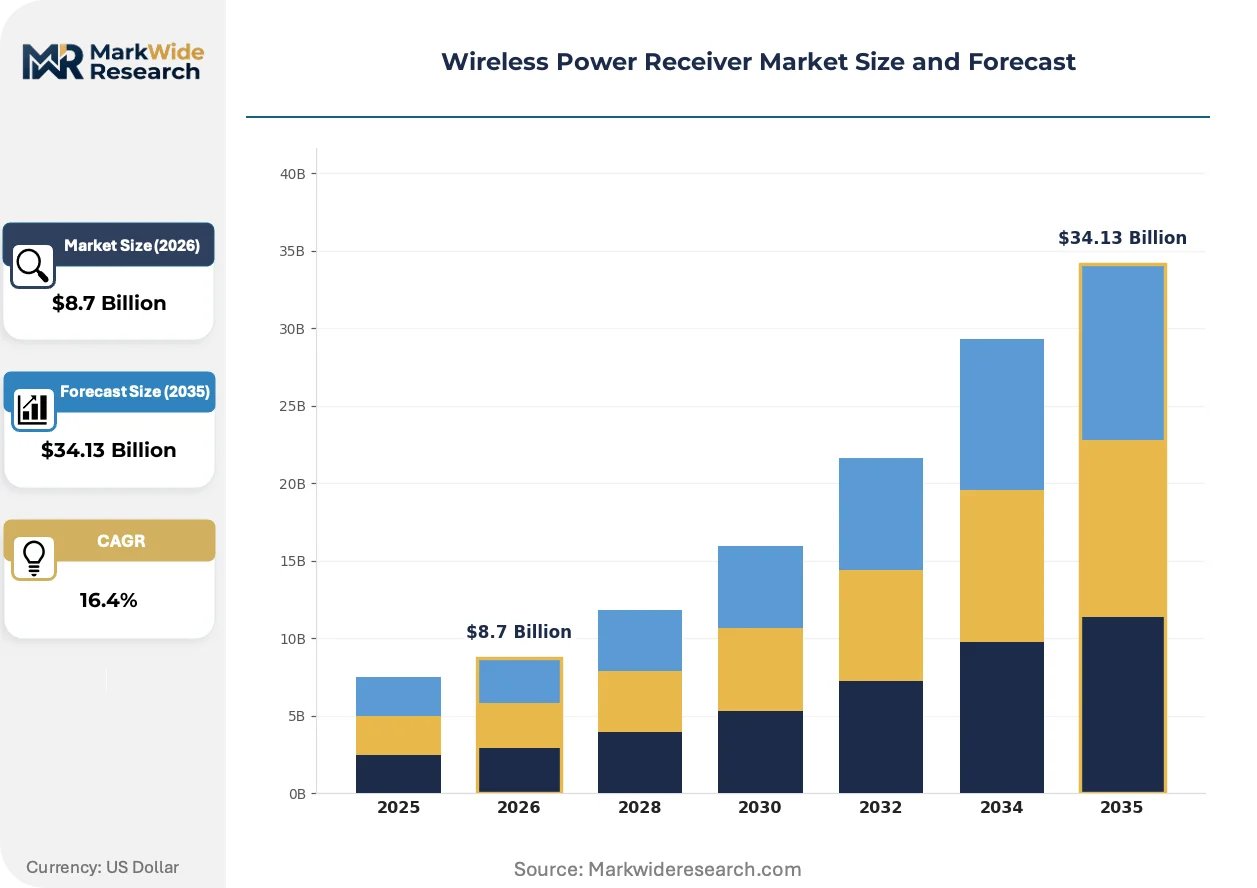
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Power Receivers, Medium-Power Receivers, High-Power Receivers, Ultra-Low-Power Receivers Technology: Magnetic Resonance, Inductive Coupling, Radio Frequency, Capacitive Coupling End User: Consumer Electronics, Automotive Industry, Medical Devices, Industrial Equipment Application: Smartphones, Electric Vehicles, Wearable Devices, IoT Devices |
| Companies Covered | Qualcomm, Texas Instruments, NXP Semiconductors, STMicroelectronics, Broadcom, Infineon Technologies, Renesas Electronics, Analog Devices, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Power Receiver Market Strategic Shifts
Receiver architectures are fragmenting into application-specific configurations as power levels diverge across smartphone, automotive, and industrial segments. Thermal management and foreign object detection now dominate engineering resource allocation.
Multi-mode receiver chipsets capable of switching between 110-205 kHz inductive and 6.78 MHz magnetic resonance protocols are modularizing hardware design. Automotive Tier 1 suppliers adopt these flexible architectures to serve multiple OEM platforms without discrete redesign cycles. This modularity compresses development timelines and reduces SKU proliferation across vehicle model years.
The EU's F-Gas Regulation and associated Ecodesign requirements are mandating removal of wired charging ports from publicly accessible infrastructure. Municipal transit authorities and retail operators must retrofit or replace legacy installations, redirecting capital toward embedded receiver modules. This regulatory pressure concentrates demand in European automotive and furniture manufacturing clusters.
Enterprise procurement of wireless charging infrastructure is consolidating toward integrated furniture-and-technology bundles. Facility managers specify complete conference table and workstation solutions rather than discrete pad procurement. This bundling shift elevates contract furniture manufacturers to primary vendor status, displacing traditional electronics distributors in North American and European commercial real estate deployments.
Wireless Power Receiver Market Segmentation
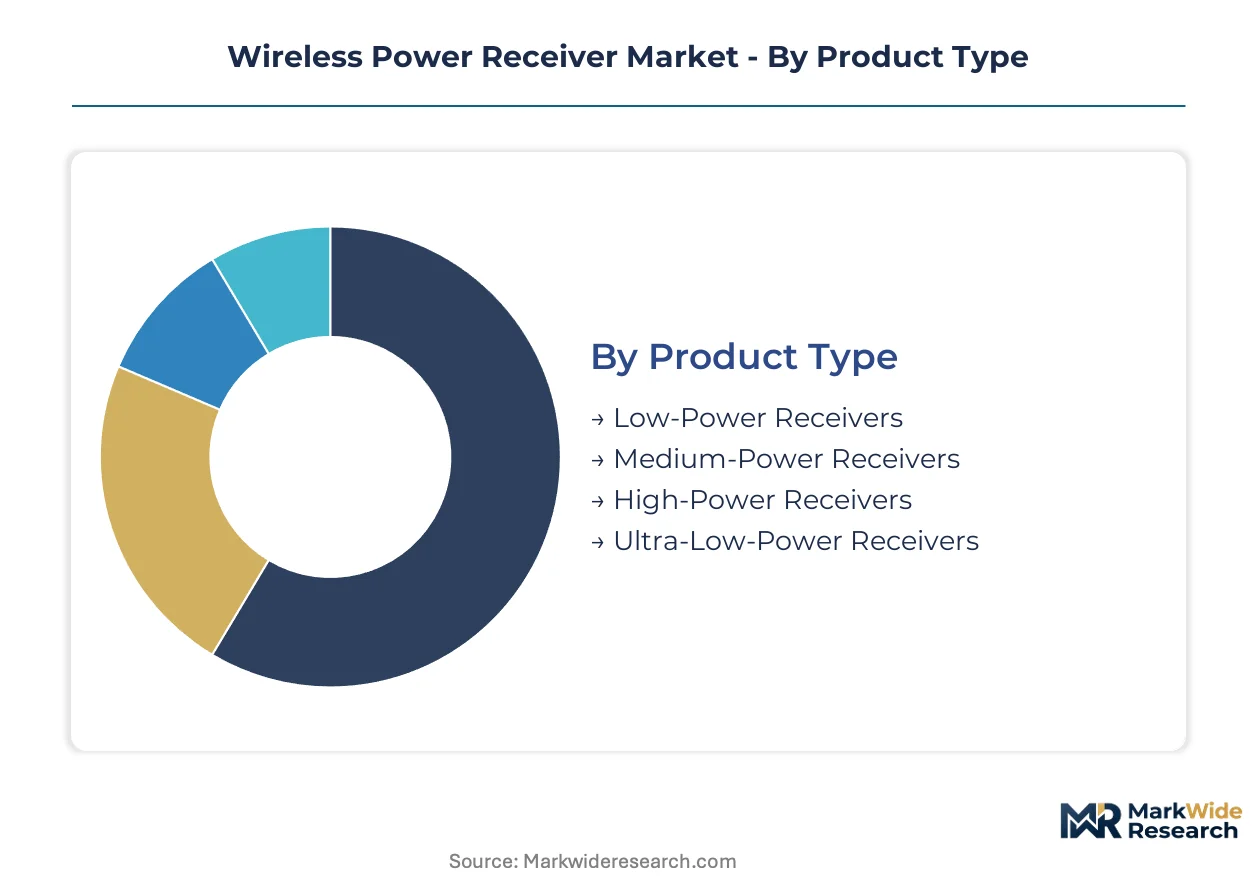
Receiver architectures fragment sharply across power levels and coupling technologies, with upgrade cycles in automotive cabins and smartphone refreshes driving replacement demand. Segmentation discipline separates margin pools from volume plays, directing capital toward qualification-heavy automotive chipsets or high-turnover consumer electronics modules.
Product Type:
Replacement cycles accelerate at opposite ends of the power spectrum, with smartphone refresh rates compressing ultra-low-power turnover while EV platform longevity stretches high-power receiver amortization.
- Low-Power Receivers:Coil arrays and power management ICs typically handle 5-15W output for handheld devices. Smartphone manufacturers in China embed these as standard features across mid-tier and flagship lines, with MIIT interoperability protocols compressing design validation timelines.
- High-Power Receivers:Thermal management systems and foreign object detection circuits manage 3.6-11kW transfer for EV charging pads. Automotive OEMs in Germany and the United States specify AEC-Q100-qualified chipsets, where extended thermal cycling validation creates 18-24 month revenue recognition delays.
- Medium-Power Receivers:15-100W configurations serve laptop and tablet charging applications.
- Ultra-Low-Power Receivers:Sub-1W harvesters target hearing aids and disposable medical sensors.
Low-Power Receivers sit at the top of the volume ranking, with High-Power Receivers climbing the fastest.
Technology:
Cost tiers separate established inductive deployments from magnetic resonance investments still absorbing R&D overhead.
- Inductive Coupling:Operating at 110-205 kHz, this mature architecture dominates commercial deployment through Qi specification alignment. The Wireless Power Consortium's interoperability standard consolidates design investment, reducing stranded technology risk for furniture and automotive integrators.
- Magnetic Resonance:6.78 MHz operation enables spatially flexible multi-device charging. FCC Part 18 RF exposure relaxation for these frequencies unlocks commercial furniture applications in United States hospitality and enterprise settings.
- Radio Frequency:Far-field harvesting targets low-power IoT sensors at extended distances.
- Capacitive Coupling:Electric field transfer suits sterile medical environments requiring enclosed, connector-free charging.
Inductive Coupling captures the dominant share of current procurement, with Magnetic Resonance gaining share fastest.
End User:
Application maturity varies sharply, with consumer electronics reaching commoditization while medical device sterilization requirements open premium pricing corridors.
- Consumer Electronics:Smartphones and wearables drive highest shipment volumes. Qualcomm's licensing ecosystem dominates smartphone-integrated designs, while domestic Chinese brands accelerate receiver embedding at manufacturing scale.
- Automotive Industry:Cabin-integrated charging pads are transitioning from premium option to factory-standard convenience. EU Green Deal mandates dismantle wired infrastructure in public spaces, redirecting municipal transit and retail capital toward embedded receiver modules.
- Medical Devices:Implantable monitors and wearable diagnostics demand enclosed, contactless charging to eliminate connector corrosion risks.
- Industrial Equipment:Harsh-environment sensors and automated guided vehicles require ruggedized receiver housings.
Consumer Electronics sits at the top of the volume ranking, with Automotive Industry climbing the fastest.
Application:
Customer type stratification concentrates procurement authority among distinct decision-makers, from fleet managers specifying EV infrastructure to facility directors bundling furniture-and-technology contracts.
- Smartphones:Multi-mode receiver chipsets switch between inductive and magnetic resonance protocols. Texas Instruments sustains R&D intensity across these flexible architectures, modularizing hardware design for Tier 1 automotive suppliers serving multiple OEM platforms.
- Electric Vehicles:Charging pad integration mandates embed inductive receivers as standard cabin features. NXP Semiconductors anchors European automotive qualification pipelines with AEC-Q100-grade chipsets.
- Wearable Devices:Ultra-compact coil arrays target smartwatches and fitness bands.
- IoT Devices:Distributed sensor networks drive demand for low-cost, high-efficiency harvesters.
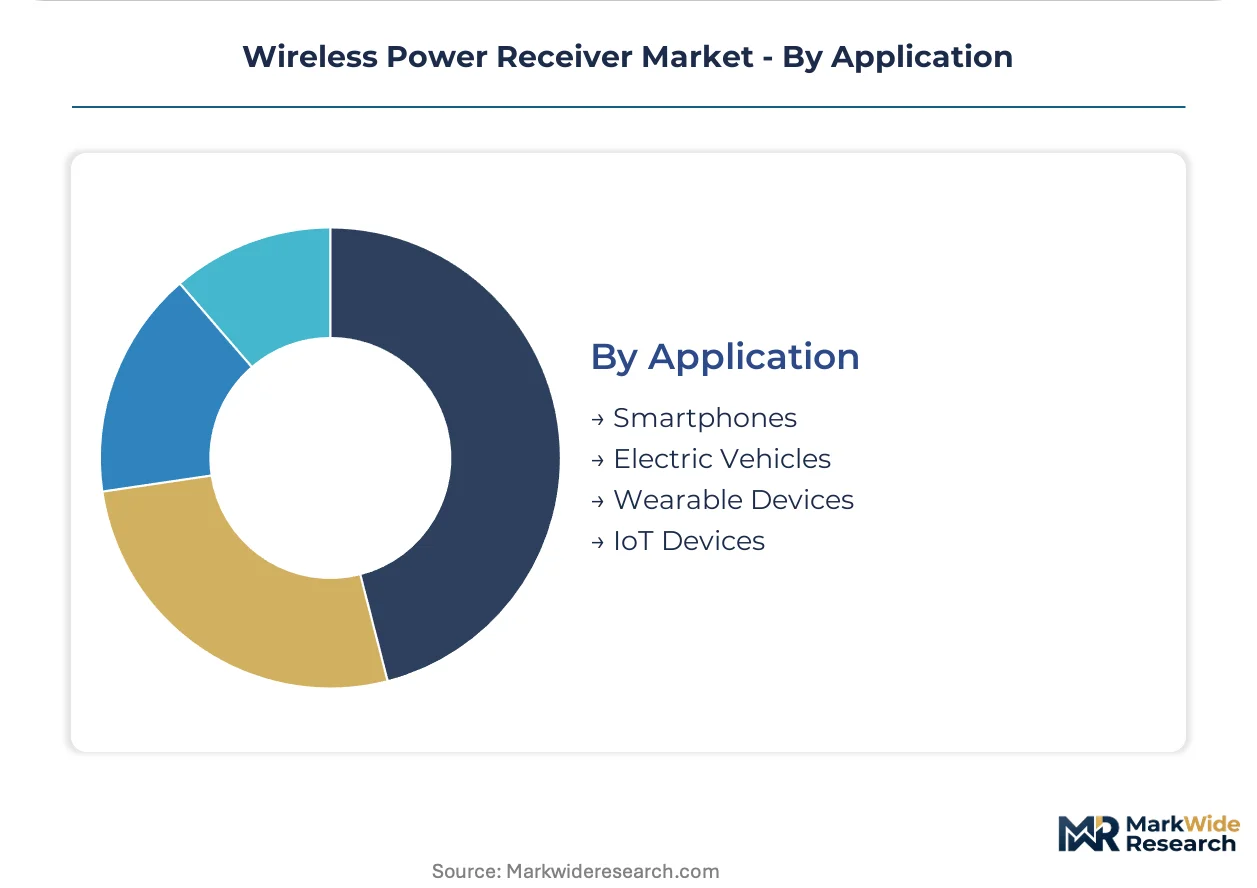
Smartphones sit at the top of the volume ranking, with Electric Vehicles climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as coil winding and PCB assembly capacity migrates toward jurisdictions offering production-linked incentives and streamlined electromagnetic compliance pathways.
China
Domestic smartphone brands and EV producers are embedding receivers at manufacturing scale under MIIT interoperability protocols. The country's GB standards dictate electromagnetic emission thresholds and interoperability testing protocols that compress design validation timelines. Shenzhen and Shanghai manufacturing clusters concentrate coil array fabrication and power management IC packaging for both consumer electronics and automotive cabin integration.
United States
Enterprise procurement of wireless charging infrastructure is consolidating toward integrated furniture-and-technology bundles in commercial real estate. FCC Part 18 governs RF exposure limits and spectrum allocation for wireless power transmission, with updated field strength thresholds for 6.78 MHz magnetic resonance systems. Dallas and Austin semiconductor corridors sustain R&D intensity across multi-mode receiver architectures serving Tier 1 automotive suppliers.
Germany
Automotive OEMs specify AEC-Q100-qualified chipsets for cabin-integrated charging pads transitioning from premium option to factory-standard convenience. The EU Green Deal and F-Gas Regulation systematically dismantle wired charging infrastructure in public spaces, redirecting municipal transit capital. Stuttgart and Munich automotive clusters anchor European qualification pipelines with extended thermal cycling and EMC validation periods.
South Korea
Semiconductor fabrication capacity for power management ICs and coil driver architectures concentrates in foundry complexes serving both domestic and export demand. The country's national telecommunications regulator enforces electromagnetic compatibility certification for receiver modules. Seoul Capital Area and Busan-Ulsan industrial zones manufacture multi-mode receiver chipsets capable of switching between inductive and magnetic resonance protocols.
India
Production-linked incentives under the PLI scheme for electronics manufacturing attract coil winding and PCB assembly capacity, creating regional supply alternatives to East Asian concentration. The Bureau of Indian Standards mandates electromagnetic emission compliance for imported receiver modules. Karnataka and Tamil Nadu electronics manufacturing clusters are expanding cleanroom assembly lines for low-power receiver components targeting smartphone and wearable device OEMs.
Wireless Power Receiver Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue magnetic resonance specialization and medical device qualification pathways. The vendor base stratifies across three maturity levels: integrated semiconductor conglomerates with multi-protocol R&D platforms, automotive-qualified chipset specialists managing extended validation timelines, and regional coil fabricators competing on assembly cost. Three archetypes dominate: silicon-first architects optimizing power management IC efficiency, automotive-focused suppliers navigating AEC-Q100 certification pipelines, and modular hardware designers serving contract furniture integrators. Competitive moves concentrate on strategic partnerships with automotive Tier 1 suppliers and geographic expansion into PLI-subsidized manufacturing jurisdictions.
Within the silicon-first architect tier, Qualcomm and Texas Instruments exemplify divergent strategic positioning. Qualcomm occupies a licensing-ecosystem position that consolidates smartphone-integrated receiver designs through patent portfolio leverage. Texas Instruments sustains R&D intensity across flexible architectures that modularize hardware design for Tier 1 automotive suppliers serving multiple OEM platforms without discrete redesign cycles. NXP Semiconductors anchors the automotive-qualified specialist archetype, representing European semiconductor vendors managing extended thermal cycling and EMC validation periods that delay revenue recognition by 18-24 months from tape-out to production release.
| Leading Market Players |
|---|
| Qualcomm |
| Texas Instruments |
| NXP Semiconductors |
| STMicroelectronics |
| Broadcom |
| Infineon Technologies |
| Renesas Electronics |
| Analog Devices |
| Samsung Electronics |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal and F-Gas Regulation mandate the phase-out of wired charging infrastructure in public spaces, creating a bifurcated supply landscape where AEC-Q100-qualified automotive chipsets command premium pricing while unqualified consumer-grade modules face cost compression from Asian foundry competition.
Pricing Analysis
Distributor margins on high-power EV receiver modules run 15-25 points above smartphone-grade components due to extended automotive qualification timelines and thermal management complexity. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer-grade levels separates margin pools, with automotive OEMs absorbing premium pricing for foreign object detection and EMC certification. Cost compression in consumer electronics tiers stems from China's MIIT-driven standardization and domestic brand competition. Fleet procurement managers at municipal transit authorities exhibit lowest price sensitivity due to regulatory mandate compliance deadlines, while contract furniture buyers negotiate aggressively on volume bundles.
Supply Chain Analysis
AEC-Q100 automotive qualification gates access to European and North American automotive OEM procurement pipelines, filtering coil array and power management IC suppliers through 18-24 month validation cycles. Taiwan, South Korea, and China concentrate semiconductor fabrication capacity for receiver chipsets, with copper coil winding capacity migrating toward India's PLI-subsidized electronics manufacturing clusters. Raw material dependencies center on LME copper futures for coil arrays, rare-earth ferrite cores for magnetic coupling efficiency, and ABF substrates for high-frequency IC packaging. Single-source vulnerability in Taiwan foundry capacity for multi-mode receiver architectures threatens supply continuity. Distribution runs through Tier 1 automotive suppliers and contract furniture integrators rather than traditional electronics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wireless power receiver market functions as a regulatory compounder where EU F-Gas Regulation mandates dismantle legacy wired infrastructure and force embedded receiver deployment across automotive, furniture, and transit applications.
For Market Incumbents: Deepen backward integration into coil array fabrication to defend margin position against copper price volatility and Asian foundry concentration. Qualcomm and Texas Instruments should extend licensing leverage into magnetic resonance protocol stacks before AirFuel fragmentation consolidates. Prioritize AEC-Q100 certification pipeline investment to capture EU automotive cabin integration mandates ahead of 18-24 month qualification delays.
For New Entrants and Emerging Players: Enter via FDA 510(k) pathway for implantable medical device charging applications where sterilization requirements block incumbent consumer electronics suppliers. India's PLI-subsidized manufacturing clusters offer the most penetrable geography for coil winding and PCB assembly capacity without Taiwan foundry dependency. Pursue direct partnerships with contract furniture manufacturers bypassing traditional electronics distribution channels.
For Investors and Strategic Acquirers: Roll-up economics work for automotive-qualified chipset specialists because AEC-Q100 validation timelines create captive customer relationships and 18-24 month revenue recognition moats. Target acquisition archetypes include Tier 2 coil fabricators with pending automotive qualification and magnetic resonance IP holders facing AirFuel protocol consolidation. Watch FCC Part 18 RF exposure threshold adjustments as inflection indicator for spatially flexible multi-device charging commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Mode Receiver Architecture Development | Texas Instruments sustains R&D intensity across 110-205 kHz and 6.78 MHz switching chipsets for Tier 1 automotive suppliers. |
| AEC-Q100 Automotive Qualification Pipeline | NXP Semiconductors anchors European OEM procurement through extended thermal cycling and EMC validation protocols. |
| Magnetic Resonance Protocol Licensing | Qualcomm consolidates smartphone-integrated designs through patent portfolio leverage against AirFuel fragmentation. |
| PLI-Subsidized Manufacturing Expansion | India's electronics manufacturing clusters attract coil winding capacity as regional alternative to East Asian concentration. |
| FDA 510(k) Medical Device Pathway | Enclosed contactless charging eliminates connector corrosion risks in implantable monitors and wearable diagnostics. |
Study Parameters
Coverage spans China, United States, Germany, South Korea, and India, with primary inputs from each market's regulatory and manufacturing clusters. Primary interviews incorporated automotive Tier 1 supplier procurement managers, semiconductor R&D directors at multi-mode receiver chipset vendors, contract furniture manufacturing executives, and FCC regulatory affairs specialists. Secondary validation drew from MIIT GB standard filings, EU F-Gas Regulation implementation directives, FCC Part 18 docket proceedings, and AEC-Q100 qualification database records. Bottom-up shipment modeling for coil arrays and power management ICs triangulated against top-down automotive OEM platform deployment forecasts.
Granularity-level modeling disaggregated receiver architectures by power tier (ultra-low, low, medium, high), coupling technology (inductive, magnetic resonance, RF, capacitive), and end-use application (consumer electronics, automotive cabin, medical device, industrial equipment). CAGRs were derived from regression analysis of historical qualification timeline data and projected OEM platform integration schedules across the analysis window. Industry-specific forecast inputs included copper LME futures trajectory assumptions and FCC RF exposure threshold adjustment probabilities.
Inputs from automotive OEM platform planning disclosures and semiconductor foundry capacity announcements were available through the study window; gaps in AirFuel protocol adoption rate data introduce uncertainty bands around magnetic resonance share projections. Forecasts reflect documented assumptions regarding EU regulatory enforcement timelines and China MIIT interoperability protocol compliance rates. A model refresh is warranted upon material change in FCC Part 18 field strength threshold rulings or EU F-Gas Regulation implementation acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Canada Thermal Power Market
Power
Sudan Power Market
Power
Japan Power Market
Power
Substation Automation System Market
Power
Marine Thermal Fluid Heaters Market
Power
North America CHP Market
Power
Middle-East and Africa Power Market
Power
Middle-East and Africa Power Rental Market
Power
Oxy-Hydrogen Generators Market
Power
Uzbekistan Power Market
Power
Harmonic Filter Market
Power
Nigeria Power Market
Power
Existent Gum Steam Generator Market
Power
Electric Arc Furnaces Market
Power
Wind Turbine Drivetrain Market
Power
Steam Turbine MRO Market