
 Recloser Market | 2026-2036
Recloser Market Size, Share, and Industry Trends Forecast 2026-2036
Recloser Market Analysis
Aftermarket service revenue is reshaping margin distribution across the recloser value chain as utilities extend asset life cycles rather than replace capital equipment. ABB leverages its installed base across Europe and North America to capture recurring retrofit and digital upgrade contracts. Eaton anchors its position through intensive R&D in solid-state interruption technology, while NOJA Power Switchgear specializes in pole-mounted automation solutions for rural and remote grid segments.
A recloser is a self-contained protective device used in medium-voltage electrical distribution networks, typically rated between 15 kV and 38 kV, that automatically interrupts and recloses fault currents to isolate temporary disturbances without sustained outages. It contains a vacuum or oil interrupter, a control mechanism, and sensing elements that detect overcurrent conditions and execute programmed reclosing sequences. Electric reclosers dominate current procurement as utilities phase out hydraulic mechanisms, while smart reclosers with integrated sensors and communication modules represent the fastest-expanding segment as grid operators pursue real-time visibility. Deployment through cloud-based architectures is gaining traction among municipal utilities seeking to reduce on-site infrastructure costs.
The Federal Energy Regulatory Commission and state public utility commissions enforce reliability standards that directly mandate fault isolation performance, compelling utilities to upgrade legacy protection schemes. IEEE C37.60 and IEC 62271-111 define testing protocols and operational parameters that manufacturers must satisfy for market access in North America and Europe. Stakeholders must monitor evolving cybersecurity requirements for grid-connected devices as remote monitoring becomes standard configuration.
Market Dynamics
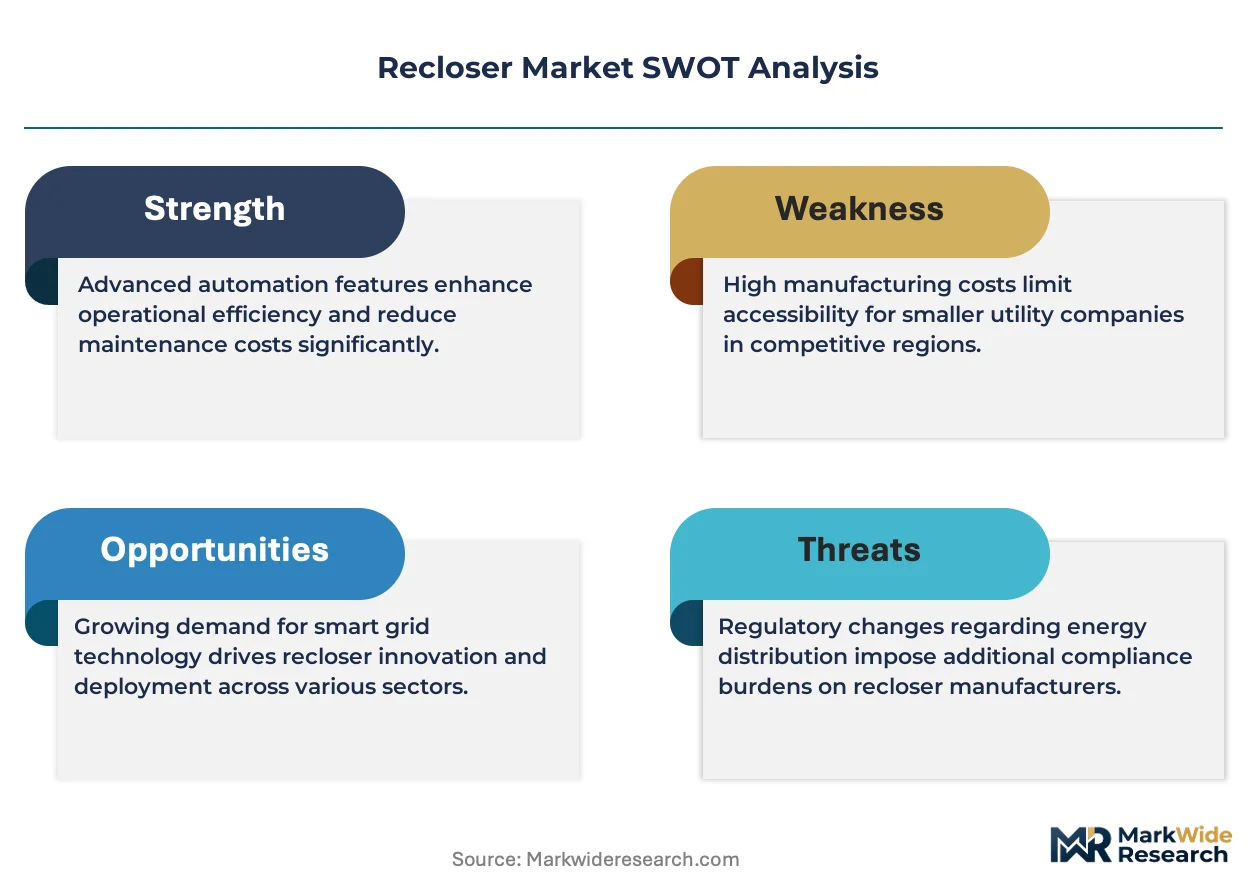
Grid hardening mandates and wildfire mitigation investments are forcing utilities to replace electromechanical protection schemes with intelligent reclosers capable of real-time fault isolation and remote telemetry.
Growth Catalysts
- IEEE 1547 interconnection standards:North American utilities must upgrade distribution protection to accommodate distributed energy resource penetration, accelerating procurement of grid-edge switching equipment with synchronized control capabilities.
- Rural electrification programs:Developing markets in Southeast Asia and Sub-Saharan Africa are deploying pole-mounted automation to extend medium-voltage networks without building centralized substations.
- Vacuum interrupter technology:Phasing out oil-based mechanisms eliminates maintenance-intensive assets and enables longer operational life cycles in harsh environmental conditions.
Market Restraints
- Copper and rare earth price volatility:Vacuum interrupter assemblies depend on specialized contact materials whose supply concentrates in limited refining jurisdictions, compressing margins during commodity spikes.
- Prolonged type-testing protocols:IEC 62271-111 and IEEE C37.60 certification cycles extend 18-24 months, freezing product variants before market entry and privileging incumbents with established test records.
- Gas-insulated switchgear substitution:Urban underground distribution projects in dense European and East Asian metros increasingly specify SF6-insulated alternatives with smaller footprints, diverting capital from air-insulated recloser installations.
Strategic Opportunities
- Microgrid islanding applications:Campus and industrial microgrids require sectionalizing devices with intentional islanding logic, creating specification pull for reclosers with advanced control algorithms.
- Brazilian grid modernization:ANEEL's regulatory framework mandates distribution automation investments, opening procurement windows for intelligent switching equipment in a market historically dominated by conventional protection.
- Edge-to-cloud telemetry convergence:Integration of recloser controllers with utility SCADA and advanced distribution management systems enables subscription-based remote monitoring services.
Industry Challenges
- Cybersecurity certification complexity:NERC CIP and emerging IEC 62351 requirements for grid-connected devices impose firmware validation and secure boot protocols that extend engineering cycles and require specialized talent pools.
- Legacy electromechanical interoperability:Utilities with mixed-vintage protection fleets face protocol translation burdens when deploying intelligent reclosers alongside decades-old relay schemes, complicating staged upgrade paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recloser Market |
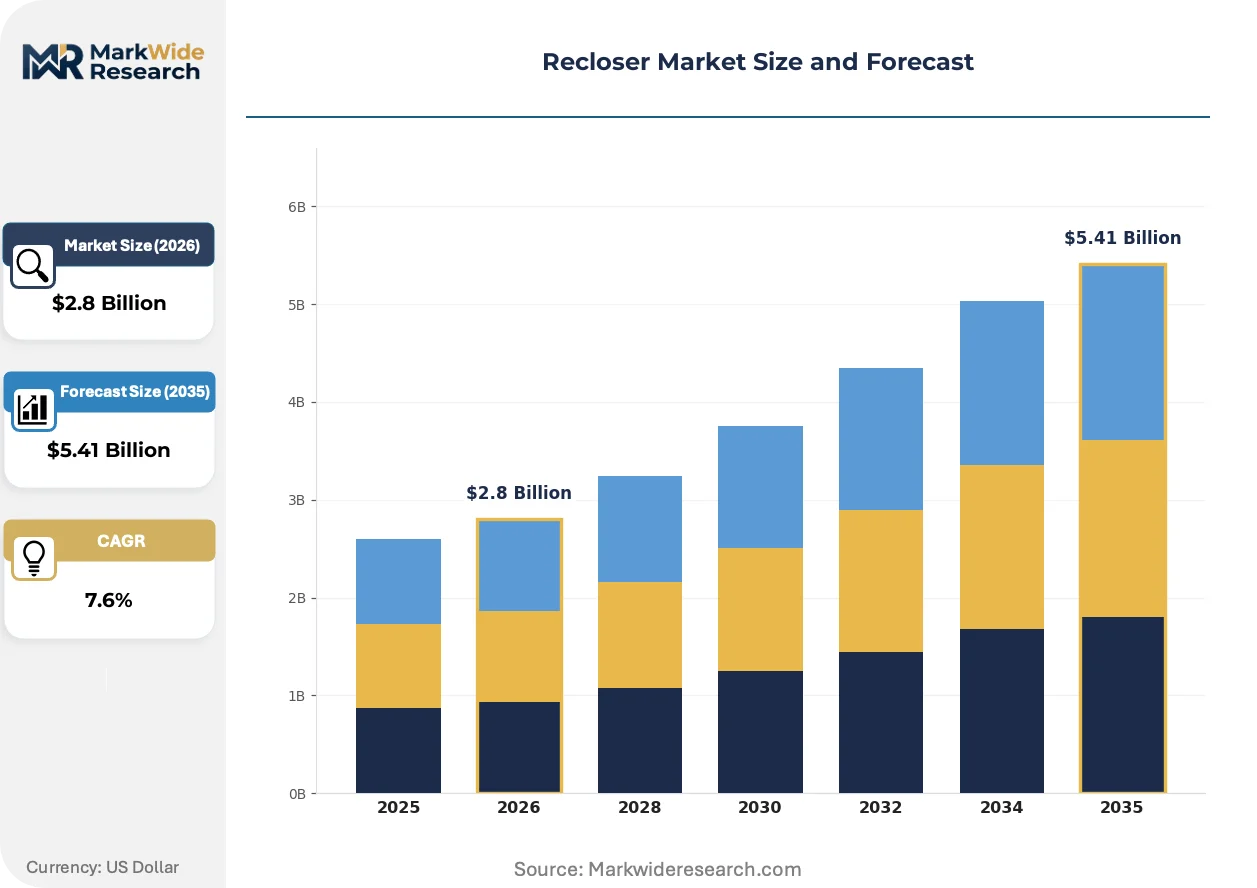
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Reclosers, Electric Reclosers, Auto Reclosers, Smart Reclosers End User: Utilities, Industrial Plants, Commercial Buildings, Municipalities Deployment: On-premise, Cloud-based, Hybrid, Remote Monitoring Operation Mode: Automatic, Manual, Semi-automatic, Remote-controlled |
| Companies Covered | ABB, Eaton, Schneider Electric, Siemens, General Electric, NOJA Power Switchgear, Hubbell, S&C Electric Company, Arteche Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recloser Market Emerging Trajectories
Solid-state interruption and digital twin architectures are compressing the functional boundary between protection devices and grid-edge computing nodes, reshaping how utilities specify and procure distribution automation.
Vacuum interrupter technology is hybridizing with power electronic current-limiting modules to enable sub-cycle fault clearing without mechanical wear. European transmission system operators are piloting these hybrid breakers for distributed generation interconnection points. This convergence is hybridizing the traditional recloser category with solid-state circuit breaker functionality, forcing manufacturers to recalibrate R&D roadmaps and field service competencies.
The EU F-Gas Regulation is accelerating phase-out timelines for sulfur hexafluoride insulation in medium-voltage equipment. Manufacturers serving European utilities must redesign sealed-tank reclosers using dry air or vacuum insulation to maintain market access. Distribution network operators in Germany and the Netherlands are now specifying SF6-free switching equipment in tender documents, compressing demand for conventional gas-insulated designs.
Performance-based service agreements are displacing transactional equipment sales among North American municipal utilities. Under these arrangements, vendors retain asset ownership and guarantee availability metrics, shifting capital expenditure to operational expenditure on utility balance sheets. This restructuring is most visible in California and Texas, where wildfire liability exposure and storm resilience mandates concentrate procurement authority at the executive level rather than engineering departments.
Recloser Market Segmentation
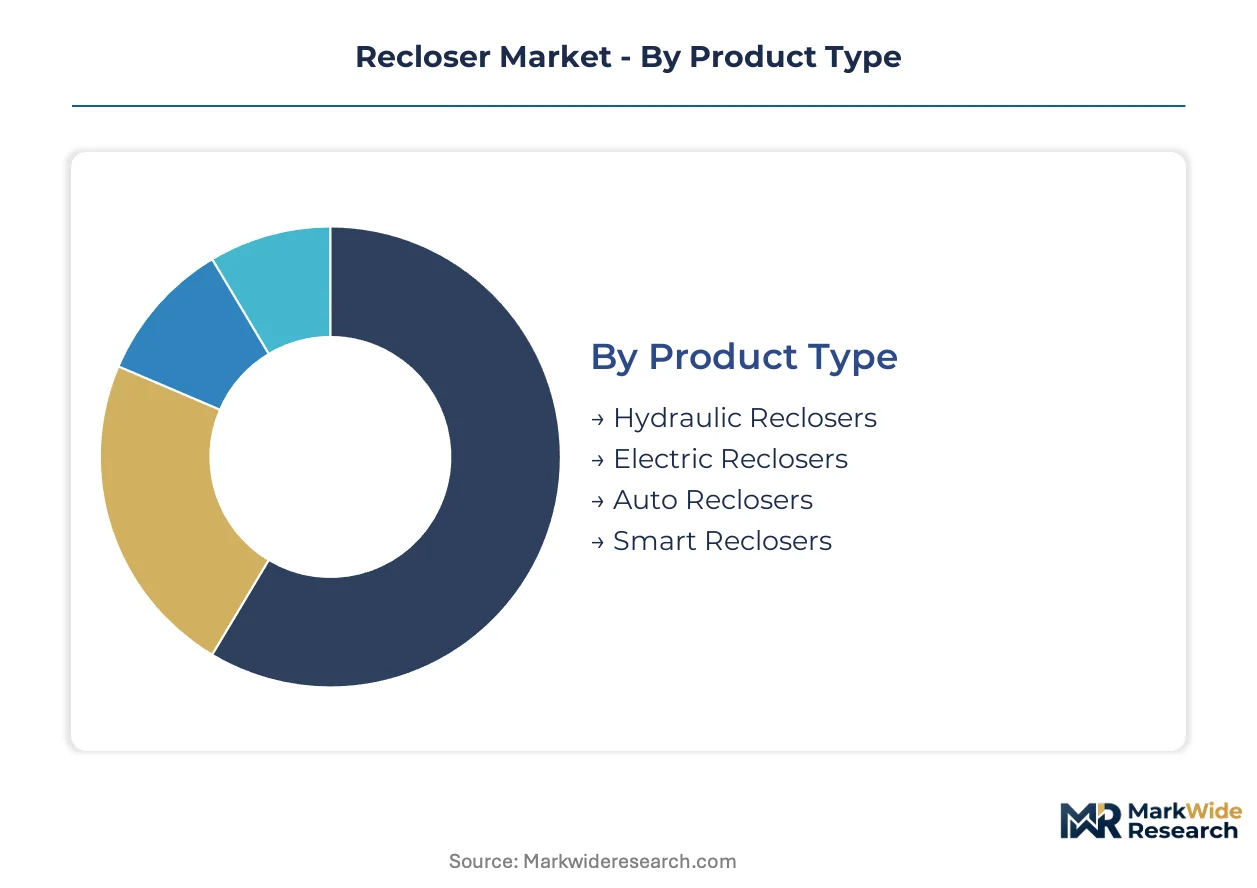
Recloser procurement patterns diverge sharply across operational contexts, with service intensity varying from decades-long maintenance contracts for hydraulic units to subscription telemetry models for cloud-connected smart variants. Understanding these segment boundaries clarifies where capital expenditure concentrates versus where operational expenditure models are displacing traditional ownership structures.
Product Type:
After-sales service intensity defines margin capture across recloser categories, with legacy hydraulic units requiring intensive field maintenance while intelligent variants generate recurring software and upgrade revenue streams.
- Electric Reclosers:These units replace hydraulic actuation with motor-driven mechanisms, eliminating fluid leaks and temperature sensitivity while enabling precise reclosing sequences. Procurement concentrates among North American utilities modernizing rural distribution feeders, driven by IEEE 1547 compliance deadlines for distributed energy resource interconnection. Electric reclosers hold the largest share; momentum sits with smart reclosers.
- Smart Reclosers:Integrated sensors, edge computing controllers, and cellular or fiber communication modules transform protection devices into grid-edge data nodes. Demand clusters in California and Texas where wildfire liability exposure and storm resilience mandates compel real-time fault visibility and predictive maintenance capabilities.
- Hydraulic Reclosers:Oil-actuated mechanisms with temperature-compensated viscosity control persist in legacy installations across Southeast Asia and Sub-Saharan Africa where capital constraints favor proven electromechanical designs over digital upgrades.
- Auto Reclosers:Pre-programmed reclosing sequences without external communication capability serve isolated rural feeders and developing grid extensions where communication infrastructure remains uneconomical.
Electric reclosers anchor current procurement volumes; smart reclosers are climbing the fastest as grid operators prioritize real-time telemetry.
End User:
Customer type determines specification authority and purchasing cycle length, with regulated utilities driving standardization while industrial end-users demand customized sectionalizing logic.
- Utilities:Investor-owned and municipal electric companies account for the dominant procurement volume, specifying IEC 62271-111 or IEEE C37.60 compliance as baseline market access requirements. These entities prioritize fleet standardization to reduce spare parts inventory and technician training overhead across thousands of installed units.
- Industrial Plants:Manufacturing campuses, petrochemical complexes, and mining operations specify reclosers with intentional islanding capability for microgrid segmentation and critical load protection during upstream disturbances.
- Commercial Buildings:Large retail distribution centers and data centers deploy reclosers at utility interconnection points to manage power quality events and enable demand response participation.
- Municipalities:City-owned electric departments and public utility districts concentrate in the United States, particularly in states with wildfire mitigation bond programs or storm hardening mandates.
Utilities dominate segment revenue; industrial plants are gaining share fastest as distributed generation penetration accelerates site-level protection investment.
Deployment:
Architecture selection reflects infrastructure economics and cybersecurity risk tolerance, with cloud migration accelerating among resource-constrained municipal operators.
- On-premise:Local SCADA integration with dedicated communication infrastructure remains preferred by large investor-owned utilities with established control center operations and internal cybersecurity teams.
- Cloud-based:SaaS-delivered recloser management reduces capital burden for small municipal utilities and rural electric cooperatives, transferring infrastructure ownership to vendors.
- Hybrid:Edge processing with cloud analytics aggregation balances latency-sensitive protection functions against centralized data warehousing for long-term asset performance modeling.
- Remote Monitoring:Telemetry-only deployments without control capability serve regulatory compliance and insurance documentation requirements for visibility into hard-to-access distribution assets.
On-premise installations retain the largest installed base; cloud-based deployment is expanding most quickly among cost-constrained operators.
Operation Mode:
Control philosophy selection tracks grid automation maturity and workforce availability, with remote capability becoming default specification for new installations.
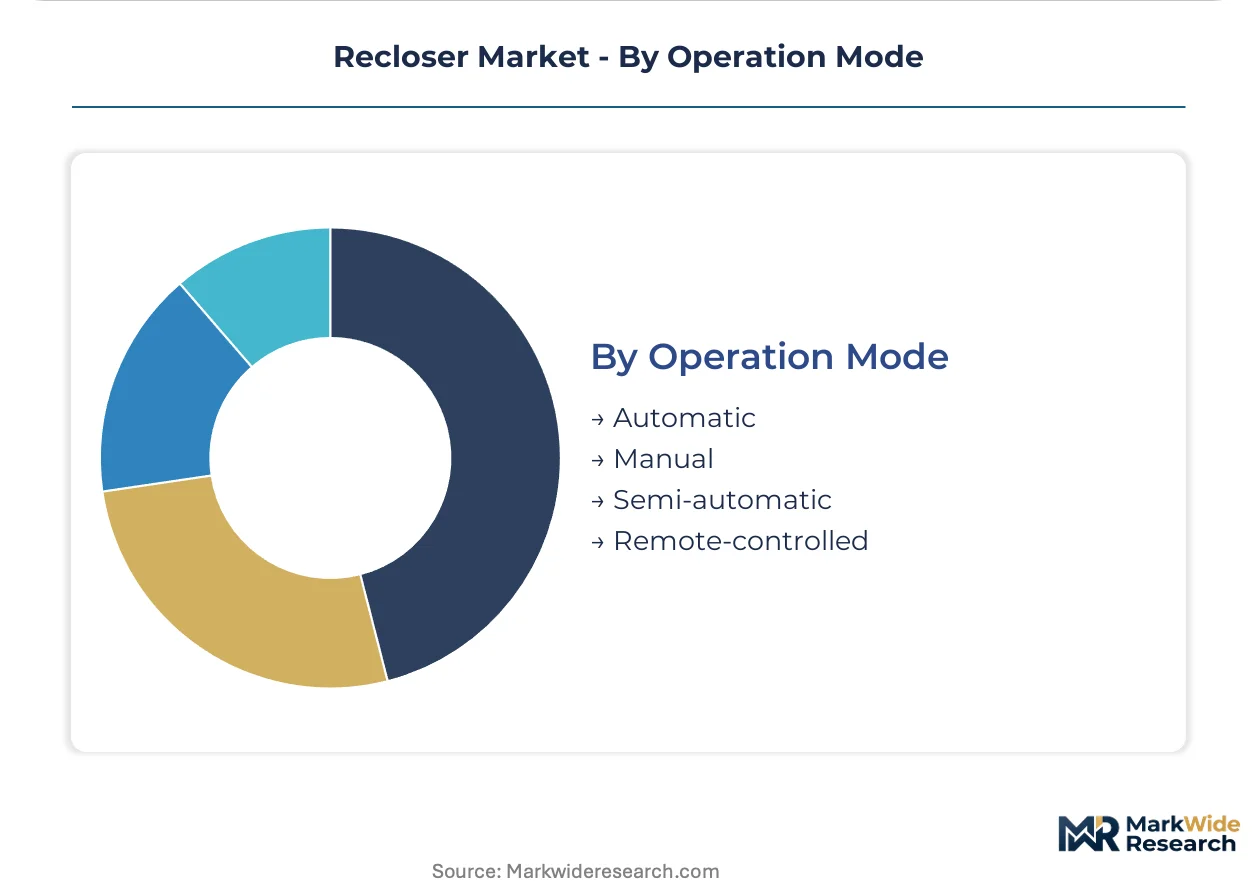
- Automatic:Self-contained fault detection and reclosing sequences without human intervention remain standard for overhead distribution feeders where temporary faults predominate.
- Remote-controlled:Operator-initiated switching from centralized control rooms enables load transfer and maintenance isolation without truck rolls, concentrating in urban and suburban networks with fiber communication coverage.
- Manual:Hand-cranked or direct-switch operation persists in backup configurations and extremely remote locations where communication and power supply reliability cannot be guaranteed.
- Semi-automatic:Local control with remote override capability serves transitional grid modernization phases where legacy and intelligent devices operate in mixed fleets.
Automatic operation holds the largest share; remote-controlled systems are gaining share fastest as distribution management system integration becomes standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recloser deployment patterns diverge sharply by geography. North American utilities prioritize wildfire-hardened intelligent switching, while European operators accelerate SF6 phase-outs under environmental mandates. Developing markets in Asia-Pacific and Latin America favor cost-optimized pole-mounted automation for rural grid extension.
United States
Wildfire mitigation bonds in California and Texas drive procurement of remote-controlled reclosers with real-time telemetry. FERC reliability standards and state-level Public Utility Commission mandates compel investor-owned utilities to replace electromechanical protection schemes. Deployment concentrates in Pacific Coast states and Texas, where storm resilience programs fund sectionalizing equipment for hardening distribution feeders against weather-related outages.
Germany
Distribution network operators specify SF6-free switching equipment following EU F-Gas Regulation acceleration timelines. The country's Energiewende grid modernization program mandates intelligent automation for distributed energy resource integration. Industrial demand clusters in North Rhine-Westphalia and Bavaria, where municipal utilities pilot hybrid vacuum interrupters with power electronic current-limiting modules.
Brazil
ANEEL's regulatory framework mandates distribution automation investments across concession areas historically served by conventional protection. Rural electrification programs in the Northeast and Amazon regions deploy pole-mounted auto-reclosers without communication infrastructure. Procurement windows concentrate in São Paulo and Minas Gerais, where large distribution utilities modernize medium-voltage networks to reduce technical losses.
India
The Ministry of Power's rural electrification schemes extend medium-voltage networks through cost-optimized hydraulic and electric reclosers. Central Electricity Authority standards govern protection device specifications for state distribution companies. Deployment activity centers in Maharashtra, Gujarat, and Tamil Nadu, where urban utilities pilot smart reclosers with SCADA integration while rural extensions rely on basic auto-reclosing sequences.
Australia
Network operators in Queensland and New South Wales specify pole-mounted automation for remote feeder sections with limited access roads. The Australian Energy Regulator's reliability incentive schemes reward utilities for reducing customer minutes lost through faster fault isolation. Procurement focuses on the National Electricity Market regions, where bushfire mitigation requirements parallel California's approach to intelligent sectionalizing.
Recloser Market Vendor Landscape
Capability concentration sits with specialized automation vendors; scale advantage sits with diversified electrical equipment conglomerates. The market exhibits a tiered structure where global power technology groups compete alongside regional specialists focused on distribution protection. Three archetypes dominate: integrated multinationals with broad energy portfolios, recloser-focused specialists with deep utility relationships, and component suppliers extending into assembled systems. Competitive moves center on retrofit service contracts for installed base monetization and solid-state interruption technology partnerships.
Among integrated electrical equipment groups, ABB and Eaton exemplify scale-driven positioning across protection and switching portfolios. NOJA Power Switchgear occupies a specialist tier focused on pole-mounted automation solutions. These three anchors represent divergent strategic postures: diversified technology breadth versus concentrated distribution protection expertise. Their collective presence shapes procurement standards and service model expectations across utility segments.
| Leading Market Players |
|---|
| ABB |
| Eaton |
| Schneider Electric |
| Siemens |
| General Electric |
| NOJA Power Switchgear |
| Hubbell |
| S&C Electric Company |
| Arteche Group |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific container freight corridors linking Chinese vacuum interrupter foundries to North American utility warehouses transmit cost volatility directly into tiered equipment pricing, compressing margins for distributors while amplifying differentiation power for manufacturers with captive component production.
Pricing Analysis
Long-term offtake agreements dominate procurement between major utilities and tier-one manufacturers, insulating baseline volumes from spot copper and rare earth swings while project-based spot purchasing governs emergency replacements and rural electrification programs. Price differentiation hinges on IEC 62271-111 certification tier and bundled telemetry service levels, with California municipal utilities showing lowest price sensitivity due to wildfire liability transfer imperatives and Southeast Asian state distributors exhibiting acute cost consciousness. Cost compression in standard-grade electric reclosers is intensifying because Chinese component suppliers are absorbing tariff exposure through volume rebates.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for vacuum interrupter assemblies and contact material refining. Manufacturing concentrates in China, Germany, and the United States for finished reclosers, with specialized contact materials drawing from South African and Australian mining jurisdictions. Ceramic insulator production rests on alumina supply from Brazilian and Chinese bauxite processing. Distribution runs through authorized utility distributors and direct OEM sales forces serving investor-owned accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recloser market sits in early-cycle expansion as grid-edge computing penetration triggers replacement waves across protection device fleets. IEEE 1547 compliance deadlines and wildfire hardening mandates create durable specification pull for intelligent variants.
For Market Incumbents: Pre-empt solid-state interruption obsolescence by acquiring power electronics specialists ahead of hybrid breaker commercialization, while locking in multi-decade service contracts for hydraulic installed bases before municipal utilities shift to subscription telemetry models. SF6 phase-out acceleration under EU F-Gas Regulation threatens sealed-tank product lines without rapid vacuum insulation redesign. For New Entrants and Emerging Players: Establish a beachhead in Brazilian distribution automation by partnering with ANEEL-regulated utilities for pilot smart recloser deployments, bypassing entrenched European and North American incumbents. Auto-recloser segments in Sub-Saharan African rural electrification programs offer lowest competitive density. Lead with cloud-native telemetry architectures that eliminate on-premise infrastructure costs for capital-constrained cooperatives. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component suppliers with backward integration into contact material refining and vacuum interrupter ceramic fabrication. Long-term viability over the next decade hinges on firmware differentiation and cybersecurity certification depth rather than mechanical engineering legacy. Watch NERC CIP enforcement intensity as the inflection signal for valuation premiums on compliant device portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Retrofit Service Contract Expansion | Captures recurring revenue from ABB and Eaton installed bases across North American utilities. |
| Solid-State Interruption R&D Partnership | Accelerates hybrid breaker timelines for European distributed generation interconnection pilots. |
| SF6-Free Product Line Redesign | Secures German and Dutch market access under accelerated EU F-Gas Regulation phase-outs. |
| Cloud Telemetry Platform Launch | Reduces capital burden for Texas and California municipal utilities seeking subscription models. |
| Brazilian Distribution Utility Alliance | Opens ANEEL-mandated automation procurement windows in São Paulo and Minas Gerais concession areas. |
Methodological Framework
Initial hypotheses were tested against primary input from utility protection engineers, distribution automation procurement managers, vacuum interrupter manufacturing executives, and SCADA integration specialists and refined through secondary validation against IEC certification databases, FERC reliability filings, and ANEEL regulatory bulletins. Bottom-up equipment shipment tracking triangulated with top-down grid investment forecasts derived from utility capital expenditure disclosures and rural electrification program budgets.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by actuation mechanism and intelligence tier, deployment architecture by on-premise and cloud-native configurations, and operation mode by automatic and remote-controlled capability. CAGRs were computed from annualized growth trajectories adjusted for regulatory compliance deadline clustering and commodity price cycle positioning. Forecast inputs included IEEE 1547 interconnection standard adoption curves and wildfire mitigation bond issuance flows.
Sensitivities concentrate around copper and rare earth price volatility, NERC CIP cybersecurity certification timeline extensions, and SF6 phase-out schedule acceleration in European jurisdictions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Global Hazardous Location Motor Starters Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
Global Electrical SCADA Market
Electrical Power Equipment
Smart Electric Heater Market
Electrical Power Equipment
Fuse Link Market
Electrical Power Equipment
Magnetic Optical Current Transformer Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Carbon Brush Market
Electrical Power Equipment
Electric Vehicle Charging Cables Market
Electrical Power Equipment
GCC Induction Motor Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Europe Gas Insulated Switchgear Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
AC-DC Controller Market
Electrical Power Equipment
Taiwan Electric Power Equipment Market