
 Middle-East and Africa Power Rental Market | 2026-2036
Middle-East and Africa Power Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Power Rental Market Foresight
Hybrid power integration with battery storage and solar augmentation is tilting how rental fleets are configured for desert and remote operations. Aggreko Middle East Ltd leverages its dual-fuel and solar-hybrid inventory to anchor long-term contracts with oilfield operators across Oman and Iraq. Byrne Equipment Rental LLC sustains a dense depot network across the UAE and Saudi Arabia, competing on mobilization speed for construction and events. Jubaili Bros. LLC dominates the Levant and East African markets with a service-led model that extends beyond equipment supply into embedded technicians and fuel management.
Middle-East and Africa power rental encompasses the short-term provision of mobile generation assets, typically diesel or gas reciprocating engines mounted on skid or trailer platforms with outputs spanning 10 kVA to 2,000 kVA, deployed to bridge grid deficits or energize off-grid industrial sites. The primary commercial purpose centers on ensuring continuity for capital-intensive operations where grid instability or project remoteness renders permanent infrastructure uneconomical. Diesel generators still occupy the majority of installed rental capacity, though gas generators are capturing share where pipeline access exists and emissions scrutiny tightens. The above 1000 kVA power rating band leads value generation, as mining and upstream oil installations require sustained multi-megawatt blocks that command premium day rates and long minimum commitments.
Saudi Arabia's SFDA and the UAE's MOHAP enforce equipment safety and environmental compliance for industrial temporary power, while local civil defense authorities mandate fire suppression and exhaust treatment standards that shape fleet specifications. The UAE's dual carbon goals and Saudi Vision 2030 efficiency benchmarks are forcing rental providers to retire older Tier 1 diesel units and certify gas and hybrid alternatives for public sector eligibility. Stakeholders must monitor how Egypt and Nigeria's evolving grid privatization frameworks redirect state utility procurement toward rental-backed independent power projects.
Market Dynamics
Dual-fuel engine technology and Saudi Vision 2030 efficiency mandates are forcing rental providers to retire Tier 1 diesel fleets and certify gas-hybrid alternatives, compressing the competitive window for legacy-only operators across the Gulf Cooperation Council corridor.
Growth Catalysts
- Upstream oilfield electrification:Exploration intensification in Oman and Iraq generates sustained demand for mobile multi-megawatt blocks where grid extension remains uneconomical.
- Saudi Vision 2030 desalination buildout:Mega-construction timelines and plant outage contingencies create peak rental requirements that permanent infrastructure cannot match.
- SFDA equipment safety certification:Mandatory fire suppression and exhaust treatment standards raise barriers to entry, consolidating contract awards toward compliant fleet operators.
Market Restraints
- Diesel fuel price volatility:Crude-linked input costs compress day-rate margins for pure diesel configurations during contract renegotiation cycles.
- Pipeline access concentration:Natural gas generator deployment depends on Gulf Cooperation Council corridor infrastructure, leaving East African markets diesel-dependent.
- Dual-fuel engine technical limitation:Gas-diesel blending ratios below 70% gas trigger derating penalties that reduce effective kVA output in high-ambient desert conditions.
Strategic Opportunities
- East African grid privatization:Nigeria's evolving independent power project frameworks redirect state utility procurement toward rental-backed generation.
- Solar-battery hybrid convergence:Photovoltaic augmentation with lithium-ion storage reduces fuel burn for remote mining camps in Mauritania and Sudan.
- MOHAP carbon eligibility criteria:UAE public sector tenders now mandate Tier 4 interim or gas certification, creating first-mover advantage for compliant fleet investors.
Industry Challenges
- Embedded technician scarcity:OEM-specific training for dual-fuel and hybrid control systems outpaces vocational pipeline output in Levant markets.
- SFDA certification timeline compression:Safety recertification cycles for modified gas trains extend mobilization lead times by 15-20 days.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Power Rental Market |
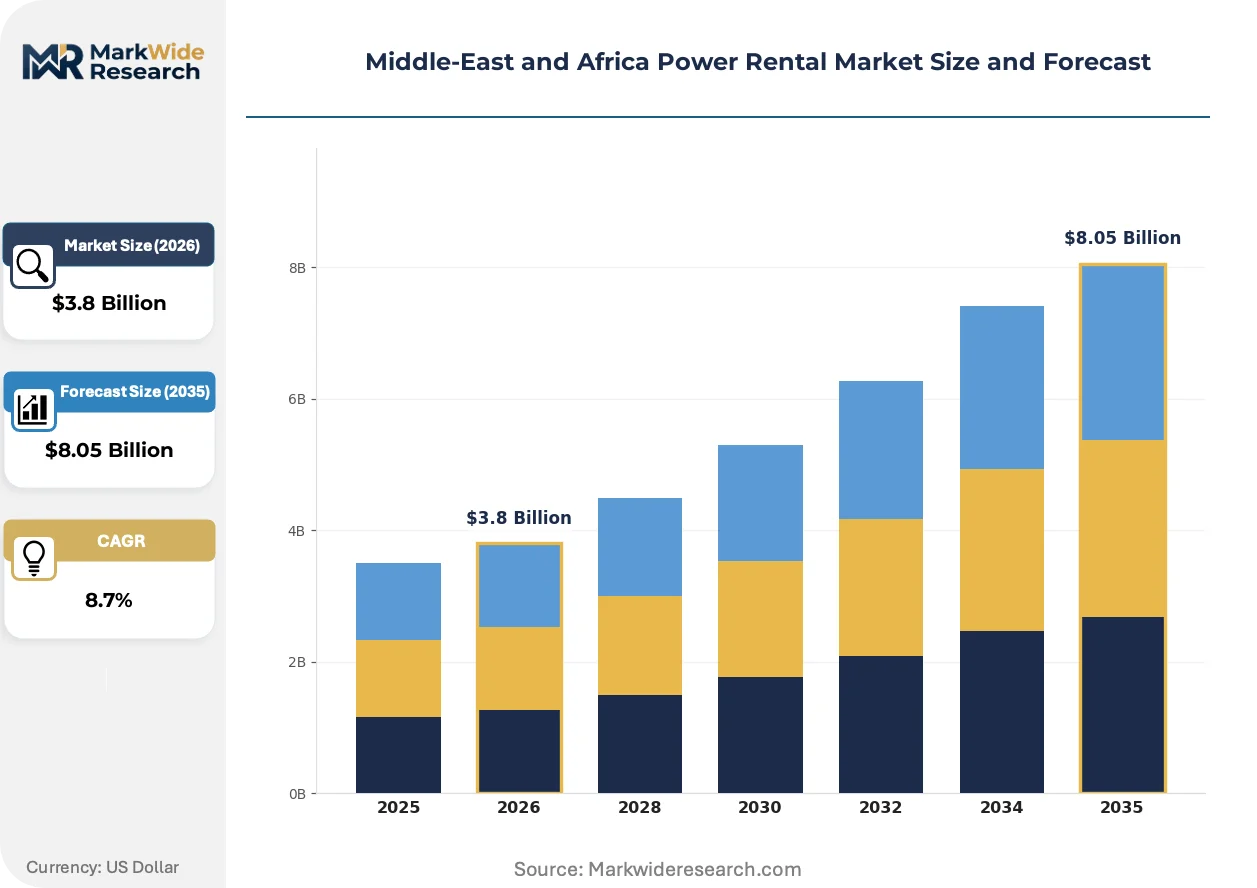
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Diesel Generators, Gas Generators, Hybrid Solutions, UPS Systems End User: Construction, Events, Oil & Gas, Mining Power Rating: 1-100 kVA, 101-500 kVA, 501-1000 kVA, Above 1000 kVA Deployment: On-site Installation, Mobile Rental, Remote Monitoring, Temporary Installations |
| Companies Covered | SES SMART Energy Solutions FZCO, Peax Equipment Rental, Aggreko Middle East Ltd, Jubaili Bros. LLC, Jozi Power Limited, Rental Solutions & Services LLC, KPS Power Generation, Atlas Copco AB, Byrne Equipment Rental LLC, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Power Rental Market Shifts & Advancements
Digital remote monitoring and predictive maintenance algorithms are virtualizing how rental fleets are managed across dispersed desert and offshore installations, collapsing the traditional service-response model.
Hybrid power control systems integrating battery storage with reciprocating engines is virtualizing the role of spinning reserve in rental configurations. Oilfield operators in Saudi Arabia and the UAE are adopting these systems for load-following applications. The technology is virtualizing the distinction between temporary and permanent generation assets by enabling grid-forming capability without synchronous condensers.
Saudi Vision 2030 efficiency benchmarks and UAE dual carbon goals are mandating Tier 4 interim or gas certification for public sector eligibility. Industrial rental providers must retire pre-2015 diesel units or forfeit government construction and desalination contracts. The above-1000 kVA segment faces the steepest compliance cost concentration due to engine replacement scale.
Long-term power purchase agreements with embedded rental provisions are displacing traditional short-term spot rentals for mining and upstream oil operations. Major extractive companies in Oman and Iraq now contract 3-5 year availability guarantees rather than monthly extensions. This pattern concentrates contract value with fleet-heavy incumbents who can underwrite balance-sheet exposure.
Middle-East and Africa Power Rental Market Segmentation
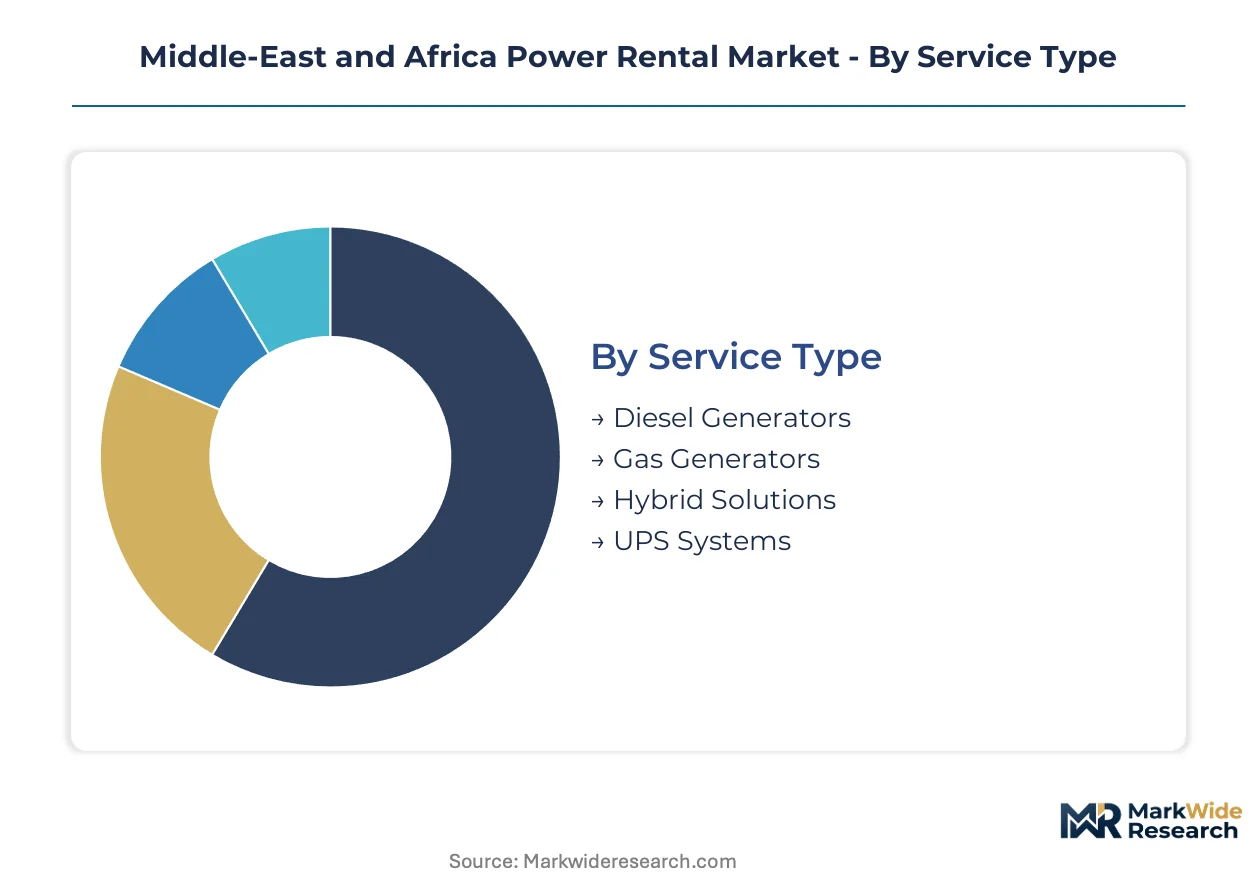
Rental fleet composition across the Middle-East and Africa power rental market follows distinct utilization cycles. Service type determines fuel burn profiles and compliance trajectories, while power rating bands dictate contract duration and margin structures.
Service Type:
Diesel generators turn over fastest on short construction cycles, while hybrid solutions lock in multi-year oilfield availability guarantees.
- Diesel Generators:Reciprocating engines burning distillate fuel oil, typically mounted on skid or trailer platforms with outputs from 10 kVA to 2,000 kVA. Saudi Aramco construction sites and UAE desalination outage contingencies absorb the highest deployment volumes, though SFDA Tier 4 interim mandates are compressing residual value for pre-2015 units.
- Gas Generators:Spark-ignited or dual-fuel reciprocating engines utilizing pipeline natural gas or LNG vaporization. Oman and Iraq oilfield electrification drives sustained demand where grid extension remains uneconomical, with Saudi Vision 2030 efficiency benchmarks accelerating fleet conversion.
- Hybrid Solutions:Battery storage integrated with reciprocating engines and photovoltaic augmentation.
- UPS Systems:Static uninterruptible power supply for critical load protection in data centers and healthcare.
Diesel generators anchor the volume base while hybrid solutions gain share at the steepest rate.
End User:
Contract duration varies sharply across end-use applications, from single-event mobilizations to decade-long mining commitments.
- Oil & Gas:Upstream exploration and production facilities requiring sustained multi-megawatt blocks. Iraq and Oman field developments generate 3-5 year availability guarantees rather than spot rentals, concentrating contract value with fleet-heavy incumbents who can underwrite balance-sheet exposure.
- Construction:Mega-project timelines in Saudi Arabia's NEOM and Red Sea developments. SFDA safety certification requirements raise barriers to entry, consolidating awards toward compliant operators with dense depot networks.
- Mining:Remote extraction sites in Mauritania and Sudan.
- Events:Temporary entertainment and sporting infrastructure in the UAE and Qatar.
Oil & Gas commands the longest contract tenors while Construction generates the highest transaction frequency.
Power Rating:
Unit economics improve non-linearly with scale, as above-1000 kVA blocks capture premium day rates and extended minimum commitments.
- Above 1000 kVA:Synchronous generator sets delivering sustained multi-megawatt output for mining camps and upstream oil installations. The steepest compliance cost concentration hits this segment due to engine replacement scale under UAE MOHAP and Saudi Vision 2030 efficiency mandates.
- 501-1000 kVA:Mid-scale blocks serving construction site offices and batching plants.
- 101-500 kVA:Distributed generation for remote work camps and small industrial loads.
- 1-100 kVA:Portable units for residential backup and small commercial applications.
Above 1000 kVA dominates value generation while 101-500 kVA shows the most rapid expansion in transaction count.
Deployment:
Service intensity and margin structure diverge based on whether assets remain under rental provider control or transfer to customer custody.
- Mobile Rental:Trailer-mounted or containerized assets relocated between sites by the rental provider. Aggreko and Byrne Equipment Rental compete on mobilization speed across the UAE and Saudi Arabia, with depot density determining response times for construction and events.
- Remote Monitoring:Digital telemetry and predictive maintenance algorithms virtualizing fleet management. Control system integration enables load-following applications without on-site technicians.
- On-site Installation:Fixed-position deployment with embedded service crews.
- Temporary Installations:Rapid-deployment configurations for emergency grid bridging.
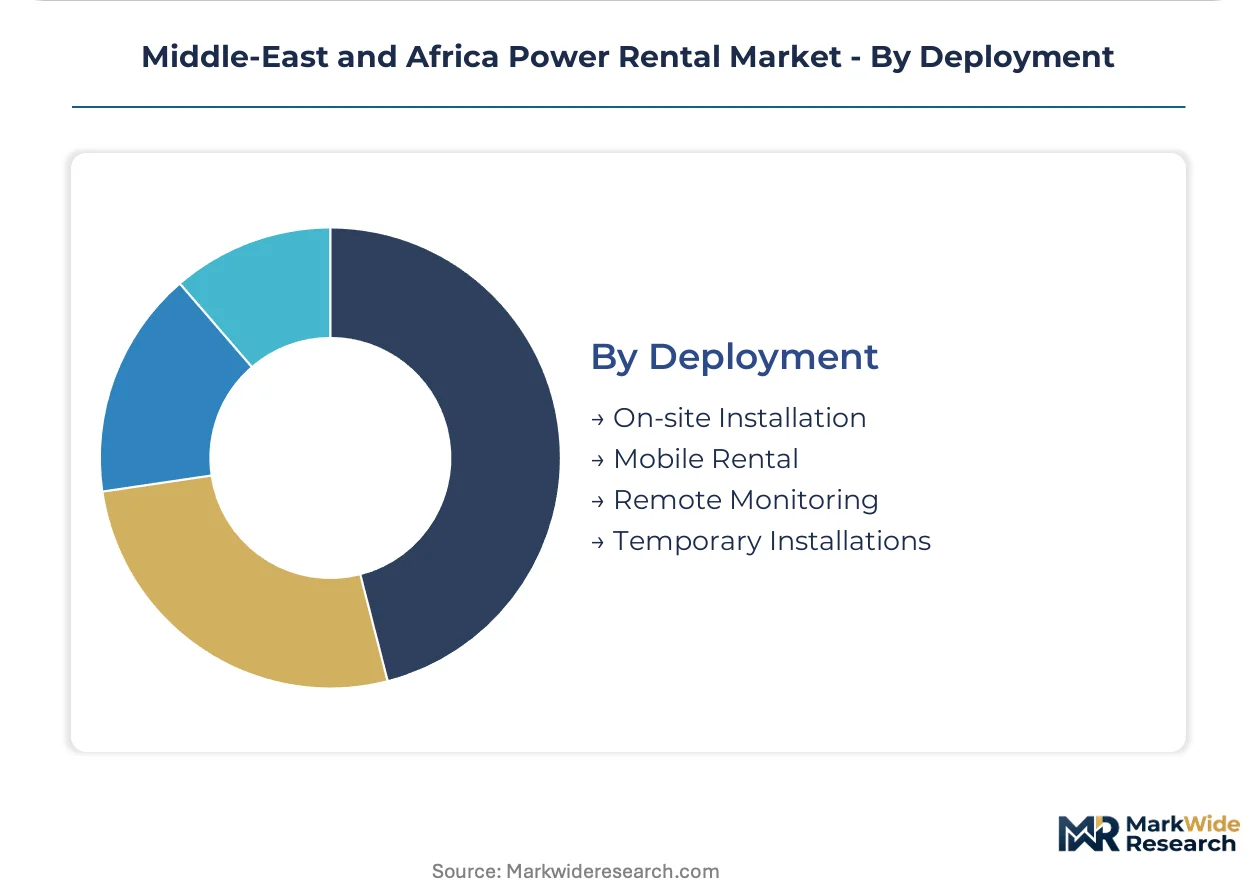
Mobile Rental captures the broadest geographic coverage while Remote Monitoring expands most quickly as a value-added layer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports temporary power capacity across the Gulf Cooperation Council corridor, serving UAE construction outages and Omani oilfield electrification projects. The regional trade pattern concentrates high-kVA blocks in Riyadh and Dubai depots for rapid redeployment.
Saudi Arabia
NEOM mega-construction and Red Sea tourism developments absorb multi-megawatt rental blocks for sustained timelines. SFDA equipment safety certification mandates fire suppression and exhaust treatment standards that disqualify pre-2015 diesel fleets from public sector tenders. Eastern Province oilfield operators contract 3-5 year availability guarantees rather than spot rentals.
United Arab Emirates
Desalination plant outage contingencies and Dubai Expo legacy infrastructure sustain peak rental demand during summer grid stress periods. MOHAP carbon eligibility criteria now mandate Tier 4 interim or gas certification for government construction contracts. Abu Dhabi National Oil Company field developments anchor long-term hybrid power agreements.
Oman
Upstream exploration intensification in Block 6 and Duqm refinery construction generates demand for mobile generation where grid extension remains uneconomical. Dual-fuel engine deployment accelerates where pipeline natural gas access permits 70% gas blending ratios. Sohar Industrial Port concentration drives depot density for mobilization speed.
Iraq
Basra oilfield electrification and grid instability create sustained demand for rental-backed generation despite security logistics complexity. Ministry of Electricity procurement frameworks redirect toward independent power projects with embedded rental provisions. Rumaila and West Qurna field clusters concentrate contract awards with fleet-heavy incumbents.
South Africa
Eskom load-shedding severity sustains commercial and industrial backup rental demand across Johannesburg and Cape Metro manufacturing corridors. National Energy Regulator of South Africa licensing requirements shape equipment specifications for embedded generation. Mining extraction sites in Rustenburg and Mpumalanga contract diesel-dependent blocks due to gas pipeline absence.
Middle-East and Africa Power Rental Market Competitive Landscape
Channel-controlling players compete with product-specialist players across depot density versus technology differentiation vectors. Fleet-heavy incumbents underwrite multi-year balance-sheet exposure for oilfield availability guarantees, while regional specialists compete on mobilization speed for construction and events. Two strategic archetypes dominate: Gulf-based depot network operators and Levant-East African service-led platforms. Competitive moves concentrate on hybrid fleet conversion and SFDA certification compliance rather than price-based rivalry.
Among Gulf-based depot network operators, Aggreko Middle East Ltd and Byrne Equipment Rental LLC exemplify the scale-driven archetype with dense UAE-Saudi coverage. Jubaili Bros. LLC anchors the service-led model extending into Levant and East African markets. These three occupy positions spanning technology certification, geographic reach, and contract tenure specialization.
| Leading Market Players |
|---|
| SES SMART Energy Solutions FZCO |
| Peax Equipment Rental |
| Aggreko Middle East Ltd |
| Jubaili Bros. LLC |
| Jozi Power Limited |
| Rental Solutions & Services LLC |
| KPS Power Generation |
| Atlas Copco AB |
| Byrne Equipment Rental LLC |
| Others |
Supply & Pricing Matrix
Engine manufacturing concentration in the United States, Germany, and Japan funnels margin capture toward OEM-certified rental providers who can absorb dual-fuel conversion capex, while Tier 1 diesel fleet operators face residual value compression under Saudi Vision 2030 mandates.
Pricing Analysis
Cost-plus contracts with diesel-indexed fuel adjustments anchor long-term oilfield agreements across Oman and Iraq, with day rates stratifying across Tier 4 interim certification, gas-hybrid capability, and embedded technician coverage. SFDA safety recertification timelines compress pricing power for non-compliant operators. Construction segments in the UAE exhibit acute price sensitivity during spot rental procurement, while mining camps in Mauritania prioritize fuel efficiency over rate negotiation.
Supply Chain Analysis
Export controls on dual-fuel engine management systems and battery storage inverters limit technology flows into the Gulf Cooperation Council corridor, concentrating advanced fleet access among incumbent operators with established OEM relationships. Component sourcing draws from engine block foundries in the United States and Germany, alternator assemblies in China, and exhaust after-treatment systems in the European Union. Single-source vulnerability in lithium-ion cell supply creates procurement risk for hybrid fleet expansion. Distribution runs through depot networks in Riyadh, Dubai, and Sohar with rapid-mobilization logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-entrenchment moat where SFDA and MOHAP certification timelines create switching costs that lock oilfield operators into incumbent relationships.
For Market Incumbents: Entrench market position by accelerating Tier 4 interim and gas-hybrid fleet conversion ahead of 2030 eligibility deadlines, while embedding predictive maintenance capabilities to extend contract tenors. Acquire distressed Tier 1 diesel assets from non-compliant competitors at residual value compression. Threat of embedded technician scarcity favors early certification investment. For New Entrants and Emerging Players: Establish a beachhead in East African mining camps where diesel dependency persists due to pipeline absence and incumbent depot density remains thin. Target Nigeria's independent power project frameworks as procurement shifts toward rental-backed generation. Go-to-market through fuel management bundling rather than equipment-only positioning. For Investors and Strategic Acquirers: Capital is best deployed toward fleet-heavy incumbents with dense Gulf Cooperation Council depot networks and multi-year availability guarantee underwriting capacity. Long-term viability hinges on hybrid technology certification breadth. Signal to monitor: MOHAP carbon eligibility criteria tightening beyond Tier 4 interim toward full gas-hybrid mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Fleet Conversion | SFDA Tier 4 interim certification locks in Saudi Aramco and NEOM contract eligibility. |
| Depot Network Expansion | Sohar and Duqm concentration captures Oman upstream exploration mobilization speed. |
| Hybrid Control System Integration | Battery-augmented load-following displaces spinning reserve in Saudi oilfield applications. |
| Embedded Technician Certification | OEM-specific training pipelines address Levant market scarcity for gas-hybrid maintenance. |
| Long-Term Availability Guarantees | 3-5 year contracts concentrate contract value with balance-sheet-capable incumbents in Iraq. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings across the Middle-East and Africa power rental market. Discussions with rental fleet managers, oilfield procurement officers, EPC contractors, and national utility planning departments informed operational dynamics. Secondary sources include SFDA equipment safety directives, MOHAP carbon eligibility frameworks, IEA power system data, and customs import records for generator sets. Bottom-up deployment modeling and top-down market sizing triangulate volume estimates.
Calibration against historical contract award patterns and fleet utilization rates shapes the analytical framework across service type, power rating, and end-use segmentation. Modeled dimensions span diesel-gas-hybrid fuel source, above-1000 kVA capacity tiers, and Gulf Cooperation Council versus East African regulatory clusters. CAGRs derive from deployment trajectory analysis and replacement cycle timing. Forecast inputs incorporate Saudi Vision 2030 desalination buildout timelines and Nigeria grid privatization procurement shifts.
Stress conditions across diesel fuel price volatility, dual-fuel engine derating penalties, and SFDA certification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding pipeline natural gas access expansion and hybrid technology cost curves. Material shifts in MOHAP carbon eligibility thresholds or East African grid privatization acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Australia Power Market
Power
Doubly Fed Induction Generator (DFIG) Market
Power
Asia-Pacific Package Substation Market
Power
Asia-Pacific Alternating Current (AC) Drive Market
Power
Asia-Pacific Turbomachinery Control Systems Market
Power
Smart Power Market
Power
India Power Market
Power
Asia-Pacific Power Market
Power
Flue Gas Desulfurization Unit Market
Power
Europe Submarine Power Cables Market
Power
Robotic Power Source Market
Power
North America CHP Market
Power
Middle East and Africa Combined Heat & Power Market
Power
Italy Power EPC Market
Power
Angola Power EPC Market
Power
Critical Power Market