
 South and Central America Oil Country Tubular Goods (OCTG) Market | 2026-2036
South and Central America Oil Country Tubular Goods (OCTG) Market Size, Share, and Industry Trends Forecast 2026-2036
South and Central America Oil Country Tubular Goods (OCTG) Market Analytics
Environmental compliance under Brazil's ANP local content mandates is expanding procurement complexity for offshore operators. Tenaris SA leverages integrated seamless pipe mills across Argentina and Brazil to sustain regional supply continuity. Vallourec SA anchors its position through premium connection technology leadership in high-pressure pre-salt applications. National-Oilwell Varco Inc. competes via drilling equipment bundling that tightens OCTG specification control for deepwater rigs.
Oil Country Tubular Goods comprise seamless and welded steel pipes manufactured to API 5CT specifications, with wall thicknesses engineered to withstand downhole pressures exceeding 15,000 psi in deepwater pre-salt formations. These products seal wellbore annular spaces and convey hydrocarbons from reservoir to surface infrastructure. Casing and tubing command the dominant product share given pre-salt completion intensity, while alloy steel grades capture expanding share as sour-service specifications tighten in Brazil's carbonate reservoirs. Production companies represent the most concentrated end-user segment, though service providers are gaining procurement influence through integrated drilling contracts.
Brazil's ANP and Argentina's Secretaría de Energía enforce local content thresholds that condition offshore concession renewals and import licensing for shale development. API 5CT and ISO 13679 standards govern product qualification, with NACE MR0175/ISO 15156 compliance mandatory for sour-service deployments. Stakeholders must monitor regulatory calibration between local manufacturing incentives and the technical feasibility of domestic alloy steel supply before committing capacity expansion decisions.
Market Dynamics
Pre-salt carbonate reservoirs in Brazil's Santos Basin are forcing specification upgrades across casing and tubing portfolios as operators push drilling depths beyond 6,000 meters. ANP local content mandates compound this technical pressure by requiring domestic manufacturing footprints for concession eligibility.
Growth Catalysts
- ANP Local Content Mandates:Brazil's regulatory framework ties offshore block renewals to minimum domestic procurement thresholds, redirecting supply chain investment toward regional mill capacity.
- Vaca Muerta Shale Development:Argentina's unconventional formation is driving horizontal well completion intensity and tubular consumption volumes in Neuquén province.
- Premium Connection Technology:High-pressure pre-salt applications are accelerating adoption of gas-tight threaded connections rated for 15,000 psi annular pressures.
Market Restraints
- Alloy Steel Import Dependence:Domestic South American supply of chromium-molybdenum grades remains insufficient for sour-service specifications, creating raw material bottlenecks.
- Deepwater Rig Availability:Limited floater fleet concentration in the Campos and Santos basins constrains drilling program scalability regardless of tubular inventory.
- Capital Intensity of Seamless Capacity:Greenfield pipe mill construction requires nine-figure investment with decade-long payback horizons, deterring new entrants.
Strategic Opportunities
- Guyana-Suriname Basin Expansion:ExxonMobil-operated Stabroek block discoveries are creating incremental demand for high-collapse casing in ultra-deepwater plays.
- Integrated Drilling Contracts:Service providers are bundling tubular procurement with rig provision, opening channel control for vertically capable suppliers.
- Colombia's Unconventional Pilot Programs:Ecopetrol's shale test wells in the Magdalena Valley represent an underpenetrated geography for OCTG specification trials.
Industry Challenges
- NACE MR0175 Certification Timelines:Sour-service qualification protocols for pre-salt carbonate environments extend product approval cycles by 12-18 months.
- Welding Technician Scarcity:Premium connection field service capabilities are concentrated among a limited pool of certified crews across Brazil and Argentina.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South and Central America Oil Country Tubular Goods (OCTG) Market |
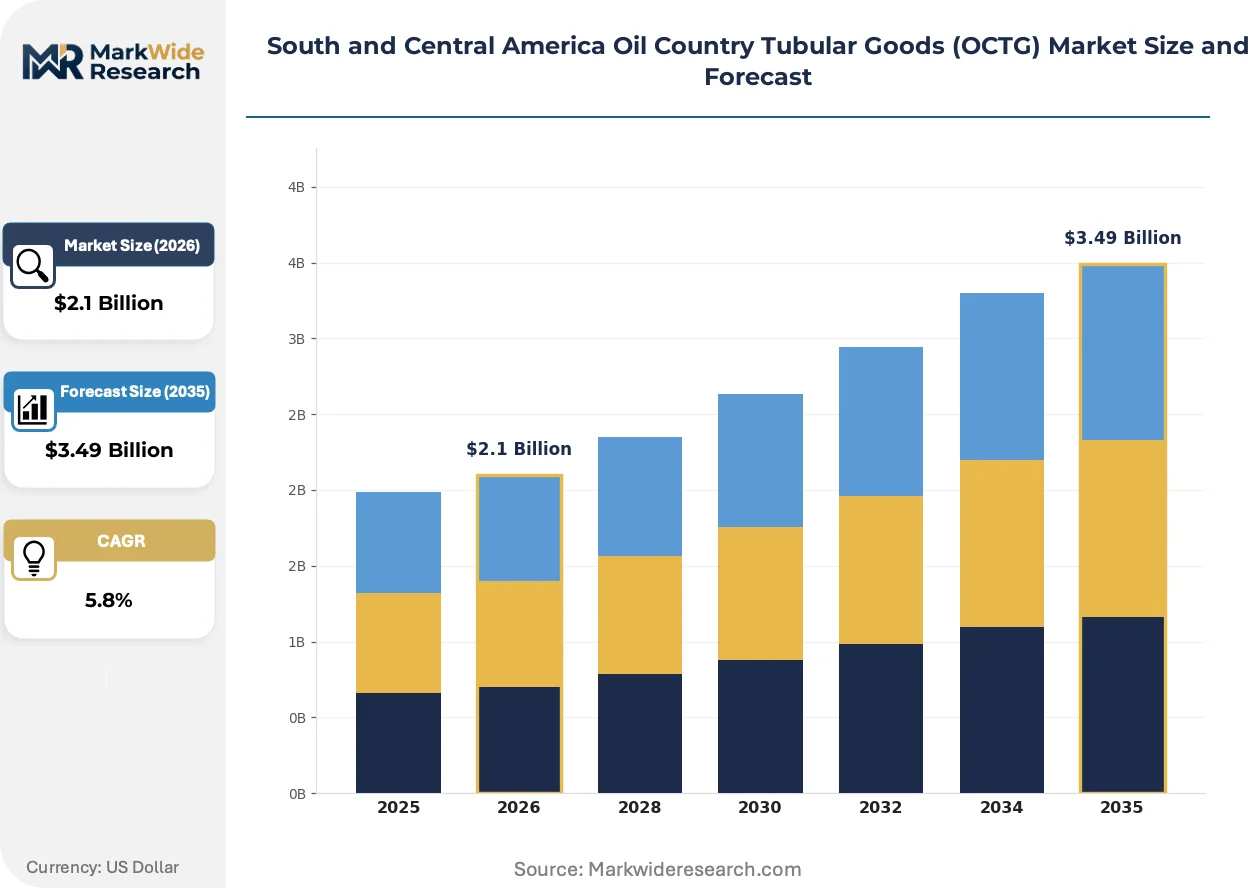
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drill Pipe, Casing, Tubing, Line Pipe Material: Carbon Steel, Alloy Steel, Stainless Steel, Others End User: Exploration Companies, Production Companies, Service Providers, Contractors Service Type: Maintenance, Installation, Inspection, Manufacturing |
| Companies Covered | Tenaris SA, National-Oilwell Varco Inc., Vallourec SA, ArcelorMittal SA, Nippon Steel Corporation, United States Steel Corporation, TMK Group, TPCO Enterprise Inc., Voestalpine AG, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South and Central America Oil Country Tubular Goods (OCTG) Market Evolving Landscape
Digital thread technologies and metallurgical advances are compressing product development cycles while regulatory ratchets force faster compliance adaptation. Three developments are restructuring competitive requirements.
Modular riser systems are modularizing subsea installation workflows by enabling stackable casing configurations that reduce offshore welding requirements. Petrobras and international operators in Brazil's pre-salt cluster are specifying these systems for 40% of new well completions. The technology is modularizing contractor specialization boundaries, forcing pipe suppliers to partner with subsea engineering houses.
ANP Resolution 854 tightened local content calculations for offshore equipment, eliminating certain imported subcomponents from domestic credit eligibility. This policy revision is redirecting capital expenditure toward Brazilian forging and heat-treatment facilities. Premium connection manufacturers with existing São Paulo state operations are expanding threading capacity to maintain concession access.
Integrated inventory management is replacing spot procurement as drilling contractors consolidate tubular specification authority under long-term service agreements. This behavior shift concentrates buying power with five major integrated service providers across Brazil's southeastern offshore cluster. The trend is most visible in pre-salt development programs where rig-day economics override unit cost optimization.
South and Central America Oil Country Tubular Goods (OCTG) Market Segmentation
Pre-salt drilling economics in Brazil and Vaca Muerta shale development in Argentina create divergent specification requirements across product portfolios. Material selection and end-user procurement authority are shifting as integrated service contracts consolidate buying power.
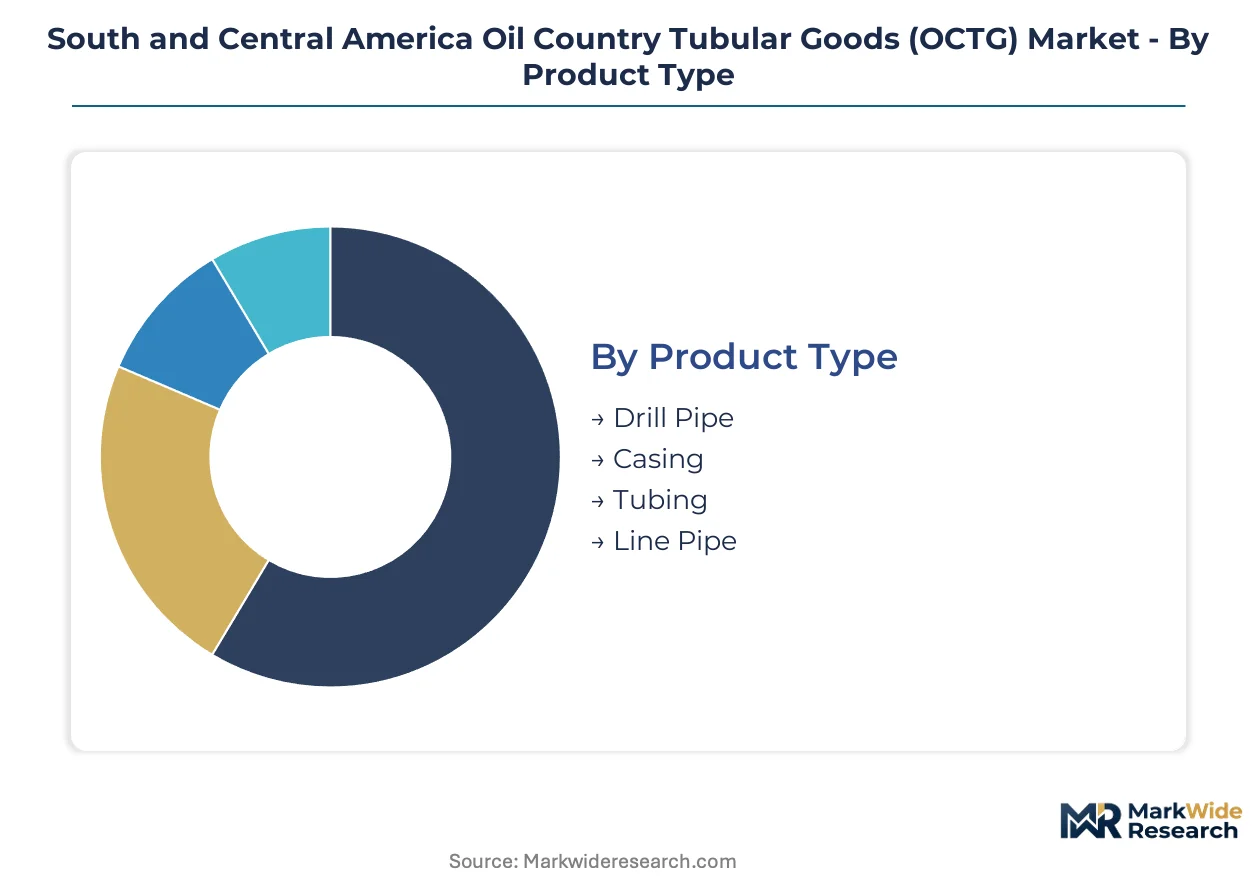
Product Type:
Well architecture complexity drives specification differentiation, with depth and pressure ratings determining procurement priority.
- Casing:Seamless and welded steel pipes engineered to API 5CT specifications seal wellbore annular spaces against formation pressures exceeding 15,000 psi in Santos Basin pre-salt formations. Petrobras and international operators in Brazil's southeastern offshore cluster specify premium connections and high-collapse grades for carbonate reservoirs below 6,000 meters.
- Tubing:Production conduit installed inside casing strings conveys hydrocarbons from reservoir to surface facilities, with gas-tight threaded connections mandatory for high-pressure pre-salt completions. Demand concentrates in Brazil's Campos and Santos basins where well completion intensity exceeds 15 strings per development well.
- Drill Pipe:Heavy-wall tubulars transmit torque and drilling fluid to the bit during well construction.
- Line Pipe:Pipeline-grade tubulars transport processed hydrocarbons from platform to shore infrastructure.
Casing leads on scale; tubing leads on momentum.
Material:
Corrosion resistance requirements in sour-service carbonate environments are elevating alloy specification premiums.
- Alloy Steel:Chromium-molybdenum grades deliver the tensile strength and sulfide stress cracking resistance mandatory for NACE MR0175/ISO 15156 compliance in Brazil's pre-salt carbonate reservoirs. Domestic South American supply of these grades remains insufficient, forcing dependence on imported raw material that extends lead times and tightens qualification protocols.
- Carbon Steel:Standard API 5CT grades dominate conventional onshore applications in Argentina's Neuquén province and Colombia's Magdalena Valley where pressure and H2S exposure remain moderate. Vaca Muerta horizontal well programs consume carbon grades for intermediate casing strings where sour-service specifications do not apply.
- Stainless Steel:Duplex and super-duplex grades address extreme corrosive conditions in high-CO2 formations.
- Others:Specialty metallurgical formulations including titanium-clad and corrosion-resistant alloy overlays.
Carbon steel dominates volume; alloy steel commands expanding specification share.
End User:
Procurement authority concentration is restructuring channel relationships across the value chain.
- Production Companies:National oil companies and international majors retain direct specification authority for long-cycle offshore developments, with Petrobras and ExxonMobil in the Guyana-Suriname basin defining technical requirements for pre-salt and ultra-deepwater programs. These entities negotiate frame agreements with mill-direct suppliers to secure volume commitments and local content compliance.
- Service Providers:Schlumberger, Halliburton, and Baker Hughes are consolidating tubular procurement under integrated drilling contracts that bundle rig provision with consumables supply. This shift concentrates buying power with five major integrated providers across Brazil's southeastern offshore cluster.
- Exploration Companies:Independent operators and concession holders in early-phase blocks.
- Contractors:Construction and installation firms executing subsea infrastructure scope.
Production companies anchor contract value; service providers are gaining procurement influence fastest.
Service Type:
Lifecycle economics are extending supplier relationships beyond manufacturing into field execution.
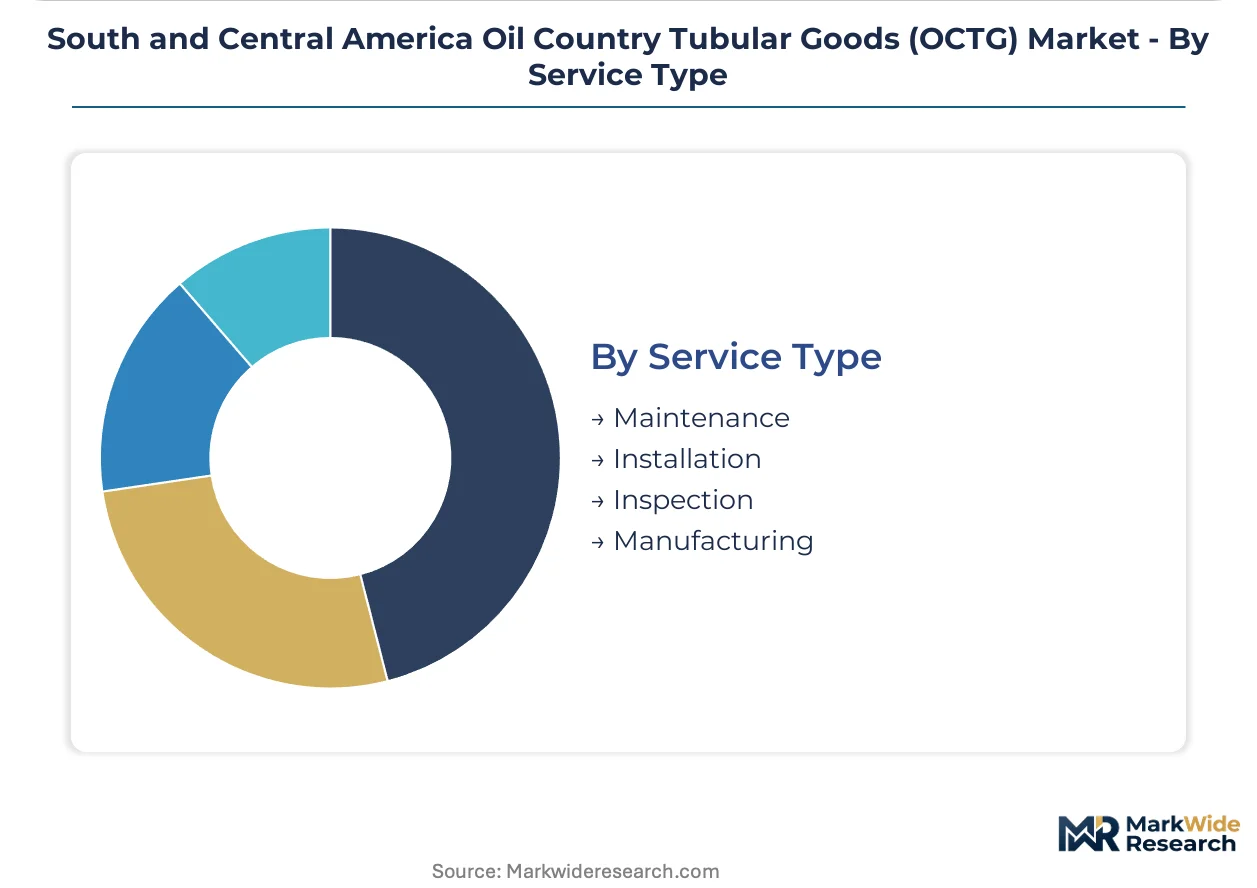
- Manufacturing:Seamless pipe production, threading operations, and heat treatment capacity located in Argentina and Brazil supply regional demand while ANP local content mandates redirect investment toward domestic forging facilities. Tenaris and Vallourec operate integrated mills across the region to sustain supply continuity under concession eligibility requirements.
- Installation:Premium connection make-up and field service capabilities are concentrated among limited certified crews across Brazil and Argentina, creating technician scarcity that extends rig downtime risk.
- Inspection:Non-destructive testing and dimensional verification protocols.
- Maintenance:Repair, re-threading, and recertification services for reusable tubular inventory.
Manufacturing captures value chain margin; installation services face capability constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized welding technicians and premium connection field service crews concentrate in Brazil's southeastern offshore corridor and Argentina's Neuquén basin, anchoring regional OCTG deployment capacity. These talent clusters determine where high-specification tubular installations proceed fastest.
Brazil
Petrobras-operated pre-salt developments in the Santos and Campos basins drive premium casing and tubing demand for wells exceeding 6,000 meters depth. ANP Resolution 854 mandates minimum domestic procurement thresholds for offshore concession renewals, redirecting supply chain investment toward São Paulo state forging facilities. The Macaé-Rio de Janeiro industrial corridor hosts threading and heat-treatment operations serving the southeastern offshore cluster.
Argentina
Vaca Muerta shale formation development in Neuquén province consumes carbon steel grades for horizontal well intermediate casing strings. The Secretaría de Energía enforces local content requirements for unconventional concession licensing, conditioning import approvals on domestic supplier participation. The Neuquén-Cipolletti industrial zone concentrates tubular distribution and field service capabilities for shale drilling programs.
Colombia
Ecopetrol's unconventional pilot programs in the Magdalena Valley generate specification trial demand for shale-appropriate casing designs. The Agencia Nacional de Hidrocarburos regulates upstream equipment imports through environmental licensing protocols that extend lead times for alloy steel grades. The Barrancabermeja refining complex anchors associated tubular maintenance and recertification services.
Guyana
ExxonMobil-operated Stabroek block ultra-deepwater discoveries require high-collapse casing rated for pressures encountered below 2,000 meters water depth. The Guyana Environmental Protection Agency oversees offshore development licensing with equipment qualification standards aligned to API 5CT specifications. Georgetown serves as the logistics coordination hub for tubular staging and offshore supply operations.
Mexico
Pemex deepwater exploration in the Perdido Fold Belt and onshore unconventional pilots in the Burgos Basin sustain OCTG procurement across pressure-rated product tiers. The Comisión Nacional de Hidrocarburos administers local content requirements for exploration and production contracts under the 2013 energy reform framework. The Altamira-Tampico corridor on the Gulf Coast maintains inventory staging and threading service capacity for offshore and onshore programs.
South and Central America Oil Country Tubular Goods (OCTG) Market Competitive Landscape
Capital-heavy integrated steel producers compete with specialized tubular manufacturers and equipment bundlers across distinct capability tiers. The market structure concentrates around mill-direct suppliers with seamless pipe capacity, premium connection technology holders, and drilling equipment integrators. Three archetypes dominate: full-line seamless producers with regional forging footprints, premium threading specialists with sour-service certification depth, and rig-package bundlers controlling specification authority. Competitive dynamics center on concession access compliance and long-term frame agreement capture.
Among integrated seamless pipe producers, Tenaris SA and Vallourec SA occupy positions defined by mill presence across Argentina and Brazil. National-Oilwell Varco Inc. represents the equipment-bundling archetype, anchoring specification control through integrated drilling contract structures. These three entities exemplify how regional manufacturing footprints, premium connection portfolios, and rig-integration capabilities respectively secure market position under ANP and Secretaría de Energía local content mandates.
| Leading Market Players |
|---|
| Tenaris SA |
| National-Oilwell Varco Inc. |
| Vallourec SA |
| ArcelorMittal SA |
| Nippon Steel Corporation |
| United States Steel Corporation |
| TMK Group |
| TPCO Enterprise Inc. |
| Voestalpine AG |
| Others |
Value Network & Pricing Analysis
Premium connection threading automation across São Paulo state forging facilities is compressing unit economics while concentrating procurement leverage among ANP-compliant domestic suppliers. This technology shift simultaneously elevates capital barriers for non-compliant imports and redirects price competition toward local content credit accumulation rather than base material cost.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by NACE MR0175 certification depth and connection gas-tightness ratings. Price differentiation hinges on sour-service qualification status and volume commitments under frame agreements with integrated drilling contractors. Cost compression in standard carbon grades is intensifying because Vaca Muerta shale operators prioritize procurement scale over metallurgical premium. Production companies retain direct specification authority are least price-sensitive; independent exploration companies in early-phase blocks exhibit highest price elasticity.
Supply Chain Analysis
Single-source vulnerability sits with chromium-molybdenum alloy feedstock drawn from European and Asian specialty steel producers. Raw material sourcing rests on imported billet, domestic seamless pipe production in Argentina and Brazil, and premium threading capacity concentrated in the Macaé-Rio de Janeiro corridor. Tariff exposure on alloy steel imports creates structural risk for sour-service product lines. Distribution runs through mill-direct frame agreements with Petrobras and integrated service provider consignment inventory at southeastern offshore supply bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANP Resolution 854 functions as a regulatory compounder, mandating domestic procurement thresholds that accelerate demand for Brazilian-forged OCTG with concession renewal cycles. This policy architecture creates structural preference for regional manufacturing footprints.
For Market Incumbents: Deploy threading capacity expansion in São Paulo state to capture ANP local content credit eligibility before concession renewal windows close. Secure backward integration into heat-treatment facilities to defend margin position against alloy steel import cost volatility. Lock long-term frame agreements with Schlumberger and Halliburton as integrated drilling contracts consolidate procurement authority. For New Entrants and Emerging Players: ANP Resolution 854 in Brazil opens a window for forging joint ventures with established European specialty steel producers lacking domestic Brazilian presence. Target Colombia's Magdalena Valley unconventional pilots as the most penetrable geography for specification trial partnerships with Ecopetrol. Pursue channel entry through premium connection field service capabilities, where certified welding technician scarcity limits incumbent coverage. For Investors and Strategic Acquirers: Roll-up economics work for premium threading specialists with NACE MR0175 certification depth because sour-service qualification timelines extend competitive moats beyond capital reach. Platform consolidation targets mid-cap Brazilian forging facilities with latent seamless pipe capacity and ANP compliance infrastructure. Monitor alloy steel import license approval velocity as the inflection signal for domestic margin expansion versus import substitution viability.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Forging Capacity Expansion | ANP Resolution 854 compliance secures Petrobras frame agreement eligibility for concession holders. |
| Premium Connection Technology Licensing | Gas-tight threading IP transfer accelerates local qualification for 15,000 psi pre-salt applications. |
| Integrated Drilling Contract Partnership | Schlumberger and Halliburton bundling concentrates procurement leverage with vertically capable suppliers. |
| Alloy Steel Import Diversification | European and Asian billet sourcing redundancy mitigates tariff exposure on sour-service grades. |
| Field Service Technician Certification Programs | ANP-compliant welding crew expansion addresses rig downtime risk in Brazil's southeastern offshore cluster. |
Research Methodology
Bottom-up drilling program modeling reconciled against top-down mill capacity tracking forms the analytical core of this study. Primary interviews with OCTG procurement managers at national oil companies, drilling contractor supply chain directors, premium connection field service supervisors, and ANP regulatory affairs specialists were validated against secondary sources including ANP concession registry filings, Brazilian customs import records for alloy steel grades, API 5CT certification databases, and Petrobras annual procurement disclosures. Triangulation between demand-side well completion forecasts and supply-side forging capacity utilization rates ensures consistency across the analysis window.
Historical trendline analysis of pre-salt drilling intensity and Vaca Muerta horizontal well completion rates established baseline growth parameters across the projection horizon. The forecast framework models segmentation by product type, material grade, end-user procurement authority, and service type integration depth. CAGRs were derived from elasticity-adjusted demand curves incorporating ANP local content threshold enforcement schedules and pre-salt carbonate reservoir pressure rating escalations. Alloy steel import lead time volatility and deepwater rig fleet availability constraints were incorporated as scenario variables.
Revisions become necessary when ANP local content calculations are recalibrated, pre-salt drilling depth records extend beyond current metallurgical specifications, or Guyana-Suriname basin discoveries accelerate faster than tubular inventory staging capacity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
India Natural Gas Market
Oil & Gas
Oil Well Cement Market
Oil & Gas
Ecuador Wireline Logging Services Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Oil and Gas Automation Market
Oil & Gas
Canada LNG Bunkering Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Global Floating LNG Terminal Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
Asia-Pacific Oilfield Services Market
Oil & Gas
Pipeline Integrity Market
Oil & Gas
Asia-Pacific Oil Country Tubular Goods Market
Oil & Gas
Coal Bed Methane Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market
Oil & Gas
Microbial Enhanced Oil Recovery Market