
 Vietnam Power Market | 2026-2036
Vietnam Power Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Power Market Outlook
Aftermarket service revenue from grid balancing and frequency regulation is narrowing as state-owned generators internalize these functions. Vietnam Electricity dominates transmission infrastructure and controls dispatch scheduling across the national grid. PetroVietnam leverages its upstream gas position to anchor natural gas-fired generation in the southeast. AES Mong Duong Power Company Limited competes on operational efficiency at its imported-coal facility in Quang Ninh province.
Vietnam power encompasses electricity generated, transmitted, and distributed across a 110-500 kV national grid serving a population exceeding 100 million, with thermal plants historically providing base-load reliability through coal and gas combustion. The system serves industrial manufacturing, residential consumption, and agricultural pumping as its primary commercial purposes. Coal generation under the power generation type segment still occupies the largest share of installed capacity despite environmental pressures, while wind installations represent the fastest-expanding category as offshore lease rounds attract foreign developers. The consumer segment tilts heavily toward industrial buyers whose offtake agreements under long-term power purchase agreements provide revenue visibility that residential tariffs cannot match.
The Ministry of Industry and Trade sets generation licensing and tariff structures under Vietnam's Electricity Law, while the Prime Minister's renewable energy incentives direct investment quotas toward non-hydro clean capacity additions. CEA standards govern grid code compliance and technical interconnect requirements for new plant commissioning. Stakeholders must monitor how the competitive generation market mechanism pilot reshapes dispatch hierarchies and merchant price exposure for independent power producers.
Market Dynamics
Vietnam's power sector is undergoing structural reconfiguration as feed-in tariff revisions redirect capital flows from guaranteed renewable pricing toward competitive auction mechanisms. The Ministry of Industry and Trade's licensing framework now favors developers capable of delivering grid-scale solar and wind at merchant-exposed rates.
Growth Catalysts
- Renewable Energy Auction Mechanisms:The Prime Minister's competitive bidding framework for solar and wind projects is attracting foreign developers with technical expertise in offshore installations. This policy shift accelerates capacity additions beyond state-owned utility timelines.
- Industrial Zone Electrification:Manufacturing clusters around Ho Chi Minh City and Hai Phong are expanding electricity offtake as export-oriented factories deepen automation and process electrification. These load centers anchor long-term power purchase agreements.
- Feed-in Tariff Revisions:Adjusted pricing structures under Vietnam's Electricity Law continue incentivizing non-hydro clean capacity additions while phasing down legacy subsidy rates. Independent power producers are recalibrating project finance assumptions.
Market Restraints
- Transmission Bottlenecks:Vietnam Electricity's monopoly over 110-500 kV infrastructure creates dispatch scheduling constraints that strand renewable generation in the central highlands. Grid reinforcement lags behind generation commissioning.
- Imported Coal Dependency:Thermal plants in Quang Ninh province rely on seaborne coal subject to freight volatility and currency fluctuation. This input cost exposure compresses operational margins for base-load generators.
- Gas Supply Concentration:PetroVietnam's upstream dominance limits alternative fuel sourcing for combined-cycle facilities in the southeast. Pipeline infrastructure constraints restrict generation flexibility during demand spikes.
Strategic Opportunities
- Offshore Wind Lease Rounds:Unallocated seabed concessions in the Mekong Delta region offer development rights for floating turbine platforms. Foreign developers with North Sea experience are pre-qualifying for upcoming tenders.
- Grid Balancing Services:Frequency regulation and ancillary service markets remain underdeveloped as state-owned generators internalize these functions. Merchant battery storage operators could capture value from dispatch volatility.
- Industrial Self-Generation:Large manufacturing facilities in Binh Duong province are installing captive solar arrays behind the meter to hedge against regulated tariff escalation and supply interruption risks.
Industry Challenges
- Interconnection Queue Delays:CEA technical compliance reviews and grid code certification timelines extend project commissioning by 12-18 months beyond construction completion. Developer working capital requirements balloon during regulatory limbo.
- Merchant Price Exposure:The competitive generation market pilot exposes independent power producers to dispatch hierarchies that favor incumbent state-owned assets. Revenue forecasting complexity deters project finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Power Market |
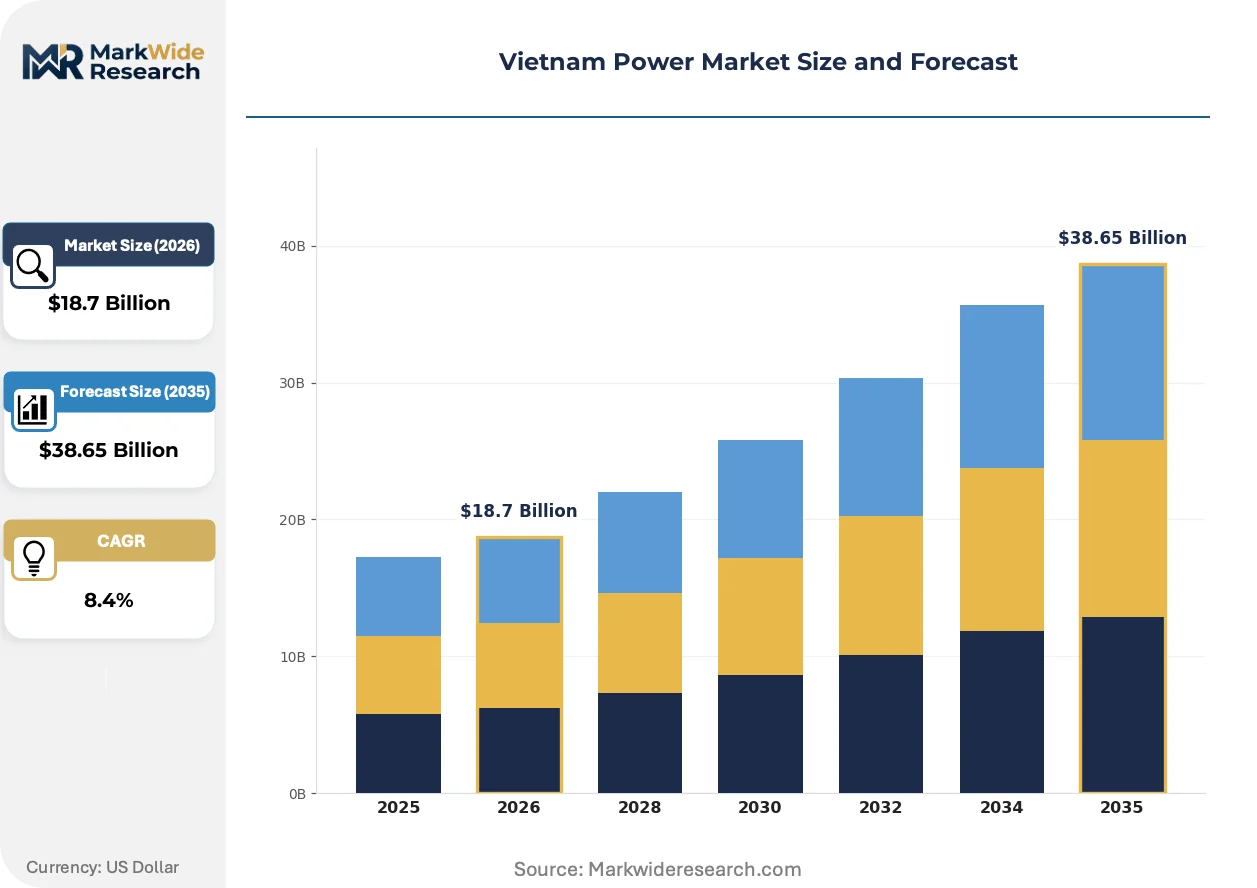
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Generation Type: Coal, Natural Gas, Hydro, Wind Consumer Segment: Residential, Commercial, Industrial, Agricultural Distribution Channel: Direct Supply, Retail Electricity, Wholesale Market, Grid Connection Regulatory Framework: Feed-in Tariff, Power Purchase Agreement, Market Competition, Renewable Energy Incentives |
| Companies Covered | Vietnam Electricity, PetroVietnam, Vinacomin, GENCO 1, GENCO 2, GENCO 3, AES Mong Duong Power Company Limited, Mekong Energy Company Ltd, Jera Co Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Power Market Strategic Shifts
Technology deployment across Vietnam's power sector is accelerating as digital infrastructure penetrates generation control systems and grid operations. Regulatory frameworks are simultaneously evolving to accommodate distributed resources and market-based dispatch.
Advanced metering infrastructure is digitizing consumption patterns across Vietnam Electricity's distribution network. Industrial facilities in southern grid regions are deploying sub-hourly monitoring to optimize demand response participation. This granularity is compressing settlement cycles and enabling real-time price signals for large offtakers.
CEA grid code revisions under the Electricity Law are mandating frequency response capabilities for new renewable interconnects. Wind and solar developers must install synthetic inertia systems or face dispatch curtailment. The central highlands generation cluster is adapting fastest due to concentration of foreign-built assets with integrated power electronics.
Corporate buyers in Ho Chi Minh City's export processing zones are contracting directly with renewable developers through virtual power purchase agreements. This bypasses Vietnam Electricity's monopoly over bilateral contracting. Electronics and textile manufacturers with sustainability mandates are driving this channel innovation most aggressively.
Vietnam Power Market Segmentation
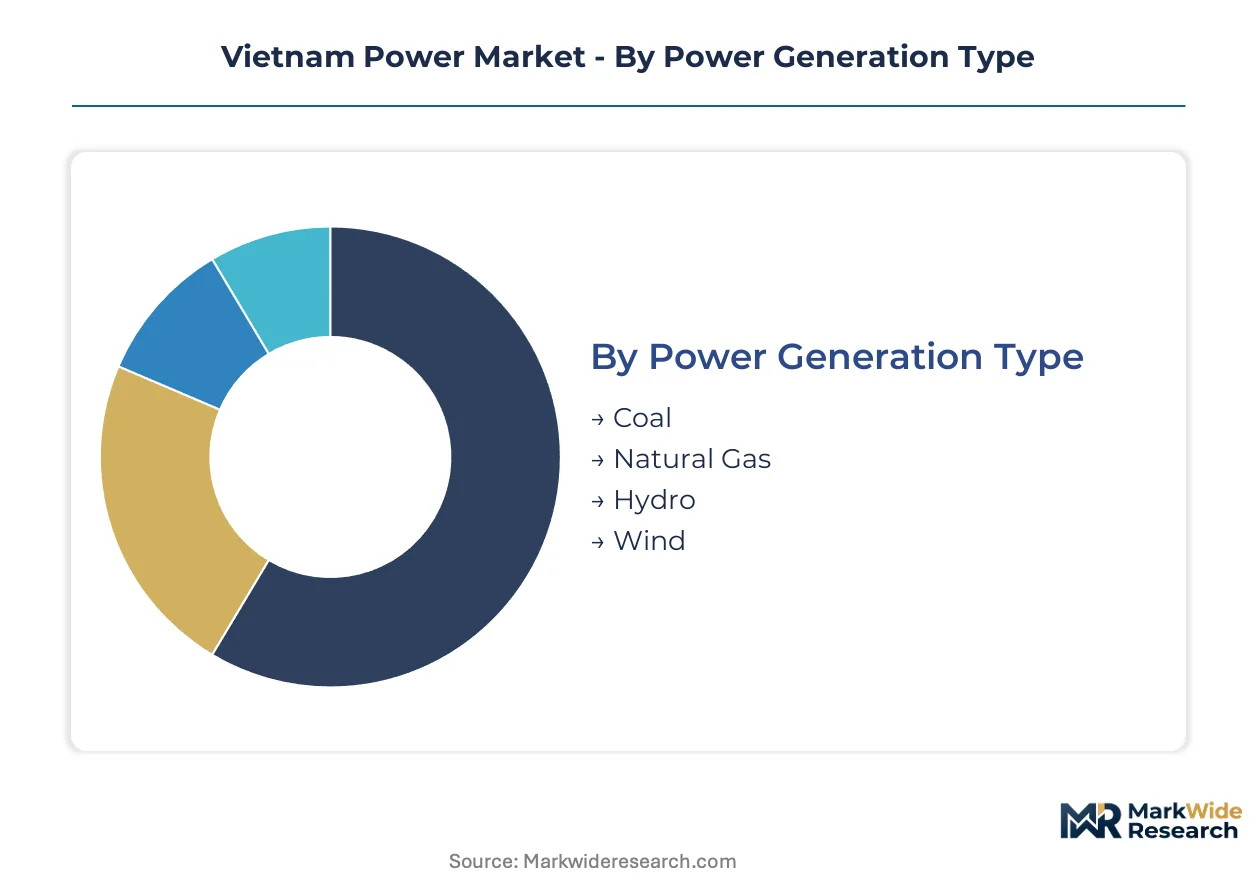
Segmentation reveals how capital allocation and regulatory exposure diverge across Vietnam's power sector. Each dimension exposes distinct risk-return profiles for developers, offtakers, and infrastructure investors navigating the transition from state-controlled dispatch toward competitive market mechanisms.
Power Generation Type:
Cost tier differentiation separates base-load reliability assets from variable renewable entrants competing on marginal generation cost.
- Coal:Imported bituminous and domestic anthracite combustion dominates installed capacity through supercritical plants in Quang Ninh province. Industrial buyers in southern grid regions anchor long-term offtake despite carbon border adjustment exposure on export-bound manufacturing.
- Wind:Onshore installations in Ninh Thuan province and emerging offshore lease rounds in the Mekong Delta attract foreign developers with floating platform expertise. Merchant price exposure under auction mechanisms compresses equity returns while accelerating capacity deployment.
- Natural Gas:Combined-cycle facilities in the southeast rely on PetroVietnam's upstream supply concentration. Pipeline constraints restrict operational flexibility during demand spikes.
- Hydro:Run-of-river and reservoir plants in the northern highlands provide peaking capacity. Seasonal flow variability limits year-round dispatch reliability.
Coal commands the established base. The steepest expansion runs through Wind.
Consumer Segment:
Application-based demand concentration tilts toward manufacturing automation and process electrification in export processing zones.
- Industrial:Electronics and textile factories in Binh Duong and Dong Nai provinces drive the largest volume offtake through long-term power purchase agreements. Automation upgrades and captive solar installations are reshaping grid dependency.
- Commercial:Office towers and retail complexes in Ho Chi Minh City's central business district deploy advanced metering for demand response participation. Real-time pricing signals are compressing consumption during peak intervals.
- Residential:Urban apartment blocks and rural households face regulated tariffs below cost-recovery levels. Vietnam Electricity's distribution monopoly limits retail choice.
- Agricultural:Mekong Delta pumping stations and post-harvest processing facilities consume seasonal loads. Irrigation electrification programs are expanding rural grid access.
Industrial offtake anchors revenue visibility. Commercial consumption is climbing the fastest.
Distribution Channel:
Volume concentration reflects state monopoly control over transmission infrastructure and emerging bilateral contracting channels.
- Direct Supply:Large industrial facilities in southern industrial zones negotiate bilateral contracts with independent power producers. This bypasses Vietnam Electricity's retail tariff structure.
- Grid Connection:New renewable developers in the central highlands face interconnection queue delays as CEA technical reviews extend commissioning timelines. Working capital requirements balloon during regulatory limbo.
- Retail Electricity:Vietnam Electricity's distribution monopoly serves residential and small commercial accounts through regulated tariff schedules. Cross-subsidization from industrial rates masks cost inefficiency.
- Wholesale Market:The competitive generation market pilot exposes independent power producers to dispatch hierarchies favoring state-owned assets. Price forecasting complexity deters project finance.
Direct supply is gaining share fastest. Grid connection constraints limit expansion velocity.
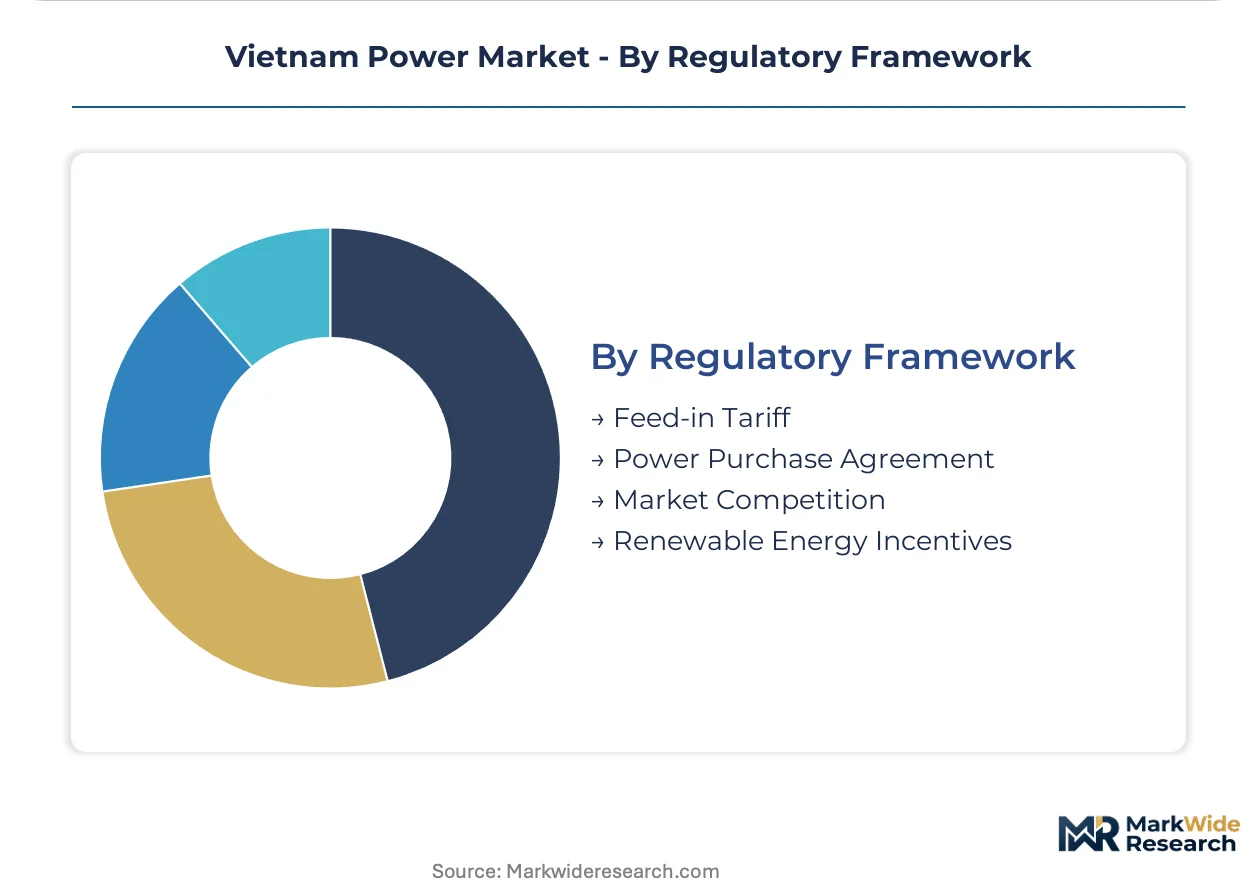
Regulatory Framework:
Margin exposure hinges on contract structure stability and incentive mechanism evolution under Vietnam's Electricity Law.
- Power Purchase Agreement:Long-term offtake contracts with Vietnam Electricity provide revenue certainty for thermal and hydro developers. Industrial self-generation is eroding traditional PPA volumes.
- Feed-in Tariff:Legacy guaranteed pricing for early solar installations is phasing down. Developers are recalibrating project finance assumptions toward merchant-exposed returns.
- Renewable Energy Incentives:Prime Minister-directed investment quotas and tax holidays accelerate non-hydro clean capacity. Auction mechanisms are displacing administratively set prices.
- Market Competition:The pilot competitive generation mechanism reshapes dispatch hierarchies. Independent power producers face revenue volatility as state-owned generators retain priority scheduling.
Power purchase agreements command the established base. Renewable energy incentives are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southern Vietnam consumes electricity differently from northern regions, with industrial load centers clustering near export processing zones rather than residential heating demand. The central highlands generation concentration contrasts with the northern reservoir-based hydro peaking capacity.
Southeast Region
Binh Duong and Dong Nai provinces anchor manufacturing electrification through electronics and textile factory automation. The Ministry of Industry and Trade's industrial zone licensing framework channels power purchase agreements toward these load centers. Ho Chi Minh City's export processing zones are installing captive solar arrays behind the meter to hedge tariff volatility.
Red River Delta
Hanoi and Hai Phong industrial corridors drive base-load demand through steel and cement production facilities. CEA grid code compliance mandates frequency response capabilities for new interconnects in this northern hub. Quang Ninh province hosts imported-coal thermal plants serving manufacturing clusters around the port city.
Central Highlands
Ninh Thuan province concentrates onshore wind installations with foreign developer participation in auction mechanisms. The Prime Minister's renewable energy investment quotas direct tax holidays toward this generation cluster. Grid reinforcement lags behind commissioning, stranding variable output during peak production periods.
Mekong Delta
Offshore wind lease rounds in seabed concessions attract developers with floating platform expertise from North Sea markets. Provincial agricultural pumping stations create seasonal demand spikes for irrigation electrification programs. Can Tho and surrounding industrial zones are negotiating direct supply contracts bypassing Vietnam Electricity's retail monopoly.
North Central Coast
Thanh Hoa and Nghe An provinces balance thermal generation with emerging solar capacity under feed-in tariff transitions. The competitive generation market pilot exposes independent power producers here to dispatch hierarchies favoring state-owned assets. Manufacturing facilities are slower to adopt captive generation compared to southern counterparts.
Vietnam Power Market Competitive Environment
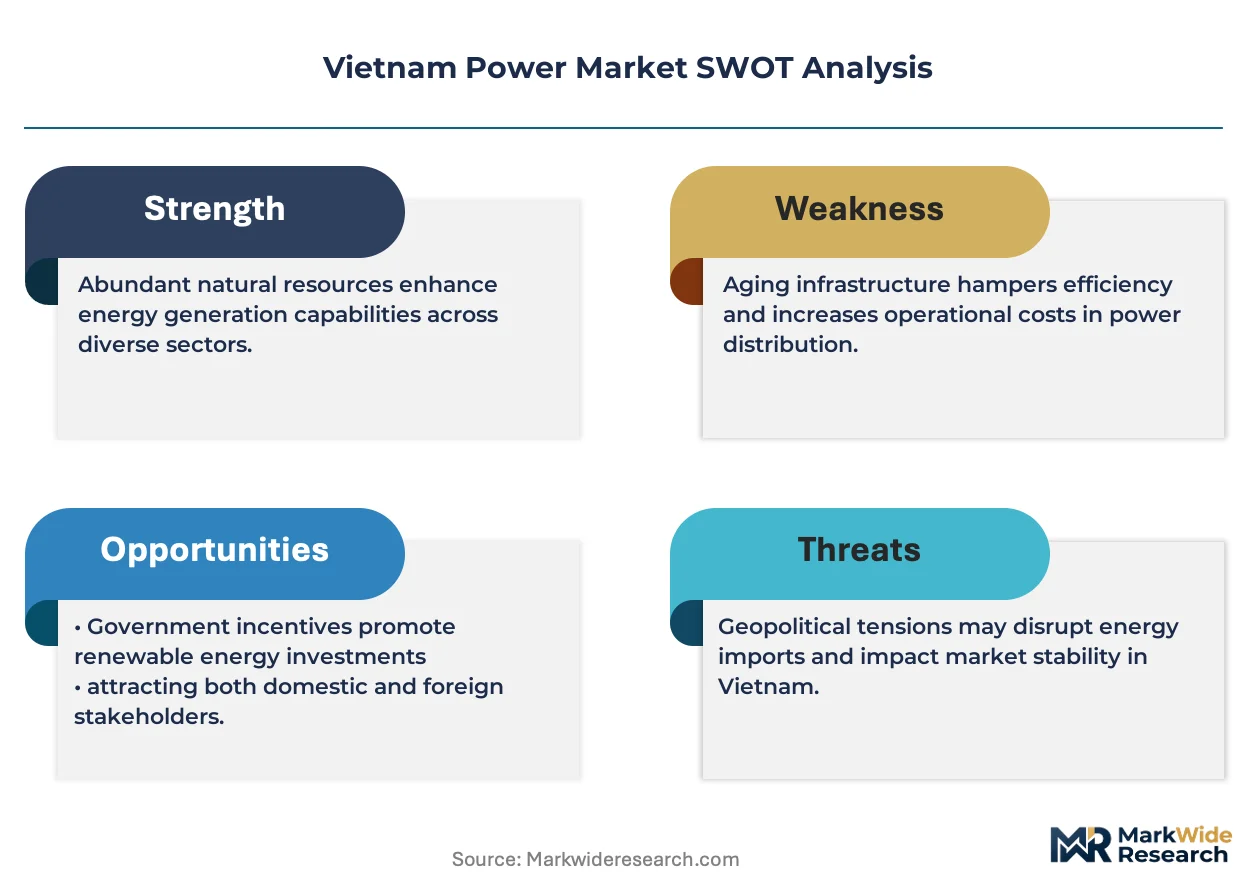
Capability concentration sits with state-owned incumbents; scale advantage sits with generation portfolio breadth. Vietnam Electricity controls transmission infrastructure and dispatch scheduling nationwide, creating structural barriers for merchant entrants. Three archetypes dominate: vertically integrated state utilities, foreign independent power producers with operational efficiency focus, and captive industrial self-generators. Competitive moves center on auction mechanism positioning and bilateral contract origination with large offtakers.
Within the state-owned tier, Vietnam Electricity and PetroVietnam anchor infrastructure control and upstream fuel supply respectively. AES Mong Duong Power Company Limited occupies a position exemplifying foreign operational efficiency specialization at imported-coal facilities. These entities represent the spectrum from transmission monopoly through fuel-integrated generation to merchant-exposed independent production.
| Leading Market Players |
|---|
| Vietnam Electricity |
| PetroVietnam |
| Vinacomin |
| GENCO 1 |
| GENCO 2 |
| GENCO 3 |
| AES Mong Duong Power Company Limited |
| Mekong Energy Company Ltd |
| Jera Co Inc. |
| Others |
Value Chain & Pricing Dynamics
Hai Phong-to-Quang Ninh coal freight corridors anchor input cost dynamics for thermal generators, concentrating supply-side pricing power with import-dependent operators while downstream industrial buyers face divergent contract structures based on volume scale and grid access priority.
Pricing Analysis
Long-term power purchase agreements with Vietnam Electricity dominate commercial arrangements, providing base-load generators revenue certainty against merchant-exposed renewable auction outcomes. Price differentiation separates industrial direct-supply contracts from regulated retail tariffs through volume scale and interruptibility provisions. Cost compression in thermal generation is intensifying because imported coal freight volatility and currency fluctuation erode operational margins. Residential tariffs remain the most price-sensitive segment due to political caps below cost-recovery levels, while export-oriented manufacturers absorb premium rates for supply security.
Supply Chain Analysis
Extended payment terms from state-owned offtakers strain developer working capital, particularly during CEA grid code certification delays that extend commissioning timelines. Equipment procurement draws from China, South Korea, and Germany for turbines, switchgear, and control systems. Seaborne coal from Indonesia and Australia feeds thermal plants in Quang Ninh province. Single-source vulnerability concentrates in PetroVietnam's upstream gas supply for southeastern combined-cycle facilities. Distribution runs through Vietnam Electricity's 110-500 kV transmission monopoly, limiting merchant generator dispatch flexibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's power sector presents a defensive-moat story anchored in Vietnam Electricity's transmission monopoly, where regulatory entrenchment creates structural barriers that deter merchant competition and protect incumbent cash flows.
For Market Incumbents: Harden dispatch priority through grid balancing service internalization, capturing frequency regulation revenue that battery storage operators seek. Expand captive renewable development in Ninh Thuan province to preempt foreign auction winners. Vertical integration into offshore wind EPC capabilities counters emerging North Sea specialist entrants.
For New Entrants and Emerging Players: Pursue industrial self-generation opportunities in Binh Duong province, where manufacturing facilities seek behind-the-meter solar to hedge regulated tariff escalation. Target direct supply contract origination with electronics and textile exporters in Ho Chi Minh City processing zones. Lead with sustainability credentials to align with corporate renewable procurement mandates.
For Investors and Strategic Acquirers: Foreign independent power producers with operational efficiency specialization represent the most defensible acquisition archetype, given their merchant-exposure experience and bilateral contracting relationships. Monitor the competitive generation market pilot's expansion as the inflection signal for dispatch hierarchy reform and independent producer margin recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Wind Lease Acquisition | Mekong Delta seabed concessions attract floating platform expertise from North Sea developers. |
| Grid Balancing Service Market Entry | Merchant battery storage operators capture value from frequency regulation demand volatility. |
| Industrial Direct Supply Contracting | Bilateral agreements with Binh Duong manufacturers bypass Vietnam Electricity's retail monopoly. |
| Captive Solar Installation | Behind-the-meter generation hedges export processors against tariff escalation risks. |
| Transmission Infrastructure Reinforcement | Grid upgrades in central highlands reduce renewable curtailment during peak production. |
Study Parameters
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity addition tracking and top-down demand forecasting were triangulated to ensure consistency across modeling approaches.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning fuel source, generation capacity tier, regulatory framework, and regional grid type. CAGRs were derived from installed capacity buildout trajectories and demand elasticity modeling. Forecast inputs incorporated industrial zone electrification rates and renewable auction mechanism participation assumptions.
Sensitivities concentrate around feed-in tariff revision timing, competitive generation market pilot expansion, and transmission reinforcement lag. Forecasts reflect documented assumptions regarding policy continuity and capital flow redirection. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Asia-Pacific Power Purchase Agreement Market
Power
Middle-East and Africa Power Rental Market
Power
Distributed Buoyancy Modules Market
Power
Modified Sine Wave Home Inverters Market
Power
Residential Micro Inverter Market
Power
Asia-Pacific Microturbine Market
Power
Wind Alarm Controller Market
Power
Europe Power Purchase Agreement Market
Power
Uzbekistan Power Market
Power
Doubly Fed Induction Generator (DFIG) Market
Power
Sudan Power EPC Market
Power
India Power Market
Power
North America Microturbine Market
Power
Harmonic Filter Market
Power
Power Rental Market
Power
China Power Market