
 Automated Demand Response Management Systems Market | 2026-2036
Automated Demand Response Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Demand Response Management Systems Market Outlook
Project finance and energy-as-a-service leasing is tilting competitive dynamics toward asset-light platform providers that bypass capital-intensive infrastructure ownership. Schneider Electric leverages its integrated hardware-software stack to anchor large commercial deployments across multiple continents. AutoGrid Systems Inc. specializes in cloud-native virtual power plant orchestration, competing on software agility rather than physical equipment. Johnson Controls sustains channel dominance through its building automation installed base, converting legacy HVAC controls into responsive grid assets.
Automated demand response management systems coordinate curtailable electrical loads through real-time telemetry, control algorithms, and utility dispatch signals, typically responding to price or reliability triggers within seconds to minutes. The primary purpose is to stabilize grid frequency and defer generation capacity investments by monetizing flexibility from distributed energy resources. Software Solutions and Cloud-Based Platforms capture expanding margin pools as utilities shift from one-time hardware purchases to recurring SaaS subscriptions for dispatch optimization. Industrial Facilities represent the fastest-growing end user segment, driven by behind-the-meter battery storage and process load flexibility that AI Algorithms continuously optimize for price and grid signal response.
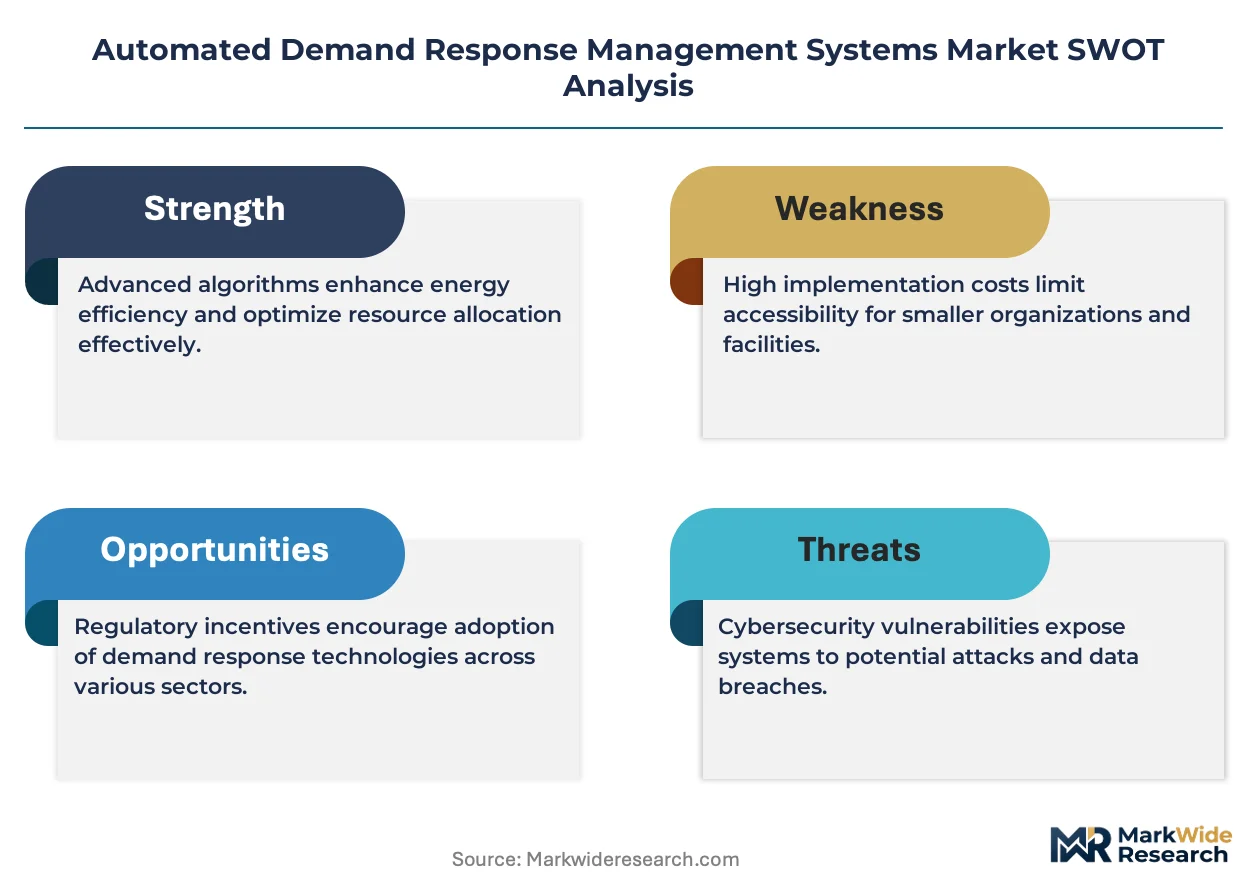
FERC Order 2222 in the United States enables aggregated distributed energy resources to participate in wholesale markets, directly expanding addressable revenue for automated demand response providers. The EU Green Deal and F-Gas Regulation pressure commercial building operators to reduce peak demand and refrigerant-intensive cooling loads, creating compliance-driven procurement of intelligent load control systems. Stakeholders must monitor how ISO New England, CAISO, and ERCOT reform their capacity market rules to value fast-responding demand flexibility versus traditional generation reserves.
Market Dynamics
Utility procurement models are pivoting from perpetual software licenses to recurring SaaS subscriptions, compressing upfront revenue recognition and forcing vendors to build lifetime customer value through continuous algorithmic improvement rather than one-time deployment fees.
Growth Catalysts
- FERC Order 2222:This US regulation enables aggregated distributed energy resources to bid into wholesale capacity markets, directly monetizing behind-the-meter flexibility that automated demand response platforms orchestrate.
- Industrial battery storage:Falling lithium-ion costs paired with AI-optimized charge-discharge cycles let manufacturing facilities participate in frequency regulation markets through automated curtailment systems.
- California and Texas:CAISO and ERCOT have mandated demand response participation for large commercial and industrial loads above specified consumption thresholds, creating compliance-driven procurement.
Market Restraints
- Legacy HVAC control fragmentation:Building automation systems from disparate vendors use incompatible communication protocols, forcing expensive middleware development for unified dispatch.
- Silicon carbide supply concentration:Power electronics enabling sub-second load response depend on SiC substrates where Chinese refining capacity dominates global output.
- Cybersecurity certification delays:North American Electric Reliability Corporation Critical Infrastructure Protection standards impose multi-year compliance timelines for cloud-connected grid assets.
Strategic Opportunities
- Virtual power plant aggregation:Cloud-native platforms can enroll residential thermostats, EV chargers, and rooftop solar inverters that legacy demand response systems cannot address.
- EU Green Deal compliance:Commercial building operators face mandated peak demand reductions and F-Gas refrigerant phase-downs, requiring intelligent load control retrofits.
- Edge computing convergence:Localized AI inference at substations reduces latency for frequency response, opening microsecond-level markets previously reserved to synchronous generators.
Industry Challenges
- Control systems integration:Facilities engineers lack expertise in both OT cybersecurity and wholesale market bidding, creating staffing bottlenecks for deployment scale-up.
- Interoperability standardization:Competing protocols from IEEE, OpenADR, and proprietary utility specifications delay multi-vendor system certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Demand Response Management Systems Market |
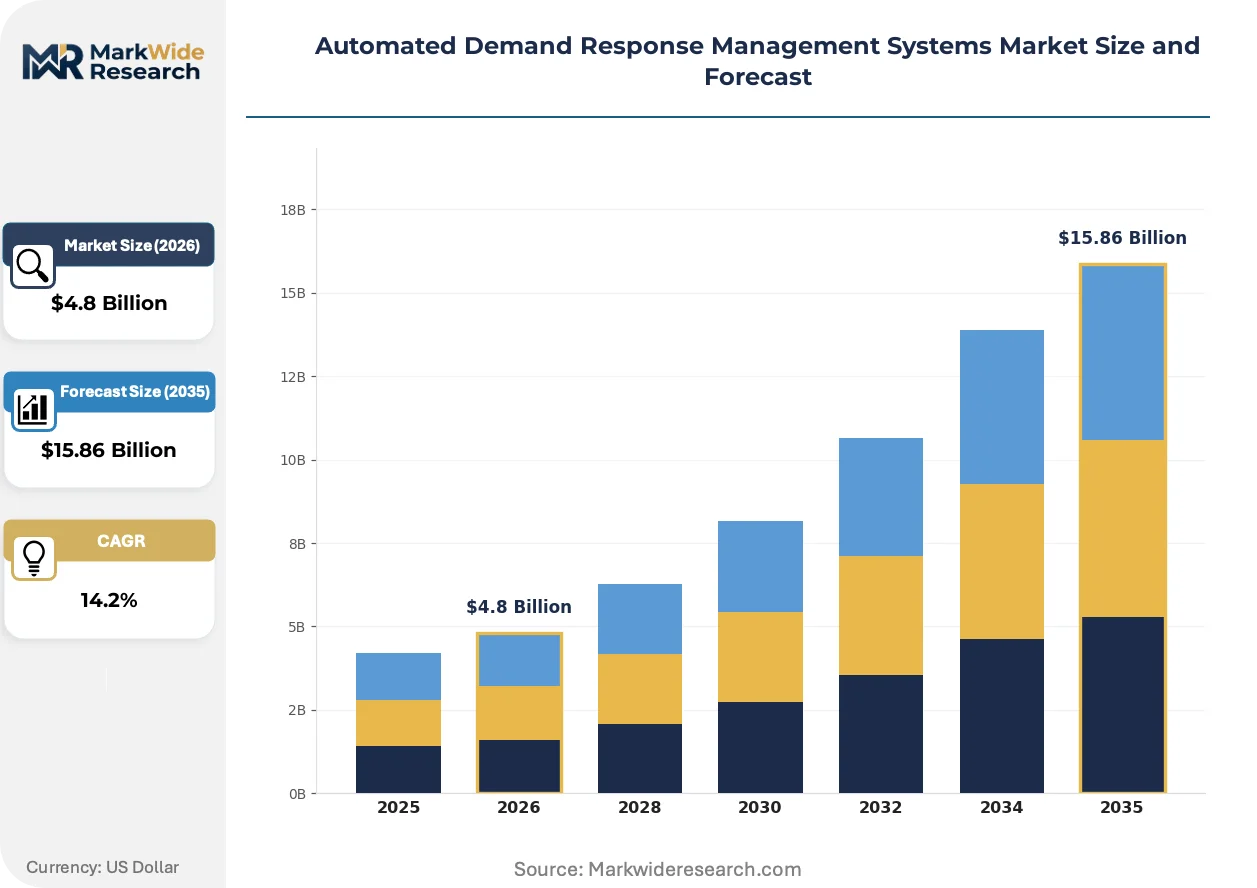
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Software Solutions, Hardware Systems, Cloud-Based Platforms, Integrated Systems End User: Residential Users, Commercial Buildings, Industrial Facilities, Utility Providers Technology: IoT Technology, Cloud Computing, AI Algorithms, Data Analytics Deployment: On-Premises, Hybrid, Fully Cloud-Based, Edge Computing |
| Companies Covered | ABB, Eaton, Schneider Electric, Siemens, Honeywell International Inc., General Electric, Itron Inc., Johnson Controls, AutoGrid Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Demand Response Management Systems Market Strategic Shifts
Algorithmic orchestration is supplanting rule-based load shedding as the dominant technical architecture, with machine learning models now predicting price spikes and grid emergencies hours ahead of dispatch signals.
Cloud-native virtual power plant software is rendering obsolete on-premise demand response management systems that require dedicated server infrastructure and manual firmware updates. Large commercial energy managers in Texas and California are migrating to API-first platforms within eighteen-month procurement cycles. This shift compresses vendor margins on hardware while expanding addressable revenue per customer through continuous optimization services.
The EU F-Gas Regulation is accelerating refrigerant-intensive cooling load displacement by mandating lower-global-warming-potential alternatives and peak demand limits for commercial buildings. Facility operators must retrofit intelligent control systems to maintain cooling capacity under constrained refrigerant volumes and power draw caps. German and French commercial real estate portfolios are prioritizing automated demand response procurement to maintain LEED and BREEAM certifications under tightened energy performance standards.
Building operators now unbundle long-term energy service contracts to procure automated demand response as standalone SaaS, separating flexibility optimization from commodity supply agreements. This disintermediation erodes traditional utility channel control and opens direct vendor relationships with facility management firms. The pattern is most pronounced in deregulated US states where competitive retail electric providers previously bundled demand response with supply contracts.
Automated Demand Response Management Systems Market Segmentation
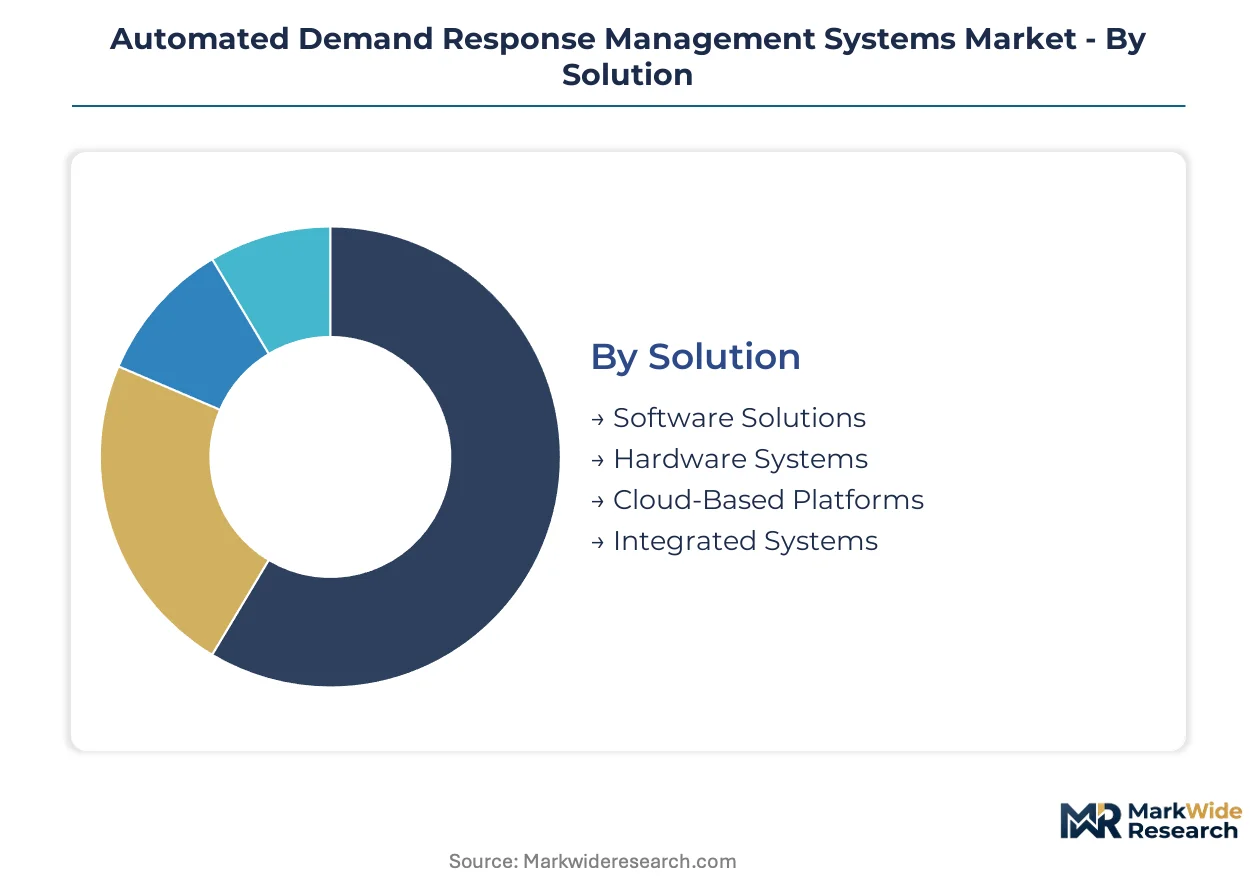
Automated demand response management systems segment across four dimensions that determine procurement complexity and vendor engagement models. Solution architecture dictates integration requirements, while deployment mode shapes cybersecurity compliance burdens and operational staffing needs.
Solution:
After-sales service intensity varies sharply across solution types, with cloud-native platforms demanding continuous algorithmic tuning while hardware systems require field maintenance contracts.
- Software Solutions:Modular applications for load forecasting, dispatch optimization, and settlement reconciliation deploy atop existing SCADA infrastructure. Manufacturing facilities in Texas and California procure these to comply with ERCOT and CAISO mandates without forklift upgrades to physical control systems.
- Cloud-Based Platforms:API-first architectures aggregate distributed energy resources through SaaS subscriptions, eliminating on-premise server maintenance. Demand concentrates among multi-site commercial real estate operators seeking unified visibility across geographically dispersed building portfolios.
- Hardware Systems:Dedicated controllers, communication gateways, and substation interfaces provide deterministic response latency for frequency regulation markets. Procurement cycles extend 18-24 months due to NERC CIP certification requirements.
- Integrated Systems:Bundled hardware-software stacks from single vendors reduce interoperability risk but lock buyers into proprietary ecosystems. Utility providers favor these for large commercial and industrial direct install programs.
By volume, Software Solutions leads. By growth pace, Cloud-Based Platforms is ahead.
End User:
Cost tier segmentation reveals divergent willingness-to-pay, with industrial facilities accepting premium pricing for sub-second response capabilities while residential programs depend on ratepayer-funded incentives.
- Industrial Facilities:Behind-the-meter battery storage and process load flexibility enable participation in wholesale frequency regulation markets. AI-optimized charge-discharge cycles at cement, steel, and data center operations in ERCOT territory monetize grid services revenue streams.
- Commercial Buildings:HVAC, lighting, and refrigeration loads provide curtailable capacity with minimal operational disruption. EU Green Deal compliance pressures German and French retail portfolios to retrofit intelligent controls for peak demand caps and F-Gas refrigerant phase-downs.
- Utility Providers:Grid operators procure platforms to manage system-wide peak events and defer generation capacity investments. Procurement models pivot from perpetual licenses toward recurring SaaS subscriptions.
- Residential Users:Thermostats, water heaters, and EV chargers aggregate into virtual power plants through opt-in enrollment programs. Margins compress due to high customer acquisition costs and regulatory caps on program participation fees.
Industrial Facilities command the highest revenue per deployment. Commercial Buildings show the steepest expansion trajectory as EU regulations tighten.
Technology:
Application maturity separates proven telemetry infrastructure from emerging predictive capabilities that reshape competitive positioning.
- AI Algorithms:Machine learning models predict price spikes and grid emergencies hours ahead of dispatch signals, enabling proactive load modulation. Continuous model retraining demands specialized data science staffing that vendors must embed or subcontract.
- IoT Technology:Sensor networks and communication modules provide real-time telemetry on electrical load status and environmental conditions. Deployment concentrates in legacy building retrofits where wired infrastructure proves cost-prohibitive.
- Cloud Computing:Scalable compute resources support multi-tenant platform architectures and rapid feature deployment. Latency constraints exclude cloud-only solutions from sub-second frequency response applications.
- Data Analytics:Historical load profiling and pattern recognition inform baseline establishment and measurement-and-verification protocols. Standards bodies and utility regulators impose strict accuracy requirements on these calculations.
IoT Technology dominates installed base. AI Algorithms are gaining share fastest as utilities prioritize predictive over reactive dispatch.
Deployment:
Customer type segmentation maps to risk tolerance, with critical infrastructure operators rejecting external connectivity while retail energy managers embrace cloud agility.
- Edge Computing:Localized AI inference at substations and facility controllers reduces latency to microseconds, opening frequency response markets previously reserved to synchronous generators. Nuclear and defense-adjacent facilities mandate air-gapped architectures.
- Hybrid:Sensitive control functions execute locally while data aggregation and market bidding shift to cloud infrastructure. This architecture balances latency requirements against scalability needs for most commercial and industrial deployments.
- Fully Cloud-Based:Complete reliance on vendor-managed infrastructure minimizes capital expenditure and IT staffing burdens. Cybersecurity certification timelines under NERC CIP standards delay North American adoption despite operational advantages.
- On-Premises:Dedicated server infrastructure within facility or utility control centers satisfies stringent data sovereignty and security requirements. Maintenance costs and firmware update cycles burden internal engineering teams.
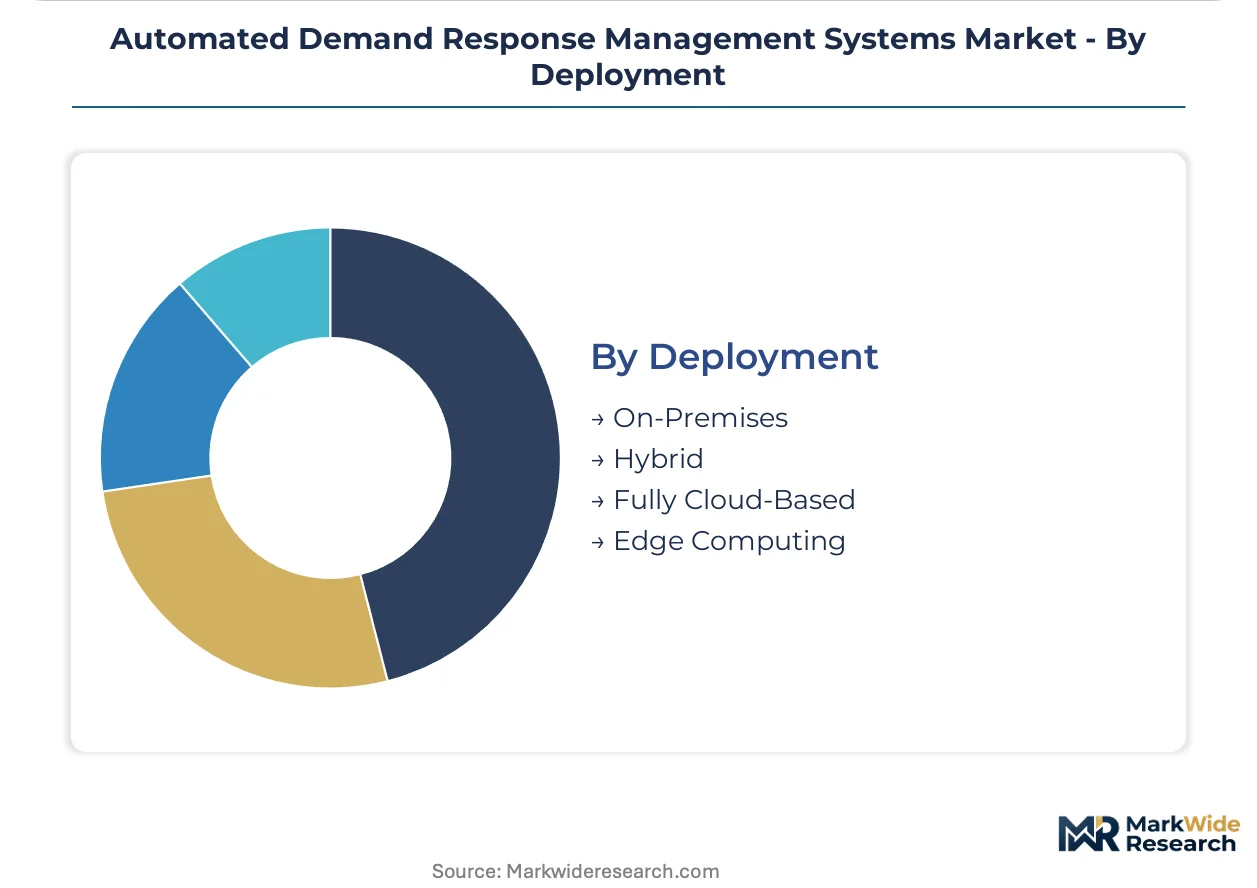
Fully Cloud-Based leads new procurement. Edge Computing climbs the fastest as markets reward speed of response.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California and Texas command pricing premiums for automated demand response platforms due to mandatory participation rules, while European markets lag on deployment velocity despite tighter building efficiency mandates.
United States
FERC Order 2222 enables aggregated distributed energy resources to bid into wholesale capacity markets, expanding revenue pools for platform providers. The Inflation Reduction Act channels federal investment into grid modernization and demand-side energy management. ERCOT in Texas and CAISO in California have mandated demand response participation for large commercial and industrial loads above specified thresholds, driving compliance-driven procurement in Houston and Los Angeles metro areas.
Germany
Commercial real estate portfolios prioritize automated demand response procurement to maintain LEED and BREEAM certifications under tightened energy performance standards. The EU F-Gas Regulation accelerates refrigerant-intensive cooling load displacement by mandating lower-global-warming-potential alternatives. Industrial clusters in Bavaria and North Rhine-Westphalia retrofit intelligent control systems to maintain cooling capacity under constrained power draw caps.
France
Building operators unbundle long-term energy service contracts to procure automated demand response as standalone SaaS, separating flexibility optimization from commodity supply agreements. The EU Green Deal pressures commercial building operators to reduce peak demand through intelligent load control retrofits. Île-de-France commercial real estate operators lead procurement volumes as Paris tightens energy performance disclosure requirements.
China
Dual carbon goals drive grid operators to procure automated demand response platforms to manage peak load events and defer generation capacity investments. Provincial grid companies pilot virtual power plant aggregation for residential thermostats and EV chargers. Yangtze River Delta manufacturing hubs deploy behind-the-meter battery storage with AI-optimized charge-discharge cycles to monetize frequency regulation markets.
United Kingdom
Deregulated retail electric markets enable facility management firms to establish direct vendor relationships outside traditional utility channels. The country's national energy regulator reforms capacity market rules to value fast-responding demand flexibility versus traditional generation reserves. London and Southeast commercial building operators migrate to API-first platforms within compressed procurement cycles.
Automated Demand Response Management Systems Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying power electronics and communication modules. The vendor base consolidates around three strategic archetypes: integrated hardware-software stack providers, cloud-native virtual power plant orchestrators, and building automation incumbents converting legacy installed bases. Dominant competitive moves include strategic partnerships between software vendors and industrial battery manufacturers, plus geographic expansion through energy-as-a-service leasing models that bypass capital-intensive infrastructure ownership.
Within the integrated systems tier, Schneider Electric leverages its bundled hardware-software stack to anchor large commercial deployments across multiple continents. AutoGrid Systems Inc. exemplifies the cloud-native archetype, competing on software agility through API-first architectures rather than physical equipment. Johnson Controls occupies a position converting legacy HVAC control installed bases into responsive grid assets, sustaining channel dominance in building automation retrofits.
| Leading Market Players |
|---|
| ABB |
| Eaton |
| Schneider Electric |
| Siemens |
| Honeywell International Inc. |
| General Electric |
| Itron Inc. |
| Johnson Controls |
| AutoGrid Systems Inc. |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide substrate concentration in Chinese refining capacity creates dual vulnerability for pricing tier compression and supply security across automated demand response hardware tiers. This single-source dependency forces tier-one system integrators to absorb input cost volatility while cloud-native software vendors capture margin expansion through decoupled SaaS architectures.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in automated demand response procurement. Price differentiation rests on NERC CIP certification tier and after-sales service bundling intensity. Cost compression in economy-tier hardware is intensifying because SiC power electronics face supply rationing from concentrated refining capacity. Commercial real estate operators show highest price sensitivity due to unbundled SaaS procurement models, while utility providers accept premium pricing for deterministic sub-second response capabilities.
Supply Chain Analysis
Contract manufacturing for power electronics controllers concentrates among Taiwanese and South Korean EMS providers with captive SiC packaging lines. Raw material flows draw from Chinese rare earth processing, German precision sensor fabrication, and Japanese communication module assembly. Single-source vulnerability in SiC substrate supply creates procurement bottlenecks for hardware systems requiring sub-second frequency response. Distribution runs through direct utility procurement channels in regulated markets and energy-as-a-service lessors in deregulated jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent automated demand response vendors face substitution pressure from cloud-native virtual power plant platforms that bypass capital-intensive hardware ownership. This displacement threat demands defensive repositioning around data moats and regulatory certification barriers.
For Market Incumbents: Build switching cost moats through embedded AI algorithm training on proprietary load datasets accumulated across utility deployments. Deepen backward integration into edge computing hardware to secure microsecond-response market access against pure-software entrants. Anchor channel control through NERC CIP certification maintenance that delays cloud-native competitor market entry timelines. For New Entrants and Emerging Players: Establish a beachhead in EU commercial building retrofits where F-Gas Regulation compliance creates urgent procurement windows for intelligent load control systems. Target mid-sized industrial facilities in ERCOT territory with battery-plus-optimization bundled offerings that legacy building automation vendors cannot assemble. Pursue energy-as-a-service leasing partnerships to bypass incumbent utility channel relationships. For Investors and Strategic Acquirers: FERC Order 2222 implementation timelines reshape the acquisition landscape toward platform providers with wholesale market bidding capabilities. Long-term viability favors asset-light orchestration software over hardware-dependent system integrators as utilities pivot to recurring SaaS subscriptions. Monitor CAISO and ERCOT capacity market rule reforms as inflection signals for demand flexibility valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | API-first architectures displace on-premise systems and expand recurring revenue per customer. |
| Edge Computing Hardware Development | Localized AI inference opens microsecond-response markets previously reserved to synchronous generators. |
| Virtual Power Plant Aggregation | Residential thermostat and EV charger enrollment expands addressable market beyond commercial-industrial base. |
| NERC CIP Certification Investment | Cybersecurity compliance timelines create defensive moats against unqualified cloud-native competitors. |
| EU Green Deal Compliance Positioning | F-Gas Regulation mandates drive German and French commercial building retrofit procurement cycles. |
Study Parameters
Initial hypotheses were tested against primary input from utility planning officers, commercial facility energy managers, grid operators, and demand response software engineers and refined through secondary validation. Utility procurement databases, FERC filings, CAISO and ERCOT market rule dockets, and EIA grid modernization expenditure records anchored quantitative sizing. Bottom-up deployment tracking across industrial facilities and commercial buildings triangulated against top-down utility spending forecasts.
Demand-supply balance modeling across the analysis window incorporated solution architecture segmentation, end-user facility type, and deployment mode latency requirements. CAGRs were derived from segment-level growth trajectory analysis calibrated to regulatory mandate implementation schedules. Wholesale market participation revenue pools under FERC Order 2222 and EU building efficiency compliance timelines informed regional expansion assumptions.
Stress conditions across SiC supply disruption severity, cybersecurity certification delay scenarios, and utility SaaS procurement acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation fidelity and battery storage cost trajectories. Quarterly review of ISO market rule reform announcements and NERC CIP certification backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Grid
China Smart Grid Network Market
Smart Grid
Saudi Arabia Smart Grid Market
Smart Grid
China Smart Power Distribution Systems Market
Smart Grid
Saudi Arabia Smart Grid Network Market
Smart Grid
Europe Microgrid Market
Smart Grid
South Korea Smart Grid Network Market
Smart Grid
Renewable Energy Integration with Smart Grid Market
Smart Grid
Smart Grid Home Area Network (HAN) Market
Smart Grid
Smart Microgrid Market
Smart Grid
Demand Response Market
Smart Grid
Smart Grid Communications Market
Smart Grid
United Kingdom Smart Grid Market
Smart Grid
Europe Automated Demand Response Market
Smart Grid
Microgrid Market
Smart Grid
UK Smart Grid Network Market
Smart Grid
Global Smart Grid Security Market