
 Chocolate and Confectionery Processing Equipment Market | 2026-2036
Chocolate and Confectionery Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Chocolate and Confectionery Processing Equipment Market Intelligence
The market for processing equipment is shifting as machinery requirements for high-volume, commodity confectionery diverge from those for small-batch, premium chocolate production. Large-scale producers favor integrated systems, where Bühler Group dominates with its comprehensive bean-to-bar solutions. In contrast, Sollich KG specializes in high-performance enrobing and cooling tunnels for a wide range of clients. Selmi specifically caters to the artisanal segment, offering compact and versatile tempering machines.
Chocolate and confectionery processing equipment includes the specialized machinery for transforming raw ingredients into finished goods. These systems must precisely control process variables like temperature gradients in tempering machines to achieve stable crystal formation in cocoa butter. Tempering machines and moulders represent a high-value equipment type, essential for producing premium chocolate bars. The application for chocolate coatings is expanding rapidly, driven by demand from snack manufacturers for enrobing biscuits and nuts.
Regulations from the U.S. FDA and the European Food Safety Authority (EFSA) mandate strict hygienic design principles for all food-contact surfaces. Compliance with standards like ISO 22000 further pushes manufacturers to adopt equipment that allows for easy cleaning and prevents cross-contamination. Consequently, equipment purchasing decisions hinge on balancing the need for high-throughput automation with the flexibility required for new product development.
Market Dynamics
The primary structural force is the bifurcation of machinery requirements. Large-scale confectionery producers seek high-throughput integrated lines, while the expanding artisanal chocolate segment demands flexible, smaller-footprint equipment for specialized, small-batch production.
Growth Catalysts
- Premium Chocolate Demand:The rise of artisanal and bean-to-bar chocolate makers directly fuels sales of specialized, small-scale machinery like compact tempering machines and moulders, particularly in North America and Western Europe.
- Food Safety Regulations:Mandates from bodies like the U.S. FDA and Europe's EFSA push processors to invest in new equipment featuring hygienic design, improved cleanability, and materials that prevent cross-contamination.
- Emerging Market Consumption:Expanding middle-class consumption of confectionery goods in Asian and Latin American countries creates new demand for both large-scale production lines and mid-sized equipment for regional brands.
Market Restraints
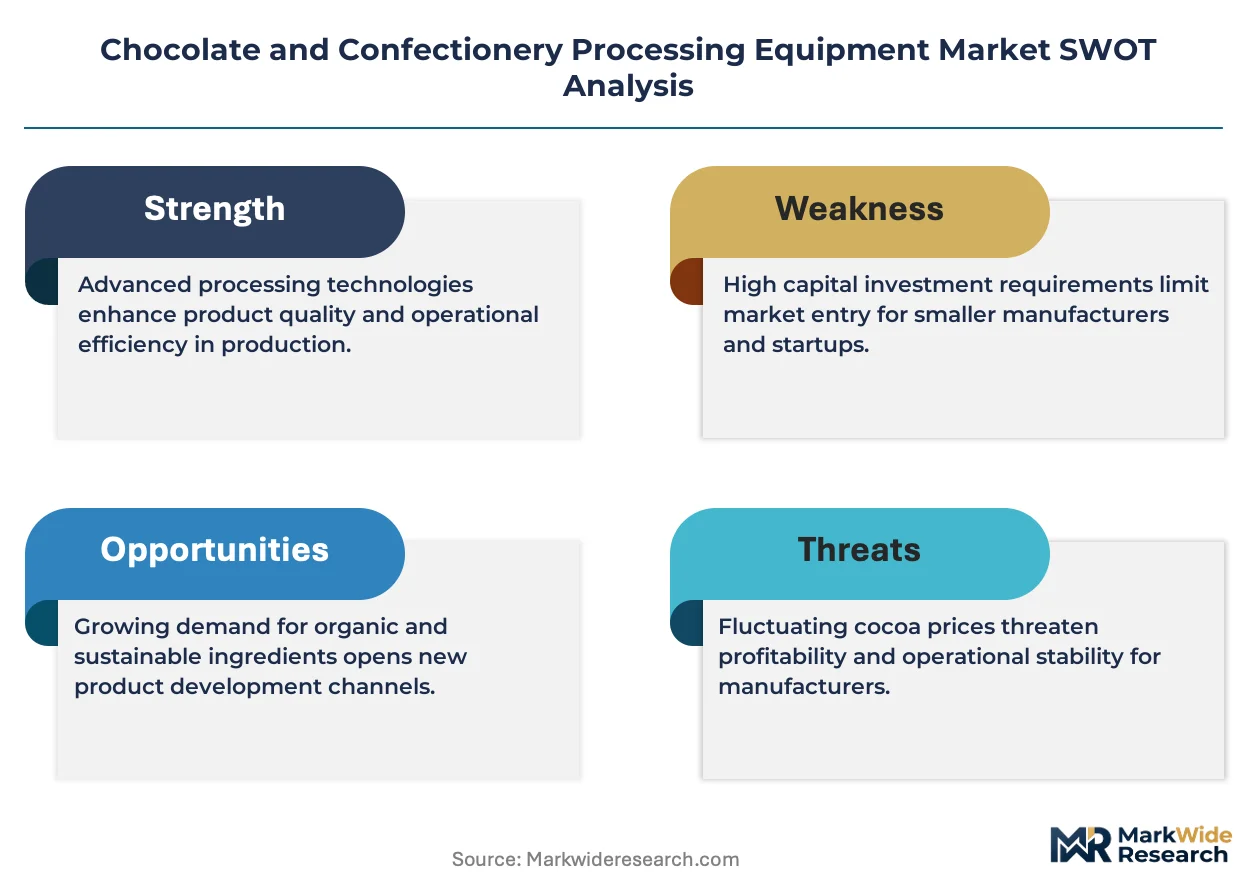
- High Capital Investment:The significant upfront cost of high-precision European-manufactured machinery, such as tempering and enrobing lines, can be a barrier for small businesses and startups without substantial financing.
- Cocoa Price Volatility:Fluctuations in the price and supply of cocoa, a primary raw material, can cause confectionery manufacturers to delay or defer major capital equipment expenditures, creating unpredictable investment cycles.
- Integration Complexity:Integrating new, advanced processing equipment with existing legacy systems on a factory floor presents significant technical and operational challenges, potentially leading to extended downtime during installation.
Strategic Opportunities
- Plant-Based Confectionery:Developing processing equipment specifically optimized for the unique viscosity and temperature profiles of plant-based and vegan chocolate formulations represents a significant new product category for equipment manufacturers.
- IIoT Integration:Embedding Industrial Internet of Things sensors for predictive maintenance and real-time process monitoring offers a value-added service, helping confectioners meet traceability standards like ISO 22000.
- Geographic Expansion:Targeting the nascent but growing craft chocolate markets in Southeast Asia and Eastern Europe with appropriately scaled and priced machinery offers a path for geographic diversification away from saturated markets.
Industry Challenges
- Skilled Operator Scarcity:A shortage of technicians trained to operate, maintain, and troubleshoot increasingly automated and software-driven confectionery processing lines poses a key operational bottleneck for chocolate manufacturers.
- Data Standardization:The lack of universal data and communication protocols between equipment from different manufacturers complicates the creation of fully integrated, smart factory environments for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chocolate and Confectionery Processing Equipment Market |
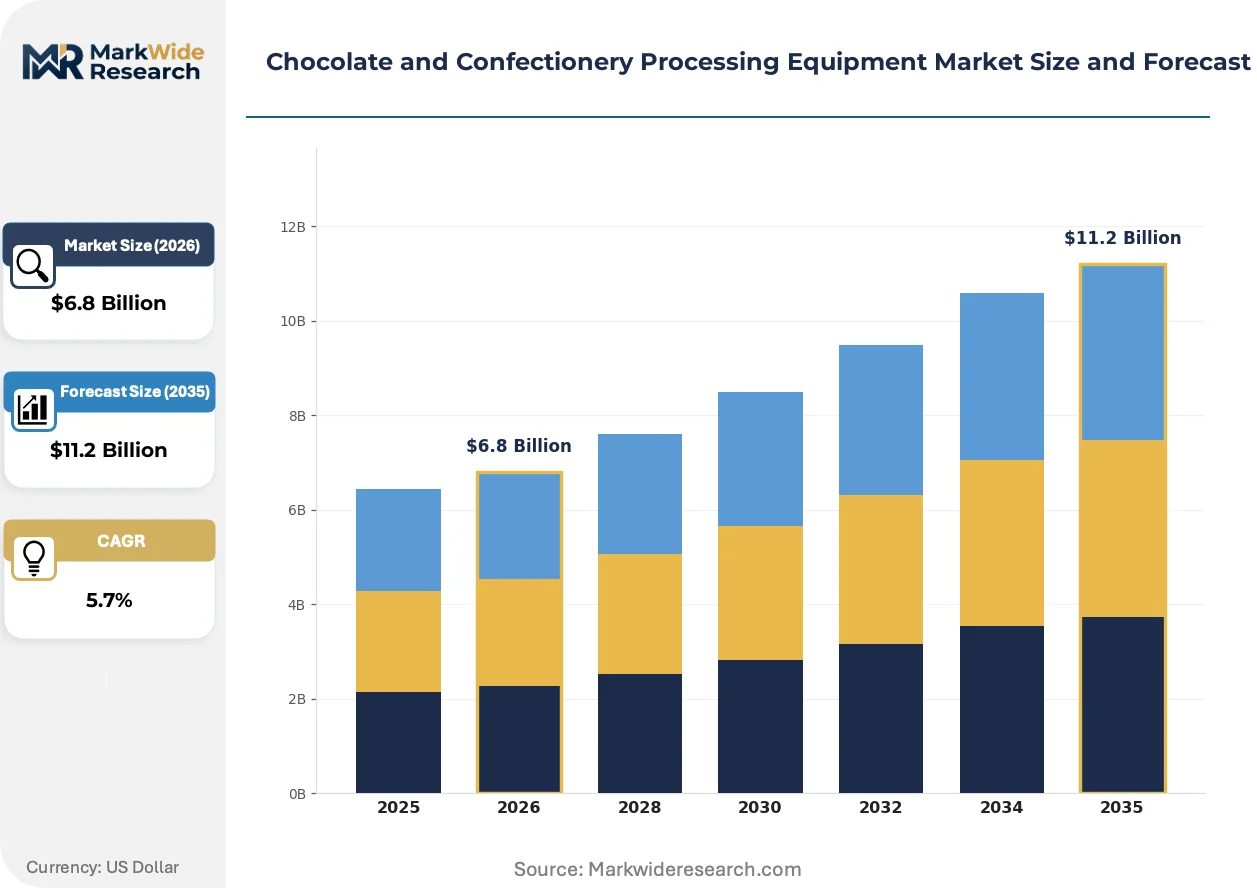
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Mixers, Moulders, Tempering Machines, Coating Machines Technology: Batch Processing, Continuous Processing, Vacuum Processing, High Shear Mixing Application: Chocolate Bars, Chocolate Coatings, Confectionery Products, Gummy Candies End User: Bakeries, Snack Manufacturers, Retail Stores, Food Service |
| Companies Covered | Selmi, Sollich KG, Bühler Group, Aasted, JBT Corporation, GEA Group, Alfa Laval, Syntegon, Royal Duyvis Wiener, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chocolate and Confectionery Processing Equipment Market Strategic Shifts & Innovations
Equipment innovation is driven by the need to support rapid product diversification without sacrificing operational efficiency. This creates a focus on machinery that offers both digital process control and physical adaptability for varied confectionery recipes and formats.
Modular equipment design allows for interchangeable components like different moulding heads or depositing nozzles. Small-to-medium batch producers and R&D labs are the primary adopters of this flexible approach. This modularity is absorbing the market for monolithic, single-function machines by enabling faster product changeovers and reducing line downtime.
The U.S. FDA's Food Safety Modernization Act (FSMA) mandates preventative controls and enhanced traceability. This requirement compels manufacturers to integrate sensors and data logging for critical control points like tempering. Tempering and enrobing equipment for the U.S. market is most affected, now requiring verifiable process documentation.
A shift towards equipment-as-a-service and leasing models is gaining traction among new market entrants and artisanal producers. This disrupts the traditional capital expenditure sales cycle, favoring vendors who offer flexible financing. The trend is most prominent in competitive European craft chocolate hubs like Belgium and France, where it lowers the barrier to entry.
Chocolate and Confectionery Processing Equipment Market Segmentation
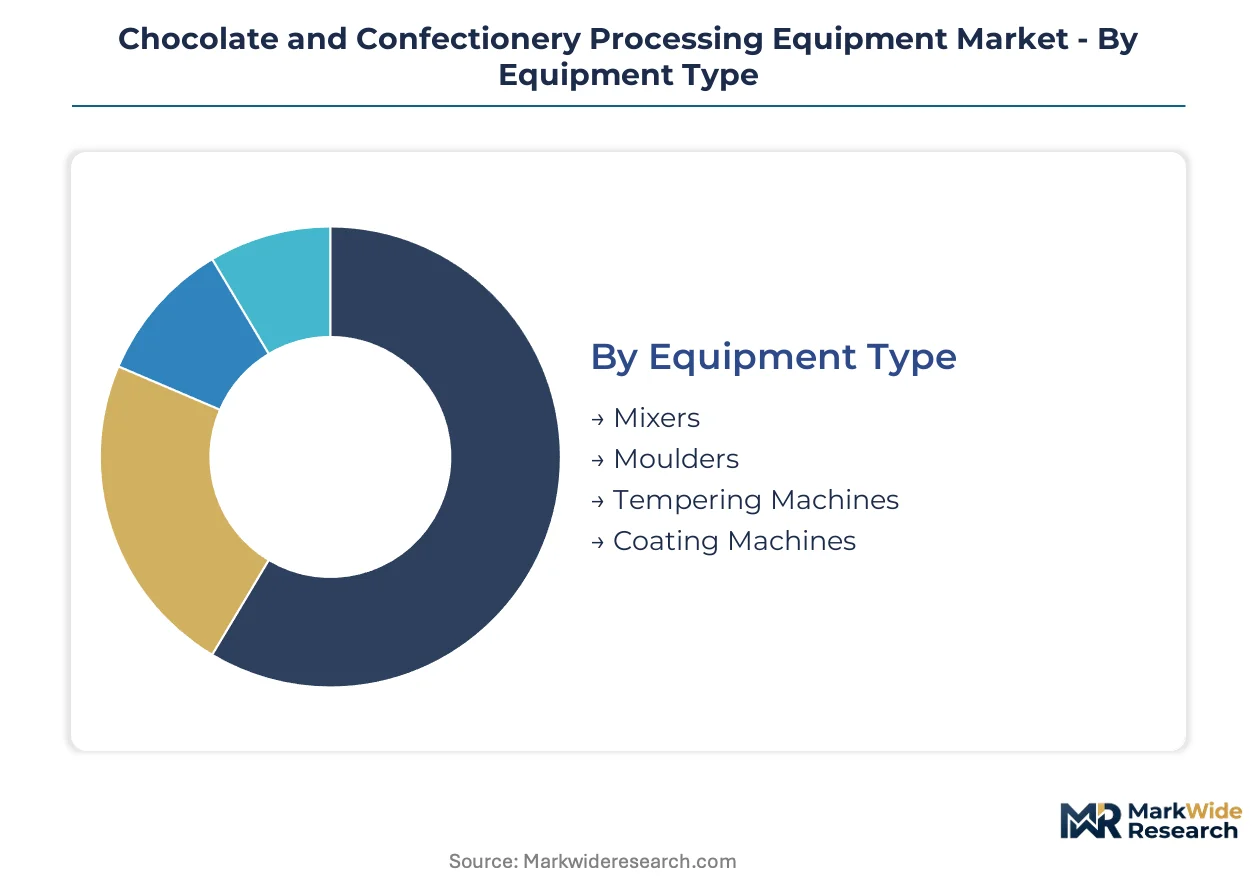
The chocolate and confectionery processing equipment market segments into distinct categories, each defined by the specific machinery, technological approach, end-product application, and ultimate user. Understanding these divisions is essential for equipment manufacturers to tailor their offerings and for confectioners to select optimal systems for their production needs.
Equipment Type:
This category distinguishes machinery based on its integration depth, from standalone units to components within larger automated lines.
- Mixers:These machines combine raw ingredients like cocoa mass, sugar, and milk powder to create a homogeneous chocolate paste. Small-scale artisanal producers and large industrial plants both rely on various mixer types for initial ingredient preparation.
- Moulders:Moulders shape liquid chocolate into specific forms, such as bars, pralines, or figures, using molds. High-precision moulders are critical for producing visually appealing premium chocolate bars with intricate designs.
- Tempering Machines:Tempering machines precisely control cocoa butter crystallization, creating stable fat structures for premium chocolate. Demand concentrates in established confectionery hubs like Switzerland, driven by the need for consistent product quality.
- Coating Machines:Coating machines apply a uniform layer of chocolate or compound to various centers, ensuring product appeal and extended shelf life. Snack manufacturers in North America drive significant demand for enrobing biscuits and nuts.
Tempering Machines leads volumes today; Coating Machines is gaining share fastest.
Technology:
This segment delineates processing methods based on their suitability for different production scales and product characteristics.
- Batch Processing:Batch processing involves distinct production runs for specific quantities, offering flexibility for varied recipes and smaller production scales. Artisanal chocolate makers in Western Europe increasingly adopt batch systems for specialized products.
- Continuous Processing:Continuous processing systems handle large volumes of ingredients without interruption, optimizing efficiency for high-throughput production lines. Major confectionery producers globally utilize these systems to meet mass market demand.
- Vacuum Processing:Vacuum processing removes moisture and volatile compounds from ingredients, enhancing flavor and extending shelf life for specific confectionery products.
- High Shear Mixing:High shear mixing rapidly disperses and homogenizes ingredients, creating fine emulsions and suspensions for smooth chocolate textures.
Efficiency gains define this category, where Continuous Processing offers speed and Batch Processing provides precision.
Application:
This category groups equipment based on the final product it helps create, reflecting diverse consumer preferences.
- Chocolate Bars:Chocolate bars represent a foundational application, ranging from commodity to premium bean-to-bar formulations. The premium segment in North America drives innovation in specialized moulding and tempering equipment.
- Chocolate Coatings:Chocolate coatings involve applying a layer of chocolate to food items, enhancing flavor, texture, and visual appeal. Snack manufacturers globally are expanding their use of coatings for various enrobed products.
- Confectionery Products:This segment includes a broad range of sugar-based candies, caramels, and nougats, requiring specialized cooking and forming equipment.
- Gummy Candies:Gummy candy production utilizes specific cooking, depositing, and drying equipment tailored for gelatin or pectin-based formulations.
The diverse applications here reflect evolving consumer tastes, with Chocolate Coatings showing significant growth potential.
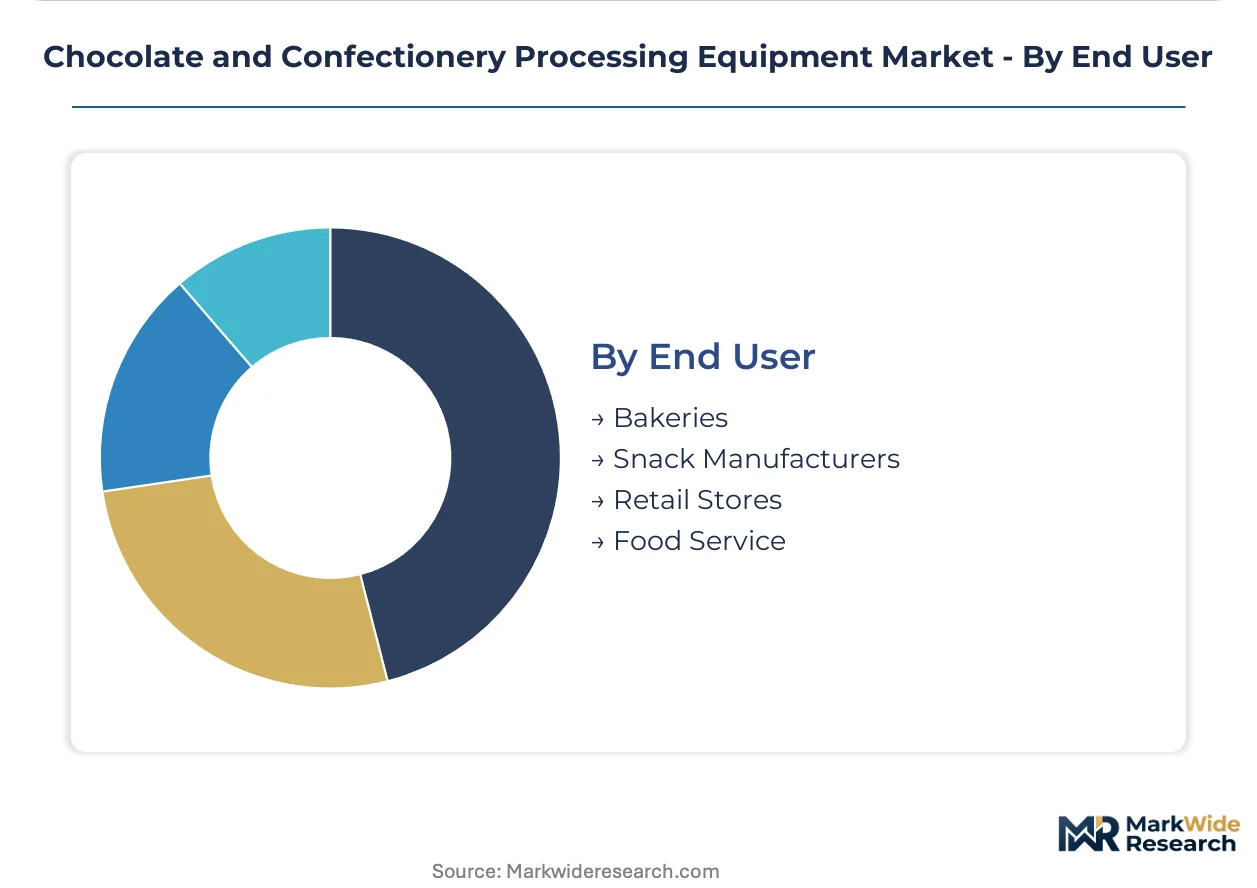
End User:
This segment differentiates buyers based on their operational scale and business model, influencing equipment choice.
- Bakeries:Bakeries utilize chocolate processing equipment for producing cakes, pastries, and other baked goods with chocolate inclusions or decorations. Small-to-medium bakeries in Europe often seek compact tempering and moulding solutions.
- Snack Manufacturers:Snack manufacturers integrate processing equipment to produce chocolate-covered snacks, expanding product lines with confectionery elements. Demand from these manufacturers is particularly strong for high-performance enrobing tunnels.
- Retail Stores:Some larger retail outlets and specialized chocolate shops invest in compact processing equipment for in-house production or customization.
- Food Service:Food service providers, including hotels and restaurants, may acquire smaller tempering or decorating machines for fresh, on-site chocolate preparations.
This segment highlights the varied operational scales, from large industrial producers to specialized artisanal shops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled engineering and confectionery expertise anchors the regional landscape for processing equipment. This concentration of specialized talent drives innovation and demand across established and emerging markets. These regional dynamics influence equipment design and adoption patterns for chocolate and confectionery producers.
Switzerland
Switzerland's confectionery heritage drives demand for high-precision tempering and moulding machines. Compliance with ISO 22000 standards is paramount for equipment manufacturers operating here. The Zurich-Bern corridor, a hub for food technology, sees continuous development in specialized machinery for premium chocolate.
Germany
Germany's robust industrial base fuels demand for integrated, high-throughput processing lines. Equipment must meet stringent EFSA hygienic design principles for food contact surfaces. North Rhine-Westphalia, an industrial powerhouse, concentrates manufacturers of large-scale confectionery machinery.
United States
The United States experiences strong demand from artisanal producers and snack manufacturers for specialized equipment. U.S. FDA regulations, particularly FSMA, mandate enhanced traceability and preventative controls for processing lines. California's craft food scene and Pennsylvania's confectionery cluster drive innovation in compact and enrobing solutions.
China
China's expanding middle-class consumption generates significant demand for both large-scale and mid-sized processing equipment. GB standards for food machinery dictate design and operational requirements for local and imported systems. The Yangtze River Delta, a major economic zone, is a focal point for confectionery production and equipment adoption.
Brazil
Brazil's growing domestic market for confectionery products creates demand for versatile, regional-brand focused equipment. ANVISA regulations ensure food safety and quality for all processing machinery sold within the country. São Paulo state, a prominent agricultural and industrial region, shows increasing investment in confectionery processing capabilities.
Chocolate and Confectionery Processing Equipment Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market share in confectionery processing equipment. The market structure is bifurcated, with a few dominant players offering comprehensive integrated solutions alongside numerous specialized manufacturers. Strategic archetypes include large-scale integrated system providers, niche players catering to artisanal segments, and component suppliers. Geographic expansion into emerging markets and strategic partnerships for technology co-development are dominant competitive moves.
Specialists in high-performance machinery, such as Sollich KG, exemplify the focus on specific process steps like enrobing and cooling tunnels, serving a wide range of clients. Bühler Group, a Swiss-based entity, represents the archetype of a comprehensive bean-to-bar solution provider, offering integrated systems for large-scale operations globally. Selmi, an Italian manufacturer, occupies a position catering to the artisanal segment with compact and versatile tempering machines, lowering the barrier to entry for smaller producers. These companies anchor different segments by providing tailored solutions.
| Leading Market Players |
|---|
| Selmi |
| Sollich KG |
| Bühler Group |
| Aasted |
| JBT Corporation |
| GEA Group |
| Alfa Laval |
| Syntegon |
| Royal Duyvis Wiener |
| Others |
Cost & Logistics Intelligence
Compliance with ISO 22000 standards, a key food safety mandate, gates access to premium-tier pricing for equipment manufacturers and qualifies their supply for stringent markets. This regulatory overhead contributes to the higher cost structure of specialized machinery, particularly for European-manufactured systems.
Pricing Analysis
The pricing structure in this market blends project-based capital expenditure for integrated lines with service-tiered models for compact, flexible machinery. Price differentiation stems from the precision engineering of European-manufactured equipment and the depth of after-sales service bundles. Pricing softness affects the entry-level segment due to increased competition from new leasing models. Small businesses and startups demonstrate the highest price sensitivity, often seeking equipment-as-a-service options.
Supply Chain Analysis
Logistics and freight costs significantly influence the final price of processing equipment, especially for specialized European machinery shipped globally. Supply concentration for high-precision components and advanced control systems resides primarily in Germany, Switzerland, and Italy. The market faces a structural risk from single-source vulnerability for highly specialized parts, impacting lead times. Distribution of large-scale integrated systems primarily runs through direct sales channels, while smaller, artisanal equipment often utilizes specialized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage play, capitalizing on lower manufacturing costs in emerging Asian economies compared to the high precision engineering overhead in Western Europe. This differential allows for competitive pricing in underserved regions.
For Market Incumbents:
Lock in existing client relationships by offering comprehensive IIoT integration for predictive maintenance and real-time process monitoring. Invest in R&D for plant-based confectionery equipment, addressing the shift in consumer preferences. The proliferation of equipment-as-a-service models poses a threat by lowering entry barriers for smaller competitors. Expand capacity in regional manufacturing hubs to mitigate logistics costs for large systems.
For New Entrants and Emerging Players:
Underserved artisanal chocolate makers in Southeast Asia and Eastern Europe represent a significant white-space opportunity. Focus on developing appropriately scaled and priced modular machinery with flexible financing options, such as leasing models. Target regions with nascent craft chocolate scenes, leveraging digital marketing to reach small-batch producers. Emphasize ease of use and rapid product changeover capabilities as a key selling proposition.
For Investors and Strategic Acquirers:
Roll-up economics work for specialized equipment manufacturers because the market exhibits fragmentation across niche segments and technologies. Long-term viability rests on the sustained demand for premium and artisanal confectionery, alongside expanding middle-class consumption in emerging markets. Target mid-sized manufacturers with strong intellectual property in specific process technologies like high-precision tempering or plant-based formulation equipment. Watch for the increasing adoption of IIoT solutions as a signal of market consolidation potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Enables manufacturers to meet rising demand from emerging markets like China and Brazil. |
| Technology Licensing | Accelerates development of specialized equipment for plant-based confectionery formulations. |
| Strategic Partnership | Facilitates market entry into new geographic regions and co-development of advanced IIoT solutions. |
| Green Manufacturing Transition | Ensures compliance with stringent hygienic design principles and reduces operational environmental impact. |
| Product Launch | Introduces modular equipment designs, allowing for faster product diversification for end-users. |
Research Approach
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region informing the market landscape. The analysis combines in-depth interviews with industry stakeholders, including plant managers, R&D directors, procurement leads at confectionery manufacturers, and food safety officers, with extensive secondary validation. Data triangulation from diverse sources, including food safety regulations from the U.S. FDA and Europe's EFSA, industry association reports, and company financial disclosures, underpins the findings, utilizing both bottom-up and top-down approaches.
The forecast framework models market dimensions at a granular level, including equipment type, technology, application, end user, and geographic region across the analysis window. Compound Annual Growth Rates (CAGRs) are derived through a rigorous statistical analysis of historical trends and projected future demand. Key industry-specific forecast inputs include global cocoa price trends and evolving consumer spending patterns on premium confectionery products, which directly impact equipment investment cycles.
Inputs from primary and secondary sources were available through the study window; gaps in specific regional trade data or detailed capital expenditure plans introduce uncertainty bands into the forecasts. Forecasts reflect a set of assumptions regarding technological advancements and regulatory stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food & Beverages
Philippines Quick Service Restaurants Market
Food & Beverages
Parmesan Cheese Market
Food & Beverages
Europe Organic Food Market
Food & Beverages
Hydrolyzed Corn Protein Market
Food & Beverages
Chicken Fat Market
Food & Beverages
Organic Beverages Market
Food & Beverages
North America Cafes & Bars Market
Food & Beverages
Gum Base Candy Market
Food & Beverages
Grass Fed Beef Market
Food & Beverages
Garlic Oleoresin Market
Food & Beverages
Mediterranean Healthy-Aging Beverage Ingredients Market
Food & Beverages
Liuweidihuang Market
Food & Beverages
Ph Adjuster Market
Food & Beverages
Citrus Alcohol Market
Food & Beverages
Floral Tea Market
Food & Beverages
Natural Food Color Ingredients Market